
 Europe Biguanide Market | 2026-2036
Europe Biguanide Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biguanide Market Foresight
Hospital procurement of biguanide therapies is pivoting toward extended-release tablets as clinicians prioritize glycemic control protocols with reduced dosing frequency. Teva leverages its European manufacturing footprint to sustain supply continuity for generic metformin across Germany and France. Sanofi competes through differentiated formulation portfolios that anchor its position in hospital and retail pharmacy channels. Bristol-Myers Squibb specializes in cardiovascular combination therapies that extend its relevance beyond standalone diabetes applications.
Biguanides comprise a class of oral hypoglycemic agents characterized by a guanide-derived core structure, with metformin hydrochloride representing the dominant active pharmaceutical ingredient produced through chemical synthesis involving dimethylamine and cyanoguanidine condensation. These compounds function primarily by suppressing hepatic gluconeogenesis and improving peripheral insulin sensitivity in type 2 diabetes management. Metformin dominates the product type landscape as the established first-line therapy, while extended-release capsules command premium positioning due to improved tolerability profiles and patient compliance advantages. The application mix tilts heavily toward type 2 diabetes, though polycystic ovary syndrome represents a faster-growing off-label segment where clinical validation is deepening.
EMA marketing authorization requirements and REACH chemical safety standards govern active pharmaceutical ingredient purity, environmental discharge limits, and manufacturing facility certifications across European production sites. The EU Green Deal pressures suppliers to decarbonize synthesis processes and validate sustainable solvent recovery systems. The F-Gas Regulation indirectly affects climate-controlled storage and transport infrastructure for temperature-sensitive formulations. Stakeholders must monitor evolving EMA guidance on nitrosamine impurity thresholds and assess backward integration into key starting material production to secure supply resilience against regulatory tightening.
Market Dynamics
Hospital procurement protocols across Germany, France, and Italy are consolidating purchasing power around extended-release metformin formulations, compressing margins for standard immediate-release suppliers while elevating manufacturers with differentiated delivery technologies.
Growth Catalysts
- EMA extended-release formulation approvals:Streamlined marketing authorization pathways for modified-release biguanides accelerate product differentiation and hospital formulary inclusion across member states.
- Type 2 diabetes prevalence:Rising patient volumes in Southern and Eastern European markets sustain volume demand for first-line oral hypoglycemic therapy.
- Polycystic ovary syndrome off-label validation:Deepening clinical evidence for metformin in reproductive endocrinology opens prescriber expansion beyond diabetology.
Market Restraints
- Dimethylamine feedstock volatility:Petrochemical-derived starting material costs fluctuate with natural gas pricing, squeezing synthesis margins for API manufacturers.
- Indian API supplier concentration:European formulation houses remain dependent on imported active pharmaceutical ingredients from concentrated Asian supply bases.
- Nitrosamine impurity thresholds:Tightening EMA guidance on NDMA limits forces costly process revalidation and batch testing protocols.
Strategic Opportunities
- Poland and Romania hospital expansion:Underpenetrated Central European procurement markets offer volume growth as healthcare infrastructure modernizes.
- Fixed-dose cardiovascular combinations:Convergence of biguanide therapy with SGLT2 inhibitor and statin platforms creates differentiated portfolio positioning.
- EU Green Deal solvent recovery mandates:Early compliance with sustainable manufacturing incentives secures preferential supplier status in public tenders.
Industry Challenges
- Process analytical technology integration:Real-time release testing implementation demands capital expenditure and specialized quality engineering talent.
- REACH registration timeline compression:Chemical safety dossier preparation for novel salt forms strains regulatory affairs capacity.
- Legacy batch record digitization:Migration from paper-based manufacturing documentation to electronic systems disrupts established plant workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biguanide Market |
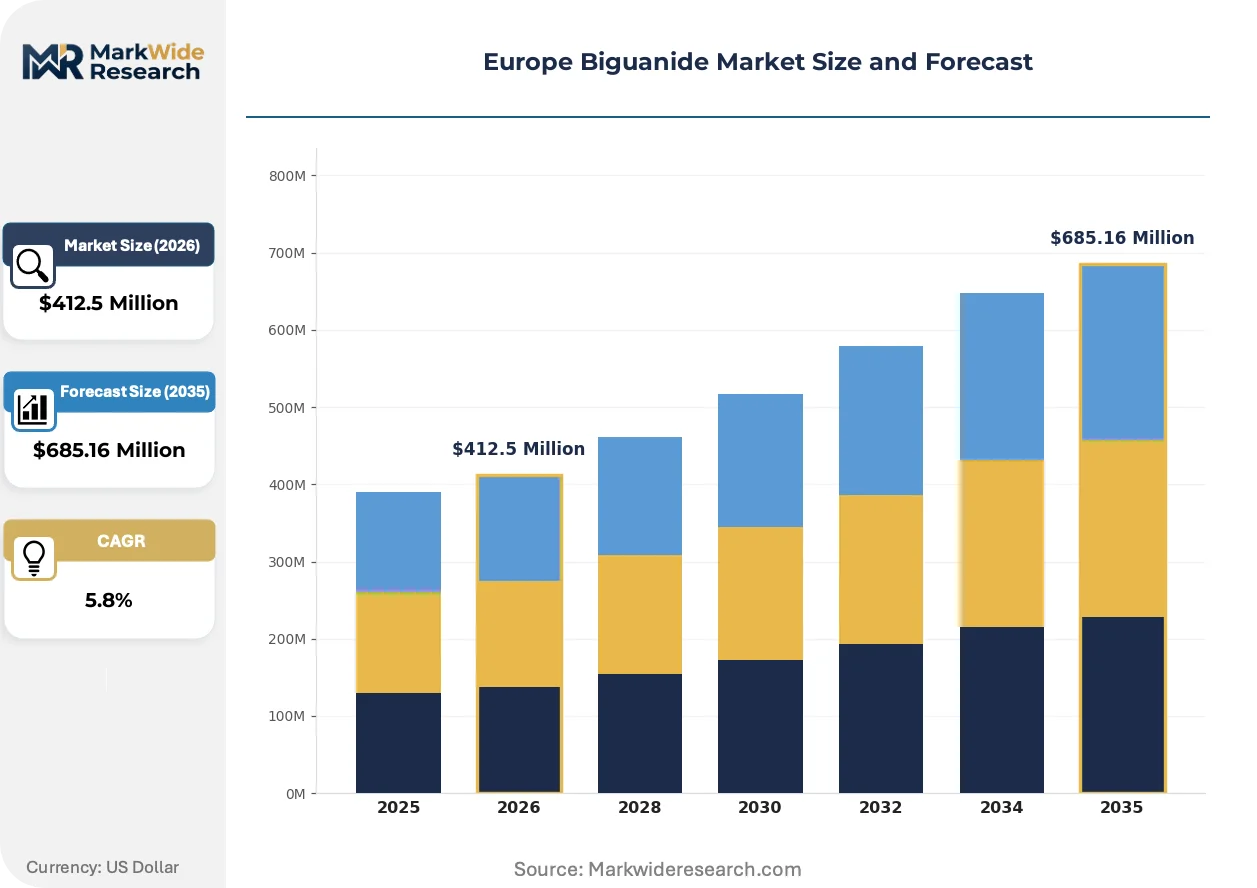
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metformin, Phenformin, Buformin, Others Application: Type 2 Diabetes, Polycystic Ovary Syndrome, Weight Management, Cardiovascular Health Formulation: Tablets, Extended-Release Capsules, Liquid Formulations, Powders End User: Hospitals, Clinics, Pharmacies, Homecare |
| Companies Covered | Teva, Takeda, Merck, Sanofi, Bristol-Myers Squibb, AstraZeneca, Boehringer Ingelheim, GlaxoSmithKline, Merck and Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biguanide Market Shifts & Advancements
Formulation science and environmental compliance are converging to reshape competitive advantage in European biguanide supply, with manufacturing sustainability and patient-centric delivery systems emerging as the primary axes of differentiation.
Modified-release polymer matrix technologies are overtaking conventional hydrophilic swellable systems in extended-release metformin production. German hospital pharmacies now specify osmotic pump formulations for high-risk patient populations requiring precise plasma concentration control. This technology compression is marginalizing standard matrix tablet suppliers in premium procurement segments.
REACH chemical safety dossier requirements now mandate complete substance lifecycle environmental impact assessment for biguanide active pharmaceutical ingredients. ECHA registration deadlines force API manufacturers to validate biodegradation pathways and aquatic toxicity profiles. Italian production sites face the steepest compliance curve due to concentrated effluent discharge into sensitive Mediterranean watersheds.
Centralized hospital procurement consortia in France and Spain are consolidating annual metformin volume commitments into multi-year framework agreements with single-source suppliers. Regional pharmacy cooperatives displace traditional wholesale distribution for extended-release formulations. This channel concentration is most advanced in Catalonia and Île-de-France, where public health system integration enables direct manufacturer-to-hospital contracting.
Europe Biguanide Market Segmentation
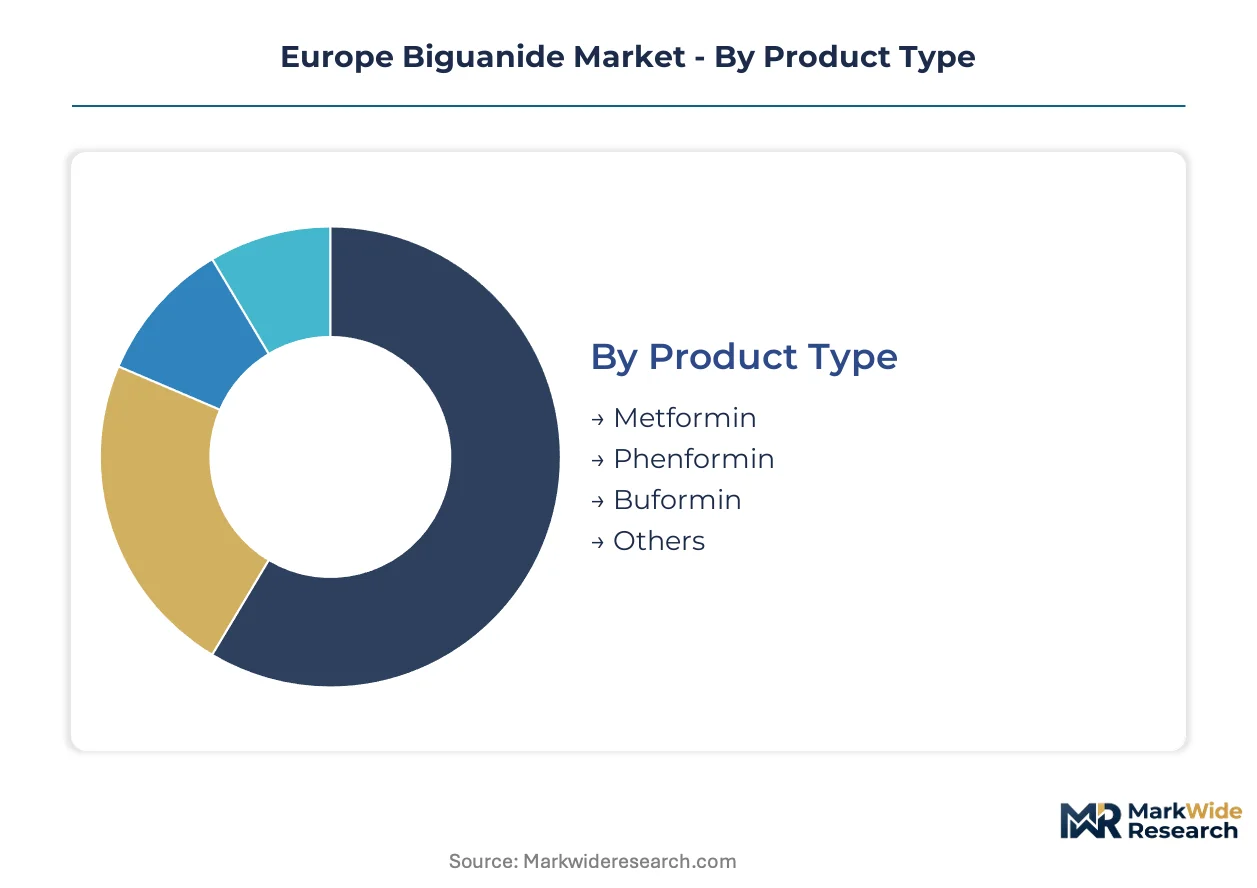
Biguanide market segmentation in Europe tracks divergent regulatory pathways and procurement economics across therapeutic applications. Each dimension carries distinct EMA certification requirements and hospital formulary positioning logic that shapes manufacturer strategy.
Product Type:
EMA marketing authorization complexity varies sharply across this category, with legacy molecules facing nitrosamine retesting burdens while established therapies maintain grandfathered status.
- Metformin:The guanide-derived biguanide dominates European prescribing as first-line type 2 diabetes therapy. German hospital procurement concentrates volume demand around extended-release hydrochloride salts, with REACH registration for dimethylamine feedstock creating compliance differentiation among API suppliers.
- Phenformin:Withdrawn from most European markets due to lactic acidosis risk, this segment persists only in specialized research applications and legacy compassionate-use protocols. Italian regulatory archives retain manufacturing specifications for historical reference standards.
- Buformin:Limited clinical presence restricted to specific Eastern European markets where national formularies maintain older biguanide approvals. Romanian hospital procurement occasionally sources this molecule for cost-sensitive patient populations.
- Others:Emerging biguanide derivatives and investigational compounds awaiting EMA scientific advice. French clinical trial networks sponsor early-phase programs exploring novel guanide modifications.
Leading the category by volume: Metformin. Growing fastest: Investigational derivatives in French-sponsored trials.
Application:
Prescriber economics and reimbursement tiers separate chronic disease management from emerging off-label territories across European health systems.
- Type 2 Diabetes:Core therapeutic indication anchoring national reimbursement lists. Spanish regional health services consolidate metformin purchasing through centralized consortia, with Andalusia and Catalonia driving volume concentration.
- Polycystic Ovary Syndrome:Off-label reproductive endocrinology application deepening clinical validation. Italian gynecology clinics in Lombardy and Emilia-Romagna expand prescriber adoption faster than diabetology growth rates.
- Weight Management:Adjunctive obesity therapy gaining traction in integrated metabolic clinics. Netherlands hospital networks pilot combination protocols with GLP-1 agonists.
- Cardiovascular Health:Cardioprotective biguanide positioning in heart failure populations. Bristol-Myers Squibb anchors this segment through fixed-dose combination development.
Dominant by revenue: Type 2 Diabetes. Steepest expansion trajectory: Polycystic Ovary Syndrome.
Formulation:
Manufacturing technology intensity and cold-chain requirements fragment competitive positioning across delivery platforms.
- Tablets:Immediate-release compression technology remains cost baseline for generic substitution. Polish pharmaceutical manufacturing clusters specialize in high-volume tablet production for Central European distribution.
- Extended-Release Capsules:Osmotic pump and polymer matrix systems command premium hospital formulary placement. German pharmacies specify these formulations for elderly populations requiring reduced dosing frequency.
- Liquid Formulations:Pediatric and dysphagia-focused delivery systems with specialized stability requirements. Belgian compounding pharmacies maintain regional production capacity.
- Powders:Bulk active pharmaceutical ingredient and research-grade supply for clinical manufacturing. Swiss chemical suppliers dominate high-purity powder specifications.
Highest margin concentration: Extended-Release Capsules. Fastest volume growth: Liquid Formulations.
End User:
Procurement sophistication and tender complexity escalate from retail pharmacy through hospital system integration.
- Hospitals:Centralized purchasing consortia in France and Spain negotiate multi-year framework agreements. Île-de-France and Catalonia public health systems lead direct manufacturer contracting.
- Clinics:Outpatient specialty practices with formulary autonomy in diabetes and endocrinology. Italian clinic networks in northern regions consolidate purchasing through regional cooperatives.
- Pharmacies:Retail dispensing with generic substitution incentives varying by national reimbursement policy. German pharmacy chains leverage volume for preferential pricing.
- Homecare:Long-term therapy delivery for stable chronic patients. Netherlands home nursing services integrate biguanide distribution into diabetes management protocols.
Largest volume channel: Hospitals. Expanding most quickly: Homecare integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European biguanide manufacturing concentrates in pharmaceutical special-economic zones offering R&D tax credits and accelerated EMA approval pathways, with production clustering around established API synthesis corridors in Germany, France, and Italy.
Germany
Hospital procurement consortia in North Rhine-Westphalia and Bavaria consolidate extended-release metformin purchasing through multi-year framework agreements. REACH registration requirements for dimethylamine feedstock create compliance differentiation among API suppliers. The Frankfurt-Rhine-Main pharmaceutical corridor anchors formulation manufacturing for Central European distribution.
France
Île-de-France public health systems pioneer direct manufacturer-to-hospital contracting for osmotic pump formulations. ANSM enforces nitrosamine impurity thresholds through tightened batch testing protocols. Lyon-based polymer matrix specialists supply modified-release technologies to regional pharmacy cooperatives.
Italy
Lombardy and Emilia-Romagna gynecology clinics expand metformin prescribing for polycystic ovary syndrome faster than diabetology growth rates. ECHA registration deadlines force API manufacturers to validate biodegradation pathways for Mediterranean watershed discharge. Milan-Turin pharmaceutical clusters concentrate effluent-sensitive production.
Spain
Andalusia and Catalonia regional health services consolidate metformin purchasing through centralized consortia. The EU Green Deal pressures suppliers to decarbonize synthesis processes and validate sustainable solvent recovery systems. Barcelona hospital networks pilot fixed-dose cardiovascular combination protocols.
Poland
Underpenetrated hospital procurement markets in Warsaw and Kraków offer volume growth as healthcare infrastructure modernizes. Polish pharmaceutical manufacturing clusters specialize in high-volume immediate-release tablet production. Central European distribution hubs leverage cost positioning for Eastern European market access.
Europe Biguanide Market Competitive Landscape
Top-tier vendors anchor hospital formulary positions, while mid-tier generic manufacturers compete on immediate-release volume and regional tender participation. The European biguanide market structures around three strategic archetypes: integrated API-to-formulation houses, pure-play generic distributors, and cardiovascular combination specialists. Competitive moves concentrate on backward integration into dimethylamine feedstock production and EMA marketing authorization for modified-release salt forms.
Among Israel-based pharmaceutical manufacturers, Teva leverages its European manufacturing footprint to sustain supply continuity for generic metformin across Germany and France. Sanofi and Bristol-Myers Squibb occupy positions on the differentiated formulation tier, with the former competing through extended-release portfolio depth and the latter specializing in cardiovascular combination therapies that extend relevance beyond standalone diabetes applications. These three exemplify the competitive tension between volume-driven generic substitution and premium positioning through delivery technology.
| Leading Market Players |
|---|
| Teva |
| Takeda |
| Merck |
| Sanofi |
| Bristol-Myers Squibb |
| AstraZeneca |
| Boehringer Ingelheim |
| GlaxoSmithKline |
| Merck and Co. |
| Others |
Supply & Pricing Matrix
Hospital formulary consolidation around extended-release metformin specifications in Germany and France forces API suppliers to retool synthesis lines and absorb compliance costs, compressing margins for immediate-release specialists while rewarding manufacturers with validated polymer matrix capabilities.
Pricing Analysis
Short lead-time premiums for osmotic pump formulations now separate German hospital procurement tiers from standard matrix tablet supply. Three-tier pricing structure across premium, standard, and economy levels tracks EMA certification status and REACH registration completeness. Cost compression in immediate-release tablets is intensifying because Polish manufacturing clusters exploit scale economies for Central European tender participation. Retail pharmacy chains in Spain exhibit highest price sensitivity, while French public health systems prioritize formulation performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Indian API manufacturers supplying dimethylamine-derived metformin hydrochloride to European formulation houses. Production gravity centers on India, China, and Switzerland for active pharmaceutical ingredients, with German and Italian sites handling downstream formulation. Feedstock costs hinge on natural gas pricing volatility and petrochemical derivative availability. Tariff exposure from REACH chemical safety dossier re-registration threatens margin stability for mid-tier suppliers. Distribution runs through regional pharmacy cooperatives in Catalonia and Île-de-France, displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European biguanide supply is consolidating around manufacturers with captive API production and validated extended-release technologies, as EMA nitrosamine guidance and REACH compliance costs force subscale players toward exit.
For Market Incumbents: Extend formulation differentiation through backward integration into dimethylamine feedstock production and accelerated EMA marketing authorization for novel salt forms. Secure multi-year framework agreements with French and Spanish hospital consortia before tender windows close. Invest in real-time release testing capabilities to preempt competitors on quality assurance positioning. For New Entrants and Emerging Players: EU Green Deal solvent recovery mandates in Italy and Spain open a window for sustainable manufacturing specialists to capture preferential supplier status in public tenders. Target underpenetrated Central European hospital procurement in Poland and Romania with cost-optimized immediate-release tablet supply. Pursue fixed-dose cardiovascular combination development partnerships with established cardiovascular franchises. For Investors and Strategic Acquirers: The window for entry favors mid-scale API-to-formulation houses with incomplete REACH registration portfolios but validated manufacturing infrastructure. Long-term viability rests on securing backward integration into petrochemical feedstocks and navigating EMA extended-release approval pathways. Watch for inflection signals in EMA guidance on nitrosamine impurity thresholds that would trigger forced process revalidation across the supplier base.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dimethylamine Feedstock | Captive supply of petrochemical-derived starting material insulates margin from natural gas volatility. |
| EMA Extended-Release Marketing Authorization | Streamlined approval for osmotic pump formulations secures premium hospital formulary placement. |
| REACH Chemical Safety Dossier Completion | Full ECHA registration validates biodegradation pathways for Mediterranean watershed discharge compliance. |
| Fixed-Dose Cardiovascular Combination Development | Convergence with SGLT2 inhibitor platforms extends therapeutic relevance beyond diabetes management. |
| Real-Time Release Testing Implementation | Process analytical technology integration enables batch release without laboratory verification delays. |
Research Methodology
Independent corroboration across EMA regulatory filings, hospital procurement databases, and REACH registration records underwrites the qualitative findings presented in this study. Primary interviews with regulatory affairs leads, hospital formulary directors, API manufacturing executives, and pharmacy cooperative procurement managers combined with secondary validation from ECHA chemical safety dossiers, ANSM batch testing protocols, and regional health service tender documents. Bottom-up volume modeling and top-down market sizing triangulated across the analysis window.
Historical reference periods anchored the projection horizon to documented EMA approval timelines and hospital procurement cycle patterns. Segmentation modeling tracked product type, application, formulation technology, and end-user channel across the European regulatory cluster. CAGRs derived from volume-weighted growth trajectories and pricing evolution assumptions. Forecast inputs incorporated REACH registration deadline impacts and EU Green Deal manufacturing transition costs.
Caveats apply where EMA nitrosamine guidance revisions, natural gas feedstock price shocks, or hospital procurement consortium restructuring could materially shift the outlook. Forecasts reflect documented assumptions about regulatory timeline adherence and manufacturing capacity expansion patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Potassium Hydrogen Fluoride Market
Chemicals
Cumene Market
Chemicals
Global Aluminum Hydroxide Market
Chemicals
Latin America Construction Chemicals Market
Chemicals
Automotive Appearance Chemicals Market
Chemicals
Egypt Acidulants Market
Chemicals
Global Tetraacetylethylenediamine (TAED) Market
Chemicals
Benzophenone (Oxybenzone) Market
Chemicals
N-Propanol Market
Chemicals
Hexachloroethane Market
Chemicals
Acrylic Acids and Esters Market
Chemicals
Formalin Market
Chemicals
4-Dichlorodiphenyl Sulfone (DCDPS) Market
Chemicals
Global Monochloroacetic Acid Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Peroxyacetic Acid Market