
 Phenothiazine Market | 2026-2036
Phenothiazine Market Size, Share, and Industry Trends Forecast 2026-2036
Phenothiazine Market Analytics
Modular packaging of phenothiazine injectables with pre-filled syringe formats is pivoting procurement decisions toward convenience-driven configurations. Janssen Pharmaceuticals leverages its long-acting injectable expertise to sustain premium positioning in psychiatric care. Hikma Pharmaceuticals anchors its competitive stance through vertical integration into active pharmaceutical ingredient supply. Sun Pharmaceutical Industries specializes in cost-efficient tablet formulations that dominate emerging market tenders.
Phenothiazine denotes a tricyclic heterocyclic compound containing sulfur and nitrogen atoms in a fused ring system, primarily synthesized through cyclization of diphenylamine derivatives with sulfur under catalytic conditions. The molecule functions as a dopamine antagonist, serving as the pharmacophore for first-generation antipsychotic and antiemetic therapeutics. Chlorpromazine and fluphenazine formulations lead the product type landscape, with the former representing a mature revenue base and the latter capturing faster growth in long-acting depot applications. Injectable formulations command superior margins compared to oral tablets, while psychiatry applications concentrate the largest patient volume and veterinary medicine represents an expanding off-label frontier.
The U.S. FDA bioequivalence requirements and EMA's MDR compliance pathways for sterile injectables shape product development timelines and market access barriers for phenothiazine manufacturers. India's CDSCO and Germany's BfArM enforce divergent stability testing protocols that fragment registration strategies across jurisdictions. Stakeholders must monitor evolving pharmacovigilance mandates for first-generation antipsychotics as regulators reassess extrapyramidal side-effect risk profiles.
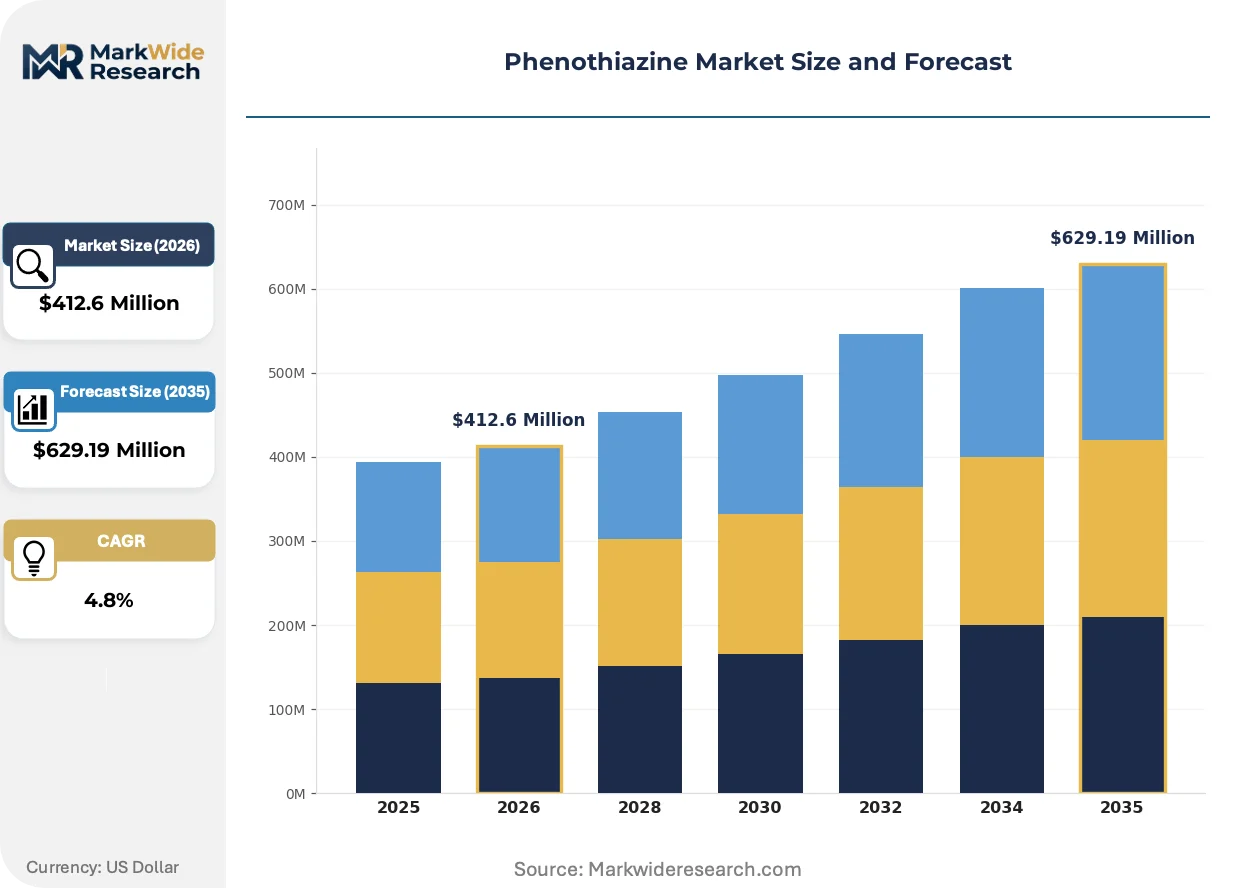
Market Dynamics
Long-acting injectable formulations are compressing dosing frequency and reshaping adherence economics across psychiatric care systems, while FDA bioequivalence tightening forces generic manufacturers toward complex formulation investments.
Growth Catalysts
- EMA MDR compliance for sterile injectables:European regulatory harmonization accelerates centralized market access for depot formulations across Germany, France, and Italy.
- Hospital formulary consolidation:Health system procurement centralization favors single-source long-acting antipsychotic contracts with bundled adherence monitoring.
- India's CDSCO streamlined ANDA pathways:Domestic manufacturers leverage accelerated review timelines to capture tender volumes in Southeast Asian export markets.
Market Restraints
- Thioether raw material concentration:Sulfur-containing intermediates for phenothiazine cyclization concentrate among Chinese specialty chemical suppliers, exposing margins to input volatility.
- Extrapyramidal side-effect liability:First-generation antipsychotic safety profiles face renewed pharmacovigilance scrutiny from FDA and EMA, constraining prescriber comfort.
- Second-generation antipsychotic substitution:Atypical alternatives like risperidone and olanzapine displace phenothiazine share in maintenance therapy protocols.
Strategic Opportunities
- Veterinary behavioral medicine expansion:Off-label phenothiazine applications in equine and companion animal sedation protocols open margin-rich specialty channels.
- Pre-filled syringe format adoption:Modular packaging configurations reduce reconstitution errors and capture premium positioning in ambulatory care settings.
- India PLI scheme for API manufacturing:Production-linked incentives for active pharmaceutical ingredient domestication support backward integration into phenothiazine precursor supply.
Industry Challenges
- Sterile formulation expertise scarcity:Long-acting injectable manufacturing requires specialized aseptic processing capabilities that concentrate among limited contract development organizations.
- Stability testing protocol fragmentation:Divergent CDSCO, BfArM, and FDA requirements for accelerated degradation studies multiply registration timelines and analytical costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenothiazine Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chlorpromazine, Thioridazine, Perphenazine, Fluphenazine Application: Psychiatry, Antiemetic, Veterinary Medicine, Pain Management Formulation: Tablets, Injectable, Liquid, Capsules End User: Hospitals, Clinics, Research Institutions, Pharmacies |
| Companies Covered | Janssen Pharmaceuticals, Hikma Pharmaceuticals, Fresenius Kabi, Novartis, AstraZeneca, Sun Pharmaceutical Industries, Teva Pharmaceutical Industries, Syensqo, KANTO CHEMICAL CO.,INC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenothiazine Market Evolving Landscape
Formulation science and regulatory science are converging to redefine competitive advantage in psychiatric therapeutics, with delivery mechanism innovation outpacing molecular discovery.
Lipid nanoparticle encapsulation of phenothiazine active pharmaceutical ingredients is consolidating the long-acting injectable landscape by enabling extended-release profiles beyond traditional ester depot technologies. Hospital systems in Germany and the United Kingdom are adopting these formulations to reduce relapse-driven readmissions. The technology is consolidating procurement decisions around fewer suppliers capable of nanoscale manufacturing.
REACH authorization requirements for sulfur-containing intermediates are tightening supply chain documentation obligations for European phenothiazine manufacturers. The regulation forces reformulation of legacy synthesis routes toward greener catalytic conditions. German and Swiss producers are responding by investing in continuous flow chemistry platforms to reduce solvent volumes and streamline compliance.
Adherence monitoring integration is reshaping psychiatric medication contracting, with health systems demanding real-world outcome data alongside product supply. Injectable formats with embedded dosing verification are displacing oral tablets in Medicaid-managed care tenders. This pattern concentrates most visibly in United States state-level behavioral health carve-outs where pay-for-performance metrics dominate vendor selection.
Phenothiazine Market Segmentation
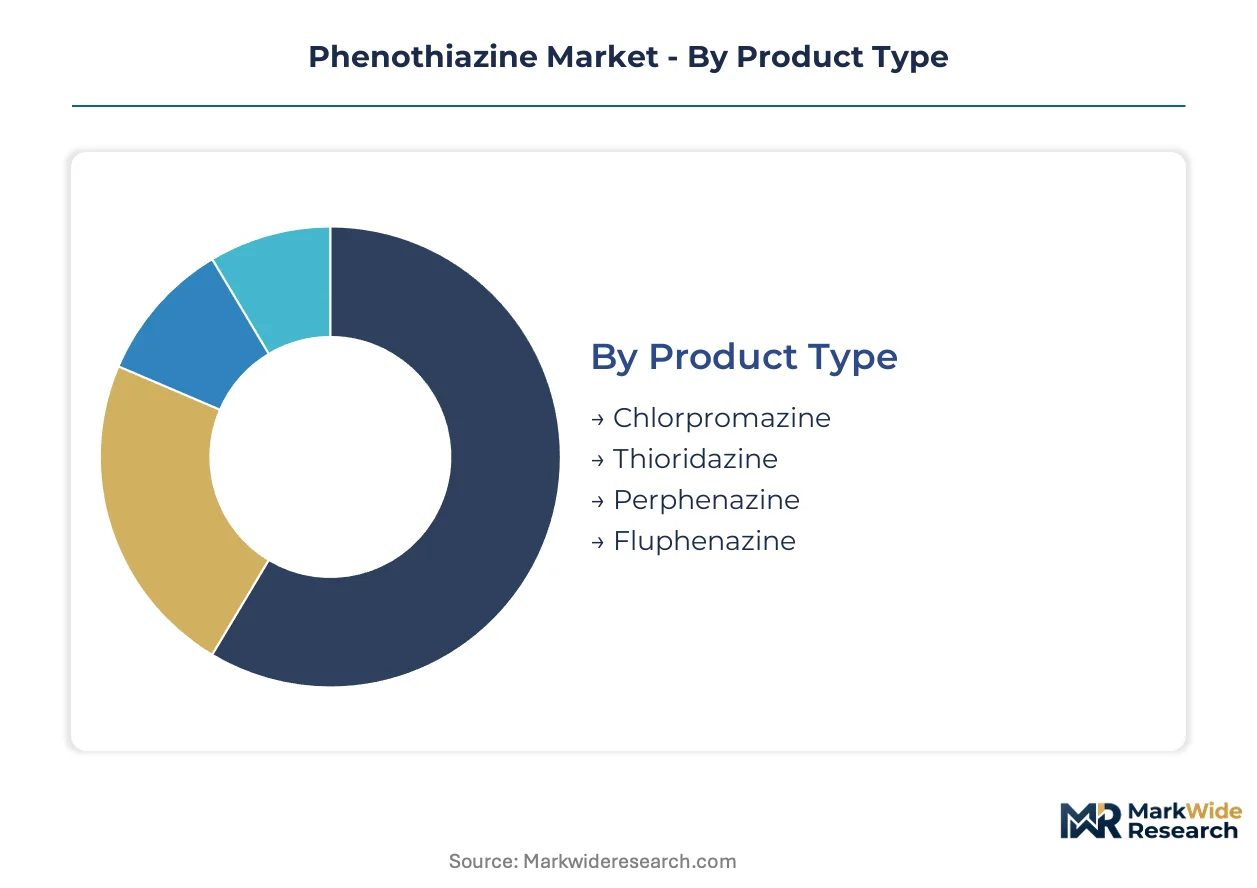
Phenothiazine market segmentation reveals distinct value capture patterns across molecular variants and delivery formats. Psychiatry applications concentrate revenue while formulation innovation determines margin stratification across hospital procurement tiers.
Product Type:
Standalone phenothiazine molecules command dedicated manufacturing lines, while derivative compounds embed into combination therapies with tighter supply integration.
- Chlorpromazine:The foundational dimethylamine-substituted phenothiazine established first-generation antipsychotic protocols. Indian CDSCO-registered manufacturers dominate tender volumes for public hospital systems across Southeast Asia.
- Fluphenazine:Long-acting decanoate and enanthate esters enable depot injection schedules extending to two-week intervals. Germany's BfArM has accelerated approvals for these formulations as adherence economics reshape psychiatric care contracting.
- Thioridazine:Piperidine-substituted variant with pronounced anticholinergic properties retained for treatment-resistant schizophrenia cases.
- Perphenazine:Piperazinyl derivative balancing extrapyramidal liability with efficacy in acute psychotic episodes.
Chlorpromazine leads volumes today; fluphenazine is gaining share fastest.
Application:
Cost tier stratification separates acute intervention protocols from maintenance therapy economics across reimbursement systems.
- Psychiatry:Schizophrenia and bipolar disorder management concentrates the largest patient population. Medicaid-managed care carve-outs in the United States increasingly mandate long-acting injectable first-line therapy.
- Antiemetic:Postoperative and chemotherapy-induced nausea prophylaxis represents mature demand with generic substitution pressure.
- Veterinary Medicine:Equine sedation and companion animal behavioral protocols command premium pricing through specialty distribution.
- Pain Management:Adjunctive use in chronic neuropathic conditions faces displacement by newer analgesic classes.
Psychiatry anchors revenue today; veterinary medicine is expanding most quickly.
Formulation:
Margin structure inverts between high-volume oral solids and low-volume sterile injectables requiring aseptic manufacturing infrastructure.
- Injectable:Depot suspensions and solutions demand specialized lyophilization and particle engineering capabilities. EMA MDR compliance timelines favor established European sterile manufacturers.
- Tablets:Immediate-release and extended-release oral solids dominate emerging market tenders through cost-efficient scale production.
- Liquid:Oral solutions serve pediatric and geriatric populations with swallowing difficulties.
- Capsules:Encapsulated formulations offer taste masking and modified release profiles for specific therapeutic indices.
Tablets lead volumes today; injectable is climbing the fastest.
End User:
Customer type determines procurement sophistication, with centralized hospital purchasing diverging from fragmented retail pharmacy channels.
- Hospitals:Inpatient psychiatric units and emergency departments drive formulary decisions through therapeutic committee governance. Health system consolidation in the United States compresses vendor lists to single-source long-acting antipsychotic contracts.
- Clinics:Outpatient mental health centers prioritize medication adherence monitoring alongside product supply.
- Research Institutions:Academic medical centers and contract research organizations source reference standards and investigational compounds.
- Pharmacies:Retail and specialty pharmacy channels handle maintenance therapy dispensing with varying prior authorization requirements.
Hospitals lead volumes today; clinics are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phenothiazine chemistry originated in European dye laboratories during the late nineteenth century, with industrial-scale synthesis later established by German and Swiss pharmaceutical houses. Manufacturing gravity now distributes across three continents as regulatory divergence shapes regional specialization patterns.
United States
Hospital formulary consolidation and Medicaid-managed care carve-outs drive demand for long-acting injectable formats. FDA bioequivalence tightening for generic antipsychotics extends product development timelines and elevates analytical investment requirements. The Philadelphia-Camden corridor hosts specialized contract manufacturers serving sterile formulation needs.
Germany
BfArM accelerated approval pathways for depot antipsychotics align psychiatric contracting with adherence economics. EMA MDR compliance for sterile injectables positions German manufacturers for centralized European market access. The Rhine-Main biotechnology cluster concentrates lipid nanoparticle engineering capabilities for next-generation extended-release formulations.
India
Domestic tender volumes for public hospital systems across Southeast Asia anchor chlorpromazine tablet production. CDSCO streamlined ANDA pathways enable accelerated review timelines for export-oriented manufacturers. The Hyderabad-Visakhapatnam pharmaceutical belt specializes in cost-efficient scale production of first-generation antipsychotic APIs.
Japan
PMDA pharmacovigilance protocols for extrapyramidal side-effects constrain first-generation antipsychotic prescribing patterns. METI industrial policy supports continuous flow chemistry adoption to reduce synthesis environmental footprint. The Kansai chemical manufacturing corridor hosts phenothiazine intermediate producers serving regional formulation demand.
Switzerland
Swissmedic stability testing requirements for sterile parenterals establish quality benchmarks for European export markets. REACH authorization obligations for sulfur-containing intermediates drive green catalytic process investment. The Basel pharmaceutical cluster integrates phenothiazine chemistry expertise with contract development organization infrastructure.
Phenothiazine Market Competitive Landscape
The competitive structure tilts toward vertically integrated pharmaceutical conglomerates with captive API supply and specialized sterile manufacturing capabilities. Tiered positioning separates long-acting injectable specialists commanding premium hospital contracts from cost-efficient tablet producers dominating emerging market tenders. Three archetypes dominate: research-origin innovators with depot formulation heritage, emerging market scale manufacturers with backward-integrated chemistry, and sterile-focused contract developers serving niche compliance requirements. Consolidation pressure intensifies through hospital procurement centralization and regulatory harmonization demands.
Among research-origin innovators, Janssen Pharmaceuticals exemplifies the long-acting injectable specialist archetype through its psychiatric care franchise positioning. Hikma Pharmaceuticals occupies the vertically integrated generic manufacturer tier with captive API capabilities and multi-jurisdictional registration expertise. Sun Pharmaceutical Industries represents the emerging market scale producer archetype, anchoring cost-efficient tablet supply for tender-driven psychiatric medication programs across South and Southeast Asia.
| Leading Market Players |
|---|
| Janssen Pharmaceuticals |
| Hikma Pharmaceuticals |
| Fresenius Kabi |
| Novartis |
| AstraZeneca |
| Sun Pharmaceutical Industries |
| Teva Pharmaceutical Industries |
| Syensqo |
| KANTO CHEMICAL CO.,INC. |
| Others |
Value Network & Pricing Analysis
Sulfur-containing thioether intermediates for phenothiazine cyclization originate with Chinese specialty chemical suppliers, then flow through Indian API manufacturers into three-tier pricing structures across German hospital tenders, U.S. Medicaid carve-outs, and Southeast Asian public procurement. This input concentration shapes margin compression dynamics downstream.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates lipid nanoparticle depot formulations from conventional ester depots and oral tablets. Premium positioning rests on EMA MDR certification and aseptic manufacturing capability, while price erosion runs through chlorpromazine tablet tenders where Indian CDSCO-registered producers compete on volume scale. Hospital procurement committees exhibit lowest price sensitivity for long-acting injectables with embedded adherence monitoring; retail pharmacy channels face highest sensitivity due to generic substitution protocols.
Supply Chain Analysis
Reverse-logistics flows for phenothiazine products remain minimal given controlled-substance regulations and single-patient dispensing protocols, though veterinary applications generate some refillable vial returns through specialty distributors. Manufacturing gravity centers on China for sulfur intermediates, India for API synthesis, and Germany for sterile formulation finishing. The chain draws from diphenylamine derivatives, catalytic sulfur reagents, and lyophilization equipment. Single-source vulnerability concentrates in Chinese thioether supply. Distribution runs through hospital GPOs in the United States, centralized tenders in Germany, and government procurement in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between India's CDSCO-accelerated ANDA pathways and the FDA's tightened bioequivalence requirements, with cost differentials of 40-60% on equivalent API production.
For Market Incumbents: Deploy long-acting injectable capacity expansion in the Rhine-Main biotechnology cluster to capture EMA MDR-compliant European hospital consolidation. Secure captive thioether supply through joint ventures with Chinese specialty chemical houses to defend against input volatility. Counter second-generation antipsychotic substitution by bundling adherence monitoring with depot formulations in U.S. Medicaid-managed care contracts. For New Entrants and Emerging Players: Begin with veterinary behavioral medicine applications in North American equine and companion animal channels, where regulatory barriers sit lower and pricing premiums exceed human pharmaceutical norms. Target pre-filled syringe format development for ambulatory psychiatric clinics in Germany and the United Kingdom. Partner with contract development organizations possessing sterile aseptic processing capabilities rather than building captive manufacturing. For Investors and Strategic Acquirers: Consolidation pressure builds where sterile formulation expertise scarcity intersects with hospital procurement centralization, favoring acquisition of mid-scale European CDMOs with EMA MDR track records. Frame long-term viability around the 5-10 year window for first-generation antipsychotic maintenance in treatment-resistant populations and veterinary off-label expansion. Monitor FDA pharmacovigilance bulletins on extrapyramidal side-effects as the critical signal for prescriber sentiment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Lipid Nanoparticle Formulation Development | Extends depot release profiles beyond traditional ester technologies for German hospital systems. |
| Backward Integration into Thioether Supply | Reduces exposure to Chinese intermediate price volatility through captive sulfur chemistry. |
| Pre-filled Syringe Format Launch | Captures premium positioning in U.S. ambulatory psychiatric clinics with reconstitution-error reduction. |
| Veterinary Behavioral Medicine Expansion | Opens margin-rich specialty channels for equine sedation and companion animal protocols. |
| EMA MDR Compliance Investment | Enables centralized European market access for sterile injectable depot formulations. |
Research Methodology
Bottom-up psychiatric application modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with drug development executives at research-origin innovators, regulatory affairs leads at emerging market manufacturers, hospital formulary directors in Germany and the United States, and payer access specialists at Medicaid-managed care organizations supplied forward-looking demand parameters. Secondary validation drew from FDA Orange Book filings, EMA centralized procedure assessments, CDSCO approval databases, and hospital procurement contract disclosures. This dual approach enabled triangulation between patient-volume estimates and manufacturing capacity utilization.
Historical trendline analysis of chlorpromazine and fluphenazine formulation volumes established baseline growth patterns across the projection horizon. The forecast framework segments by molecular variant, dosage form, administration route, and regional regulatory cluster. CAGRs derived from regression analysis of tender award volumes, prescription dispensing data, and API trade flows. Industry-specific inputs include BfArM approval timelines for depot formulations, CDSCO ANDA review acceleration metrics, and FDA bioequivalence study complexity indices.
Several conditions sit outside the modeled scope, including potential FDA reclassification of first-generation antipsychotics, REACH authorization disruptions for sulfur intermediates, and breakthrough therapy designations for competing atypical compounds. Forecasts reflect assumptions about regulatory stability and prescriber protocol continuity. Practitioners should monitor EMA pharmacovigilance reassessments and Indian PLI scheme implementation pace for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Bronopol Market
Chemicals
P-Hydroxybenzoic Acid (PHBA) Market
Chemicals
Global Diacetone Alcohol Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
Pinoxaden Market
Chemicals
Global Wood Preservative Chemicals and Coatings Active Ingredients Market
Chemicals
Global Calcium Hypochlorite Market
Chemicals
Phosphotungstic Acid Market
Chemicals
P-Ethylphenol Market
Chemicals
Methanol Market
Chemicals
Global Anhydrous Aluminum Chloride Market
Chemicals
Muriatic Acid Market
Chemicals
Periodic Acid Market
Chemicals
Isooctyl Alcohol Market
Chemicals
Asia-Pacific Construction Chemicals Market
Chemicals
Hexafluorosilicic Acid Market