
 Global Gas Pressure Regulator Market | 2026-2036
Global Gas Pressure Regulator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gas Pressure Regulator Market Analysis
The gas pressure regulator market is shifting along a widening fault line between precision-engineered premium units and standardized commodity hardware. Emerson Electric Co. leverages its process automation portfolio to dominate high-specification industrial installations where accuracy tolerances tighten annually. Rotarex S.A. anchors its position through specialized cryogenic and medical gas regulation expertise that commands durable margin pools.
A gas pressure regulator is a mechanically or electronically actuated control device that reduces variable inlet pressure to a stable, predetermined outlet pressure, typically achieving accuracy within ±0.5% to ±2% of setpoint depending on diaphragm design and spring calibration. These devices serve as critical safety and efficiency components across natural gas distribution, industrial process control, and medical oxygen delivery systems. Single-stage regulators occupy the volume base in residential and light commercial applications where cost sensitivity dominates procurement, while electronic and pilot-operated variants capture expanding share in power generation and large-scale manufacturing where remote monitoring and rapid response cycles justify premium positioning. Dual-stage configurations sustain relevance in laboratory and semiconductor environments where ultra-stable delivery protects process yields.
The EPA in the United States enforces methane emission thresholds that directly shape seal material specifications and testing protocols for distribution-grade regulators. ECHA's REACH restrictions in Europe limit elastomer chemistries available for diaphragm construction, compelling reformulation investments across the supply base. China's GB standards and MIIT industrial safety directives impose mandatory certification cycles that filter non-compliant imports from infrastructure tenders. Stakeholders must monitor how hydrogen compatibility certifications reshape qualification requirements before committing to long-term capacity plans.
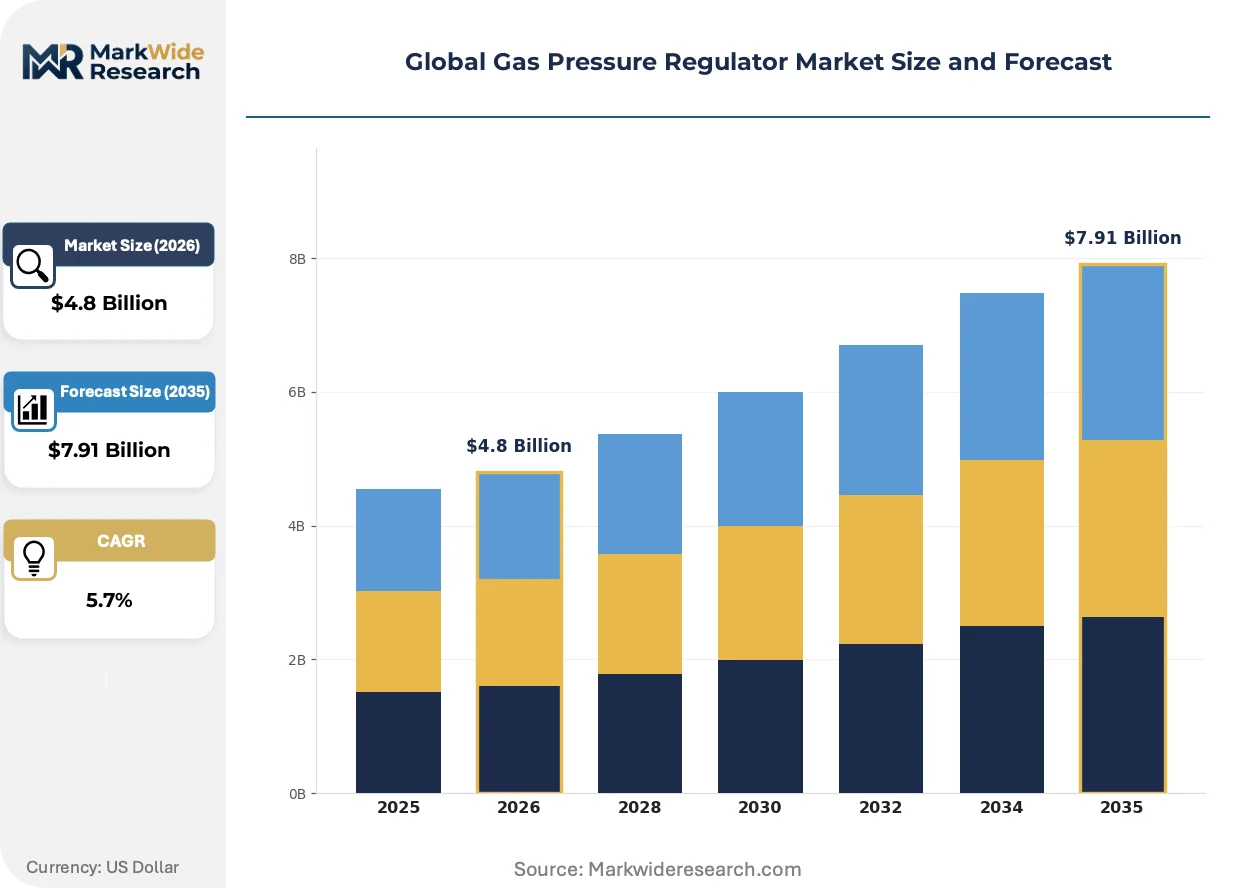
Market Dynamics
Industrial gas distribution networks are expanding adoption of precision regulation equipment as hydrogen blending trials and methane emission mandates force infrastructure upgrades across pipeline systems.
Growth Catalysts
- EU F-Gas Regulation:Tightening leakage standards accelerate material upgrades to low-emission seal technologies across European industrial gas networks.
- China pipeline infrastructure renewal:MIIT industrial safety directives and GB standards drive mandatory certification cycles that filter non-compliant imports from infrastructure tenders.
- Hydrogen compatibility certifications:Hydrogen blending trials in Germany, the United States, and China intensify procurement of next-generation regulator systems.
Market Restraints
- Elastomer input cost volatility:ECHA REACH restrictions limit diaphragm chemistries available for construction, compelling reformulation investments.
- Supply concentration in precision machining:High-specification diaphragm and spring production clusters in Germany and Japan create bottlenecks for tier-one procurement.
- Technical limitation in cryogenic sealing:Ultra-low temperature gas applications face material brittleness thresholds that standard fluorocarbon compounds cannot breach.
Strategic Opportunities
- Underpenetrated medical oxygen delivery:India and Brazil present expansion potential as hospital gas infrastructure modernizes and homecare oxygen systems proliferate.
- Remote monitoring convergence:Electronic actuation and IIoT sensor integration create premium positioning in power generation and large-scale manufacturing.
- US IRA clean hydrogen incentives:Production tax credits accelerate hydrogen hub development, pulling demand for compatible high-pressure regulation equipment.
Industry Challenges
- Certification timeline compression:China's GB standards and MIIT directives impose mandatory recertification cycles that strain product development bandwidth.
- Integration complexity with legacy SCADA:Pilot-operated electronic regulators face protocol friction when retrofitting into existing natural gas distribution control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gas Pressure Regulator Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-stage, Dual-stage, Electronic, Pilot-operated Application: Industrial, Residential, Commercial, Power Generation End User: Utilities, Manufacturing, Oil & Gas, Food Service Installation Type: Indoor, Outdoor, Integrated, Standalone |
| Companies Covered | Air Products and Chemicals Inc., Rotarex S.A., Emerson Electric Co., Parker Hannifin Corporation, Cavagna Group S.p.A, The Linde Group, Honeywell Process Solutions, Swagelok Company, Air Liquide S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gas Pressure Regulator Market Emerging Trajectories
Equipment architecture is fragmenting into configurable subsystems as end-users demand field-adaptable pressure control without full unit replacement.
Smart diaphragm assemblies with embedded pressure sensors and wireless telemetry capability are modularizing regulator maintenance workflows. Oil and gas midstream operators and chemical process plants adopt these units fastest, cutting field service intervals by half. The technology is modularizing supplier revenue models toward predictive service subscriptions rather than transactional hardware sales.
EPA methane emission thresholds directly shape seal material specifications and testing protocols for distribution-grade regulators in the United States. Manufacturers must validate elastomer permeation rates under cyclic pressure loading to retain market access. The rule compresses qualification timelines for new compound introductions, favoring incumbents with established testing infrastructure.
Asset-light rental and performance-guarantee contracts displace capital purchase in North American industrial gas procurement. Midstream energy firms and semiconductor fabs now specify uptime commitments rather than unit specifications, transferring operational risk to OEM service arms. This shift concentrates most visibly in Texas and California hydrogen pilot projects where technology uncertainty delays ownership commitments.
Global Gas Pressure Regulator Market Segmentation
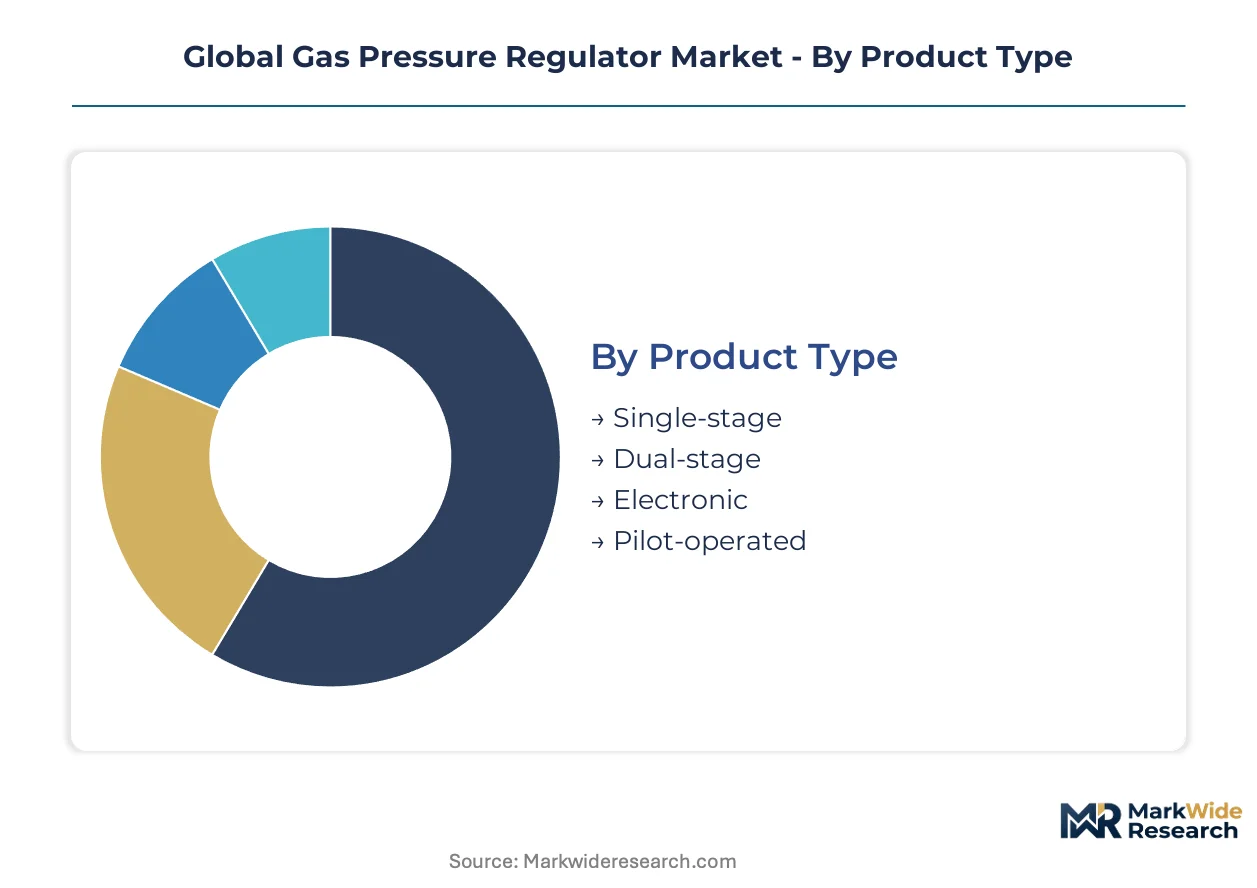
Product architecture in gas pressure regulation fragments across precision tiers and integration depths. Procurement patterns diverge sharply between standalone field installations and embedded process control systems.
Product Type:
Single-stage units dominate standalone outdoor installations where cost sensitivity outweighs precision requirements. Electronic and pilot-operated variants embed into automated process architectures.
- Single-stage:Diaphragm-spring mechanisms reduce variable inlet pressure in one reduction step, achieving ±2% accuracy tolerance. Residential and light commercial procurement in China and India concentrates here, driven by pipeline infrastructure renewal mandates and cost-constrained utility tenders.
- Electronic:Microprocessor-controlled actuation with embedded pressure transducers enables ±0.5% setpoint accuracy and remote telemetry integration. Power generation and semiconductor manufacturing in Germany and the United States pull these units for SCADA-compatible process control.
- Dual-stage:Cascaded diaphragm chambers deliver ultra-stable outlet pressure for laboratory and medical oxygen delivery.
- Pilot-operated:Hydraulic amplification mechanisms handle high-flow industrial distribution with rapid response cycles.
Volume placements concentrate in Single-stage; the faster expansion belongs to Electronic.
Application:
Cost tier stratification separates precision-engineered process control from standardized distribution hardware. Margin pools concentrate where certification complexity and technical performance requirements escalate.
- Industrial:Process control installations demand pilot-operated and electronic variants with hydrogen compatibility certifications. Chemical manufacturing and refining complexes in Germany and the United States specify these for methane emission compliance under EPA and EU F-Gas Regulation thresholds.
- Power Generation:Combined-cycle and hydrogen-ready turbine facilities require high-accuracy regulation for fuel gas conditioning. US IRA clean hydrogen incentives accelerate procurement of compatible high-pressure equipment for hub development projects.
- Residential:Single-stage units serve natural gas distribution to households through utility meter sets.
- Commercial:Restaurant and light manufacturing applications balance precision needs against capital constraints.
Industrial captures the dominant revenue share; Power Generation climbs the fastest as hydrogen blending trials intensify.
End User:
Customer type determines specification intensity and procurement modality. Asset-heavy utilities favor capital purchase; manufacturing and midstream energy increasingly specify performance contracts.
- Utilities:Natural gas distribution operators procure single-stage and pilot-operated regulators for pipeline pressure management. China's MIIT certification cycles and EPA methane rules in the United States reshape material specifications and testing protocols for this segment.
- Oil & Gas:Midstream operators and hydrogen pilot projects in Texas and California specify uptime commitments over unit ownership, transferring operational risk to OEM service arms.
- Manufacturing:Process plants integrate electronic regulators into legacy SCADA architectures with protocol adaptation challenges.
- Food Service:Commercial kitchens deploy compact single-stage units for cooking gas delivery with basic safety shutoff.
Utilities anchor procurement volume; Oil & Gas is gaining share fastest through rental and performance-guarantee contract displacement.
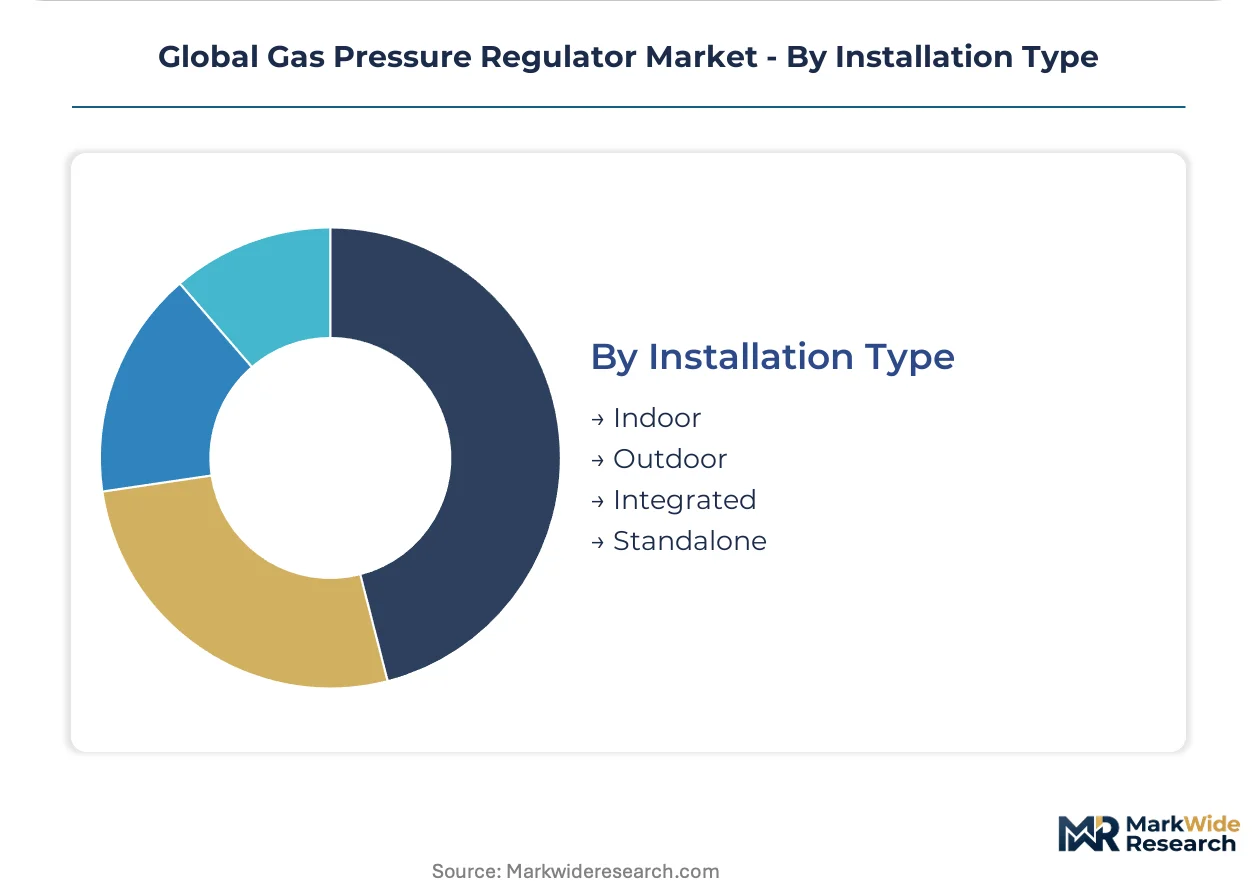
Installation Type:
Physical deployment context shapes environmental sealing requirements and maintenance accessibility. Indoor and integrated configurations command premium positioning against exposed field installations.
- Outdoor:Weather-resistant housings with enhanced elastomer sealing serve pipeline distribution and utility meter applications. EPA methane emission thresholds in the United States and ECHA REACH restrictions in Europe compel material upgrades to low-permeation seal technologies.
- Integrated:Subsystem embedding into skid-mounted process equipment or medical gas manifolds demands compact form factors and standardized port configurations. Semiconductor fabs and hospital infrastructure projects in Japan and South Korea specify these for space-constrained installations.
- Indoor:Controlled-environment installations in manufacturing and laboratory settings reduce sealing complexity.
- Standalone:Field-replaceable units dominate residential and commercial maintenance workflows.
Outdoor placements dominate unit volume; Integrated configurations expand most quickly through modular equipment architecture adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American procurement intensity as hydrogen hub development and pipeline integrity programs concentrate demand for high-pressure regulation equipment. The city's midstream energy corridor hosts pilot projects specifying performance-guarantee contracts over traditional capital purchase. This geographic pattern repeats across three additional national markets where infrastructure renewal and emission mandates reshape procurement.
United States
EPA methane emission thresholds and IRA clean hydrogen production tax credits drive material specification upgrades across Texas and California pilot projects. Distribution utilities face compressed qualification timelines for low-permeation seal compounds. The Permian Basin and Gulf Coast hydrogen corridors concentrate procurement of next-generation high-pressure systems.
Germany
EU F-Gas Regulation leakage standards and hydrogen blending trials in industrial clusters accelerate diaphragm material reformulation investments. The country's precision machining base in Baden-Württemberg and North Rhine-Westphalia supplies tier-one diaphragm and spring components. Chemical manufacturing complexes along the Rhine specify pilot-operated variants for methane compliance.
China
MIIT industrial safety directives and GB standards impose mandatory certification cycles that filter non-compliant imports from infrastructure tenders. Pipeline renewal programs in the Yangtze River Delta and Beijing-Tianjin-Hebei corridor concentrate single-stage unit procurement. State-owned utilities dominate tender volumes for residential distribution networks.
India
Hospital gas infrastructure modernization and homecare oxygen system proliferation create expansion potential for dual-stage medical regulators. The country's national pharmaceutical regulator enforces device safety standards that shape import qualification. Maharashtra and Gujarat industrial corridors drive process control equipment demand from specialty chemical manufacturing.
Japan
Semiconductor fabrication facilities in Kyushu and the Tokyo metropolitan area specify integrated regulator configurations for space-constrained installations. METI industrial safety directives align with international hydrogen compatibility standards. Precision component manufacturing clusters in Nagoya supply high-specification diaphragm assemblies to regional OEMs.
Global Gas Pressure Regulator Market Vendor Landscape
Premium-margin players sit above commodity-margin players across precision tiers, with electronic and pilot-operated variants commanding durable positioning against single-stage hardware. The vendor base organizes into three strategic archetypes: diversified industrial conglomerates with process automation portfolios, specialized gas equipment fabricators with cryogenic expertise, and component-focused precision manufacturers. Competitive moves concentrate on strategic partnerships for hydrogen compatibility certification and geographic expansion through regional distribution agreements.
Within the diversified industrial tier, Emerson Electric Co. and Parker Hannifin Corporation exemplify scale-driven positioning across multiple pressure regulation segments. Rotarex S.A. occupies a specialist position anchored by cryogenic and medical gas regulation expertise. Honeywell Process Solutions represents the automation-integrated archetype, sitting within control system architectures rather than standalone hardware procurement. These three companies illustrate how competitive positioning fragments across precision requirements and integration depth rather than converging on uniform product specifications.
| Leading Market Players |
|---|
| Air Products and Chemicals Inc. |
| Rotarex S.A. |
| Emerson Electric Co. |
| Parker Hannifin Corporation |
| Cavagna Group S.p.A |
| The Linde Group |
| Honeywell Process Solutions |
| Swagelok Company |
| Air Liquide S.A. |
| Others |
Supply Flow & Price Mechanics
Elastomer compound costs cascade from petrochemical feedstocks through diaphragm manufacturing into tiered regulator pricing, with fluorocarbon and hydrogenated nitrile formulations commanding premium positioning against commodity neoprene alternatives in distribution-grade hardware.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for electronic and pilot-operated variants in North American hydrogen pilot projects. Three-tier pricing structure across premium, standard, and economy levels separates SCADA-integrated electronic units from single-stage utility hardware, with certification grade and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from ECHA REACH-driven elastomer reformulation costs filtering into mid-tier products. Residential utilities in China and India exhibit highest price sensitivity; semiconductor fabs and hydrogen hub developers accept premium positioning for yield protection.
Supply Chain Analysis
High-specification diaphragm and spring production rests on precision machining clusters in Germany and Japan, with secondary capacity in South Korea for electronic actuator components. Raw material dependencies span specialty fluorocarbon elastomers, precision-wound spring steel, and microprocessor-controlled pressure transducers. Single-source vulnerability concentrates in cryogenic seal compound formulations where qualified suppliers number below five globally. Distribution runs through OEM direct sales for integrated process architectures and regional distributor networks for standalone field replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
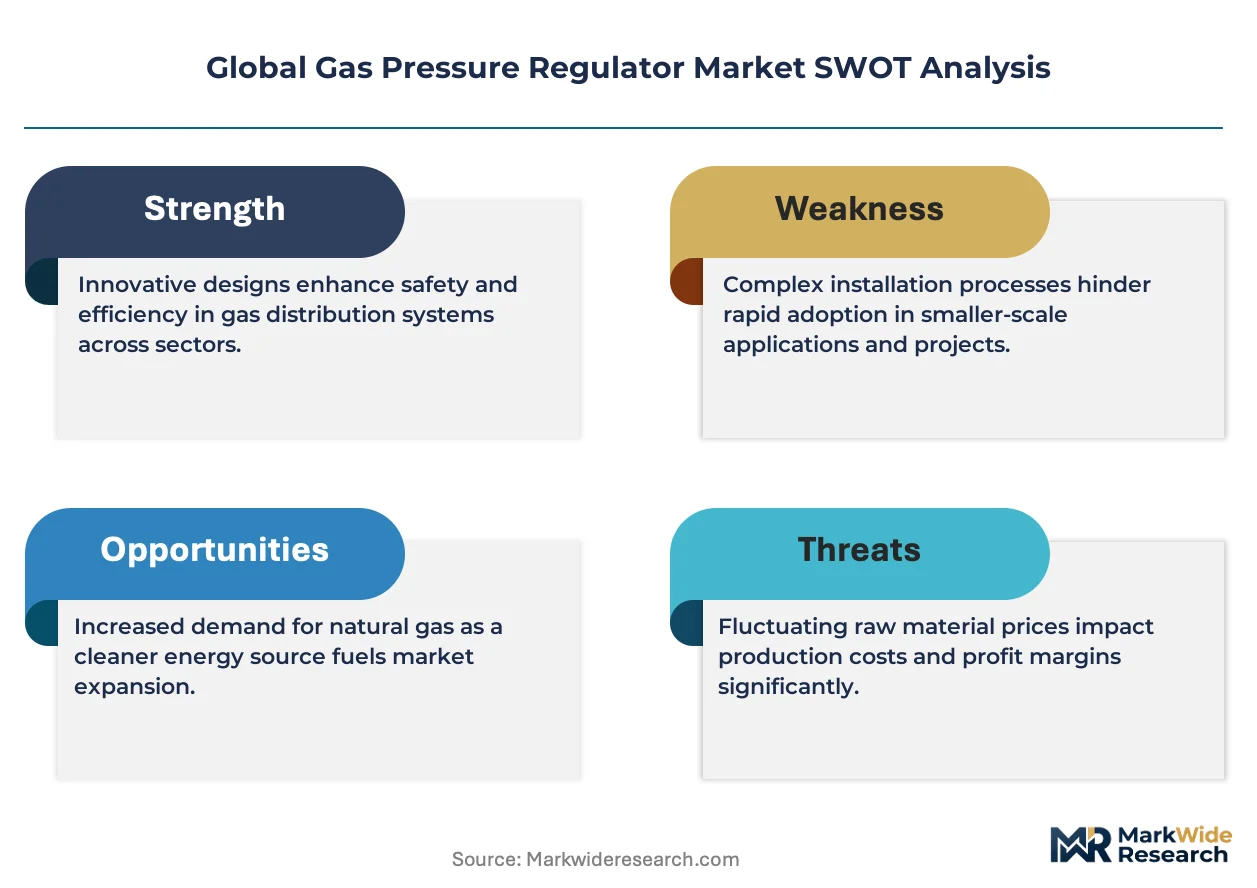
This market functions as a cost-of-compliance story where EPA methane thresholds and EU F-Gas Regulation leakage standards erect certification barriers that filter non-compliant imports and sustain margin pools for incumbents with established testing infrastructure.
For Market Incumbents: Anchor positioning through captive supply of hydrogen-compatible seal compounds and backward integration into precision diaphragm machining in Baden-Württemberg or Nagoya clusters. Threat from emerging Asian competitors with state-subsidized certification acceleration demands preemptive capacity expansion in hydrogen hub corridors. Prioritize R&D in smart diaphragm telemetry to defend against commoditization of standalone hardware. For New Entrants and Emerging Players: Enter via medical oxygen delivery in Maharashtra and Gujarat where hospital infrastructure modernization outpaces established supplier coverage. Most penetrable segment: dual-stage laboratory regulators for pharmaceutical manufacturing with lower certification burden than industrial process control. Go-to-market angle: partnership with regional gas distribution utilities for integrated manifold systems rather than standalone unit sales. For Investors and Strategic Acquirers: First-mover hydrogen compatibility certification in the Permian Basin is the leading indicator that technology validation timelines are compressing and acquisition premiums for qualified assets will escalate. Long-term viability favors specialists with cryogenic expertise and medical gas regulatory track records over diversified industrial conglomerates. Target acquisition archetype: mid-cap precision fabricators with MIIT certification and established diaphragm compound formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Compatibility Certification | EPA and EU F-Gas Regulation mandates accelerate qualification timelines for next-generation seal technologies. |
| Backward Integration into Diaphragm Manufacturing | German and Japanese precision machining clusters create supply bottlenecks that captive production alleviates. |
| Smart Diaphragm Telemetry Development | IIoT sensor integration enables predictive maintenance subscriptions and displaces transactional hardware revenue. |
| Regional Distribution Partnership Expansion | MIIT certification requirements in China filter non-compliant imports and favor localized assembly partnerships. |
| Performance-Guarantee Contract Structuring | Texas and California hydrogen pilots specify uptime commitments that transfer operational risk to OEM service arms. |
Methodological Framework
Document review covered regulatory filings from EPA, ECHA, and MIIT, trade customs data for industrial gas equipment, and OEM technical specifications, complemented by interviews with plant engineers at chemical manufacturing complexes, procurement leads at natural gas distribution utilities, aftermarket service heads at midstream energy firms, and regulatory affairs directors at precision component suppliers. Secondary validation drew from FERC pipeline integrity reports, EIA natural gas distribution data, and industrial safety directive databases. Bottom-up unit demand modeling triangulated against top-down market sizing across precision tiers.
Installed base projections and replacement cycle analysis produced volume and value estimates across the projection horizon. Segmentation dimensions modeled include product architecture (single-stage, electronic, dual-stage, pilot-operated), application intensity (industrial process control, power generation, residential distribution), and integration depth (standalone field units versus embedded process subsystems). CAGRs derived from regression analysis of historical procurement patterns against regulatory mandate implementation schedules, with hydrogen blending trial timelines and methane emission compliance deadlines as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated hydrogen infrastructure deployment or prolonged elastomer supply constraints. Forecasts reflect assumptions regarding certification timeline adherence, regional infrastructure spending continuity, and material compatibility validation schedules. Regulatory revision in the EU F-Gas Regulation, EPA methane rulemaking, or China's GB standards revision represent primary forecast revision triggers. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Solenoid Valves Market
Valves
Portable Valve Actuator Market
Valves
Valve Sack Market
Valves
Valve Interlocks Market
Valves
Flow Computer Market
Valves
Global Pipeline Safety Market
Valves
Global Valves Market
Valves
Pressure Gauge Market
Valves
Global Pressure Relief Valves Market
Valves
Global Industrial Thermostatic Control Valves Market
Valves
Emergency Shutdown Valves Market
Valves
Battery Pack Cooling Valve Actuator Systems Market
Valves
Fin Tube Market
Valves
North America Butterfly Valve Market
Valves
HVAC Valves Market
Valves
Sandblast Valves Market