
 Cryogenic Valve Market | 2026-2036
Cryogenic Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Valve Market Intelligence
Project finance tied to LNG export terminals is reshaping competitive access in cryogenic valve supply chains. Velan Inc. leverages its Montreal manufacturing base to dominate North American LNG infrastructure bids. HEROSE GmbH anchors European demand through specialized stainless steel valve portfolios for chemical cryogenics. Larsen and Toubro Ltd. competes on EPC-integrated valve procurement across Middle Eastern mega-projects.
Cryogenic valves are precision-engineered flow control devices constructed from austenitic stainless steel or nickel alloys, designed to operate below −150°C with bubble-tight sealing to prevent catastrophic LNG or liquid hydrogen leakage. Their primary purpose is to isolate, regulate, and protect high-value cryogenic fluid systems across energy, aerospace, and scientific applications. Ball valves capture dominant share in LNG processing due to quarter-turn reliability under thermal cycling stress. Stainless steel material grades command premium positioning as buyers prioritize corrosion resistance and low-temperature ductility. Aerospace engineering applications represent the fastest-expanding segment as liquid hydrogen propulsion systems advance.
OSHA process safety management rules and EPA leak detection mandates in the United States compel valve manufacturers to certify products to ISO 28921 cryogenic testing protocols. The EU F-Gas Regulation and REACH chemical restrictions in Europe drive material substitution toward bronze and nickel alloy alternatives with lower greenhouse gas footprint. Stakeholders must monitor hydrogen economy infrastructure commitments to calibrate R&D spending between LNG-cycle durability and liquid hydrogen compatibility requirements.
Market Dynamics
The LNG-to-hydrogen infrastructure pivot is fragmenting cryogenic valve demand between established LNG cycle durability requirements and emerging liquid hydrogen compatibility specifications. This bifurcation is forcing manufacturers to split R&D portfolios while maintaining certification continuity across both fluid systems.
Growth Catalysts
- EPA Fugitive Emission Mandates:US process safety rules compel material upgrades to nickel alloys and extended bonnet designs, accelerating replacement cycles across petrochemical infrastructure.
- Qatar's Ras Laffan Cluster:Mega-scale LNG export terminal construction concentrates procurement volumes for cryogenic isolation valves in a single geographic node.
- Liquid Hydrogen Propulsion:Aerospace engineering applications for satellite launch vehicles and hypersonic aircraft are opening parallel demand channels beyond traditional energy end-uses.
Market Restraints
- Nickel Alloy Supply Concentration:Inconel and Monel feedstock dependence on limited specialty steel mills creates input cost volatility and lead time uncertainty.
- EU F-Gas Regulatory Friction:REACH chemical restrictions and fluorinated gas phase-outs complicate seal material selection, extending qualification timelines.
- Substitution by Membrane Separation:Advanced pressure swing adsorption systems in small-scale hydrogen liquefaction reduce valve count requirements in pilot plants.
Strategic Opportunities
- Saudi Arabia NEOM Green Hydrogen:Giga-scale renewable hydrogen export infrastructure represents uncaptured valve demand outside established LNG procurement patterns.
- Modular LNG Plant Architecture:Factory-fabricated skid-mounted processing units enable valve OEM direct sales channels, bypassing traditional EPC intermediaries.
- ISO 19880 Hydrogen Fueling Standards:Emerging certification frameworks for vehicle refueling stations create first-mover positioning in automotive cryogenic distribution.
Industry Challenges
- Welding Certification Scarcity:Qualified orbital TIG welders for nickel alloy cryogenic joints command premium labor rates and extended hiring cycles.
- Dual Certification Burden:Manufacturers must simultaneously maintain ISO 28921 LNG test protocols and new ISO 19880 hydrogen compatibility approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Valve Market |
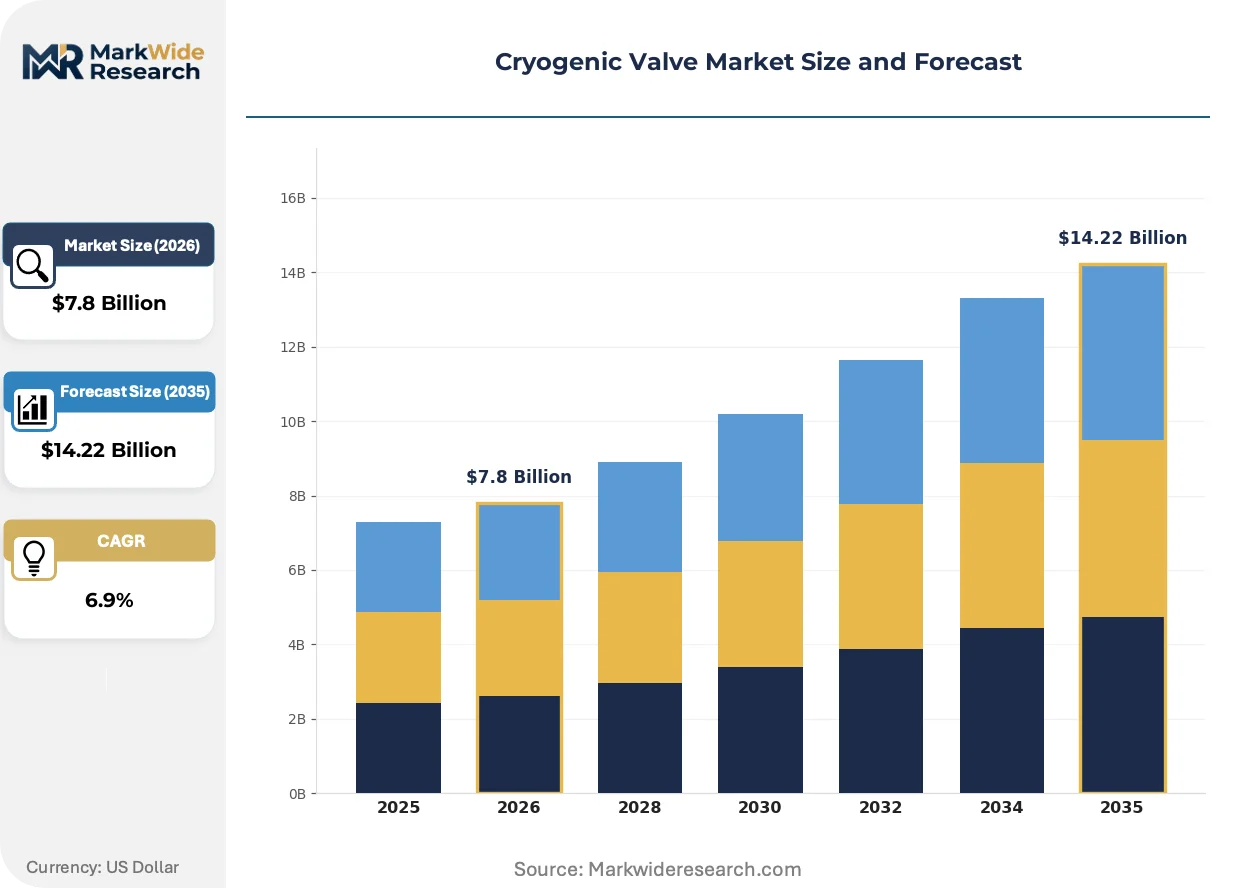
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $14.22 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Valve Type: Ball Valve, Globe Valve, Gate Valve, Butterfly Valve, Check Valve Material: Carbon Steel, Stainless Steel, Aluminum, Bronze, Nickel Alloy Application: LNG Processing, Aerospace Engineering, Chemical Processing, Cryogenic Storage, Research Laboratories End User Industry: Oil & Gas, Aerospace OEMs, Chemical Manufacturing, Scientific Research Institutions |
| Companies Covered | ITT Inc., Velan Inc., Parker Hannifin Corp., Cryofab Inc., Larsen and Toubro Ltd., Emerson Electric Co., SAMSON AG, HEROSE GmbH, Flowserve Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Valve Market Strategic Shifts & Innovations
Digital twin integration is compressing valve design validation cycles while predictive maintenance platforms are unbundling traditional spare parts revenue models. These shifts are redistributing value capture toward software-enabled service providers.
Digital valve positioners with embedded edge computing are virtualizing traditional pneumatic actuator control architectures. LNG terminal operators in the US Gulf Coast are deploying these systems for real-time seat leakage detection. The technology is virtualizing maintenance scheduling by replacing calendar-based inspections with condition-triggered interventions.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon-based seal materials is accelerating fluoroelastomer substitution with perfluoropolyether compounds. European chemical cryogenics processors face reformulation costs exceeding prior seal procurement budgets. Aerospace valve suppliers serving the Ariane launch program are responding fastest due to pre-existing space-grade material qualification pathways.
Lifecycle service contracting is displacing discrete equipment purchases among Middle Eastern national oil companies. EPC-integrated procurement teams now bundle valve supply with decade-long maintenance commitments. This pattern concentrates most visibly in Qatar's North Field expansion projects, where single-source accountability reduces interface risk across multi-billion dollar LNG trains.
Cryogenic Valve Market Segmentation
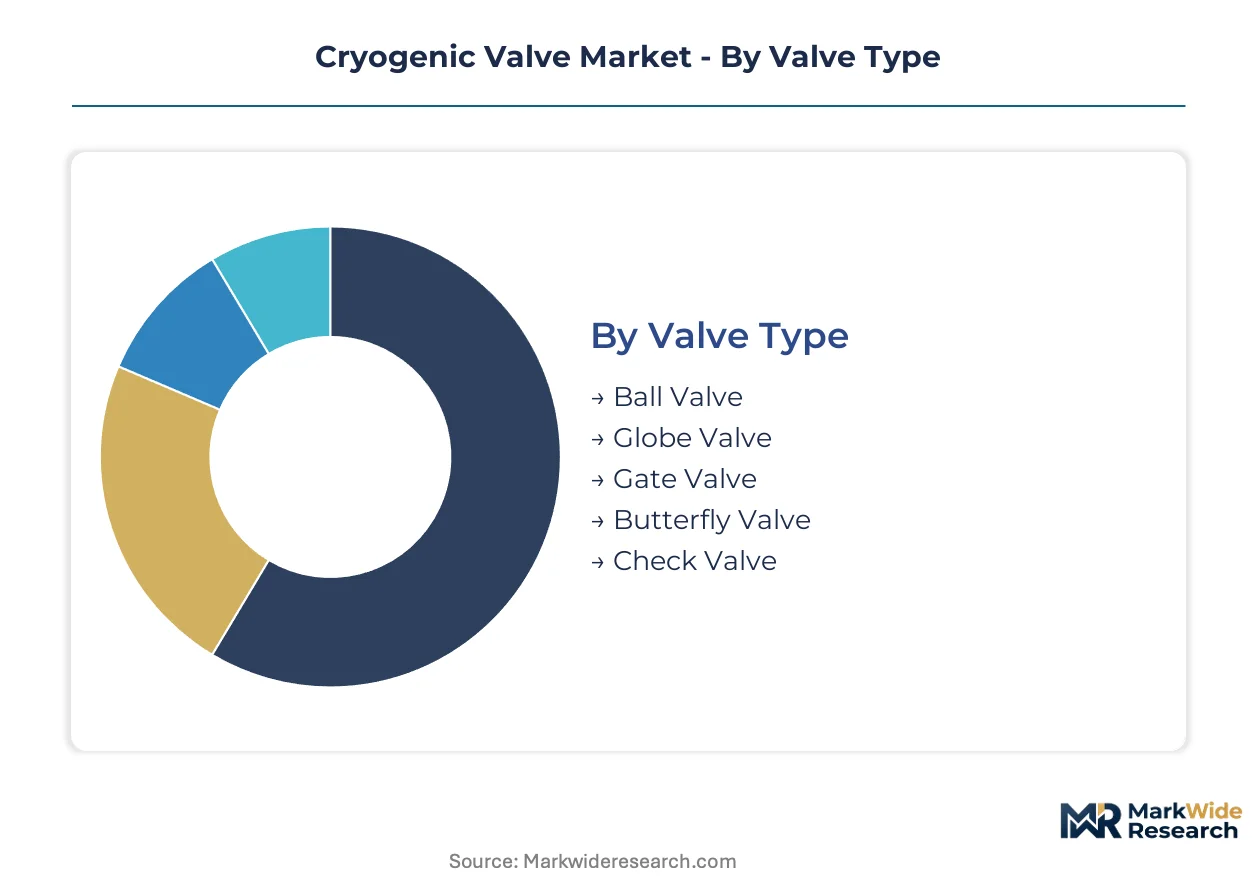
Cryogenic valve segmentation reveals distinct service intensity profiles across valve architectures and material grades. Each category carries specific aftermarket attachment rates that reshape manufacturer revenue models and customer lifetime value calculations.
Valve Type:
After-sales service intensity varies sharply by valve architecture, with rotating stem designs demanding more frequent packing replacement and seat refurbishment than static configurations.
- Ball Valve:Quarter-turn stainless steel or nickel alloy sphere mechanisms deliver bubble-tight isolation across thermal cycling stress. Qatar's Ras Laffan LNG export terminals specify full-port ball configurations for high-flow isolation in liquefaction trains, driven by EPA fugitive emission mandates requiring extended bonnet designs.
- Globe Valve:Linear stem motion enables precise throttling control in cryogenic distribution headers. Aerospace engineering applications for liquid hydrogen propulsion systems concentrate procurement in Germany and France, where ESA launch programs demand zero-leakage seat qualification.
- Gate Valve:Wedge or parallel slide mechanisms provide straight-through flow with minimal pressure drop for cryogenic storage tank isolation.
- Butterfly Valve:Compact wafer or lug designs suit space-constrained LNG regasification skids with lower pressure ratings.
- Check Valve:Swing or piston configurations prevent backflow in multi-stage liquefaction compressor discharge lines.
Ball valves hold the largest share; momentum sits with globe valves as liquid hydrogen propulsion expands.
Material:
Material selection directly governs procurement cost tiers, with nickel alloy grades commanding 3-4x carbon steel pricing and extending lead times through specialty mill dependence.
- Stainless Steel:Austenitic 300-series grades dominate LNG infrastructure through proven cryogenic ductility down to −196°C. US Gulf Coast terminal operators prioritize 316L specifications under OSHA process safety management rules, with FERC pipeline safety directives accelerating replacement of legacy carbon steel installations.
- Nickel Alloy:Inconel and Monel compositions address extreme thermal shock in hydrogen liquefaction heat exchangers. Japanese hydrogen fueling station deployments under METI subsidy programs drive qualification demand for ISO 19880 compatibility testing.
- Carbon Steel:Limited to warm-end piping transitions where temperatures remain above −50°C.
- Aluminum:Lightweight forgings suit aerospace weight-critical applications with moderate pressure requirements.
- Bronze:EU F-Gas Regulation compliance drives substitution for fluorocarbon-exposed seal housings in chemical cryogenics.
Stainless steel anchors volume procurement; nickel alloys are climbing the fastest on hydrogen infrastructure commitments.
Application:
Application segmentation maps directly to certification burden and qualification timeline variation, with aerospace programs requiring 18-24 month approval cycles versus 6-9 months for industrial LNG.
- LNG Processing:Liquefaction, storage, and regasification systems constitute the foundational demand base. Mega-scale export terminals in Qatar and Australia concentrate procurement volumes for isolation and control valve packages.
- Aerospace Engineering:Liquid hydrogen turbopump feed systems and tank pressurization circuits represent the steepest expansion trajectory. US FAA certification pathways for commercial space launch vehicles compress supplier qualification timelines.
- Chemical Processing:Ethylene cracker cold boxes and air separation units require corrosion-resistant trim packages.
- Cryogenic Storage:Bulk liquid nitrogen and helium dewar isolation demands high-cycle reliability.
- Research Laboratories:Scientific institutions specify ultra-high purity valves with minimal outgassing characteristics.
LNG processing retains dominant volume; aerospace engineering gains share fastest on propulsion system investments.
End User Industry:
End user concentration determines contract structure preferences, with national oil companies favoring lifecycle service bundles and aerospace OEMs demanding fixed-price development programs.
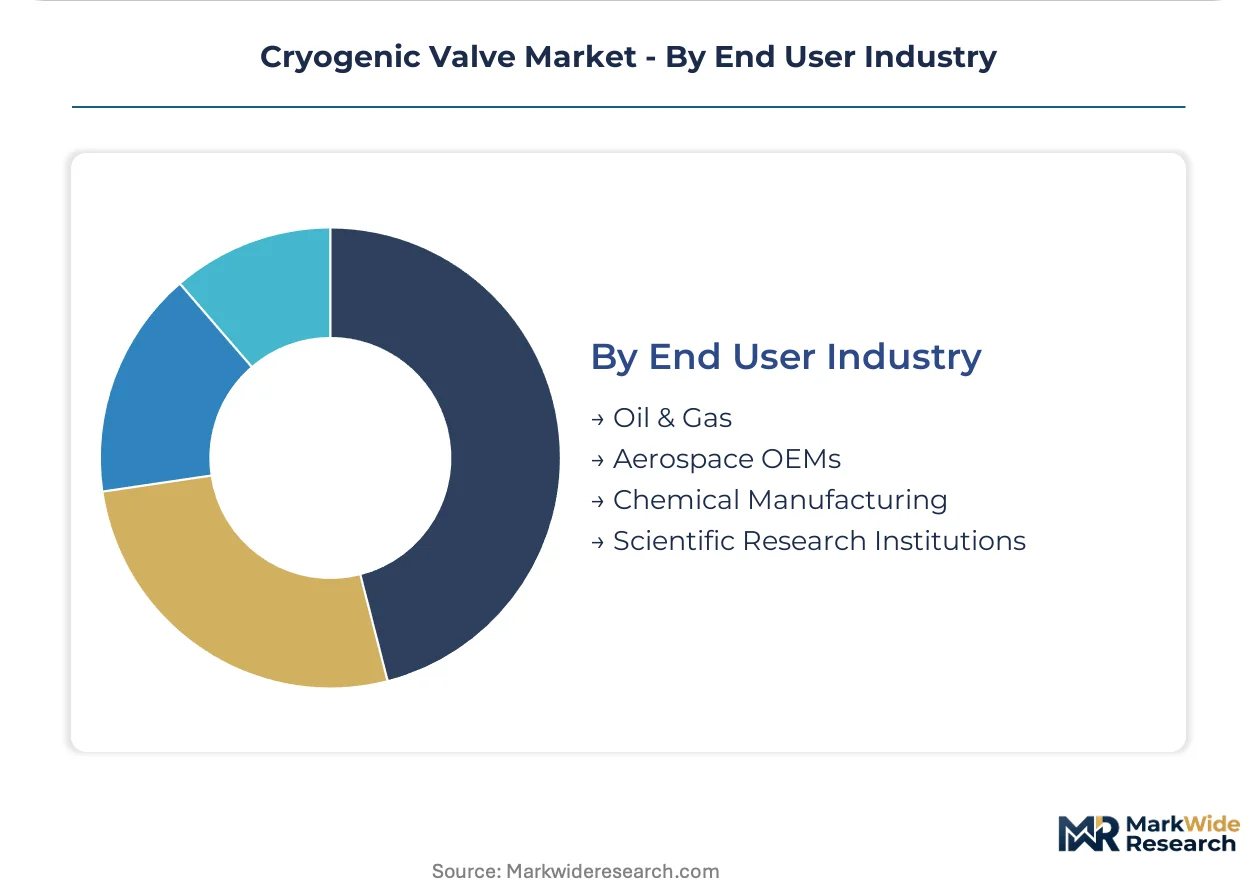
- Oil & Gas:Integrated majors and LNG project developers drive specification authority through EPC-integrated procurement. Saudi Aramco's unconventional gas developments and QatarEnergy's North Field expansion concentrate Middle Eastern demand.
- Aerospace OEMs:Launch vehicle prime contractors and satellite propulsion system suppliers impose material traceability requirements exceeding industrial standards. ArianeGroup and SpaceX qualification programs dominate European and North American procurement respectively.
- Chemical Manufacturing:Basf and Linde operate captive cryogenic valve specifications for air separation and syngas processing.
- Scientific Research Institutions:CERN and national laboratory accelerators specify custom ultra-high vacuum cryogenic configurations.
Oil and gas commands the largest share; aerospace OEMs show the steepest growth curve on hydrogen propulsion commercialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in liquefied natural gas are redrawing procurement geography for cryogenic isolation equipment. Qatar's Ras Laffan cluster and US Gulf Coast terminals now function as paired supply nodes, with valve demand flowing toward whichever region expands liquefaction capacity fastest.
United States
EPA fugitive emission mandates under the Clean Air Act are forcing material upgrades across Texas and Louisiana LNG corridors. FERC pipeline safety directives accelerate replacement of legacy carbon steel valve installations with 316L stainless steel specifications. Cheniere Energy's Corpus Christi expansion and Venture Global's Plaquemines facility concentrate procurement volumes along the Gulf Coast.
Qatar
North Field expansion projects represent the single largest concentrated valve demand node globally. QatarEnergy's integrated procurement teams bundle cryogenic isolation packages with decade-long maintenance commitments. Ras Laffan Industrial City's mega-scale LNG trains require full-port ball valve configurations for high-flow isolation under extreme thermal cycling stress.
Germany
EU F-Gas Regulation compliance is driving seal material substitution toward perfluoropolyether compounds in chemical cryogenics processing. ECHA REACH restrictions on fluorinated greenhouse gases extend qualification timelines for valve OEMs serving BASF and Linde air separation units. The Ruhr industrial cluster and Bavarian chemical corridor anchor continental demand for austenitic stainless steel trim packages.
Japan
METI subsidy programs for hydrogen fueling station deployment are accelerating ISO 19880 compatibility testing for nickel alloy valve configurations. Kobe Steel and Iwatani Corporation's liquid hydrogen supply chain investments concentrate procurement in the Osaka-Kobe industrial zone. Japanese hydrogen liquefaction heat exchangers specify Inconel compositions for extreme thermal shock resistance.
Saudi Arabia
NEOM Green Hydrogen giga-scale renewable export infrastructure represents uncaptured valve demand outside established LNG procurement patterns. Saudi Aramco's unconventional gas developments in the Eastern Province complement hydrogen economy investments. The kingdom's state-backed project finance structure favors lifecycle service contracting over discrete equipment purchases.
Cryogenic Valve Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in material-critical niches. The vendor base organizes around three functional layers: full-flow control system houses, precision valve fabricators with captive metallurgy expertise, and regional EPC-integrated procurement channels. Consolidation pressure concentrates at the middle tier, where nickel alloy supply scarcity favors players with backward integration into specialty steel sourcing. Competitive positioning hardens through dual certification maintenance—simultaneous ISO 28921 LNG protocols and emerging ISO 19880 hydrogen standards.
Among North American fabricators, Velan Inc. and Parker Hannifin Corp. occupy positions shaped by proximity to Gulf Coast LNG infrastructure investment cycles. HEROSE GmbH anchors European demand representation through specialized stainless steel portfolios. Larsen and Toubro Ltd. exemplifies EPC-integrated procurement leverage across Middle Eastern mega-projects. These three names illustrate how geographic clustering of end-use demand reproduces itself in supplier capability concentration.
| Leading Market Players |
|---|
| ITT Inc. |
| Velan Inc. |
| Parker Hannifin Corp. |
| Cryofab Inc. |
| Larsen and Toubro Ltd. |
| Emerson Electric Co. |
| SAMSON AG |
| HEROSE GmbH |
| Flowserve Corporation |
| Others |
Cost & Logistics Intelligence
Undercapacity at European specialty steel mills is compressing nickel alloy availability and amplifying pricing power for backward-integrated valve fabricators while forcing spot buyers toward extended lead-time premiums or material substitution.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where ISO 28921 certification tier and volume scale drive price differentiation. Premium-mid-economy pricing differentiation separates full-lifecycle service bundles from discrete equipment transactions. Cost compression in standard stainless steel grades is intensifying because Gulf Coast LNG terminal operators are consolidating procurement around fewer qualified suppliers. National oil companies show least price sensitivity due to bundled decade-long maintenance commitments, while pilot-scale hydrogen fueling station developers exhibit highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Extended payment terms from Qatari national oil companies are reshaping supplier financing structures, with EPC-integrated procurement teams demanding 180-day cycles that strain mid-tier fabricators. Geographic supply concentration centers on Germany, Japan, and the United States for precision-machined valve bodies and actuation packages. Raw material dependencies rest on Inconel and Monel feedstock from specialty steel mills, fluoroelastomer seal compounds, and austenitic stainless steel forgings. Single-source vulnerability in nickel alloy mill capacity poses structural risk. Distribution runs through EPC contractor channels for mega-projects and direct OEM sales for modular skid-mounted units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized welding expertise for nickel alloy cryogenic joints represents the critical bottleneck, with qualified orbital TIG welders commanding premium labor rates that constrain capacity expansion across all tiers.
For Market Incumbents: Build certification moats by maintaining simultaneous ISO 28921 LNG and ISO 19880 hydrogen approvals ahead of regulatory convergence. Secure captive supply of Inconel feedstock through long-term offtake agreements with specialty steel mills to insulate against nickel alloy supply concentration. Expand technical training pipelines for orbital TIG welding certification to preempt labor scarcity bottlenecks. For New Entrants and Emerging Players: Build out direct sales channels to modular LNG plant fabricators bypassing traditional EPC intermediaries, as factory-fabricated skid-mounted units enable valve OEM direct relationships. Target Japanese hydrogen fueling station deployments under METI subsidy programs where ISO 19880 qualification requirements create first-mover windows outside established LNG procurement patterns. Lead with liquid hydrogen compatibility testing services to differentiate from legacy LNG-cycle suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among valve fabricators with decade-long lifecycle service contracts tied to Middle Eastern national oil company mega-projects. Long-term viability over the coming decade favors players with dual certification maintenance capabilities and backward integration into specialty steel sourcing. Watch for Saudi Arabia NEOM Green Hydrogen project finance commitments as inflection signal for giga-scale renewable hydrogen valve demand outside established LNG patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous ISO 28921 and ISO 19880 approvals unlock access to both LNG and hydrogen infrastructure procurement channels. |
| Backward Integration into Nickel Alloy Supply | Captive Inconel feedstock sourcing insulates margins from specialty steel mill capacity constraints and price volatility. |
| Lifecycle Service Contracting | Decade-long maintenance bundles with QatarEnergy and Saudi Aramco concentrate revenue visibility and reduce customer acquisition costs. |
| Digital Twin Integration | Real-time seat leakage detection systems at Cheniere Energy terminals compress validation cycles and enable predictive maintenance revenue streams. |
| Modular Plant Direct Sales | Factory-fabricated skid-mounted LNG units bypass EPC intermediaries and capture margin otherwise lost to procurement layers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from listed valve manufacturers, EIA liquefaction capacity databases, and FERC pipeline safety directives. Primary interviews engaged plant engineers at LNG terminal operators, procurement leads at EPC contractors, aftermarket service heads at valve OEMs, and technical directors at specialty steel mills. Bottom-up project pipeline enumeration triangulates against top-down energy infrastructure investment forecasts.
Forecast inputs incorporate valve type segmentation by architecture, material grade tiering, application-specific certification burden, and end-user industry contract structure preferences across the projection horizon. Modeled dimensions span ball, globe, gate, butterfly, and check valve configurations; stainless steel, nickel alloy, and bronze material grades; LNG processing, aerospace engineering, and chemical processing applications; and oil and gas, aerospace OEM, and chemical manufacturing end users. CAGRs derive from capacity expansion timelines, regulatory compliance-driven replacement cycles, and hydrogen infrastructure commitment trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed hydrogen economy investors would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Sand Control System Market
Valves
Global Gas Pressure Regulator Market
Valves
Industrial Safety Valves Market
Valves
Rupture Discs Market
Valves
Valve Sack Market
Valves
Europe Electro Hydraulic Servo Valve Market
Valves
Blasting Stemming Plugs Market
Valves
Steam Trap Market
Valves
Pressure Gauge Market
Valves
Choke Valves Market
Valves
Electronic Expansion Valves Market
Valves
Blow - Off Valves Market
Valves
Sanitary Valves Market
Valves
Global Marine Actuators and Valves Market
Valves
Global Stainless Steel Control Valves Market
Valves
Valve Seat Inserts Market