
 Asia-Pacific Medium Voltage Switchgear Market | 2026-2036
Asia-Pacific Medium Voltage Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Medium Voltage Switchgear Market Insights
Copper-to-aluminum busbar migration is recalibrating cost structures across medium voltage switchgear production. Mitsubishi Electric Corporation leverages proprietary gas-insulated designs to sustain premium positioning in Japanese utility tenders. Schneider Electric SE anchors its Asia-Pacific footprint through localized manufacturing hubs in Vietnam and Indonesia.
Medium voltage switchgear encompasses electrical apparatus rated between 1 kV and 52 kV that controls, protects, and isolates power circuits using vacuum, air, or sulfur hexafluoride interruption mediums. The equipment serves critical functions in distribution networks, industrial facilities, and renewable energy collection points where fault interruption and operational continuity are essential. Gas insulated switchgear dominates margin pools in dense urban installations where footprint constraints command price premiums, while air insulated variants retain cost advantages in outdoor substations across Australia's mining belt. Hybrid switchgear is gaining traction at voltage levels where utilities seek to balance dielectric performance with maintenance accessibility.
China's GB standards and NMPA-equivalent electrical safety frameworks mandate localized testing protocols that shape product certification timelines for foreign suppliers. India's BIS certification and CEA technical standards enforce indigenous content thresholds that redirect procurement toward domestic assembly operations. METI's efficiency benchmarks in Japan and South Korea's MFDS-aligned electrical equipment directives add compliance layers that favor established regional players. Stakeholders must weigh regulatory divergence against scale economics when configuring regional supply architectures.
Market Dynamics
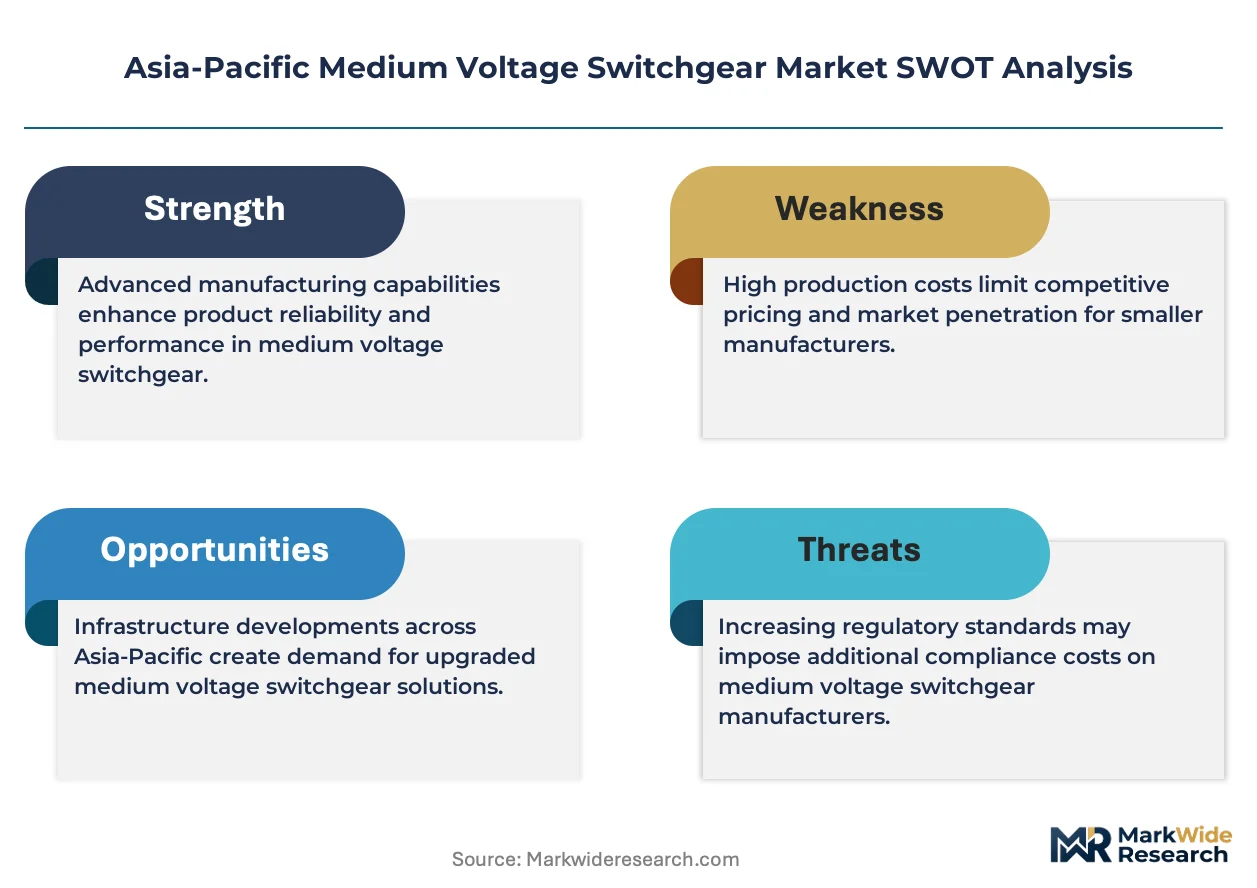
Copper-to-aluminum busbar migration is compressing material costs across Asia-Pacific switchgear production while China's GB standards and India's BIS certification enforce localized testing protocols that reshape supply chain geography.
Growth Catalysts
- India's PLI scheme for power equipment:Indigenous content thresholds redirect procurement toward domestic assembly operations, accelerating local manufacturing capacity across industrial corridors.
- Renewable energy collection infrastructure:Utility-scale solar and wind farms in Vietnam and Indonesia require fault-interruption equipment at collection points, expanding addressable demand.
- Urban footprint constraints:Dense metropolitan substations in Tokyo and Seoul command price premiums for gas-insulated designs that minimize physical space requirements.
Market Restraints
- Copper price volatility:Raw material cost swings complicate long-term contract pricing for air-insulated switchgear producers serving Australia's mining belt.
- SF6 regulatory pressure:Japan's METI efficiency benchmarks and South Korea's MFDS-aligned directives impose compliance layers that extend certification timelines for sulfur hexafluoride-dependent designs.
- Technical limitation in hybrid architectures:Voltage-level optimization between dielectric performance and maintenance accessibility creates engineering trade-offs that slow product standardization.
Strategic Opportunities
- Underpenetrated Indonesian archipelago:Distributed renewable microgrids across island provinces require modular switchgear solutions with minimal maintenance requirements.
- Technology convergence of digital monitoring and vacuum interruption:Integrated condition-monitoring systems paired with maintenance-free vacuum bottles enable predictive asset management for utilities.
- Thailand's smart grid mandates:Regulatory tailwinds favor intelligent switchgear with embedded sensors and remote-operated disconnectors.
Industry Challenges
- Certification timeline compression:China's NMPA-equivalent electrical safety frameworks mandate localized testing protocols that extend product approval cycles for foreign suppliers.
- Capex intensity in gas-insulated production:Cleanroom assembly facilities and precision welding equipment require substantial upfront investment for SF6-free alternatives.
- Skill scarcity in gas handling:Specialized technician training for sulfur hexafluoride recovery and recycling limits service network expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Medium Voltage Switchgear Market |
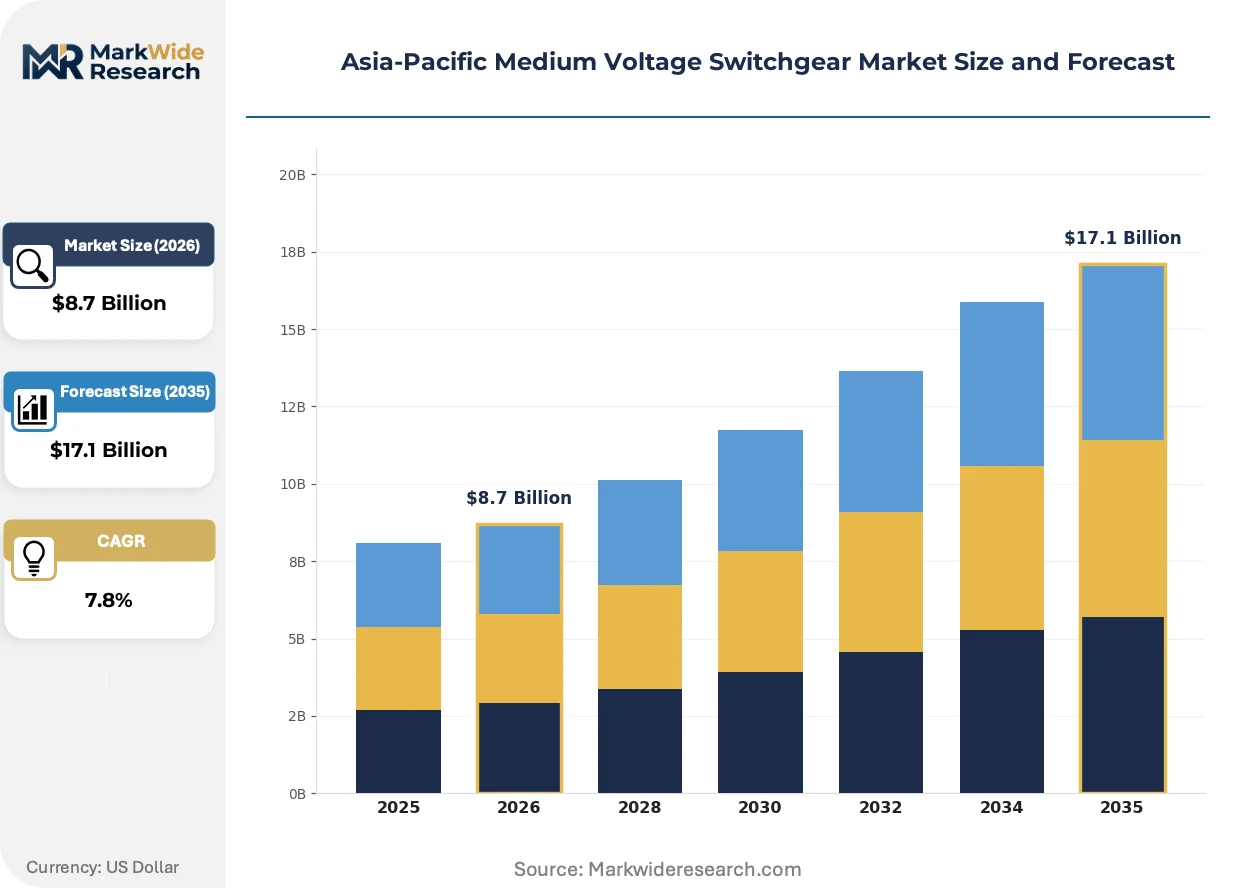
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Insulated Switchgear, Air Insulated Switchgear, Hybrid Switchgear, Others End User: Utilities, Industrial, Commercial, Healthcare Installation Type: Indoor, Outdoor, Portable, Modular Voltage Level: 12kV, 15kV, 24kV, 36kV |
| Companies Covered | General Electric Company, Mitsubishi Electric Corporation, Schneider Electric SE, Toshiba Corp., Chint Group, Siemens AG, Eaton Corporation PLC, Hyosung Heavy Industries Corp., Hitachi ABB Power Grids Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Medium Voltage Switchgear Market Trends and Innovations
Digitalization of medium voltage infrastructure is unifying protection, control, and asset management functions into single-platform architectures that reshape how utilities specify switchgear procurement.
Vacuum interruption technology is unifying fault-clearing performance with environmental compliance across the 12-24 kV range. Japanese utilities specify maintenance-free vacuum bottles for urban underground substations where SF6 access is restricted. This convergence is compressing the market for legacy air-magnetic designs while elevating premium positioning for integrated vacuum-cell modules.
China's dual carbon goals and GB standards revisions are accelerating phase-out timelines for sulfur hexafluoride in new installations. Provincial grid companies now prioritize SF6-free alternatives in tender specifications despite 15-20% cost premiums. Foreign suppliers face extended type-testing requirements at domestic laboratories, favoring established regional players with certified local production.
Asset-intensive buyers in Australian mining and Indian steel corridors are unbundling after-sales service from equipment procurement, contracting predictive maintenance separately through OEM digital platforms. This disintermediation compresses traditional distributor margins while elevating recurring revenue streams for manufacturers with captive IoT infrastructure. The shift is most visible in Western Australia's Pilbara region where remote operational sites prioritize uptime guarantees over capital equipment ownership.
Asia-Pacific Medium Voltage Switchgear Market Segmentation
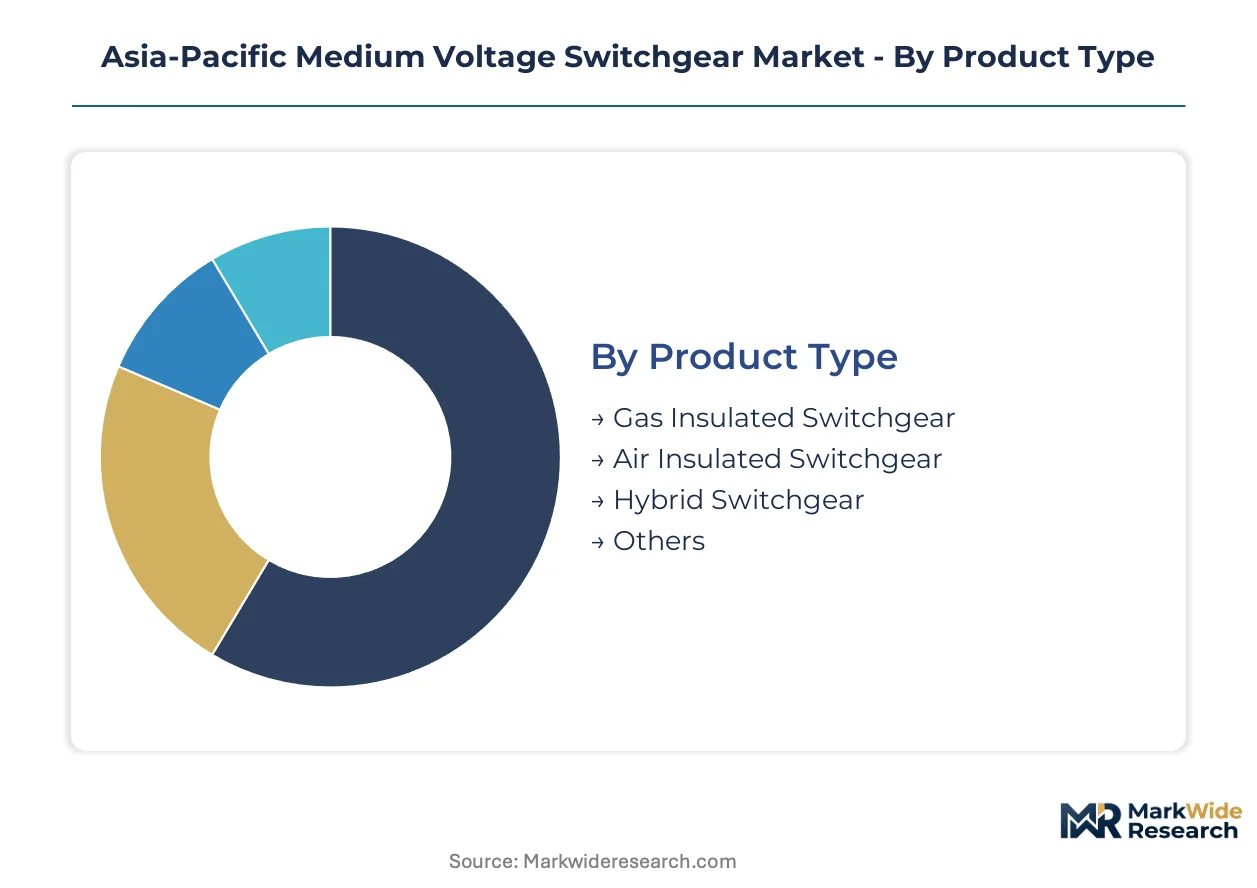
Segmentation reveals how capital intensity, regulatory constraints, and application environments fragment procurement patterns across Asia-Pacific. Equipment buyers in Tokyo's dense substations and Australia's remote mining sites operate on fundamentally different value equations.
Product Type:
Capital intensity varies sharply: gas-insulated designs demand cleanroom welding facilities and precision SF6 handling infrastructure, while air-insulated variants require less specialized manufacturing.
- Gas Insulated Switchgear:Sealed metal enclosures with sulfur hexafluoride dielectric medium achieve compact footprints essential for urban underground installations. Tokyo and Seoul utilities specify these designs for metropolitan substations where land scarcity commands substantial price premiums despite higher upfront costs.
- Air Insulated Switchgear:Open-air conductor arrangements with porcelain or composite insulators dominate outdoor substations across Australia's Pilbara mining belt and Indian industrial corridors. Copper-to-aluminum busbar migration is compressing material costs for these designs, though raw material volatility complicates long-term contract pricing.
- Hybrid Switchgear:Combines gas-insulated busbars with air-insulated circuit breakers to balance dielectric performance against maintenance accessibility.
- Others:Includes solid-insulated and oil-based legacy designs with limited new installation demand.
Gas insulated switchgear absorbs the bulk of installed capacity in dense metropolitan zones; hybrid configurations are expanding most quickly as utilities seek middle-ground solutions.
End User:
Procurement scale and technical specification authority diverge sharply between centralized utilities and fragmented industrial buyers.
- Utilities:Grid operators in China, India, and Southeast Asia drive standardization through bulk tendering. State Grid Corporation of China and Power Grid Corporation of India specify GB standards and BIS certification requirements that reshape supplier qualification timelines.
- Industrial:Steel, cement, and petrochemical facilities across India's Chhattisgarh and Odisha corridors demand fault-interruption equipment with high cycling durability. Asset-intensive buyers in Western Australia are unbundling after-sales service from equipment procurement, contracting predictive maintenance separately.
- Commercial:Data centers and logistics facilities in Singapore and Sydney require compact switchgear with integrated digital monitoring for uptime-critical operations.
- Healthcare:Hospital complexes in Melbourne and Bangkok prioritize seamless transfer switching for life-safety electrical systems.
Utilities command the largest absolute volumes; industrial buyers are gaining share fastest as manufacturing capacity expands across Vietnam and Indonesia.
Installation Type:
Physical deployment constraints determine maintenance accessibility, environmental protection requirements, and logistics complexity.
- Indoor:Climate-controlled substation buildings in Japanese urban centers and Singapore's underground infrastructure protect equipment from tropical humidity and pollution. These installations favor gas-insulated designs with minimal ventilation requirements.
- Outdoor:Exposed installations across Australia's mining regions and India's rural distribution networks must withstand temperature extremes, dust ingress, and monsoon conditions. Air-insulated variants with enhanced creepage distances dominate this specification.
- Portable:Trailer-mounted switchgear serves temporary construction power and emergency restoration for typhoon-affected grid segments in the Philippines.
- Modular:Factory-assembled skid packages accelerate deployment for renewable energy collection points in Indonesia's distributed archipelago microgrids.
Outdoor installations retain the largest installed base; modular configurations are climbing the fastest as renewable project timelines compress.
Voltage Level:
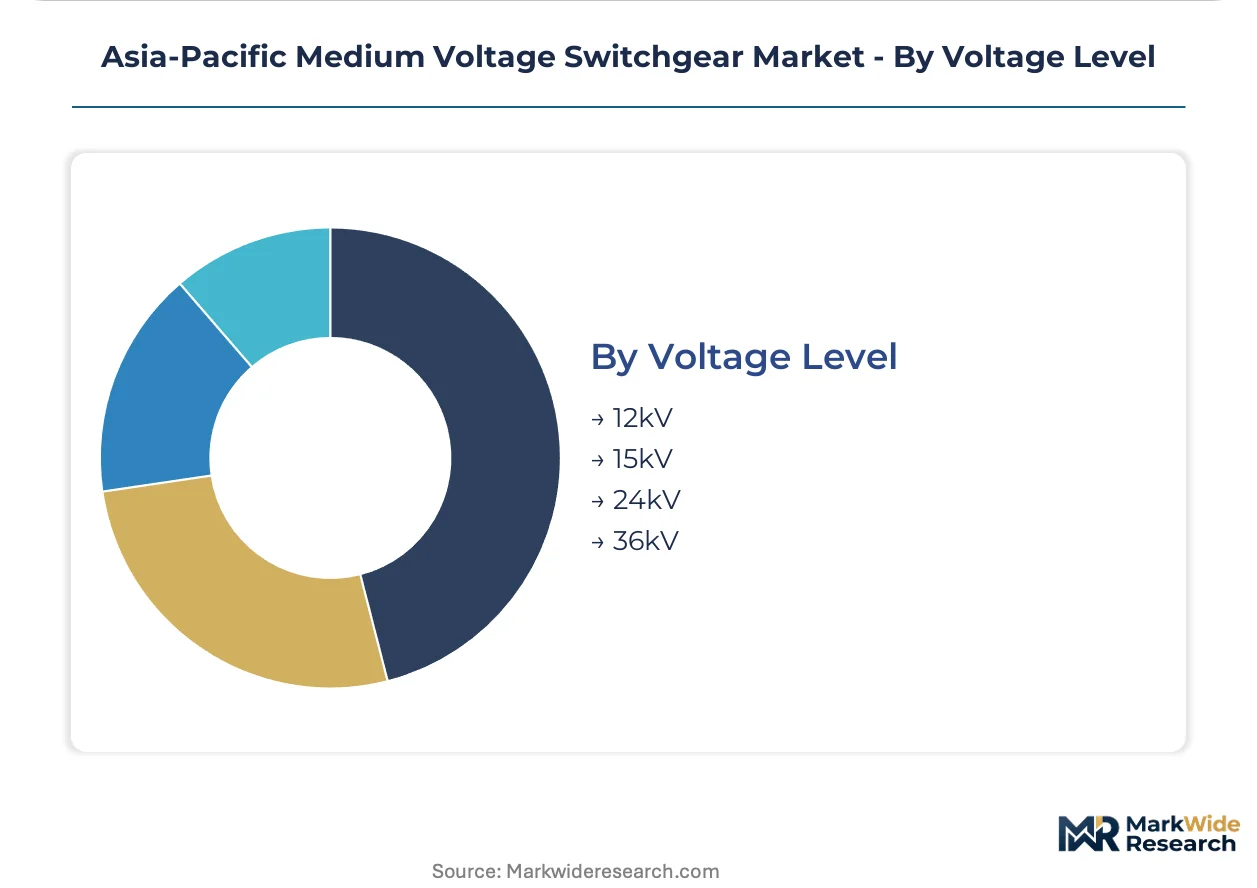
Standardization around IEC ratings creates procurement bands with distinct competitive dynamics and import substitution patterns.
- 12kV:Distribution network workhorse rating dominates urban underground cable systems and industrial facility feeders. Vacuum interruption technology has largely displaced air-magnetic designs at this level across Japanese and South Korean specifications.
- 15kV:Prevailing standard for North American-influenced specifications in Philippine and Australian legacy infrastructure.
- 24kV:Emerging preference for renewable energy collection infrastructure in Vietnam and Thailand, where longer feeder distances demand higher insulation coordination.
- 36kV:Sub-transmission interface rating for rural electrification and large industrial substations in India's state transmission networks.
The 12kV class holds the dominant share of unit shipments; 24kV specifications are gaining share fastest as utility-scale solar and wind farms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's special economic zones for power equipment manufacturing and China's dual carbon demonstration zones are concentrating medium voltage switchgear demand across the Asia-Pacific region. These designated zones channel investment toward localized production while utilities expand grid infrastructure to accommodate renewable energy integration.
China
State Grid Corporation bulk tenders drive standardization across provincial grid companies. GB standards revisions and the national dual carbon goals are accelerating phase-out timelines for sulfur hexafluoride in new installations. Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang provinces are scaling cleanroom assembly facilities for gas-insulated designs.
India
Power Grid Corporation specifications and state transmission utilities propel demand across rural electrification and industrial corridor expansion. The PLI scheme for power equipment enforces indigenous content thresholds that redirect procurement toward domestic assembly operations. Chhattisgarh and Odisha industrial corridors are absorbing fault-interruption equipment for steel and cement facilities.
Japan
Tokyo Electric Power and regional utilities specify maintenance-free vacuum bottles for dense metropolitan underground substations. METI efficiency benchmarks impose compliance layers that extend certification timelines for foreign suppliers. Kanto region urban infrastructure projects command substantial price premiums for compact gas-insulated designs.
Australia
Western Australia's Pilbara mining belt and Queensland renewable zones generate concentrated demand for outdoor air-insulated variants with enhanced environmental protection. TGA-aligned electrical equipment directives shape procurement specifications for healthcare and critical infrastructure. Remote operational sites across Western Australia are unbundling after-sales service from equipment procurement.
Vietnam
Utility-scale solar and wind farms in the central highlands and Mekong Delta require fault-interruption equipment at collection points. National power development plans prioritize grid infrastructure expansion to accommodate renewable energy targets. Ho Chi Minh City metropolitan substations are specifying gas-insulated designs where land scarcity commands space-efficient solutions.
Asia-Pacific Medium Voltage Switchgear Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated electrical conglomerates commanding utility tenders while regional fabricators capture industrial procurement. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive grid relationships, specialized switchgear houses with certified local production, and scale-driven contract manufacturers serving price-sensitive segments. Competitive moves center on backward integration into busbar fabrication and technology licensing for SF6-free alternatives.
Among Japan-based electrical conglomerates, Mitsubishi Electric Corporation and Toshiba Corp. exemplify the diversified industrial archetype with established utility relationships. Schneider Electric SE, a France-based multinational, occupies a position within the premium-tier specialist segment through localized manufacturing hubs. Siemens AG, a German engineering group, anchors the technology-licensing vector with vacuum interruption platforms. These three entities represent distinct competitive positioning strategies without implying specific market share claims.
| Leading Market Players |
|---|
| General Electric Company |
| Mitsubishi Electric Corporation |
| Schneider Electric SE |
| Toshiba Corp. |
| Chint Group |
| Siemens AG |
| Eaton Corporation PLC |
| Hyosung Heavy Industries Corp. |
| Hitachi ABB Power Grids Ltd |
| Others |
Pricing and Supply Chain Analysis
Specialized gas-handling technician concentrations in the Yangtze River Delta and Chubu region feed labor-cost differentials that widen pricing-tier spreads between premium gas-insulated designs and standard air-insulated variants across Asia-Pacific procurement.
Pricing Analysis
Volume concentration in bulk utility tenders compresses margins while premium positioning in dense urban installations sustains wider spreads. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Cost compression in aluminum-intensive air-insulated tiers is intensifying because copper-to-aluminum busbar migration accelerates. Mining operators in Western Australia exhibit highest price sensitivity; Japanese metropolitan utilities demonstrate lowest sensitivity due to footprint-constrained specifications.
Supply Chain Analysis
Single-source vulnerability sits with precision SF6 handling equipment suppliers concentrated in Germany and Japan. Manufacturing draws from copper and aluminum busbar feedstock anchored in China and India, with vacuum interrupter ceramic assemblies sourced from Japan. Logistics chokepoints at ASEAN port infrastructure create delivery uncertainty for modular skid packages. Distribution runs through electrical equipment distributors with captive service networks in Australia and direct-to-utility channels in China and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over busbar fabrication and SF6 recovery infrastructure determines margin capture across tender cycles.
For Market Incumbents: Acquire certified local testing laboratory capacity to compress approval timelines for foreign competitors. Strengthen backward integration into aluminum busbar rolling mills to offset raw material volatility. State Grid Corporation bulk tender standardization and India's BIS indigenous content thresholds threaten suppliers without domestic assembly presence.
For New Entrants and Emerging Players: EPC contractors with captive renewable project pipelines offer channel access without direct utility qualification. Indonesia's distributed archipelago microgrids present the most penetrable geography given minimal incumbent service infrastructure. Lead with modular switchgear configurations that minimize specialized technician requirements.
For Investors and Strategic Acquirers: Re-rating potential sits with SF6-free technology specialists given China's dual carbon demonstration zone procurement preferences. Five-to-ten year viability hinges on technology licensing revenue from vacuum interruption platforms displacing legacy gas-insulated architectures. Monitor METI efficiency benchmark revisions as inflection indicator for regional technology adoption curves.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Busbar Fabrication | Captive aluminum rolling capacity insulates margin from LME price swings in Australian mining contracts. |
| SF6-Free Technology Licensing | Patent portfolios for vacuum interruption platforms unlock premium positioning in China's dual carbon zones. |
| Certified Local Production Investment | CEA and BIS compliance accelerates qualification for Power Grid Corporation bulk tenders. |
| Predictive Maintenance Platform Development | IoT-enabled asset management captures recurring revenue from Pilbara mining unbundled service contracts. |
| Modular Skid Package Standardization | Factory-assembly reduces deployment timelines for Vietnam renewable collection infrastructure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with utility planning officers, EPC contractors, switchgear procurement managers, and aftermarket service heads combined with State Grid Corporation tender databases, CEA technical standards documentation, and IEC certification registries. Bottom-up project pipeline tracking and top-down macroeconomic indicators underwent cross-validation to ensure consistency across estimation approaches.
Reconciliation of shipment data, tender award values, and manufacturing capacity utilization informed the analytical framework across the projection horizon. Segmentation dimensions encompassed product insulation technology, end-user procurement authority, installation environment constraints, and voltage rating specifications. CAGRs derived from curve-fitting techniques applied to disclosed utility capital expenditure plans and industrial capacity expansion announcements, with particular weighting for renewable energy collection infrastructure deployment schedules.
Caveats apply where GB standards revision timelines or PLI scheme indigenous content threshold adjustments could materially shift the outlook. Forecasts reflect documented assumptions regarding copper-aluminum price spreads and SF6 regulatory phase-out pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Emergency Venting System Market
Valves
Sanitary Valves Market
Valves
Gas Equipment Market
Valves
Global Gas Pressure Regulator Market
Valves
Valve Cover Gasket Market
Valves
Global Plastic Valves Market
Valves
3-Way Pilot Operated Directional Control Valves Market
Valves
Reciprocating Compressor Components Market
Valves
Global Check Valve Market
Valves
Large Bore Vacuum Insulated Pipe Market
Valves
Air Heated Vaporizer Market
Valves
Directional Control Valves Market
Valves
North America Irrigation Valves Market
Valves
Hot Blast Valves Market
Valves
Valve Sack Market
Valves
Instrumentation Valves and Fittings Market