
 Gate Impellers Market | 2026-2036
Gate Impellers Market Size, Share, and Industry Trends Forecast 2026-2036
Gate Impellers Market Foresight
Modular retrofit kits for existing agitation systems is rebalancing procurement patterns among municipal utilities and chemical processors. EKATO Holding GmbH leverages its German engineering base to dominate precision-mixed applications in European pharmaceutical and chemical plants. Flowserve Corporation anchors its position through extensive aftermarket service networks that sustain long-term customer relationships in power generation and water treatment. KSB SE & Co. KGaA specializes in energy-efficient hydraulic designs that differentiate its offerings in municipal infrastructure tenders across multiple continents.
Gate impellers are radial-flow mixing elements featuring flat vertical blades mounted on a central hub, typically constructed from stainless steel or corrosion-resistant alloys to withstand abrasive slurries and aggressive chemical environments. Their primary function is to generate strong tangential velocity profiles for uniform solids suspension and gas dispersion in tanks and reactors. Closed impellers command premium positioning in high-pressure chemical processing where containment integrity prevents hazardous leakage, while open impellers compete on maintenance accessibility in water treatment basins with high solids loading. The centrifugal technology segment leads unit shipments across manufacturing plants and power generation facilities, though axial configurations are gaining traction in low-shear agriculture irrigation systems where pump efficiency directly affects operating costs.
The United States Environmental Protection Agency enforces effluent limitations that compel municipal utilities to replace outdated mixing equipment with higher-efficiency gate impeller systems. Germany's REACH regulation and the EU F-Gas Regulation jointly constrain material selection and sealing technologies, elevating compliance costs for suppliers serving European chemical processors. China's Ministry of Ecology and Environment implements discharge standards that accelerate equipment upgrades in industrial clusters along the Yangtze River basin. Stakeholders must monitor how evolving carbon accounting rules and embodied-emissions thresholds reshape supplier qualification criteria in public infrastructure procurement.
Market Dynamics
Modular retrofit kits for existing agitation systems are compressing replacement cycles across municipal utilities and chemical processors, forcing incumbent suppliers to reconfigure service revenue models around upgrade compatibility rather than full-system sales.
Growth Catalysts
- REACH and F-Gas Regulation compliance mandates:European chemical processors must replace legacy sealing systems with corrosion-resistant alloys, accelerating gate impeller upgrades in pharmaceutical and specialty chemical plants.
- High-viscosity mixing expansion:Chemical processing plants are scaling gate impeller deployment in polymer and slurry applications where radial-flow elements outperform axial alternatives.
- Yangtze River basin discharge enforcement:China's Ministry of Ecology and Environment standards are compelling industrial clusters to modernize aeration and mixing infrastructure ahead of permit renewal deadlines.
Market Restraints
- Stainless steel price volatility:Raw material input swings compress margin predictability for fabricators serving water treatment and power generation sectors.
- Precision-mixing supplier concentration:German engineering bases dominate pharmaceutical-grade applications, creating procurement bottlenecks for non-European chemical processors seeking qualified vendors.
- Axial impeller substitution in low-shear irrigation:Agriculture pump systems increasingly favor propeller-style elements where energy efficiency trumps solids suspension capability.
Strategic Opportunities
- Aftermarket service unbundling:Power generation and water treatment operators are separating maintenance contracts from initial equipment procurement, opening standalone service revenue streams.
- Carbon accounting integration:Embodied-emissions thresholds in public infrastructure tenders are creating qualification advantages for suppliers with verified lifecycle data.
- Closed impeller containment demand:High-pressure chemical processing segments seek leakage-prevention designs that command premium positioning in hazardous material handling.
Industry Challenges
- Hydraulic design talent scarcity:Municipal infrastructure tenders across multiple continents require energy-efficient impeller engineering expertise that outpaces vocational training pipeline output.
- Legacy system integration complexity:Retrofit kit compatibility with existing agitation drives demands customized shaft and seal adaptations that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gate Impellers Market |
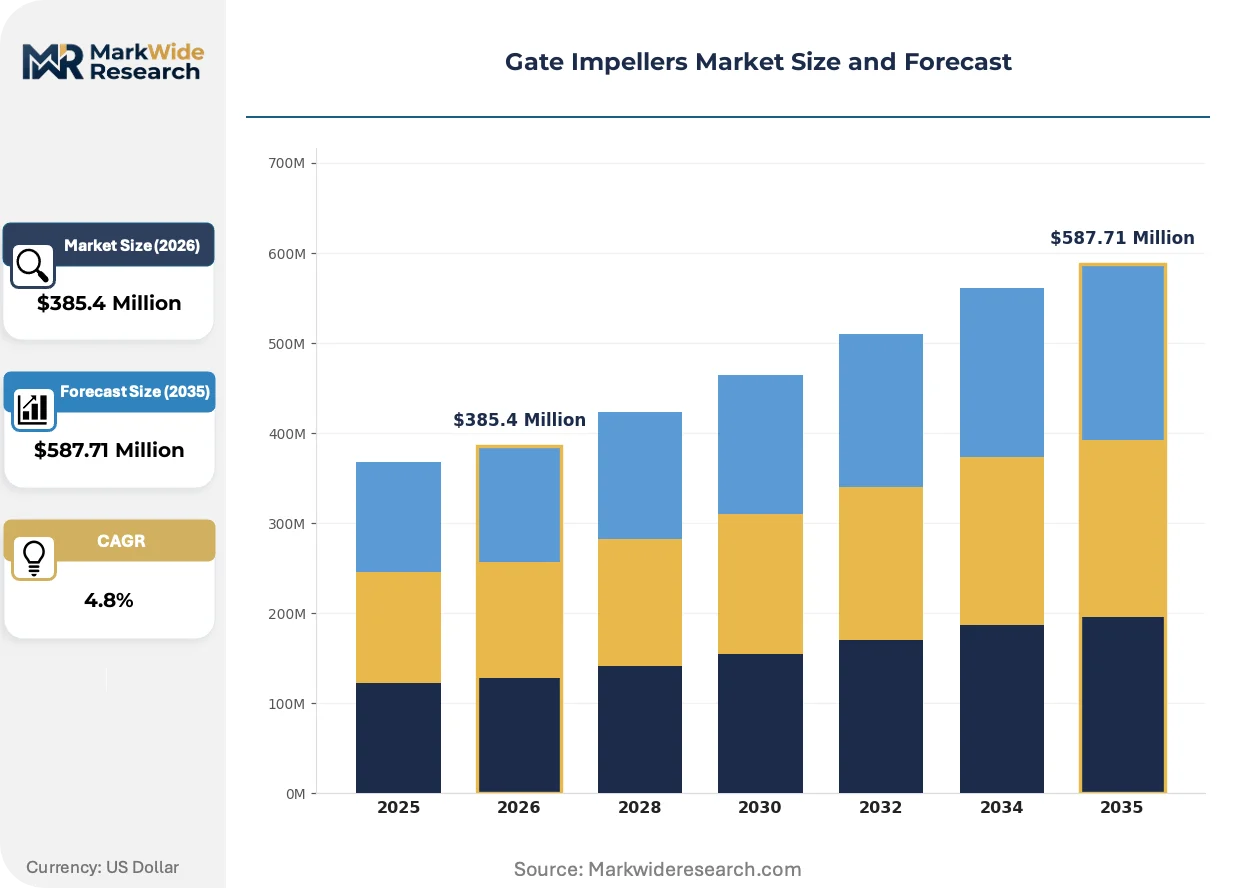
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed Impellers, Open Impellers, Semi-Open Impellers, Vortex Impellers Technology: Centrifugal, Axial, Mixed Flow, Diaphragm Application: Water Treatment, Chemical Processing, Agriculture Irrigation, Mining Operations End User Industry: Manufacturing Plants, Power Generation Facilities, Municipal Utilities, Construction Firms |
| Companies Covered | EKATO Holding GmbH, MGT Liquid & Process Systems, Statiflo Group, Jongia, Fusion Fluid Equipment, Philadelphia Mixing Solutions Ltd, Mixer Direct, Flowserve Corporation, KSB SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gate Impellers Market Shifts & Advancements
Computational fluid dynamics and additive manufacturing are converging to reshape impeller geometry optimization, while regulatory pressure on embodied emissions is forcing material selection transparency throughout supplier qualification processes.
Computational fluid dynamics simulation is consolidating design authority among specialized engineering houses capable of validating custom blade angles for specific viscosity profiles. Pharmaceutical and chemical processors in Germany and Switzerland are adopting these validated geometries at accelerating pace. The technology is consolidating competitive position around simulation capability rather than manufacturing scale.
REACH substance restrictions and the EU F-Gas Regulation are jointly constraining elastomer and alloy selections for sealing assemblies in European chemical processing. Compliance costs are elevating total cost of ownership calculations in procurement evaluations. Closed impeller configurations with advanced metallurgy are capturing preference in high-pressure pharmaceutical reactors where leakage prevention justifies premium outlays.
Buyers are unbundling aftermarket service agreements from initial capital equipment purchases in power generation and municipal water treatment. Traditional bundled procurement models are yielding to separate maintenance contracts and performance-based service tiers. This pattern is most visible in United States utility districts where EPA effluent enforcement has compressed equipment replacement timelines and strained capital budgets.
Gate Impellers Market Segmentation
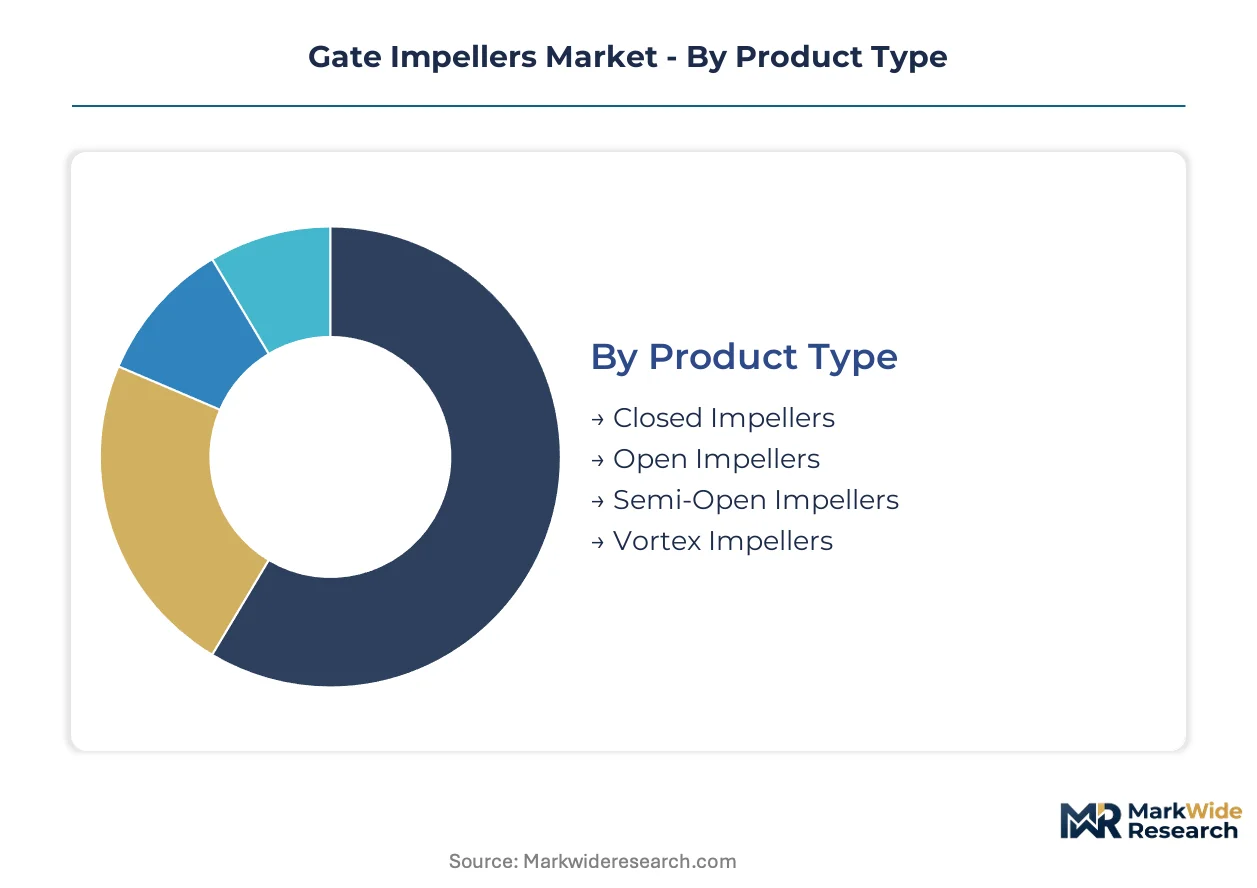
Gate impeller procurement decisions pivot on containment requirements, hydraulic efficiency demands, and retrofit compatibility with legacy agitation infrastructure. Specification engineers weigh initial capital outlay against lifecycle maintenance accessibility when selecting across product architectures.
Product Type:
Containment integrity versus maintenance accessibility drives buyer selection between sealed and open-blade configurations.
- Closed Impellers:Fully shrouded blade assemblies containing process fluids within precision-machined channels. Pharmaceutical reactors in Germany and Switzerland specify these designs where REACH-mandated sealing prevents hazardous leakage. Premium positioning reflects metallurgy costs for corrosion-resistant alloys.
- Open Impellers:Exposed blade geometry enabling rapid inspection and cleaning without full pump disassembly. Municipal water treatment basins across the United States favor this architecture where EPA effluent enforcement demands frequent solids-handling maintenance.
- Semi-Open Impellers:Partial shroud designs balancing containment with serviceability for mid-viscosity chemical slurries.
- Vortex Impellers:Recessed blade configurations minimizing wear in abrasive mining tailings and wastewater grit applications.
Closed impellers lead on scale; open impellers lead on momentum.
Technology:
Hydraulic efficiency requirements and shear sensitivity determine flow regime selection across installation contexts.
- Centrifugal:Radial discharge impellers generating high head pressure through rotational kinetic energy conversion. Manufacturing plants and power generation facilities in China's industrial corridor cities deploy these systems where process reliability trumps energy optimization.
- Axial:Propeller-style elements producing high flow rates at low pressure differentials. Agriculture irrigation networks increasingly specify axial configurations where pump efficiency directly affects operating costs across large-scale water movement.
- Mixed Flow:Hybrid geometry combining radial and axial characteristics for intermediate head-flow requirements in chemical transfer operations.
- Diaphragm:Positive displacement mechanisms isolating fluid from mechanical components in precision metering applications.
Centrifugal technology dominates installed base; axial configurations are expanding most quickly.
Application:
Process fluid characteristics and regulatory discharge standards shape specification priorities across vertical markets.
- Water Treatment:Aeration and mixing operations in municipal and industrial effluent systems. Stricter discharge standards in Germany and the United States compel utilities to upgrade aging equipment with higher-efficiency gate impeller assemblies.
- Chemical Processing:High-viscosity polymer and slurry mixing where radial-flow elements outperform axial alternatives. Yangtze River basin industrial clusters drive demand as China's MEE enforcement accelerates modernization timelines.
- Agriculture Irrigation:Low-shear water distribution where energy efficiency competes with solids suspension capability against propeller-style substitutes.
- Mining Operations:Abrasive slurry handling requiring hardened metallurgy and rapid-wear component replacement protocols.
Water treatment leads on scale; chemical processing leads on momentum.
End User Industry:
Capital budget cycles and regulatory compliance timelines create divergent procurement rhythms across customer categories.
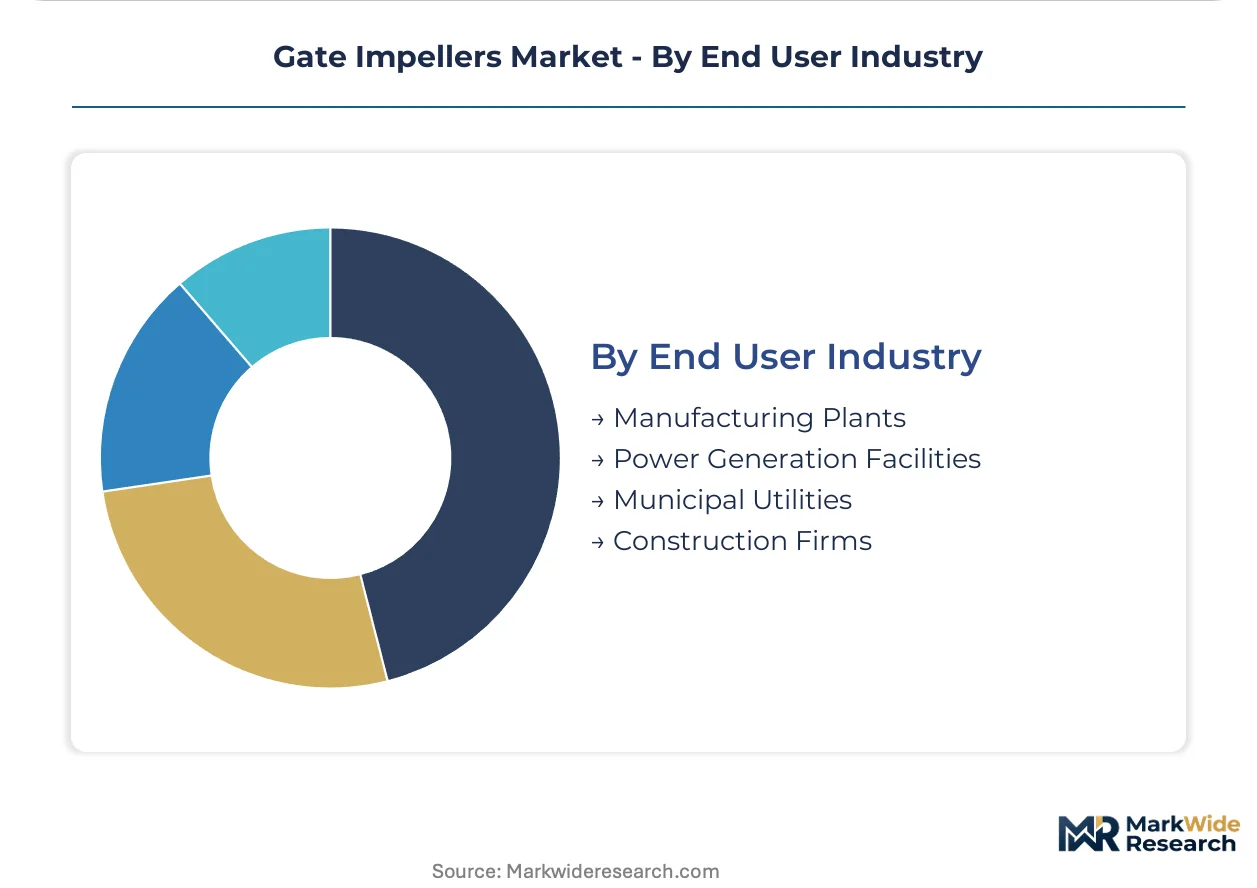
- Manufacturing Plants:Process-integrated mixing systems serving continuous production lines. Chemical and pharmaceutical processors prioritize validated geometries from specialized engineering houses over manufacturing scale.
- Municipal Utilities:Public infrastructure operators unbundling aftermarket service from initial equipment procurement. EPA effluent limitations in the United States compress replacement timelines and strain capital budgets.
- Power Generation Facilities:Cooling water and effluent treatment systems requiring long-term service relationships sustained through extensive aftermarket networks.
- Construction Firms:Project-based procurement for temporary dewatering and slurry management with shorter equipment lifecycles.
Municipal utilities lead on scale; manufacturing plants lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gate impeller engineering originated in German industrial centers during the mid-20th century, with precision-mixing expertise subsequently diffusing to Swiss pharmaceutical corridors and North American chemical processing hubs. Contemporary demand concentrates in manufacturing-intensive economies with stringent environmental enforcement regimes.
United States
EPA effluent limitations are compelling municipal utilities across the Great Lakes and Ohio River basins to replace legacy mixing equipment with higher-efficiency gate impeller assemblies. The agency's National Pollutant Discharge Elimination System enforcement has compressed replacement timelines for aging water treatment infrastructure. Chicago and Milwaukee metropolitan districts are deploying upgraded aeration systems ahead of permit renewal deadlines.
Germany
REACH substance restrictions and the EU F-Gas Regulation are jointly constraining elastomer and alloy selections for sealing assemblies in pharmaceutical and specialty chemical plants. ECHA compliance mandates are accelerating upgrades to corrosion-resistant gate impeller configurations. The Rhine-Ruhr industrial corridor hosts concentrated retrofit activity as processors modernize high-viscosity mixing operations.
China
MEE discharge standards along the Yangtze River basin are compelling industrial clusters to modernize aeration and mixing infrastructure ahead of environmental permit deadlines. The ministry's enforcement protocols target chemical and petrochemical processors in Jiangsu and Zhejiang provinces. Shanghai and Ningbo manufacturing zones are scaling gate impeller deployment in polymer production facilities.
Switzerland
Swissmedic pharmaceutical manufacturing standards and cantonal environmental regulations are elevating precision-mixing equipment specifications for active pharmaceutical ingredient production. Basel-area chemical processors are adopting validated impeller geometries from specialized engineering houses. The country's precision manufacturing tradition sustains premium positioning for containment-grade closed impeller systems.
India
Central Pollution Control Board effluent standards and state-level environmental clearances are driving equipment upgrades in Gujarat and Maharashtra chemical processing zones. The country's national pharmaceutical regulator is tightening manufacturing practice requirements that cascade into mixing equipment specifications. Mumbai and Ahmedabad industrial corridors are expanding gate impeller procurement for bulk drug and intermediate production.
Gate Impellers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across metallurgy sophistication and simulation-validated design capability. The vendor base stratifies between German-engineered precision specialists and volume-oriented fabricators serving water treatment utilities. Three archetypes dominate: simulation-capable engineering houses, aftermarket service integrators, and scale-driven commodity fabricators. Consolidation pressure is intensifying through strategic partnerships for retrofit kit compatibility and geographic expansion into China's industrial corridor cities.
Among German-engineered precision specialists, EKATO Holding GmbH exemplifies the simulation-validated tier, while Flowserve Corporation and KSB SE & Co. KGaA occupy positions spanning aftermarket service integration and energy-efficient hydraulic design. These three entities represent distinct competitive vectors—engineering authority, service network density, and municipal infrastructure specialization—that structure procurement segmentation across pharmaceutical, power generation, and water treatment verticals.
| Leading Market Players |
|---|
| EKATO Holding GmbH |
| MGT Liquid & Process Systems |
| Statiflo Group |
| Jongia |
| Fusion Fluid Equipment |
| Philadelphia Mixing Solutions Ltd |
| Mixer Direct |
| Flowserve Corporation |
| KSB SE & Co. KGaA |
| Others |
Supply & Pricing Matrix
Municipal utilities in the United States and Germany anchor procurement volume for gate impeller systems, compressing pricing power toward contract-based long-term offtake models that bundle aftermarket service with initial equipment sales. This buyer concentration forces suppliers to compete on lifecycle cost rather than unit price, while raw material volatility in stainless steel alloys feeds back into margin protection strategies across fabrication tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates simulation-validated closed impellers for pharmaceutical reactors from open-blade configurations serving water treatment basins. Price differentiation hinges on metallurgy grade and REACH-compliant sealing certification, with German-engineered precision systems commanding substantial premiums over commodity fabrications. Cost compression in the standard tier is intensifying because municipal budget constraints in the United States favor retrofit compatibility over performance optimization. Chemical processors demonstrate least price sensitivity due to containment failure risks, while agricultural irrigation operators prioritize energy efficiency metrics that expose them to axial impeller substitution.
Supply Chain Analysis
Single-source vulnerability sits with German precision-mixing engineering houses for simulation-validated geometries, while stainless steel feedstock draws from Chinese and Indonesian nickel processing and German specialty alloy foundries. Raw material dependencies center on corrosion-resistant alloys, elastomer sealing compounds, and precision-machined shaft components. Tariff exposure on Chinese-sourced rare earth elements for high-performance magnets in drive systems presents structural risk for axial configuration suppliers. Distribution runs through OEM-direct channels for large chemical processors and regional distributor networks for municipal utility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gate impellers function as a regulatory compounder where EPA effluent limitations and REACH substance restrictions create replacement demand independent of industrial capacity cycles. Compliance mandates in the United States, Germany, and China establish predictable procurement windows that favor prepared suppliers.
For Market Incumbents: Cement aftermarket service network density in Great Lakes and Ohio River basin utility districts to capture unbundled maintenance contracts separated from capital equipment procurement. Deepen backward integration into corrosion-resistant alloy supply through captive foundry partnerships or long-term offtake agreements with German specialty metallurgy suppliers, insulating margin compression from stainless steel price volatility while blocking emerging entrants from qualified vendor status in pharmaceutical-grade applications. For New Entrants and Emerging Players: Engineering service firms with CFD simulation capability represent the most accessible channel partner type for penetrating pharmaceutical and specialty chemical processor accounts in India and China's Yangtze River basin industrial clusters. Target mid-viscosity chemical slurry applications in Gujarat and Maharashtra zones where incumbent German suppliers create procurement bottlenecks for qualified vendors. Position around rapid retrofit kit customization with shorter project timelines than established engineering houses. For Investors and Strategic Acquirers: Water treatment-focused aftermarket service integrators are the most active acquirer in this space, seeking bolt-on simulation capability to defend positioning as municipal utilities unbundle procurement. Long-term viability favors specialists with verified lifecycle carbon data qualifying for public infrastructure tenders. Watch for MEE enforcement acceleration in Jiangsu and Zhejiang provinces as inflection indicator for Chinese demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Supply | Captive metallurgy sourcing insulates German precision suppliers from nickel price volatility affecting REACH-compliant sealing assemblies. |
| CFD Simulation Capability Acquisition | Engineering houses in Basel and Rhine-Ruhr corridors consolidate design authority through validated custom blade angle development. |
| Retrofit Kit Compatibility Expansion | Modular upgrade paths capture municipal utility replacement cycles compressed by EPA NPDES permit renewal deadlines. |
| Carbon Accounting Data Verification | Embodied-emissions thresholds in EU public tenders create qualification advantages for suppliers with lifecycle transparency. |
| Joint Venture in Yangtze River Basin | Local manufacturing presence accelerates MEE compliance-driven modernization timelines in Jiangsu chemical clusters. |
Research Methodology
Direct dialogue with plant engineers at chemical processing facilities, procurement leads at municipal water treatment districts, aftermarket service heads at power generation operators, and technical directors at precision-mixing engineering houses grounded qualitative findings. Secondary validation drew from EPA enforcement databases, ECHA REACH substance restriction filings, Chinese MEE discharge standard protocols, customs trade data on corrosion-resistant alloy imports, and SEC 10-K disclosures from listed pump and mixing equipment manufacturers. Bottom-up demand modeling across retrofit kit shipments and top-down industrial capacity expansion assessments were triangulated to cross-verify segment-level outputs.
Unit shipment and value estimates across the projection horizon reflect segmentation by impeller architecture, hydraulic technology, process application, and end-user industry vertical. The analytical framework modeled centrifugal versus axial technology substitution patterns, closed versus open impeller containment requirements, and geographic regulatory enforcement intensity as primary demand drivers. CAGRs were derived from equipment replacement cycle compression tied to named regulatory deadlines, overlaying industrial capacity expansion in China's manufacturing corridor cities against agricultural irrigation efficiency priorities in low-shear applications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to stainless steel price volatility, REACH substance restriction amendments, and MEE enforcement intensity variations in Yangtze River basin industrial clusters. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Naval Actuators and Valves Market
Valves
Fluid Power Cylinder Market
Valves
Tubing Heads Market
Valves
Europe Electro Hydraulic Servo Valve Market
Valves
Pipeline Pigging System Market
Valves
Low Voltage (LV) and Medium Voltage (MV) Switchgear Market
Valves
Compressor Valves Market
Valves
Deluge Valve Market
Valves
Chemical Injection Metering Pumps and Valves Market
Valves
GCC and MENA Valves Market
Valves
Actuators and Valves Market
Valves
Global Flow Control Market
Valves
Global Plastic Valves Market
Valves
China Explosion-Proof Equipment Market
Valves
Valve Remote Control System Market
Valves
Industrial Safety Valves Market