
 Penstock Market | 2026-2036
Penstock Market Size, Share, and Industry Trends Forecast 2026-2036
Penstock Market Analysis
Project-specified distribution channels for hydroelectric infrastructure is reshaping how penstock manufacturers engage engineering-procurement-construction consortia. ANDRITZ Hydro leverages its turbine-to-penstock integration capability to anchor turnkey project workflows. AVK Group competes through valve-penstock system bundling that reduces interface risk for contractors. Jash Engineering specializes in custom-fabricated steel penstocks for India's dam modernization pipeline.
A penstock is a pressure conduit that conveys water from a reservoir or forebay to turbines, turbines, or treatment facilities, typically fabricated from welded steel plate with diameters spanning 1 to 12 meters and designed to withstand internal pressures exceeding 20 bar. Steel penstocks dominate large-head hydropower installations due to tensile strength requirements, while fiberglass variants gain traction in corrosive water chemistry environments where cathodic protection costs escalate. Concrete penstocks retain share in low-head irrigation schemes where embedded construction reduces capital outlay. By end user, hydropower plants generate the deepest specification intensity, though water supply utilities are driving inspection services demand as buried infrastructure ages beyond design life.
ISO 10771 governs fatigue testing protocols for welded penstock joints, while the EU Green Deal's embodied carbon requirements are pressuring mills to document steel production emissions. In the United States, FERC dam safety inspections mandate periodic penstock wall-thickness assessments that sustain aftermarket service revenue. Stakeholders must weigh material substitution timelines against the decade-long service intervals that characterize owner capital planning cycles.
Market Dynamics
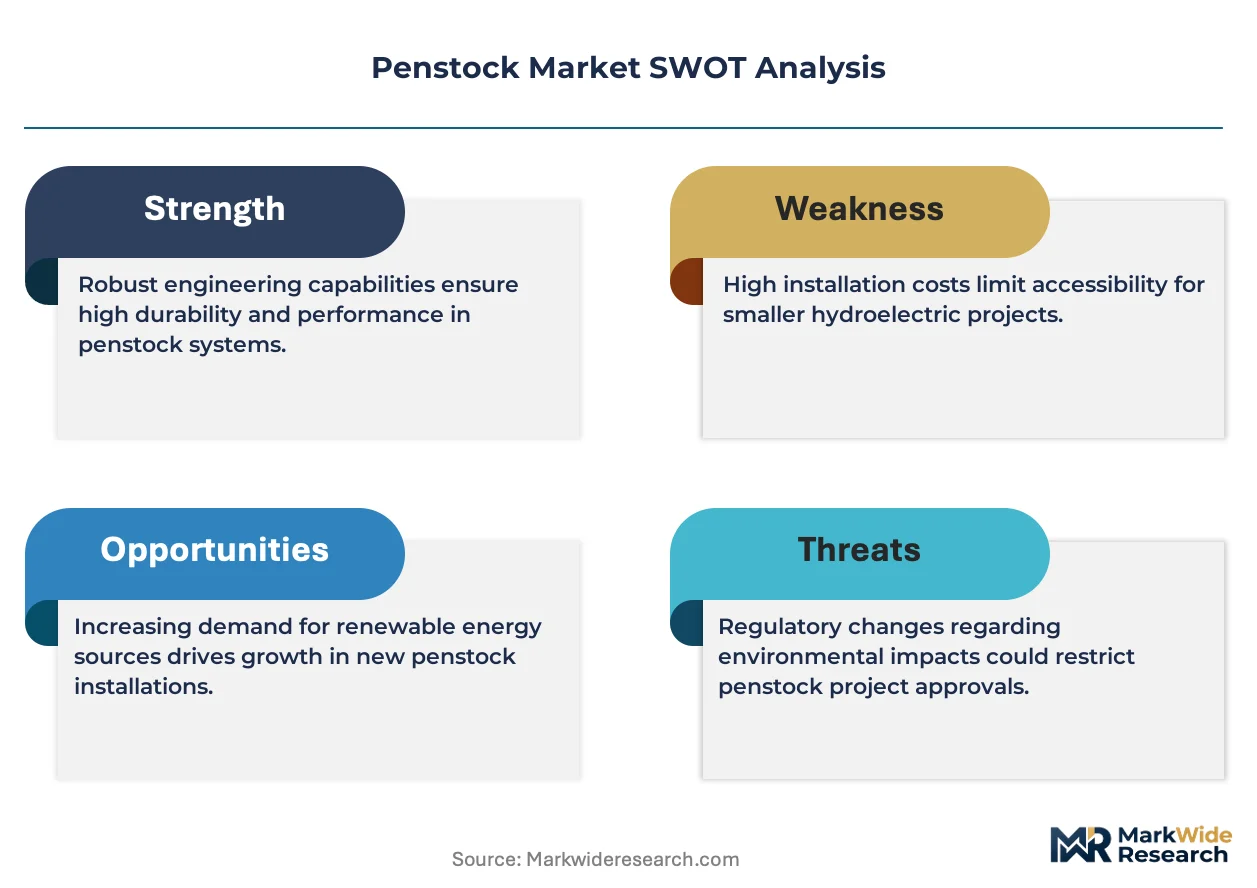
EU Green Deal embodied carbon mandates are forcing steel mills to document Scope 3 emissions across penstock supply chains, compressing procurement timelines for hydropower EPC consortia.
Growth Catalysts
- Dam Modernization Mandates:Germany's federal infrastructure program requires large-diameter steel penstock replacements at aging facilities, creating sustained order flow for fabricators.
- F-Gas Regulation:The EU's tightening specifications on industrial equipment materials are disqualifying certain gasket and seal technologies, favoring welded steel construction over bolted alternatives.
- Fiberglass Technology Maturation:Advanced filament winding processes now produce corrosion-resistant penstocks for saline water chemistry applications where cathodic protection costs previously favored concrete.
Market Restraints
- Steel Input Volatility:Hot-rolled coil price swings at European mills compress fabrication margins on fixed-price EPC contracts.
- Specialized Welder Scarcity:Qualified ASME Section IX certified welders concentrate in Central European industrial clusters, constraining capacity expansion elsewhere.
- Concrete Penstock Persistence:Low-head irrigation schemes in South Asia continue specifying embedded concrete construction for capital cost containment.
Strategic Opportunities
- India Dam Rehabilitation Pipeline:Central Electricity Authority-mandated safety upgrades at state-owned hydro facilities require custom-fabricated steel replacements.
- Digital Twin Integration:Convergence of finite element analysis with IoT sensor networks enables predictive maintenance contracts for buried penstock infrastructure.
- Turnkey System Bundling:Valve-penstock integration packages reduce interface risk for contractors and capture higher-margin installation revenue.
Industry Challenges
- ISO 10771 Fatigue Certification:Welded joint testing protocols extend qualification timelines for new fabrication entrants.
- Legacy Concrete Assessment:Embedded infrastructure condition evaluation requires specialized ultrasonic inspection capabilities that concentrate among established service providers.
- Cross-Border Logistics Coordination:Oversized steel penstock segments face rail gauge and road clearance constraints across European transport networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Penstock Market |
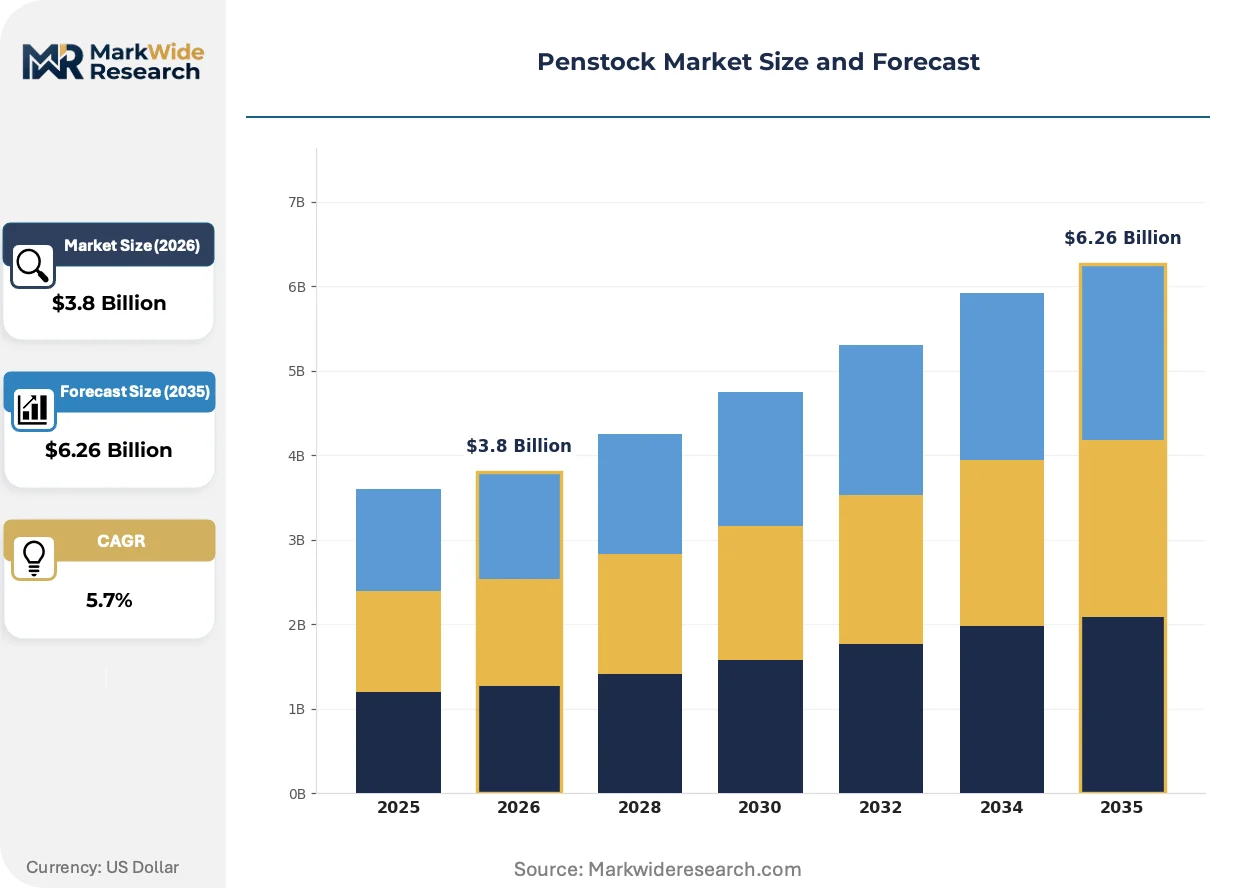
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
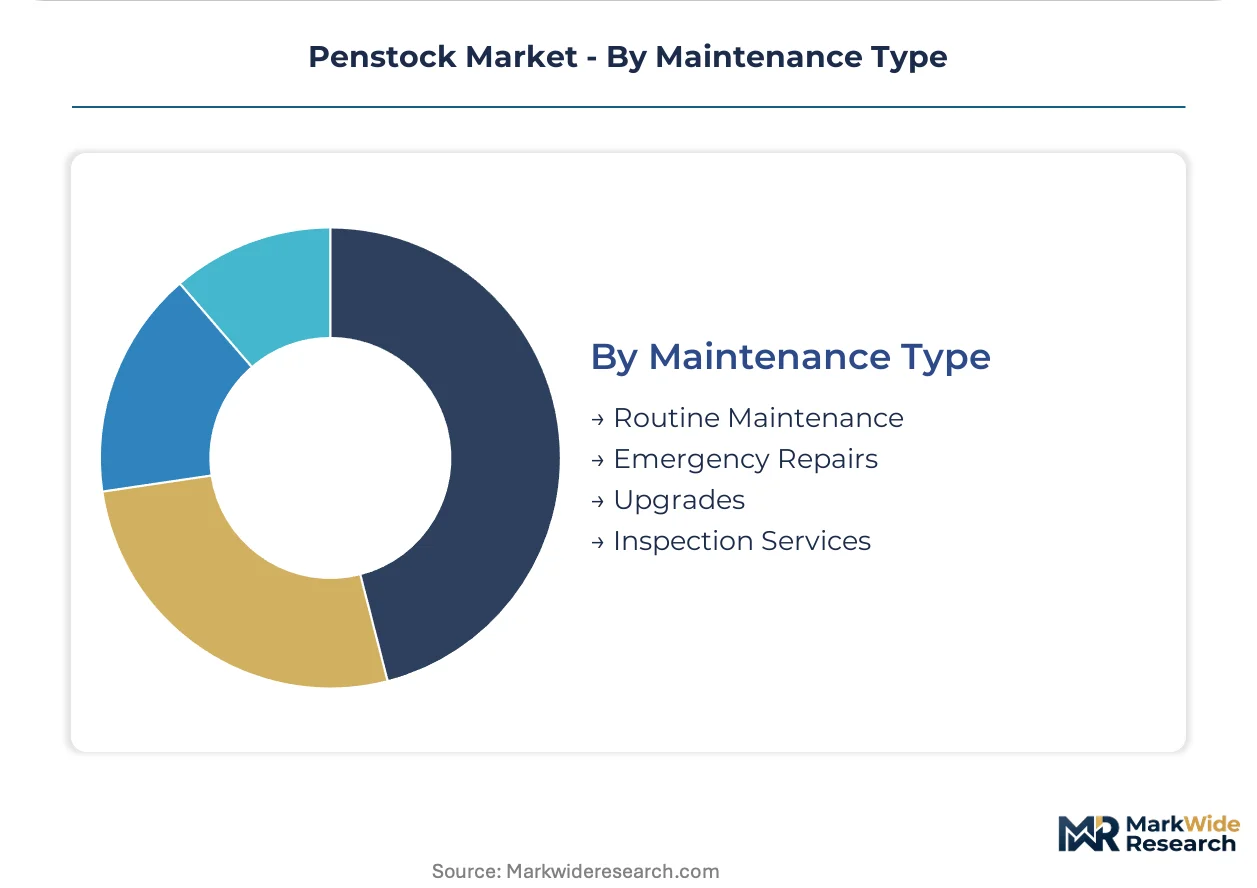
| Segmentation | Product Type: Steel Penstock, Concrete Penstock, Fiberglass Penstock, Composite Penstock Installation Type: Above Ground, Below Ground, Horizontal, Vertical End User: Hydropower Plants, Water Supply Utilities, Irrigation Systems, Manufacturing Facilities Maintenance Type: Routine Maintenance, Emergency Repairs, Upgrades, Inspection Services |
| Companies Covered | Fernco, Jash Engineering, AVK Group, Awma Water Control Solutions, ANDRITZ Hydro, WAMGROUP, Australian Penstock & Damper Valve Company, ORBINOX, Aqseptence Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Penstock Market Emerging Trajectories
Digital fabrication methods and embedded carbon tracking are compressing traditional procurement cycles while opening new service revenue streams for inspection and predictive maintenance.
Filament-wound fiberglass penstocks with vinyl ester resin matrices now withstand internal pressures exceeding 15 bar in corrosive environments. Water treatment utilities in coastal Spain and Portugal are specifying these for brackish intake systems. Cathodic protection engineering for steel alternatives is rendering obsolete traditional cost comparisons in high-chloride applications.
The EU Green Deal's embodied carbon disclosure requirements now cover imported steel for infrastructure projects. Mills must provide Environmental Product Declarations verified against EN 15804. German and Austrian hydropower developers are prioritizing domestic European steel sources to satisfy procurement scoring criteria.
Engineering-procurement-construction consortia now demand integrated valve-penstock packages with single-source warranty coverage. This specification pattern displaces fragmented component sourcing for contractors. The model concentrates in German dam modernization tenders where interface risk allocation drives contractor preference.
Penstock Market Segmentation

Penstock procurement patterns diverge sharply across material specifications and installation contexts. Hydropower developers prioritize pressure-rated steel for high-head installations, while water utilities balance corrosion resistance against buried infrastructure lifecycle costs.
Product Type:
Cost tier separation between materials drives specification divergence across project types and operating environments.
- Steel Penstock:Welded carbon or stainless steel plate construction withstands internal pressures exceeding 20 bar in high-head hydropower installations. German dam modernization programs and India's Central Electricity Authority-mandated safety upgrades concentrate demand for large-diameter replacements. Steel mills face EU Green Deal embodied carbon documentation requirements that compress procurement timelines.
- Concrete Penstock:Embedded reinforced concrete construction dominates low-head irrigation schemes in South Asia where capital cost containment outweighs pressure performance. Embedded installation eliminates joint complexity but complicates condition assessment and limits pressure ratings.
- Fiberglass Penstock:Filament-wound vinyl ester resin matrices serve brackish water intake systems at coastal Spanish and Portuguese treatment facilities. Corrosion resistance eliminates cathodic protection engineering costs in high-chloride chemistries.
- Composite Penstock:Hybrid material systems combining structural cores with corrosion barriers address niche pressure-corrosion tradeoffs in specialized industrial applications.
Steel penstock holds installed capacity. Fiberglass penstock is rotating up the share rankings.
Installation Type:
Application context determines access requirements, joint configuration, and inspection protocol selection.
- Above Ground:Exposed steel installations at hydropower facilities enable direct visual inspection and simplify emergency access for wall-thickness assessments mandated by FERC dam safety protocols in the United States.
- Below Ground:Buried configurations predominate in water supply utility networks where urban land constraints and aesthetic requirements drive placement. Digital twin integration with IoT sensor networks enables predictive maintenance contracts for inaccessible infrastructure.
- Horizontal:Standard alignment for penstock runs from forebay to powerhouse, minimizing head loss through gradual elevation change.
- Vertical:Shaft configurations in mountainous terrain or deep intake structures require specialized thrust restraint and joint design.
Below ground installations dominate utility procurement volumes. Above ground specifications are climbing the fastest in hydropower rehabilitation contracts.
End User:
Customer type dictates specification intensity, procurement channel, and service attachment rates.
- Hydropower Plants:Generate deepest engineering specification intensity with pressure ratings, fatigue certification under ISO 10771, and integrated valve-penstock system bundling to reduce EPC contractor interface risk. German and Austrian developers prioritize domestic European steel sources for procurement scoring.
- Water Supply Utilities:Drive inspection services demand as buried infrastructure ages beyond design life. FERC-mandated periodic wall-thickness assessments sustain aftermarket service revenue in the United States.
- Irrigation Systems:Low-head schemes in South Asia specify concrete penstocks for capital cost containment.
- Manufacturing Facilities:Industrial process water applications require corrosion-resistant materials for chemical exposure environments.
Hydropower plants anchor fabrication order books. Water supply utilities are expanding the fastest in inspection and digital service attachments.
Maintenance Type:
Service revenue stratification follows asset age profiles and regulatory inspection mandates across owner categories.
- Routine Maintenance:Scheduled joint inspection and coating renewal programs extend service life for steel installations in accessible above-ground configurations.
- Emergency Repairs:Unplanned intervention for leakage or structural compromise requires specialized ASME Section IX certified welder deployment, with talent concentration in Central European industrial clusters constraining response capacity.
- Upgrades:Capacity expansion or pressure rating enhancement projects at aging facilities drive steel replacement demand in Germany's federal infrastructure program.
- Inspection Services:Ultrasonic wall-thickness assessment for embedded concrete and buried steel infrastructure concentrates among established service providers with specialized capabilities.
Inspection services hold contract volume concentration. Upgrade projects are gaining share fastest in European dam modernization tenders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor anchors European penstock demand through Germany's federal dam modernization pipeline. India's Central Electricity Authority-mandated safety upgrades at state-owned hydro facilities concentrate Asian procurement volumes.
Germany
Federal infrastructure programs require large-diameter steel penstock replacements at aging hydropower stations. The EU Green Deal's embodied carbon documentation requirements compress procurement timelines for domestic steel mills. Bavarian industrial clusters around Nuremberg host specialized fabrication capacity serving Austrian and Swiss cross-border projects.
United States
FERC dam safety inspections mandate periodic penstock wall-thickness assessments that sustain aftermarket service revenue. The Federal Energy Regulatory Commission's aging infrastructure protocols drive rehabilitation contracts at Pacific Northwest hydroelectric facilities. Colorado and California utilities concentrate buried steel replacement demand in municipal water supply networks.
India
Central Electricity Authority safety upgrades at state-owned hydro facilities require custom-fabricated steel penstock replacements. Bureau of Indian Standards certification protocols govern welded joint specifications for domestic fabrication. Maharashtra and Karnataka host established metalworking clusters supplying penstock components to dam rehabilitation projects across the Western Ghats.
Spain
Brackish water intake systems at coastal treatment facilities specify filament-wound fiberglass penstocks for corrosion resistance. The country's national water utility regulator enforces infrastructure lifecycle cost assessments that favor composite materials in high-chloride environments. Catalan engineering firms specialize in vinyl ester resin matrix applications for Mediterranean coastal installations.
Australia
Murray-Darling Basin irrigation authorities evaluate penstock materials for saline water conveyance efficiency. The country's national infrastructure safety framework requires condition assessments for embedded concrete assets exceeding design life. New South Wales regional water utilities drive inspection service demand for buried steel infrastructure in Greater Sydney supply networks.
Penstock Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in material supply and discrete fabrication. The vendor base separates into consolidated turnkey providers and fragmented regional metalworkers. Three archetypes dominate: turbine-to-penstock integrators, valve-penstock bundlers, and custom steel fabricators. Strategic moves concentrate on integrated system warranties and cross-border logistics partnerships for oversized segment transport.
Among diversified industrial groups, ANDRITZ Hydro exemplifies the platform integrator archetype through turbine-to-penstock workflow anchoring. AVK Group occupies a position within the valve-penstock bundling tier, representing interface-risk reduction strategies for EPC contractors. Jash Engineering sits within the custom fabrication specialist category, exemplifying regionally concentrated steel penstock production for dam modernization pipelines.
| Leading Market Players |
|---|
| Fernco |
| Jash Engineering |
| AVK Group |
| Awma Water Control Solutions |
| ANDRITZ Hydro |
| WAMGROUP |
| Australian Penstock & Damper Valve Company |
| ORBINOX |
| Aqseptence Group |
| Others |
Supply Flow & Price Mechanics
The Bavarian industrial cluster around Nuremberg anchors European fabrication capacity, with hot-rolled coil input costs and ASME-certified welder scarcity concentrating pricing power among established steel penstock producers serving German dam modernization programs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with ISO 10771 fatigue certification and domestic European steel sourcing under EU Green Deal scoring driving premium tier premiums. Cost compression in standard-tier fixed-price EPC contracts intensifies as hot-rolled coil volatility at European mills squeezes fabrication margins. Water supply utilities exhibit highest price sensitivity due to municipal budget constraints, while hydropower developers prioritize certification and integration warranties over unit cost.
Supply Chain Analysis
Extended payment terms from German and Austrian hydropower developers to EPC consortia cascade upstream to steel mills, compressing working capital cycles for fabricators. Supply concentrates in Germany, India, and Austria, with hot-rolled coil, welding consumables, and vinyl ester resin feeding production. Single-source vulnerability around ASME Section IX certified welder pools in Central European clusters poses structural risk. Distribution runs through engineering-procurement-construction consortia with integrated valve-penstock bundling specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin integration with IoT sensor networks is reshaping penstock market economics, creating platform-based predictive maintenance ecosystems that displace transactional component sales with recurring service revenue streams.
For Market Incumbents: Build certification moats through accelerated ISO 10771 fatigue testing infrastructure investment ahead of EU Green Deal Scope 3 documentation mandates. Anchor turnkey system bundling capabilities to capture valve-penstock integration premiums and defend against emerging fiberglass entrants in coastal corrosion applications. Prioritize captive supply of domestic European steel sources to satisfy procurement scoring criteria. For New Entrants and Emerging Players: India's Central Electricity Authority-mandated dam rehabilitation pipeline represents the most penetrable entry point, with custom-fabricated steel replacement demand outpacing domestic fabrication capacity. Coastal Spanish and Portuguese water treatment utilities seeking brackish intake corrosion resistance offer fiberglass specialization white space. Partner with established ultrasonic inspection service providers to embed condition assessment capabilities into initial equipment supply. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture infrastructure play because dam safety mandates and embodied carbon documentation requirements create durable barriers to unqualified entrants. Target acquisition archetypes combine digital twin software capabilities with established ASME-certified fabrication footprints. Monitor FERC inspection mandate enforcement intensity in the United States as aftermarket service revenue inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Valve-Penstock System Bundling | Single-source warranty coverage reduces EPC contractor interface risk in German tenders. |
| Digital Twin Platform Development | IoT sensor convergence enables predictive maintenance contracts for buried utility infrastructure. |
| Domestic Steel Sourcing Certification | EU Green Deal embodied carbon scoring prioritizes European mill Environmental Product Declarations. |
| Fiberglass Filament Winding Capacity | Vinyl ester resin matrices address high-chloride coastal applications in Spain and Portugal. |
| ASME Welder Training Pipeline | Certified talent concentration in Central European clusters constrains competitor capacity expansion. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with hydropower EPC procurement officers, dam safety engineering consultants, steel fabrication plant managers, and utility infrastructure directors; and secondary validation through FERC dam safety filings, EU Green Deal technical documentation, Bureau of Indian Standards certification protocols, and customs trade data on hot-rolled coil movements. Bottom-up project pipeline assessment triangulated against top-down market size estimation.
Forecast inputs considered material substitution timelines, regulatory compliance cost trajectories, and owner capital planning cycle durations across the analysis window. Segmentation modeling captured product type tiering, installation context access requirements, end-user specification intensity, and maintenance service attachment patterns. CAGRs derived from project backlog analysis and replacement cycle normalization, with steel input cost volatility and welder availability constraints as industry-specific demand modifiers.
Practitioners should monitor EU Green Deal Scope 3 documentation enforcement intensity, FERC inspection mandate expansion, and fiberglass pressure rating advancement for early signals of structural shift. Forecasts reflect assumptions of sustained dam modernization program funding and stable hot-rolled coil supply. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Industrial Safety Valves Market
Valves
Choke Valves Market
Valves
United States Valves Market
Valves
Global Gas Pressure Regulator Market
Valves
Vacuum Insulated Pipe Market
Valves
North America Residential Ball Valves Market
Valves
Tubing Heads Market
Valves
Portable Valve Actuator Market
Valves
Actuators and Valves Market
Valves
Safety Valve Test Benches Market
Valves
Battery Safety Valve Market
Valves
Global Control Valves Market
Valves
Tank Hydrogen Valve Market
Valves
Safety Valve Market
Valves
Fin Tube Market
Valves
Naval Actuators and Valves Market