
 Limited-Service Restaurants Market | 2026-2036
Limited-Service Restaurants Market Size, Share, and Industry Trends Forecast 2026-2036
Limited-Service Restaurants Market Analytics
The EU Green Deal's packaging waste directives is shifting how limited-service chains design disposable serviceware and portion formats. McDonald's leverages its global procurement scale to pilot fiber-based packaging alternatives across European markets. Domino's Pizza anchors its competitive position through integrated delivery logistics technology that reduces per-order material intensity. Subway differentiates with made-to-order formats that generate less pre-consumer food waste than batch-prepared competitors.
Limited-service restaurants are foodservice establishments where patrons order at a counter or terminal and receive food without traditional table service, typically completing transactions in under five minutes with average check sizes below full-service equivalents. Drive-thru infrastructure dominates capital allocation among top chains, with dedicated vehicle lanes generating sustained throughput advantages in suburban and exurban locations. Counter service formats retain the largest share of urban footprint where real estate constraints limit vehicle queue space, while delivery partnerships with third-party platforms represent the fastest-expanding service type as ghost kitchen configurations reduce front-of-house requirements. Combo meals within the pricing model concentrate margin pools through engineered menu architecture that lifts average transaction value above a la carte baselines.
The FDA's Food Safety Modernization Act shapes ingredient traceability requirements across US-based supply chains, while the EPA's food waste reduction targets pressure operators to reformulate preparation protocols. REACH compliance in Europe restricts certain food-contact substances, compelling reformulation of coatings and adhesives in disposable packaging. Stakeholders must monitor how divergent regulatory timelines between North American and European jurisdictions create compliance complexity for chains operating across both markets.

Market Dynamics
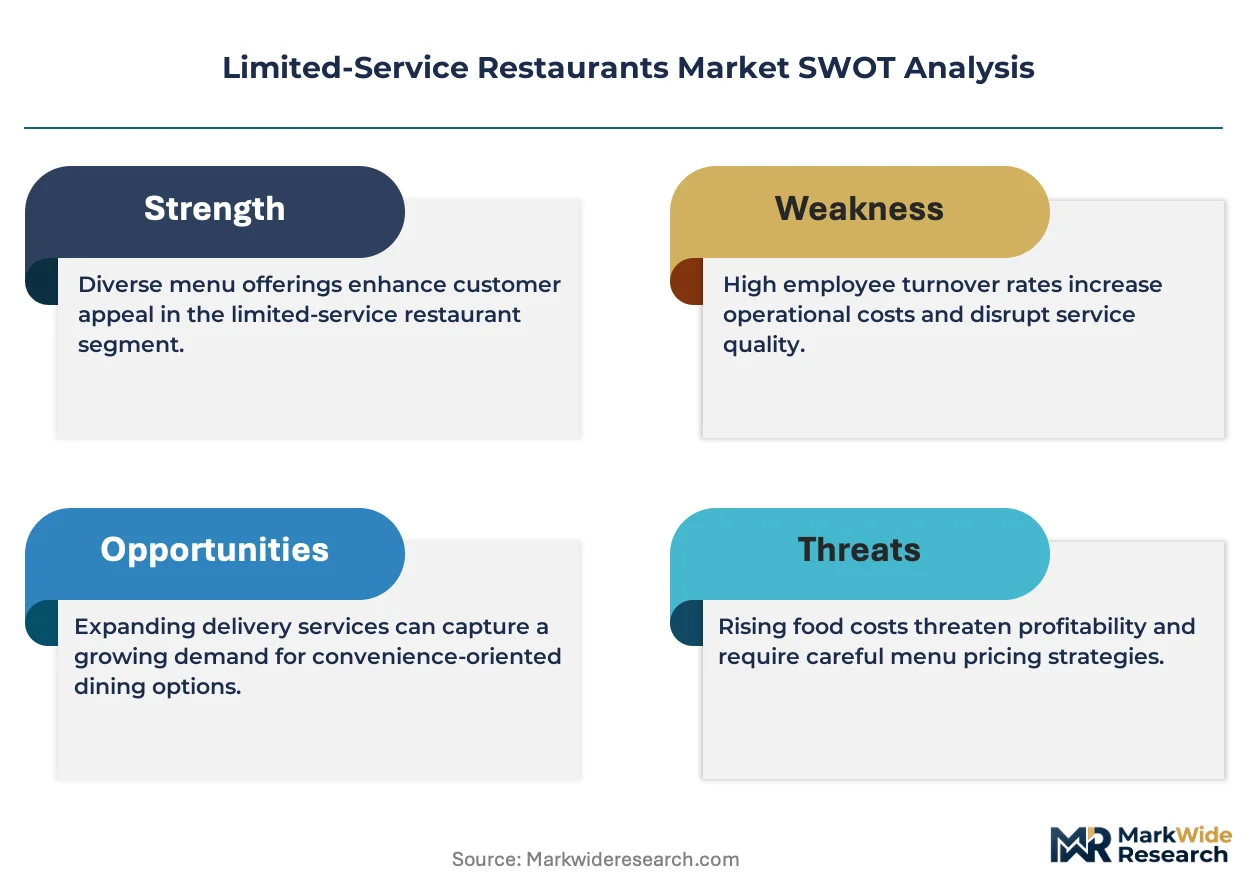
Digital ordering infrastructure is compressing front-of-house labor requirements while EU packaging directives force simultaneous capital redeployment into sustainable serviceware. Chains must balance throughput velocity against compliance timelines.
Growth Catalysts
- EU Green Deal packaging mandates:Fiber-based alternatives command premium positioning as single-use plastics phase out across member states.
- Urban professional consumption:Mobile-first ordering platforms capture commute-window demand in dense metropolitan corridors.
- Drive-thru throughput engineering:Dedicated vehicle lanes sustain volume advantages in suburban real estate configurations.
Market Restraints
- Input cost volatility:Protein and cooking oil prices swing with commodity futures, compressing menu margin flexibility.
- Supply concentration risk:Third-party delivery platforms extract 15-30% per-order fees, eroding operator economics.
- Technical limitation:Frozen dough and pre-portioned proteins constrain freshness differentiation against fast-casual competitors.
Strategic Opportunities
- Ghost kitchen expansion:Delivery-only formats strip front-of-house capital requirements in high-rent urban zones.
- AI-driven demand forecasting:Machine learning models reduce pre-consumer food waste below batch-prepared baselines.
- US Sun Belt corridor density:Population migration into Texas, Florida, and Arizona metro areas concentrates addressable demand.
Industry Challenges
- Cross-jurisdictional compliance:Divergent FDA and REACH timelines force dual-track packaging reformulation programs.
- Legacy POS integration:Franchise systems struggle to unify fragmented technology stacks across decades-old hardware.
- Labor scheduling optimization:Predictive workforce platforms require data infrastructure most operators lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Limited-Service Restaurants Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Counter Service, Delivery, Drive-Thru, Takeout Customer Type: Individuals, Families, Students, Professionals Menu Category: Burgers, Pizza, Sandwiches, Salads Pricing Model: Value Menu, Premium Offerings, Combo Meals, Bundle Deals |
| Companies Covered | Hunt Brothers Pizza, Domino’s Pizza, Subway, Burger King, Pizza Hut, Starbucks, Taco Bell, Wendy’s, McDonald's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Limited-Service Restaurants Market Evolving Landscape
Kitchen automation and regulatory packaging mandates are converging to reshape capital deployment patterns. Operators face simultaneous pressure to reduce labor intensity and material environmental impact.
Computer vision-enabled cooking stations are automating fryer and grill operations in high-volume locations. Chains with 500+ unit footprints deploy these systems to standardize output consistency. The technology is automating line-cook roles that previously required six-month training curves.
REACH compliance deadlines are accelerating coating and adhesive reformulation across European supply chains. Food-contact substance restrictions force packaging suppliers to certify fiber-based alternatives by 2026. Quick-service operators in Germany, France, and Netherlands markets face compressed procurement timelines.
Subscription-based meal programs are displacing traditional transaction-by-transaction purchasing among remote workers. Corporate campus contracts and residential building partnerships now aggregate individual orders into batch delivery windows. This shift concentrates most visibly in Seattle, Austin, and Denver metropolitan corridors where hybrid work patterns stabilized post-pandemic.
Limited-Service Restaurants Market Segmentation
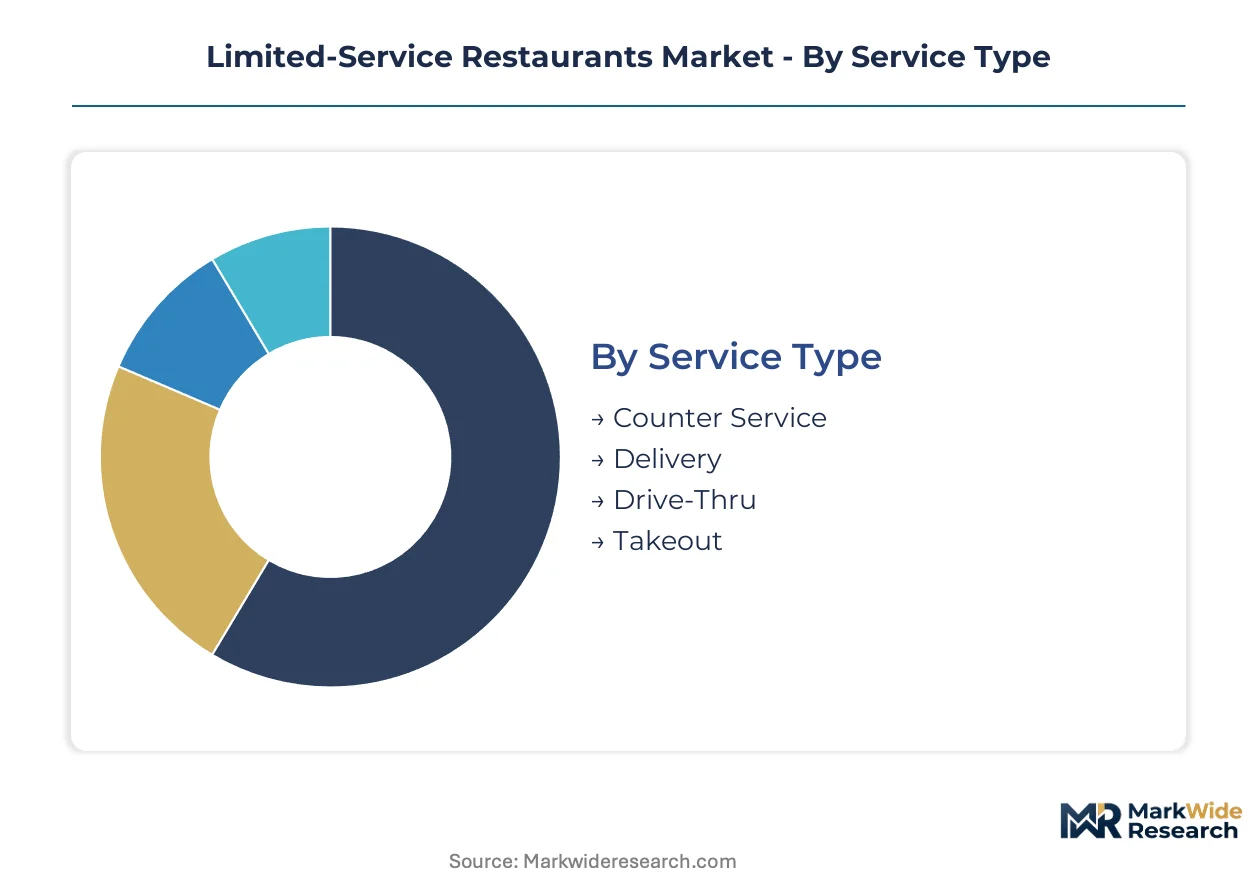
Limited-service restaurants deploy distinct operational configurations to match real estate constraints and consumer time budgets. Segmentation reveals how capital allocation, labor deployment, and menu engineering vary across service modalities and customer cohorts.
Service Type:
Operators upgrade service infrastructure in response to shifting time-utility preferences and real estate availability, with each format demanding different capital intensity and throughput optimization.
- Counter Service:Patrons order at fixed terminals or staffed points before receiving food at pickup stations. Dense urban corridors in New York, London, and Tokyo concentrate demand where vehicle queue space is unavailable.
- Delivery:Third-party platform integration or captive logistics networks transport prepared items to residential or workplace locations. Ghost kitchen configurations in Austin, Denver, and Seattle are stripping front-of-house requirements entirely.
- Drive-Thru:Dedicated vehicle lanes with sequential menu boards and payment windows sustain throughput advantages. Suburban Dallas, Houston, and Phoenix corridors allocate disproportionate capital to dual-lane and triple-lane configurations.
- Takeout:Advance digital ordering with in-store retrieval minimizes dwell time. Mobile-first professionals in Chicago, Los Angeles, and Miami metro areas drive adoption during commute windows.
Drive-Thru sits at the top of the volume ranking, with Delivery climbing the fastest.
Customer Type:
Menu architecture and promotional cadence calibrate to distinct consumption occasions, with each cohort presenting different price elasticity and frequency patterns.
- Individuals:Solo diners prioritize speed and portion control over social seating arrangements. Remote workers in Seattle and Austin residential clusters sustain mid-afternoon demand troughs that batch-preparation kitchens struggle to fill.
- Families:Multi-person parties concentrate spending around weekend lunch and dinner dayparts. Value-menu engineering and toy-inclusive offerings target parents in Orlando, San Antonio, and Atlanta suburban corridors.
- Students:Campus-adjacent locations capture price-sensitive demand with limited transportation options. University towns including Chapel Hill, Ann Arbor, and Boulder concentrate late-night operating hour extensions.
- Professionals:Time-constrained white-collar workers trade margin for convenience during compressed meal windows. Corporate campus contracts in Silicon Valley, Boston's Route 128, and Manhattan's Midtown district aggregate individual orders into batch delivery windows.
Professionals generate the highest per-transaction value, with Families showing the steepest expansion trajectory as suburban population migration accelerates.
Menu Category:
Protein format and preparation complexity dictate equipment requirements, supply chain specifications, and margin architecture across kitchen configurations.
- Burgers:Fresh or frozen beef patties with standardized topping configurations dominate capital allocation for grill and holding equipment. Sun Belt metro corridors in Texas, Arizona, and Florida sustain volume leadership through drive-thru dominance.
- Pizza:Oven-intensive preparation with extended cook times requires distinct real estate footprints and delivery logistics integration. Detroit, Chicago, and New York metro areas anchor regional style differentiation.
- Sandwiches:Cold or toasted assembly formats with made-to-order customization generate less pre-consumer waste than batch-prepared alternatives. Subway, Jimmy John's, and similar chains concentrate in downtown business districts and highway interchanges.
- Salads:Perishable ingredient management and limited holding times constrain location economics to high-turnover urban corridors. Los Angeles, San Diego, and Denver health-conscious demographics sustain premium pricing acceptance.
Burgers command the largest revenue pool, with Salads gaining share fastest among urban professional segments.
Pricing Model:
Transaction architecture engineers average check elevation through bundled combinations and tiered entry points calibrated to occasion and cohort.
- Value Menu:Restricted-item, restricted-size offerings establish price-floor accessibility without diluting core menu margins. Dollar-menu descendants in McDonald's, Burger King, and Wendy's systems target price-sensitive students and families.
- Premium Offerings:Upscale ingredient specifications and larger portion formats capture willingness-to-pay among affluent professionals. Shake Shack, Five Guys, and similar positioned chains concentrate in coastal metropolitan corridors.
- Combo Meals:Engineered bundling of entree, side, and beverage lifts transaction value above a la carte baselines. Drive-thru operators in suburban Dallas, Atlanta, and Phoenix metro areas maximize combo attachment rates through menu board architecture.
- Bundle Deals:Multi-person packaging with family-sized portions and variety configurations targets group occasions. Weekend dayparts in Orlando, Las Vegas, and Branson tourism corridors sustain promotional intensity.
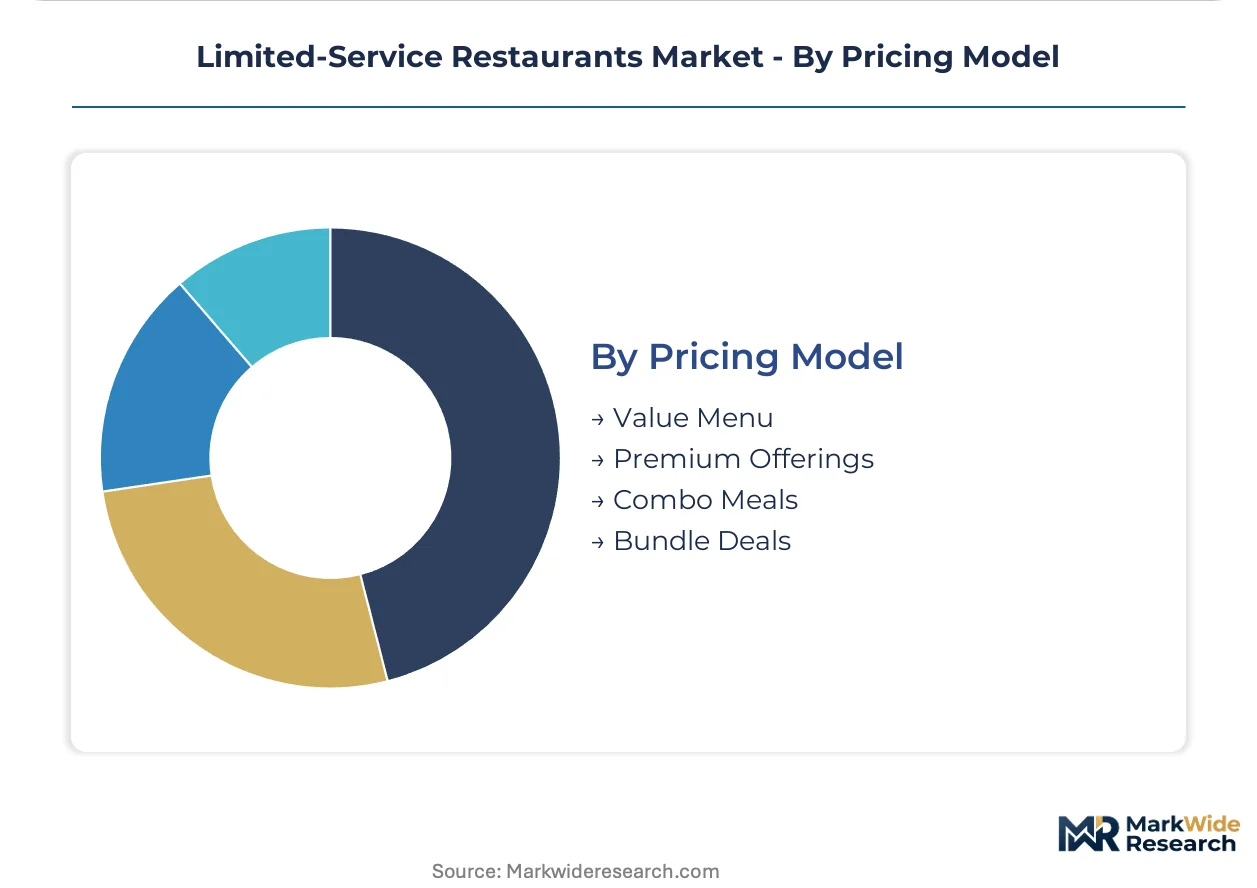
Combo Meals anchor the majority of transaction volume, with Premium Offerings expanding most quickly as fast-casual crossover intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern limited-service restaurant format traces its lineage to post-war American drive-in culture, with the United States pioneering standardized quick-service systems that later diffused to European and Asian markets through franchise expansion.
United States
Sun Belt metropolitan corridors in Texas, Florida, and Arizona concentrate new unit development as population migration accelerates. The FDA's Food Safety Modernization Act mandates ingredient traceability across multi-state supply chains. Dallas-Fort Worth and Houston metro areas allocate disproportionate capital to triple-lane drive-thru configurations that maximize suburban throughput.
Germany
Urban professionals in Berlin, Munich, and Hamburg drive demand for mobile-first ordering platforms during compressed commute windows. REACH compliance deadlines force packaging suppliers to certify fiber-based alternatives by 2026. The Rhine-Ruhr industrial corridor hosts concentrated ghost kitchen development as delivery-only formats strip front-of-house requirements.
United Kingdom
London's dense metropolitan core sustains counter-service dominance where vehicle queue space is unavailable. The UK's post-Brexit regulatory divergence from EU packaging timelines creates dual-track compliance complexity for chains operating across both jurisdictions. Manchester and Birmingham corridors anchor regional drive-thru expansion into suburban catchments.
Japan
Tokyo's Kanto region and Osaka's Kansai corridor concentrate demand for ultra-efficient transaction formats suited to extreme time constraints. METI guidelines on food waste reduction pressure operators to reformulate preparation protocols. Nagoya's Chubu region hosts pilot deployments of computer vision-enabled cooking stations in high-volume locations.
Australia
Sydney and Melbourne metropolitan areas sustain premium-positioned fast-casual crossover concepts with health-conscious demographics. The country's national environmental regulator enforces packaging waste reduction targets that accelerate sustainable serviceware adoption. Brisbane and Perth corridors concentrate drive-thru development as suburban population density increases.
Limited-Service Restaurants Market Competitive Landscape
Capital-heavy operators with extensive real estate footprints compete with asset-light digital-native entrants that rely on third-party logistics networks. The market structure consolidates around chains with 500+ unit footprints capable of amortizing technology investments across system-wide scale. Three archetypes dominate: vertically integrated legacy chains controlling supply chain and real estate, platform-dependent aggregators leveraging delivery infrastructure, and fast-casual specialists commanding premium positioning through ingredient differentiation. M&A activity concentrates on technology capabilities and regional market access, while strategic partnerships with ghost kitchen operators expand addressable demand without proportional capital deployment.
Within the vertically integrated tier, McDonald's and Domino's Pizza exemplify scale-driven operators that anchor competitive dynamics through procurement leverage and logistics control. Subway occupies a position as the made-to-order specialist with distributed real estate footprints in highway interchanges and downtown business districts. Starbucks represents the premium-positioned archetype that commands pricing power through brand equity and beverage-centric repeat purchase patterns.
| Leading Market Players |
|---|
| Hunt Brothers Pizza |
| Domino's Pizza |
| Subway |
| Burger King |
| Pizza Hut |
| Starbucks |
| Taco Bell |
| Wendy's |
| McDonald's |
| Others |
Value Network & Pricing Analysis
EU Green Deal packaging mandates are compelling operators to absorb fiber-based serviceware premiums while simultaneously engineering menu formats that preserve margin pools. Chains must recalibrate procurement strategies as sustainable packaging transitions from positioning advantage to compliance baseline.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by occasion and cohort. Price differentiation hinges on ingredient quality grade and geographic delivery cost, with suburban drive-thru operators commanding throughput-driven margin advantages. Pricing pressure stems from third-party delivery platform fees that extract substantial per-order revenue. Students and price-sensitive families exhibit highest elasticity, while time-constrained professionals accept premium positioning for convenience.
Supply Chain Analysis
Domestic-content requirements in the EU and emerging US state-level packaging regulations are reshaping sourcing patterns for fiber-based alternatives. Protein and cooking oil inputs draw from concentrated agricultural regions in the United States, Brazil, and Argentina. Single-source vulnerability in third-party logistics networks creates exposure during peak demand windows. Distribution runs through multi-temperature cold chain networks anchored by regional distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Limited-service restaurant economics favor margin expansion through ghost kitchen formats that strip front-of-house capital intensity while capturing delivery-premium pricing.
For Market Incumbents: Deepen vertical control over last-mile logistics to offset third-party platform fee erosion. Consolidate procurement scale across fiber-based packaging transitions mandated by EU REACH deadlines. Defensive positioning requires AI-driven demand forecasting that reduces pre-consumer waste below batch-prepared baselines. For New Entrants and Emerging Players: Begin with delivery-only ghost kitchen configurations in Sun Belt metropolitan corridors where population migration concentrates addressable demand. Target mid-afternoon demand troughs that remote workers in Austin, Denver, and Seattle residential clusters sustain. Anchor go-to-market strategy through corporate campus subscription contracts that aggregate individual orders into batch delivery windows. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-enabled operators that automate kitchen operations and standardize output consistency. Long-term viability favors chains capable of amortizing computer vision-enabled cooking stations across 500-plus unit footprints. Monitor AI-driven workforce scheduling adoption as inflection indicator for operational efficiency leadership.| Strategic Initiative | Industry Significance |
|---|---|
| Ghost Kitchen Expansion | Strips front-of-house capital requirements in high-rent urban zones like Manhattan and London. |
| AI-Driven Demand Forecasting | Reduces pre-consumer food waste below batch-prepared baselines for Subway-style made-to-order formats. |
| Fiber-Based Packaging Transition | Positions operators ahead of EU REACH compliance deadlines across Germany, France, and Netherlands markets. |
| Drive-Thru Throughput Engineering | Maximizes suburban volume advantages in Dallas-Fort Worth and Phoenix metro corridors. |
| Corporate Subscription Partnerships | Aggregates individual orders into batch delivery windows for remote workers in Seattle and Austin. |
Research Methodology
Multiple input streams — executive interviews with quick-service chain operators, procurement discussions with packaging suppliers, and operational data from ghost kitchen developers — were reconciled against regulatory filings and trade association datasets. Primary fieldwork captured perspectives from franchise development officers, supply chain directors, and third-party logistics coordinators. Secondary validation drew from FDA Food Safety Modernization Act guidance documents, EU ECHA REACH substance restrictions, and municipal health department inspection records. Bottom-up unit economics modeling and top-down market sizing were cross-referenced for triangulation.
Historical transaction velocity patterns were cross-referenced against panel input from multi-unit operators to construct projection frameworks. Segmentation dimensions modeled include service type, customer cohort, menu category, and pricing architecture across the analysis window. CAGRs were derived from regression analysis of unit development trajectories and per-location revenue benchmarks. Forecast inputs incorporated drive-thru throughput engineering investments and EU packaging compliance timeline acceleration.
Caveats apply where commodity protein and cooking oil price volatility or divergent regulatory timelines between FDA and REACH jurisdictions could materially shift the outlook. Forecasts reflect documented assumptions regarding population migration patterns and hybrid work stabilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Qatar Food Service Market
Food Service
Peer-To-Peer Dining Market
Food Service
Street Vendors Market
Food Service
Bar Refrigeration Market
Food Service
One-Off Chopsticks Market
Food Service
Portion Cups Market
Food Service
Global Dark Store Market
Food Service
Quick-Service Restaurants Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
Catering Food Warmers Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
A La Carte Market
Food Service
Shaker Bottles Market
Food Service
Food Delivery Services Market
Food Service
Restaurant Griddle Market