
 North America Food Platform-To-Consumer Delivery Market | 2026-2036
North America Food Platform-To-Consumer Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Platform-To-Consumer Delivery Market Analytics
Platform-to-consumer food delivery is reconfiguring how restaurants reach households without owning physical dining infrastructure. DoorDash, Inc. leverages its logistics density to sustain same-day coverage across suburban and exurban zones. Uber Technologies Inc. anchors cross-utilization of its driver network between meal and ride-hail dispatch. Grubhub Inc. competes through corporate account penetration and campus dining contracts.
Food platform-to-consumer delivery denotes a digitally intermediated fulfillment system where aggregated restaurant or grocery inventory is matched to end consumers via algorithmic dispatch, mobile interface, and contracted courier networks. GPS tracking and automated dispatch coordinate order handoff timing within narrow delivery windows measured in minutes. Restaurant delivery commands the largest revenue pool, while grocery delivery represents the fastest-expanding service type as platform infrastructure adapts to perishable handling. Subscription-based delivery models concentrate recurring revenue and reduce customer acquisition costs relative to on-demand ordering.
The US Department of Labor, Health Canada, and the Canadian Food Inspection Agency govern food safety, courier classification, and cross-border platform operations across the North American footprint. Labor reclassification proceedings in California and Ontario directly threaten variable cost structures that underpin platform unit economics. Stakeholders must monitor regulatory divergence between US federal contractor rules and provincial labor codes as compliance fragmentation escalates operating complexity.
Market Dynamics
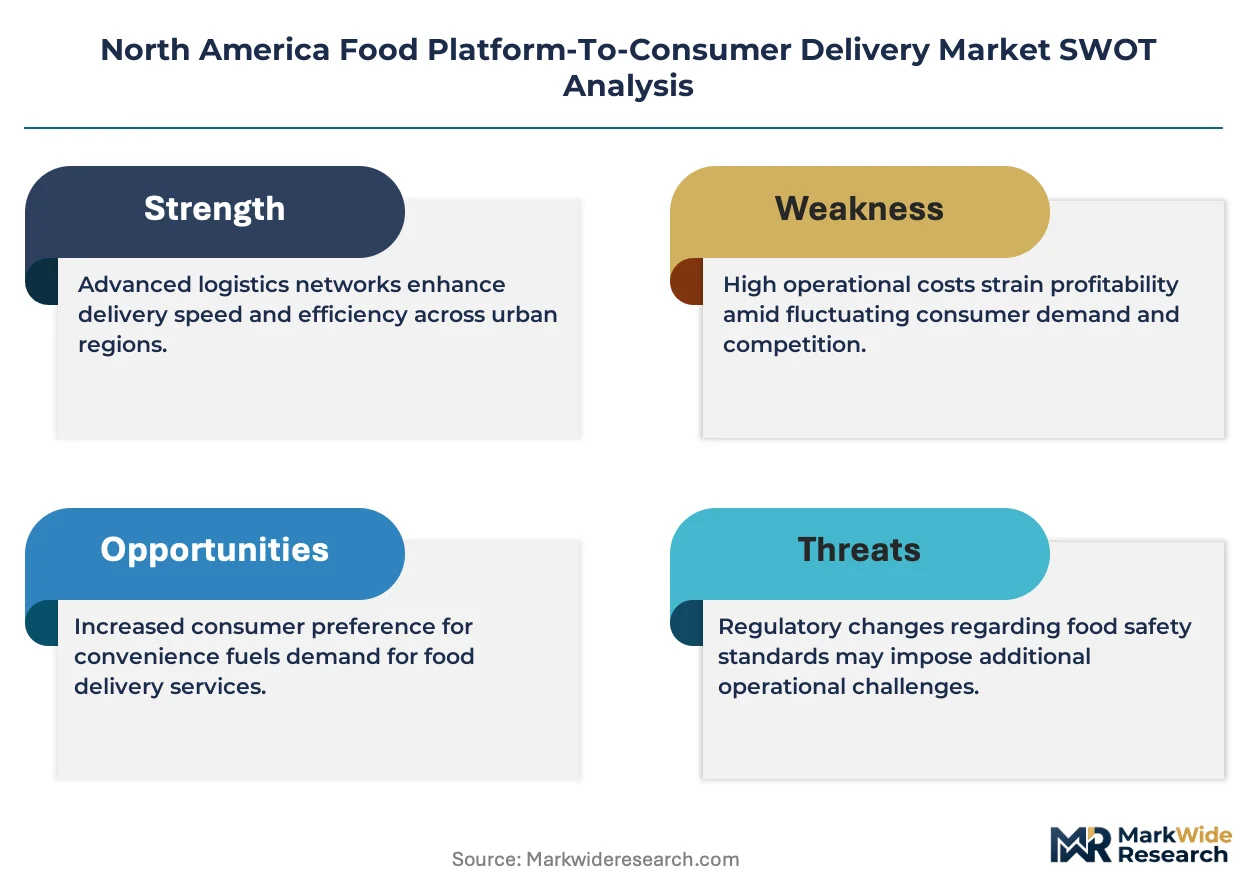
Algorithmic dispatch systems and labor reclassification proceedings are compressing delivery margins while reshaping contractor economics across the North American footprint.
Growth Catalysts
- Quick-service restaurant expansion:Chain operators are consolidating platform partnerships to access suburban households without capital-intensive dining infrastructure.
- Subscription model adoption:Recurring revenue structures reduce customer acquisition expenditure compared to on-demand ordering patterns.
- USDA food safety protocols:Standardized handling requirements enable cross-platform inventory pooling and shared cold-chain infrastructure.
Market Restraints
- Courier reclassification risk:US Department of Labor contractor rules and Ontario labor codes threaten variable-cost labor models.
- Metropolitan corridor concentration:Demand clustering in New York-Los Angeles-Toronto corridors leaves exurban zones with subscale unit economics.
- Perishable handling complexity:Grocery inventory spoilage rates exceed restaurant packaging durability, compressing margin on fastest-expanding service type.
Strategic Opportunities
- Campus and corporate contract penetration:Institutional dining accounts offer predictable volume with lower marketing expenditure.
- Cross-border regulatory arbitrage:Divergence between US federal contractor guidance and Canadian provincial labor codes creates structural positioning advantages.
- Exurban logistics density:Suburban zone coverage gaps present first-mover infrastructure deployment potential.
Industry Challenges
- Algorithmic dispatch talent scarcity:Machine learning engineers with route-optimization expertise command premium compensation in competing logistics sectors.
- Cold-chain capex intensity: Perishable grocery expansion requires refrigerated vehicle fleets and insulated packaging systems.
- Multi-jurisdiction compliance fragmentation: Health Canada, Canadian Food Inspection Agency, and US state-level labor boards impose overlapping audit requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Platform-To-Consumer Delivery Market |
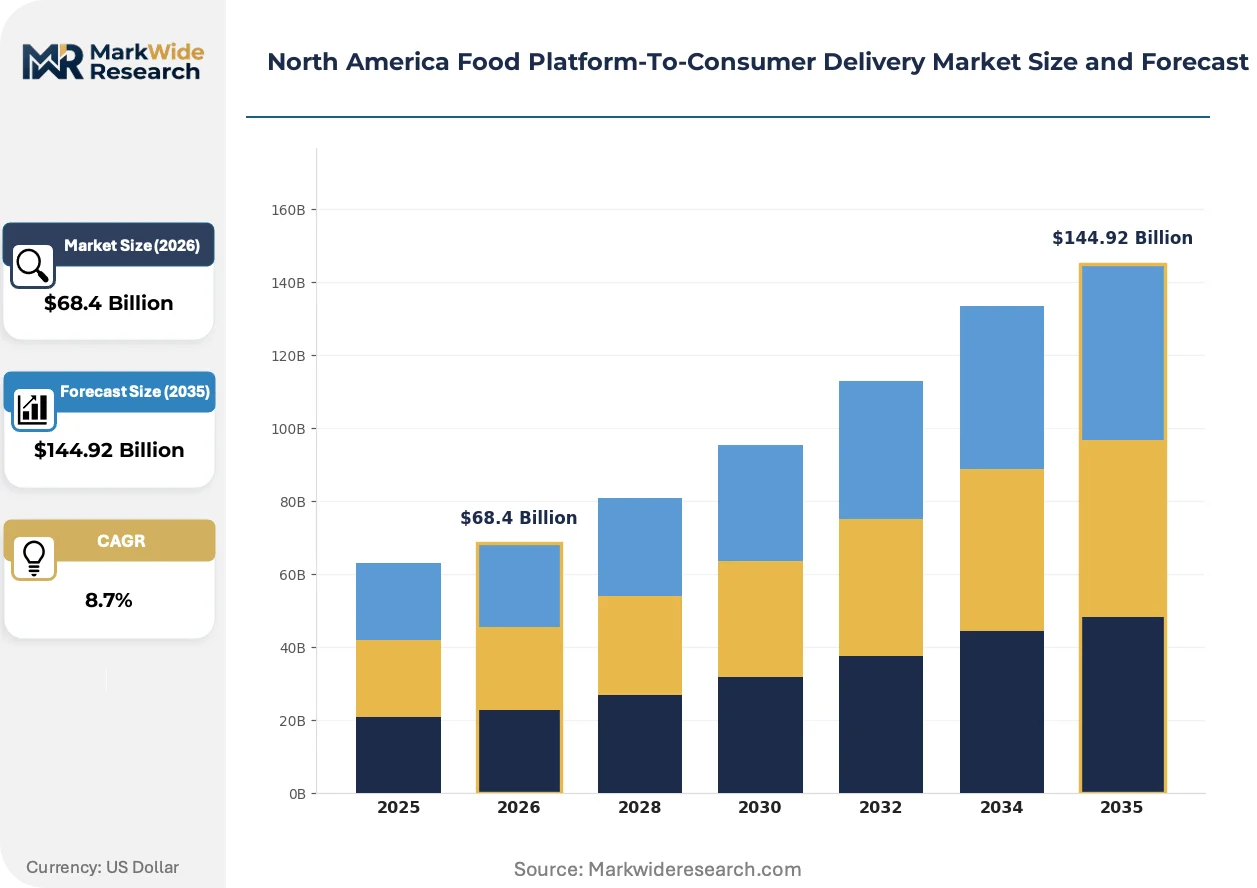
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Grocery Delivery, Meal Kits, Restaurant Delivery, Specialty Delivery Customer Type: Individuals, Families, Businesses, Institutions Delivery Model: On-Demand, Scheduled, Subscription-Based, Same-Day Delivery Technology: Mobile Applications, Web Platforms, GPS Tracking, Automated Dispatch |
| Companies Covered | DoorDash, Inc., Uber Technologies Inc., Grubhub Inc., Seamless North America LLC, goBrands, Inc., Caviar, Inc., Postmates, ChowNow, Munchery Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Platform-To-Consumer Delivery Market Evolving Landscape
Delivery platforms are converging on predictive logistics and automated dispatch to compress delivery windows while labor cost pressures mount.
Predictive demand algorithms aggregate historical order patterns, weather data, and event calendars to pre-position courier supply. Quick-service chains and grocery aggregators deploy these systems across metropolitan zones. Static routing based on historical averages is rendering obsolete as real-time demand sensing enables sub-30-minute fulfillment commitments.
The US Department of Labor's evolving contractor classification framework redefines independent worker status tests. Platform operators face reclassification exposure that would trigger wage and benefit obligations. California and Ontario jurisdictions are responding with ballot initiatives and legislative carve-outs to preserve gig labor structures.
Household purchasing is fragmenting across multiple platform interfaces rather than consolidating on single-provider relationships. Subscription fatigue and promotional arbitrage drive churn between DoorDash, Uber Eats, and Instacart interfaces. Urban corridors exhibit the highest multi-homing rates as consumers optimize delivery fees and restaurant availability.
North America Food Platform-To-Consumer Delivery Market Segmentation
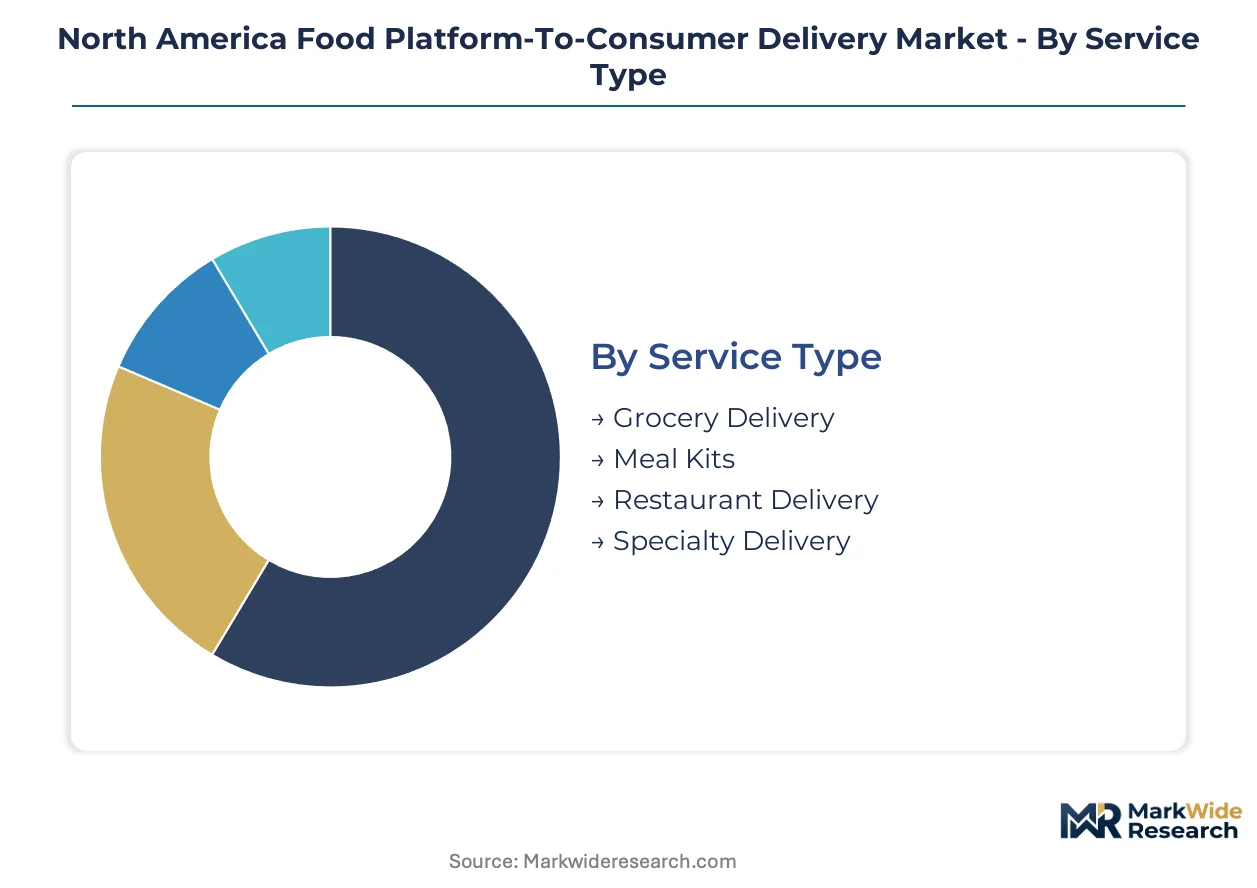
Platform-to-consumer delivery operators segment their addressable market to align logistics infrastructure with divergent service economics. Grocery handling demands refrigerated fleets and predictive spoilage management, while restaurant dispatch prioritizes speed over temperature control. Customer type and delivery model selections determine whether platforms pursue variable-cost gig labor or invest in dedicated fulfillment capacity.
Service Type:
After-sales service intensity varies sharply across service types, with perishable grocery requiring temperature-monitoring infrastructure and restaurant delivery focusing on complaint resolution speed.
- Restaurant Delivery:Hot-food logistics dominate transaction volume through algorithmic dispatch matching couriers to kitchen-ready times. Demand clusters in metropolitan corridors linking New York, Los Angeles, and Toronto where kitchen density supports sub-30-minute fulfillment windows.
- Grocery Delivery:Cold-chain compliance distinguishes this segment, requiring insulated packaging and refrigerated vehicle fleets to manage spoilage risk. USDA food safety protocols enable cross-platform inventory pooling while compressing margins through handling complexity.
- Meal Kits:Pre-portioned ingredient bundles with recipe instructions target suburban households seeking convenience without restaurant markup.
- Specialty Delivery:Alcohol, pharmacy, and gourmet products face jurisdiction-specific licensing requirements that fragment operational scale.
By volume, Restaurant Delivery leads. By growth pace, Grocery Delivery is expanding most quickly.
Customer Type:
Cost tier stratification separates individual consumers seeking promotional arbitrage from institutional accounts demanding contracted service levels.
- Individuals:Single-user accounts drive promotional churn across competing platforms, with subscription fatigue fragmenting loyalty. Urban corridors exhibit highest multi-homing rates as consumers optimize delivery fees.
- Families:Multi-person households generate larger average order values and stronger subscription attachment through recurring meal planning needs.
- Businesses:Corporate dining accounts concentrate in metropolitan office clusters, offering predictable volume with lower marketing expenditure than consumer acquisition.
- Institutions:University and healthcare campus contracts require dedicated dispatch windows and compliance with Health Canada or state-level food safety audit protocols.
Individual accounts dominate transaction count. Institutional contracts deliver the steadiest margin profile.
Delivery Model:
Application intensity distinguishes subscription subscribers receiving priority dispatch from on-demand users competing for courier availability during peak windows.
- Subscription-Based:Recurring revenue structures reduce customer acquisition expenditure compared to on-demand ordering patterns. DoorDash and Uber Eats deploy membership tiers to lock in habitual users.
- On-Demand:Immediate fulfillment commands premium fees during lunch and dinner peaks, straining algorithmic dispatch capacity. Variable pricing surges balance supply against demand spikes.
- Scheduled:Advance-booked slots enable route consolidation and improved courier utilization in suburban zones with lower kitchen density.
- Same-Day Delivery:Grocery-focused promise requires predictive inventory positioning and micro-fulfillment center networks to meet narrow windows.
On-Demand captures the highest fee revenue. Subscription-Based models are gaining share fastest through reduced churn economics.
Technology:
Margin tiering separates platforms investing in proprietary automated dispatch from those licensing third-party routing software.
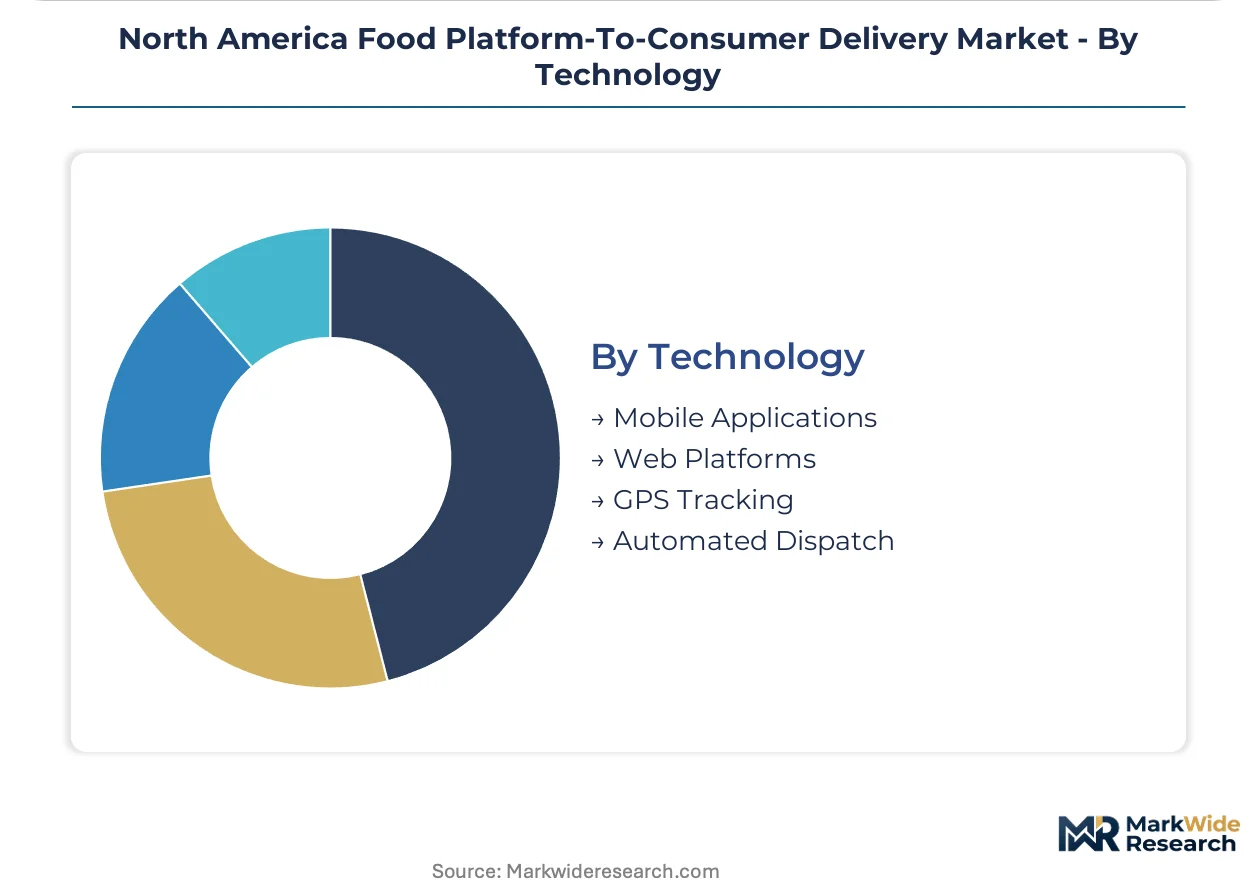
- Mobile Applications:Consumer-facing interfaces concentrate user engagement and payment processing, with push notification systems driving reorder frequency.
- Automated Dispatch:Machine learning route optimization coordinates courier handoff timing within narrow delivery windows. Talent scarcity for algorithmic engineers commands premium compensation.
- GPS Tracking:Real-time location sharing enables precise arrival estimates and dispute resolution through verified delivery confirmation.
- Web Platforms:Browser-based ordering captures corporate procurement workflows and household planning sessions outside mobile-first contexts.
Mobile Applications dominate user sessions. Automated Dispatch represents the steepest expansion trajectory as labor cost pressures mount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the New York-Los Angeles-Toronto corridor while Mexican metro zones absorb margin compression from lower-density logistics networks.
United States
Suburban household penetration and quick-service restaurant chain consolidation drive volume expansion across the Sun Belt and Midwest. The US Department of Labor's evolving contractor classification rules reshape gig labor economics in California and New York. The New York-Los Angeles corridor anchors demand density with sub-30-minute fulfillment windows.
Canada
Urban corridor concentration in Toronto, Vancouver, and Montreal supports platform infrastructure deployment with higher per-order economics. Health Canada and the Canadian Food Inspection Agency govern cross-border platform operations and food safety compliance. The Toronto metro zone exhibits the highest subscription adoption rates in the North American footprint.
Mexico
Mexico City Metro and Monterrey logistics clusters absorb platform expansion from US-based operators seeking geographic diversification. The country's national labor regulator and consumer protection agency impose emerging compliance requirements on delivery contractors. Northern border states experience cross-border demand spillover from US platform marketing expenditure.
North America Food Platform-To-Consumer Delivery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in logistics software and cold-chain packaging. The North American market consolidates around three dominant platform operators with overlapping metropolitan footprints. Strategic archetypes include logistics-density aggregators, cross-utilization network operators, and corporate-contract specialists. Competitive positioning hardens through subscription model proliferation and campus dining contract capture.
Within the logistics-density tier, DoorDash, Inc. and Uber Technologies Inc. anchor platform infrastructure deployment across suburban zones. Grubhub Inc. occupies a position within the corporate and institutional contract segment. These three entities exemplify divergent strategic bets on subscription retention versus cross-platform utilization economics.
| Leading Market Players |
|---|
| DoorDash, Inc. |
| Uber Technologies Inc. |
| Grubhub Inc. |
| Seamless North America LLC |
| goBrands, Inc. |
| Caviar, Inc. |
| Postmates |
| ChowNow |
| Munchery Inc. |
| Others |
Value Network & Pricing Analysis
Courier network concentration in California and Texas metropolitan zones feeds directly into margin pools held by platforms commanding suburban logistics density. The interplay between gig labor availability and algorithmic dispatch sophistication determines where pricing power accumulates across the North American footprint.
Pricing Analysis
Configured-to-order pricing for corporate dining contracts commands substantial premiums over standard on-demand consumer rates. Subscription-based models stratify across premium membership tiers, standard delivery fees, and economy promotional windows based on courier availability and kitchen density. Pricing pressure stems from courier reclassification proceedings in California and Ontario that threaten variable-cost labor structures. Individual consumers exhibit highest price sensitivity, while institutional campus contracts demonstrate fee tolerance tied to contracted service levels.
Supply Chain Analysis
Extended payment terms from quick-service restaurant chains to platform operators compress working capital cycles throughout the fulfillment network. Cold-chain infrastructure draws from specialized packaging suppliers in Mexico, refrigerated vehicle fleets assembled in Canada, and insulated container manufacturers concentrated in the US. Single-source vulnerability sits with dominant algorithmic dispatch software providers. Distribution runs through metropolitan micro-fulfillment centers positioned within sub-30-minute delivery radii of dense kitchen clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-to-consumer delivery operates as a substitution defense against in-house restaurant logistics and direct grocery fulfillment, with ghost kitchen proliferation representing the most immediate substitute threat incumbents must neutralize.
For Market Incumbents: Entrench logistics density through refrigerated fleet expansion in exurban zones where competitor coverage remains subscale. Deepen backward integration into predictive demand software to reduce third-party algorithmic dependency. Ghost kitchen operators threaten margin capture by bypassing platform intermediation entirely. For New Entrants and Emerging Players: Pursue campus dining contracts and corporate account penetration where incumbent switching costs remain lowest. Healthcare facility meal delivery offers underdeveloped white-space with stringent compliance barriers protecting established relationships. A go-to-market angle anchored in Health Canada audit protocols can accelerate trust formation with institutional procurement committees. For Investors and Strategic Acquirers: Capital is best deployed toward platforms with demonstrated subscription retention above industry benchmarks and proprietary dispatch infrastructure. Long-term viability over the next decade hinges on regulatory arbitrage capabilities across US federal contractor rules and Canadian provincial labor codes. Watch courier reclassification ballot initiatives in California and Ontario as inflection indicators for labor cost structure stability.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Model Expansion | Recurring revenue structures reduce customer acquisition expenditure compared to on-demand patterns. |
| Campus Contract Penetration | Institutional dining accounts offer predictable volume with lower marketing expenditure than consumer acquisition. |
| Cold-Chain Infrastructure Deployment | Refrigerated vehicle fleets enable grocery delivery expansion with USDA food safety protocol compliance. |
| Algorithmic Dispatch Investment | Machine learning route optimization compresses delivery windows as labor cost pressures intensify. |
| Cross-Border Regulatory Arbitrage | Divergence between US Department of Labor guidance and Ontario labor codes creates structural positioning advantages. |
Research Methodology
Cross-validation between platform operator financial disclosures and restaurant chain partnership announcements anchors the qualitative findings in verifiable operational data. Primary interviews with logistics operations directors, restaurant procurement managers, courier network coordinators, and institutional dining contract administrators combined with secondary validation from SEC filings, USDA food safety enforcement records, and provincial labor board proceedings. Bottom-up transaction volume modeling and top-down market sizing triangulation ensure consistency across estimation approaches.
Calibration against historical subscription adoption curves and courier network expansion patterns informs the projection framework across the analysis window. Segmentation dimensions include service type, customer archetype, delivery model, and technology deployment tier. CAGRs derive from logistic diffusion modeling applied to platform penetration rates and grocery delivery adoption velocity. Forecast inputs incorporate labor reclassification probability assessments and cold-chain capex intensity thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated ghost kitchen operators or rapid grocery retailer platform buildouts would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Europe Cloud Kitchen Market
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
Germany Foodservice Market
Food Service
Commercial Steam Table Market
Food Service
Online Catering Market
Food Service
Restaurant Glassware Market
Food Service
United States Foodservice Market
Food Service
Kuwait Food Service Market
Food Service
US Healthcare/Hospital Food Services Market
Food Service
Stirrers Market
Food Service
Snack Subscription Box Service Market
Food Service
Food Logistics Market
Food Service
Saudi Arabia Quick Service Restaurants Market
Food Service
Commercial Pizza Oven Market
Food Service
Global Self Heating Instant Hot Pot Market
Food Service
UK Smokeless Indoor Grills Market