
 Galley Equipment Market | 2026-2036
Galley Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Galley Equipment Market Intelligence
Modular galley configurations is realigning buyer choice across aviation and maritime sectors, as operators swap fixed installations for reconfigurable units that cut turnaround downtime. Diehl Aviation leverages its integrated cabin systems portfolio to dominate narrow-body retrofit programs. AIM Altitude anchors its position through specialized composite manufacturing that reduces galley weight. Safran Cabin competes via global MRO networks that sustain aftermarket service revenues.
Galley equipment encompasses food preparation, storage, and handling systems engineered for confined spaces in mobile environments, typically constructed from lightweight aluminum alloys or carbon-fiber composites and rated for vibration resistance, fire containment, and hygiene compliance under AS9100 and ISO 22000 standards. Its primary purpose is to enable safe, efficient meal service operations where space, weight, and energy consumption face strict operational limits. Permanent installations retain the largest installed base across long-haul fleets, though modular systems represent the fastest-growing installation category as carriers seek operational flexibility. Airlines drive the dominant share of end-user demand, while cruise lines command premium pricing for custom galley configurations.
FAA airworthiness directives and EASA certification standards govern electrical load management and fire suppression in aircraft galleys, forcing manufacturers to redesign heating elements and power distribution modules. EU MDR and FDA food-contact material regulations extend compliance burdens to maritime galley suppliers serving transatlantic routes. Stakeholders must monitor evolving CSRD sustainability disclosure requirements that will soon mandate embodied carbon reporting for cabin interior components.
Market Dynamics
Modular galley systems are compressing procurement cycles as airlines prioritize reconfigurable cabin architectures over fixed installations, forcing suppliers to redesign around standardized connection interfaces and rapid-swap power modules.
Growth Catalysts
- FAA Airworthiness Directives:Tightened electrical safety mandates for fire suppression systems in narrow-body galleys are accelerating replacement schedules across aging fleets.
- Carbon-fiber composite adoption:Weight reduction targets in aviation are pulling demand toward advanced material galley constructions that cut fuel burn per flight hour.
- China fleet expansion:COMAC production scaling and domestic carrier retrofit programs are concentrating new equipment procurement in East Asian manufacturing hubs.
Market Restraints
- Aerospace-grade aluminum supply:Input cost volatility for 7075-T6 and 2024-T3 alloys creates margin pressure on fixed-price contracts.
- AS9100 certification backlog:Limited accredited testing facilities extend product qualification timelines by 8-14 months for new entrants.
- Permanent installation lock-in:Legacy wide-body fleets with welded galley structures face high retrofit labor costs that delay upgrade decisions.
Strategic Opportunities
- India narrow-body penetration:IndiGo and Air India Express fleet growth creates untapped demand for line-fit galley configurations on A320neo and 737 MAX deliveries.
- EU CSRD carbon disclosure:Embodied carbon reporting mandates position early-compliant suppliers for preferred procurement status with European flag carriers.
- IoT-enabled predictive maintenance:Sensor-integrated galley modules that monitor component wear open recurring revenue streams through performance-based service agreements.
Industry Challenges
- Multisite certification coordination:Simultaneous FAA, EASA, and CAAC validation requires dedicated regulatory affairs teams that strain mid-tier engineering resources.
- Legacy 28VDC integration:Newer 270VDC galley architectures face compatibility friction with existing aircraft power distribution systems during retrofit installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Galley Equipment Market |
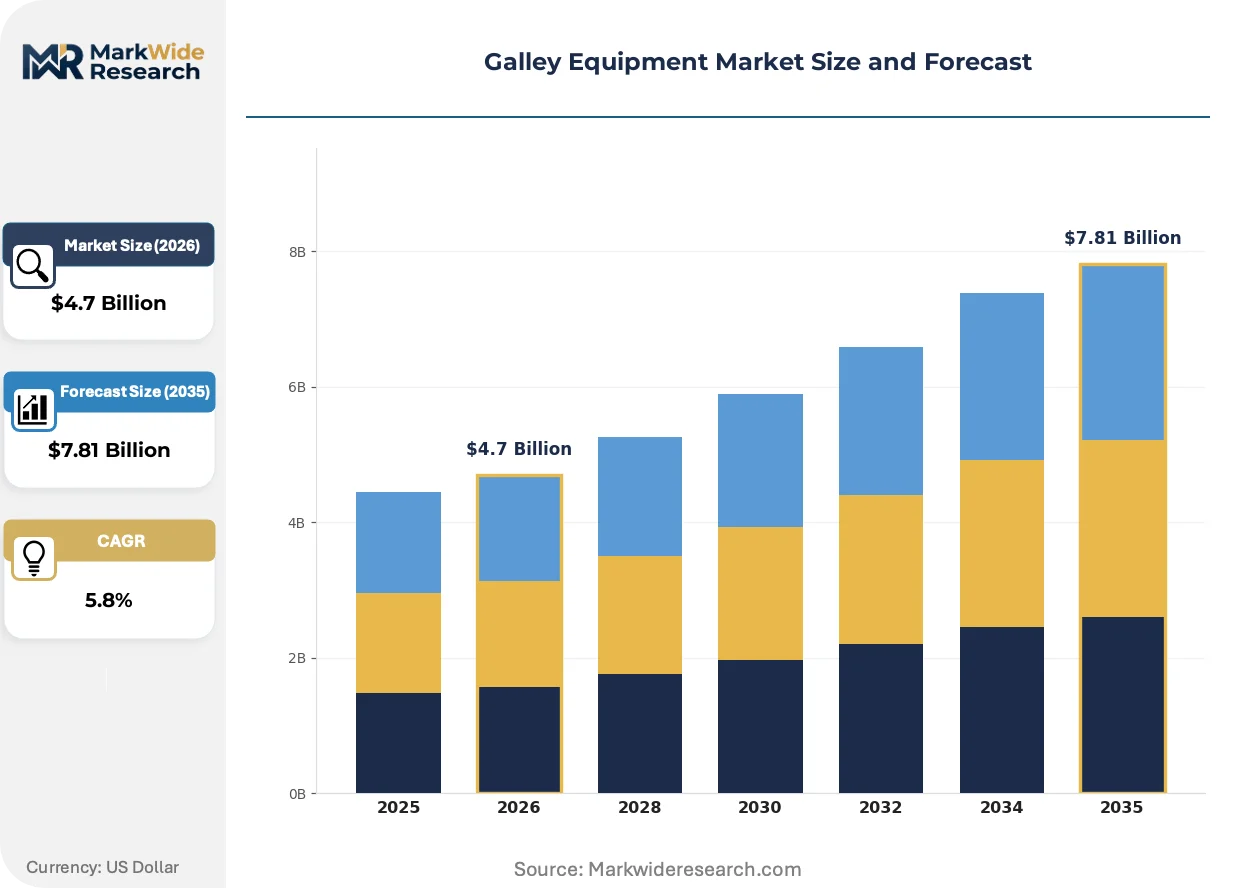
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $7.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ovens, Refrigerators, Dishwashers, Food Warmers End User: Airlines, Cruise Lines, Military, Commercial Ships Installation Type: Permanent Installations, Mobile Units, Retrofit Solutions, Modular Systems Service Type: Maintenance, Repair, Consulting, Training |
| Companies Covered | Diehl Aviation, AIM Altitude, Collins Aerospace, Zodiac Aerospace, Aerolux Limited, Safran Cabin, Bucher Leichtbau, Loipart AB, JAMCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Galley Equipment Market Strategic Shifts & Innovations
Active reshaping of the galley equipment landscape centers on three intersecting forces: material substitution driven by weight targets, regulatory disclosure mandates, and compressed buyer decision cycles that favor flexible procurement.
Electro-thermal ice protection systems for galley plumbing is overtaking traditional bleed-air heating in next-generation narrow-body programs. Boeing and Airbus are specifying these solid-state alternatives on new 737 MAX and A321XLR deliveries. The technology is overtaking legacy pneumatic architectures by eliminating ducting weight and reducing engine bleed load, compressing total galley system mass by 12-18 percent in forward galley configurations.
REACH substance restrictions on hexavalent chromium coatings are forcing manufacturers to transition toward trivalent chrome and plasma electrolytic oxidation surface treatments for aluminum galley components. EU-based suppliers face the steepest compliance curves as coating conversion requires requalification of entire fastener and track systems. Maritime galley segments serving transatlantic cruise routes are accelerating this transition ahead of aviation to preempt supply chain disruption.
Airline technical procurement teams are consolidating vendor relationships through multi-year framework agreements that bundle initial equipment with lifecycle parts provisioning. This behavior shift displaces transactional spot purchasing for galley retrofits and line-fit programs. North American legacy carriers and Gulf-based superconnectors are most visible in this consolidation, with Etihad and United both moving toward single-source galley system contracts spanning 10-15 year horizons.
Galley Equipment Market Segmentation
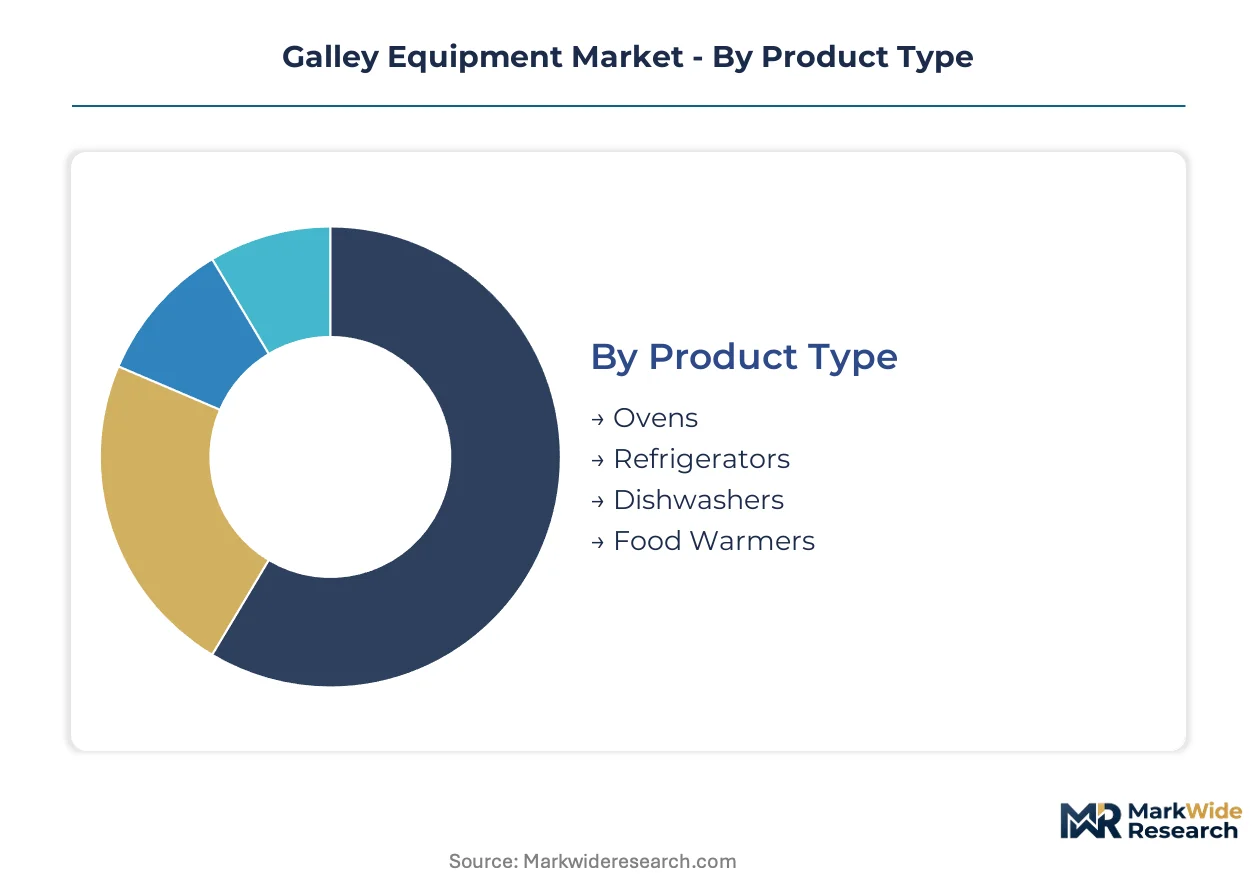
Galley equipment procurement decisions split across four intersecting dimensions: thermal processing hardware, vessel operator type, installation architecture, and lifecycle service requirements. Each dimension carries distinct margin profiles and certification burdens that reshape supplier competitive positioning.
Product Type:
Airline technical buyers prioritize thermal efficiency and weight reduction when selecting galley hardware, with power consumption per meal cycle serving as the primary screening metric.
- Ovens:Convection and steam-injection configurations dominate narrow-body programs, with forced-air designs rated to 150°C cutting pre-flight preparation windows. Demand concentrates in China as COMAC C919 line-fit specifications specify lightweight aluminum-alloy enclosures over legacy stainless-steel alternatives.
- Refrigerators:Vapor-compression and thermoelectric cooling modules engineered for 28VDC and 270VDC dual-voltage compatibility. Cold-chain reliability requirements from FDA food-contact regulations pull demand toward redundant compressor architectures on transatlantic cruise routes.
- Dishwashers:Compact fresh-water recycling units with 3-minute cycle times for high-frequency short-haul turnarounds.
- Food Warmers:Radiant and conduction heating elements with fire-suppression interlocks meeting FAA airworthiness directive standards.
Ovens lead on scale; refrigerators lead on momentum.
End User:
Operator type dictates specification severity, with aviation and maritime sectors diverging sharply on weight tolerance and hygiene compliance frameworks.
- Airlines:Narrow-body carriers retrofitting A320neo and 737 MAX fleets drive procurement volume, with galley reconfigurations tied to cabin densification programs. AS9100 certification requirements and FAA electrical safety mandates compress vendor qualification pools.
- Cruise Lines:Premium custom configurations for expedition and luxury vessels command pricing multiples, with EU MDR food-contact material regulations extending compliance to transatlantic itineraries. Shipyard construction cycles in Italy and Germany anchor demand timing.
- Military:Ruggedized galley systems rated for shock, vibration, and electromagnetic interference aboard naval vessels and transport aircraft.
- Commercial Ships:Container vessel and offshore platform galleys prioritizing space efficiency and crew capacity over thermal performance refinement.
Airlines dominate procurement volume; cruise lines capture margin premium.
Installation Type:
Carrier fleet strategy—growth versus renewal—determines whether procurement flows to line-fit OEM channels or aftermarket retrofit specialists.
- Permanent Installations:Welded aluminum structures with integrated power distribution retain the largest installed base across legacy wide-body fleets. High retrofit labor costs delay upgrade decisions, stretching replacement cycles.
- Modular Systems:Reconfigurable units with standardized connection interfaces and rapid-swap power modules. Airlines in Asia-Pacific expanding fleet modernization programs are accelerating adoption to enable cabin layout flexibility between business and economy density configurations.
- Mobile Units:Self-contained galley carts for temporary capacity expansion and VIP charter configurations.
- Retrofit Solutions:Engineering packages for in-service aircraft and vessels requiring structural modification to accommodate upgraded equipment.
Permanent installations retain installed base dominance; modular systems gain share fastest.
Service Type:
Aftermarket revenue stability depends on contract structure, with performance-based agreements displacing transactional parts procurement among large fleet operators.
- Maintenance:Scheduled inspection and component replacement programs governed by flight-hour and cycle-count intervals. North American legacy carriers consolidating vendor relationships through multi-year framework agreements that bundle initial equipment with lifecycle parts provisioning.
- Repair:Unscheduled corrective action for fire suppression system faults and heating element failures, with EASA certification standards tightening response time requirements.
- Consulting:Cabin layout optimization and galley workflow engineering for new-build programs and major retrofit campaigns.
- Training:Crew certification on updated food-handling protocols and emergency shutdown procedures.
Maintenance commands revenue scale; consulting shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Galley equipment manufacturing originated in post-war Germany and the United States, where aluminum fabrication expertise from military aviation transferred into commercial cabin interiors. Early production clusters formed around Hamburg, Seattle, and Toulouse as jetliner assembly scaled.
United States
FAA airworthiness directives on electrical fire suppression are accelerating narrow-body galley replacement at American, United, and Delta. The FAA mandates tightened certification timelines for heating element redesigns. Wichita, Kansas hosts specialized MRO facilities retrofitting 737 MAX fleets with modular galley architectures.
Germany
REACH substance restrictions on hexavalent chromium coatings are forcing coating conversion across aluminum galley component suppliers. EASA certification standards for electrical load management compress vendor qualification pools. Hamburg anchors European galley manufacturing, with shipyard-adjacent fabricators serving both aviation and maritime segments.
China
COMAC C919 production scaling and domestic carrier retrofit programs are concentrating procurement in East Asian manufacturing hubs. MIIT standards for aviation equipment certification align with FAA and EASA frameworks. Shanghai and Tianjin host emerging galley fabrication clusters supplying Air China and China Eastern narrow-body densification programs.
France
EU CSRD carbon disclosure mandates are positioning early-compliant suppliers for preferred procurement with Air France-KLM. EASA tightening of galley fire suppression standards drives heating element redesign cycles. Toulouse maintains its historical role as cabin systems engineering hub adjacent to Airbus final assembly.
Japan
JIS standards for aviation equipment quality management align with AS9100 certification requirements for galley suppliers. ANA and JAL fleet modernization programs are generating line-fit demand for A320neo and 737 MAX configurations. Nagoya-area precision metalworking clusters supply lightweight aluminum-alloy galley structural components.
Galley Equipment Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification depth and material specialization. The vendor base organizes into three tiers: integrated cabin systems houses, composite manufacturing specialists, and regional MRO service providers. Strategic archetypes include full-system integrators bundling galleys with adjacent cabin components, weight-focused composite fabricators, and aftermarket service networks sustaining long-term revenue. Consolidation pressure manifests through framework agreement consolidation and multi-year single-source contracts spanning 10-15 year horizons.
Within the integrated systems tier, Diehl Aviation and Safran Cabin exemplify full-cabin portfolio strategies. AIM Altitude represents the composite specialization archetype. Zodiac Aerospace and Collins Aerospace occupy positions linking galley equipment to broader avionics and cabin systems integration. Bucher Leichtbau, Loipart AB, and JAMCO Corporation represent geographically distributed fabrication capacity across European, Nordic, and Japanese manufacturing bases respectively.
| Leading Market Players |
|---|
| Diehl Aviation |
| AIM Altitude |
| Collins Aerospace |
| Zodiac Aerospace |
| Aerolux Limited |
| Safran Cabin |
| Bucher Leichtbau |
| Loipart AB |
| JAMCO Corporation |
| Others |
Cost & Logistics Intelligence
Carbon-fiber composite manufacturing migration is compressing unit economics while redrawing supplier geography, as automated fiber placement and out-of-autoclave curing slash labor content and enable production dispersion beyond traditional aluminum fabrication centers. FAA and EASA certification requirements for fire suppression integration simultaneously elevate entry barriers and concentrate pricing power among qualified suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AS9100-certified integrated system providers from component specialists and unqualified fabricators. Price differentiation rests on certification depth and material grade, with aerospace-specification aluminum alloys commanding substantial premiums over commercial-grade alternatives. Cost compression in standard-tier modular systems is intensifying because Chinese COMAC suppliers are scaling domestic production capacity. Narrow-body retrofit carriers exhibit highest price sensitivity; Gulf-based superconnectors demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Hamburg, Wichita, and Shanghai anchor hub-and-spoke patterns that feed line-fit OEM channels and MRO retrofit facilities. Manufacturing concentration draws from Germany, the United States, and China, with precision metalworking clusters in Nagoya supplying structural components. Raw material dependencies center on aerospace-grade aluminum alloys, carbon-fiber prepreg, and trivalent chromium surface treatments. Single-source vulnerability persists in AS9100-accredited testing capacity. Distribution runs through airframe OEM integrated procurement and airline framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where tightened FAA airworthiness directives on electrical fire suppression are accelerating replacement demand across aging narrow-body fleets.
For Market Incumbents: Extend aftermarket service contract penetration through performance-based agreements that lock in 10-15 year parts provisioning. Deepen backward integration into carbon-fiber prepreg manufacturing to defend margin position against Chinese COMAC supply chain buildout. Certification investment in dual FAA-EASA validation preserves access to European flag carrier procurement. For New Entrants and Emerging Players: Sensor-integrated predictive maintenance modules offer technology-first wedge into airline technical procurement teams seeking operational data visibility. White-space targets include India narrow-body line-fit programs and EU CSRD-compliant carbon disclosure services. Go-to-market through MRO channel partnerships bypasses OEM qualification backlogs. For Investors and Strategic Acquirers: Valuations sit cheapest among regional composite fabricators lacking AS9100 certification but possessing technical capability for coating conversion and REACH compliance. Long-term viability frames around 5-10 year regulatory-driven replacement cycles and fleet densification trends. Watch COMAC C919 production rate acceleration as inflection signal for East Asian supply chain rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Conversion | Trivalent chromium transition preempts EU regulatory disruption for Hamburg-based suppliers. |
| IoT-Enabled Predictive Maintenance | Sensor-integrated modules open recurring revenue streams with United and Etihad framework agreements. |
| Dual-Voltage Power Architecture | 28VDC and 270VDC compatibility addresses Boeing 737 MAX and Airbus A321XLR specifications. |
| Carbon-Fiber Composite Scale-Up | Out-of-autoclave curing reduces unit costs for weight-critical narrow-body galley configurations. |
| Multi-Year Framework Consolidation | Single-source contracts spanning 10-15 years displace transactional spot purchasing among North American legacy carriers. |
Research Approach
Direct dialogue with airline technical procurement directors, galley system engineering leads, MRO facility managers, and EASA regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from FAA airworthiness directive filings, EASA certification databases, COMAC production disclosures, and customs trade data for aerospace-grade aluminum imports. Bottom-up and top-down triangulation cross-checked supplier capacity announcements against fleet delivery schedules and retrofit program timelines.
Bottom-up modeling aggregated individual program volumes across oven, refrigerator, and modular system categories, while top-down analysis calibrated aggregate market expansion against aviation fleet growth projections and maritime new-build orderbooks. Segmentation dimensions spanned product type, end-user operator class, installation architecture, and service contract structure. CAGRs were derived from fitted growth curves anchored to disclosed fleet modernization schedules and regulatory replacement mandates. Industry-specific inputs included heating element redesign cycles tied to FAA directive timelines and carbon-fiber adoption rates in next-generation narrow-body programs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to COMAC production scaling, REACH substance restriction enforcement, and aluminum alloy price volatility. Forecasts reflect documented assumptions regarding certification timeline clearance and fleet densification program continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Pizza Foodservice Market
Food Service
New Zealand Foodservice Market
Food Service
Online Grocery Market
Food Service
Electric Tiffin Market
Food Service
UK Smokeless Indoor Grills Market
Food Service
Canada Food Service Market
Food Service
Australia Foodservice Market
Food Service
Restaurant Takeout Market
Food Service
Restaurants and Mobile Food Services Market
Food Service
Instant Noodle Vending Machine Market
Food Service
Asia-Pacific Halal Food and Beverage Market
Food Service
India Quick Service Restaurant Market
Food Service
Europe Food Service Market
Food Service
Qatar Food Service Market
Food Service
Restaurant Glassware Market
Food Service
Switzerland Food Service Market