
 Haute Cuisine Market | 2026-2036
Haute Cuisine Market Size, Share, and Industry Trends Forecast 2026-2036
Haute Cuisine Market Analysis
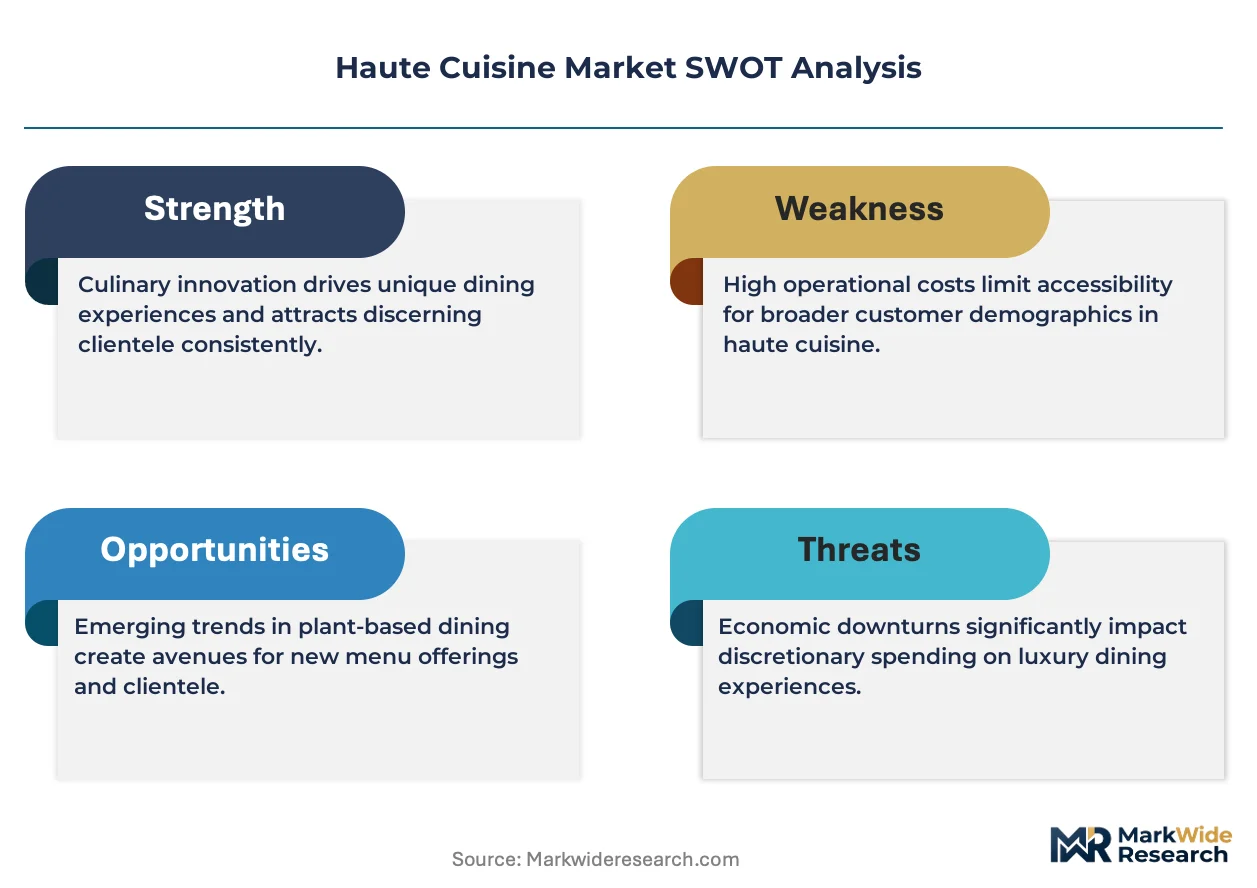
Asset-light kitchen licensing and ghost-kitchen partnerships is tilting competitive entry toward chef-entrepreneurs without legacy real estate burdens. Alain Ducasse Group leverages its multi-venue operating platform to sustain presence across three continents. Narisawa anchors its competitive position through deep integration of Japanese terroir methodology and foraged ingredient networks. Alinea Group differentiates through proprietary service-theater formats that command premium pricing power in Chicago and forthcoming satellite locations.
Haute cuisine denotes the apex of formal culinary arts, characterized by meticulous technique, premium ingredient provenance, multi-course progression, and service choreography governed by established codes of gastronomic ritual. French haute cuisine traditionally demands classical mother-sauce mastery, precise temperature control, and plate architecture executed under brigade hierarchy. Among cuisine type segments, French and Japanese formats occupy the deepest heritage positions and command sustained patron loyalty, while molecular gastronomy represents the fastest-expanding innovation frontier where margin pools concentrate in exclusive tasting-menu formats. Service style segmentation reveals fine dining as the mature revenue core, though pop-up restaurants are capturing disproportionate growth by lowering capital barriers for experimental concepts.
France's Appellation d'Origine Contrôlée and Japan's Ministry of Agriculture, Forestry and Fisheries certification systems shape ingredient sourcing requirements and geographic exclusivity claims that directly influence menu pricing architecture. The European Union's Geographical Indications framework and FDA seafood HACCP protocols in the United States further constrain supply chain flexibility while elevating compliance costs for imported specialty ingredients. Stakeholders must monitor evolving carbon-footprint disclosure obligations and biodiversity-sourcing restrictions that are beginning to penetrate procurement standards at the three-star tier.
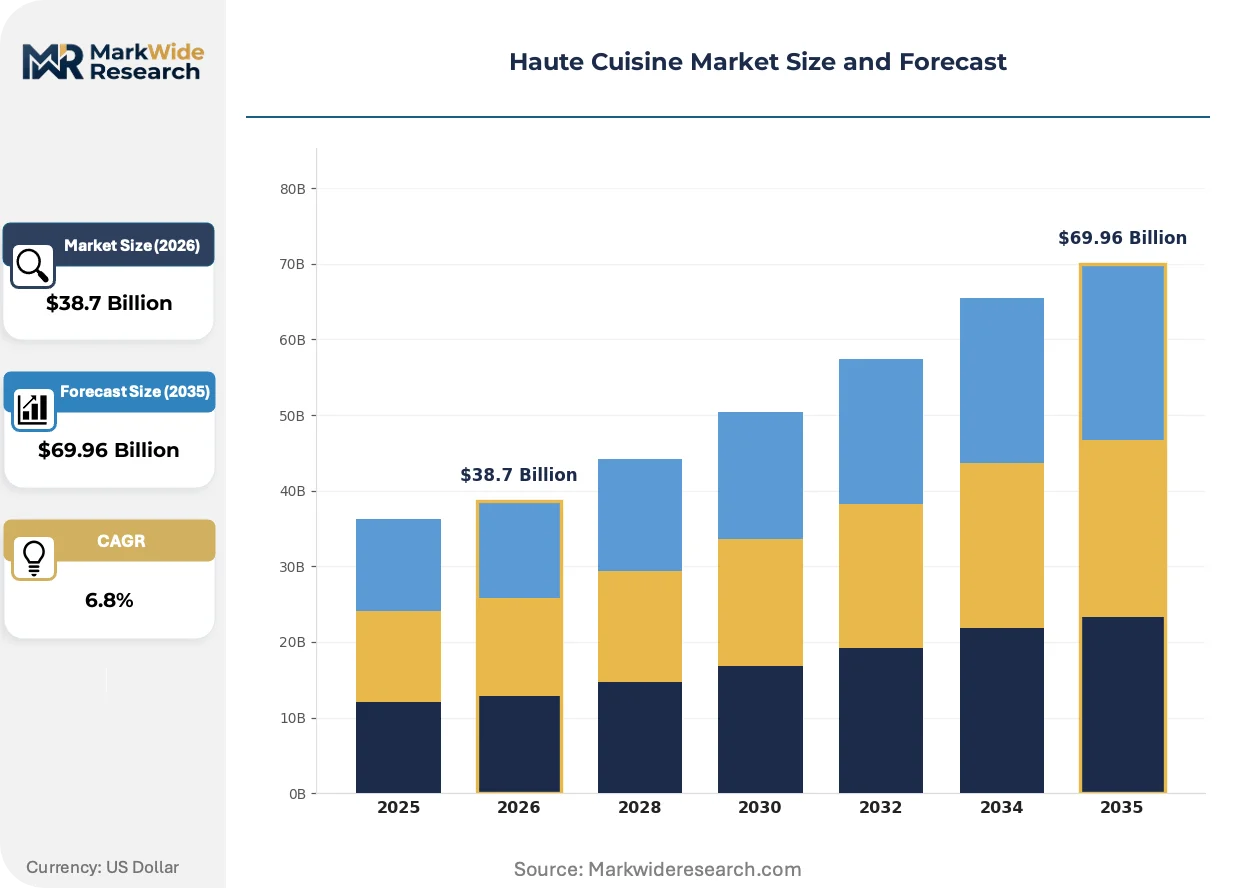
Market Dynamics
Asset-light licensing models are compressing capital barriers for chef-entrepreneurs while fragmenting competitive control across venue networks. Ghost-kitchen partnerships now enable rapid format testing without legacy real estate burdens.
Growth Catalysts
- Japan's MAFF certification systems:Geographic exclusivity claims for foraged ingredients and terroir methodology sustain premium pricing power in Tokyo's Ginza and Roppongi districts.
- Luxury hotel dining expansion:Southeast Asian hospitality groups are embedding haute cuisine commitments into flagship properties, creating captive demand for three-star formats.
- French AOC framework tightening:Ingredient provenance standards for elite establishments reinforce heritage positioning and justify extended tasting-menu architectures.
Market Restraints
- Imported specialty ingredient compliance:FDA seafood HACCP protocols and EU Geographical Indications elevate procurement costs and constrain supply chain flexibility for cross-border sourcing.
- Carbon-footprint disclosure obligations:Emerging biodiversity-sourcing restrictions at the three-star tier are beginning to penetrate procurement standards and elevate operational complexity.
- Brigade hierarchy labor intensity:Classical mother-sauce mastery and precise temperature control demand sustained apprenticeship pipelines that face demographic compression.
Strategic Opportunities
- Pop-up restaurant formats:Experimental concepts are capturing disproportionate growth by lowering capital barriers and accelerating menu iteration cycles beyond fixed-venue constraints.
- Molecular gastronomy innovation frontier:Exclusive tasting-menu formats concentrate margin pools where proprietary service-theater configurations command premium positioning.
- Chef-entrepreneur platform licensing:Multi-venue operating models enable sustained continental presence without per-location ownership burdens.
Industry Challenges
- Apprenticeship pipeline compression:Classical technique transmission through brigade hierarchy faces generational attrition as alternative culinary career paths proliferate.
- Certification timeline friction:Three-star tier compliance with evolving carbon-footprint and biodiversity-sourcing standards requires reconfiguration of established procurement relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Haute Cuisine Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cuisine Type: French, Italian, Japanese, Molecular Gastronomy Service Style: Fine Dining, Casual Dining, Pop-up Restaurants, Food Trucks Ingredient Source: Local, Organic, Imported, Seasonal Meal Type: Breakfast, Lunch, Dinner, Dessert |
| Companies Covered | Eleven Madison Park, Osteria Francescana, Alain Ducasse Group, El Celler de Can Roca, The Fat Duck, Joël Robuchon, Narisawa, Alinea Group, Hakkasan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Haute Cuisine Market Emerging Trajectories
Formal gastronomic ritual is undergoing format fragmentation as digital-native patrons seek compressed experiential density. Service choreography now competes with theatrical immediacy.
Precision fermentation for specialty dairy and protein analogs is migrating from experimental kitchens to Michelin-starred menus. Tokyo and Copenhagen establishments are adopting these inputs at accelerating pace. The technology is migrating from novelty positioning to core ingredient architecture, compressing traditional terroir claims and forcing provenance narrative reinvention.
EU CSRD disclosure mandates and emerging biodiversity-sourcing restrictions are reshaping procurement documentation requirements. Three-star establishments must now track and report ingredient carbon intensity across extended supply chains. French and Japanese venues face the steepest compliance curves as their certification systems integrate these frameworks.
Patron preference is rotating toward experiential density over extended progression formats. Tasting-menu compression and hybrid service-theater configurations are displacing traditional multi-course rituals in Chicago and forthcoming satellite locations. This behavioral shift concentrates in metropolitan markets where time scarcity intersects with premium experience seeking.
Haute Cuisine Market Segmentation
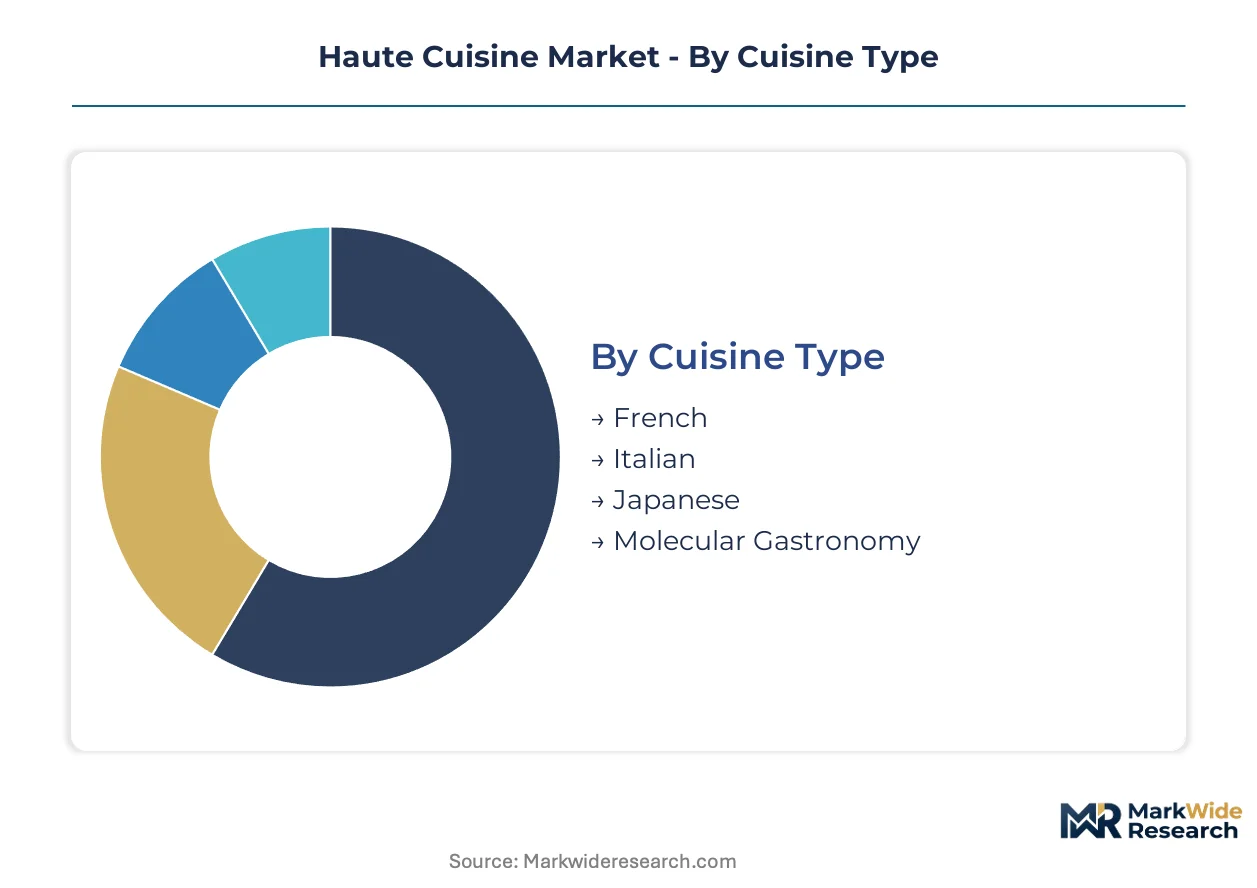
Haute cuisine segmentation reveals divergent capital intensity and format turnover rhythms. Cuisine type and service style categories command the longest investment cycles, while ingredient sourcing and meal type segments rotate with seasonal and regulatory tempo.
Cuisine Type:
French and Japanese formats anchor multi-decade heritage investments with the slowest concept refresh cycles. Molecular gastronomy compresses R&D-to-menu timelines through rapid technique iteration.
- French:Classical mother-sauce mastery and brigade hierarchy demand sustained apprenticeship pipelines. Tokyo's Ginza district and Paris maintain the deepest patron loyalty for this format, though demographic compression in kitchen labor pools constrains expansion velocity.
- Japanese:Deep integration of terroir methodology and foraged ingredient networks creates geographic exclusivity claims under MAFF certification. Tokyo's Roppongi district exceeds Paris in Michelin-starred density, concentrating demand for kaiseki and omakase architectures.
- Italian:Regional heritage positioning across Piedmont, Tuscany, and coastal traditions sustains premium pricing in heritage venues.
- Molecular Gastronomy:Exclusive tasting-menu formats concentrate margin pools where proprietary service-theater configurations command premium positioning.
French dominates installed base. Molecular gastronomy is where expansion concentrates.
Service Style:
Capital deployment varies dramatically across fixed-venue and itinerant formats. Fine dining demands the heaviest real estate commitments, while pop-up and mobile configurations enable rapid market testing.
- Fine Dining:Mature revenue core with established brigade hierarchies and extended tasting-menu architectures. Southeast Asian luxury hotel dining programs embed these formats into flagship properties, creating captive demand for three-star service choreography.
- Pop-up Restaurants:Experimental concepts capture disproportionate growth by lowering capital barriers and accelerating menu iteration cycles beyond fixed-venue constraints. Chicago and forthcoming satellite locations favor hybrid service-theater configurations.
- Casual Dining:Compressed experiential formats serve time-scarce metropolitan patrons seeking density over ritual extension.
- Food Trucks:Mobile platforms test ingredient provenance narratives without legacy real estate burdens.
Fine dining dominates installed base. Pop-up restaurants are climbing the fastest.
Ingredient Source:
Certification complexity and supply chain documentation requirements differentiate sourcing tiers. Local and seasonal categories align with emerging carbon-footprint disclosure mandates, while imported specialty ingredients face escalating compliance friction.
- Local:Terroir methodology and foraged ingredient networks sustain premium pricing power through geographic exclusivity claims. French AOC framework tightening reinforces heritage positioning for elite establishments sourcing within designated zones.
- Imported:FDA seafood HACCP protocols and EU Geographical Indications elevate procurement costs and constrain supply chain flexibility for cross-border specialty inputs. Three-star tier establishments face the steepest documentation curves.
- Organic:Certification systems shape menu pricing architecture through verified production method claims.
- Seasonal:Rotation rhythms compress procurement windows and demand predictive supplier relationships.
Local dominates installed base. Seasonal is where expansion concentrates.
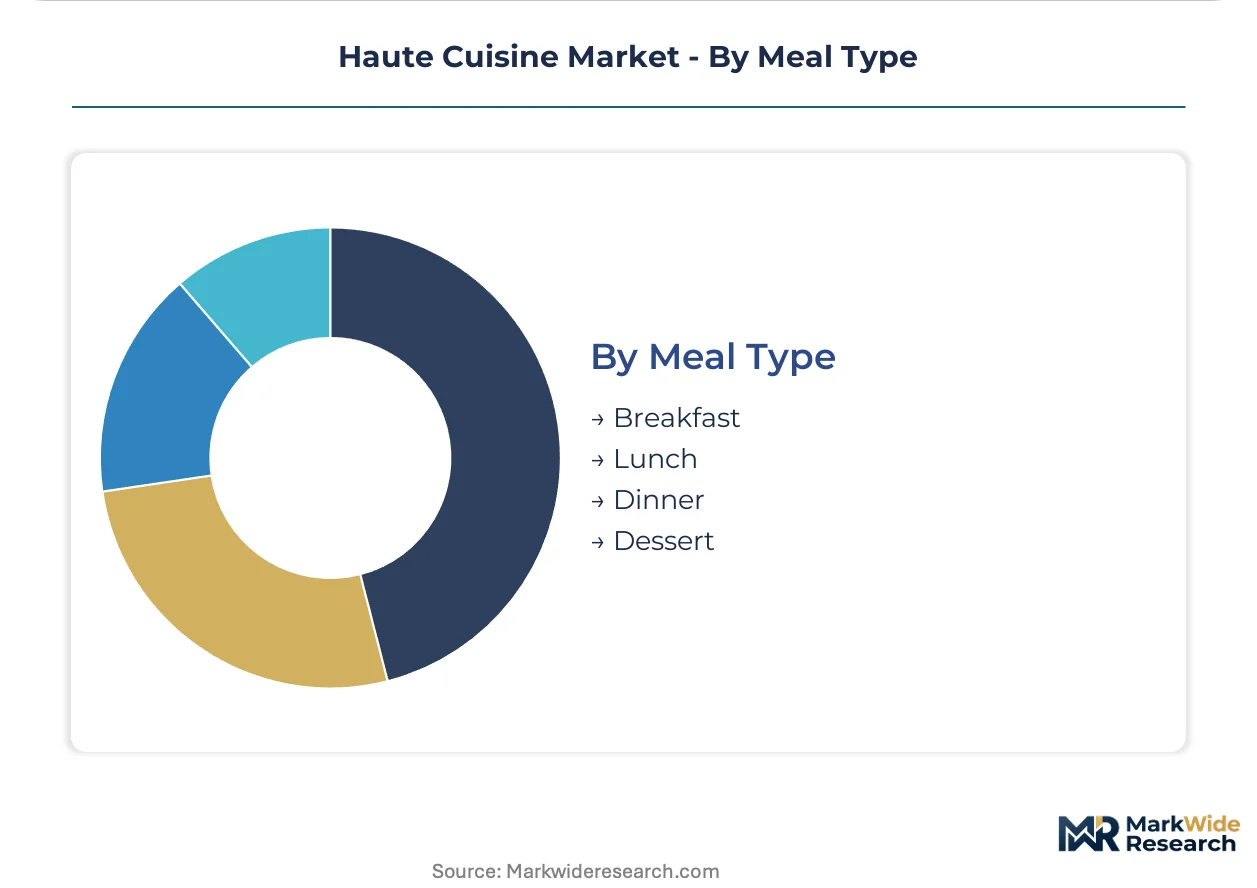
Meal Type:
Revenue concentration and experiential investment vary sharply across dayparts. Dinner commands the deepest service choreography and longest progression formats, while breakfast and dessert enable compressed innovation cycles.
- Dinner:Multi-course progression and formal gastronomic ritual achieve fullest expression in this daypart. Extended tasting-menu architectures justify premium pricing through temporal and technical investment density.
- Dessert:Precision fermentation for specialty dairy and protein analogs migrates from experimental kitchens to Michelin-starred menus most rapidly in this segment. Tokyo and Copenhagen establishments adopt these inputs at accelerating pace.
- Lunch:Compressed formats serve time-scarce metropolitan patrons without full brigade deployment.
- Breakfast:Lowest capital barrier for format experimentation and ingredient narrative testing.
Dinner dominates installed base. Dessert is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's Appellation d'Origine Contrôlée tightening and Japan's MAFF certification systems are reshaping competitive entry requirements across major haute cuisine clusters. Regulatory divergence between heritage frameworks and emerging disclosure mandates is fragmenting procurement compliance curves.
France
Paris maintains the deepest heritage investment in classical mother-sauce mastery and brigade hierarchy. The AOC framework continues tightening ingredient provenance standards, elevating compliance costs for elite establishments. Île-de-France concentrates three-star density, though demographic compression in kitchen labor pools constrains expansion velocity beyond flagship venues.
Japan
Tokyo's Ginza and Roppongi districts now exceed Paris in Michelin-starred density, concentrating demand for kaiseki and omakase architectures. MAFF certification systems sustain geographic exclusivity claims for foraged ingredients and terroir methodology. The Kanto region anchors premium pricing power through deep integration of seasonal ingredient networks.
United States
Chicago and New York metropolitan areas favor hybrid service-theater configurations that compress traditional multi-course rituals. FDA seafood HACCP protocols elevate procurement documentation requirements for imported specialty inputs. The analysis identifies accelerating format experimentation in satellite locations seeking to replicate proprietary experiential density models.
Spain
Catalonia and the Basque Country sustain regional heritage positioning through precision technique transmission and extended apprenticeship pipelines. EU Geographical Indications constrain supply chain flexibility for cross-border sourcing while reinforcing local terroir claims. Barcelona and San Sebastián clusters concentrate experimental molecular gastronomy innovation.
United Kingdom
London anchors disproportionate growth in pop-up restaurant formats that lower capital barriers for experimental concepts. EU CSRD disclosure mandates are penetrating procurement documentation requirements ahead of formal adoption timelines. The capital's hospitality groups are embedding haute cuisine commitments into flagship properties, creating captive demand for three-star service choreography.
Haute Cuisine Market Vendor Landscape
On the supply side, the industry is bifurcating between heritage venue networks with multi-decade real estate commitments and asset-light platform operators. Consolidation pressure concentrates around chef-entrepreneurs leveraging ghost-kitchen partnerships and licensing models to bypass legacy capital burdens. Three strategic archetypes dominate: brigade-hierarchy heritage houses, terroir-integrated Japanese formations, and service-theater innovators. Competitive moves center on multi-venue operating platform expansion and proprietary format licensing across continental footprints.
Within the heritage venue tier, Alain Ducasse Group and Joël Robuchon exemplify sustained continental presence through multi-venue operating architectures. Narisawa occupies a distinctive position anchoring competitive advantage through Japanese terroir methodology and foraged ingredient network integration. These formations represent divergent pathways for sustaining premium positioning—one through scale-enabled geographic replication, the other through deep geographic exclusivity claims that resist platformization.
| Leading Market Players |
|---|
| Eleven Madison Park |
| Osteria Francescana |
| Alain Ducasse Group |
| El Celler de Can Roca |
| The Fat Duck |
| Joël Robuchon |
| Narisawa |
| Alinea Group |
| Hakkasan Group |
| Others |
Supply Flow & Price Mechanics
Tokyo's Ginza and Roppongi districts concentrate Michelin-starred density that exceeds Paris, compressing supplier leverage and elevating premium pricing power for establishments with MAFF-certified foraged ingredient networks. This geographic concentration of culinary prestige creates asymmetric cost structures where terroir-integrated venues command disproportionate margin capture.
Pricing Analysis
Certification level under France's AOC and Japan's MAFF frameworks creates the primary spread between heritage-tier establishments and experimental formats. Three-tier pricing structure across heritage, terroir-integrated, and molecular gastronomy levels stratifies patron access. Cost compression in pop-up and ghost-kitchen formats is intensifying because asset-light licensing reduces fixed-cost amortization. Corporate hospitality buyers in Southeast Asian luxury hotels exhibit lowest price sensitivity, while metropolitan casual diners show greatest elasticity.
Supply Chain Analysis
Extended payment terms from Southeast Asian hospitality groups and supply-chain finance facilities anchored in Japanese ingredient networks are restructuring working capital flows. Geographic supply concentration centers on France for AOC-designated dairy and wine inputs, Japan for MAFF-certified seafood and foraged mountain vegetables, and Italy for regional heritage grains and cured products. Raw material dependencies rest on specialty dairy, wild-harvested botanicals, and precision-fermented protein analogs. Single-source vulnerability runs through Tokyo's foraged ingredient networks where climate volatility disrupts seasonal availability. Distribution feeds from direct procurement relationships into brigade-hierarchy kitchens without intermediary consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from precision-fermented ingredient architectures that compress traditional terroir claims and force provenance narrative reinvention.
For Market Incumbents: Pre-empt platform fragmentation by consolidating multi-venue operating licenses across continental footprints before chef-entrepreneurs capture ghost-kitchen scale. Deepen backward integration into MAFF-certified foraged ingredient networks to defend against precision-fermentation substitution. Anchor brigade hierarchy renewal through apprenticeship pipeline investments that resist demographic compression. For New Entrants and Emerging Players: Establish a beachhead in dessert-centric molecular gastronomy formats where precision fermentation migrates fastest from experimental kitchens to Michelin-starred menus. Target Chicago and forthcoming satellite locations favoring hybrid service-theater configurations with compressed experiential density. Deploy pop-up restaurant formats to accelerate menu iteration cycles without fixed-venue capital burdens. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors terroir-integrated Japanese formations with defensible geographic exclusivity claims over scalable platform operators facing format commoditization. Long-term viability concentrates in establishments with MAFF certification systems and deep seasonal ingredient network integration. Watch carbon-footprint disclosure mandate penetration as inflection indicator for compliance cost escalation at three-star tier.| Strategic Initiative | Industry Significance |
|---|---|
| MAFF Certification Investment | Secures geographic exclusivity claims for foraged ingredients under Japan's agricultural framework. |
| Precision Fermentation Integration | Migrates specialty dairy and protein analogs from novelty positioning to core ingredient architecture. |
| Ghost-Kitchen Licensing Expansion | Enables rapid format testing without legacy real estate burdens across metropolitan markets. |
| Apprenticeship Pipeline Development | Sustains classical technique transmission through brigade hierarchy against generational attrition. |
| Carbon-Disclosure Compliance Buildout | Tracks ingredient carbon intensity across extended supply chains ahead of regulatory mandates. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with executive chefs, hospitality group procurement directors, MAFF certification officers, luxury hotel F&B executives, and foraged ingredient network coordinators. Secondary validation drew from EU CSRD disclosure filings, FDA seafood HACCP protocol documentation, Japanese Ministry of Agriculture certification registries, and Michelin guide historical listings. Bottom-up venue revenue modeling and top-down hospitality sector expenditure analysis were triangulated to anchor market sizing.
Calibration against historical CAGR trajectories in adjacent premium foodservice segments informed growth rate boundaries across the projection horizon. Segmentation dimensions modeled include cuisine type, service style, ingredient source certification tier, and meal type daypart. Growth rates were derived from elasticity analysis between hospitality investment cycles and haute cuisine penetration rates, with particular weighting for Southeast Asian luxury hotel expansion pipelines and Tokyo district-level star density differentials.
Stress conditions across carbon-footprint disclosure mandate timelines, precision-fermentation technology adoption curves, and apprenticeship pipeline demographic compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory integration pace and substitution technology maturation. Macroeconomic hospitality investment cycles, biodiversity-sourcing restriction enforcement intensity, or molecular gastronomy format saturation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Restaurant Glassware Market
Food Service
Asia-Pacific and Middle-East Inflight Catering Market
Food Service
South Korea Foodservice Market
Food Service
Global Waffle Maker Market
Food Service
Canada Food Service Market
Food Service
Ice Cream Carts Market
Food Service
Europe Food Cold Chain Logistics Market
Food Service
International Food Subscription Box Service Market
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
Russia Foodservice Market
Food Service
Saudi Arabia Quick Service Restaurants Market
Food Service
Clear Ice Maker Market
Food Service
Europe Cloud Kitchen Market
Food Service
Cloud Kitchen Market
Food Service
Commercial Beverage Dispenser Market
Food Service
Switzerland Food Service Market