
 Wide Field Imaging Devices Market | 2026-2036
Wide Field Imaging Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Wide Field Imaging Devices Market Intelligence
Silicon-based sensor arrays are repositioning product economics in wide field imaging by displacing legacy CCD architectures with lower-cost, higher-resolution CMOS alternatives. Carl Zeiss Meditec AG leverages its vertically integrated optical manufacturing to sustain premium positioning across European and North American channels. Heidelberg Engineering GmbH anchors its competitive stance through proprietary scanning laser technology, while Optos PLC differentiates via ultra-widefield 200-degree capture systems that dominate pediatric and peripheral retinal diagnostics.
Wide field imaging devices capture retinal images extending beyond the posterior pole to encompass the mid-periphery and far periphery, typically spanning 100 to 200 degrees in a single acquisition using scanning laser ophthalmoscopy or wide-angle fundus photography with specialized optical elements. These systems enable early detection of peripheral retinal pathology without pupil dilation, serving primary clinical purposes in diabetic retinopathy screening, retinopathy of prematurity monitoring, and intraoperative surgical guidance. Fundus camera platforms retain the largest installed base and margin pool across mature markets, while multi-modal imaging configurations combining angiography with structural OCT represent the fastest-growing product configuration as clinics consolidate diagnostic workflows. Near infrared imaging technology is gaining clinical traction for choroidal visualization, though digital imaging remains the dominant technology backbone across cost-sensitive procurement segments.
The FDA's Quality System Regulation and 510(k) premarket notification framework govern device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for ophthalmic imaging systems entering European markets. ISO 10993 biocompatibility standards and IEC 60601-1 electrical safety requirements shape product design parameters for manufacturers targeting multiple regulatory jurisdictions. Stakeholders must monitor evolving reimbursement coding for ultra-widefield imaging procedures, as coverage determinations will influence capital equipment purchase cycles across hospital outpatient departments and independent ophthalmology practices.
Market Dynamics
Silicon-based CMOS sensor arrays are compressing legacy CCD economics while integrated health networks consolidate diagnostic imaging procurement into multi-year enterprise contracts.
Growth Catalysts
- FDA 510(k) Streamlining:The premarket notification pathway for Class II ophthalmic devices accelerates commercial entry for manufacturers targeting United States hospital outpatient departments.
- Diabetic Retinopathy Screening Mandates:Ophthalmology clinics expand adoption of wide field retinal imaging as payors tighten quality metrics for diabetes care management.
- Silicon Photonics Cost Curves:CMOS fabrication scale economies reduce per-unit sensor costs, enabling price-competitive ultra-widefield systems for mid-tier practices.
Market Restraints
- Optical Element Supply Concentration:Precision aspheric lens manufacturing clusters in German and Japanese specialty glassworks, creating single-source vulnerability for wide-angle fundus camera producers.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation imposes extended timeline requirements for ophthalmic imaging systems entering European markets, compressing launch windows.
- Fluorescein Dye Substitution Pressure:Non-invasive near infrared imaging technologies threaten angiography-dependent system configurations in pediatric and screening applications.
Strategic Opportunities
- Retinopathy of Prematurity Surveillance:Neonatal intensive care units in India and Brazil present underpenetrated demand for portable ultra-widefield systems with telemedicine connectivity.
- Multi-Modal Workflow Consolidation:Integrated platforms combining structural OCT with angiography capture growing share of capital budgets as clinics reduce device footprints.
- Reimbursement Code Expansion:Emerging CPT coverage determinations for ultra-widefield imaging procedures in United States Medicare outpatient settings will unlock capital purchase cycles.
Industry Challenges
- Image Interpretation Training Gap:Peripheral retinal pathology recognition requires specialized expertise that residency programs have not standardized, creating bottlenecks for clinical adoption.
- Legacy PACS Integration Friction:Wide field imaging DICOM compliance varies across vendor implementations, forcing hospital IT departments into costly middleware deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wide Field Imaging Devices Market |
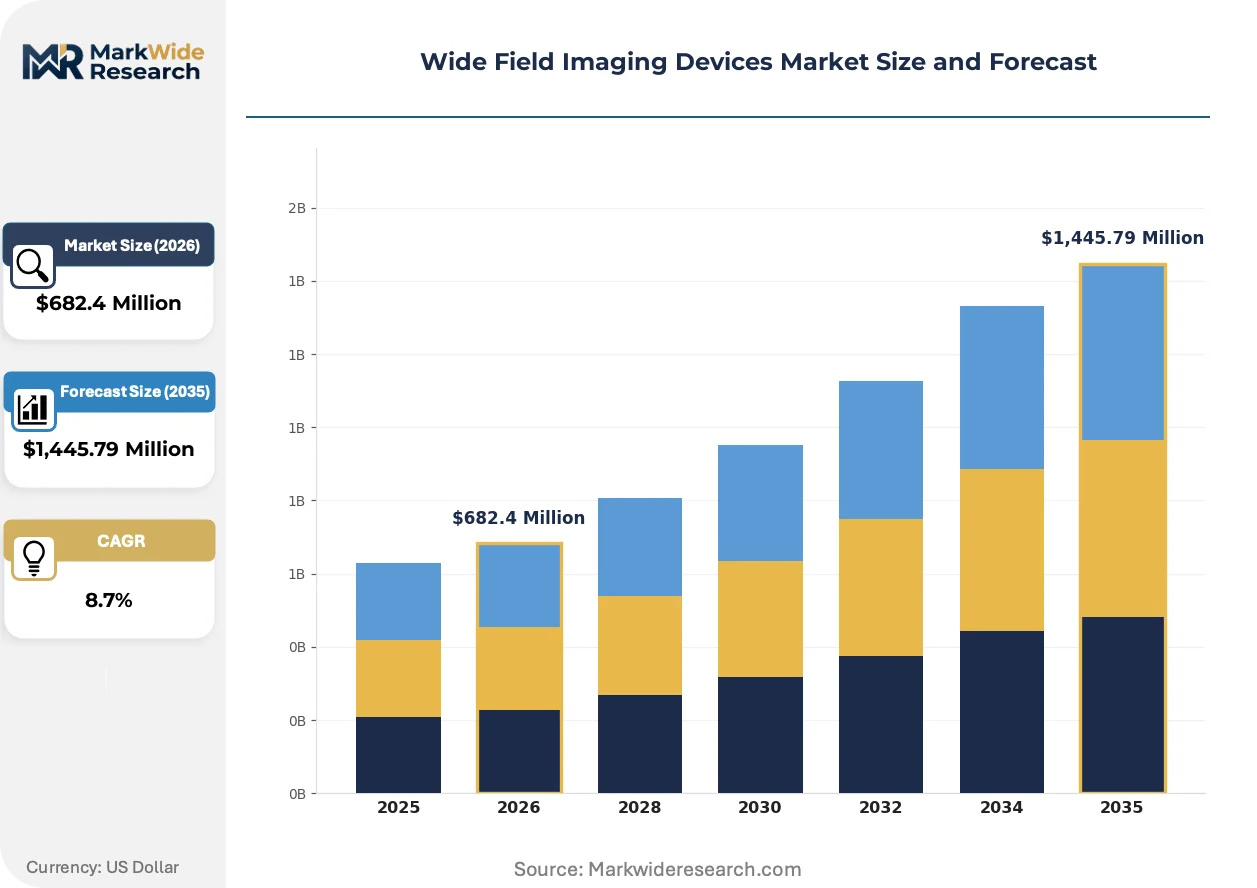
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,445.79 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
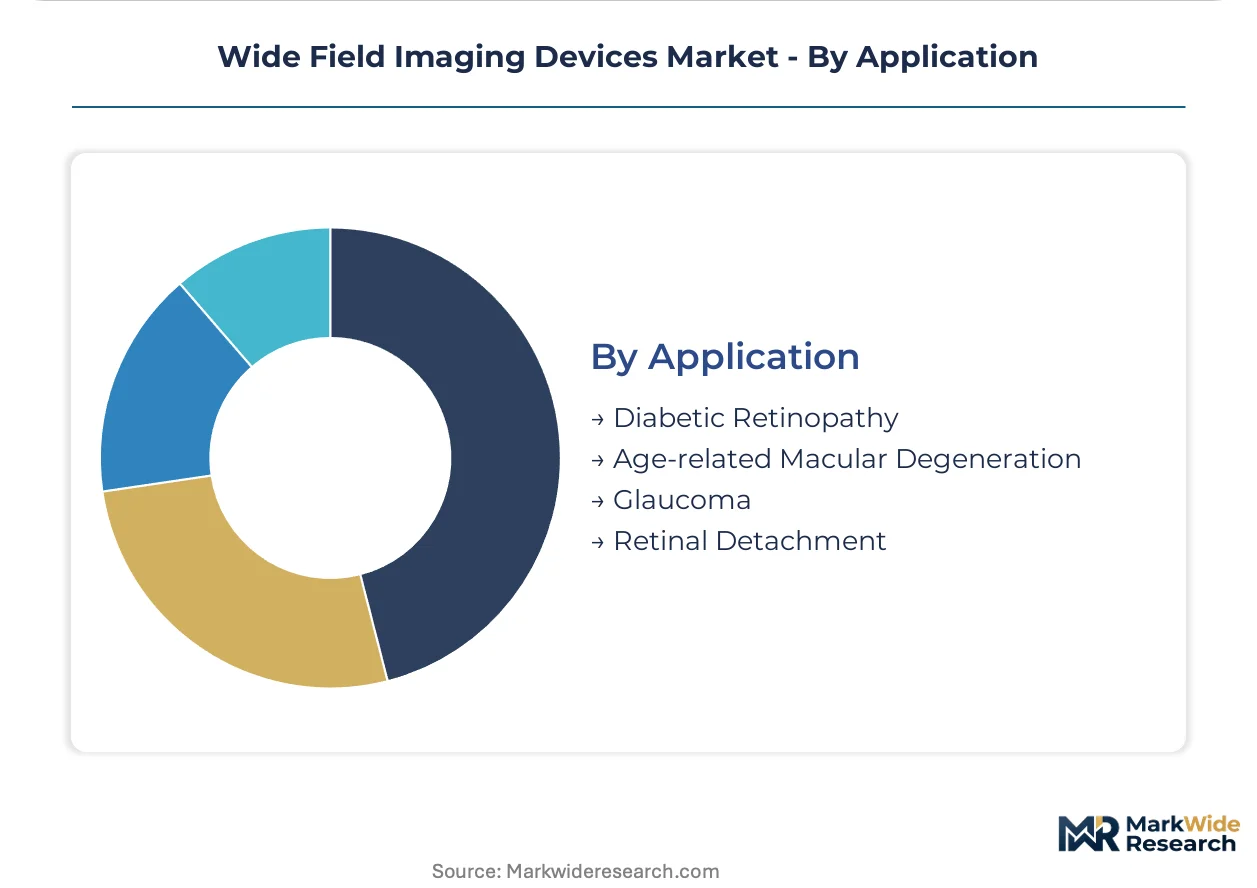
| Segmentation | Product Type: Fundus Camera, Optical Coherence Tomography, Retinal Imaging, Multi-modal Imaging Technology: Digital Imaging, Fluorescein Angiography, Indocyanine Green Angiography, Near Infrared Imaging End User: Ophthalmology Clinics, Research Institutions, Hospitals, Diagnostic Centers Application: Diabetic Retinopathy, Age-related Macular Degeneration, Glaucoma, Retinal Detachment |
| Companies Covered | Olympus Corporation, Carl Zeiss Meditec AG, Thermo Fisher Scientific Inc., Heidelberg Engineering GmbH, Optos PLC, Canon Inc., Bruker Corporation, Clarity Medical Systems Inc., Agilent Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wide Field Imaging Devices Market Strategic Shifts & Innovations
Active developments across sensor architecture, regulatory frameworks, and procurement models are restructuring how wide field imaging capabilities reach clinical endpoints.
Scanning laser ophthalmoscopy paired with adaptive optics is rewriting resolution benchmarks for peripheral retinal visualization. Academic medical centers in the United States and Germany are piloting these configurations for inherited retinal dystrophy research. The technology is compressing the gap between research-grade imaging and community clinic diagnostic standards.
The EU Medical Device Regulation's post-market surveillance requirements are extending clinical follow-up obligations for ophthalmic imaging manufacturers. Device makers must now maintain active safety registries across multiple member states. Systems with embedded AI diagnostic assistance face additional scrutiny under the EU AI Act's high-risk system classification.
Integrated health networks in the United States are consolidating diagnostic imaging procurement into centralized capital committees. Independent ophthalmology practices face exclusion from preferred vendor lists unless they adopt network-mandated device platforms. This concentration is visible across Kaiser Permanente, Mayo Clinic, and Cleveland Clinic affiliated facilities.
Wide Field Imaging Devices Market Segmentation
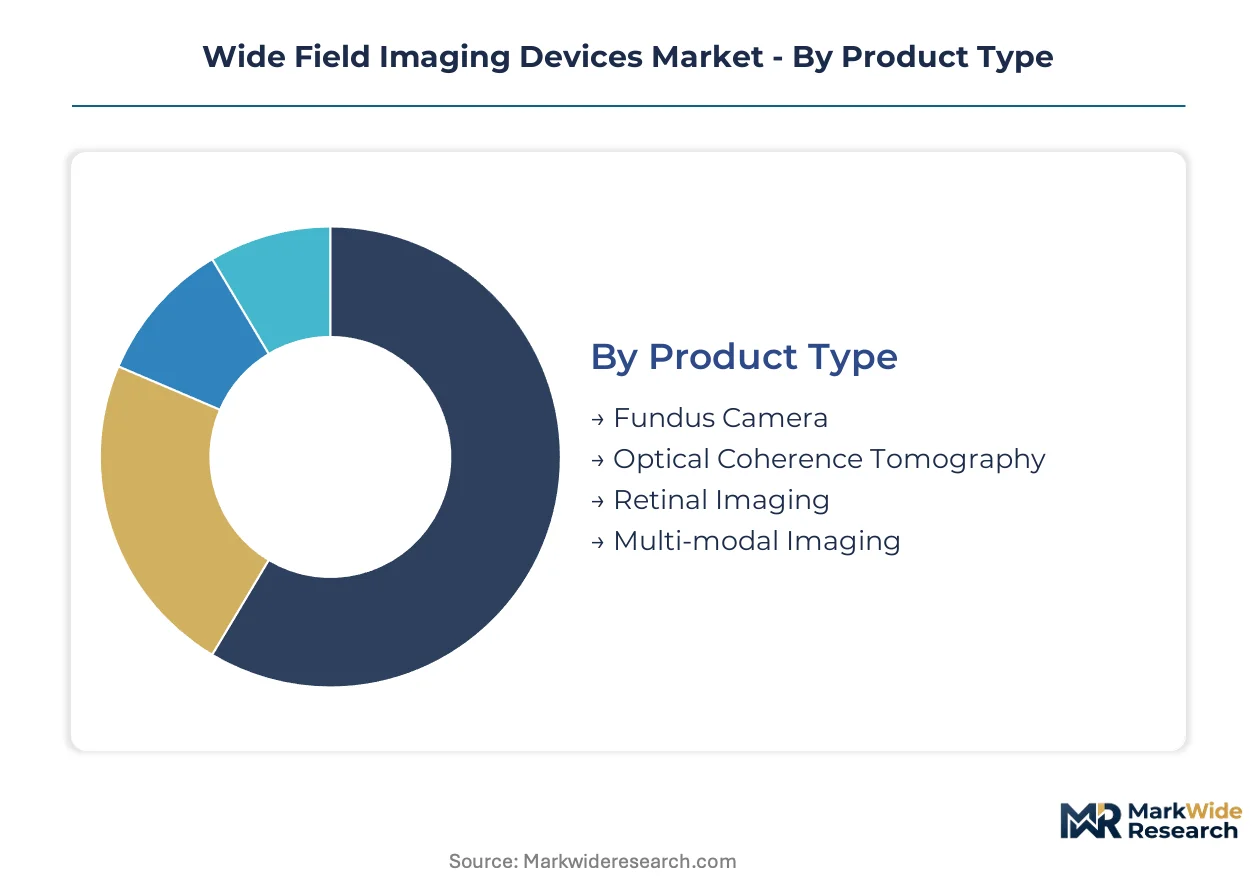
Segmentation in wide field imaging devices reveals how clinical workflows, reimbursement structures, and technology maturity create distinct procurement patterns across healthcare settings. Understanding these divides helps manufacturers align product configurations with specific capital allocation cycles and regulatory requirements.
Product Type:
Standardization dominates high-volume categories while customization concentrates in premium configurations serving academic medical centers.
- Fundus Camera:Wide-angle fundus photography systems with specialized optical elements capture 100-200 degree retinal fields in single acquisitions. Hospital outpatient departments in the United States favor these platforms for diabetic retinopathy screening workflows due to established CPT reimbursement codes and minimal operator training requirements.
- Multi-modal Imaging:Integrated platforms combining structural OCT with angiography consolidate diagnostic footprints for space-constrained ophthalmology clinics. Kaiser Permanente and Mayo Clinic affiliated networks are concentrating procurement into these configurations as they standardize enterprise-wide imaging protocols.
- Optical Coherence Tomography:Cross-sectional retinal imaging systems with wide-field scanning capabilities.
- Retinal Imaging:Dedicated peripheral visualization systems for pediatric and surgical applications.
Leading the category by volume: Fundus Camera. Expanding most quickly: Multi-modal Imaging.
Technology:
Cost tier stratification separates established dye-dependent methods from emerging non-invasive alternatives reshaping pediatric and screening protocols.
- Digital Imaging:CMOS sensor-based capture architectures displace legacy CCD systems across cost-sensitive procurement segments. Mid-tier ophthalmology practices in Germany and Japan are adopting these platforms as silicon photonics scale economies compress per-unit sensor costs.
- Near Infrared Imaging:Non-invasive choroidal visualization without fluorescein dye injection addresses pediatric safety concerns and dye shortage vulnerabilities. Neonatal intensive care units in India and Brazil are piloting these systems for retinopathy of prematurity surveillance where dye administration poses logistical constraints.
- Fluorescein Angiography:Contrast dye-based vascular imaging retaining diagnostic gold standard status for neovascular pathologies.
- Indocyanine Green Angiography:Specialized dye imaging for choroidal neovascularization and polypoidal choroidal vasculopathy assessment.
Dominating procurement volume: Digital Imaging. Gaining share fastest: Near Infrared Imaging.
End User:
Customer type determines service intensity requirements, with research institutions demanding configurable platforms and hospitals prioritizing interoperability.
- Ophthalmology Clinics:Independent and network-affiliated practices purchasing capital equipment through centralized procurement committees. These settings concentrate demand for ultra-widefield systems as payors tighten quality metrics for diabetes care management and require documented peripheral retinal examination.
- Hospitals:Integrated delivery networks with enterprise PACS infrastructure and dedicated IT support for DICOM compliance middleware. Cleveland Clinic affiliated facilities exemplify this segment's preference for vendor platforms with proven legacy system integration.
- Research Institutions:Academic medical centers piloting adaptive optics configurations for inherited retinal dystrophy studies.
- Diagnostic Centers:High-throughput screening facilities serving capitated health plans with standardized imaging protocols.
Highest equipment turnover: Ophthalmology Clinics. Steepest technology upgrade trajectory: Research Institutions.
Application:
Disease prevalence and reimbursement generosity create divergent addressable market sizes across clinical indications.
- Diabetic Retinopathy:Population-scale screening mandates drive the largest installed base of wide field imaging systems. The United States Medicare program's coverage determinations for ultra-widefield procedures directly influence capital purchase cycles for this indication.
- Retinal Detachment:Emergency and surgical applications requiring rapid peripheral retinal assessment. German and Japanese specialty glassworks supply the precision aspheric lenses essential for wide-angle capture in these time-critical settings.
- Age-related Macular Degeneration:Chronic disease monitoring with established imaging reimbursement pathways.
- Glaucoma:Optic nerve and retinal nerve fiber layer assessment integrating wide field peripheral data.
Widest reimbursement coverage: Diabetic Retinopathy. Fastest protocol adoption: Retinal Detachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Medical Device Single Audit Program recognition zone in Singapore concentrates regional ophthalmic device distribution. German precision glassworks supply critical optical elements to assembly operations clustered near major metropolitan health networks. Regulatory harmonization across key markets accelerates product registration timelines for manufacturers with established quality management systems.
United States
Kaiser Permanente and Mayo Clinic affiliated networks consolidate diagnostic imaging procurement into multi-year enterprise contracts. The FDA's 510(k) premarket notification pathway streamlines commercial entry for Class II ophthalmic devices targeting hospital outpatient departments. The Cleveland Clinic cluster in Ohio exemplifies preference for vendor platforms with proven legacy PACS integration.
Germany
Heidelberg Engineering GmbH anchors proprietary scanning laser technology development in the Baden-Württemberg medical technology corridor. The EU Medical Device Regulation imposes extended clinical evidence requirements that compress launch windows for new ophthalmic imaging systems. Precision aspheric lens manufacturing concentrates in specialty glassworks serving wide-angle fundus camera producers.
Japan
METI industrial policy supports CMOS sensor fabrication scale economies that reduce per-unit costs for wide field imaging devices. The PMDA reviews ophthalmic imaging systems under consolidated quality system assessments aligned with international harmonization efforts. Tokyo and Osaka metropolitan areas host concentrated procurement committees for integrated health network diagnostic equipment.
India
Neonatal intensive care units in Maharashtra and Karnataka present underpenetrated demand for portable ultra-widefield systems with telemedicine connectivity. The CDSCO medical device registration framework governs commercialization timelines for imported ophthalmic equipment. Mumbai and Bengaluru clusters concentrate private hospital chain procurement for diabetic retinopathy screening mandates.
Brazil
Retinopathy of prematurity surveillance programs in São Paulo and Rio de Janeiro drive pediatric ultra-widefield system adoption. ANVISA medical device registration requirements shape product configuration decisions for manufacturers targeting Latin American market entry. The Southeast region concentrates ophthalmology clinic density and associated capital equipment purchase cycles.
Wide Field Imaging Devices Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated optical fabricators commanding premium positioning in fundus camera configurations while modular component suppliers penetrate cost-sensitive procurement tiers. The vendor base concentrates around three strategic archetypes: precision optics specialists with captive glassworks, multi-modal platform integrators combining structural OCT with angiography, and CMOS sensor-scale manufacturers exploiting silicon photonics cost curves. Dominant competitive moves include backward integration into specialty lens production and strategic partnerships with integrated health networks for enterprise-wide imaging protocol standardization.
Among German precision optics fabricators, Carl Zeiss Meditec AG and Heidelberg Engineering GmbH exemplify vertically integrated manufacturing archetypes with proprietary technology positions. Optos PLC occupies a distinct tier through ultra-widefield 200-degree capture specialization. These three entities represent contrasting strategic postures: optical manufacturing depth, scanning laser technology differentiation, and pediatric-peripheral diagnostic focus respectively.
| Leading Market Players |
|---|
| Olympus Corporation |
| Carl Zeiss Meditec AG |
| Thermo Fisher Scientific Inc. |
| Heidelberg Engineering GmbH |
| Optos PLC |
| Canon Inc. |
| Bruker Corporation |
| Clarity Medical Systems Inc. |
| Agilent Technologies Inc. |
| Others |
Cost & Logistics Intelligence
Captive optical manufacturing in German and Japanese specialty glassworks anchors premium pricing power for fundus camera producers while compressing margin headroom for modular assemblers dependent on external lens sourcing. This integration choice separates Carl Zeiss Meditec AG and Heidelberg Engineering GmbH from competitors forced into multi-year supply agreements with limited volume flexibility.
Pricing Analysis
Volume concentrates in economy-tier digital imaging platforms while margin pools accrue to premium multi-modal configurations with embedded angiography. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA 510(k) cleared systems commanding substantial premiums over CE-marked-only alternatives. Cost compression in CMOS sensor tiers is intensifying because silicon photonics scale economies are flooding mid-tier practices with price-competitive alternatives. Independent ophthalmology practices exhibit highest price sensitivity, while integrated health networks prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements from Kaiser Permanente and Mayo Clinic procurement committees mandate qualified secondary suppliers for critical optical subassemblies, forcing vendors into redundant manufacturing relationships. Precision aspheric lens fabrication clusters in Germany and Japan, while CMOS sensor wafer production centers on Taiwan and South Korea. Single-source vulnerability in specialty glassworks creates concentrated exposure to logistics chokepoints affecting wide-angle fundus camera assembly. Distribution runs through regional ophthalmic device distributors with direct hospital sales forces for enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation's extended clinical evidence requirements have erected a cost-of-compliance barrier that favors incumbents with established quality management systems and active safety registries across multiple member states.
For Market Incumbents: Deepen backward integration into specialty lens production to neutralize German and Japanese glassworks supply concentration risk. Fortify enterprise imaging protocol partnerships with integrated health networks before CPT reimbursement code expansion unlocks competitor capital purchase cycles. Prioritize AI diagnostic assistance development under EU AI Act high-risk system classification frameworks to preempt regulatory displacement.
For New Entrants and Emerging Players: Begin with portable ultra-widefield configurations for neonatal intensive care units in Maharashtra and Karnataka, where telemedicine connectivity requirements exceed incumbent platform capabilities. Target retinopathy of prematurity surveillance applications where dye-free near infrared imaging addresses unmet pediatric safety needs. Deploy direct clinical specialist engagement bypassing distributor markup structures.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multi-modal platform integrators seeking optical manufacturing depth. Long-term viability hinges on regulatory certification moats widening as EU MDR post-market surveillance obligations extend clinical follow-up timelines. Monitor FDA 510(k) clearance velocity for ultra-widefield imaging procedures as inflection indicator for capital equipment purchase cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined premarket notification accelerates commercial entry for Class II ophthalmic devices targeting hospital outpatient departments. |
| CE Marking Pathway | EU MDR clinical evidence requirements compress launch windows but erect barriers against non-compliant competitors. |
| Hospital System Partnership | Enterprise-wide imaging protocol standardization with Kaiser Permanente secures multi-year capital commitment visibility. |
| Software Companion Development | AI diagnostic assistance integration triggers EU AI Act high-risk system scrutiny requiring additional validation investment. |
| Reimbursement Strategy | CPT coverage determination advocacy for ultra-widefield procedures unlocks Medicare outpatient capital purchase cycles. |
Research Approach
Independent corroboration across ophthalmology clinic purchasing committees, biomedical engineering directors, and GPO contracts managers underwrites the qualitative findings. Primary interviews with clinicians, hospital IT integration specialists, and regulatory affairs leads at device manufacturers combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, and hospital procurement databases. Bottom-up installed base estimates triangulate against top-down addressable market calculations across product type, technology, and end user segmentation dimensions.
Comparable-period anchoring to historical reimbursement code adoption curves and capital equipment replacement cycles shaped the projection horizon analytical framework. Modeled dimensions span product configuration, imaging technology, clinical application, and procurement channel type throughout the forecast period. CAGRs derived from regression analysis against diabetic retinopathy screening mandate expansion rates and CMOS sensor cost curve trajectories. Industry-specific inputs include fluorescein dye substitution pressure indices and integrated health network consolidation velocity.
Underlying measurement precision varies by segment; fundus camera volume estimates carry tighter precision than emerging near infrared imaging adoption curves. Forecasts reflect assumptions regarding FDA 510(k) clearance timelines, EU MDR transition completion, and Medicare coverage determination schedules. Deviation in reimbursement code expansion velocity or optical element supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Smartphone with Periscope Lens Market
Imaging
Thermal Imaging Systems Market
Imaging
Image Signal Processor and Vision Processor Market
Imaging
Asia Pacific Smartphone Camera Module Market
Imaging
Widefield Imaging Systems Market
Imaging
Semiconductor Microscopes Market
Imaging
Japan Digital X-Ray Market
Imaging
Hybrid Imaging Systems Market
Imaging
Europe Thermal Imaging Systems Market
Imaging
IR and Thermal Imaging Systems Market
Imaging
Industrial Computed Tomography Market
Imaging
Holographic Imaging Market
Imaging
Gige Camera Market
Imaging
Global 4K Camera Market
Imaging
AI-Based Fever Detection Camera Market
Imaging
Sub-Micrometer Computed Tomography Market