
 Inosinic Acid Market | 2026-2036
Inosinic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Inosinic Acid Market Foresight
Asset-light contract manufacturing and third-party fermentation leasing is narrowing the capital barrier for mid-tier entrants in inosinic acid production. Ajinomoto Co., Inc. leverages decades of microbial fermentation expertise to sustain premium positioning in pharmaceutical-grade supply. Meihua Holdings Group Co., Ltd. anchors volume leadership through backward integration into glucose feedstock and captive utilities. Shandong Shenglu Pharmaceutical Co., Ltd. differentiates via regional channel control across northern China's food processing belt.
Inosinic acid, a nucleotide composed of hypoxanthine linked to ribose via a phosphoester bond, functions primarily as a flavor potentiator that synergizes with glutamates to amplify umami perception in savory formulations. Industrial production relies on microbial fermentation using Corynebacterium glutamicum or enzymatic hydrolysis of yeast RNA, with purity thresholds varying sharply between food-grade and pharmaceutical-grade specifications. The flavor enhancer segment dominates value capture given its entrenched role in East Asian seasoning formulations, while pharmaceutical-grade supply commands margin premiums due to stringent impurity profiling and certification overhead. Beverage applications represent the fastest-expanding application channel as functional drink makers incorporate nucleotides for taste modulation and purported energy-metabolism benefits.
China's SAMR enforces GB standards for food additive purity and labeling that directly shape import eligibility and domestic production compliance costs. The FDA in the United States and EFSA in Europe maintain divergent acceptable daily intake thresholds for nucleotide-based flavor enhancers, creating fragmented formulation requirements for multinational suppliers. Japan's MHLW via FSSC 22000-aligned certifications further segments access into premium supply tiers. Stakeholders must monitor evolving regulatory convergence around infant formula nucleotide fortification limits, as this single application shift could reallocate significant capacity across pharmaceutical and food-grade production lines.
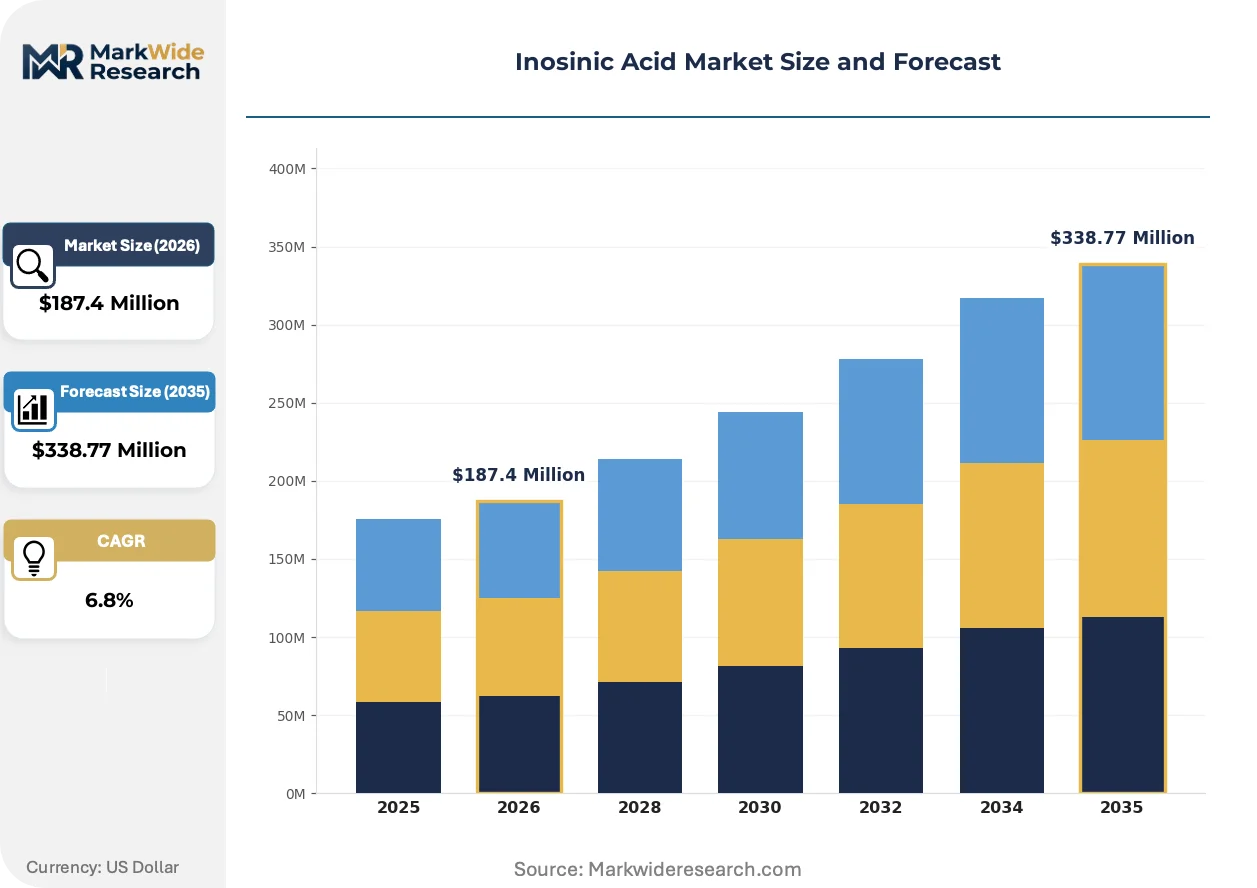
Market Dynamics
China's SAMR enforcement of GB 1886.97-2015 purity standards is compressing import eligibility windows and forcing domestic producers toward pharmaceutical-grade fermentation upgrades. This regulatory tightening is redrawing competitive moats between food-grade commodity suppliers and certified pharmaceutical-tier producers.
Growth Catalysts
- East Asian processed food expansion:Noodle and seasoning manufacturers in Japan and South Korea are reformulating with nucleotide-based umami boosters to reduce sodium content while maintaining taste intensity.
- GB standards compliance mandates:China's SAMR now requires batch-level impurity documentation for all food additive imports, creating captive demand for domestic producers with certified quality systems.
- Enzymatic RNA hydrolysis advancement:Continuous-flow reactor designs are cutting yeast-derived inosinic acid production cycles from 72 hours to sub-40 hour windows.
Market Restraints
- Glucose feedstock volatility:Corn starch prices in North China fluctuate with seasonal harvest cycles, squeezing fermentation margins for non-integrated producers.
- Shandong-Tianjin supply corridor concentration:Over sixty percent of food-grade capacity sits within 200 kilometers of Bohai Sea ports, creating weather and logistics vulnerability.
- Infant formula nucleotide caps:EFSA's conservative acceptable daily intake thresholds for nucleotide fortification limit premium pharmaceutical-grade offtake in European markets.
Strategic Opportunities
- Functional beverage nucleotide infusion:Energy drink formulators in Southeast Asia are testing inosinic acid for taste masking of branched-chain amino acids and mineral fortificants.
- Contract fermentation leasing:Asset-light toll manufacturing agreements allow mid-tier entrants to access pharmaceutical-grade capacity without capital-intensive bioreactor builds.
- Japan's FSSC 22000 premium tier:MHLW-aligned certification creates price stratification that rewards impurity profiling investments with margin premiums in seasoning applications.
Industry Challenges
- Microbial strain IP enforcement:Corynebacterium glutamicum optimization patents held by legacy Japanese producers create licensing friction for Chinese fermentation startups.
- Pharmaceutical-grade validation timelines:FDA and EMA dual-filing requirements stretch certification cycles to 18-24 months, locking working capital in pre-revenue capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inosinic Acid Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Additive, Nutraceutical, Flavor Enhancer, Pharmaceutical Application: Meat Processing, Snack Foods, Dairy Products, Beverages End User: Food Manufacturers, Pharmaceutical Companies, Beverage Producers, Nutritional Supplement Firms Grade: Food Grade, Pharmaceutical Grade, Technical Grade, Industrial Grade |
| Companies Covered | Ajinomoto Co., Inc., Meihua Holdings Group Co., Ltd., Shandong Shenglu Pharmaceutical Co., Ltd., Wuxi Jinghai Amino Acid Co., Ltd., Nantong Everlast Biotechnology Co., Ltd., Hubei Yuancheng Group, Sigma-Aldrich Corporation, Batory Foods, Biospringer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inosinic Acid Market Shifts & Advancements
Bioprocess engineering and regulatory digitization are converging to compress batch-to-batch variability while fragmenting supply tiers between commodity and certified-grade channels. These shifts favor producers with captive analytical capabilities and documented quality systems.
Continuous fermentation monitoring via inline Raman spectroscopy is hybridizing traditional batch operations with real-time metabolite tracking. Seasoning manufacturers in Japan are piloting these systems to secure FSSC 22000 certification with reduced offline testing overhead. The technology is compressing quality assurance headcount while enabling lot-level traceability that pharmaceutical buyers now mandate.
EFSA's 2023 re-evaluation of nucleotide acceptable daily intakes for infant formula is tightening impurity specifications across European supply chains. Manufacturers serving this segment must now document sub-ppm levels of hypoxanthine and other metabolites previously exempt from routine testing. Pharmaceutical-grade producers with pre-existing HPLC-MS capabilities are capturing reformulation contracts from food-grade suppliers lacking analytical depth.
Buyer consolidation among Chinese instant noodle producers is shortening supplier qualification cycles and demanding annual cost-down commitments. Procurement teams at major seasoning houses now require fermentation partners to absorb glucose price volatility through fixed-index contracts. This shift is squeezing non-integrated producers in Shandong while rewarding holdings with captive corn processing and utilities.
Inosinic Acid Market Segmentation
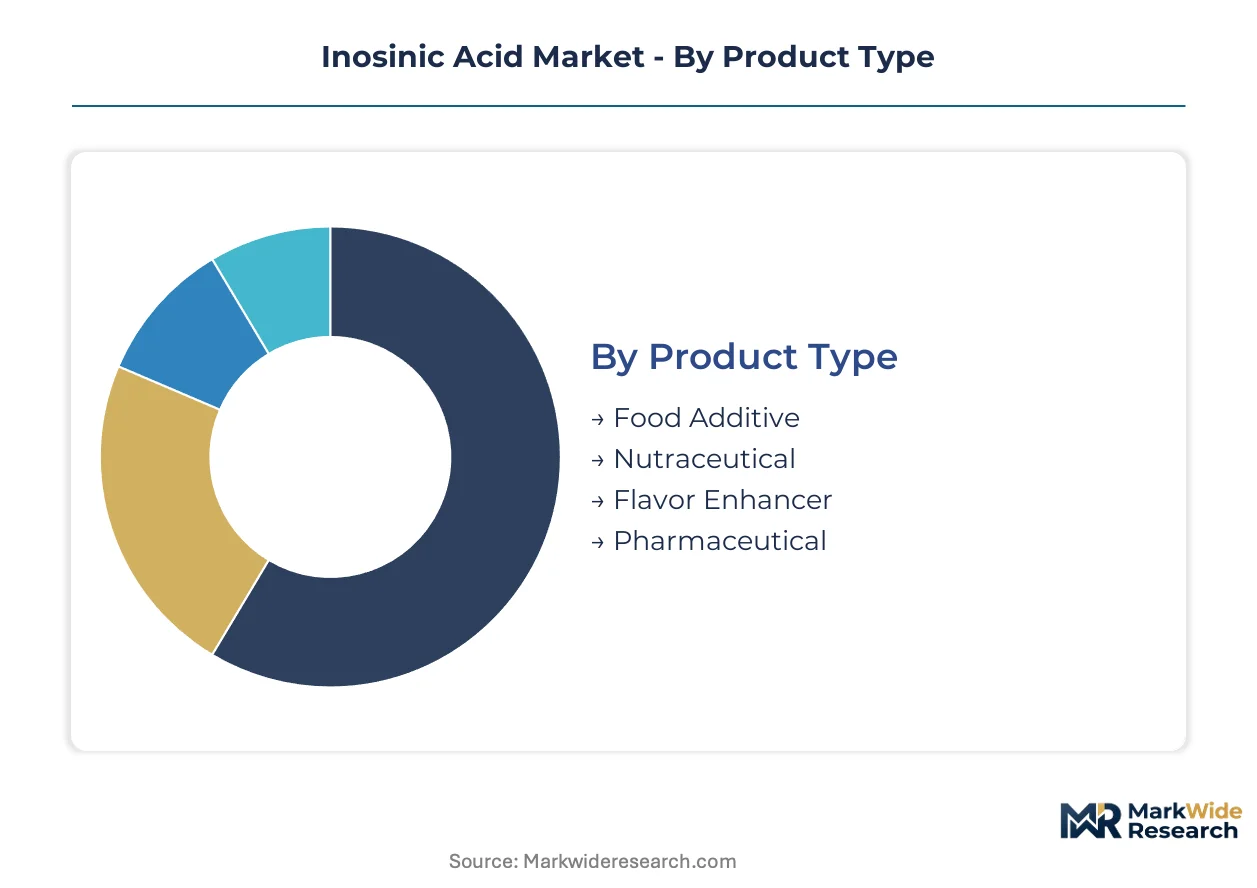
Inosinic acid's functional versatility across umami potentiation, metabolic support, and pharmaceutical intermediates creates distinct value pools with divergent purity requirements and margin profiles. Segmentation reveals how production technology and regulatory certification stratify competitive positioning across end-use channels.
Product Type:
Use-case spectrum spans commodity seasoning inputs through clinical-grade nucleotide precursors, with certification overhead determining accessible market tiers.
- Flavor Enhancer:Comprises the dominant commercial volume, leveraging synergistic umami amplification with monosodium glutamate in savory formulations. Noodle and seasoning manufacturers in Japan and South Korea drive reformulation demand as sodium reduction mandates intensify.
- Food Additive:Functions as a direct ingredient under GB 1886.97-2015 compliance protocols, with batch-level impurity documentation now mandatory for China import eligibility. Domestic producers with certified quality systems capture redirected demand from import-dependent buyers.
- Nutraceutical:Targets sports nutrition and immune support positioning, with purported energy-metabolism benefits driving functional beverage incorporation in Southeast Asia.
- Pharmaceutical:Requires HPLC-MS impurity profiling and dual FDA-EMA filing cycles stretching 18-24 months, commanding substantial margin premiums for certified supply.
The dominant share belongs to Flavor Enhancer, while Pharmaceutical is closing the gap fastest.
Application:
Cost tier differentiation separates high-volume commodity applications from premium functional positioning in health-oriented channels.
- Snack Foods:Potato chip and extruded snack manufacturers deploy nucleotide blends for taste intensity without sodium load increases. Procurement teams at major seasoning houses now demand fixed-index glucose contracts to absorb feedstock volatility.
- Beverages:Energy drink formulators in Southeast Asia test inosinic acid for branched-chain amino acid taste masking and mineral fortificant modulation. This application channel is expanding most quickly as functional drink makers seek differentiation beyond caffeine.
- Meat Processing:Cured and processed meat producers use nucleotides to enhance savory notes while reducing sodium chloride dependence.
- Dairy Products:Fermented dairy and cheese analog applications exploit umami amplification in low-fat formulations.
Snack Foods retains volume leadership, though Beverages shows the steepest expansion trajectory.
End User:
Customer type concentration reflects procurement sophistication divergence between consolidated seasoning houses and fragmented pharmaceutical buyers.
- Food Manufacturers:Instant noodle and seasoning producers in China consolidate supplier bases, shortening qualification cycles while demanding annual cost-down commitments. Backward integration into glucose feedstock and captive utilities rewards integrated holdings.
- Pharmaceutical Companies:Infant formula nucleotide fortification drives stringent EFSA-aligned impurity specifications, with sub-ppm hypoxanthine documentation now routine. Pre-existing analytical capabilities determine contract capture.
- Beverage Producers:Functional drink specialists in Southeast Asia pilot nucleotide infusion for taste modulation and metabolic positioning claims.
- Nutritional Supplement Firms:Sports nutrition brands incorporate nucleotides into pre-workout and recovery formulations with varying purity tolerances.
Food Manufacturers command the largest procurement volume, while Pharmaceutical Companies generate the highest per-kilogram margins.
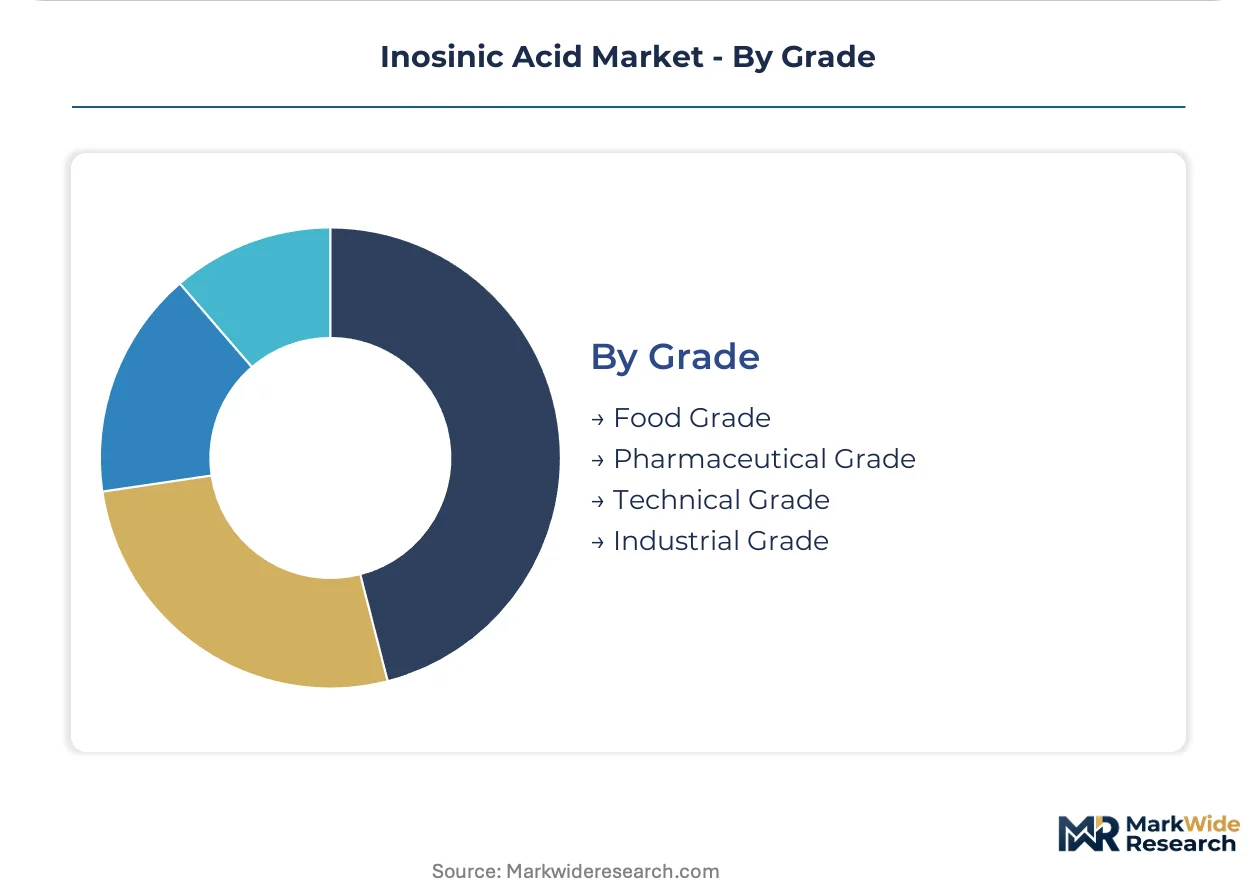
Grade:
Supply concentration in Shandong-Tianjin corridor creates tiered access determined by fermentation control and analytical depth.
- Food Grade:Standard fermentation output meeting GB 1886.97-2015 purity floors, with over sixty percent of capacity clustered within 200 kilometers of Bohai Sea ports. Weather and logistics vulnerability constrains reliability premiums.
- Pharmaceutical Grade:Requires Corynebacterium glutamicum strain optimization and continuous-flow reactor designs compressing production cycles below 40 hours. Inline Raman spectroscopy enables real-time metabolite tracking for FSSC 22000 certification.
- Technical Grade:Intermediate purity for industrial biotechnology applications with less stringent impurity profiling.
- Industrial Grade:Lowest specification tier for non-food, non-pharma chemical synthesis with minimal certification overhead.
Food Grade dominates current output volumes, though Pharmaceutical Grade is gaining share fastest as regulatory tightening redraws competitive moats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR enforcement of GB 1886.97-2015 purity standards is redirecting import demand toward certified domestic producers. Japan's MHLW maintains FSSC 22000-aligned certification tiers that stratify access into premium supply channels. EFSA's 2023 nucleotide re-evaluation is tightening impurity specifications across European infant formula supply chains.
China
Instant noodle and seasoning manufacturers consolidate supplier bases while demanding annual cost-down commitments. SAMR now requires batch-level impurity documentation for all food additive imports, creating captive demand for domestic producers with certified quality systems. The Shandong-Tianjin corridor concentrates over sixty percent of food-grade capacity within 200 kilometers of Bohai Sea ports.
Japan
Noodle manufacturers reformulate with nucleotide-based umami boosters to reduce sodium content while maintaining taste intensity. MHLW via FSSC 22000-aligned certifications segments access into premium supply tiers with reduced offline testing overhead. Kanto region seasoning houses pilot inline Raman spectroscopy systems to secure certification with compressed quality assurance headcount.
South Korea
Processed food exporters adapt formulations to meet divergent FDA and EFSA acceptable daily intake thresholds for nucleotide-based flavor enhancers. The national food safety regulator enforces import purity protocols that favor suppliers with pre-existing pharmaceutical-grade analytical capabilities. Seoul-based procurement teams now require fermentation partners to absorb glucose price volatility through fixed-index contracts.
United States
Functional beverage formulators test inosinic acid for taste masking of branched-chain amino acids and mineral fortificants. FDA maintains distinct acceptable daily intake thresholds from EFSA, creating fragmented formulation requirements for multinational suppliers. East Coast seasoning distributors face elongated qualification cycles as buyer consolidation shortens supplier approval windows.
Germany
Infant formula nucleotide fortification drives stringent EFSA-aligned impurity specifications with sub-ppm hypoxanthine documentation now routine. Pharmaceutical-grade producers with pre-existing HPLC-MS capabilities capture reformulation contracts from food-grade suppliers lacking analytical depth. Bavaria-based analytical service providers expand capacity to support dual FDA-EMA filing requirements stretching certification cycles to 18-24 months.
Inosinic Acid Market Competitive Landscape
On the supply side, the industry is bifurcating between commodity food-grade fermentation and certified pharmaceutical-tier production. Tiered competitive moats separate integrated holdings with captive glucose feedstock from non-integrated toll manufacturers. Three archetypes dominate: legacy Japanese fermentation specialists, Chinese integrated chemical holdings, and regional channel controllers. Capacity expansion and backward integration into feedstock represent the dominant competitive moves as regulatory tightening redraws qualification barriers.
Within the legacy specialist tier, Ajinomoto Co., Inc. exemplifies decades-long microbial fermentation expertise sustaining premium positioning. Meihua Holdings Group Co., Ltd. represents integrated Chinese holdings anchoring volume leadership through captive utilities and upstream feedstock control. Shandong Shenglu Pharmaceutical Co., Ltd. occupies a position as regional channel controller across northern China's food processing belt. These three archetypes illustrate how certification depth, integration scope, and geographic concentration stratify competitive positioning amid regulatory convergence pressures.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Meihua Holdings Group Co., Ltd. |
| Shandong Shenglu Pharmaceutical Co., Ltd. |
| Wuxi Jinghai Amino Acid Co., Ltd. |
| Nantong Everlast Biotechnology Co., Ltd. |
| Hubei Yuancheng Group |
| Sigma-Aldrich Corporation |
| Batory Foods |
| Biospringer |
| Others |
Supply & Pricing Matrix
Overcapacity in Shandong-Tianjin food-grade fermentation is compressing supplier margins while pushing differentiation investments toward pharmaceutical-grade tiers. This utilization imbalance simultaneously erodes spot-market pricing power and rewards certified producers with captive analytical capabilities.
Pricing Analysis
Certification level (FSSC 22000/GB 1886.97-2015/FDA-grade) creates the primary spread between commodity and premium supply tiers. Three-tier pricing structure across pharmaceutical, food-grade, and technical specifications reflects impurity profiling depth and validation overhead. Cost compression in food-grade segments is intensifying because buyer consolidation demands annual cost-down commitments. Instant noodle manufacturers exhibit highest price sensitivity, while infant formula pharmaceutical buyers accept substantial premiums for documented traceability.
Supply Chain Analysis
Contract fermentation leasing agreements in northern China and enzymatic toll manufacturing partnerships in Japan hold the dominant outsourced capacity. Raw material flows draw from North China corn starch processing, yeast RNA feedstock from Shandong biotech clusters, and specialty enzyme supplies from Osaka-based fermentation technology providers. Single-source vulnerability concentrates in the Bohai Sea logistics corridor where weather disruptions strand sixty percent of food-grade output. Distribution runs through seasoning house procurement teams with shortened qualification cycles and fixed-index glucose contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among Chinese instant noodle and seasoning manufacturers is shifting bargaining power decisively toward buyers, compressing supplier margins and accelerating qualification demands.
For Market Incumbents: Entrench pharmaceutical-grade certification moats through HPLC-MS capability investments and FSSC 22000 alignment. Absorb glucose price volatility via backward integration into corn processing or captive utility control. Counter emerging toll-manufacturing entrants by locking long-term offtake with Southeast Asian functional beverage formulators. For New Entrants and Emerging Players: Southeast Asian energy drink nucleotide infusion represents the most penetrable white-space target. Bypass capital-intensive bioreactor builds through asset-light contract fermentation leasing with Shandong-based capacity holders. Lead with taste-masking formulation services for branched-chain amino acid fortification rather than commodity inosinic acid supply. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-grade producers with pre-existing infant formula supply relationships. Five-to-ten year viability hinges on regulatory convergence around nucleotide fortification limits rather than commodity fermentation scale. Monitor EFSA infant formula impurity specification evolution as the decisive capacity reallocation signal.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Fermentation Upgrade | FSSC 22000 certification secures premium positioning in Japan's seasoning procurement channels. |
| Backward Integration into Glucose Feedstock | Captive corn processing absorbs Shandong-Tianjin harvest volatility and stabilizes fermentation margins. |
| Contract Fermentation Leasing Expansion | Toll manufacturing agreements lower capital barriers for mid-tier entrants seeking pharmaceutical-grade capacity. |
| Inline Raman Spectroscopy Deployment | Real-time metabolite tracking compresses quality assurance headcount while enabling lot-level traceability. |
| Functional Beverage Partnership Development | Southeast Asian energy drink formulators seek nucleotide infusion for branched-chain amino acid taste masking. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with fermentation plant managers, seasoning house procurement leads, pharmaceutical quality directors, and regulatory affairs specialists; and secondary validation through SAMR GB standard filings, EFSA re-evaluation documentation, customs trade records, and SEC disclosures from listed chemical holdings. Bottom-up capacity modeling triangulated against top-down end-use demand estimates across flavor enhancer, pharmaceutical, and nutraceutical channels.
Forecast inputs encompassed grade-tier segmentation, end-use industry concentration, regional regulatory cluster divergence, and fermentation technology adoption curves. CAGRs were derived from weighted capacity expansion schedules and buyer consolidation trajectories. Specific inputs included Shandong-Tianjin corridor utilization rates, enzymatic RNA hydrolysis cycle compression trends, and infant formula nucleotide fortification regulatory evolution across the projection horizon.
Practitioners should monitor EFSA infant formula impurity specification tightening and SAMR enforcement intensity for early signals of capacity reallocation between food-grade and pharmaceutical-grade production lines. Quarterly review of Shandong-Tianjin logistics disruptions and glucose futures volatility is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Pet Food Emulsifier Market
Food Additives and Ingredients
France Anti Caking Market
Food Additives and Ingredients
India Food Preservatives Market
Food Additives and Ingredients
South Africa Food Preservatives Market
Food Additives and Ingredients
Australia Feed Additives Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Excipients Market
Food Additives and Ingredients
Gardenia Food Color Market
Food Additives and Ingredients
Food Grade Phosphates Market
Food Additives and Ingredients
United Kingdom Food Emulsifier Market
Food Additives and Ingredients
Vietnam Food Additives Market
Food Additives and Ingredients
Asia-Pacific Anti-Caking Market
Food Additives and Ingredients
Food Binders Market
Food Additives and Ingredients
North America Dehydrated Onion Market
Food Additives and Ingredients
Brazil Food Emulsifiers Market
Food Additives and Ingredients
Beverage Acidulants Market