
 India Food Preservatives Market | 2026-2036
India Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
India Food Preservatives Market Foresight
Natural extracts from rosemary and green tea are displacing synthetic benzoates in beverage formulations, and this shift is realigning cost structures across mid-tier preservative portfolios. Cargill Inc leverages its Ahmedabad technical center to anchor clean-label antioxidant supply for Indian dairy cooperatives. Jungbunzlauer Ag competes through citric acid fermentation scale at its Maharashtra facility, while BASF SE differentiates via tocopherol concentrates tailored to tropical stability requirements.
India food preservatives comprise chemical or biological substances added to food matrices to inhibit microbial spoilage, enzymatic browning, or oxidative rancidity, typically dosed at 0.01% to 0.1% by weight depending on food category pH and water activity. Their primary commercial purpose is extending shelf stability under ambient distribution conditions where refrigerated logistics remain fragmented. Synthetic preservatives still dominate volume in ready-to-eat meals and bakery items, though natural preservatives command widening margin pools as FSSAI disclosure rules tighten. Antimicrobials targeting dairy applications face accelerated qualification cycles as paneer and flavored milk segments expand.
FSSAI additive schedules, BIS purity specifications, and state-level food safety commissionerates collectively determine permissible preservative categories and maximum limits across India's 28 states. The PLI scheme for food processing infrastructure indirectly amplifies demand by subsidizing cold-chain-adjacent manufacturing capacity. Stakeholders must monitor pending FSSAI consultations on natamycin and nisin thresholds, as these rulings will reshape competitive access for domestic versus imported preservative suppliers.
Market Dynamics
Cold-chain fragmentation across Maharashtra and Gujarat is forcing packaged dairy manufacturers to front-load preservative procurement, while FSSAI's disclosure mandates compress reformulation timelines for clean-label migration.
Growth Catalysts
- PLI scheme subsidies:Food processing infrastructure incentives in western India are expanding cold-chain-adjacent manufacturing capacity, amplifying demand for shelf-stability additives in ambient distribution corridors.
- Paneer and flavored milk segments:Accelerated qualification cycles for antimicrobials are opening procurement windows as dairy cooperatives scale production without refrigerated logistics coverage.
- FSSAI labeling norms:Tightened additive disclosure rules are pulling mid-tier manufacturers toward natural extract reformulation, creating procurement urgency ahead of compliance deadlines.
Market Restraints
- Petrochemical feedstock volatility:Synthetic benzoate and sorbate input costs fluctuate with crude-linked benzene derivatives, compressing margin pools for commodity preservative portfolios.
- Western India supply concentration:Maharashtra and Gujarat host disproportionate fermentation and extraction capacity, creating geographic vulnerability to monsoon logistics disruptions and state-level commissionerate enforcement variance.
- Clean-label technical ceiling:Natural rosemary and green tea extracts face stability degradation under tropical humidity, limiting substitution depth in ambient-distributed ready-to-eat meals.
Strategic Opportunities
- Southern India processing corridors:Tamil Nadu and Karnataka dairy clusters remain underpenetrated for antimicrobial preservatives, offering first-mover positioning as cooperatives modernize without full cold-chain coverage.
- Pending natamycin thresholds:FSSAI consultations on dairy mold inhibitors will reshape competitive access, favoring domestic fermentation specialists over imported concentrate suppliers if thresholds tighten.
- Blockchain-integrated traceability:Convergence of distributed ledger verification with additive certification is enabling premium pricing for preservative batches with farm-to-fork documentation.
Industry Challenges
- Reformulation chemist scarcity:Clean-label antioxidant stability under tropical conditions requires specialized formulation expertise that outpaces current technical training pipeline output.
- BIS purity certification timelines:Batch testing for heavy metal and microbial specifications creates 8-12 week qualification windows that mismatch dairy sector procurement urgency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Food Preservatives Market |
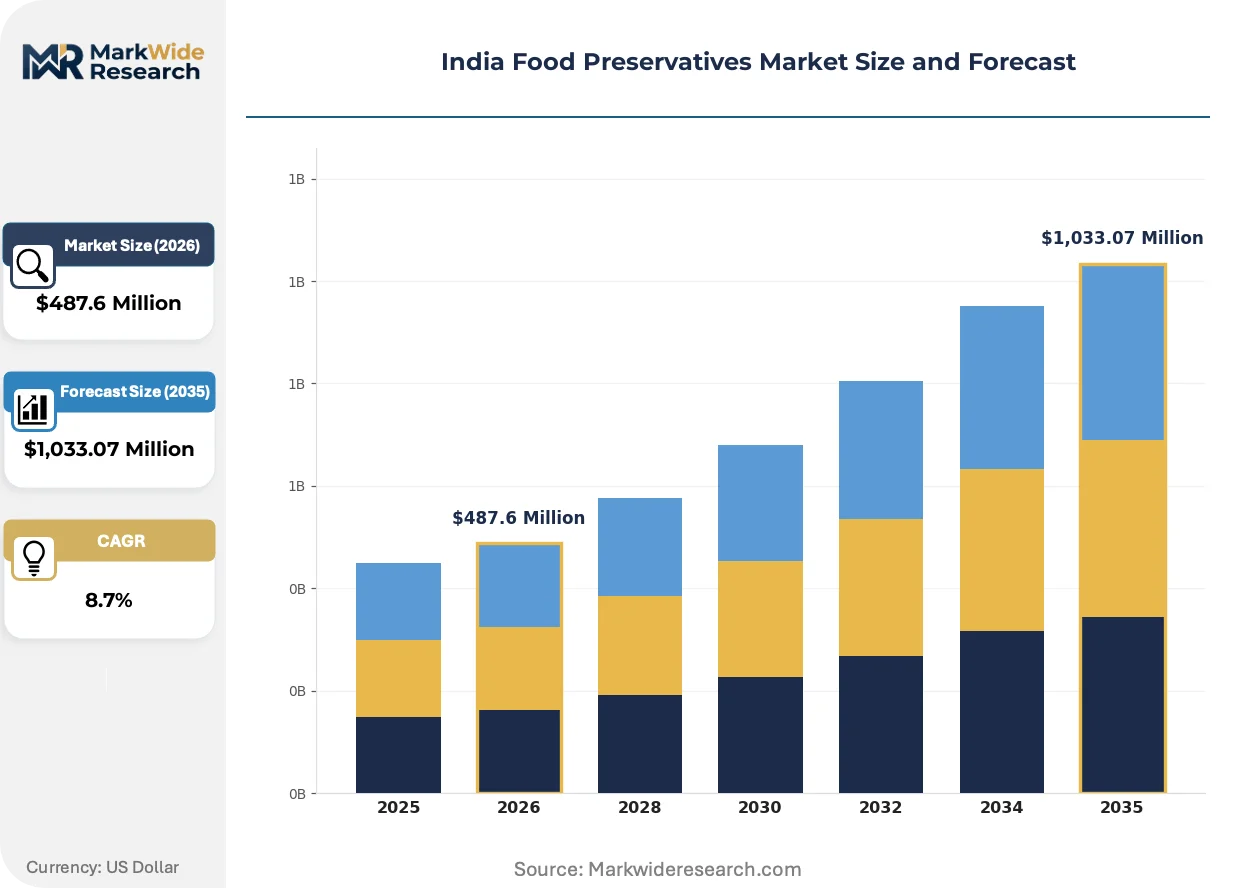
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Preservatives, Synthetic Preservatives, Antioxidants, Antimicrobials Application: Dairy Products, Bakery Items, Ready-to-Eat Meals, Beverages Form: Liquid, Powder, Granules, Tablets End User: Food Manufacturers, Retailers, Food Service Providers, Household |
| Companies Covered | DSM, Jungbunzlauer Ag, Cargill Inc, Camlin Fine Sciences, Archer Daniels Midland Company, Kerry Group, BASF SE, Ingredion Incorporated, Corbion Purac, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Food Preservatives Market Shifts & Advancements
Preservative technology is pivoting toward bio-based stabilization as synthetic chemistry faces disclosure friction, with extraction and fermentation platforms commanding technical investment priority.
Encapsulated tocopherol concentrates are absorbing moisture-sensitive antioxidant demand from dairy processors in Gujarat and Maharashtra. Mid-tier paneer manufacturers are adopting these formats at accelerated pace to bypass tropical rancidity without synthetic label penalties. The technology is absorbing margin compression from cold-chain infrastructure gaps by enabling ambient distribution windows previously requiring refrigerated logistics.
FSSAI's pending consultations on natamycin and nisin maximum limits are compressing supplier qualification timelines. Domestic fermentation facilities are scaling capacity ahead of rulings to capture threshold-driven procurement shifts. Dairy antimicrobials face the most acute compliance pressure, with cooperatives pre-qualifying alternative suppliers before mandate finalization.
Direct procurement from fermentation specialists is displacing layered distributor relationships in western India. Large dairy cooperatives in Ahmedabad and Pune are consolidating additive purchasing through technical service agreements with extraction facilities. This channel consolidation is most visible in antioxidant procurement, where shelf-stability specifications now travel directly from plant quality teams to supplier R&D labs.
India Food Preservatives Market Segmentation
Preservative procurement patterns in India diverge sharply across product categories and end-use applications, with FSSAI certification requirements and cold-chain infrastructure gaps dictating supplier selection criteria. Understanding these segment boundaries reveals where margin pools concentrate and which technical specifications command procurement urgency.
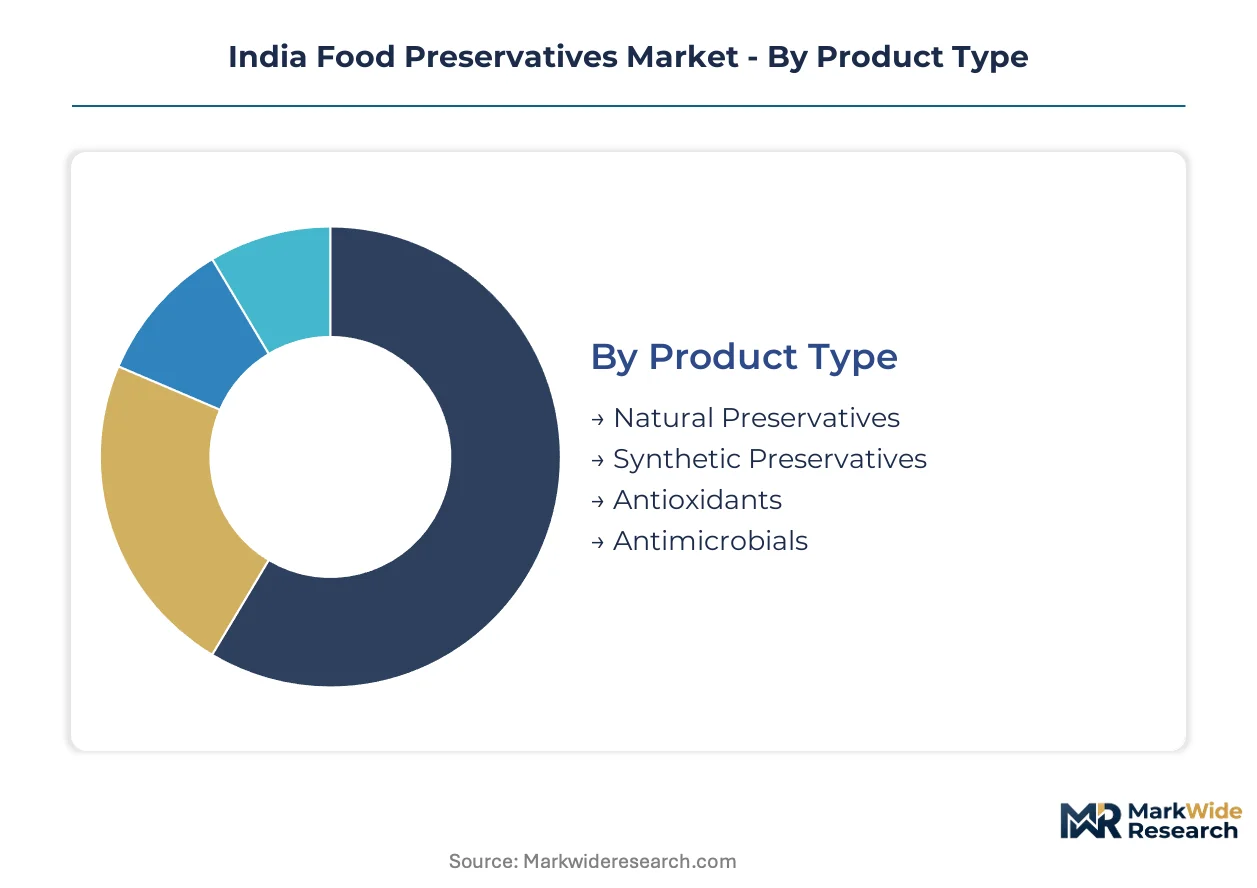
Product Type:
FSSAI additive schedules impose distinct purity certification burdens across preservative chemistries, with natural extracts requiring botanical source documentation and synthetic variants demanding heavy metal batch testing.
- Natural Preservatives:Rosemary oleoresins and green tea catechins extracted through supercritical CO2 or solvent-based methods deliver antioxidant protection without synthetic label declarations. Demand clusters in Gujarat and Maharashtra dairy cooperatives where FSSAI disclosure mandates have accelerated clean-label procurement timelines.
- Synthetic Preservatives:Benzoates, sorbates, and propionates manufactured from petrochemical feedstocks dominate ready-to-eat meal and bakery applications where cost sensitivity outweighs label preference. Maharashtra fermentation facilities supply bulk volumes, though crude-linked benzene derivative costs compress margin stability.
- Antioxidants:Tocopherol concentrates and ascorbic acid derivatives prevent lipid oxidation in ambient-distributed dairy products.
- Antimicrobials:Nisin and natamycin fermentation-derived inhibitors target mold and Gram-positive spoilage organisms in paneer and flavored milk segments.
Leading the category by volume: Synthetic Preservatives. Expanding most quickly: Natural Preservatives.
Application:
Cold-chain coverage gaps determine which food categories front-load preservative procurement, with unrefrigerated distribution corridors driving antimicrobial and antioxidant specification intensity.
- Dairy Products:Paneer, flavored milk, and processed cheese formulations require dual-function stabilization against microbial spoilage and oxidative rancidity. Western India cooperatives in Ahmedabad and Pune qualify suppliers through direct technical service agreements rather than distributor layers.
- Bakery Items:Bread, cakes, and biscuits utilize propionates and sorbates to inhibit mold without altering sensory profiles. Procurement concentrates in Maharashtra and Gujarat processing clusters where ambient shelf-life requirements exceed fourteen days.
- Ready-to-Eat Meals:Retort pouches and shelf-stable curries combine acidification with preservative dosing for tropical stability.
- Beverages:Fruit juices and dairy-based drinks deploy benzoates or natural extracts depending on label positioning and pH buffering capacity.
Highest procurement urgency: Dairy Products. Steepest specification evolution: Ready-to-Eat Meals.
Form:
Physical format selection hinges on manufacturing equipment compatibility and tropical humidity exposure during storage and distribution.
- Liquid:Aqueous solutions of organic acids and parabens integrate directly into high-moisture food matrices without dissolution steps. Preferred by large-scale beverage manufacturers in western India for continuous dosing accuracy.
- Powder:Spray-dried antioxidant concentrates and antimicrobial salts offer extended ambient stability and precise weight-based dosing. Dominates bakery premix and seasoning blend applications where moisture sensitivity prevents liquid incorporation.
- Granules:Agglomerated formats improve flowability for automated dispensing systems in high-volume dairy processing.
- Tablets:Compressed unit-dose formats serve small-scale food service and household segments with limited weighing infrastructure.
Dominant manufacturing format: Powder. Gaining adoption fastest: Granules for automated lines.
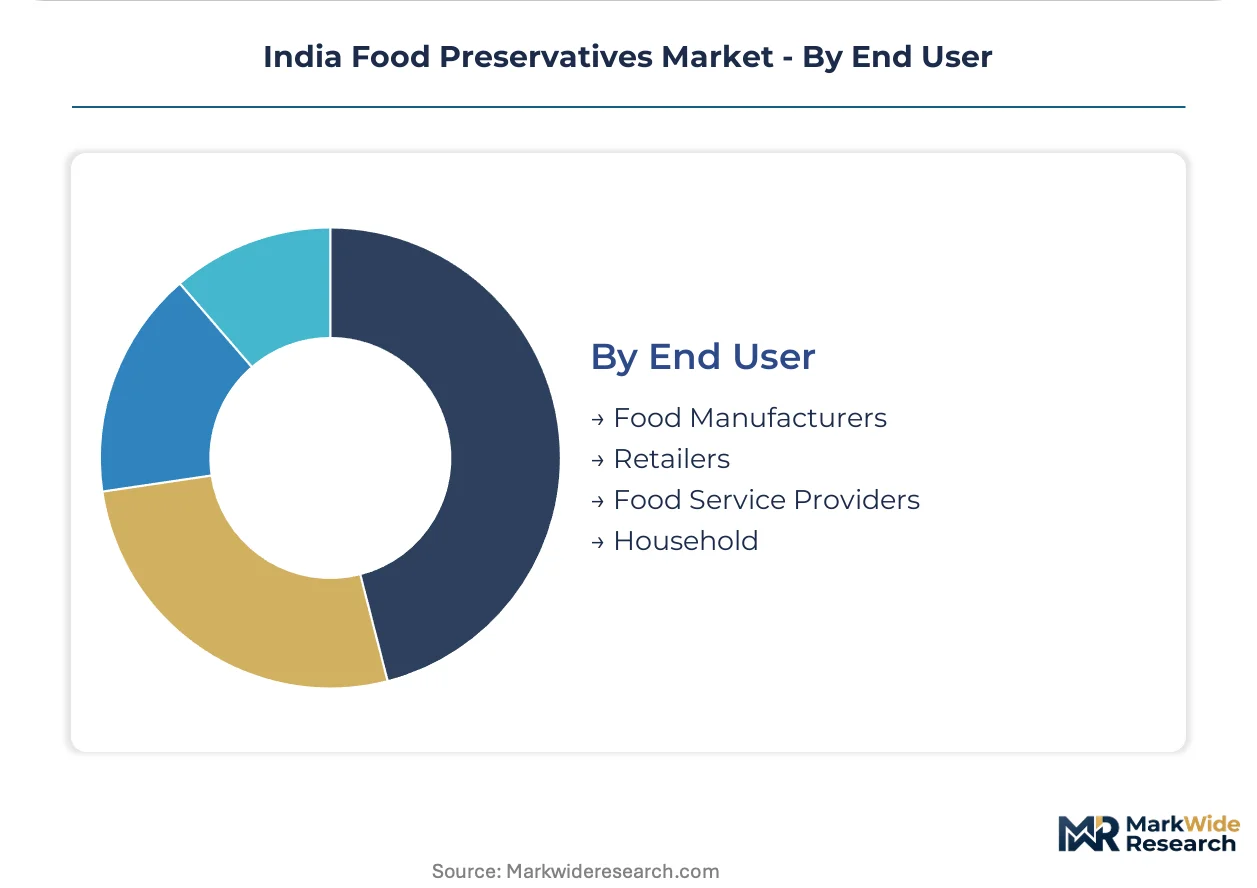
End User:
Procurement scale and technical service requirements fragment sharply across buyer categories, dictating channel structure and pricing architecture.
- Food Manufacturers:Integrated dairy cooperatives and multinational processing subsidiaries demand batch-level traceability, direct supplier R&D collaboration, and FSSAI-compliant documentation packages. Western India concentrates the largest procurement volumes through consolidated technical service agreements.
- Retailers:Private-label packaged food programs drive specification standardization across multiple contract manufacturers, with centralized quality teams mandating preservative approval lists.
- Food Service Providers:Restaurant chains and institutional caterers prioritize cost-optimized shelf-stable ingredients with minimal preparation steps.
- Household:Consumer-packaged preservative blends for home pickling and preservation represent marginal volume with high margin per kilogram.
Commanding procurement volume: Food Manufacturers. Expanding specification influence: Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Maharashtra and Gujarat anchor preservative demand concentration, with MIDC zones and Dahej SEZ hosting fermentation and extraction facilities that supply western India's food processing corridor.
Maharashtra
Paneer and flavored milk cooperatives in Pune and Nashik districts drive antimicrobial procurement urgency. FSSAI state commissionerate enforcement variance creates compliance complexity for out-of-state suppliers. The Baramati dairy cluster qualifies preservative vendors through direct technical service agreements, bypassing traditional distributor layers.
Gujarat
Ahmedabad's integrated dairy processors deploy encapsulated tocopherol concentrates to bridge cold-chain gaps in ambient distribution. PLI scheme subsidies for food processing infrastructure expand fermentation capacity at Dahej and Sanand industrial zones. Cargill's technical center anchors clean-label antioxidant supply for Amul-affiliated cooperatives.
Karnataka
Bangalore-Tumkur dairy modernization creates underpenetrated procurement windows for antimicrobial preservatives. State-level food safety infrastructure lags western India, extending supplier qualification timelines. The Kolar milk shed cooperatives represent first-mover opportunities as cold-chain coverage remains fragmented.
Tamil Nadu
Thanjavur and Erode dairy clusters scale paneer production without full refrigerated logistics coverage. BIS purity certification timelines mismatch procurement urgency from cooperative quality teams. The Coimbatore food processing corridor attracts preservative suppliers seeking southern India manufacturing presence.
Delhi-NCR
Ready-to-eat meal manufacturers in Noida and Gurugram specify dual-function stabilization for ambient shelf-stable curries. FSSAI headquarters proximity accelerates regulatory consultation participation for reformulation timing. The Kundli industrial area concentrates bakery preservative demand from contract manufacturers serving retail private-label programs.
India Food Preservatives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fermentation-derived natural preservatives commanding premium positioning against commodity synthetic suppliers. The vendor base concentrates around three strategic archetypes: integrated agribusiness conglomerates with extraction capabilities, dedicated fermentation specialists scaling citric acid and lactic acid platforms, and regional botanical extractors serving clean-label dairy reformulation. Capacity expansion and direct technical service agreements represent the dominant competitive moves, as large cooperatives consolidate procurement through plant-level R&D collaboration.
Within the integrated agribusiness tier, Cargill Inc and Archer Daniels Midland Company anchor supply relationships through technical center proximity to western India dairy clusters. Jungbunzlauer AG exemplifies the fermentation specialist archetype with citric acid scale at its Maharashtra facility. BASF SE occupies a position among tocopherol concentrate suppliers addressing tropical stability requirements. These three represent distinct capability configurations rather than interchangeable commodity supply.
| Leading Market Players |
|---|
| DSM |
| Jungbunzlauer Ag |
| Cargill Inc |
| Camlin Fine Sciences |
| Archer Daniels Midland Company |
| Kerry Group |
| BASF SE |
| Ingredion Incorporated |
| Corbion Purac |
| Others |
Supply & Pricing Matrix
Encapsulated tocopherol concentrate production is migrating from batch extraction to continuous fermentation platforms, simultaneously compressing unit economics and concentrating supply relationships around Maharashtra and Gujarat facilities with captive technical service capabilities.
Pricing Analysis
Volume-vs-margin splits sharply across synthetic benzoates and natural rosemary extracts. Three-tier pricing structure across fermentation-derived antimicrobials, encapsulated antioxidants, and commodity synthetic salts reflects FSSAI certification grade and cold-chain coverage requirements. Cost compression in synthetic portfolios is intensifying because crude-linked benzene derivative volatility feeds directly into sorbate and benzoate input costs. Mid-tier dairy cooperatives in western India show highest price sensitivity, while Amul-affiliated processors prioritize stability specifications over per-kilogram rates.
Supply Chain Analysis
Skilled fermentation technicians and extraction chemists concentrate disproportionately in Pune and Ahmedabad industrial corridors, anchoring capacity expansion decisions to these workforce clusters. Manufacturing draws from petrochemical feedstocks for synthetic preservatives, rosemary oleoresins from contract farming networks in Rajasthan, and citric acid from Maharashtra molasses fermentation. Single-source vulnerability runs through concentrated fermentation capacity at Dahej SEZ and MIDC zones. Distribution runs through direct technical service agreements between extraction facilities and dairy cooperative quality teams, bypassing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around fermentation scale and FSSAI certification speed, with pending natamycin threshold rulings forcing sub-scale botanical extractors toward exit or acquisition.
For Market Incumbents: Lock in cooperative relationships through embedded R&D collaboration at plant quality labs before threshold rulings finalize. Secure backward integration into rosemary contract farming networks in Rajasthan to buffer oleoresin supply volatility. Cargill's technical center model demonstrates how proximity to Ahmedabad dairy clusters creates switching costs for rival suppliers. For New Entrants and Emerging Players: Begin with antimicrobial qualification for Karnataka and Tamil Nadu dairy clusters where cold-chain gaps persist and incumbent technical service coverage remains thin. The Bangalore-Tumkur corridor offers first-mover positioning as cooperatives modernize without full refrigerated logistics. Lead with BIS purity certification speed as the primary go-to-market wedge against established western India suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated agribusiness conglomerates seeking fermentation capacity and FSSAI-compliant documentation infrastructure. Long-term viability hinges on clean-label reformulation capabilities that outpace synthetic disclosure friction. Watch FSSAI consultation timelines on natamycin and nisin thresholds as the critical inflection signal for domestic versus imported supplier competitive access.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Maharashtra fermentation scale-up captures antimicrobial demand from Pune dairy clusters. |
| Backward Integration | Rajasthan rosemary contract farming secures oleoresin supply for Gujarat extraction facilities. |
| Long-term Supply Agreement | Direct technical service contracts with Amul-affiliated cooperatives create switching barriers. |
| Joint Venture | Dahej SEZ partnerships with domestic fermentation specialists accelerate FSSAI qualification timelines. |
| Green Manufacturing Transition | Supercritical CO2 extraction platforms align with clean-label procurement from western India dairy processors. |
Research Methodology
FSSAI additive schedules, BIS purity specifications, and PLI scheme documentation formed the secondary backbone, supplemented by customs records on benzoate and sorbate imports. Primary interviews with dairy cooperative quality managers, fermentation plant technical directors, and FSSAI state commissionerate enforcement officers anchored demand-side validation. Top-down triangulation against food processing sector output data and bottom-up aggregation across Maharashtra, Gujarat, Karnataka, and Tamil Nadu procurement patterns produced volume estimates.
Bottom-up modeling tracked preservative dosing rates by food category pH and water activity, while top-down analysis calibrated against dairy sector expansion across the analysis window. Segmentation dimensions included product chemistry (natural extracts versus synthetic salts), application matrix (dairy, bakery, ready-to-eat, beverages), physical format (liquid, powder, granules), and end-user procurement scale. CAGRs derived from weighted average of segment growth trajectories, with cold-chain infrastructure gaps and FSSAI compliance timelines as primary forecast inputs.
Underlying measurement precision varies by segment; synthetic preservatives carry tighter precision given established petrochemical input cost visibility, while natural extract pricing reflects volatile agricultural commodity cycles. Forecasts reflect assumptions on PLI scheme disbursement continuity and FSSAI consultation timelines. A small set of triggers—monsoon logistics disruptions in western India, natamycin threshold rulings, and benzene derivative price spikes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Banana Powder Market
Food Additives and Ingredients
Annatto Food Colors Market
Food Additives and Ingredients
Noodles Preservatives Market
Food Additives and Ingredients
Mexico Anti Caking Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
Bread Emulsifier Market
Food Additives and Ingredients
Inosinic Acid Market
Food Additives and Ingredients
PVPP Beer Stabilizer Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
India Anti Caking Market
Food Additives and Ingredients
Asia-Pacific Fermented Ingredient Market
Food Additives and Ingredients
Global Integrated Food Ingredient Market
Food Additives and Ingredients
Hydrocolloid Carrier Market
Food Additives and Ingredients
Africa Food Enzymes Market
Food Additives and Ingredients
Food Grade Ammonium Bicarbonate Market
Food Additives and Ingredients
Global Oleate Esters Market