
 Brazil Food Emulsifiers Market | 2026-2036
Brazil Food Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Food Emulsifiers Market Outlook
Bakery and dairy applications is rebalancing toward plant-based emulsifier demand as Brazilian consumers shift preferences. Cargill leverages its soy lecithin supply chain across the Midwest and Southeast production zones. Kerry Group anchors its position through specialized emulsifier blends for clean-label bakery lines. Palsgaard competes with advanced polyglycerol ester technologies tailored to tropical climate stability requirements.
Food emulsifiers are surface-active agents with hydrophilic-lipophilic balance values typically between 3 and 8, manufactured through glycerolysis of fats or enzymatic modification of phospholipids, that stabilize oil-water interfaces in processed foods. Mono- and diglycerides dominate volume due to cost efficiency in mass-market bakery and dairy applications, while polyglycerol esters capture premium positioning in sauces requiring thermal stability. Plant-based sources, particularly soy lecithin, outpace animal-based alternatives as vegan certification becomes a procurement criterion for multinational food manufacturers operating in Brazil.
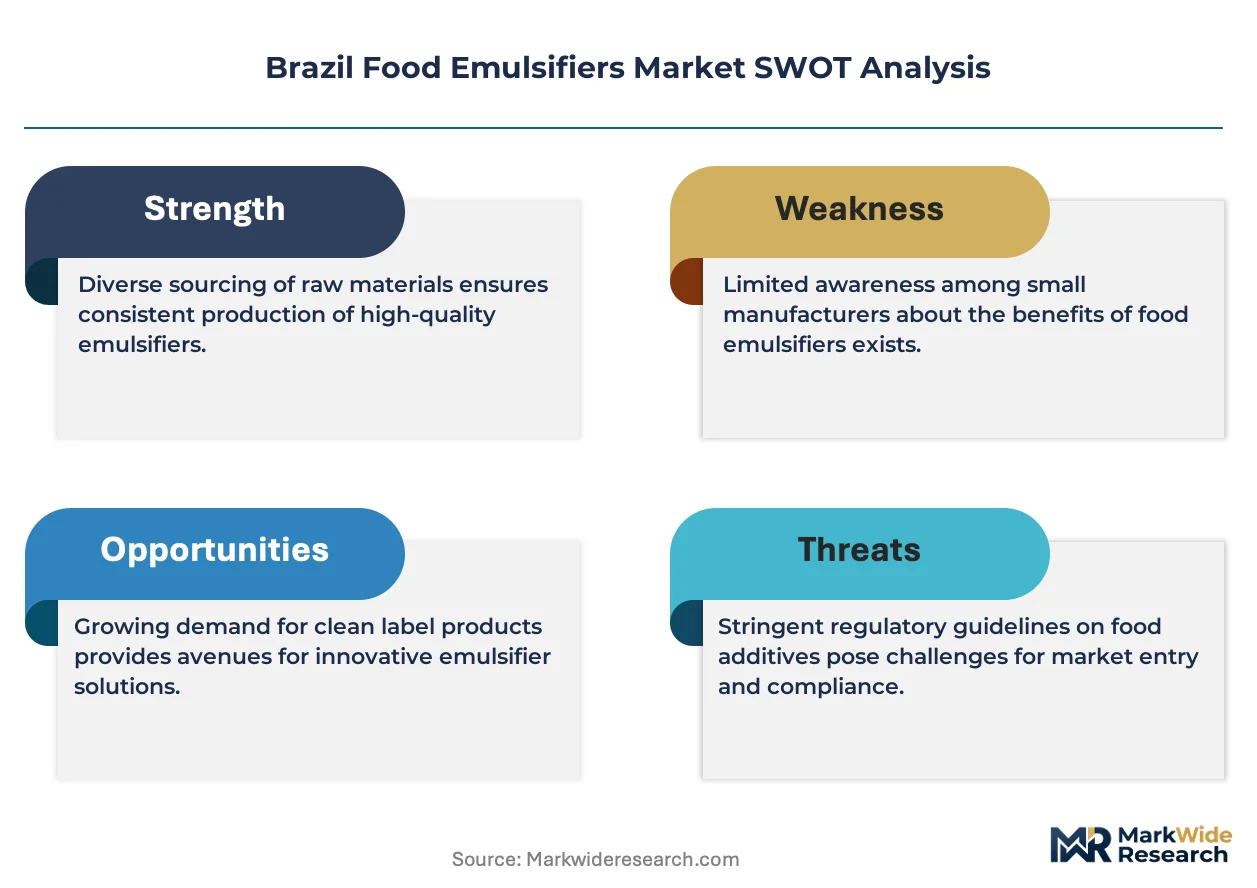
ANVISA governs food additive approvals and maximum usage levels under Brazilian health surveillance law, directly determining which emulsifier grades achieve market access. The Ministry of Agriculture's MAPA inspection protocols enforce traceability requirements that favor suppliers with integrated quality systems. ABIA, the Brazilian Food Industry Association, coordinates voluntary standards that often prefigure regulatory updates. Stakeholders must monitor pending ANVISA revisions to emulsifier purity specifications and align R&D investments with anticipated clean-label compliance thresholds.
Market Dynamics
ANVISA's tightening purity specifications for imported emulsifiers are forcing manufacturers to reconfigure supply chains toward domestic soy lecithin sources and enzymatic processing upgrades.
Growth Catalysts
- Clean-label bakery expansion:Brazilian consumers reject synthetic additives, pulling demand toward mono- and diglycerides from vegetable sources in São Paulo state's industrial bakery corridor.
- ANVISA regulatory alignment:Updated food additive frameworks create compliance certainty that accelerates foreign supplier certification and market entry.
- Polyglycerol ester thermal stability:Tropical climate requirements in Brazil's sauce and dressing sector drive premium positioning for heat-resistant emulsifier technologies.
Market Restraints
- Soy lecithin input volatility:Midwest and Southeast Brazilian soybean harvest fluctuations transmit directly to emulsifier production costs.
- Import dependency concentration:Specialized polyglycerol ester grades rely on European suppliers, exposing buyers to currency and logistics risk.
- Enzymatic modification capex barriers:Small Brazilian processors lack capital for phospholipase reactor systems, locking them out of high-margin clean-label segments.
Strategic Opportunities
- Northeast Brazil underpenetration:Bahia and Pernambuco food processing clusters lack local emulsifier blending capacity, creating white space for regional production facilities.
- Plant-based dairy analogues:Oat and almond milk expansion requires tailored emulsifier systems beyond traditional dairy applications.
- MAPA traceability mandates:Integrated quality systems become competitive differentiators as Ministry of Agriculture inspection protocols tighten.
Industry Challenges
- Phospholipid enzymology talent scarcity:Brazilian universities produce few specialists in lipid biochemistry, constraining R&D staffing for advanced emulsifier development.
- ANVISA certification timeline compression:Pending purity specification revisions force simultaneous reformulation and regulatory submission, straining quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Food Emulsifiers Market |
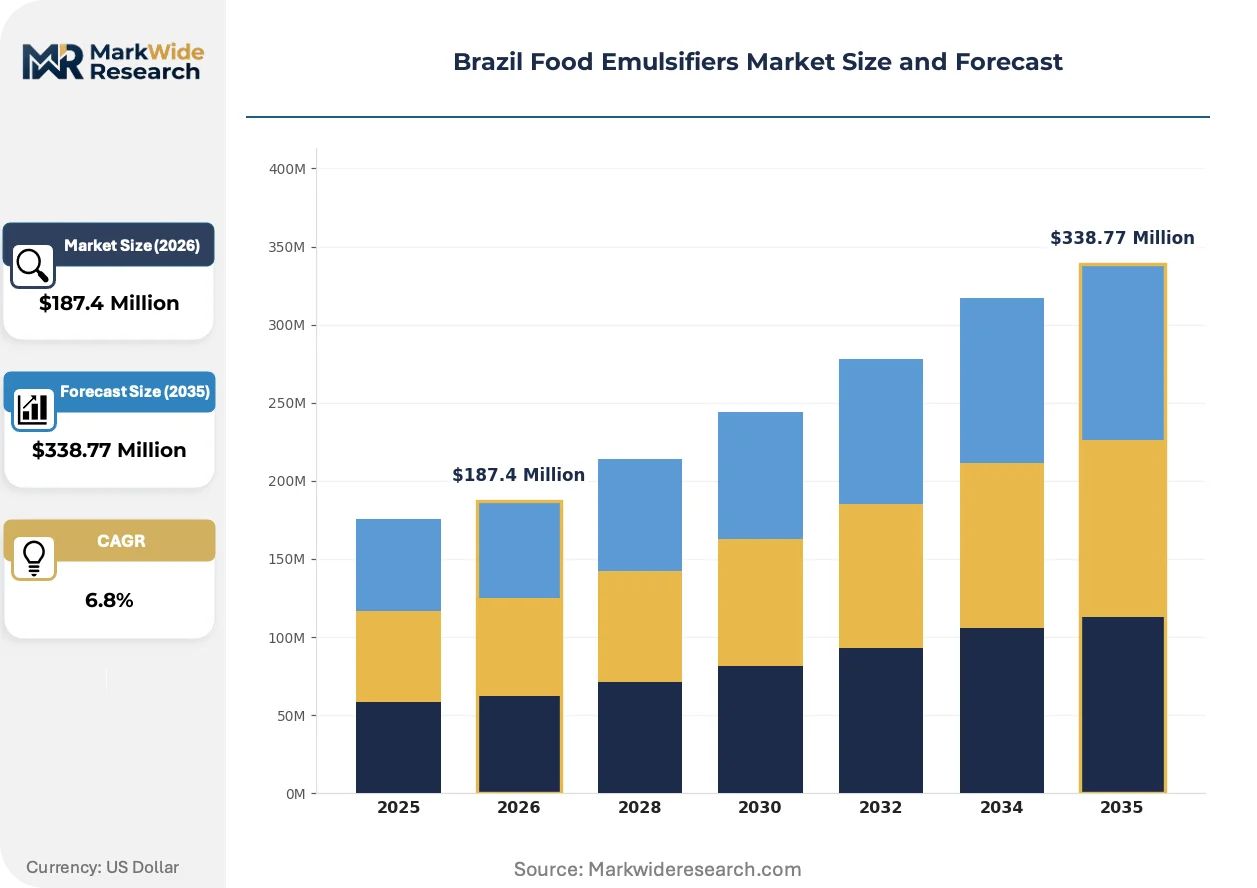
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Lecithin, Egg Yolk Lecithin, Mono- and Diglycerides, Polyglycerol Esters Application: Beverages, Bakery, Dairy Products, Sauces Source: Plant-Based, Animal-Based, Synthetic, Fermented End User: Food Manufacturers, Beverage Producers, Retail Outlets, Food Service |
| Companies Covered | DuPont de Nemours, Kerry Group, Cargill, Corbion, Tate & Lyle, Archer Daniels Midland Company, BASF SE, Palsgaard, Ingredion Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Food Emulsifiers Market Strategic Shifts
Enzymatic processing and clean-label certification are restructuring competitive advantage in Brazilian food emulsifiers, with technology adoption speed determining supplier tier positioning.
Enzymatically modified soy lecithin is absorbing market share from chemically processed alternatives as phospholipase treatments enable superior emulsification with cleaner ingredient declarations. Mid-sized Brazilian sauce manufacturers are adopting this technology fastest, compressing margins for conventional glycerolysis-based suppliers. The shift is absorbing volume from standard-grade lecithin channels and redirecting procurement toward integrated crush-to-emulsifier operations.
ANVISA's pending revisions to food additive purity specifications are tightening heavy metal and solvent residue limits for imported emulsifiers. This regulatory pressure is forcing foreign suppliers to establish Brazilian analytical certification partnerships or face market exclusion. Premium bakery and infant nutrition segments are responding earliest, demanding documentary evidence of enzymatic versus chemical processing methods.
Brazilian food manufacturers are consolidating emulsifier procurement through direct partnerships with Midwest soybean processors, bypassing traditional ingredient distributors. This channel compression is most visible in São Paulo state's dairy and margarine sectors, where volume buyers negotiate captive supply arrangements. Distributor margins are compressing as technical service and formulation support become the residual value proposition.
Brazil Food Emulsifiers Market Segmentation
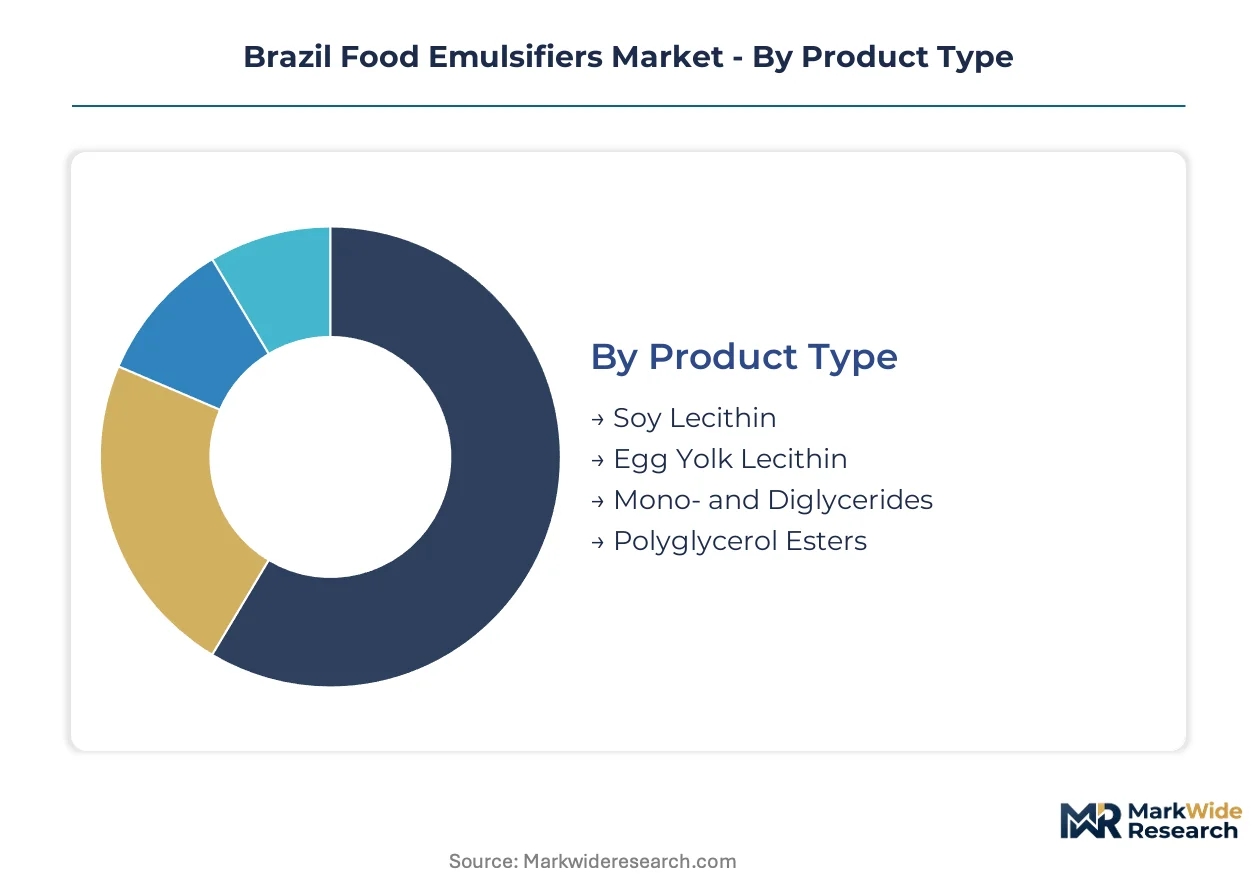
Emulsifier procurement in Brazil fragments across technical specifications, regulatory pathways, and supply chain configurations. Each segmentation dimension reveals distinct margin structures and competitive dynamics that determine supplier positioning.
Product Type:
Supply concentration in São Paulo state's processing corridor favors emulsifier categories with integrated domestic manufacturing.
- Soy Lecithin:Phospholipid concentrate extracted from Brazilian Midwest soybean crush operations, typically 60-95% phosphatidylcholine content. São Paulo's dairy and margarine manufacturers anchor demand, with ANVISA traceability mandates pushing procurement toward verified domestic crush facilities.
- Mono- and Diglycerides:Glycerol esters of fatty acids produced through glycerolysis of vegetable oils, dominating mass-market bakery applications by cost efficiency. Clean-label rejection of synthetic additives concentrates demand in São Paulo state's industrial bakery corridor, where enzymatic processing upgrades differentiate supplier tiers.
- Egg Yolk Lecithin:Phospholipid-rich extract from poultry processing, positioned in premium sauce emulsification.
- Polyglycerol Esters:Advanced thermal-stabilizing agents for tropical climate requirements, currently import-dependent from European suppliers.
Today's leader: Mono- and Diglycerides. Tomorrow's challenger: Enzymatically upgraded Soy Lecithin.
Application:
End-use differentiation in Brazil tracks regional food processing specialization and climate-driven formulation requirements.
- Bakery:Clean-label momentum is strongest here, with São Paulo's industrial bakeries reformulating away from synthetic emulsifiers toward vegetable-derived mono- and diglycerides.
- Sauces:Tropical heat stability requirements create premium positioning for polyglycerol ester technologies, with demand concentrating in Southeast Brazil's condiment manufacturing belt.
- Dairy Products:Traditional lecithin applications in cheese and margarine face plant-based analogue displacement.
- Beverages:Functional drink emulsification demands are climbing fastest, particularly for clouding agents and vitamin stabilization.
Sauces command premium pricing tiers. Bakery drives absolute volume absorption.
Source:
Certification requirements and consumer preference shifts are reconfiguring raw material procurement across Brazilian emulsifier supply chains.
- Plant-Based:Soy and sunflower lecithin dominate, with vegan certification becoming mandatory for multinational manufacturer procurement.
- Animal-Based:Egg and dairy-derived emulsifiers retain niche positioning in traditional confectionery.
- Synthetic:Chemically produced emulsifiers face accelerating clean-label displacement in consumer-facing applications.
- Fermented:Biosurfactant production via microbial fermentation represents emerging capacity, constrained by phospholipid enzymology talent scarcity.
Plant-based sources absorb share fastest. Fermented alternatives await technical workforce expansion.
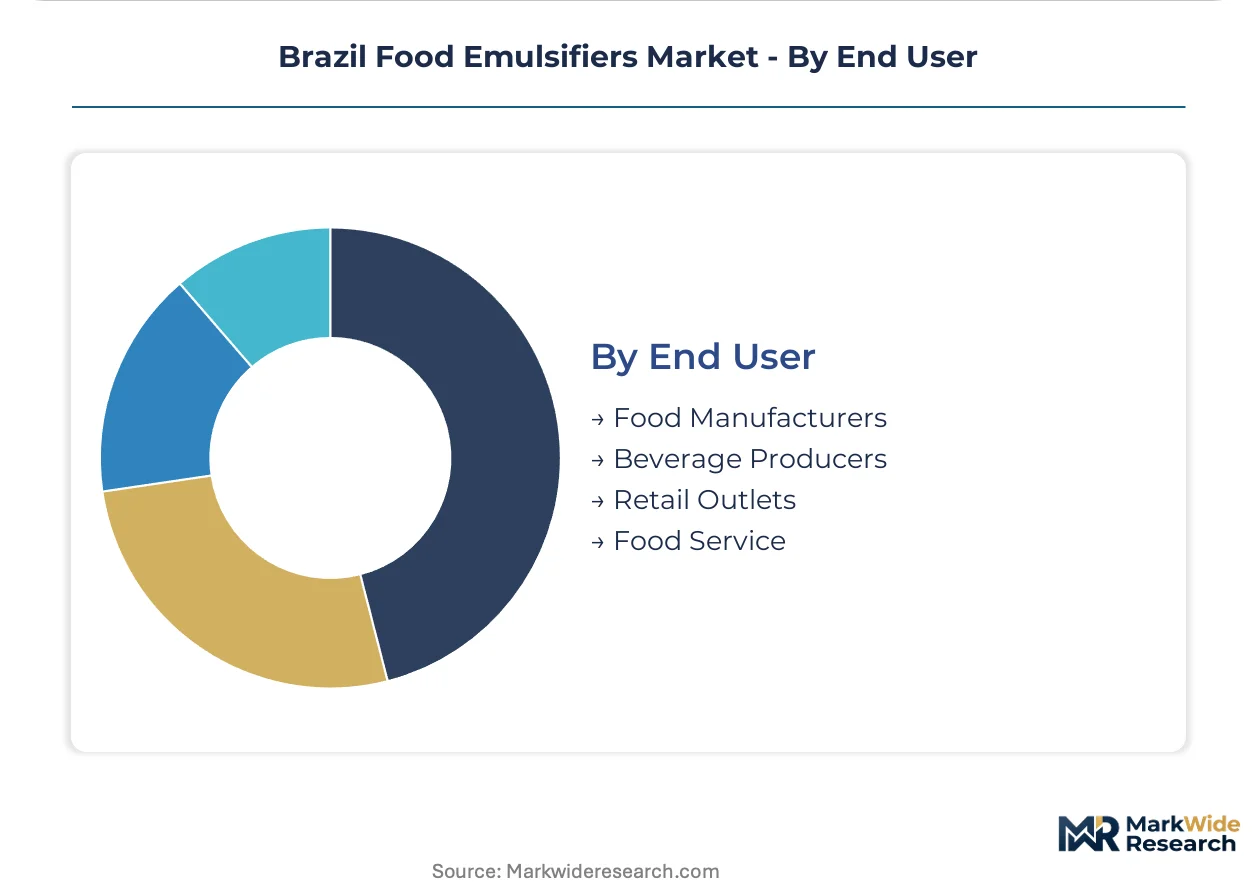
End User:
Channel structure in Brazil compresses as volume buyers consolidate procurement through direct processor partnerships.
- Food Manufacturers:São Paulo state's dairy and margarine sectors negotiate captive supply arrangements with Midwest soybean processors, bypassing traditional distributors.
- Beverage Producers:Functional drink formulators drive specialized emulsifier demand for stability in acidic and thermal-stressed matrices.
- Food Service:Distributed bakery and sauce preparation requires smaller-batch emulsifier formats with technical service support.
- Retail Outlets:Private-label penetration in supermarket bakery and dairy creates mid-tier emulsifier specification demand.
Food Manufacturers consolidate procurement power. Beverage Producers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's tightening purity specifications create compliance cost gaps that favor domestic Brazilian production over import-dependent supply chains. Midwest soybean processors capture arbitrage advantages as foreign suppliers face recertification burdens.
São Paulo
Industrial bakery corridors in São Paulo state absorb the highest emulsifier volumes, with clean-label reformulation accelerating demand for vegetable-derived mono- and diglycerides. ANVISA's updated food additive frameworks concentrate technical service resources here. Campinas and Sorocaba clusters host captive supply negotiations between major dairy processors and Midwest lecithin suppliers.
Minas Gerais
Dairy and margarine manufacturing in Minas Gerais drives lecithin procurement from integrated crush facilities. MAPA inspection protocols enforce traceability requirements that favor verified domestic sourcing. Uberlândia's food processing belt anchors backward integration negotiations with Goiás soybean suppliers.
Rio Grande do Sul
Poultry processing concentration supports niche egg yolk lecithin extraction for premium sauce applications. State environmental regulations constrain expansion of chemically intensive glycerolysis operations. Porto Alegre's condiment manufacturers test enzymatic alternatives for tropical climate stability.
Bahia
Underpenetrated food processing clusters in Salvador and Feira de Santana lack local emulsifier blending capacity. Northeast logistics costs disadvantage imported polyglycerol ester grades. State development incentives attract distribution hub investments from Southeast-based suppliers.
Paraná
Soybean crush capacity in Maringá and Londrina supplies phospholipid feedstock for enzymatic lecithin upgrades. State agricultural research institutions partner with processors on phospholipase reactor development. Curitiba's beverage formulators drive specialized demand for clouding agent emulsifiers.
Brazil Food Emulsifiers Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated agricultural processors commanding volume tiers and European technology licensors occupying premium niches. The vendor base stratifies into three tiers: captive crush-to-emulsifier operators, specialized blenders with formulation services, and import-dependent distributors of advanced polyglycerol esters. Dominant competitive moves include backward integration into soybean processing and enzymatic technology licensing partnerships.
Among integrated agricultural processors, Cargill and Archer Daniels Midland Company exemplify the captive supply archetype through Midwest and Southeast Brazilian crush-to-emulsifier operations. Kerry Group and Palsgaard occupy positions within the specialized technology tier, with the former anchoring clean-label bakery formulation services and the latter representing advanced polyglycerol ester capabilities. DuPont de Nemours and BASF SE sit within the diversified chemical technology segment, leveraging broader ingredient portfolios to secure multinational manufacturer contracts.
| Leading Market Players |
|---|
| DuPont de Nemours |
| Kerry Group |
| Cargill |
| Corbion |
| Tate & Lyle |
| Archer Daniels Midland Company |
| BASF SE |
| Palsgaard |
| Ingredion Incorporated |
| Others |
Value Chain & Pricing Dynamics
Phospholipid enzymology specialists concentrated in São Paulo state's research corridor widen pricing-tier spreads between enzymatically processed premium grades and conventional glycerolysis-based alternatives, as labor-cost differentials for technical talent compound input-cost advantages for integrated crush-to-emulsifier operators.
Pricing Analysis
Distributor margin compression now runs through São Paulo state's dairy and margarine sectors as volume buyers negotiate direct-to-processor arrangements that bypass traditional ingredient channels. Three-tier pricing structure across premium enzymatic grades, standard vegetable-derived mono- and diglycerides, and economy synthetic alternatives reflects certification-level differentiation and volume-scale thresholds. Pricing pressure stems from enzymatic processing capex barriers that strand smaller Brazilian processors in lower-margin conventional tiers. Food manufacturers demonstrate lowest price sensitivity due to captive supply arrangements, while food service distributors face acute margin compression without technical service differentiation.
Supply Chain Analysis
Returns and quality-failure flows from tropical climate stability failures in sauce applications create reverse-logistics burdens that favor domestic Brazilian suppliers with rapid reformulation response capabilities over European polyglycerol ester importers. Supply concentrates in Brazil's Midwest soybean crush corridor, with secondary phospholipid feedstock draws from Argentina and Paraguay crush operations. Raw material dependencies center on Brazilian soybean harvests, glycerol supply from biodiesel co-production, and imported polyglycerol backbone chemistries. Single-source vulnerability for specialized enzymatic processing equipment creates procurement risk for clean-label grade expansion. Distribution runs through direct processor partnerships in São Paulo and Minas Gerais, with distributor networks residual in Northeast underpenetrated zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil Food Emulsifiers Market operates as a stable compounder anchored by clean-label reformulation mandates that perpetually refresh demand for enzymatically upgraded plant-based grades across bakery and dairy applications.
For Market Incumbents: Anticipate ANVISA purity specification revisions by accelerating enzymatic processing upgrades ahead of regulatory timeline compression, while defending position through backward integration into verified domestic crush facilities that satisfy MAPA traceability mandates before foreign suppliers achieve recertification. For New Entrants and Emerging Players: Capture white space in Bahia and Pernambuco food processing clusters where local emulsifier blending capacity gaps intersect with state development incentives for distribution hub investments, leveraging technical service partnerships as the primary go-to-market angle against established Southeast suppliers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized Brazilian enzymatic processors lacking capital for phospholipase reactor scale-up but holding ANVISA certification pathways and regional customer relationships. Long-term viability frames around 5-10 year clean-label displacement curves in mass-market bakery. Monitor ANVISA publication timelines for emulsifier purity specification drafts as the critical inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Upgrade | Phospholipase reactor investments differentiate clean-label grades ahead of ANVISA purity mandates. |
| Backward Integration into Crush | Captive soybean processing secures MAPA-traceable lecithin feedstock for premium certification tiers. |
| Northeast Distribution Hub | Bahia facility placement reduces logistics cost disadvantage against import-dependent polyglycerol ester supply. |
| Technical Service Partnership | Formulation support contracts lock food service distributors amid channel compression toward direct procurement. |
| Plant-Based Dairy Analogue Development | Oat and almond milk tailored emulsifier systems open expansion beyond traditional dairy applications. |
Study Parameters
Bottom-up food manufacturer demand modeling reconciled against top-down soybean crush and emulsifier production tracking forms the analytical core of this study. Primary interviews with plant managers at Midwest and Southeast Brazilian crush facilities, procurement leads at São Paulo dairy and margarine processors, ANVISA regulatory affairs specialists, and technical R&D directors at enzymatic processing operations combined with secondary validation from customs and trade data, ABIA industry reports, MAPA inspection protocol publications, and ANVISA food additive regulatory filings. Triangulation between consumption-side volume estimates and supply-side production capacity assessments ensures consistency across segmentation dimensions.
Input-output matrices mapping soybean crush volumes through phospholipid extraction yields to end-use absorption in bakery, dairy, sauce, and beverage applications structure the forecast framework across the analysis window. Segmentation modeling incorporates product type tiers, application-specific thermal stability requirements, source-based certification pathways, and end-user channel configurations. CAGRs derive from regression analysis of historical volume trends against projected clean-label penetration curves and regulatory compliance timeline assumptions. Industry-specific forecast inputs include Brazilian soybean harvest projections and ANVISA regulatory revision probability assessments.
ANVISA timeline delays, Midwest soybean harvest volatility, and phospholipid enzymology workforce expansion rates are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding regulatory compliance thresholds and clean-label adoption velocity. Practitioners should monitor ANVISA draft publication schedules, CONAB crop estimates, and federal university biochemistry program enrollment trends for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Africa Food Emulsifiers Market
Food Additives and Ingredients
Quillaja Saponaria Ingredient Market
Food Additives and Ingredients
Global Yeast and Yeast Ingredients Market
Food Additives and Ingredients
Global Sodium Starch Glycolate Market
Food Additives and Ingredients
Food Grade Glue Market
Food Additives and Ingredients
North America Food Starch Market
Food Additives and Ingredients
Liquid Caramel Color Market
Food Additives and Ingredients
India Food Acidulants Market
Food Additives and Ingredients
Egg Stabilizer Market
Food Additives and Ingredients
Spain Food Colorants Market
Food Additives and Ingredients
Plant Based Preservatives Market
Food Additives and Ingredients
Food Coating Ingredients Market
Food Additives and Ingredients
Transglutaminase Market
Food Additives and Ingredients
Food Grade Stearic Acid Market
Food Additives and Ingredients
Neohesperidine DC Market
Food Additives and Ingredients
Africa Food Hydrocolloids Market