
 United Kingdom Food Emulsifier Market | 2026-2036
United Kingdom Food Emulsifier Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Food Emulsifier Market Analytics
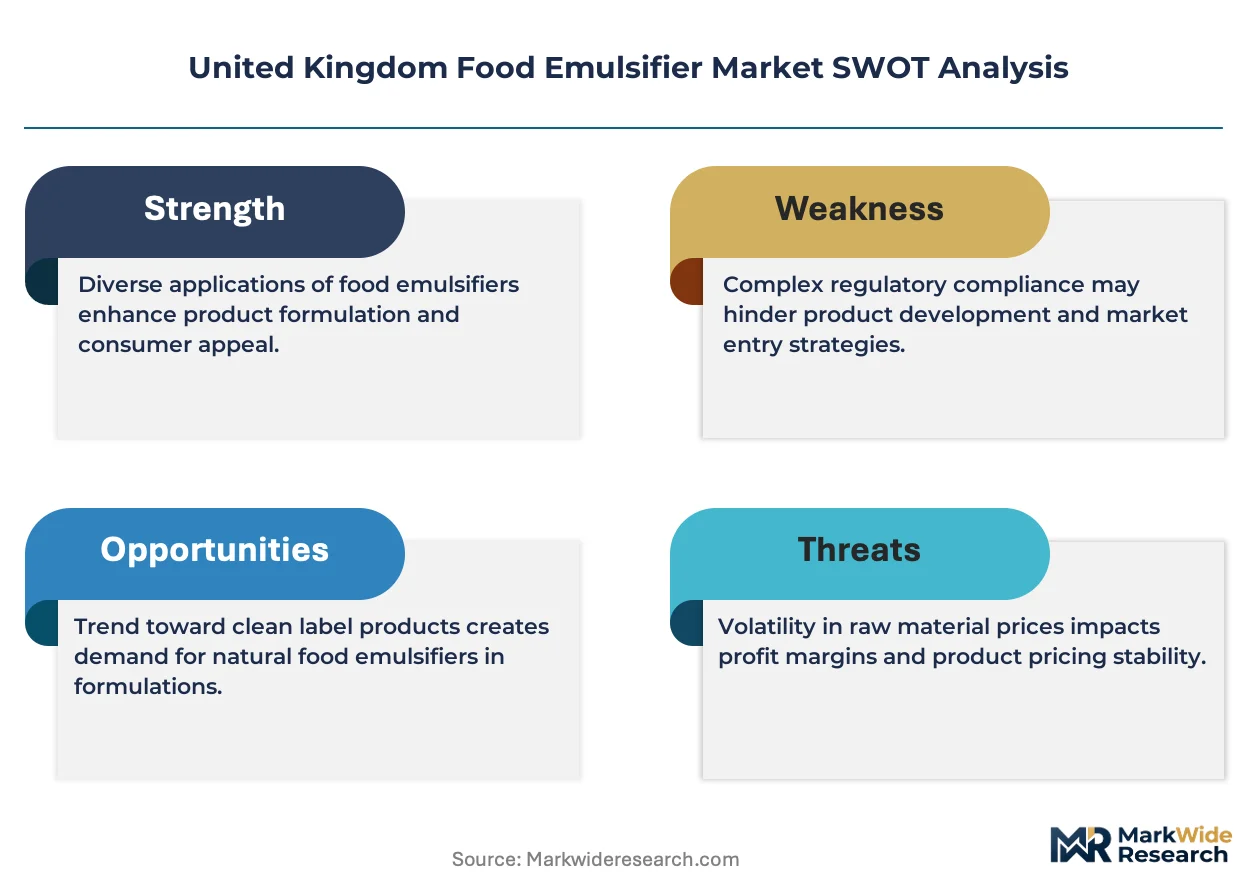
Enzymatic modification of emulsifiers is reshaping how UK food manufacturers achieve clean-label functionality without synthetic additives. Palsgaard A/S leverages its Danish R&D heritage to supply enzymatically treated monoglycerides into British bakery chains. Kerry Group Plc anchors its UK emulsifier portfolio through backward integration into dairy-derived lipid feedstocks. Corbion NV specializes in fermentation-based lecithin alternatives that navigate tightening EU-origin labelling requirements post-Brexit.
Food emulsifiers are surface-active agents containing hydrophilic and lipophilic moieties that reduce interfacial tension between immiscible phases, typically manufactured through glycerolysis of triglycerides or solvent extraction from oilseed sources, and function primarily to stabilize texture, extend shelf life, and control fat crystallization in processed foods. Lecithin dominates volume flows across UK ingredient distributors due to its broad regulatory acceptance and non-GMO positioning, while monoglycerides capture premium margin pools in industrial bakery applications demanding precise aeration control. Powder forms lead unit economics for large-scale food processors operating automated dosing systems, though liquid emulsifiers sustain growth in sauce and dressing manufacturing where pumpability reduces handling costs.
The Food Standards Agency enforces additive labelling thresholds that push reformulation toward single-ingredient emulsifiers, while retained EU REACH obligations govern chemical safety dossiers for imported emulsifier raw materials. BSI standards for food-grade emulsifier purity create compliance barriers that favour suppliers with established UK technical service teams. Stakeholders must monitor divergence between UK and EU novel food approval pathways as this determines access timelines for next-generation plant-based emulsifier technologies.
Market Dynamics
Clean-label reformulation mandates from the Food Standards Agency are compressing formulation cycles across UK bakery and prepared food manufacturing, forcing ingredient buyers to validate enzymatically modified emulsifiers against synthetic alternatives on accelerated timelines.
Growth Catalysts
- FSA Additive Reduction Guidance:The agency's push toward simplified ingredient decks drives bakery chains to specify single-ingredient emulsifiers over compound blends, expanding addressable volume for monoglyceride suppliers.
- Enzymatic Processing Advancement:Lipase-catalyzed modification of triglycerides now achieves functional parity with chemically esterified alternatives at comparable unit economics, removing the clean-label cost premium barrier.
- Greater Manchester-East Midlands Processing Corridor:Concentrated food manufacturing infrastructure in this belt generates procurement efficiencies and technical service density that accelerate new emulsifier adoption curves.
Market Restraints
- Sunflower Lecithin Supply Volatility:Black Sea sourcing disruptions for de-oiled lecithin feedstocks create input cost spikes that compress margins for distributors serving mid-tier bakery accounts.
- EU REACH Retention Complexity:Post-Brexit divergence risk in chemical safety dossier requirements forces dual-track compliance spending for emulsifier importers maintaining EU-UK parallel market access.
- Fermentation Capacity Bottleneck:Microbial lecithin alternatives face scale-up constraints at UK-based bioprocessing facilities, limiting supply elasticity for clean-label demand surges.
Strategic Opportunities
- Scottish Plant-Based Dairy Expansion:Oat and pea protein beverage manufacturing in the Central Belt creates unmet demand for lipid-compatible emulsifiers that prevent phase separation in neutral-pH formulations.
- Retained EU Novel Food Pathway Arbitrage:Faster UK approval timelines for enzymatically modified phospholipids versus pending EFSA evaluations offer first-mover positioning in cross-border ingredient trade.
- Direct-to-Manufacturer Digital Procurement:Platform-based ordering systems bypass traditional distributor markups for mid-scale food processors, enabling emulsifier suppliers to capture margin pool redistribution.
Industry Challenges
- Food Technologist Talent Scarcity:Formulation specialists capable of optimizing enzymatic emulsifier performance in reduced-fat bakery applications command premium compensation that strains R&D budgets at regional manufacturers.
- BSI Certification Timeline Compression:Accelerated purity standard verification for new enzymatic grades creates queue bottlenecks at accredited testing laboratories, delaying product launch windows.
- Legacy Dosing System Retrofit Costs:Automated powder handling infrastructure at established bakery plants requires capital expenditure to accommodate hygroscopic enzymatic emulsifier flow characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Food Emulsifier Market |
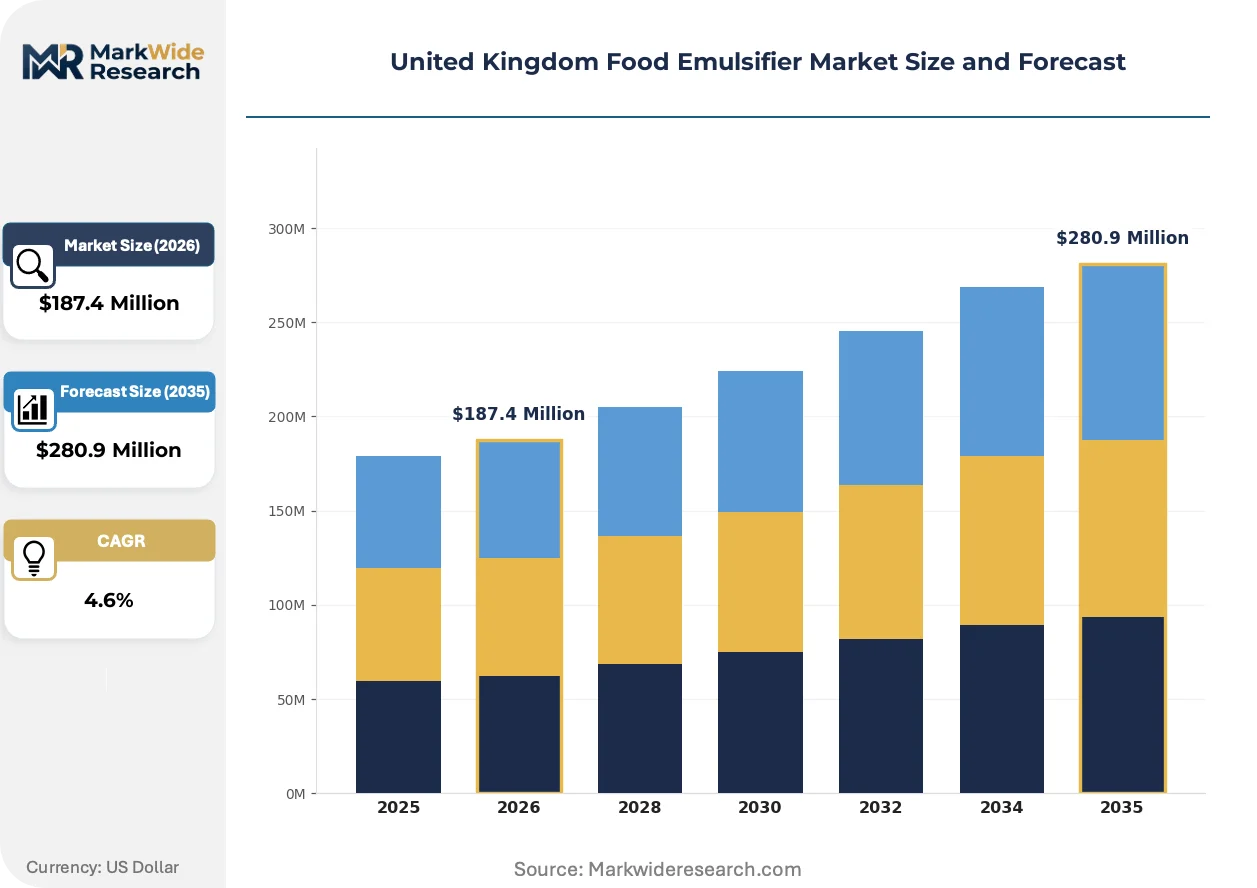
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lecithin, Monoglycerides, Diglycerides, Starches Application: Dairy Products, Bakery, Sauces, Dressings Form: Powder, Liquid, Granular, Paste End User: Food Processing, Restaurants, Canteens, Households |
| Companies Covered | Corbion NV, Archer Daniels Midland Company, DuPont de Nemours, Inc., Palsgaard A/S, Ingredion Incorporated, Cargill, Incorporated, Kerry Group Plc, Tate & Lyle, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Food Emulsifier Market Evolving Landscape
Digital formulation platforms are compressing the emulsifier selection cycle from months to weeks, enabling real-time substitution modeling that accelerates clean-label transitions without extensive bench testing.
Enzymatic interesterification is virtualizing the traditional chemical glycerolysis process for monoglyceride production. Industrial bakery manufacturers in the East Midlands are adopting these grades at triple-digit annual growth rates. This virtualization is compressing capital requirements for new production capacity while eliminating solvent residue compliance burdens.
Retained EU REACH obligations combined with emerging UK REACH divergence create a dual-dossier burden for imported emulsifier raw materials. Chemical importers now maintain parallel safety data management systems to preserve market access flexibility. Specialty lecithin grades face the highest compliance friction due to complex oilseed origin traceability requirements.
Ingredient procurement at mid-scale UK food manufacturers is consolidating toward direct supplier relationships with technical service commitments. Traditional distributor intermediaries lose share to platform-enabled direct ordering with embedded formulation support. This channel shift is most visible in the prepared sauces and dressings segment, where pumpable liquid emulsifier specifications require application-specific technical validation.
United Kingdom Food Emulsifier Market Segmentation
Segmentation reveals how emulsifier procurement priorities diverge across UK food manufacturing. Each dimension—product chemistry, application requirements, physical form, and end-user scale—creates distinct specification and service demands that reshape supplier positioning.
Product Type:
Cost tier differentiation separates commodity phospholipids from premium modified lipids in UK ingredient procurement.
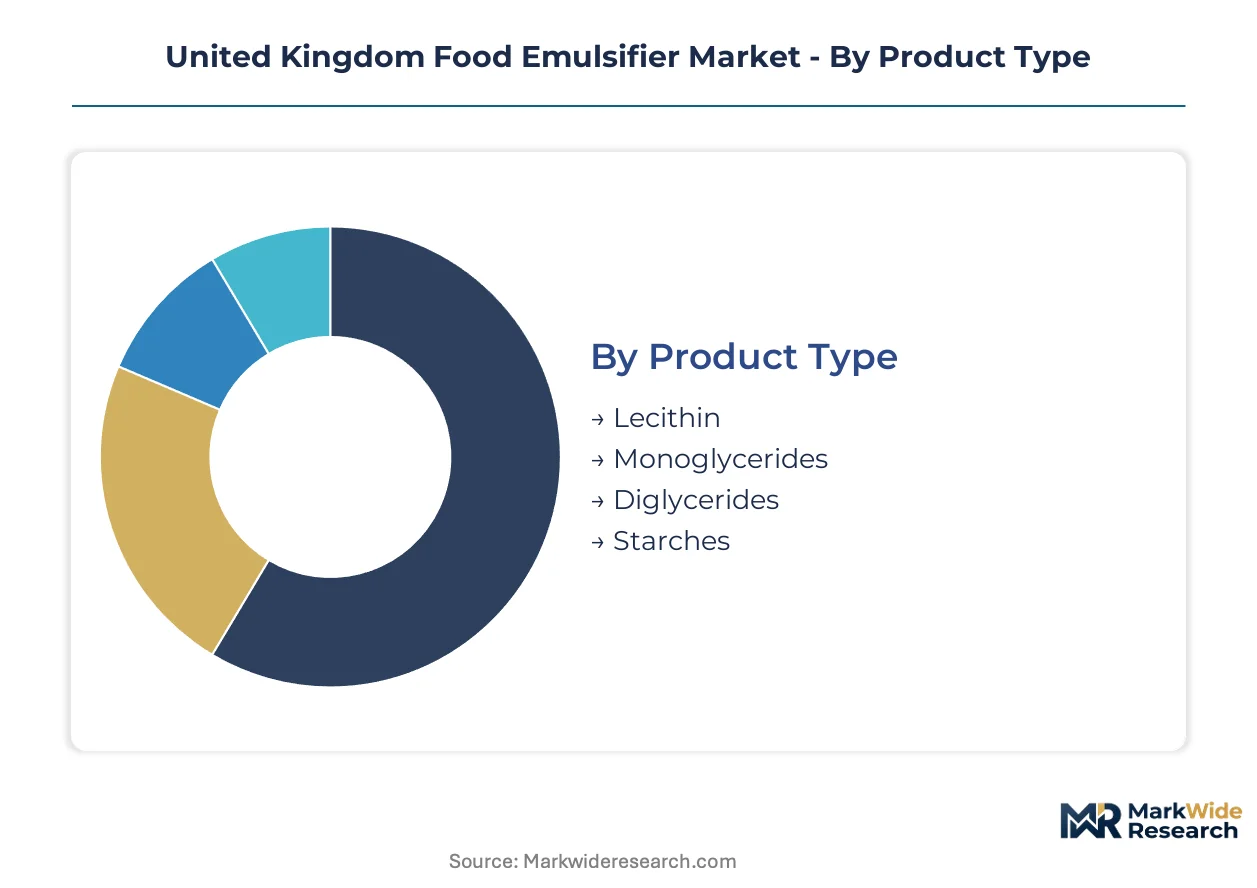
- Lecithin:Oilseed-derived phospholipid mixtures dominate volume flows through UK distributors. De-oiled grades from sunflower sources face Black Sea supply disruptions that spike input costs for mid-tier bakery accounts.
- Monoglycerides:Enzymatically modified triglycerides achieve functional parity with chemically esterified alternatives. East Midlands industrial bakeries specify these grades at triple-digit annual growth rates for precise aeration control in clean-label formulations.
- Diglycerides:Co-product streams from monoglyceride manufacturing serve cost-sensitive frying fat applications.
- Starches:Modified corn and tapioca derivatives function as secondary emulsifiers in gluten-free bakery systems.
Monoglycerides holds installed capacity. Lecithin is rotating up the share rankings.
Application:
Application-specific performance requirements dictate emulsifier selection protocols across UK food manufacturing verticals.
- Dairy Products:Lipid-compatible emulsifiers prevent phase separation in neutral-pH oat and pea protein beverages. Central Belt Scottish manufacturers drive unmet demand for plant-based dairy stabilization systems.
- Bakery:Industrial manufacturers in Greater Manchester demand enzymatic grades for reduced-fat applications where precise fat crystallization control determines texture outcomes.
- Sauces:Pumpable liquid specifications require application-specific technical validation from direct supplier relationships.
- Dressings:Cold-process emulsification needs drive interest in low-temperature dispersible powder systems.
Bakery commands formulation R&D attention. Dairy Products is climbing the fastest.
Form:
Physical state determines handling infrastructure compatibility and procurement economics for UK food processors.
- Powder:Automated dosing systems at large-scale processors favor free-flowing granular grades. Hygroscopic enzymatic variants require capital retrofit of legacy pneumatic handling infrastructure.
- Liquid:Pumpable emulsifiers reduce handling costs in sauce and dressing manufacturing where viscosity-optimized flow characteristics enable direct tanker-to-silo transfer.
- Granular:Intermediate particle sizes bridge dust control and dissolution speed requirements for mid-scale compound ingredient blenders.
- Paste:High-viscosity concentrates serve artisan bakery and small-batch sauce producers lacking automated dispersion equipment.
Powder retains installed base dominance. Liquid is expanding most quickly in prepared foods.
End User:
Customer scale and technical capability create diverging service and packaging requirements across the UK emulsifier demand base.
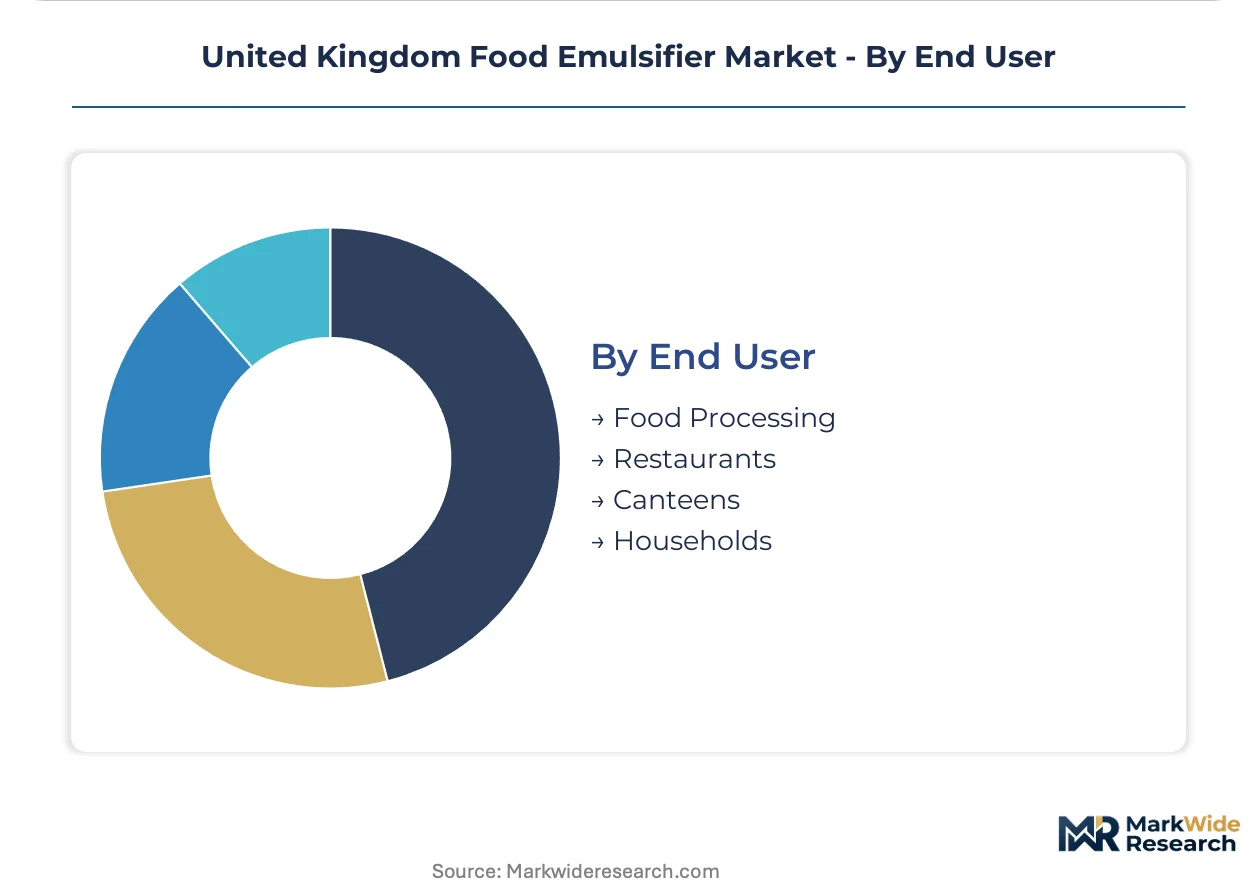
- Food Processing:Automated manufacturing lines in the Greater Manchester-East Midlands corridor specify bulk tonnage with embedded formulation support and BSI-certified purity documentation.
- Restaurants:Central kitchen chains and contract caterers procure pre-dispersed liquid concentrates for sauce finishing stations.
- Canteens:Institutional feeding operations prioritize cost-optimized compound blends with extended ambient stability.
- Households:Retail-packaged lecithin granules serve home baking enthusiasts through specialty ingredient channels.
Food Processing anchors volume commitments. Restaurants is gaining share fastest in liquid emulsifier procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient buyers cluster in England's food processing corridor, with procurement patterns diverging sharply between industrial-scale manufacturers and artisan producers across UK sub-regions.
Greater London and Southeast England
Specialty food manufacturers and premium bakery chains drive demand for clean-label emulsifiers with organic certification. The Food Standards Agency maintains its headquarters here, shaping national additive guidance that ripples through formulation decisions nationwide. Reading and Slough host technical service centers where suppliers validate enzymatic grades against legacy synthetic alternatives.
East Midlands
Industrial bakery operations specify enzymatically modified monoglycerides at accelerating rates for reduced-fat applications. BSI certification laboratories in Leicester create compliance bottlenecks for new emulsifier grades awaiting purity verification. Corby and Kettering anchor a dense cluster of automated manufacturing lines demanding bulk powder emulsifiers with embedded formulation support.
Greater Manchester and North West England
Prepared sauce and dressing manufacturers favor pumpable liquid emulsifiers that reduce handling costs through direct tanker-to-silo transfer. Retained EU REACH obligations force dual-track compliance spending among chemical importers maintaining EU-UK parallel market access. Warrington and Oldham concentrate procurement teams for mid-scale food processors consolidating toward direct supplier relationships.
Scotland
Oat and pea protein beverage manufacturing in the Central Belt generates unmet demand for lipid-compatible emulsifiers that prevent phase separation in neutral-pH formulations. Scottish Food Standards enforcement creates marginal regulatory divergence from England on novel ingredient approvals. Glasgow and Edinburgh anchor plant-based dairy expansion where fermentation-based lecithin alternatives face supply elasticity constraints.
Wales and Northern Ireland
Smaller-scale compound ingredient blenders prioritize cost-optimized emulsifier blends with extended ambient stability for institutional feeding contracts. UK REACH divergence risk complicates chemical safety dossier management for cross-border suppliers serving these markets. Cardiff and Belfast lack the technical service density of England's processing corridor, extending validation timelines for new enzymatic grades.
United Kingdom Food Emulsifier Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that favors established suppliers with backward integration into lipid feedstocks and fermentation capacity. The vendor base spans multinational ingredient conglomerates and regional enzymatic processing specialists. Two strategic archetypes dominate: integrated nutrition platforms leveraging captive dairy lipid supplies, and emulsifier-pure-play firms with Danish or Dutch R&D heritage. Competitive moves concentrate on enzymatic processing advancement and direct-to-manufacturer digital procurement platforms that bypass traditional distributor markups.
Among the integrated nutrition platforms, Kerry Group Plc exemplifies the archetype leveraging in-house production of dairy-derived lipid feedstocks to anchor UK emulsifier supply security. Palsgaard A/S and Corbion NV occupy positions within the specialist tier, with the former representing Danish enzymatic modification heritage and the latter exemplifying fermentation-based alternatives to oilseed-derived phospholipids. These three firms illustrate how geographic R&D concentration—Irish dairy integration, Danish enzymatic expertise, and Dutch bioprocessing—shapes competitive positioning in clean-label emulsifier supply.
| Leading Market Players |
|---|
| Corbion NV |
| Archer Daniels Midland Company |
| DuPont de Nemours, Inc. |
| Palsgaard A/S |
| Ingredion Incorporated |
| Cargill, Incorporated |
| Kerry Group Plc |
| Tate & Lyle |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Black Sea sunflower lecithin concentration hands pricing power to upstream oilseed processors, while downstream margin pools accrue to enzymatic monoglyceride suppliers serving East Midlands industrial bakeries with clean-label specifications.
Pricing Analysis
Cost-plus contracts indexed to Rotterdam vegetable oil futures dominate lecithin procurement, with de-oiled grades carrying organic certification premiums. Three-tier pricing structure across enzymatic premium, standard chemical, and economy co-product grades separates formulation support levels. Pricing pressure stems from Black Sea supply disruptions compressing mid-tier bakery margins. Compound ingredient blenders exhibit highest price sensitivity; automated food processors with captive formulation teams show lowest.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities anchor working capital arrangements for UK distributors managing Black Sea, Argentine, and Dutch oilseed sourcing. Raw material flows draw from sunflower phospholipids, palm-derived triglycerides, and fermentation-based microbial lipids. Single-source vulnerability concentrates in Ukrainian de-oiled lecithin grades. Distribution runs through technical service-embedded direct supplier relationships displacing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic processing advancement constitutes a high-growth disruption, with FSA additive reduction guidance compressing formulation cycles and accelerating clean-label substitution timelines.
For Market Incumbents: Build captive enzymatic modification capacity to deepen moats against Danish and Dutch specialist entrants. Kerry Group Plc's backward integration into dairy lipid feedstocks exemplifies supply security leverage. Secure BSI certification queue priority at Leicester testing laboratories to compress new grade launch windows. Channel control through embedded formulation teams defends margin pools against platform-based procurement disintermediation. For New Entrants and Emerging Players: Scottish Central Belt oat and pea protein beverage manufacturing represents the most penetrable entry point, with unmet demand for neutral-pH lipid-compatible emulsifiers. Fermentation-based lecithin alternatives face supply elasticity constraints that create white-space for bioprocessing scale-up specialists. Direct-to-manufacturer digital procurement platforms with technical validation modules offer the strongest go-to-market angle for mid-scale processor access. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across enzymatic processing virtualization, compressing barrier-to-entry for bioprocessing technology acquisitions. Five-to-ten year viability favors fermentation capacity specialists with UK-based bioprocessing assets over oilseed-dependent legacy distributors. Monitor UK-EU novel food approval pathway divergence as the critical signal for cross-border ingredient trade arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Capacity Expansion | Virtualized glycerolysis eliminates solvent residue compliance burdens for East Midlands bakery suppliers. |
| Backward Integration into Dairy Lipid Feedstocks | Kerry Group Plc's captive supply secures UK emulsifier raw material independence from Black Sea volatility. |
| Fermentation-Based Lecithin Scale-Up | Corbion NV's bioprocessing addresses EU-origin labelling constraints tightening post-Brexit. |
| Direct-to-Manufacturer Digital Procurement Platform | Technical service-embedded ordering captures margin pool redistribution from traditional distributors. |
| BSI Certification Fast-Track Investment | Accelerated purity verification at Leicester laboratories compresses enzymatic grade launch timelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with bakery formulation technologists, ingredient procurement managers at prepared food manufacturers, enzymatic processing R&D directors, and distributor category buyers. Secondary validation drew from FSA additive guidance publications, BSI food-grade purity standards, retained EU REACH dossier filings, and UK trade customs data. Bottom-up volume modeling across product chemistry, application vertical, physical form, and end-user scale segments triangulated against top-down macroeconomic demand indicators.
Calibration against historical price index movements and capacity utilization rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass lecithin-monoglyceride-diglyceride chemistry tiers, bakery-dairy-sauce-dressing application verticals, powder-liquid-granular physical states, and food processing-restaurant-canteen-household end-user scales. CAGRs derived from slope-intercept trend analysis of clean-label adoption curves and enzymatic grade penetration rates. Industry-specific forecast inputs included FSA reformulation mandate compliance timelines and Black Sea supply disruption probability scenarios.
Macroeconomic conditions sit as an overlay; deviation in vegetable oil commodity prices, sterling-euro exchange rates, or UK-EU regulatory divergence timelines would shift the trajectory. Forecasts embed assumptions regarding enzymatic processing cost parity achievement and BSI certification throughput capacity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Australia Food Acidulants Market
Food Additives and Ingredients
North America Food Coating Ingredients Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Excipients Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
France Food Emulsifiers Market
Food Additives and Ingredients
Flour Whiteners Market
Food Additives and Ingredients
Asia-Pacific Food Additives Market
Food Additives and Ingredients
North America Anti-Caking Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Lime Oil Market
Food Additives and Ingredients
Food Grade Sodium Citrate Market
Food Additives and Ingredients
Russia Food Preservatives Market
Food Additives and Ingredients
Isodecanol Market
Food Additives and Ingredients
Fatty Esters Market