
 Technical Aerosol Market | 2026-2036
Technical Aerosol Market Size, Share, and Industry Trends Forecast 2026-2036
Technical Aerosol Market Analytics
Recurring aerosol formulation services and technical support subscriptions is consolidating around specialized industrial distributors. 3M leverages its fluoropolymer chemistry expertise to anchor premium coating aerosol lines across aerospace maintenance networks. Henkel competes through adhesives aerosol systems that sustain factory-floor bonding workflows in automotive assembly plants.
Technical aerosols are pressurized dispersions of active ingredients—resins, solvents, lubricants, or cleaning compounds—delivered through hydrocarbon, dimethyl ether, or compressed gas propellants, typically packaged in aluminum or tinplate cans with precision actuators enabling targeted spray patterns. Their primary purpose spans protective coatings, precision cleaning, adhesive activation, and corrosion inhibition across manufacturing and maintenance operations. Propellant-based formulations still dominate volume in heavy-industrial applications where spray force and drying speed matter, while water-based systems are gaining fastest in household and regulated indoor environments where volatile organic compound limits tighten. The coatings application segment captures the deepest margin pools, especially in automotive touch-up and aerospace MRO channels where specification-grade performance commands premium positioning.
EPA regulations under the Clean Air Act constrain solvent content in consumer and industrial aerosols, while REACH and the EU F-Gas Regulation in Europe restrict fluorinated propellants and mandate chemical registration for imported formulations. These frameworks force reformulation investments and create compliance moats for manufacturers with in-house toxicology and regulatory affairs capabilities. Stakeholders must monitor propellant transition timelines and regional divergence in chemical approval pathways to avoid supply disruptions or market access losses.
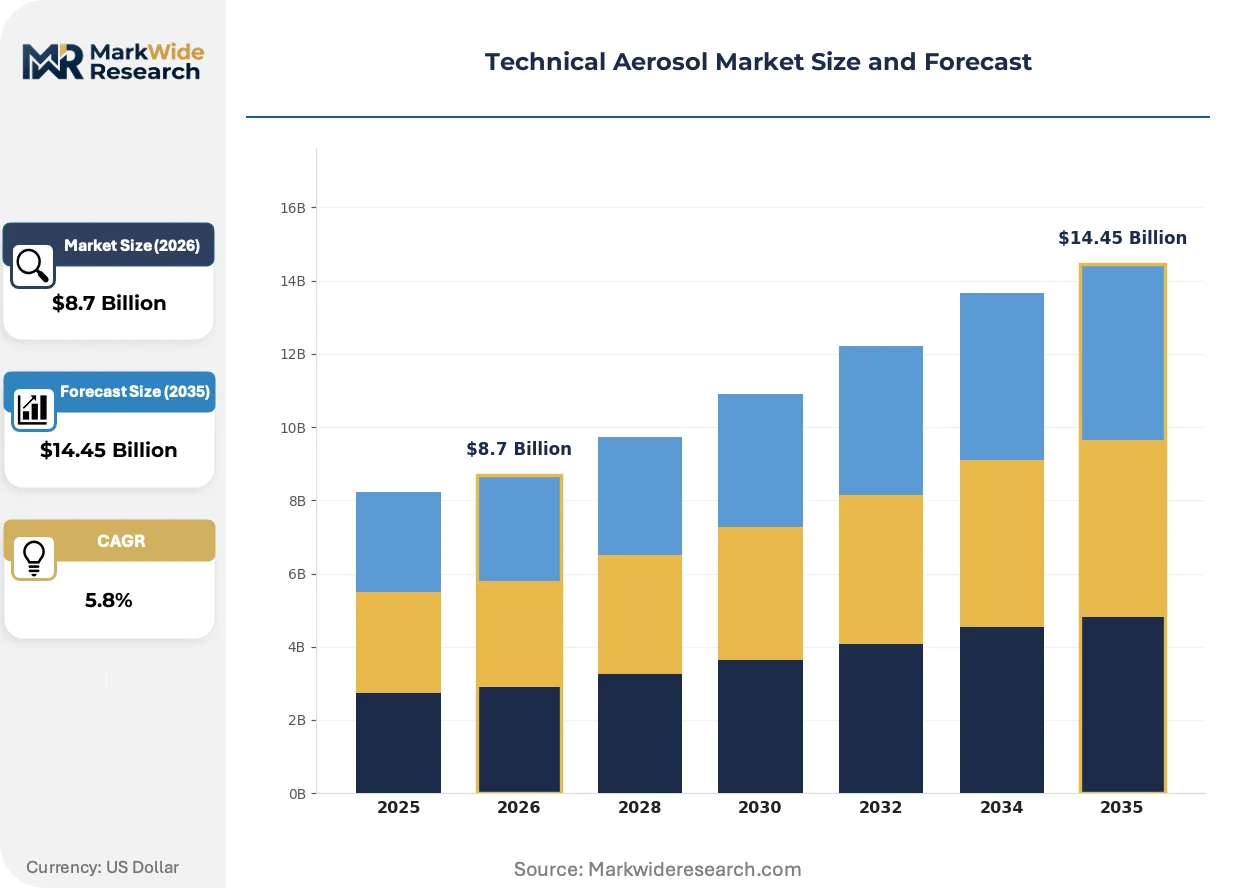
Market Dynamics
Propellant chemistry transitions and tightening volatile organic compound limits are compressing formulation margins while forcing capital redeployment toward water-based and compressed gas alternatives across industrial coating applications.
Growth Catalysts
- REACH compliance deadlines:European manufacturers accelerating reformulation investments ahead of registration cutoffs, creating specification-grade demand for compliant solvent systems in Germany's automotive refinishing corridors.
- Aerospace MRO expansion:Fleet utilization rates driving touch-up coating consumption through precision aerosol formats in maintenance hangars clustered around Hamburg and Toulouse.
- Fluoropolymer performance tier:High-temperature corrosion resistance specifications in turbine maintenance applications pulling premium formulation volumes.
Market Restraints
- Aluminum can supply concentration:Three European suppliers controlling two-thirds of lithographed aerosol packaging capacity, creating input bottlenecks during seasonal demand spikes.
- Dimethyl ether price volatility:Petrochemical feedstock exposure transmitting crude oil fluctuations directly into propellant cost structures.
- Technical limitation of water-based drying:Extended cure times excluding aqueous formulations from high-throughput automotive assembly line applications where solvent speed remains mandatory.
Strategic Opportunities
- Underpenetrated Indian industrial maintenance:PLI scheme incentives for domestic manufacturing creating localized formulation demand in Gujarat and Maharashtra chemical corridors.
- Emerging cold-chain logistics coating:Insulative spray foam aerosols addressing refrigerated transport fleet expansion in Southeast Asian food distribution networks.
- EU F-Gas Regulation phase-down:Compressed nitrogen and air propellant systems capturing displaced hydrofluorocarbon volumes in household and professional cleaning segments.
Industry Challenges
- Toxicology assessment capacity scarcity:REACH dossier preparation timelines extending 18-24 months, delaying market access for reformulated products.
- Legacy filling line retrofit costs:Water-based system conversion requiring stainless steel infrastructure replacement incompatible with existing tinplate handling equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Technical Aerosol Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Propellant-Based, Solvent-Based, Water-Based, Compressed Gas Application: Coatings, Adhesives, Cleaning Agents, Personal Care End User: Automotive, Aerospace, Household, Industrial Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | 3M, Illinois Tool Works, DuPont, Henkel, SC Johnson, CRC Industries, European Aerosols, WD-40 Company, Pidilite Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Technical Aerosol Market Evolving Landscape
Reformulation priorities are pivoting around propellant substitution timelines, with manufacturers racing to lock in compressed gas and aqueous platforms before regulatory deadlines eliminate solvent-based options from key industrial segments.
Compressed nitrogen propellant systems are overtaking hydrocarbon alternatives in precision coating applications where flammability constraints and volatile organic compound limits intersect. Automotive OEM touch-up operations in Stuttgart and Munich are adopting these platforms at accelerating rates. The technology is overtaking solvent-based formats in specification-driven channels where insurance and facility safety protocols now mandate non-flammable storage.
EPA volatile organic compound rules under the Clean Air Act are constraining solvent content thresholds in consumer and industrial aerosol categories simultaneously. Manufacturers face dual-track compliance investments for US and European formulations with divergent chemical approval pathways. Coatings serving the automotive refinishing segment absorb the heaviest compliance burden, with German suppliers maintaining parallel formulation portfolios to serve transatlantic customers.
Specification-driven procurement now dominates aerospace and automotive MRO channels, with buyers unbundling after-sales technical support from product supply contracts. Industrial distributors in France and the United Kingdom are capturing this service layer through subscription-based formulation consulting. Germany's Ruhr industrial cluster exhibits the most pronounced shift, with maintenance workshops consolidating vendor relationships around distributors offering REACH documentation packages and application training.
Technical Aerosol Market Segmentation
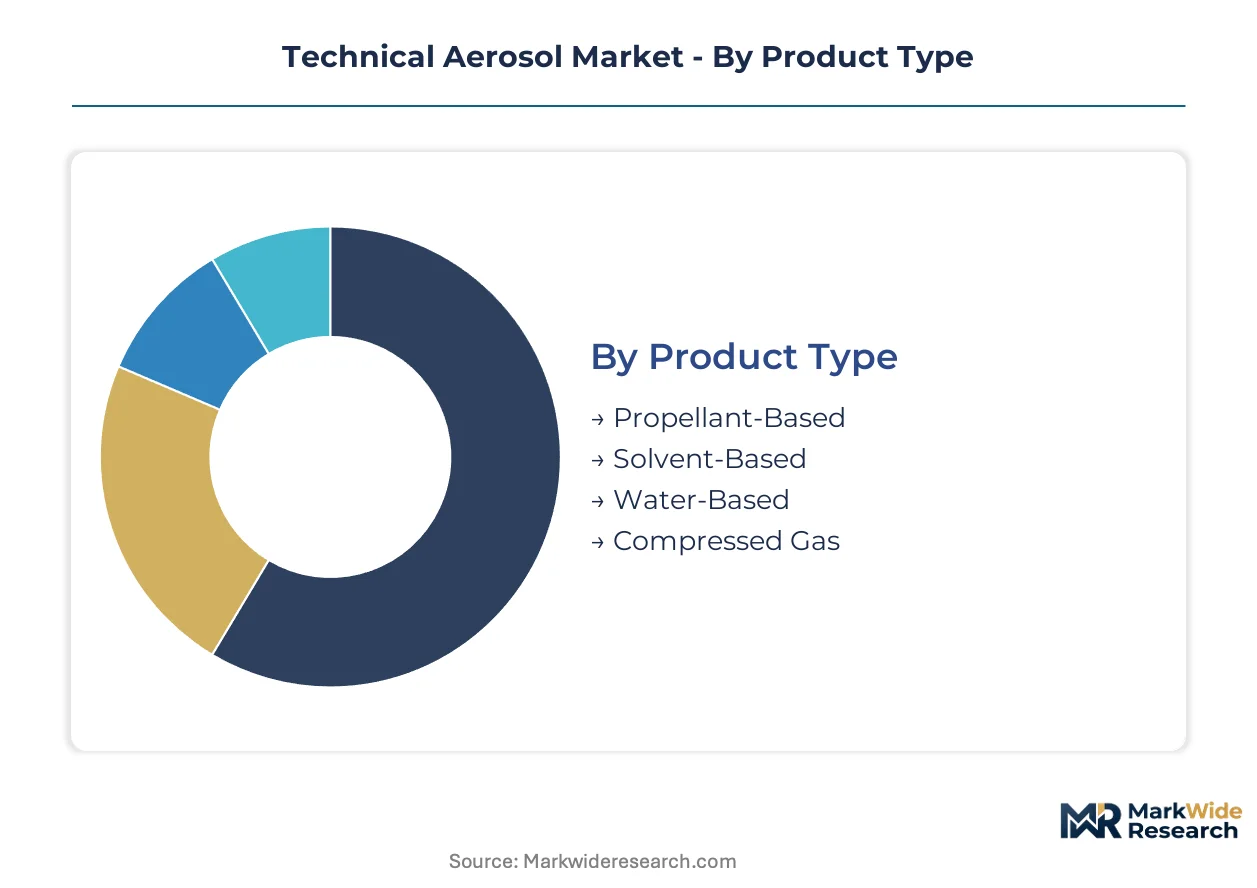
Technical aerosol segmentation reveals how formulation chemistry, application intensity, and procurement channel determine margin capture. Buyers sort across these dimensions based on regulatory exposure, performance specifications, and volume scale.
Product Type:
Customization intensity spans from commodity compressed gas platforms to highly engineered solvent systems requiring precise propellant-propellant compatibility testing.
- Propellant-Based:Hydrocarbon and dimethyl ether systems deliver high spray force and rapid drying through aluminum can delivery. Demand clusters in German automotive refinishing corridors where throughput speed outweighs volatile organic compound exposure.
- Solvent-Based:Resin-dissolved active ingredients in hydrocarbon carriers dominate aerospace MRO touch-up applications. REACH compliance deadlines are forcing reformulation investments among European suppliers serving Hamburg and Toulouse maintenance clusters.
- Water-Based:Aqueous dispersions with compressed air propulsion address indoor regulated environments. Extended cure times limit penetration in high-throughput automotive assembly.
- Compressed Gas:Nitrogen and air systems eliminate flammability constraints in precision coating operations. Stuttgart OEM touch-up facilities are adopting these platforms fastest.
Most installed capacity flows through Propellant-Based formulations. Expansion is steepest in Compressed Gas systems.
Application:
Margin structure inverts across this category, with specification-grade channels commanding premium positioning over commodity maintenance applications.
- Coatings:Protective and decorative films for substrate preservation, ranging from automotive touch-up to turbine corrosion inhibition. Aerospace MRO channels in France and Germany absorb the deepest margin pools.
- Adhesives:Bonding activation systems for factory-floor assembly workflows. Henkel anchors this segment through automotive plant supply contracts.
- Cleaning Agents:Degreasing and precision removal formulations for maintenance operations. Water-based alternatives gain share in regulated indoor environments.
- Personal Care:Cosmetic and hygiene dispersions with mild propellant systems. EPA volatile organic compound rules constrain solvent content thresholds.
Coatings generate the highest revenue per liter. Cleaning Agents are gaining share fastest in regulated geographies.
End User:
Procurement sophistication separates industrial buyers with formulation consulting requirements from household consumers prioritizing shelf availability.
- Automotive:OEM assembly plants and aftermarket refinishing shops drive specification-grade demand. Germany's Ruhr cluster concentrates vendor relationships around distributors offering REACH documentation.
- Aerospace:Fleet utilization rates pull precision aerosol consumption through MRO networks. 3M fluoropolymer lines anchor turbine maintenance specifications.
- Household:Consumer cleaning and personal care applications with retail distribution. EU F-Gas Regulation phase-down is displacing hydrofluorocarbon propellants.
- Industrial:Manufacturing maintenance and corrosion inhibition across chemical and metalworking facilities. India's PLI scheme is creating localized formulation demand in Gujarat.
Automotive channels represent the largest volume aggregation. Aerospace exhibits the steepest expansion trajectory.
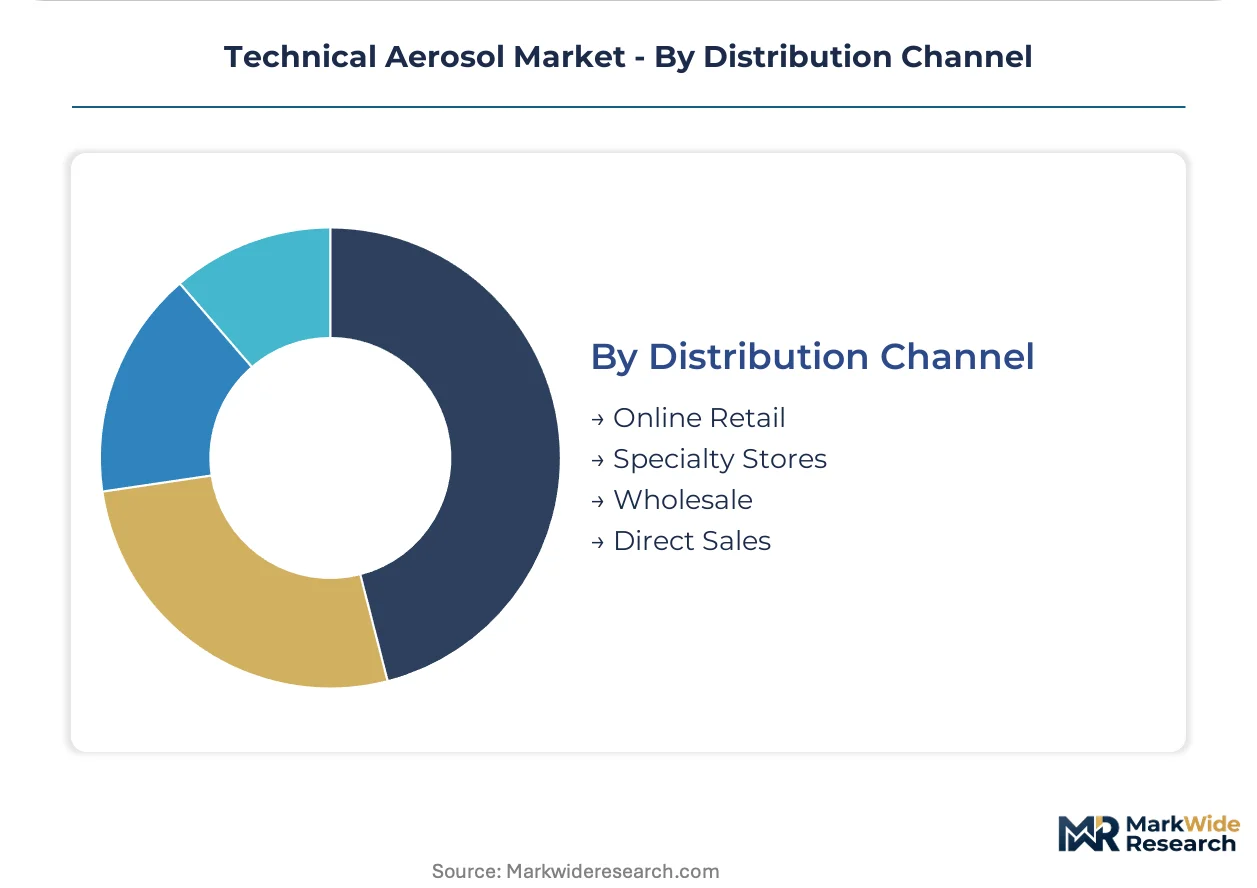
Distribution Channel:
Channel selection determines service bundling intensity, from unadorned product supply to integrated formulation consulting and application training.
- Online Retail:E-commerce platforms serving household and small professional buyers with standardized SKUs. Logistics networks limit aerosol shipping through carrier restrictions.
- Specialty Stores:Industrial distributors capturing service layers through subscription-based technical support. UK and French distributors lead this consolidation.
- Wholesale:Volume aggregation for automotive refinishing chains and maintenance contractors. Seasonal demand spikes expose aluminum can supply bottlenecks.
- Direct Sales:Manufacturer-to-OEM relationships for specification-grade coatings with embedded technical service. German automotive OEMs prefer this channel for touch-up systems.
Wholesale channels move the highest absolute volumes. Specialty Stores are climbing the fastest as service bundling consolidates procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the deepest specification-grade demand pools, while the United States drives the heaviest compliance-driven reformulation investments across transatlantic supply chains.
Germany
Automotive OEM refinishing corridors in Stuttgart and Munich absorb premium coating aerosol volumes. REACH dossier preparation timelines extend 18-24 months, compressing market access for new entrants. The Ruhr industrial cluster concentrates maintenance workshop procurement around distributors bundling technical support with REACH documentation packages.
United States
EPA volatile organic compound rules under the Clean Air Act constrain solvent content thresholds in consumer and industrial categories simultaneously. Automotive refinishing shops expand solvent-based technical aerosol use for precision coating applications despite tightening formulation standards. The Great Lakes manufacturing belt anchors heavy-industrial aerosol consumption where spray force and drying speed outweigh regulatory exposure.
France
Aerospace MRO networks around Toulouse pull precision aerosol consumption through maintenance hangars serving fleet utilization expansion. ECHA registration requirements force parallel formulation portfolios for transatlantic customers. Industrial distributors in Paris and Lyon capture service layers through subscription-based formulation consulting and application training.
India
PLI scheme incentives for domestic manufacturing create localized formulation demand in Gujarat and Maharashtra chemical corridors. BIS standards compliance requirements shape import substitution strategies among multinational suppliers. The Delhi-NCR industrial belt exhibits fastest uptake in compressed gas propellant systems for regulated indoor environments.
United Kingdom
Specialty industrial distributors consolidate recurring aerosol formulation services and technical support subscriptions. Post-Brexit regulatory divergence from REACH creates dual-track compliance investments for suppliers serving EU and UK markets. The Midlands manufacturing corridor anchors corrosion inhibition aerosol demand across metalworking and chemical processing facilities.
Technical Aerosol Market Competitive Landscape
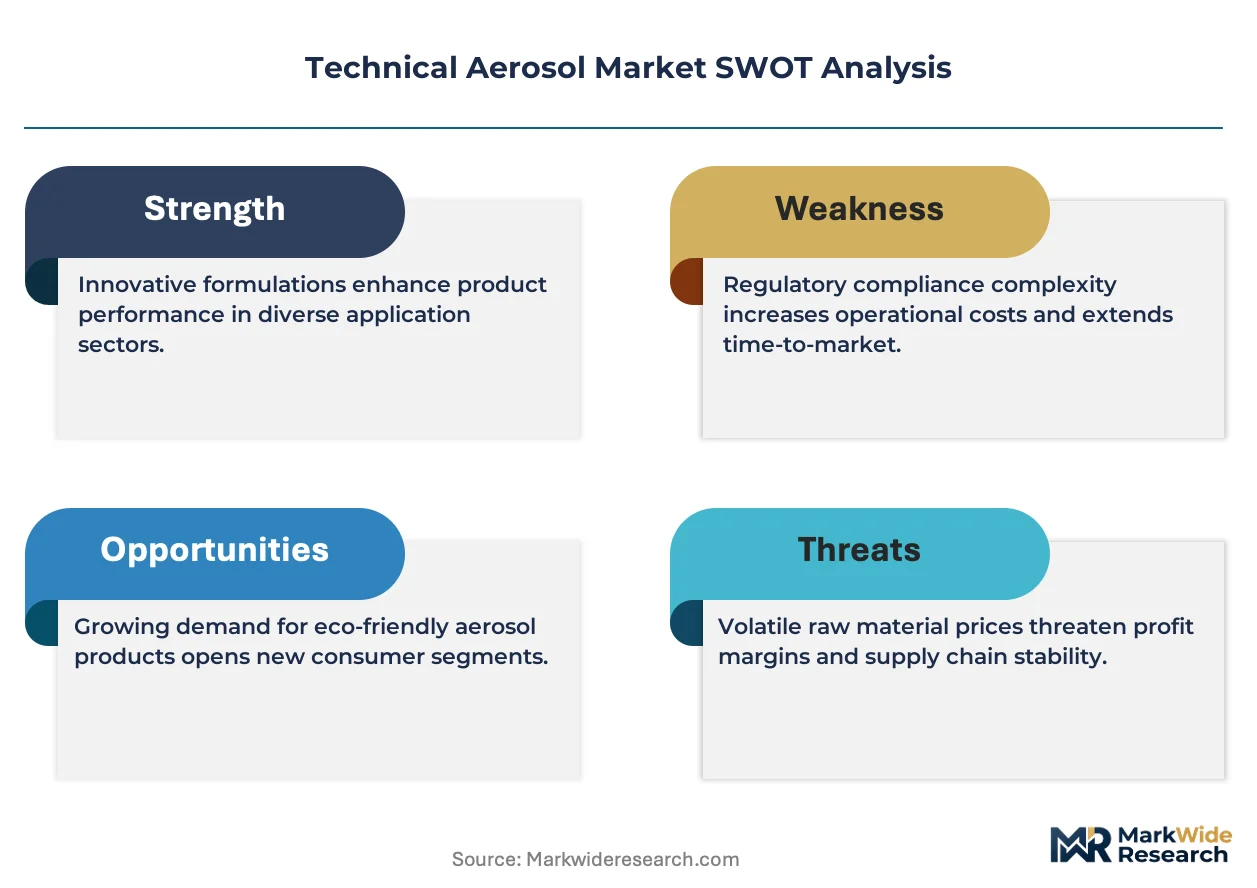
Top-tier vendors anchor specification-grade aerospace and automotive channels, while mid-tier formulators compete on reformulation agility and regional compliance speed. The vendor base stratifies across fluoropolymer chemistry specialists, adhesives systems integrators, and diversified industrial maintenance suppliers. Two strategic archetypes dominate: chemistry-anchored premium coating developers and distributor-integrated service bundlers. Competitive moves concentrate on M&A for toxicology assessment capabilities and capacity expansion into water-based filling infrastructure.
Within the chemistry-specialist tier, 3M and DuPont exemplify fluoropolymer expertise anchoring premium coating lines across aerospace maintenance networks. Henkel occupies a position within the adhesives systems archetype, representing factory-floor bonding workflow integration in automotive assembly plants. WD-40 Company and CRC Industries sit within the industrial maintenance mainstream, exemplifying brand-recognized penetrants and precision cleaning formulations distributed through wholesale and specialty retail channels.
| Leading Market Players |
|---|
| 3M |
| Illinois Tool Works |
| DuPont |
| Henkel |
| SC Johnson |
| CRC Industries |
| European Aerosols |
| WD-40 Company |
| Pidilite Industries |
| Others |
Value Network & Pricing Analysis
Aluminum ingot price indices on the London Metal Exchange cascade through aerosol packaging costs, compressing margins for mid-tier formulators while concentrating pricing power among European can manufacturers with long-term smelter contracts. This raw-material pass-through mechanism stratifies the market into specification-grade premium tiers anchored by fluoropolymer chemistry and commodity solvent-based lines exposed to petrochemical volatility.
Pricing Analysis
Capacity additions in Germany's water-based filling infrastructure are reshaping price floors for compliant formulations as REACH deadlines force legacy line retirements. Three-tier pricing structure across premium fluoropolymer, specification-grade solvent, and economy hydrocarbon levels separates aerospace MRO buyers from automotive refinishing shops and industrial maintenance contractors. Cost compression in commodity solvent tiers is intensifying because dimethyl ether feedstock costs track crude oil benchmarks. Automotive assembly plants exhibit the lowest price sensitivity due to specification lock-in, while independent refinishing shops in wholesale channels absorb the highest margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with German and Austrian aluminum can lithography suppliers controlling two-thirds of European aerosol packaging capacity. Raw material flows draw from Saudi petrochemical complexes for hydrocarbon propellants, Belgian chemical corridors for dimethyl ether, and domestic compressed gas facilities for nitrogen propulsion systems. Supply chain risk centers on seasonal demand spikes exposing aluminum can bottlenecks during automotive refinishing peak periods. Distribution runs through industrial distributors in France and the United Kingdom bundling technical support subscriptions with product supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Technical Aerosol Market functions as a stable compounder underpinned by mandatory reformulation cycles that regenerate demand for compliant formulations across regulatory jurisdictions. This structural replacement dynamic insulates volume trajectories from cyclical industrial downturns.
For Market Incumbents: Anticipate compressed gas propellant transitions by securing stainless steel filling line capacity ahead of EU F-Gas Regulation phase-down deadlines. Defensive consolidation should prioritize toxicology assessment capabilities to compress REACH dossier preparation timelines. Backward integration into aluminum can sourcing through long-term offtake agreements with German and Austrian suppliers mitigates seasonal packaging bottlenecks.
For New Entrants and Emerging Players: Mid-sized automotive refinishing shops in India's Gujarat chemical corridor represent an underserved buyer archetype seeking localized REACH-compliant formulations without distributor markups. Cold-chain logistics coating applications across Southeast Asian food distribution networks offer white-space penetration with lower incumbent saturation. A direct technical service model bypassing wholesale channels captures margin pools currently allocated to French and UK distributors.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap formulators possessing water-based platform expertise and established ECHA registration portfolios. Long-term viability across the analysis window favors suppliers with dual US-European compliance capabilities serving transatlantic automotive OEMs. The signal to monitor is accelerated adoption of compressed nitrogen systems in Stuttgart and Munich touch-up facilities, indicating inflection toward non-flammable storage mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Can Supply | Long-term offtake agreements with German lithographers eliminate seasonal packaging bottlenecks for high-volume formulators. |
| Water-Based Filling Capacity Expansion | Stainless steel infrastructure investments capture reformulation demand as REACH deadlines eliminate solvent-based options. |
| Toxicology Assessment Capability Acquisition | In-house REACH dossier preparation compresses 18-24 month market access timelines for new product launches. |
| Compressed Gas Propellant Platform Development | Nitrogen and air systems capture displaced hydrofluorocarbon volumes under EU F-Gas Regulation phase-down schedules. |
| Direct Technical Service Model Deployment | Manufacturer-to-workshop relationships in Germany's Ruhr cluster bypass distributor markups and capture subscription revenue. |
Research Methodology
Multiple input streams — primary interviews with plant managers at automotive refinishing facilities, procurement leads at aerospace MRO networks, distribution channel partners in France and the United Kingdom, and technical R&D directors at formulation houses — were reconciled against secondary validation from ECHA registration databases, EPA Clean Air Act filing records, customs trade data, and SEC 10-K disclosures from listed aerosol manufacturers. Bottom-up volume builds across product type, application, and end-user segments were cross-checked against top-down market sizing derived from aluminum can production statistics and propellant consumption reports.
Historical volume trajectories were cross-referenced against expert panel inputs from industry stakeholders to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include propellant chemistry tier, application intensity grade, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from slope analysis of segment-level demand curves calibrated to REACH compliance timelines and aerospace fleet utilization projections. Forecast inputs incorporated propellant substitution timelines, aluminum can capacity utilization rates, and toxicology assessment bottlenecks.
Underlying measurement precision varies by segment; coatings and aerospace MRO channels carry tighter precision than household cleaning applications due to specification-grade documentation requirements. Forecasts reflect assumptions around regulatory deadline adherence, feedstock cost pass-through mechanisms, and distributor consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Textile Flame Retardants Market
Specialty Chemicals
Xanthene Derivatives Market
Specialty Chemicals
Specialty Biocides Market
Specialty Chemicals
Brominated Flame Retardants Market
Specialty Chemicals
Propyl Isovalerate Market
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
Sizing and Thickening Market
Specialty Chemicals
Taurine Market
Specialty Chemicals
Pyrrolidone Market
Specialty Chemicals
North America Sugarcane Wax Market
Specialty Chemicals
Petroleum Jelly Market
Specialty Chemicals
Alkoxide Market
Specialty Chemicals
Global Immersion Oil Market
Specialty Chemicals
Zinc Eugenol Market
Specialty Chemicals
Global Lactobionic Acid Market
Specialty Chemicals
Phosphonate Market