
 Inland Water Passenger Transport Market | 2026-2036
Inland Water Passenger Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Inland Water Passenger Transport Market Analytics
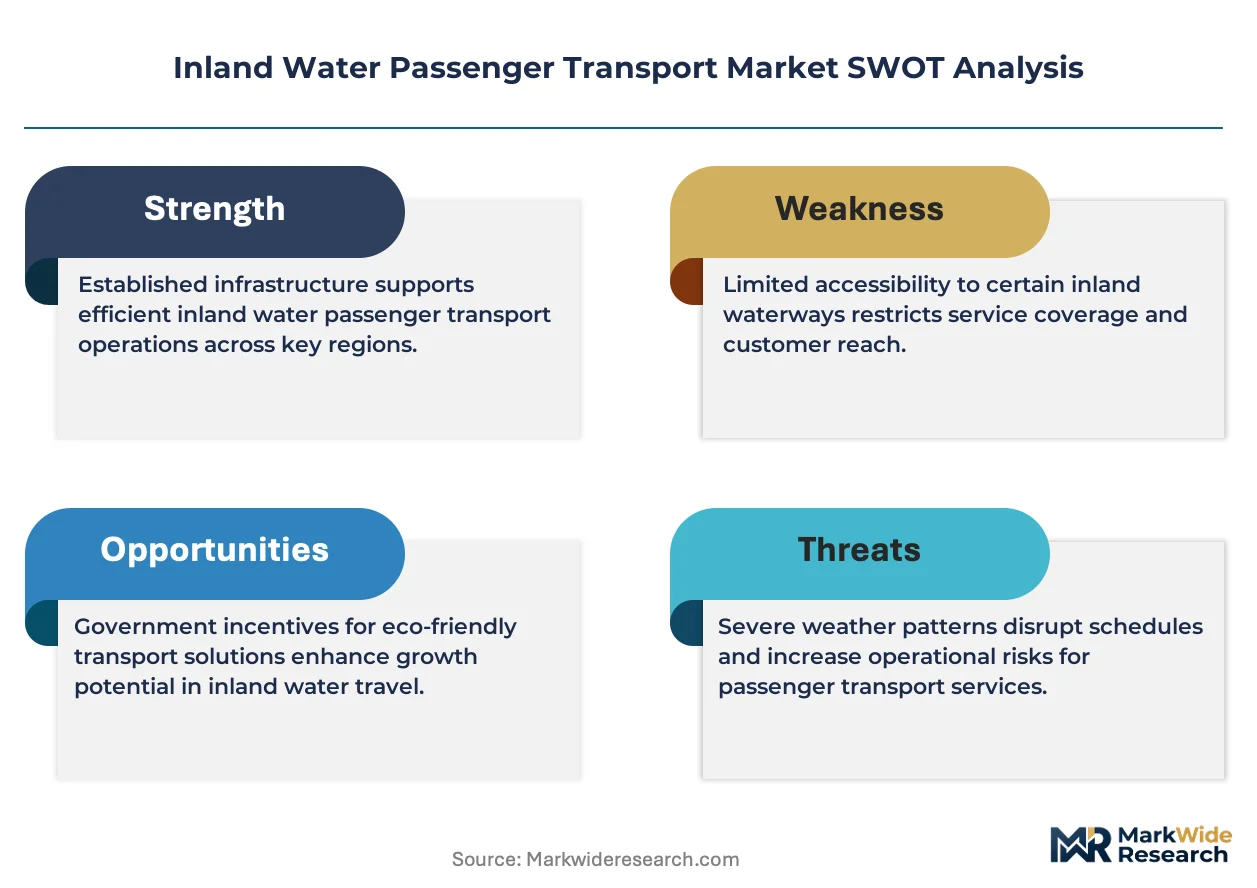
Buyer concentration among luxury river cruise operators is hardening as high-net-worth travelers consolidate spending with established brands. Viking River Cruises dominates European itineraries with extensive longship deployment. AmaWaterways differentiates through culinary partnerships and wellness programming. Scenic Tours anchors the premium all-inclusive segment with butler-service suites.
Inland water passenger transport encompasses scheduled and chartered movement of people along rivers, canals, lakes, and protected coastal waterways using vessels typically ranging from 10 to 135 meters in length with draft limits under 3 meters for channel compatibility. These systems serve commercial tourism corridors, urban commuter links, and recreational access points where road or rail infrastructure proves impractical. Cruise ships command the largest revenue pool within vessel type segmentation due to extended itineraries and high per-passenger yields, while water taxis represent the fastest-expanding category in congested Asian and European cities. The service model dimension shows scheduled public transport retaining volume leadership, though charter services capture disproportionate margin share through bespoke routing and exclusive amenities.
The European Commission enforces F-Gas Regulation and EU Green Deal mandates that compel engine retrofits and alternative fuel adoption across member-state fleets. The US Coast Guard and EPA jointly regulate passenger vessel safety and emissions under separate but overlapping frameworks. China's MEE implements GB standards for inland waterway pollution control affecting Yangtze cruise operations. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs reshape competitive economics and fleet renewal timelines.
Market Dynamics
Fleet decarbonization mandates under the EU Green Deal are forcing synchronous engine retrofits across Rhine-Danube operators while hydrogen fuel cell pilots rewrite vessel economics.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for hydrofluorocarbons are accelerating ammonia and CO2 refrigeration retrofits in hotel-cruise segments.
- Urban congestion pricing:London, Singapore, and Stockholm congestion schemes are diverting commuter flows onto water taxi networks.
- Canal corridor development:China's Grand Canal restoration and Yangtze Three Gorges cruise expansion are opening new itinerary capacity.
Market Restraints
- Steel and aluminum input volatility:Hull construction costs swing with commodity markets, compressing yard margins on fixed-price contracts.
- Lock infrastructure concentration:Rhine-Main-Danube corridor chokepoints at Rüdesheim and Kelheim limit fleet scaling regardless of demand.
- LNG bunkering gaps:Inland LNG infrastructure remains sparse outside Rotterdam-Antwerp corridor, stranding dual-fuel investments.
Strategic Opportunities
- Danube-Black Sea integration:Romanian and Bulgarian port modernization is opening underserved delta itineraries beyond Vienna.
- Battery-electric harbor shuttles:Convergence of solid-state batteries and autonomous docking is enabling zero-emission urban circuits.
- France's inland waterway tourism subsidies:Voies Navigables de France incentive programs are underwriting newbuild boutique vessels.
Industry Challenges
- Marine engineer scarcity:Specialized training programs for dual-fuel and electric propulsion systems lag fleet renewal timelines.
- CE certification complexity:Recreational Craft Directive compliance for novel propulsion technologies extends newbuild delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inland Water Passenger Transport Market |
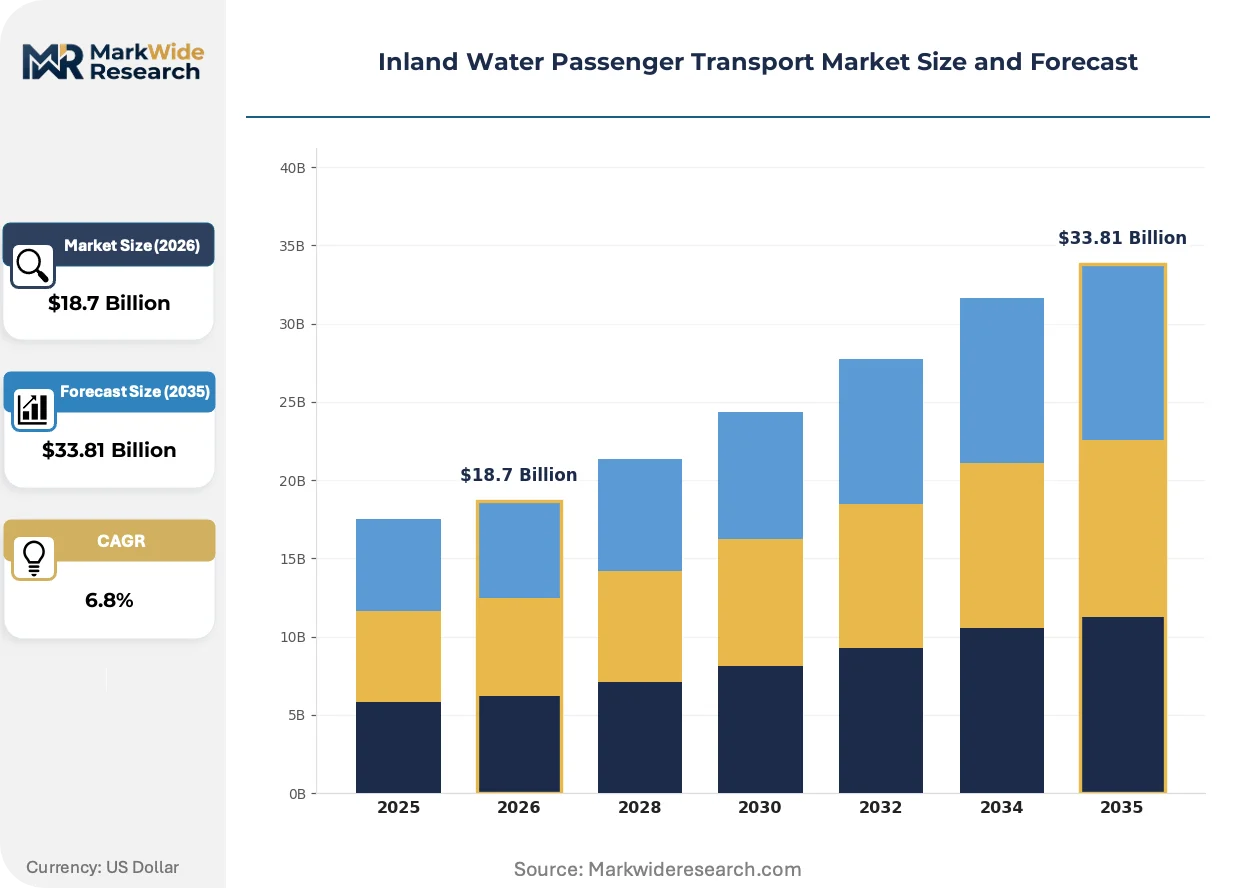
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Cruise Ships, Ferries, Water Taxis, Tour Boats Service Model: Public Transport, Charter Services, Private Rentals, Scheduled Services End User Sector: Tourism, Commuters, Logistics, Marine Recreation Ticketing Approach: Advance Booking, On-Demand, Subscription, Group Rates |
| Companies Covered | Tauck, Scenic Tours, Viking River Cruises, Uniworld River Cruises, Avalon Waterways, AmaWaterways, Emerald Waterways, Croisi Europe, Uniworld Boutique River Cruise Collection, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inland Water Passenger Transport Market Evolving Landscape
Propulsion technology and booking platform architecture are converging to compress operating costs and disintermediate traditional charter intermediaries.
Hybrid diesel-electric propulsion with shore-power connectivity is rewriting energy consumption profiles for overnight river cruisers. Rhine operators with established longship fleets are retrofitting battery banks and cold-ironing capability at priority berths. This technology is compressing fuel cost exposure and enabling overnight silent operation in urban heritage zones.
The EU Green Deal's Fit for 55 package is mandating 55% emissions reductions by 2030 for inland vessels. Engine manufacturers must certify Stage V compliance or face market exclusion. Danube operators are responding with methanol-ready newbuilds and hydrogen pilot partnerships.
Direct-to-consumer booking platforms are displacing traditional tour operator intermediaries in European river cruising. Viking and AmaWaterways have built proprietary reservation engines capturing repeat travelers. This channel shift is most visible in German-speaking markets where brand loyalty concentrates with established flag carriers.
Inland Water Passenger Transport Market Segmentation
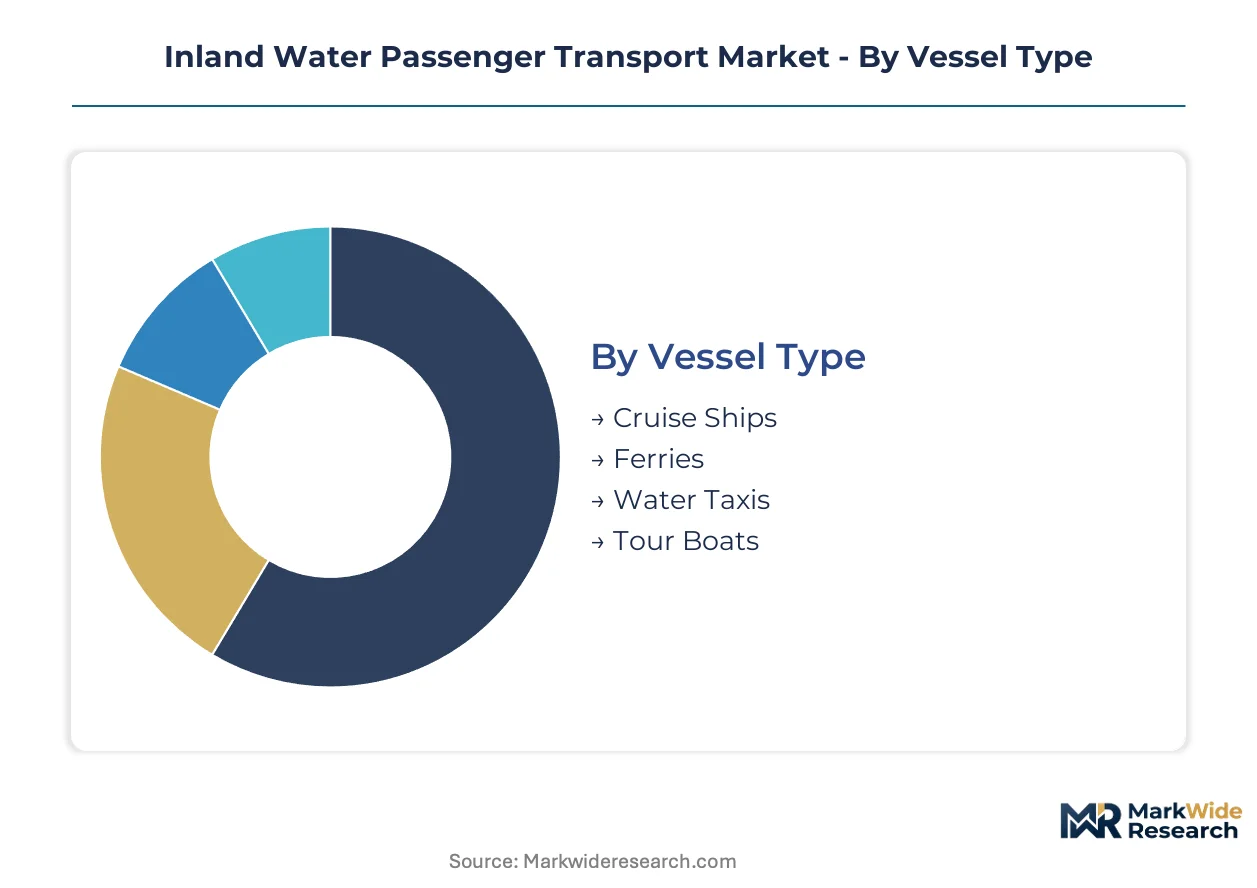
Segmentation in inland water passenger transport reveals how vessel specifications, service architectures, and customer acquisition models determine regulatory exposure and capital intensity. Operators must align fleet composition with corridor infrastructure limits and passenger yield profiles.
Vessel Type:
CE certification under the Recreational Craft Directive and EU Green Deal engine standards apply differentially across hull configurations, with larger vessels facing disproportionate retrofit burdens.
- Cruise Ships:Multi-deck vessels ranging 100-135 meters with hotel facilities and draft limits near 2.8 meters for Rhine-Danube lock compatibility. Demand concentrates in Germany's Rhine Gorge and Austria's Wachau Valley, where extended itineraries generate highest per-passenger yields. The F-Gas Regulation mandates ammonia or CO2 refrigeration retrofits for these hotel-intensive configurations.
- Water Taxis:Compact craft under 20 meters optimized for high-frequency urban circuits with rapid turnaround. Asian and European cities—Bangkok, Istanbul, Hamburg—are expanding fleets as congestion pricing diverts commuters from road networks. Battery-electric pilots are rewriting operating economics for harbor shuttles.
- Ferries:Scheduled cross-water services on fixed routes with capacity for 50-400 passengers and vehicle decks where infrastructure permits.
- Tour Boats:Day-trip vessels with open or partially enclosed decks serving heritage waterways and wildlife corridors.
Leading the category by volume: Cruise Ships. Growing fastest: Water Taxis.
Service Model:
Margin structures diverge sharply between fixed-schedule operations with route monopolies and bespoke services where pricing power depends on exclusivity and customization depth.
- Charter Services:Bespoke vessel deployment with exclusive routing and dedicated crew, capturing disproportionate margin share through event tourism and corporate hospitality. Rhine operators report strongest yield concentration in wedding and conference segments.
- Scheduled Services:Fixed-route, fixed-timetable operations with public service obligations or commercial licenses. Danube commuter corridors between Vienna and Bratislava demonstrate how frequency investment builds ridership loyalty.
- Public Transport:Municipal or state-subsidized networks integrated with metro and bus systems.
- Private Rentals:Bareboat or skippered vessel hire for self-directed itineraries on canal systems.
Highest margin capture: Charter Services. Steepest expansion trajectory: Scheduled Services.
End User Sector:
Customer archetypes determine seasonality patterns, price elasticity, and the viability of premium amenity investment.
- Tourism:International and domestic leisure travelers purchasing packaged or independent itineraries. China's Yangtze Three Gorges corridor and France's Canal du Midi represent contrasting volume concentrations—mass cruise versus boutique barge.
- Commuters:Regular work-trip passengers with high frequency tolerance and low amenity expectations. London's Thames Clipper and Stockholm's archipelago services prove waterborne transit viability where road congestion taxes apply.
- Marine Recreation:Angling, diving, and wildlife observation participants with equipment transport needs.
- Logistics:Crew transfer and supply services for port and offshore operations.
Dominant revenue source: Tourism. Gaining share fastest: Commuters.
Ticketing Approach:
Distribution architecture shapes customer acquisition costs and yield management sophistication.
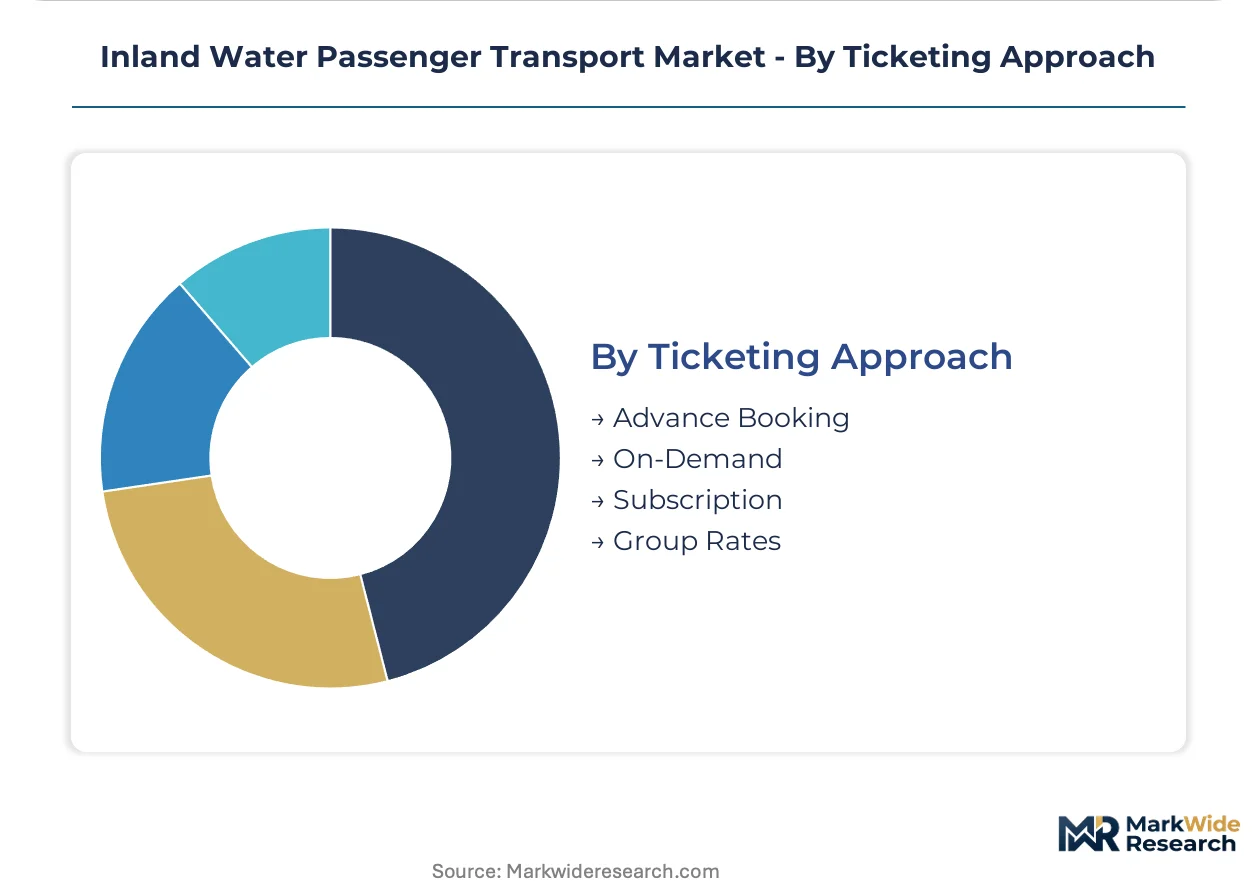
- Advance Booking:Reservation systems with dynamic pricing for capacity-constrained peak seasons. Proprietary platforms at major river cruise operators are displacing tour operator intermediaries.
- On-Demand:Immediate purchase via mobile applications or dockside terminals, dominant in water taxi networks.
- Subscription:Monthly or annual passes for commuter corridors with unlimited travel.
- Group Rates:Volume discounts for corporate, educational, and association block bookings.
Most prevalent mechanism: Advance Booking. Expanding most quickly: On-Demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
River cruise demand concentrates along the Rhine-Danube corridor where lock infrastructure and heritage zoning create natural capacity constraints. Germany's Rhineland-Palatinate and Austria's Wachau Valley anchor European yield premiums. Asian water taxi networks in Bangkok and Istanbul are expanding frequency as congestion pricing redirects commuter flows from road networks.
Germany
The Rhine Gorge between Rüdesheim and Koblenz generates the highest per-passenger yields in European river cruising. The EU Green Deal's Fit for 55 package mandates 55% emissions reductions by 2030, forcing synchronous engine retrofits across Cologne-based operator fleets. Bavaria's Kelheim lock remains a persistent bottleneck limiting fleet scaling on the Main-Danube link.
China
Yangtze Three Gorges cruise expansion is opening mass-market itinerary capacity between Chongqing and Yichang. The MEE enforces GB standards for inland waterway pollution control affecting hotel-cruise operations. Sichuan-Chongqing basin operators are testing methanol-ready newbuilds to anticipate dual carbon compliance timelines.
France
Canal du Midi boutique barge operations capture premium yields through slow-travel positioning. Voies Navigables de France incentive programs are underwriting newbuild vessels for heritage waterway circuits. Burgundy and Alsace clusters concentrate culinary-themed charter capacity.
United States
Mississippi River cruise revival is attracting European operator joint ventures for domestic itinerary development. The EPA regulates passenger vessel emissions under overlapping frameworks with Coast Guard safety mandates. St. Louis and New Orleans anchor emerging port infrastructure investments.
Netherlands
Rotterdam-Antwerp corridor hosts the densest inland LNG bunkering infrastructure outside maritime ports. Amsterdam's canal ring restrictions are accelerating battery-electric tour boat adoption. Randstad urban water taxi networks are integrating with metro systems under municipal climate targets.
Inland Water Passenger Transport Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized charter niches and zero-emission technology pilots. The vendor base stratifies across three maturity tiers: legacy European river cruise houses with proprietary longship fleets, Asian water taxi operators scaling battery-electric pilots, and regional ferry consortia consolidating under public service obligations. Competitive dynamics center on fleet renewal timing relative to F-Gas Regulation compliance deadlines and direct-to-consumer booking platform development displacing tour operator intermediaries.
Within the premium-tier vector, Viking River Cruises and AmaWaterways exemplify divergent specialization strategies—one through standardized fleet deployment, the other through culinary partnership differentiation. Scenic Tours anchors the all-inclusive segment with butler-service suite positioning. Tauck represents the multi-generational family travel archetype with extended shore excursion programming. These operators collectively illustrate how brand architecture and itinerary exclusivity determine yield capture in capacity-constrained corridors.
| Leading Market Players |
|---|
| Tauck |
| Scenic Tours |
| Viking River Cruises |
| Uniworld River Cruises |
| Avalon Waterways |
| AmaWaterways |
| Emerald Waterways |
| Croisi Europe |
| Uniworld Boutique River Cruise Collection |
| Others |
Value Network & Pricing Analysis
Steel and aluminum price indices cascade through inland vessel construction into three distinct pricing tiers, with commodity volatility compressing yard margins on fixed-price contracts and forcing operators to renegotiate charter rates or absorb material cost swings.
Pricing Analysis
High-volume scheduled services trade margin for frequency while charter operators capture premium yields through exclusivity. Pricing stratifies across luxury river cruise, standard ferry, and economy water taxi tiers, with brand reputation and itinerary rarity driving differentiation. Cost compression in the standard tier is intensifying because hull material inflation outpaces fare indexation. Commuter segments exhibit highest price sensitivity, whereas wedding and corporate hospitality buyers accept substantial premiums for bespoke routing.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Shanghai coordinate hub-and-spoke patterns for marine propulsion systems and hotel outfitting. Germany, China, and the Netherlands anchor hull fabrication and engine assembly. Supply chains draw from steel mills, aluminum smelters, and specialized marine electronics foundries. Single-source vulnerability concentrates in German engine certification labs. Distribution runs through port-side logistics hubs serving Rhine-Danube and Yangtze corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as operators pursue captive control over shipyard capacity to secure fleet renewal slots before F-Gas Regulation deadlines.
For Market Incumbents: Deploy proprietary booking platform investment to disintermediate tour operator intermediaries and capture repeat traveler lifetime value. Secure long-term shipyard contracts with methanol-ready specifications to preempt engine retrofit cycles. Battery-electric pilots from Asian entrants threaten yield compression on urban circuits. For New Entrants and Emerging Players: Municipal transit authorities represent the most penetrable channel partner type for zero-emission harbor shuttle deployment. Target underserved Danube-Black Sea delta itineraries beyond Vienna where port modernization lags fleet expansion. Pursue France's Voies Navigables de France subsidy pathways for boutique vessel newbuilds. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional ferry consortia in Central and Eastern Europe where public service obligation contracts provide revenue visibility. Five-to-ten year viability hinges on dual-fuel transition execution rather than asset age. Monitor hydrogen bunkering infrastructure commitments as the inflection signal for technology winner determination.| Strategic Initiative | Industry Significance |
|---|---|
| Shipyard Capacity Lock-in | Long-term yard contracts secure construction slots before EU Green Deal retrofit deadlines compress availability. |
| Proprietary Booking Platform Development | Direct-to-consumer reservation engines displace tour operator intermediaries in German-speaking source markets. |
| Methanol-Ready Newbuild Specification | Stage V compliance pathways future-proof vessels against F-Gas Regulation phase-down mandates. |
| Battery-Electric Harbor Shuttle Pilot | Rotterdam-Antwerp corridor testing validates zero-emission economics for urban water taxi networks. |
| Danube-Black Sea Route Expansion | Romanian and Bulgarian port investments open delta itineraries beyond capacity-constrained Vienna terminus. |
Research Methodology
EU vessel registration databases, Rhine-Main-Danube lock traffic statistics, and China MEE pollution disclosure filings formed the secondary backbone. Primary interviews with river cruise fleet managers, marine engine procurement leads, shipyard commercial directors, and port authority planning officers validated capacity and pricing assumptions. Bottom-up vessel counts and top-down corridor revenue estimates were triangulated to anchor market sizing.
Historical trendline analysis of fleet renewal cycles and emissions compliance investments informed projection modeling. Segmentation dimensions included vessel type, service model, propulsion architecture, and regional regulatory cluster across the analysis window. CAGRs were derived from capacity expansion schedules and yield trajectory assumptions. Forecast inputs incorporated F-Gas Regulation phase-down timelines and hydrogen bunkering infrastructure development curves.
Caveats apply where steel and aluminum commodity volatility, lock infrastructure bottlenecks, or marine engineer training program shortfalls could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement consistency and shipyard delivery reliability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Global Passenger Cars Market
Passenger Vehicles
India Automotive Market
Passenger Vehicles
Automotive Passenger Vehicle Sensor Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
Large Suvs Market
Passenger Vehicles
Convertible Vehicles Market
Passenger Vehicles
Wheelchair Accessible Vehicle Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
Latin America Passenger Car Market
Passenger Vehicles
Indonesia Passenger Car Market
Passenger Vehicles
Passenger Vehicle Market
Passenger Vehicles
Luxury Car Market
Passenger Vehicles
North America MUV Rental Market
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
Medium Cars Market