
 Water Taxi Market | 2026-2036
Water Taxi Market Size, Share, and Industry Trends Forecast 2026-2036
Water Taxi Market Analysis
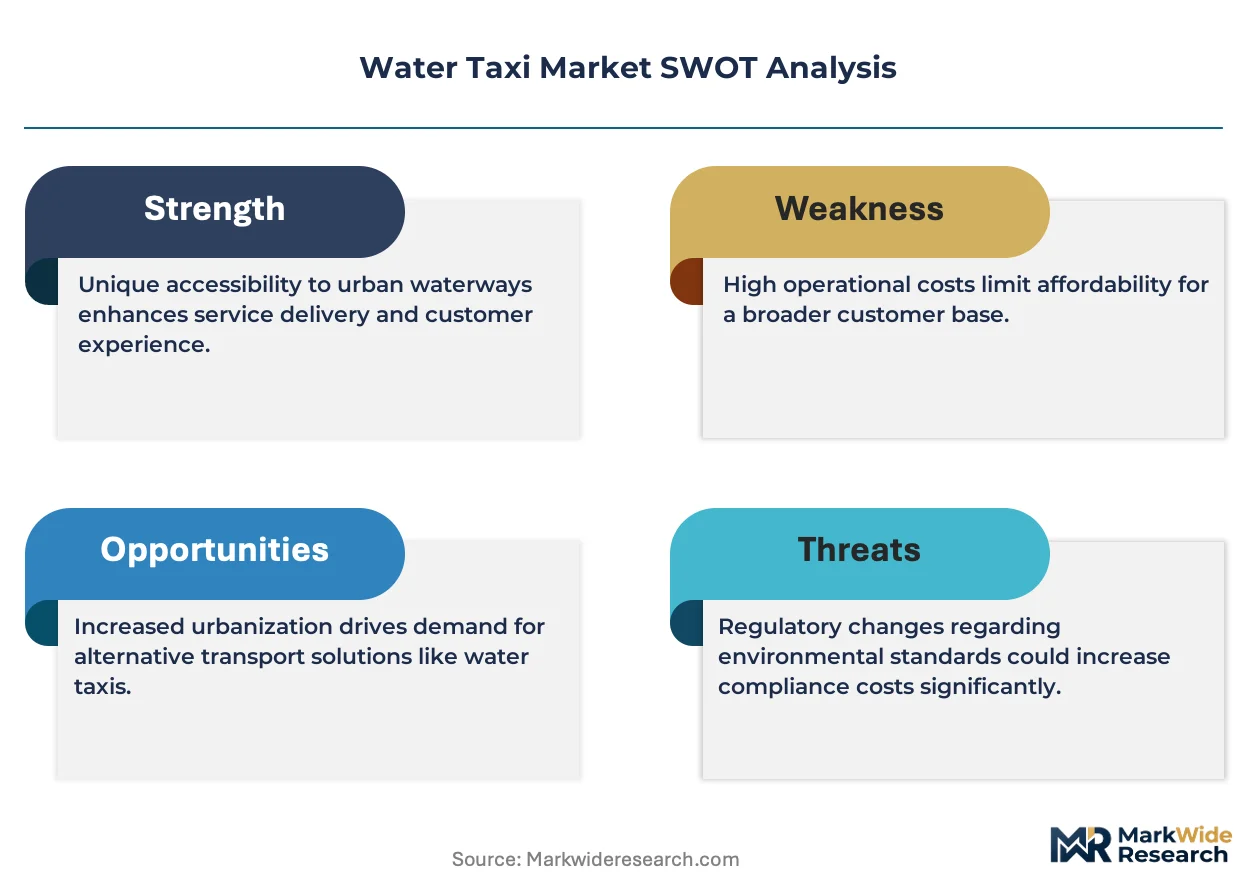
Licensed marine pilot availability is rotating toward electric vessel certification programs, constraining fleet expansion timelines in established harbors. Brunswick Corporation leverages its manufacturing scale to dominate conventional hull production across North American waterways. Candela Technology specializes in hydrofoil electric propulsion systems that differentiate its offering from displacement-hull competitors. Vision Marine Technologies sustains its technology leadership through integrated battery-electric outboard development for urban shuttle operators.
A water taxi is a small to medium passenger vessel operating on fixed or on-demand routes in harbors, rivers, and coastal zones, typically accommodating 6 to 50 passengers with diesel, hybrid, or fully electric propulsion systems designed for frequent short-cycle operations. Luxury Transport commands premium fare structures and higher per-vessel margins among service type categories, while Shuttle Services anchors daily ridership volume in congested waterfront cities. GPS Navigation and Real-Time Tracking now function as baseline operational requirements rather than differentiators, compressing technology margins but expanding addressable market access for fleet operators lacking legacy infrastructure.
The US Coast Guard enforces passenger vessel safety standards under 46 CFR Subchapter T, directly shaping hull design, stability calculations, and crew qualification requirements for domestic operators. The EU Green Deal and F-Gas Regulation constrain diesel engine deployments across European harbors, redirecting procurement budgets toward electric and hydrogen fuel cell alternatives. Stakeholders must monitor evolving port authority electrification timelines and crew retraining pipelines to align fleet investment cycles with infrastructure readiness.
Market Dynamics
The International Maritime Organization's emission reduction mandates are forcing fleet operators to accelerate electrification timelines ahead of port infrastructure readiness, compressing capital deployment cycles and reshaping procurement criteria across harbor authorities.
Growth Catalysts
- IMO 2030 Carbon Intensity Targets:Maritime authorities in the United Arab Emirates, Singapore, and Norway are mandating fleet decarbonization, directing public procurement budgets toward electric and hybrid vessel categories.
- Urban Waterfront Tourism:Coastal metropolitan transit authorities in Barcelona, Sydney, and Vancouver are expanding marine transport networks to relieve road congestion and capture visitor spending.
- Hydrofoil Propulsion Maturation:Reduced drag coefficients from computer-optimized foil designs are extending electric range thresholds, enabling longer inter-harbor routes previously reserved for diesel craft.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Cell production concentrates in East Asian manufacturing clusters, exposing European and North American operators to raw material price volatility and extended lead times.
- Licensed Marine Pilot Scarcity:Certification bodies have not scaled electric vessel training programs proportionally to fleet expansion targets, creating operational bottlenecks in established harbors.
- Port Electrification Lag:Shore power infrastructure at major terminals in Hamburg, Rotterdam, and Long Beach remains incomplete, limiting charging availability for high-frequency operators.
Strategic Opportunities
- India Coastal Connectivity:The country's Sagarmala port modernization initiative is creating demand corridors between Mumbai, Goa, and Kochi for inter-city water transport services.
- Autonomous Navigation Convergence:Integration of LiDAR obstacle detection with AI-powered route optimization is opening regulatory pathways for reduced-crew operations in controlled waterways.
- EU Green Deal Maritime Funding:The European Investment Bank's sustainable transport facility is offering concessional financing for zero-emission vessel procurement, improving project economics for municipal operators.
Industry Challenges
- Electric Propulsion Certification Timelines:Classification societies have not harmonized safety standards for high-voltage marine systems, forcing operators to navigate country-specific approval processes.
- Crew Retraining Pipeline Gaps:Maritime academies lack simulation infrastructure for electric drivetrain troubleshooting, extending time-to-competency for engineering officers transitioning from diesel backgrounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Taxi Market |
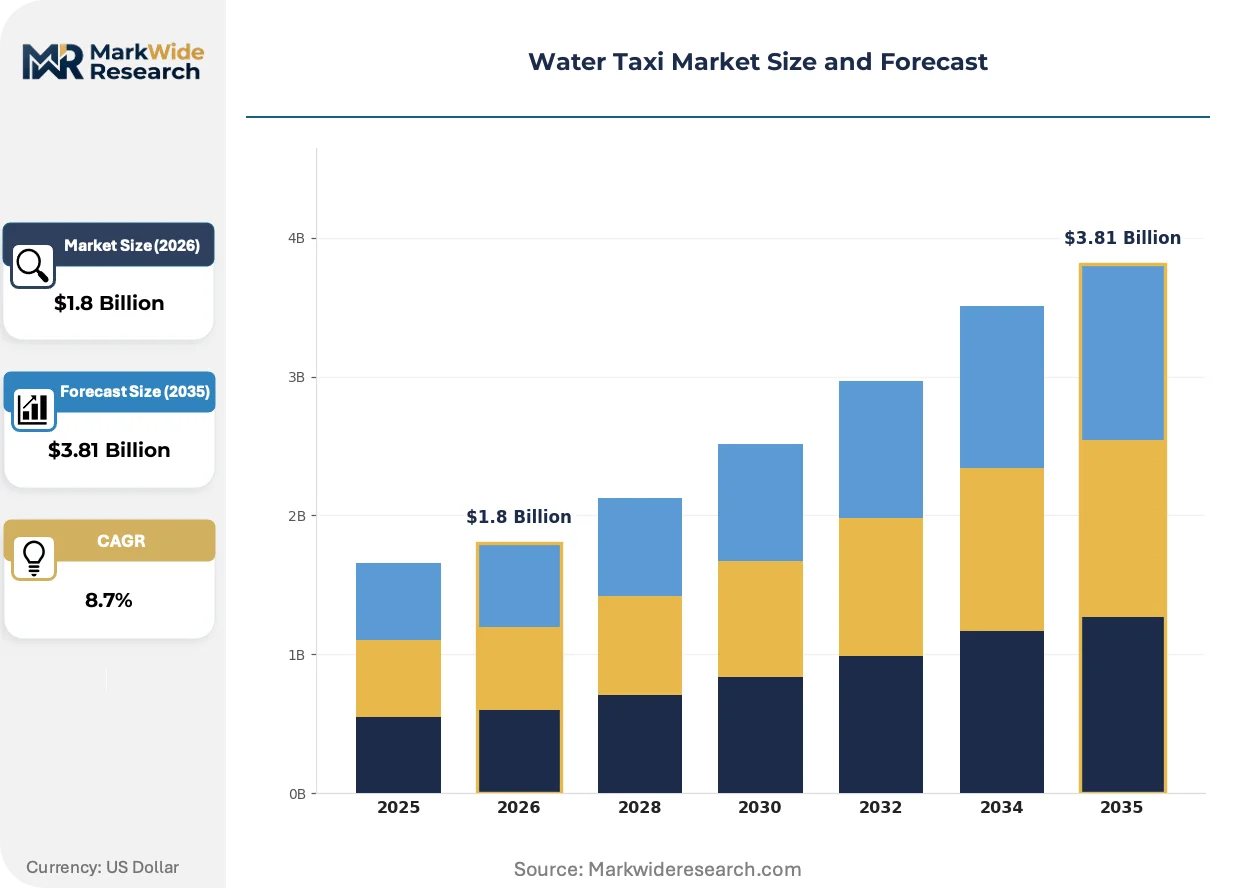
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Luxury Transport, Shuttle Services, Sightseeing Tours, Emergency Services End User: Tourists, Commuters, Corporate Clients, Event Planners Fleet Size: Small Fleets, Medium Fleets, Large Fleets, On-Demand Services Technology: GPS Navigation, Eco-Friendly Engines, Mobile Booking, Real-Time Tracking |
| Companies Covered | Sunseeker International, Volvo Penta, Brunswick Corporation, BAE Systems, Candela Technology, Azimut-Benetti Group, Beneteau Group, Vision Marine Technologies, Ferretti Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Taxi Market Emerging Trajectories
Hull design and propulsion architectures are undergoing fundamental revision as operators balance passenger capacity against energy efficiency requirements, with software-defined vessel management emerging as a parallel transformation layer.
Hydrofoil electric propulsion is displacing conventional displacement hulls in premium urban shuttle routes. Candela Technology and competitors are deploying computer-stabilized foil systems that reduce water resistance by approximately 80 percent at cruising speed. Harbor authorities in Stockholm and Venice are prioritizing foil-equipped tenders for their reduced wake impact and extended range per charge.
The EU F-Gas Regulation and complementary national bans on internal combustion engine sales are compressing diesel vessel residual values. Operators in Amsterdam, Copenhagen, and Hamburg are advancing fleet replacement schedules to avoid stranded asset risk. Classification society DNV has responded with streamlined approval pathways for battery-electric and hydrogen fuel cell installations.
Service unbundling is fragmenting traditional fleet management contracts. Municipal transit authorities are separating vessel ownership from operations and maintenance, creating openings for specialized electric fleet managers. The Port of San Francisco and Transport for London have both tendered operations-only contracts, shifting capital burden to infrastructure funds and leasing specialists.
Water Taxi Market Segmentation
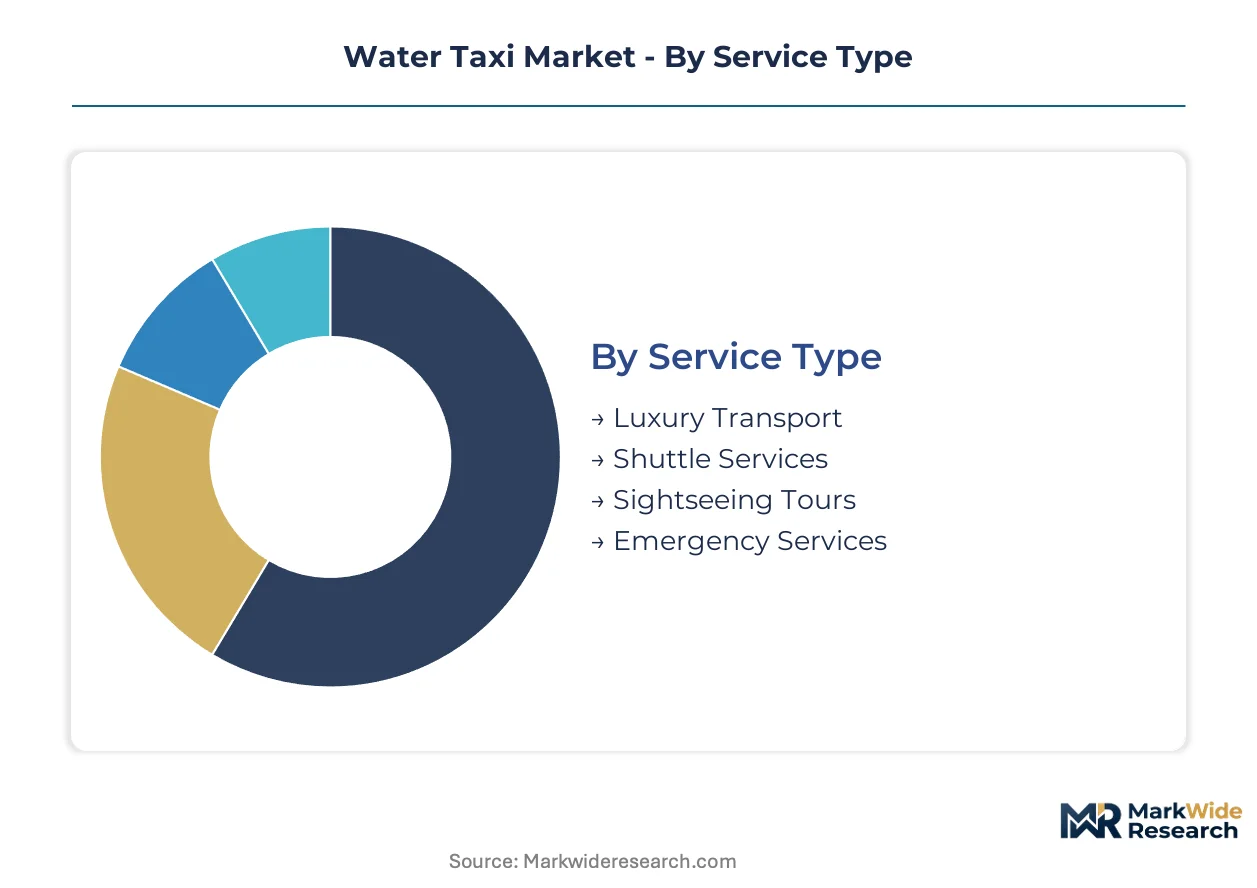
Water taxi operators configure fleet and service architectures around passenger willingness-to-pay, operational density, and harbor infrastructure constraints. Segmentation reveals where capital deployment concentrates and which technology bundles command premium positioning.
Service Type:
Margin pools concentrate in premium passenger experiences where fare elasticity remains low and vessel utilization rates justify higher per-unit capital investment.
- Luxury Transport:Vessels feature climate-controlled cabins, premium seating configurations, and dedicated crew ratios below fifteen passengers per staff member. Dubai's marine transport expansion and Monaco's harbor authorities are directing procurement toward this category to capture high-value visitor segments and corporate hospitality demand.
- Shuttle Services:High-frequency fixed-route operations prioritize passenger throughput over amenity density, with vessels optimized for sub-five-minute boarding cycles. Barcelona and Sydney coastal metropolitan transit authorities are expanding these networks to relieve road congestion during peak commuter windows.
- Sightseeing Tours:Seasonal demand patterns dominate revenue recognition, with operators in Venice and Stockholm deploying convertible deck configurations.
- Emergency Services:Specialized hull designs prioritize maneuverability and medical equipment payload capacity.
Shuttle Services holds installed capacity. Luxury Transport is rotating up the share rankings.
End User:
Volume concentration follows daily ridership patterns, with repeat-trip customers driving fleet sizing decisions and single-use visitors shaping seasonal capacity planning.
- Tourists:Intermittent demand with high price sensitivity and strong correlation to cruise ship arrival schedules and hotel occupancy rates. Operators in Vancouver and Sydney calibrate vessel availability against visitor bureau forecasts.
- Commuters:Predictable daily demand enables subscription pricing models and dedicated vessel allocation. Singapore's harbor authorities are integrating water taxi passes with broader metropolitan transit cards to capture this segment.
- Corporate Clients:Contracted shuttle services for waterfront business districts.
- Event Planners:Charter demand tied to conference and wedding calendars.
Commuters anchor baseline utilization. Tourists generate the steepest expansion trajectory during peak seasons.
Fleet Size:
Capital intensity and operational flexibility trade off across scale tiers, with regulatory compliance costs creating discontinuities in optimal fleet configuration.
- Small Fleets:Owner-operated vessels with limited route coverage and high dependency on individual harbor master relationships. Amsterdam's canal operators and smaller Mediterranean ports sustain this tier through niche route specialization.
- Medium Fleets:Regional coverage with dedicated maintenance facilities and standardized crew training programs. Operators in the UAE are consolidating toward this tier to meet IMO emission reduction mandates.
- Large Fleets:Multi-harbor networks with centralized dispatch and integrated technology platforms.
- On-Demand Services:App-mediated matching of passengers to available capacity without fixed route obligations.
Medium Fleets is climbing the fastest as electrification capital requirements favor scaled procurement. Small Fleets retains route density in protected waterways.
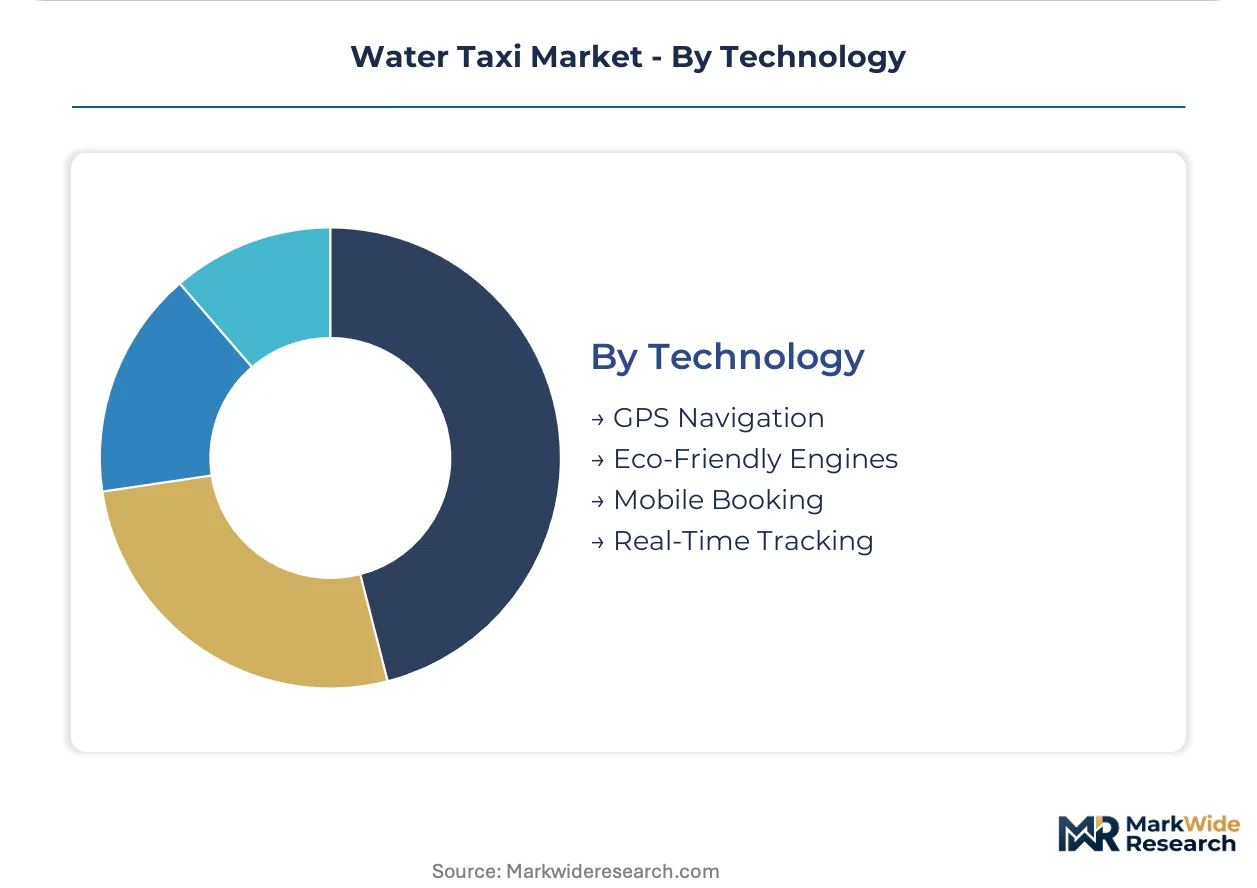
Technology:
Technology bundling has shifted from competitive differentiation to operational baseline, compressing standalone pricing power while expanding market access.
- GPS Navigation:Standard route optimization with real-time traffic integration now mandatory for harbor authority operating permits.
- Eco-Friendly Engines:Electric and hydrogen fuel cell propulsion systems. Norway's maritime authorities and the EU Green Deal are redirecting procurement budgets toward this segment.
- Mobile Booking:Platform-mediated reservation and payment systems.
- Real-Time Tracking:Passenger-facing arrival prediction and fleet visibility tools.
Eco-Friendly Engines is gaining share fastest as regulatory deadlines approach. GPS Navigation and Real-Time Tracking have converged to commodity status.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The International Maritime Organization's emission reduction mandates are reshaping procurement criteria across harbor authorities. Urban waterfront tourism adoption is accelerating among coastal metropolitan transit authorities. Fleet operators must align investment cycles with port electrification timelines and crew retraining pipelines.
United Arab Emirates
Dubai's marine transport expansion anchors regional investment demand. MOHAP certification requirements for passenger vessels are accelerating electric fleet procurement timelines. Abu Dhabi harbor authorities are consolidating medium-fleet operators to meet IMO decarbonization targets ahead of infrastructure readiness.
United States
Congested waterfront cities in California and New York are expanding shuttle services to relieve road congestion. The US Coast Guard enforces passenger vessel safety standards under 46 CFR Subchapter T, directly shaping hull design and crew qualification requirements. San Francisco port authorities have tendered operations-only contracts, shifting capital burden to infrastructure funds.
Norway
Maritime authorities are mandating fleet decarbonization ahead of IMO 2030 carbon intensity targets. The country's national maritime regulator has streamlined approval pathways for battery-electric installations. Oslo and Bergen harbor authorities are prioritizing hydrofoil-equipped tenders for reduced wake impact and extended range per charge.
Netherlands
Amsterdam canal operators sustain small-fleet tier through niche route specialization. The EU F-Gas Regulation and complementary national bans on internal combustion engine sales are compressing diesel vessel residual values. Rotterdam port electrification infrastructure remains incomplete, limiting charging availability for high-frequency operators.
India
The Sagarmala port modernization initiative is creating demand corridors between Mumbai, Goa, and Kochi for inter-city water transport services. The country's central maritime authority is redirecting procurement budgets toward electric alternatives under national emission reduction commitments. Mumbai metropolitan transit authorities are expanding marine transport networks to capture visitor spending and commuter ridership volume.
Water Taxi Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in water taxi manufacturing. Conventional hull producers with manufacturing scale advantages dominate established North American and European waterways. Hydrofoil electric propulsion specialists and integrated battery-electric outboard developers represent distinct technology archetypes. Competitive moves concentrate on strategic partnerships with harbor authorities and technology licensing agreements for electric drivetrain systems.
Within the integrated manufacturing tier, Brunswick Corporation exemplifies scale-driven conventional hull production. Candela Technology and Vision Marine Technologies occupy positions as technology specialists, with the former representing hydrofoil electric propulsion architecture and the latter anchoring integrated battery-electric outboard development for urban shuttle operators. These three companies illustrate the market's bifurcation between legacy manufacturing scale and emerging electric propulsion specialization.
| Leading Market Players |
|---|
| Sunseeker International |
| Volvo Penta |
| Brunswick Corporation |
| BAE Systems |
| Candela Technology |
| Azimut-Benetti Group |
| Beneteau Group |
| Vision Marine Technologies |
| Ferretti Group |
| Others |
Supply Flow & Price Mechanics
Manufacturing scale economies in conventional hull production anchor price floors across North American and European waterways, compressing margins for smaller operators while concentrating procurement power among harbor authorities with fleet-standardization mandates. Brunswick Corporation's production volumes enable cost absorption that specialist electric-foil builders cannot match, creating tiered entry barriers that reshape competitive dynamics from procurement through aftermarket service.
Pricing Analysis
Dubai commands premium fare multiples over Amsterdam canal routes, reflecting divergent passenger willingness-to-pay and harbor authority subsidy structures. Three-tier pricing structure across premium, standard, and economy levels separates luxury transport with dedicated crew ratios from high-frequency shuttle services with minimal amenity density. Cost compression in mid-tier electric vessel procurement is intensifying because lithium-ion battery supply concentration exposes European operators to raw material price volatility. Tourists exhibit highest price sensitivity with strong correlation to cruise ship schedules, while corporate clients and contracted commuters accept subscription premiums for dedicated vessel allocation.
Supply Chain Analysis
Strategic stockpiling of high-voltage marine batteries remains rare given rapid cell chemistry evolution and IMO regulatory uncertainty, forcing operators toward just-in-time procurement with extended lead time exposure. Cell production concentrates in China, South Korea, and Japan, while hull fabrication clusters in the United States, Italy, and Turkey. Supply chains rest on lithium carbonate, nickel sulfate, and marine-grade aluminum as critical inputs. Single-source vulnerability in battery management system firmware creates operational risk for fleet operators scaling beyond pilot deployments. Distribution runs through harbor authority tender processes and municipal procurement frameworks rather than open-market vessel sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified marine pilots with electric vessel qualifications represent the binding constraint on fleet expansion timelines, creating capability scarcity that rewards early investment in crew retraining infrastructure and simulation partnerships with maritime academies.
For Market Incumbents: Fortify position through backward integration into battery-electric drivetrain assembly and exclusive harbor authority service contracts that lock out emerging hydrofoil specialists. Candela Technology's foil-stabilization patents threaten displacement-hull incumbents in premium urban shuttle routes. Capacity addition in UAE and Norwegian waters with preemptive electric fleet certification secures first-mover advantage as IMO 2030 deadlines approach. For New Entrants and Emerging Players: Anchor in India's Sagarmala corridor between Mumbai, Goa, and Kochi, where port modernization creates demand without entrenched incumbent fleets. Underpenetrated inter-city water transport offers white-space opportunity absent from saturated European harbor networks. Direct sales to state maritime authorities with concessional financing packaging bypasses capital-constrained municipal procurement cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated battery-electric outboard developers over conventional hull assemblers facing stranded asset risk from EU F-Gas Regulation compression. Long-term viability hinges on shore power infrastructure buildout pace and classification society harmonization timelines. Acquisition targets with DNV approval pathways and existing UAE or Norway harbor contracts signal readiness for capital deployment acceleration. Watch for lithium-ion battery price inflection as synthetic graphite anode capacity expands.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Certification Investment | MOHAP and DNV streamlined pathways accelerate UAE and Norway deployment timelines. |
| Harbor Authority Operations-Only Contracting | San Francisco and Transport for London tenders shift capital burden to infrastructure funds. |
| Hydrofoil Propulsion Licensing | Candela Technology's computer-stabilized foil systems reduce water resistance by approximately eighty percent. |
| Maritime Academy Simulation Partnership | Crew retraining pipeline gaps extend time-to-competency for diesel-to-electric engineering transitions. |
| Shore Power Infrastructure Joint Development | Rotterdam and Long Beach electrification lag limits charging availability for high-frequency operators. |
Methodological Framework
A spread of perspectives from fleet operations directors, harbor authority procurement managers, maritime academy training coordinators, and electric drivetrain engineers converged on the working assumptions underlying vessel deployment forecasts. Primary fieldwork combined structured interviews with secondary validation through IMO regulatory filings, EU Green Deal implementation progress reports, port authority electrification timelines, and customs data on marine vessel imports. Bottom-up triangulation of operator fleet plans against top-down harbor capacity constraints anchored volume estimates.
Segmentation dimensions modeled include service type architecture, propulsion technology tier, fleet scale category, and end-user demand pattern across the projection horizon. CAGRs were derived from vessel order backlogs, harbor authority capital expenditure disclosures, and regulatory deadline proximity. Forecast inputs incorporated lithium-ion battery cost curves, licensed marine pilot training pipeline throughput, and shore power infrastructure completion schedules.
Decision-makers should treat outputs as directional under assumptions of sustained IMO emission mandate enforcement and lithium supply chain stability; material deviation would warrant model refresh. Forecasts hinge on port electrification timelines and crew certification scaling. Revision becomes warranted when battery chemistry substitution or autonomous navigation regulatory clearance crosses commercial deployment thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Hydrogen-Powered Yacht Market
Marine Vehicles
Outboard Boats Market
Marine Vehicles
Cargo Vessel Market
Marine Vehicles
India Aluminium Fishing Boat Market
Marine Vehicles
Marine Electric Vehicle Market
Marine Vehicles
Airboats Market
Marine Vehicles
Marine Boat Passenger Seat Market
Marine Vehicles
Aluminium Fishing Boat Market
Marine Vehicles
Amphibious Vehicle Market
Marine Vehicles
Marine Passenger Seat Market
Marine Vehicles
Trawler Boat Market
Marine Vehicles
Marine Seats Market
Marine Vehicles
Boat and Ship MRO Market
Marine Vehicles
Global Outboard Motors Market
Marine Vehicles
Sea-Based Vehicle Carrier Market
Marine Vehicles
Asean Boat Davits Market