
 Latin America Passenger Car Market | 2026-2036
Latin America Passenger Car Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Passenger Car Market Foresight
Brazilian automotive assembly capacity is pivoting toward flex-fuel and hybrid production lines to align with federal biofuel mandates. Toyota Motor Corporation leverages its regional hybrid leadership to sustain premium positioning across São Paulo and Mexico City metropolitan markets. Volkswagen AG anchors its competitive stance through deep manufacturing integration at its São Bernardo do Campo complex, while Stellantis NV competes aggressively on entry-level hatchback and sedan portfolios tailored to first-time buyer credit structures.
A passenger car denotes a motor vehicle designed primarily for personal transportation, typically seating four to five occupants, with unibody construction, independent suspension systems, and power outputs ranging from 70 to 400 horsepower depending on segment classification. The category serves individual mobility, household transport, and fleet-based commercial applications across urban and interurban road networks. SUV configurations now command the dominant margin pool across Latin American markets, absorbing buyer preference shifts away from traditional sedans, while hybrid fuel types represent the fastest-growing propulsion category as city-level emissions restrictions tighten and electricity infrastructure remains uneven outside major metropolitan zones.
Brazil's ANFAVEA alignment with Inovar-Auto provisions and Mexico's integration with USMCA automotive rules of origin create dual regulatory anchors shaping regional production economics and cross-border supply chain configuration. ANVISA in Brazil and Mexico's environmental secretariat (SEMARNAT) impose evolving emissions and safety certification requirements that filter directly into product planning cycles. Stakeholders must monitor how pending Mercosur-EU trade agreement automotive chapters could restructure tariff exposure and local content thresholds across the region's manufacturing footprint.
Market Dynamics
Flex-fuel hybrid drivetrains are absorbing engineering investment across Brazilian assembly plants as ANFAVEA compliance deadlines tighten and ethanol infrastructure maturity outpaces electric grid reliability in secondary cities.
Growth Catalysts
- Inovar-Auto successor frameworks:Brazil's industrial policy mandates continue redirecting capital toward localized powertrain production, compelling foreign OEMs to deepen component sourcing from Minas Gerais and Paraná supplier clusters.
- Fleet electrification procurement:Corporate mobility managers in São Paulo and Mexico City are accelerating hybrid vehicle adoption for urban delivery and executive transport pools ahead of municipal emissions restrictions.
- USMCA rules of origin:North American trade provisions are pulling Mexican assembly capacity toward higher-value component integration, strengthening cross-border supply linkages with Guanajuato and Querétaro industrial corridors.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack production remains concentrated in Asian manufacturing hubs, exposing Latin American assemblers to input cost volatility and currency mismatch risks.
- SEMARNAT emissions certification timelines:Mexico's environmental secretariat maintains extended validation periods for new powertrain variants, compressing product launch windows against competitor cycles.
- Credit access fragmentation:First-time buyer financing depends on concentrated regional banking networks in Brazil's Northeast, constraining volume penetration outside southeastern metropolitan zones.
Strategic Opportunities
- Colombian market underpenetration:Andean passenger car density remains below southern cone levels, creating white space for entry-level hybrid portfolios as Bogotá's pico y placa restrictions tighten.
- Biofuel-electric convergence:Flex-fuel plug-in hybrid architectures are emerging as a technology bridge, enabling OEMs to leverage Brazil's ethanol distribution network while capturing electric range benefits.
- Subscription mobility platforms:Fleet-as-a-service operators are opening direct procurement channels that bypass traditional dealer networks, reshaping volume allocation toward dedicated production lines.
Industry Challenges
- Powertrain engineering talent scarcity:Brazilian technical universities produce insufficient hybrid system specialists, forcing assemblers to import calibration expertise or fund captive training programs.
- Dual certification complexity:Products serving both Mercosur and USMCA markets must satisfy diverging crash-test and emissions protocols, extending development timelines and testing expenditures.
- Legacy supplier integration friction:Established component manufacturers in São Bernardo do Campo industrial parks face capability gaps in electric motor and inverter production, requiring parallel supply chain construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Passenger Car Market |
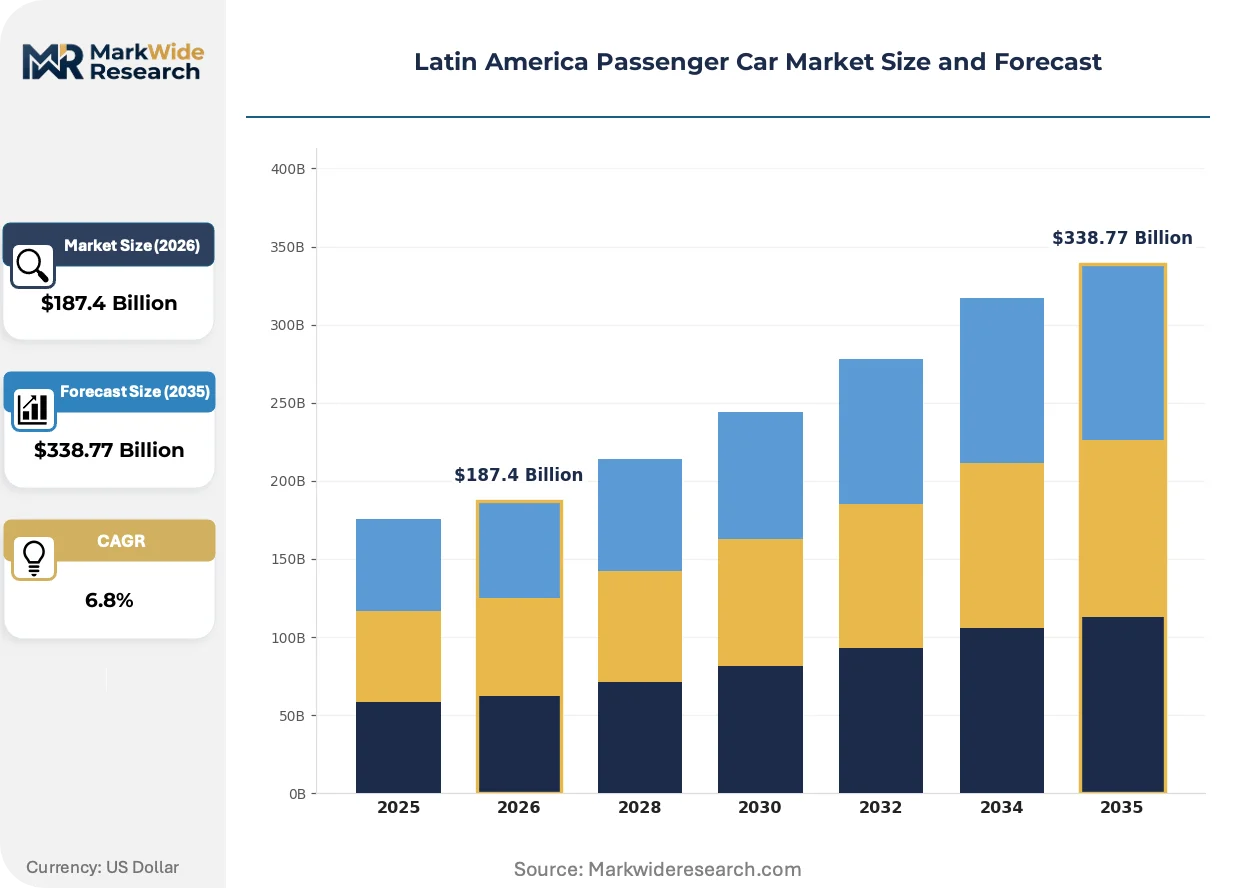
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Hatchback, Coupe Fuel Type: Petrol, Diesel, Electric, Hybrid Customer Segment: First-Time Buyers, Fleet Operators, Luxury Buyers, Used Car Customers Sales Channel: Direct Sales, Dealerships, Online Platforms, Auctions |
| Companies Covered | Toyota Motor Corporation, Nissan Motor Co., Volkswagen AG, Renault Group, Hyundai Motor Company, Stellantis NV, Ford Motor Company, Honda Motor Co., General Motors Company, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Passenger Car Market Shifts & Advancements
Electrification pathways are fragmenting across Latin American markets as regulatory calendars diverge and infrastructure maturity varies sharply between metropolitan cores and interior highway corridors.
Flex-fuel hybrid systems are absorbing the dominant share of powertrain development resources at Brazilian engineering centers. These configurations enable OEMs to satisfy ANFAVEA efficiency mandates while preserving consumer fuel choice flexibility. The technology is absorbing market share from conventional internal combustion engines in the C-segment sedan and compact SUV categories where total cost of ownership sensitivity peaks.
ANVISA safety certification requirements are expanding to include advanced driver assistance system validation for all new vehicle registrations above entry-level price thresholds. This regulatory expansion is forcing importers to standardize sensor suites across trim levels rather than segmenting by market. The premium SUV segment faces the steepest compliance cost escalation as lane-keeping and automatic emergency braking become mandatory.
Corporate fleet procurement is consolidating around total mobility cost metrics rather than acquisition price alone. Leasing operators and large employers in Santiago and Buenos Aires are demanding telematics-integrated vehicles that enable usage-based insurance and predictive maintenance scheduling. Chilean mining sector fleet managers are pioneering this shift, negotiating multi-year supply agreements that bundle vehicle, service, and energy costs into single contracted rates.
Latin America Passenger Car Market Segmentation
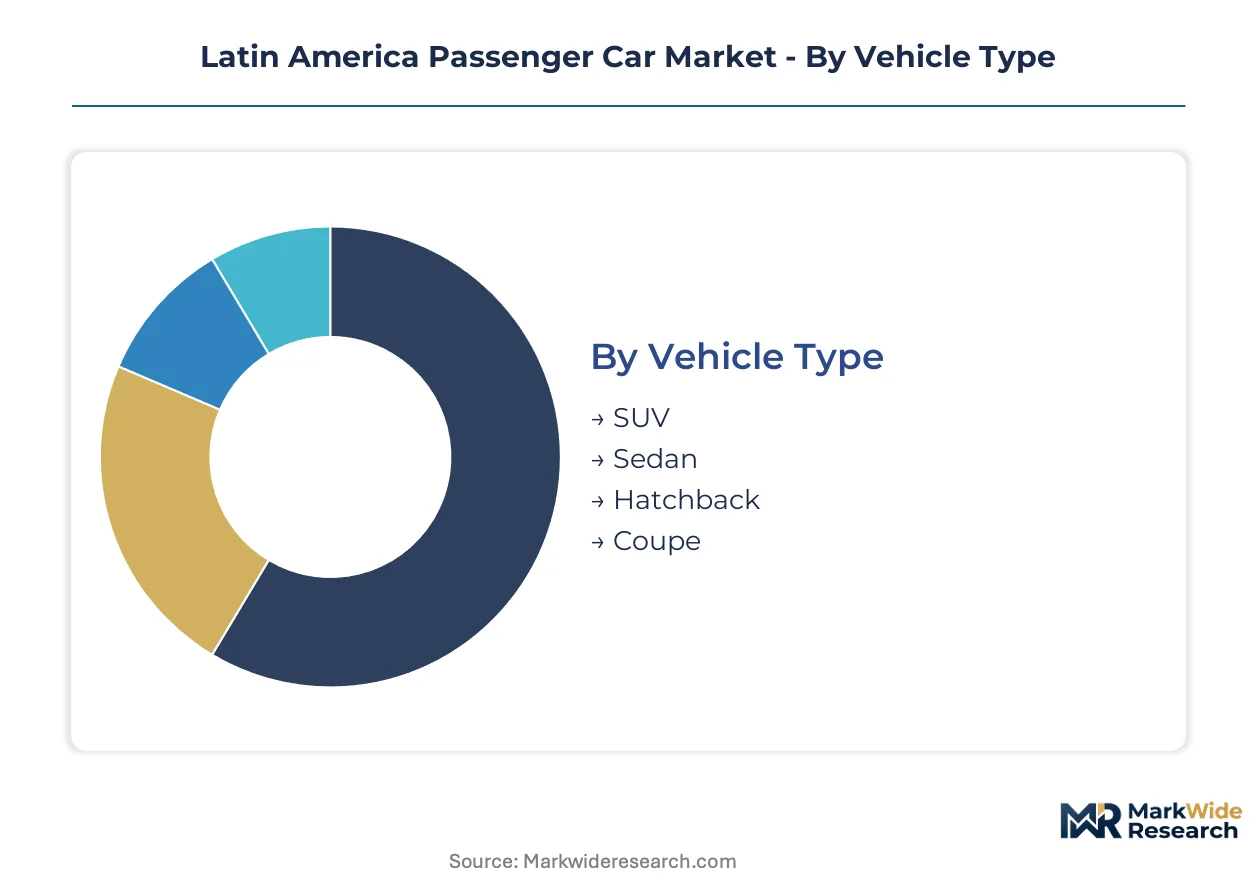
Passenger car purchasing patterns across Latin America fragment sharply along fuel infrastructure maturity, credit access depth, and fleet procurement centralization. Understanding these segment boundaries enables OEMs to align powertrain portfolios with regulatory calendars and distributor networks with buyer financing constraints.
Vehicle Type:
Standalone vehicle architectures dominate assembly line configuration, while platform-sharing strategies embed common underpinnings across multiple body styles to amortize development costs.
- SUV:Unibody crossovers with elevated ride heights and flexible cargo configurations absorb the dominant margin pool across São Paulo and Mexico City dealer networks. Brazilian assembly plants at São Bernardo do Campo and Betim prioritize SUV production lines to capture preference shifts away from traditional three-box sedans.
- Sedan:Three-box configurations with dedicated trunks retain volume concentration in fleet procurement channels and credit-dependent first-time buyer segments where lower entry pricing outweighs utility premiums. Mexico's USMCA-aligned export capacity continues feeding sedan demand into North American rental and corporate pools.
- Hatchback:Compact two-box designs with fold-flat rear seating dominate entry-level urban mobility in Buenos Aires and Santiago metropolitan zones.
- Coupe:Two-door fixed-roof configurations with sport-tuned suspensions serve narrow premium niches in Brazil's southeastern industrial corridor.
SUV leads volumes today; Hatchback is gaining share fastest among first-time buyer credit programs.
Fuel Type:
Cost tier stratification separates established liquid fuel infrastructure from emerging electrification pathways requiring parallel supply chain construction.
- Petrol:Internal combustion engines calibrated for gasoline deliver proven reliability across Brazil's interior highway corridors where ethanol blending ratios fluctuate seasonally. São Paulo state refineries anchor distribution logistics, though price volatility at Petrobras-administered pumps compresses operating cost predictability for fleet managers.
- Hybrid:Dual-powertrain architectures combining electric motor assist with flex-fuel combustion engines are absorbing engineering investment at Toyota's Indaiatuba technical center. ANFAVEA efficiency mandates and São Paulo municipal emissions restrictions are pulling corporate fleet procurement toward hybrid configurations ahead of full electrification readiness.
- Diesel:Compression-ignition engines with high-torque output serve commercial fleet applications in Argentine agricultural zones and Chilean mining corridors.
- Electric:Battery-electric drivetrains with lithium-ion cell packs face infrastructure constraints outside major metropolitan charging networks.
Petrol leads volumes today; Hybrid is climbing the fastest on fleet electrification procurement.
Customer Segment:
Application focus distinguishes individual mobility decisions from centralized procurement governed by total cost of ownership metrics.
- Fleet Operators:Centralized procurement departments at logistics companies, mining conglomerates, and ride-hailing platforms negotiate multi-year supply agreements bundling vehicles, maintenance, and energy costs. Chilean mining sector fleet managers pioneered telematics-integrated contracts enabling usage-based insurance and predictive maintenance scheduling.
- First-Time Buyers:Credit-dependent purchasers accessing concentrated regional banking networks in Brazil's Northeast and Colombia's Andean cities face higher financing spreads than southeastern metropolitan applicants.
- Luxury Buyers:Premium segment purchasers in São Paulo's Jardins district and Mexico City's Polanco neighborhood prioritize advanced driver assistance systems and brand heritage over total cost metrics.
- Used Car Customers:Secondary market participants in Buenos Aires and Santiago acquire depreciated vehicles through informal dealer networks and peer-to-peer platforms.
Fleet Operators lead volumes today; First-Time Buyers are expanding most quickly on credit program extension.
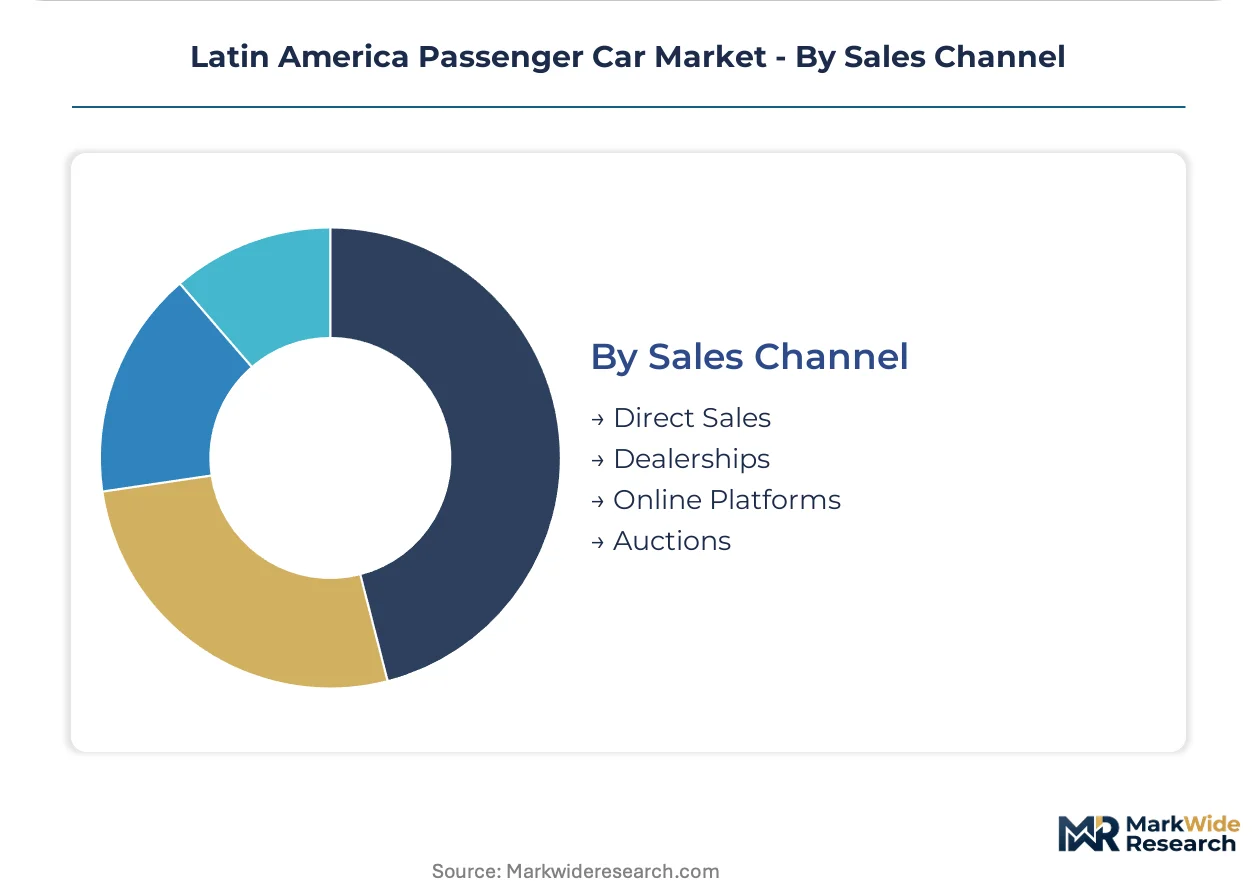
Sales Channel:
Geographic concentration of inventory and financing capability determines channel effectiveness across metropolitan and interior markets.
- Dealerships:Brick-and-mortar networks with captive finance subsidiaries dominate vehicle delivery in Brazil's southeastern industrial corridor, where São Paulo state concentration enables same-day credit approval and immediate inventory access. ANFAVEA-authorized dealers maintain exclusive distribution rights for warranty-backed new vehicles.
- Direct Sales:Manufacturer-owned showrooms and corporate fleet account teams bypass traditional retail markups for large-volume purchasers. Subscription mobility platforms are opening direct procurement channels that reshape volume allocation toward dedicated production lines.
- Online Platforms:Digital marketplaces with virtual configurators and home delivery logistics are penetrating credit-preapproved buyer segments in Mexico City and Santiago.
- Auctions:Wholesale vehicle exchanges with condition grading systems serve dealer inventory replenishment and fleet remarketing cycles.
Dealerships lead volumes today; Direct Sales is gaining share fastest on fleet-as-a-service platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions where Inovar-Auto compliance costs and USMCA rules of origin create assembly advantages over import tariffs. Brazilian and Mexican plants capture investment flows as regional content requirements tighten.
Brazil
Fleet electrification procurement and flex-fuel hybrid adoption drive assembly expansion. ANFAVEA efficiency mandates under Inovar-Auto successor frameworks compel localized powertrain sourcing. São Bernardo do Campo and Betim industrial corridors concentrate SUV and hybrid production lines.
Mexico
USMCA automotive rules of origin pull component integration toward higher-value assemblies. SEMARNAT emissions certification timelines compress product launch windows against competitor cycles. Guanajuato and Querétaro industrial corridors strengthen cross-border supply linkages with North American markets.
Argentina
Credit-dependent first-time buyer segments sustain entry-level hatchback demand in Buenos Aires metropolitan zones. The country's national automotive regulator maintains diverging crash-test protocols from Mercosur partners. Córdoba and Buenos Aires provinces anchor sedan and compact vehicle assembly.
Chile
Telematics-integrated fleet procurement from mining sector conglomerates reshapes commercial vehicle specifications. Santiago's municipal emissions restrictions tighten ahead of interior highway corridor readiness. Antofagasta and Santiago metropolitan clusters concentrate heavy-duty and executive transport pools.
Colombia
Andean passenger car density gaps below southern cone levels create white space for entry-level hybrid portfolios. Bogotá's pico y placa restrictions tighten circulation for conventional powertrains. Bogotá and Medellín industrial zones absorb emerging subscription mobility platform investment.
Latin America Passenger Car Market Competitive Landscape
Japanese and Korean producers anchor hybrid technology tiers; German and American manufacturers hold manufacturing integration positions. The vendor base concentrates around five multinational groups controlling assembly capacity across São Paulo and Mexico City corridors. Three archetypes dominate: flex-fuel hybrid specialists, USMCA-integrated exporters, and entry-level credit-focused assemblers. Capacity expansion and strategic partnerships represent the dominant competitive moves as local content requirements tighten.
Among Japanese manufacturers, Toyota Motor Corporation and Honda Motor Co. exemplify hybrid technology leadership anchored at Brazilian engineering centers. Volkswagen AG and Stellantis NV occupy positions spanning manufacturing integration and entry-level portfolio breadth. Hyundai Motor Company represents Korean manufacturing scale competing across multiple fuel-type segments. These anchors reflect how regulatory alignment with ANFAVEA and USMCA provisions determines competitive positioning.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Nissan Motor Co. |
| Volkswagen AG |
| Renault Group |
| Hyundai Motor Company |
| Stellantis NV |
| Ford Motor Company |
| Honda Motor Co. |
| General Motors Company |
| Others |
Supply & Pricing Matrix
Fleet electrification procurement in São Paulo and Mexico City is compressing margins on conventional powertrains while elevating hybrid premiums, compelling assemblers to rebalance production mix and supplier payments toward flex-fuel electric architectures.
Pricing Analysis
Dealer markup layers in Brazil's southeastern corridor absorb financing spread differentials between captive finance subsidiaries and regional banking networks. Three-tier pricing structure across premium, standard, and economy levels stratifies by ADAS certification grade and after-sales service bundling. Price erosion runs through entry-level hatchback segments as credit access fragmentation intensifies competition for first-time buyers. Fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership contracting, while Northeast Brazilian retail applicants face steepest financing premiums.
Supply Chain Analysis
Freight cost differentials between Asian lithium-ion cell ports and Brazilian assembly plants are amplifying working capital requirements for hybrid powertrain inventory. Component sourcing concentrates in China, South Korea, and Japan for battery cells, with Minas Gerais and Paraná supplier clusters capturing localized electric motor and inverter assembly. Raw material dependencies span lithium carbonate, rare earth magnets, and high-grade steel sheet. Single-source vulnerability in semiconductor gate drivers for inverter control modules threatens production continuity. Distribution runs through ANFAVEA-authorized dealer networks with captive logistics for warranty-backed vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America passenger car market functions as a geographic-arbitrage play where Brazilian Inovar-Auto local content requirements create cost barriers against Mexican USMCA-integrated export capacity, rewarding assembly footprint in both jurisdictions.
For Market Incumbents: Acquire flex-fuel hybrid calibration engineering capabilities to defend against Toyota's regional technology leadership. Deepen component sourcing from Minas Gerais supplier parks to satisfy ANFAVEA efficiency mandates. Secure long-term lithium supply agreements to offset Asian cell concentration risk. For New Entrants and Emerging Players: Battery-electric drivetrains with subscription mobility platform integration offer a technology-first wedge into Bogotá's pico y placa restricted zones where charging infrastructure gaps exclude incumbent OEMs. Target Colombian entry-level hybrid portfolios through direct fleet procurement channels bypassing established dealer networks. For Investors and Strategic Acquirers: Asymmetric upside sits with flex-fuel plug-in hybrid specialists positioned at the convergence of Brazil's ethanol distribution network and municipal emissions restrictions. Long-term viability hinges on Mercosur-EU trade agreement automotive chapter outcomes. Monitor SEMARNAT certification timeline compression as inflection indicator for Mexican assembly capacity utilization.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell volumes from Asian manufacturers for Brazilian hybrid production lines. |
| Flex-Fuel Powertrain Localization | Aligns assembly capacity with ANFAVEA efficiency mandates and ethanol infrastructure maturity. |
| Subscription Mobility Platform Partnership | Opens direct procurement channels bypassing traditional ANFAVEA-authorized dealer networks. |
| ADAS Certification Investment | Satisfies ANVISA safety requirements expanding to lane-keeping and automatic emergency braking. |
| Geographic Manufacturing Footprint | Balances Brazilian Inovar-Auto compliance against Mexican USMCA rules of origin advantages. |
Research Methodology
Coverage spans Brazil, Mexico, Argentina, Chile, and Colombia, with primary inputs from each market combining interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operations managers, and dealership network heads. Secondary validation draws from ANFAVEA production databases, vehicle registration data, customs trade records, and SEMARNAT emissions filings. Bottom-up assembly capacity modeling triangulates against top-down demand segmentation across propulsion architectures.
Rate-of-change decomposition separates volume growth into fleet electrification procurement, first-time buyer credit expansion, and replacement cycle timing across the projection horizon. Segmentation dimensions span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from production capacity utilization trends, regulatory compliance cost trajectories, and ethanol-electric convergence technology adoption curves.
The model holds under stable Inovar-Auto successor framework provisions and USMCA rules of origin continuity; deviation in Mercosur-EU trade agreement automotive chapters or lithium supply contract renegotiations would shift assembly investment flows. Forecasts reflect assumptions on infrastructure buildout timelines and credit market depth. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
Luxury Car Market
Passenger Vehicles
Large Suvs Market
Passenger Vehicles
Three-Wheeler Vehicle Market
Passenger Vehicles
China Luxury Car Market
Passenger Vehicles
Ghana Automobile Market
Passenger Vehicles
North American Lightweight Car Market
Passenger Vehicles
India Passenger Car Market
Passenger Vehicles
North America MUV Rental Market
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
Luxury Vehicles Market
Passenger Vehicles
Family Car Market
Passenger Vehicles
Inland Water Passenger Transport Market
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
Global SUV Market