
 Global Printing Toners Market | 2026-2036
Global Printing Toners Market Size, Share, and Industry Trends Forecast 2026-2036
Global Printing Toners Market Foresight
Polymerization-based toner manufacturing is reconfiguring particle morphology control and enabling narrower particle size distributions for sharper image resolution. HP Inc. leverages its captive printer installed base to secure recurring consumables revenue across enterprise fleets. Xerox Corporation anchors its position through vertical integration into chemically produced toner feedstock. Canon Inc. differentiates via proprietary spherical toner architectures optimized for high-speed color production presses.
Printing toner comprises a dry powder mixture of polymer resin, carbon black or color pigments, charge control agents, and fusing additives, engineered to electrostatically adhere to photoconductive drums and permanently bond to paper substrates under heat and pressure. Laser technology dominates commercial throughput due to its cost efficiency at volume, while electrophotographic methods retain strong positioning in transactional and direct mail applications. Specialty toner formulations command premium positioning as security printing and textured finish requirements expand across packaging and label segments.
EPA emission standards constrain solvent use in toner resin production across the United States, while REACH registration requirements in Europe mandate granular chemical substance disclosure throughout supply chains. Japan's METI enforces energy efficiency benchmarks that indirectly shape fusing temperature specifications and polymer glass transition point selection. Stakeholders must monitor evolving chemical compliance obligations alongside raw material substitution timelines to preserve market access and avoid reformulation cost shocks.
Market Dynamics
Polymerization manufacturing methods are compressing particle size tolerances and forcing legacy pulverization plants into accelerated retooling cycles across supplier networks.
Growth Catalysts
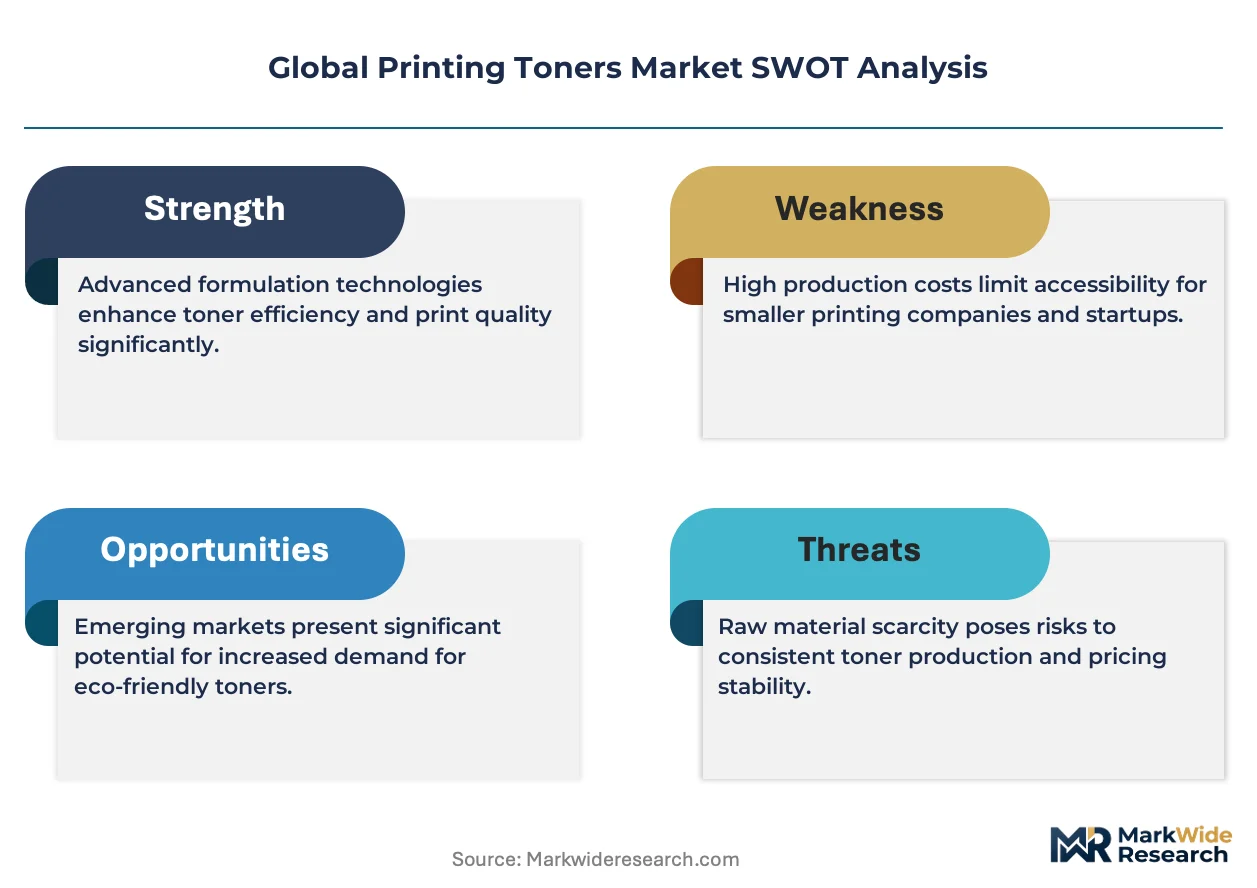
- REACH chemical disclosure mandates:European ECHA registration requirements are filtering out non-compliant resin suppliers and consolidating qualified vendor pools for multinational print fleet operators.
- China manufacturing cluster expansion:Domestic laser printer assembly lines in Dongguan and Suzhou are pulling chemically produced toner volumes upward through localized supply contracts.
- Security printing applications:Government document authentication programs and anti-counterfeit packaging specifications are creating formulation premiums for specialized magnetic and infrared-responsive toner variants.
Market Restraints
- Petroleum-derived resin cost volatility:Styrene-acrylic copolymer feedstock prices swing with crude oil benchmarks, compressing margin predictability for non-integrated compounders.
- Single-source pigment concentration:High-purity carbon black supply for monochrome formulations clusters among three multinational chemical producers, creating qualification bottlenecks during capacity constraints.
- Fusing temperature floor:Polymer glass transition points cannot drop below energy efficiency thresholds set by Japan's METI without sacrificing image permanence on coated stocks.
Strategic Opportunities
- India commercial print modernization:BIS certification alignment and PLI scheme incentives for domestic electronics manufacturing are opening cartridge assembly localization prospects.
- Textured finish packaging:Specialty toner formulations enabling tactile security elements on folding cartons command price multiples in cosmetics and pharmaceutical segments.
- Remanufacturing regulatory tailwinds:EU Green Deal circular economy requirements and extended producer responsibility frameworks are legitimizing refurbished cartridge channels against OEM resistance.
Industry Challenges
- Polymerization process engineering talent:Suspension and emulsion polymerization expertise for sub-10-micron particle control remains concentrated among Japanese and German specialty chemical workforces.
- Cross-border formulation registration:Divergent EPA volatile organic compound limits, REACH substance restrictions, and China's GB standards force parallel compliance tracks that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Printing Toners Market |
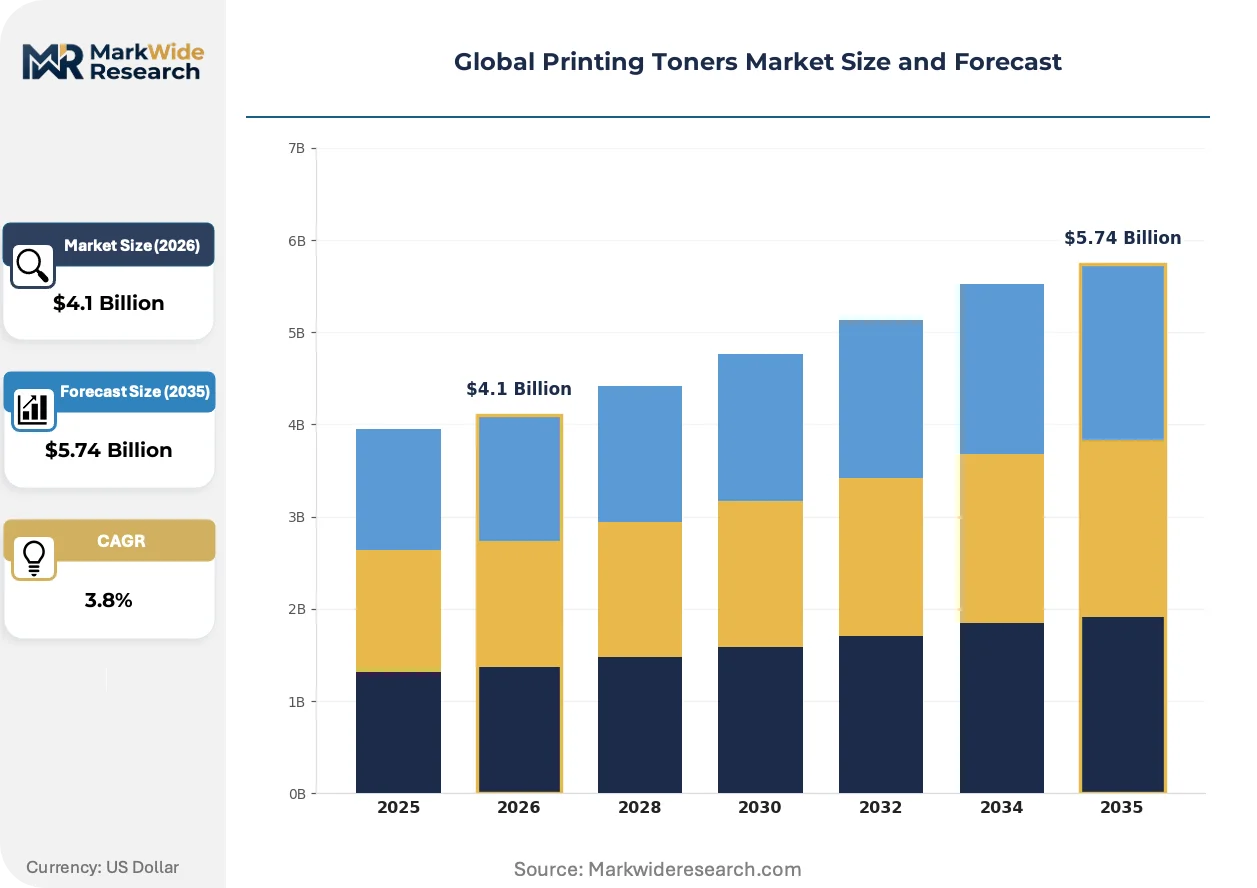
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $5.74 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Toner, Cyan Toner, Magenta Toner, Yellow Toner, Specialty Toner Technology: Laser, Solid Ink, Inkjet, Thermal Transfer, Electrophotographic Application: Commercial Printing, Office Printing, Packaging, Textile Printing, Label Printing End User: Corporate Offices, Print Shops, Educational Institutions, Government Agencies, Design Studios |
| Companies Covered | HP Inc., Xerox Corporation, Canon Inc., Konica Minolta, Epson, Panasonic, Brother International Corporation, Lexmark International, ACM Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Printing Toners Market Shifts & Advancements
Chemical production methods are displacing mechanical grinding across toner manufacturing, while regulatory chemical frameworks and procurement centralization reshape competitive access and pricing structures.
Polymerization-based suspension manufacturing is digitizing particle morphology control through closed-loop feedback systems that adjust resin cross-linking in real time. Commercial print service providers in Germany and Japan are adopting these chemically produced toners fastest, locking in multi-year supply agreements that exclude pulverization-based competitors from fleet refresh cycles.
REACH authorization requirements for substances of very high concern are forcing reformulation of charge control agents across European supply chains. Toner compounders must substitute legacy quaternary ammonium salts with alternative chemistries, extending qualification periods for photoconductor drum compatibility testing by OEMs.
Fleet management centralization among enterprise buyers is compressing vendor counts and unbundling hardware from consumables procurement. Managed print service contracts now specify page-cost guarantees rather than cartridge unit pricing, shifting risk to suppliers who must forecast yield accuracy across variable paper weights and fusing temperatures. This pattern is most visible in United States healthcare and financial services verticals where HIPAA and SEC record retention requirements mandate predictable document output costs.
Global Printing Toners Market Segmentation
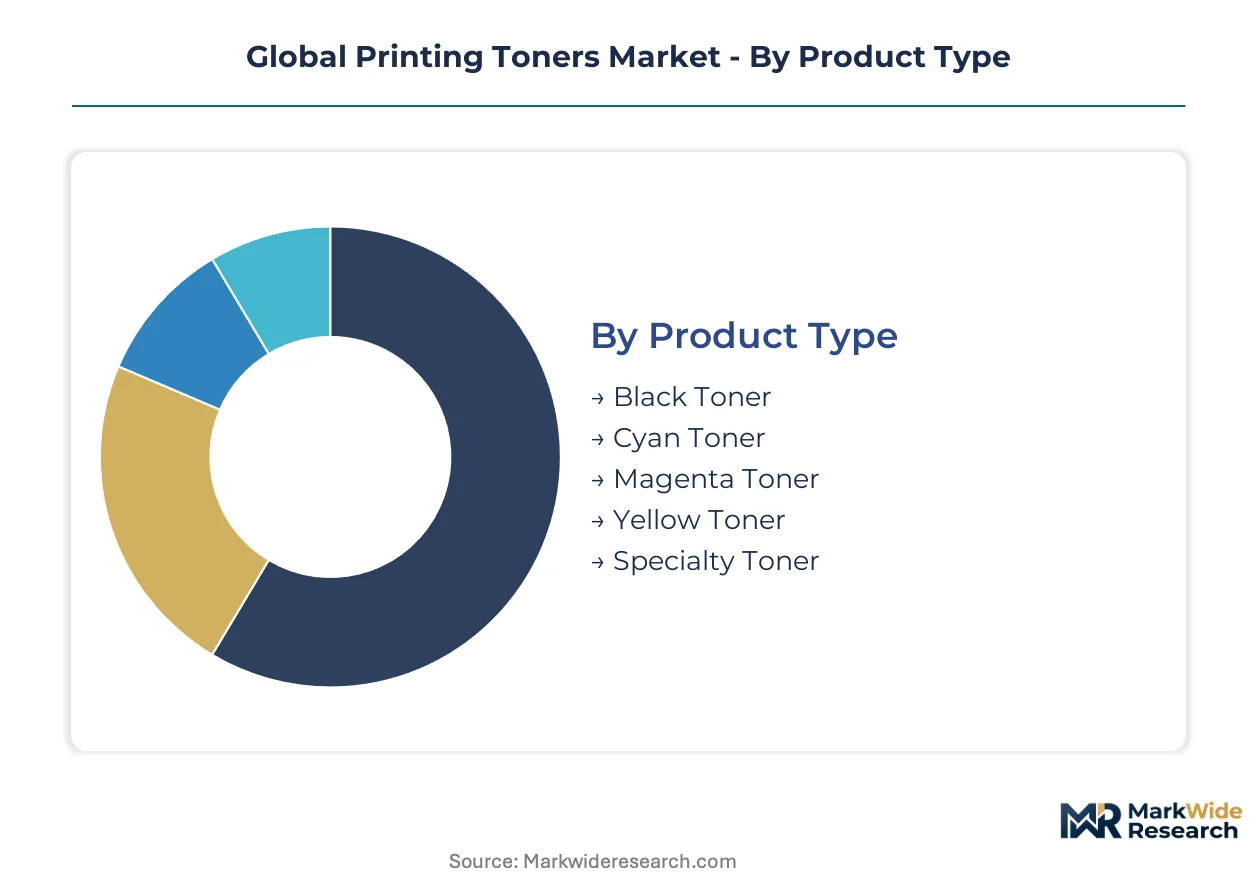
Toner segmentation reveals how formulation chemistry, imaging physics, and end-use durability requirements create distinct supply chain configurations. Each dimension shapes procurement patterns, regulatory exposure, and margin structures differently across commercial and industrial printing environments.
Product Type:
Mature monochrome formulations coexist with emerging color and security-grade chemistries that command formulation premiums.
- Black Toner:Carbon black pigment dispersed in styrene-acrylic resin matrices dominates high-volume transactional printing. Corporate offices in Germany and the United States pull substantial volumes for invoice and statement generation, though petroleum-derived feedstock cost swings compress margin predictability for non-integrated compounders.
- Specialty Toner:Magnetic, infrared-responsive, and tactile formulations enable government document authentication and anti-counterfeit packaging. Security printing applications across China's government procurement channels and EU member state document programs create qualification barriers that filter out commodity suppliers.
- Cyan Toner:Phthalocyanine pigment systems engineered for color accuracy in marketing collateral production.
- Magenta Toner:Quinacridone-based formulations optimized for skin tone reproduction in commercial photography applications.
- Yellow Toner:Isoindoline pigment chemistries balancing lightfastness with fusing temperature compatibility.
Black toner handles the majority of throughput; specialty toner is the fastest mover on share.
Technology:
Cost tier stratification separates capital-intensive polymerization methods from legacy mechanical grinding operations facing accelerated obsolescence.
- Laser:Electrophotographic imaging with dry powder toner transferred via laser-addressed photoconductive drums dominates commercial throughput. Print shops in Japan and the United States favor laser systems for cost efficiency at volume, with fleet management centralization shifting procurement toward page-cost guarantees rather than cartridge unit pricing.
- Electrophotographic:Broad imaging platform encompassing LED array and traditional laser exposure systems for transactional and direct mail applications. Government agencies across multiple geographies specify electrophotographic output for record retention compliance, locking in multi-year consumables contracts.
- Solid Ink:Wax-based phase-change formulations eliminating cartridge waste streams.
- Inkjet:Liquid ink deposition systems competing for short-run color applications.
- Thermal Transfer:Ribbon-based imaging for barcode and label durability requirements.
Laser technology anchors installed base economics; electrophotographic methods retain defensive positioning in compliance-driven verticals.
Application:
Volume concentration in commercial print contrasts with margin expansion in specialized packaging and security segments.
- Commercial Printing:High-volume marketing collateral, direct mail, and publication production consuming chemically produced toner in continuous-feed systems. Print service providers in Germany are adopting polymerization-based formulations fastest, locking in supply agreements that exclude pulverization-based competitors.
- Packaging:Folding carton and corrugated applications requiring tactile finish capabilities and food-contact compliance. Cosmetic and pharmaceutical segments in China and the United States command price multiples for specialty formulations enabling textured security elements.
- Office Printing:Distributed document output across corporate and institutional environments.
- Textile Printing:Transfer paper and direct-to-garment applications with distinct fusing requirements.
- Label Printing:Pressure-sensitive and shrink-sleeve applications demanding abrasion resistance.
Commercial printing concentrates volume throughput; packaging applications are expanding most quickly on value contribution.
End User:
Customer type determines procurement centralization, compliance exposure, and technical specification stringency.
- Corporate Offices:Managed print service contracts consolidating hardware and consumables procurement under page-cost guarantees. Healthcare and financial services verticals in the United States specify HIPAA and SEC-compliant output infrastructure, shifting yield risk to suppliers.
- Print Shops:Independent and franchise operations serving regional commercial print demand with equipment refresh cycles tied to polymerization toner availability.
- Government Agencies:Document authentication and record retention programs with extended qualification periods.
- Educational Institutions:Volume-driven procurement with sustainability preference weighting.
- Design Studios:Color-critical proofing and short-run production with premium tolerance requirements.
Corporate offices dominate contract value concentration; print shops represent the most price-sensitive volume pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise fleet operators in Germany, Japan, and the United States concentrate the largest consumables procurement contracts, while China's manufacturing clusters pull substantial chemically produced toner volumes through localized supply arrangements.
United States
Healthcare and financial services verticals drive managed print service consolidation under HIPAA and SEC record retention mandates. EPA volatile organic compound limits constrain solvent use in resin production. Commercial print operations across Chicago and Dallas-Fort Worth metro areas are locking in multi-year page-cost guarantee contracts that shift yield risk to suppliers.
Germany
Commercial print service providers in Bavaria and North Rhine-Westphalia are adopting polymerization-based formulations fastest. REACH authorization requirements for substances of very high concern are forcing charge control agent reformulation across European supply chains. The Stuttgart industrial corridor hosts specialized chemical compounders qualifying spherical toner architectures for high-speed color production.
China
Domestic laser printer assembly lines in Dongguan and Suzhou manufacturing clusters pull substantial chemically produced toner volumes. GB standards on chemical substance disclosure create parallel compliance tracks alongside REACH and EPA frameworks. Government procurement channels for document authentication programs are creating qualification barriers that filter out commodity suppliers.
Japan
METI energy efficiency benchmarks indirectly shape fusing temperature specifications and polymer glass transition point selection. Suspension and emulsion polymerization expertise for sub-10-micron particle control concentrates among specialty chemical workforces in Nagoya and Osaka. Print shops favor laser systems for cost efficiency at volume, with fleet centralization shifting procurement toward performance guarantees.
India
BIS certification alignment and PLI scheme incentives for domestic electronics manufacturing are opening cartridge assembly localization prospects. Commercial print modernization across Maharashtra and Gujarat is accelerating equipment refresh cycles. Print service providers in Mumbai and Ahmedabad are negotiating supply agreements tied to polymerization toner availability.
Global Printing Toners Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where hardware-captive suppliers face independent chemical compounders. The vendor base stratifies between integrated OEMs with printer installed bases and specialty chemical producers supplying third-party cartridge assemblers. Two strategic archetypes dominate: vertically integrated imaging equipment manufacturers and independent toner compounders with polymerization process expertise. Competitive moves center on backward integration into resin feedstock and geographic expansion through localized supply contracts.
Within the integrated OEM tier, HP Inc., Xerox Corporation, and Canon Inc. exemplify contrasting strategic positions. HP leverages its captive printer installed base to secure recurring consumables revenue across enterprise fleets. Xerox anchors its position through in-house production of chemically produced toner feedstock. Canon differentiates via proprietary spherical toner architectures optimized for high-speed color production presses.
| Leading Market Players |
|---|
| HP Inc. |
| Xerox Corporation |
| Canon Inc. |
| Konica Minolta |
| Epson |
| Panasonic |
| Brother International Corporation |
| Lexmark International |
| ACM Technologies |
| Others |
Supply & Pricing Matrix
Japanese and German specialty chemical workforces controlling suspension polymerization expertise concentrate upstream margin capture, while downstream pricing power accrues to enterprise fleet operators consolidating procurement under page-cost guarantees.
Pricing Analysis
Cost-plus contracts with styrene-acrylic resin feedstock indexation dominate procurement between compounders and integrated OEMs. Pricing stratifies across premium spherical architectures, standard chemically produced formulations, and economy pulverization-based tiers differentiated by particle size tolerance and drum compatibility certification. Cost compression in commodity black toner intensifies as petroleum-derived resin volatility transfers risk to non-integrated suppliers. Print shops represent the most price-sensitive buyer pool, while government security printing contracts tolerate formulation premiums for magnetic and infrared-responsive variants.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for cartridge assembly operations. Raw material sourcing draws from Japanese polymerization expertise, German charge control agent production, and Chinese domestic manufacturing clusters for laser printer assembly feedstock. High-purity carbon black for monochrome formulations rests on concentrated multinational chemical production, creating single-source vulnerability during capacity constraints. Distribution runs through OEM captive channels, independent remanufacturers, and third-party cartridge assemblers serving regional print service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet management centralization among enterprise buyers has shifted bargaining power decisively toward procurement functions, with healthcare and financial services verticals consolidating vendor counts under multi-year page-cost guarantees.
For Market Incumbents: Build formulation moats around REACH-compliant charge control agent substitutes ahead of legacy quaternary ammonium salt phase-outs. Secure backward integration into resin feedstock production to buffer styrene-acrylic copolymer cost volatility, while locking print service providers into multi-year supply agreements that exclude pulverization-based competitors from equipment refresh cycles. For New Entrants and Emerging Players: India's commercial print modernization presents the most penetrable white-space target, with BIS certification alignment and PLI scheme incentives enabling cartridge assembly localization. Pursue specialty toner formulation partnerships with cosmetic and pharmaceutical packaging segments commanding price multiples for tactile security elements, leveraging polymerization process licensing from Japanese or German technology holders. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialty chemical compounders holding suspension polymerization expertise for sub-10-micron particle control. Long-term viability hinges on regulatory compliance adaptability across divergent EPA, REACH, and GB chemical disclosure frameworks. Watch for EU Green Deal circular economy enforcement legitimizing remanufactured cartridge channels as the inflection signal for refurbished toner market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Feedstock | Captive styrene-acrylic supply buffers HP and Xerox against petroleum cost volatility. |
| Polymerization Process Licensing | Japanese and German technology transfers enable Indian and Chinese compounder qualification. |
| REACH-Compliant Formulation Reformulation | Charge control agent substitution preserves European market access for qualified suppliers. |
| Remanufacturing Channel Partnership | EU Green Deal alignment legitimizes refurbished cartridge distribution against OEM resistance. |
| Security Printing Qualification | Government document authentication contracts in China and EU member states filter out commodity competitors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with toner compounder R&D directors, OEM procurement managers, print service provider operations heads, and regulatory affairs specialists across Germany, Japan, China, and the United States. Secondary validation drew from EPA emission standard filings, ECHA REACH registration databases, METI energy efficiency benchmarks, and SEC 10-K disclosures from integrated imaging equipment manufacturers. Bottom-up volume modeling across monochrome, color, and specialty toner formulations triangulated against top-down macroeconomic indicators and print industry output indices.
Calibration against historical price realizations and yield performance data informed projection assumptions across the analysis window. Segmentation dimensions modeled include product type chemistry, polymerization versus pulverization manufacturing technology, commercial print versus packaging versus office application, and corporate office versus print shop versus government agency end-user archetype. CAGRs were derived from regression analysis of consumables pull-through against laser printer installed base expansion, with specific inputs including fusing temperature specification evolution and petroleum-derived resin cost trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic compounders or accelerated EU circular economy enforcement would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Global Chemical Indicator Inks Market
Printing Inks
Lithographic Printing Chemicals Market
Printing Inks
Solvent-Based Inks Market
Printing Inks
Specialty Ink Market
Printing Inks
Rapid Liquid Printing Market
Printing Inks
Printing Inks Market
Printing Inks
Waterborne Ink Market
Printing Inks
Rotogravure Printing Inks Market
Printing Inks
Global Light Changing Packaging Inks Market
Printing Inks
Returnable Glass Bottle Ink Market
Printing Inks
Flexible Letterpress Printing Ink Market
Printing Inks
Thermal Inkjet Inks Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
Food Marking Inks Market
Printing Inks
Screen Printing Mesh Market
Printing Inks
Molecular Ink Market