
 Food Grade Inks Market | 2026-2036
Food Grade Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Inks Market Analysis
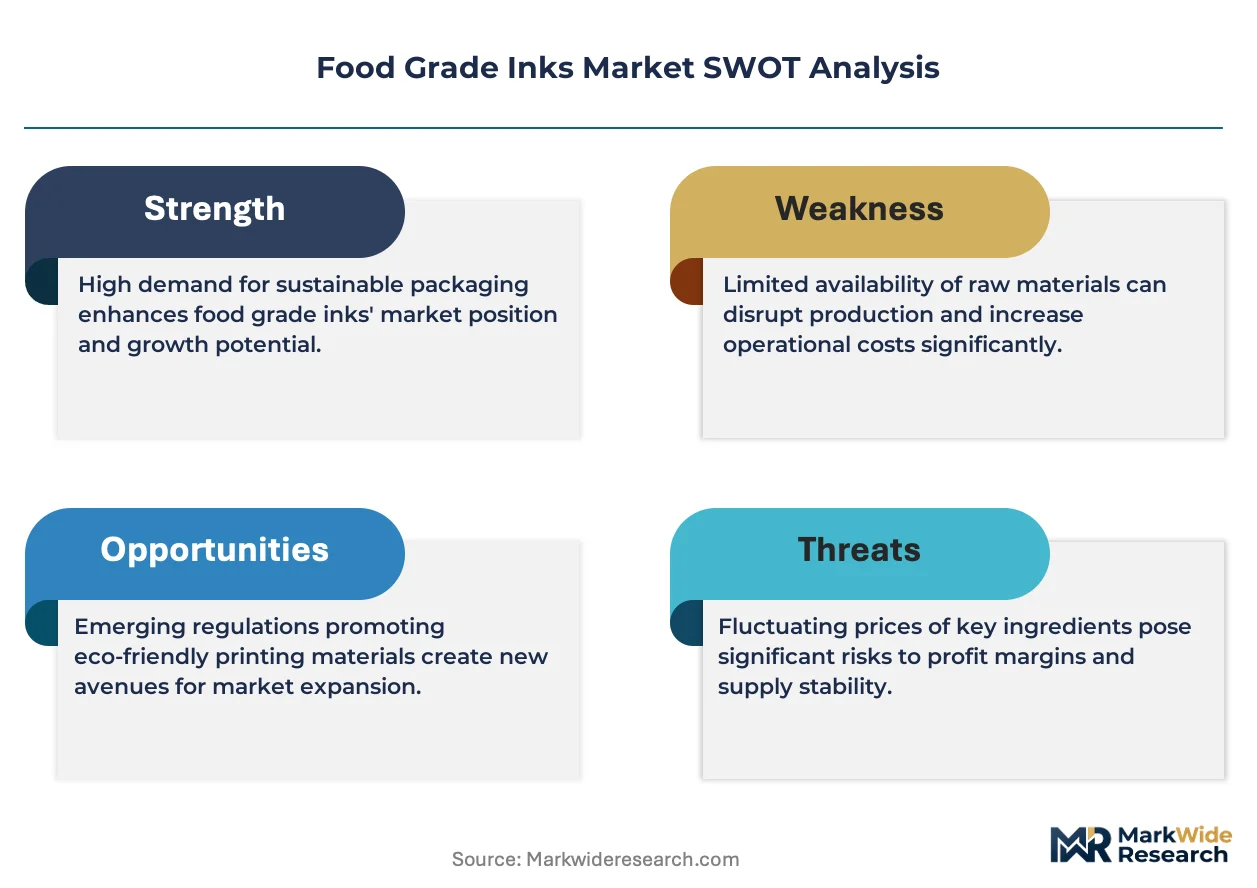
EU REACH is decoupling formulation costs from commodity ink economics by forcing substitution of legacy pigment classes. Sun Chemical leverages captive resin synthesis to absorb these input shocks. Siegwerk Druckfarben AG & Co. KGaA anchors its position through dedicated food-contact laboratories in Hamburg and Jakarta. DIC Corporation competes via backward integration into high-purity pigment manufacturing.
Food grade inks are formulated printing systems meeting strict migration limits for direct or indirect food contact, typically specified at 10 ppb or lower for individual substances under EU framework. These compositions exclude heavy metals, aromatic amines, and photoinitiators above threshold limits while maintaining adhesion to plastic, metal, glass, and paper substrates. Water-based formulations dominate volume due to lower volatile organic compound profiles and compatibility with absorbent packaging stocks, though UV-curable systems capture margin pools in premium beverage and confectionery segments where rub resistance and shelf appeal command price premiums. Flexible packaging applications sustain the largest addressable base as retort pouches and lidding films multiply SKUs across chilled and ambient food categories.
FDA indirect food additive regulations under 21 CFR 175.105 and the EU Printing Ink Regulation coordinate compliance burdens across Atlantic supply chains, with EFSA scientific opinions periodically resetting acceptable daily intake benchmarks. BIS certification requirements in India and China's GB standards for food-contact materials add parallel testing protocols that fragment qualification timelines. Stakeholders must monitor regulatory divergence between migration testing methodologies as the gap between European and North American acceptable limits widens for emerging photoinitiator chemistries.
Market Dynamics
EU REACH is decoupling formulation costs from commodity ink economics by forcing substitution of legacy pigment classes, compelling manufacturers to absorb input shocks through captive resin synthesis or backward integration into high-purity pigment streams.
Growth Catalysts
- Direct-print beverage formats:Brands switching to glass and aluminum packaging lines require food-contact compliant inks for shelf appeal and regulatory adherence.
- Swissmedic-grade export channels:German confectionery and dairy exporters demand certified formulations for premium European market access.
- Retort pouch SKU multiplication:Flexible packaging applications across chilled and ambient categories sustain volume demand for migration-compliant lidding films.
Market Restraints
- Pigment input cost volatility:Substitution of heavy metal and aromatic amine-based colorants under REACH disrupts legacy supply economics.
- Supply concentration in resin synthesis:Captive production capabilities cluster among integrated majors, fragmenting mid-tier access.
- Photoinitiator technical limitations:UV-curable systems face migration threshold compression as EFSA resets acceptable daily intake benchmarks.
Strategic Opportunities
- India BIS certification whitespace:Domestic food-contact material standards create first-mover advantage for qualified suppliers.
- UV-LED technology convergence:Energy-curable platforms paired with low-migration photoinitiators unlock premium beverage segment margin pools.
- E-commerce direct channel emergence:Specialty ink procurement bypasses traditional distributor networks for mid-size converters.
Industry Challenges
- Migration testing skill scarcity:Analytical chemists capable of simultaneous EU and FDA protocol execution command premium compensation.
- Dual certification capex intensity:Parallel BIS and GB standard qualification timelines require dedicated laboratory infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Inks Market |
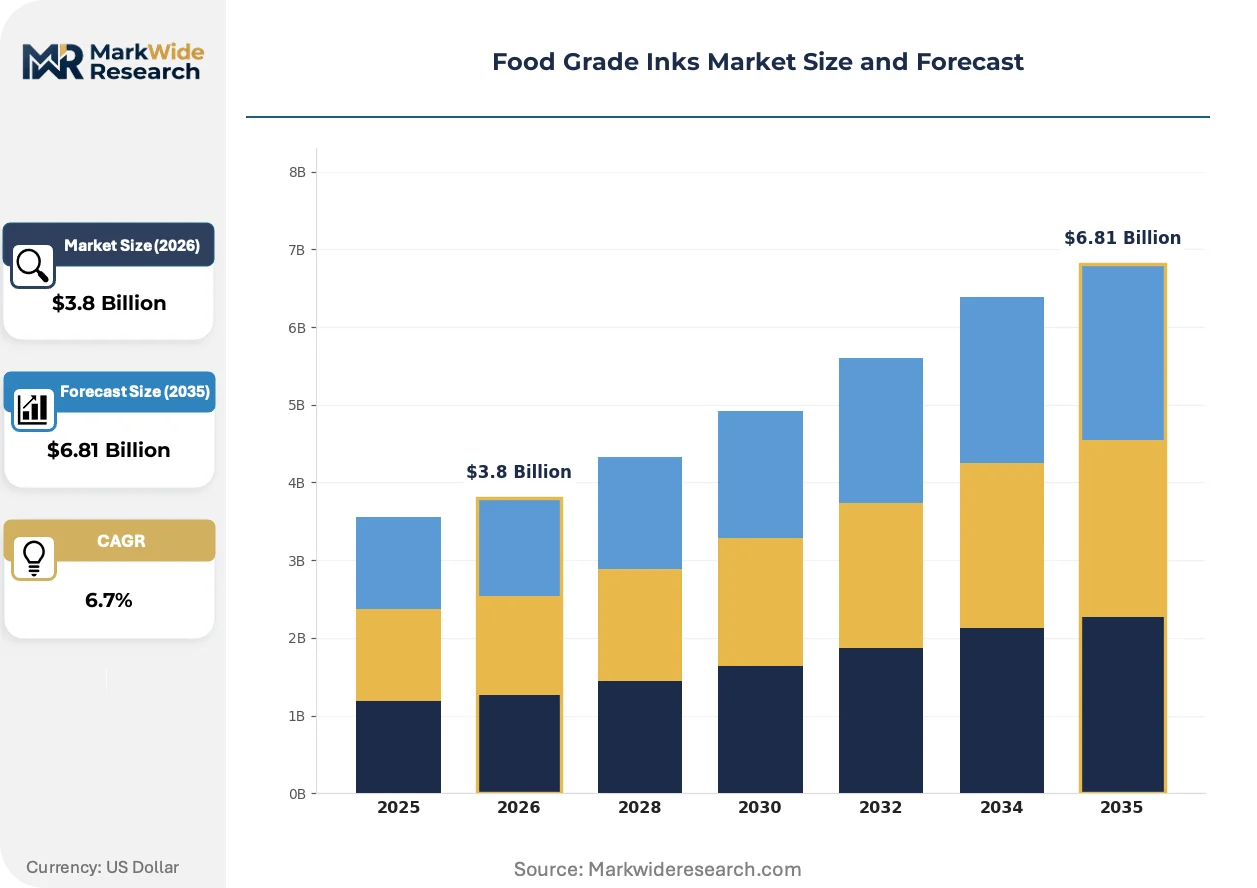
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, UV-Curable, Oil-Based Packaging Type: Flexible Packaging, Rigid Packaging, Labels, Tags Application: Food Packaging, Beverage Packaging, Labeling, Printing End User: Food Producers, Beverage Manufacturers, Printing Companies, Packaging Firms |
| Companies Covered | Sun Chemical, Flint Group, Siegwerk Druckfarben AG & Co. KGaA, Toyo Ink SC Holdings Co., Ltd., Sakata INX Corporation, Huber Group, DIC Corporation, ALTANA AG, INX International Ink Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Inks Market Emerging Trajectories
Water-based and UV-curable formulation platforms are converging around ultra-low migration specifications, compressing the performance gap between cost-driven absorbent stocks and premium rub-resistant finishes.
Hybrid water-UV systems are unifying the adhesion benefits of aqueous carriers with the instant cure and durability of energy-curable chemistries. Premium beverage and confectionery converters are adopting these platforms at accelerated qualification cycles. The technology is unifying previously separate equipment investments, enabling single-pass production across plastic, metal, and glass substrates.
REACH Annex XVII restrictions on aromatic amines and heavy metals are tightening substance-specific migration limits below 10 ppb thresholds. Formulators must redesign pigment portfolios and validate alternative chemistries through extended extraction protocols. Flexible packaging converters serving EU export markets are absorbing the longest recertification timelines and steepest reformulation costs.
Certification-driven procurement preferences are displacing price-primary supplier selection among multinational food brands. Technical buyers now weight Swissmedic, FDA, and BIS compliance documentation equally with unit economics in vendor scorecards. This behavioral shift concentrates contract volumes with qualified suppliers in Germany and Switzerland while marginalizing uncertified regional competitors.
Food Grade Inks Market Segmentation
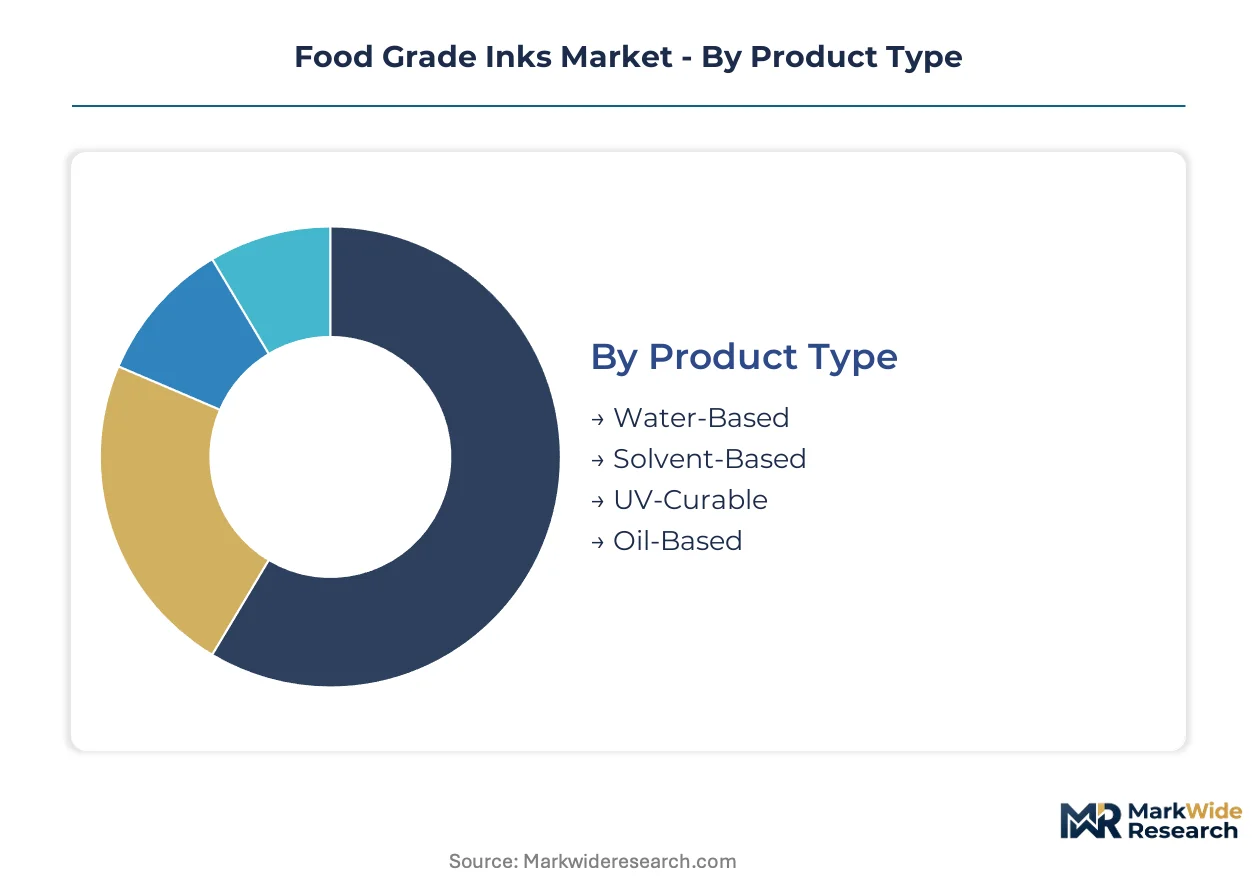
Food grade ink selection hinges on substrate compatibility and migration limits. Formulators must match chemistries to packaging formats while satisfying divergent regulatory thresholds across export destinations. Segmentation reveals where volume economics clash with premium specification requirements.
Product Type:
Water-based systems dominate tonnage while UV-curable platforms command margin premiums in beverage and confectionery segments.
- Water-Based:Aqueous carrier systems with low volatile organic compound profiles suit absorbent paper and board stocks. Flexible packaging converters across Germany and France specify these formulations for chilled dairy lidding films where cost efficiency outweighs rub resistance demands.
- UV-Curable:Energy-curable compositions with photoinitiator packages deliver instant cure and premium shelf appeal. Beverage brands in Switzerland and Austria specify these for direct-print aluminum cans where EFSA migration limits for photoinitiator breakdown products are tightening fastest.
- Solvent-Based:Hydrocarbon-carrier systems retain niche use in non-absorbent plastic film applications where water-based adhesion fails.
- Oil-Based:Vegetable oil carrier formulations serve specific confectionery wrapping applications requiring grease resistance.
Today's leader: Water-Based. Tomorrow's challenger: UV-Curable.
Packaging Type:
Flexible formats multiply SKUs while rigid formats concentrate value in premium export channels.
- Flexible Packaging:Retort pouches, lidding films, and flow-wrap structures constitute the largest addressable base. German confectionery exporters demand Swissmedic-grade compliant inks for premium chocolate and biscuit packaging destined for Swiss and Austrian retail channels.
- Rigid Packaging:Glass and aluminum direct-print applications concentrate value in beverage segments. Italian mineral water and French wine producers specify migration-compliant UV systems for shelf differentiation in domestic and export markets.
- Labels:Pressure-sensitive and shrink-sleeve formats require adhesion to varied substrates with indirect food contact compliance.
- Tags:String-tie and adhesive formats for fresh produce and bakery items occupy lower specification tiers.
Flexible Packaging holds volume dominance. Rigid Packaging climbs fastest on beverage premiumization.
Application:
Beverage packaging lines are switching to direct-print formats faster than food packaging converters.
- Beverage Packaging:Direct-print glass and aluminum formats require compliant inks for regulatory adherence and shelf appeal. German breweries and Austrian soft drink producers are retrofitting lines to eliminate label application steps.
- Food Packaging:Flexible and rigid food containers sustain baseline demand. French dairy and Italian pasta exporters specify compliant formulations for EU internal market distribution.
- Labeling:Indirect contact applications face lower migration thresholds but require substrate versatility across paper, film, and foil stocks.
- Printing:Specialty decorative and informational printing on food-contact materials spans secondary packaging tiers.
Beverage Packaging is expanding most quickly. Food Packaging retains structural volume.
End User:
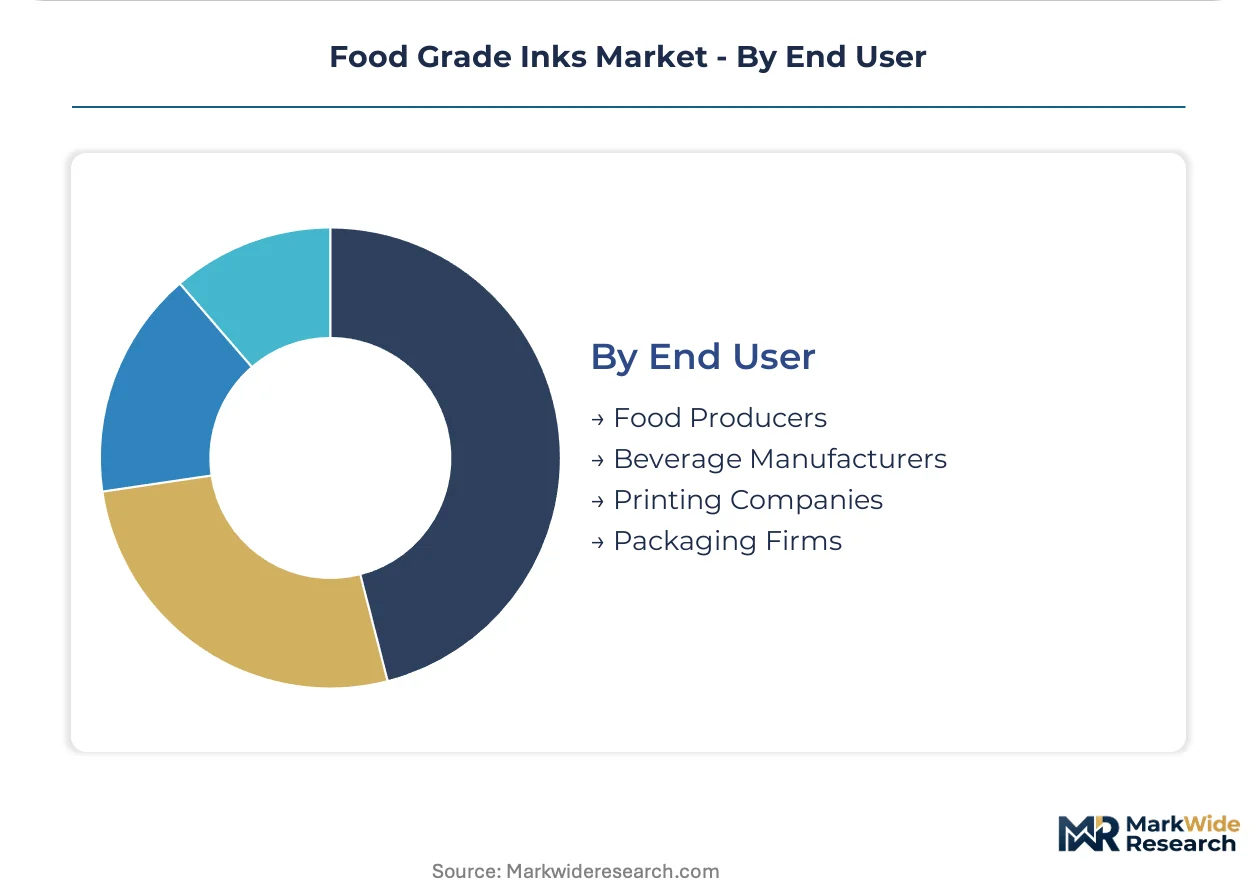
Packaging firms and beverage manufacturers drive specification intensity while printing companies face margin compression.
- Beverage Manufacturers:Brand owners in Germany, Switzerland, and Austria are internalizing compliance requirements and auditing ink suppliers directly. Mineral water and craft beer producers specify Swissmedic-grade documentation for premium positioning.
- Packaging Firms:Integrated converters serving multinational food brands concentrate procurement with qualified suppliers. Hamburg-based flexible packaging specialists demand batch-level migration test certificates for retort pouch production.
- Food Producers:Confectionery and dairy exporters in Germany and France specify compliant inks for premium channel access.
- Printing Companies:Independent converters face qualification cost barriers and distributor margin erosion.
Beverage Manufacturers set the specification pace. Packaging Firms consolidate supply relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized analytical chemists capable of simultaneous EU and FDA protocol execution concentrate in Germany, Switzerland, and the United States, anchoring regional compliance capabilities and migration testing infrastructure.
Germany
Confectionery and dairy exporters in Hamburg and North Rhine-Westphalia drive Swissmedic-grade certification demand for premium chocolate and biscuit packaging. ECHA REACH enforcement tightens aromatic amine migration limits below 10 ppb, forcing pigment portfolio redesigns. Flexible packaging specialists in Hamburg demand batch-level migration test certificates for retort pouch production serving Austrian and Swiss retail channels.
United States
Craft beverage producers in Colorado and California retrofit direct-print aluminum can lines to eliminate label application steps. FDA indirect food additive regulations under 21 CFR 175.105 coordinate compliance burdens with Atlantic supply chains. Migration testing laboratories in Greater Boston and the Pacific Northwest specialize in dual EU-FDA protocol execution for multinational brand owners.
Switzerland
Mineral water and premium food brands in Zurich and Geneva anchor Swissmedic-grade specification intensity for direct-print glass formats. Swissmedic certification requirements exceed baseline EU thresholds, creating procurement preference concentration among qualified suppliers. Printing ink formulators in Basel maintain dedicated food-contact laboratories serving German and Austrian export markets.
China
Flexible packaging converters in the Yangtze River Delta and Pearl River Delta face parallel GB standards qualification for food-contact materials. SAMR and NMPA coordination tightens domestic migration testing protocols for retort pouch exports to European markets. Pigment manufacturers in Shandong Province invest in high-purity production streams to absorb REACH-driven input cost volatility.
India
Mid-size converters in Maharashtra and Gujarat confront BIS certification whitespace as domestic food-contact material standards formalize. FSSAI and BIS alignment creates first-mover advantage for qualified suppliers entering specialty ink procurement channels. Mumbai-based packaging firms absorb dual certification capex intensity for parallel EU and domestic market access.
Food Grade Inks Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base clusters around three strategic archetypes: integrated pigment-to-ink manufacturers with captive resin synthesis, dedicated food-contact laboratories with certification-heavy service models, and regional converters with distributor-dependent access. Dominant competitive moves include backward integration into high-purity pigment streams and dedicated laboratory infrastructure for simultaneous multi-jurisdiction qualification.
Within the integrated manufacturing tier, Sun Chemical and DIC Corporation exemplify archetypes with upstream control over input chemistry. Siegwerk Druckfarben AG & Co. KGaA anchors the certification-service specialist position. These three occupy differentiated competitive spaces based on supply chain depth versus regulatory service intensity rather than direct product rivalry.
| Leading Market Players |
|---|
| Sun Chemical |
| Flint Group |
| Siegwerk Druckfarben AG & Co. KGaA |
| Toyo Ink SC Holdings Co., Ltd. |
| Sakata INX Corporation |
| Huber Group |
| DIC Corporation |
| ALTANA AG |
| INX International Ink Co. |
| Others |
Supply Flow & Price Mechanics
EU REACH Annex XVII restrictions on aromatic amines and heavy metals gate qualified supply and premium-tier pricing access, forcing pigment portfolio redesigns that concentrate certified formulation premiums among integrated manufacturers with captive resin synthesis capabilities.
Pricing Analysis
Bundled certification-plus-formulation services command 25-40% premiums over unbundled commodity ink transactions. Three-tier pricing structure across Swissmedic-grade premium, FDA-compliant standard, and economy non-certified levels separates migration-tested batches from basic compliant stocks. Price differentiation hinges on certification depth and volume scale, with beverage manufacturers absorbing the steepest premiums for photoinitiator-compliant UV systems. Pricing pressure stems from REACH-driven pigment substitution costs, while independent printing companies show highest price sensitivity against integrated packaging firms.
Supply Chain Analysis
Freight cost volatility from Shandong Province pigment manufacturers to European formulators has compressed margin buffers for non-integrated buyers. Raw material supply concentrates in China, Germany, and Japan, with high-purity pigment streams and specialized photoinitiator packages anchoring input dependencies. The chain faces single-source vulnerability in EU-compliant resin synthesis, where captive production capabilities cluster among majors. Distribution runs through qualified converter networks rather than open distributor channels, with batch-level migration certificates accompanying each shipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Food Grade Inks Market compounds steadily as regulatory migration thresholds tighten predictably across EU, US, and Asian jurisdictions, forcing recurring reformulation cycles that concentrate value with qualified suppliers.
For Market Incumbents: Cement market position through backward integration into high-purity pigment manufacturing and dedicated food-contact laboratory infrastructure in Hamburg or Basel. Absorb REACH-driven input cost volatility via captive resin synthesis rather than passing through price increases. Expand certification service capabilities to capture Swissmedic-grade premium tiers before mid-tier competitors qualify. For New Entrants and Emerging Players: Begin with BIS certification whitespace in Maharashtra and Gujarat, where domestic food-contact standards formalize ahead of qualified supplier penetration. Target mid-size flexible packaging converters serving export markets with dual EU-India compliance needs. Lead with e-commerce direct channel procurement models that bypass traditional distributor networks and compress customer acquisition costs. For Investors and Strategic Acquirers: Roll-up economics work for regional certification-heavy specialists because migration testing skill scarcity and dual-capex intensity fragment mid-tier competitive viability. Platform consolidation across German and Swiss laboratory assets offers 5-10 year visibility as regulatory divergence widens acceptable daily intake benchmarks. Watch EFSA photoinitiator opinion resets as the signal for accelerated UV-curable system obsolescence and replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Manufacturing | Captures margin pools as REACH forces substitution of legacy colorant classes. |
| Food-Contact Laboratory Certification Investment | Enables simultaneous EU-FDA-BIS protocol execution for multinational brand owners. |
| UV-LED Technology Platform Development | Unlocks premium beverage segment access as EFSA tightens photoinitiator thresholds. |
| Geographic Expansion to India BIS Whitespace | Captures first-mover advantage before domestic standards formalize completely. |
| E-Commerce Direct Channel Establishment | Bypasses distributor margin erosion for mid-size converter procurement relationships. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ink formulation chemists, flexible packaging procurement leads, beverage brand technical buyers, and regulatory affairs specialists at EFSA and FDA with secondary validation from EU REACH substance restriction databases, BIS food-contact material notifications, and customs trade flow records. Bottom-up SKU-level volume estimates triangulated against top-down market sizing from pigment manufacturer capacity disclosures.
Segment-weighting applied product type, packaging format, application, and end-user dimensions across the projection horizon. CAGRs derived from regression analysis of historical migration limit tightening patterns correlated with reformulation cycle frequencies. Modeled inputs included REACH Annex XVII substance restriction timelines, Swissmedic certification queue lengths, and UV-LED equipment installation rates at European beverage converters.
Several conditions sit outside the modeled scope, including unannounced EFSA scientific opinion resets, abrupt BIS-GB standard harmonization, and photoinitiator breakthrough chemistries that compress migration thresholds overnight. Forecasts reflect documented assumptions about regulatory enforcement intensity and certification backlog durations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Screen Printing Inks Market
Printing Inks
Security Printing Market
Printing Inks
Eco-Friendly Inks Market
Printing Inks
Ink-Cartridge Market
Printing Inks
Global Water-Based Inks Market
Printing Inks
Squid Ink Market
Printing Inks
Non-Conductive Ink Market
Printing Inks
United States Flexographic Printing Market
Printing Inks
Roll-To-Roll Type UV Imprinting Machines Market
Printing Inks
Continuous Inkjet Ink Market
Printing Inks
Food Marking Inks Market
Printing Inks
Packaging Inks and Coatings Market
Printing Inks
Global Conductive Inks Market
Printing Inks
Plant Oil Based Printing Inks Market
Printing Inks
UV Cured Inks Market
Printing Inks
Ink Additives Market