
 Non-Conductive Ink Market | 2026-2036
Non-Conductive Ink Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Conductive Ink Market Intelligence
REACH is rebalancing the cost-of-entry calculus for European non-conductive ink suppliers by mandating stricter substance registration and solvent emission thresholds. DuPont de Nemours, Inc. leverages its polymer science heritage to sustain high-performance dielectric formulations for advanced packaging. Henkel AG & Co. KGaA anchors its position through adhesive and functional coating integration that extends beyond standalone ink sales. Cabot Corporation specializes in pigment and dispersion technology that controls color stability in high-voltage insulation applications.
Non-conductive ink comprises dielectric formulations engineered to prevent electrical current transmission, typically incorporating ceramic fillers, polymer resins such as polyimide or epoxy, and viscosity modifiers tuned to specific deposition methods. These formulations serve primarily to insulate conductive traces, protect sensitive components from moisture and corrosion, and define active versus inactive zones in printed electronic architectures. UV-curable ink dominates value capture due to instant polymerization that eliminates solvent handling and reduces thermal damage to temperature-sensitive substrates. Flexible electronics applications are expanding fastest as roll-to-roll manufacturing of wearable sensors and foldable displays demands inks that withstand repeated mechanical deformation without dielectric breakdown.
EPA regulations in the United States restrict volatile organic compound emissions from solvent-based formulations, while ECHA administers REACH substance restrictions that affect halogenated flame retardants common in legacy PCB insulation inks. Japan's METI promotes green procurement guidelines that favor low-environmental-impact materials in consumer electronics supply chains. Stakeholders must monitor regulatory divergence between jurisdictions where identical formulations face different compliance costs, and decide whether to maintain regional product variants or pursue universal formulations that satisfy the strictest standards.
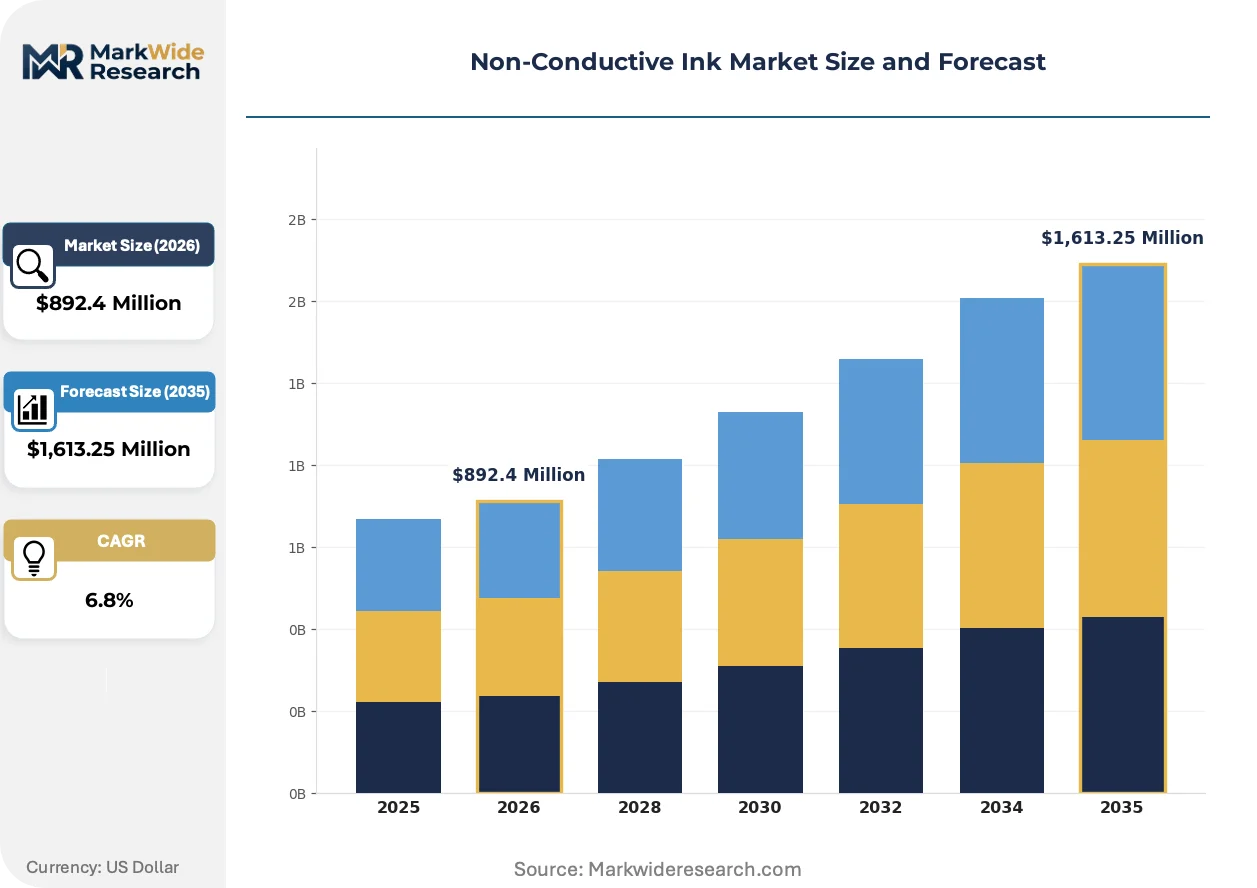
Market Dynamics
UV-curable ink chemistry is compressing production cycles and eliminating solvent handling costs, forcing reformulation investments across the supplier base while rewarding early movers with qualification advantages in automotive and flexible electronics supply chains.
Growth Catalysts
- Electric vehicle battery insulation:Automotive OEMs specify dielectric inks for thermal management and high-voltage isolation, with South Korean cell manufacturers driving formulation standardization.
- REACH solvent thresholds:ECHA mandates accelerate water-based and UV-curable adoption, creating first-mover advantages for compliant suppliers in European electronics supply chains.
- Roll-to-roll manufacturing:Flexible display and wearable sensor producers demand inks that withstand repeated bending without dielectric breakdown, pulling specialty polymer development.
Market Restraints
- Silver flake price volatility:Conductive filler cost swings compress margins for hybrid ink suppliers dependent on precious metal supply chains.
- Japanese pigment concentration:Specialty ceramic filler production clusters in Osaka-Kobe chemical corridors, creating single-source risk for high-voltage insulation grades.
- Cure depth limitations:UV formulations struggle with dielectric consistency above 50-micron thickness, constraining applications in heavy-duty PCB insulation.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme incentives for semiconductor packaging and display fabs create qualified supplier gaps for dielectric materials.
- Biodegradable substrate compatibility:Emerging compostable flexible circuits require reformulated inks that maintain insulation properties through biodegradation cycles.
- AI-assisted formulation:Machine learning platforms accelerate polymer resin screening, compressing R&D timelines for custom dielectric specifications.
Industry Challenges
- Cleanroom operator scarcity:Precision ink deposition requires technicians trained in ISO Class 5 protocols, with German and Japanese vocational pipelines failing to match demand.
- Multi-jurisdiction certification lag:UL, VDE, and JIS safety approvals for new formulations require 18-24 month timelines, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Conductive Ink Market |
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,613.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Ink, Solvent-Based Ink, UV-Curable Ink, Eco-Friendly Ink Application: Flexible Electronics, Printed Circuit Boards, Textiles, Packaging End User: Consumer Electronics, Automotive, Aerospace, Healthcare Technology: 3D Printing, Screen Printing, Inkjet Printing, Gravure Printing |
| Companies Covered | Teikoku Printing Inks Mfg. Co., Ltd., Nano Dimension Ltd., DuPont de Nemours, Inc., 3M Company, The Dow Chemical Company, Henkel AG & Co. KGaA, Mitsubishi Chemical Corporation, Cabot Corporation, Sun Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Conductive Ink Market Strategic Shifts & Innovations
Nano-scale ceramic fillers and AI-driven formulation platforms are compressing development cycles while regulatory pressure on solvent emissions forces chemistry pivots that favor integrated coating-ink systems over standalone products.
Nano-alumina and nano-silica dispersions are integrating into dielectric formulations to achieve sub-10-micron insulation layers with thermal conductivity above legacy polymer resins. Flexible OLED manufacturers in South Korea and Taiwan specify these grades for foldable display backplanes. The technology is integrating previously separate barrier and insulation functions into single-pass deposition, eliminating lamination steps and compressing bill-of-material costs.
EPA volatile organic compound restrictions under the Clean Air Act tighten permissible solvent content in screen-printing operations, forcing US-based converters toward UV-curable or water-based alternatives. ECHA simultaneously advances REACH authorization requirements for halogenated flame retardants common in legacy PCB inks. Suppliers serving both markets face divergent compliance calendars, with automotive and aerospace insulation grades experiencing the most acute reformulation pressure.
Buyer consolidation among tier-one automotive suppliers compresses qualification timelines and shifts contract structures toward performance guarantees rather than material specifications. Korean battery cell producers now require dielectric ink suppliers to warranty insulation integrity across 10-year vehicle lifecycles. This risk transfer is most visible in German and South Korean supply chains, where cell-to-pack architectures eliminate module-level redundancy and amplify single-point-of-failure exposure.
Non-Conductive Ink Market Segmentation
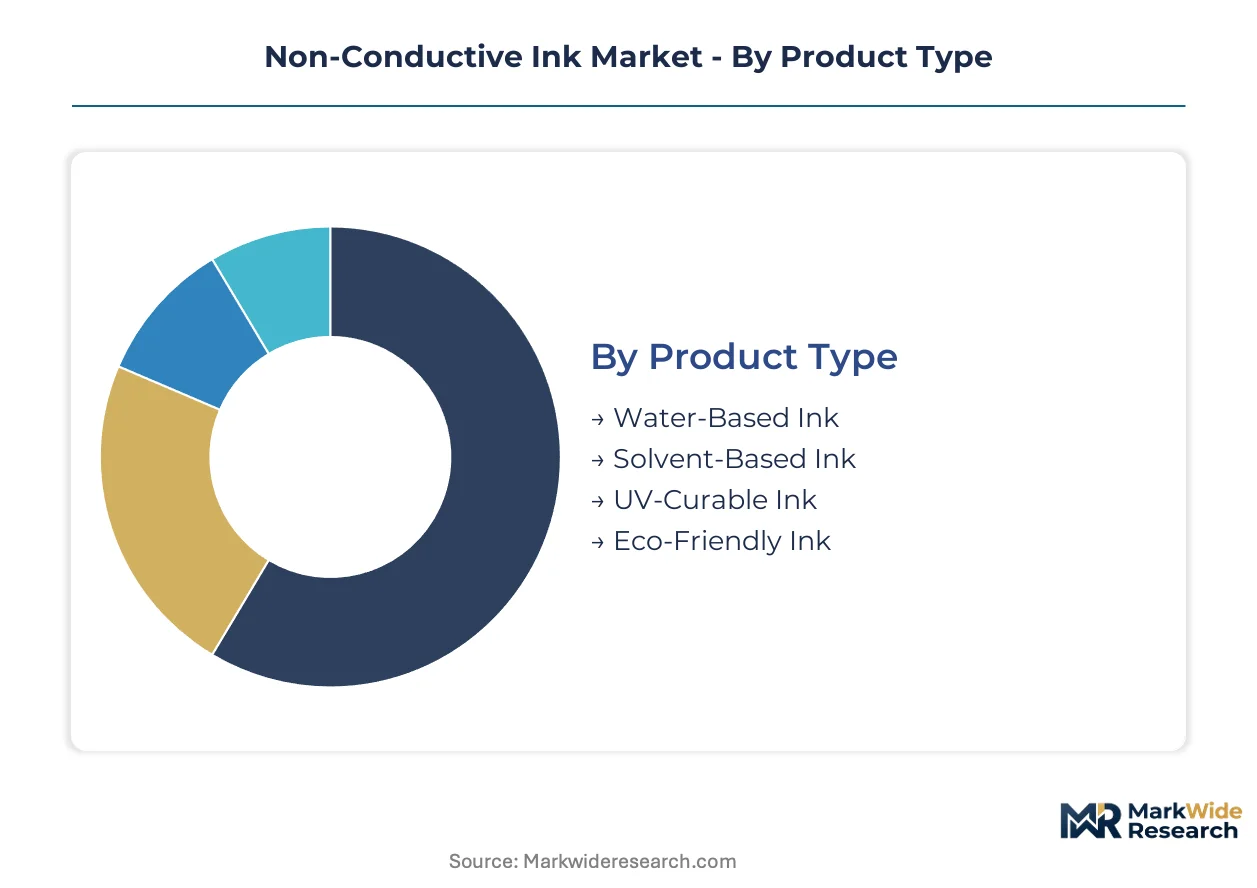
Non-conductive ink segmentation reveals how formulation chemistry, deposition method, and end-use severity dictate certification requirements. Suppliers must maintain parallel qualification tracks across automotive, aerospace, and medical device standards, multiplying compliance overhead for multi-industry portfolios.
Product Type:
Certification burden varies sharply by chemistry: UV-curable inks face UL and VDE electrical safety validation, water-based formulations trigger EPA VOC compliance and ECHA SVHC screening, while solvent-based legacy products confront REACH authorization timelines for restricted substances.
- UV-Curable Ink:Photoinitiator-triggered polymerization enables instant curing without thermal substrate damage. South Korean flexible display manufacturers specify these grades for foldable OLED backplanes where dielectric layers must withstand repeated mechanical stress. ECHA restrictions on certain photoinitiators are forcing reformulation investments.
- Solvent-Based Ink:Traditional formulations incorporating aromatic thinners and halogenated flame retardants deliver thick-film insulation for heavy-duty PCBs. REACH authorization requirements for legacy flame retardant chemistries are compressing viable production windows in European supply chains.
- Water-Based Ink:Acrylic and polyurethane dispersions with reduced VOC profiles satisfy EPA Clean Air Act thresholds for US screen-printing operations.
- Eco-Friendly Ink:Bio-derived resin systems and biodegradable additives target emerging compostable electronics applications.
Leading the category by volume: UV-Curable Ink. Growing fastest: Eco-Friendly Ink.
Application:
Application segments separate by substrate fragility and electrical isolation requirements, with foldable displays demanding polymer flexibility that rigid PCB insulation cannot accommodate.
- Flexible Electronics:Roll-to-roll manufacturing of wearable sensors and stretchable circuits requires dielectric inks with elongation above 100% without dielectric breakdown. Taiwan and South Korean display fabs are driving specification standardization for foldable smartphone architectures.
- Printed Circuit Boards:High-voltage isolation layers in automotive power electronics and aerospace avionics demand ceramic-filled formulations with thermal conductivity exceeding 0.5 W/mK. Japanese material suppliers dominate high-reliability grades for satellite and defense applications.
- Textiles:E-textile integration for medical monitoring and athletic performance tracking imposes wash-cycle durability requirements.
- Packaging:Anti-static and moisture barrier functions for sensitive electronics shipping containers utilize lower-performance dielectric coatings.
Flexible Electronics commands premium pricing. Printed Circuit Boards anchor volume demand.
End User:
End-user concentration determines qualification timeline length and warranty risk transfer, with automotive and aerospace imposing decade-long performance guarantees.
- Automotive:Battery cell-to-pack architectures eliminate module-level redundancy, amplifying single-point-of-failure exposure for dielectric materials. German and South Korean cell manufacturers now require 10-year insulation integrity warranties.
- Aerospace:Outgassing specifications for satellite applications restrict allowable volatile content to fractions of commercial grades.
- Consumer Electronics:Smartphone and tablet manufacturers drive cost-down pressure through high-volume procurement.
- Healthcare:Wearable diagnostic devices require biocompatibility certification under ISO 10993.
Automotive generates fastest specification evolution. Consumer Electronics delivers largest unit volumes.
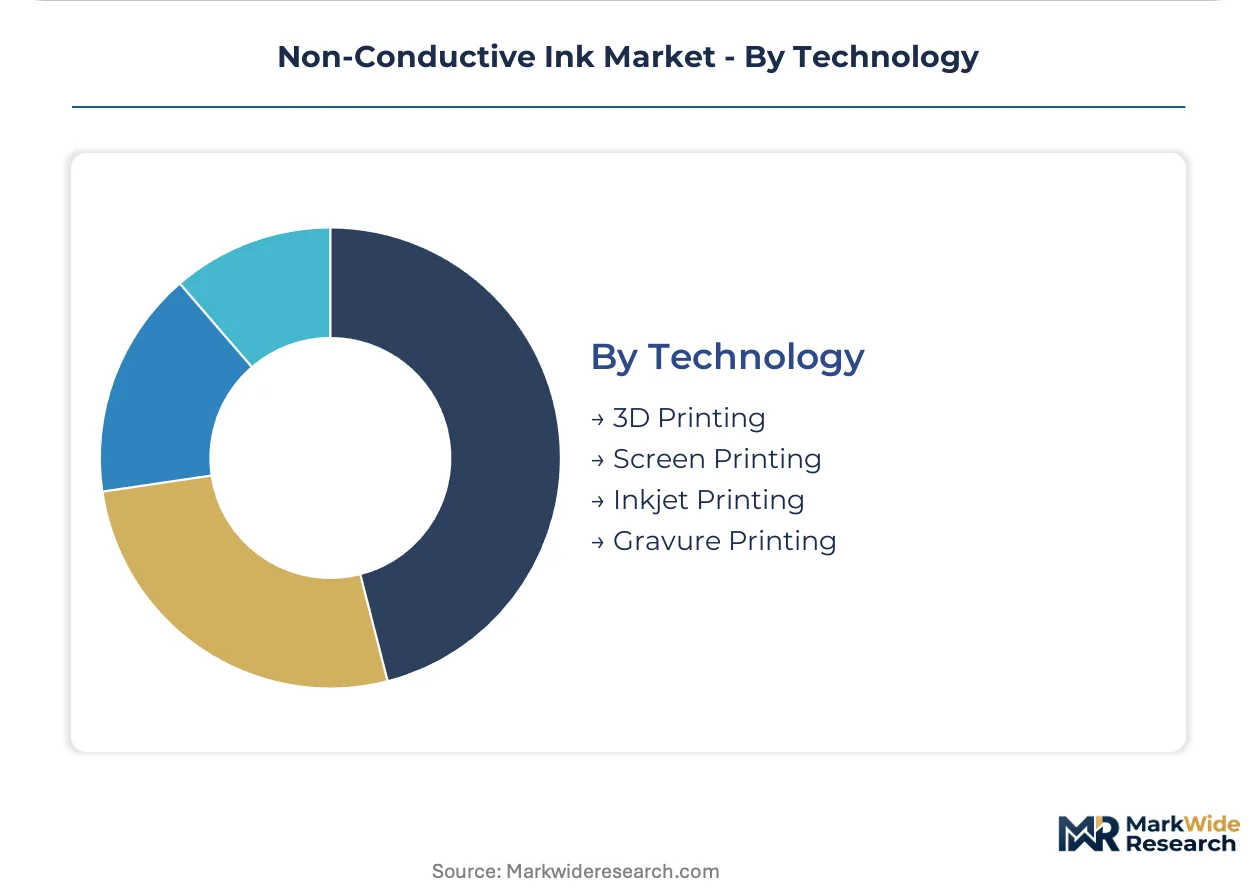
Technology:
Deposition technology segments align with production scale and pattern complexity, from prototype 3D printing to high-speed gravure for commodity packaging.
- Screen Printing:Thick-film deposition of 20-100 micron dielectric layers dominates PCB and automotive power module manufacturing. German and Japanese equipment suppliers control high-precision registration systems for multi-layer insulation stacks.
- Inkjet Printing:Drop-on-demand precision enables additive manufacturing of embedded passive components and 3D-structured insulation. Taiwanese semiconductor packaging houses are qualifying piezoelectric inkjet systems for fan-out wafer-level packaging.
- 3D Printing:Stereolithography and material jetting enable conformal coating of complex geometries.
- Gravure Printing:High-speed rotary engraving suits flexible packaging and textile applications.
Screen Printing retains largest installed base. Inkjet Printing shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian special economic zones and European chemical corridors concentrate non-conductive ink production through tax-advantaged manufacturing parks and clustered supplier ecosystems. Government-backed industrial zones in South Korea, Japan, and Germany anchor formulation R&D and high-volume output.
United States
EPA Clean Air Act enforcement tightens volatile organic compound thresholds for screen-printing operations, pushing converters toward UV-curable alternatives. The Inflation Reduction Act subsidizes domestic battery cell manufacturing, amplifying dielectric ink procurement for EV power electronics. Michigan and Ohio automotive corridors host qualification programs for cell-to-pack insulation materials.
Germany
REACH authorization timelines compress viable production windows for solvent-based formulations containing legacy flame retardants. The KBA mandates decade-long performance warranties for automotive battery insulation, transferring failure risk to material suppliers. Bavarian chemical clusters near Munich coordinate reformulation investments for compliant dielectric grades.
South Korea
Seoul Capital Area display fabs drive specification standardization for foldable OLED backplanes requiring mechanical stress tolerance. METI-aligned green procurement guidelines favor low-environmental-impact materials in consumer electronics supply chains. Busan-Ulsan chemical corridors concentrate ceramic filler production for high-voltage insulation grades.
Japan
Osaka-Kobe chemical corridors anchor specialty ceramic filler production, creating single-source dependencies for high-reliability dielectric formulations. JIS standards govern outgassing specifications for satellite applications that restrict volatile content below commercial grades. METI promotes domestic qualification of nano-alumina dispersions for sub-10-micron insulation layers.
India
PLI scheme incentives for semiconductor packaging and display fabs generate qualified supplier gaps for dielectric materials. BIS certification requirements extend qualification timelines for imported formulations. Gujarat and Tamil Nadu electronics manufacturing clusters attract formulation tolling partnerships with East Asian suppliers.
Non-Conductive Ink Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and deposition technology vectors. Market structure tilts toward consolidation among polymer science heritage players and adhesive-coating integrators, while nano-dispersion specialists occupy niche premium positions. Three archetypes dominate: diversified materials conglomerates leveraging cross-divisional R&D, functional coating integrators bundling ink with adjacent chemistries, and ceramic filler specialists controlling pigment dispersion quality. Competitive moves concentrate on strategic partnerships for automotive qualification and capacity expansion in East Asian manufacturing zones.
Among diversified materials conglomerates, DuPont de Nemours, Inc. and 3M Company exemplify scale-driven archetypes with polymer science heritage spanning multiple industrial verticals. Japanese specialists including Teikoku Printing Inks Mfg. Co., Ltd. and Mitsubishi Chemical Corporation occupy positions within functional coating and chemical intermediate supply chains. Cabot Corporation represents the ceramic filler specialist archetype, anchoring pigment dispersion capabilities that underpin dielectric consistency in high-voltage applications.
| Leading Market Players |
|---|
| Teikoku Printing Inks Mfg. Co., Ltd. |
| Nano Dimension Ltd. |
| DuPont de Nemours, Inc. |
| 3M Company |
| The Dow Chemical Company |
| Henkel AG & Co. KGaA |
| Mitsubishi Chemical Corporation |
| Cabot Corporation |
| Sun Chemical Corporation |
| Others |
Cost & Logistics Intelligence
Tier-one automotive OEMs and South Korean battery cell manufacturers concentrate procurement power through long-term offtake agreements, anchoring contract-based pricing that transfers decade-long performance risk to ink suppliers while compressing spot-market liquidity for specialty grades.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to UV-curable formulations qualified for foldable display backplanes, while spot inventory of legacy solvent-based grades trades at discounts as REACH authorization timelines compress viable production windows. Price differentiation hinges on UL certification tier and volume scale, with automotive power electronics grades commanding substantial premiums over packaging applications. Cost compression in water-based alternatives is intensifying because EPA VOC enforcement accelerates converter migration from solvent systems. Consumer electronics manufacturers exhibit highest price sensitivity, whereas aerospace satellite applications show minimal elasticity due to outgassing specification stringency.
Supply Chain Analysis
Reverse-logistics flows for spent ceramic fillers and reformulated legacy inks remain underdeveloped, creating disposal cost burdens that concentrate in German and Japanese chemical corridors. Raw material sourcing draws from Japanese nano-alumina specialists, South Korean photoinitiator producers, and German polymer resin manufacturers. Single-source vulnerability concentrates in Osaka-Kobe ceramic filler production clusters. Distribution runs through East Asian tolling partnerships and European chemical distributor networks serving qualified converter bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
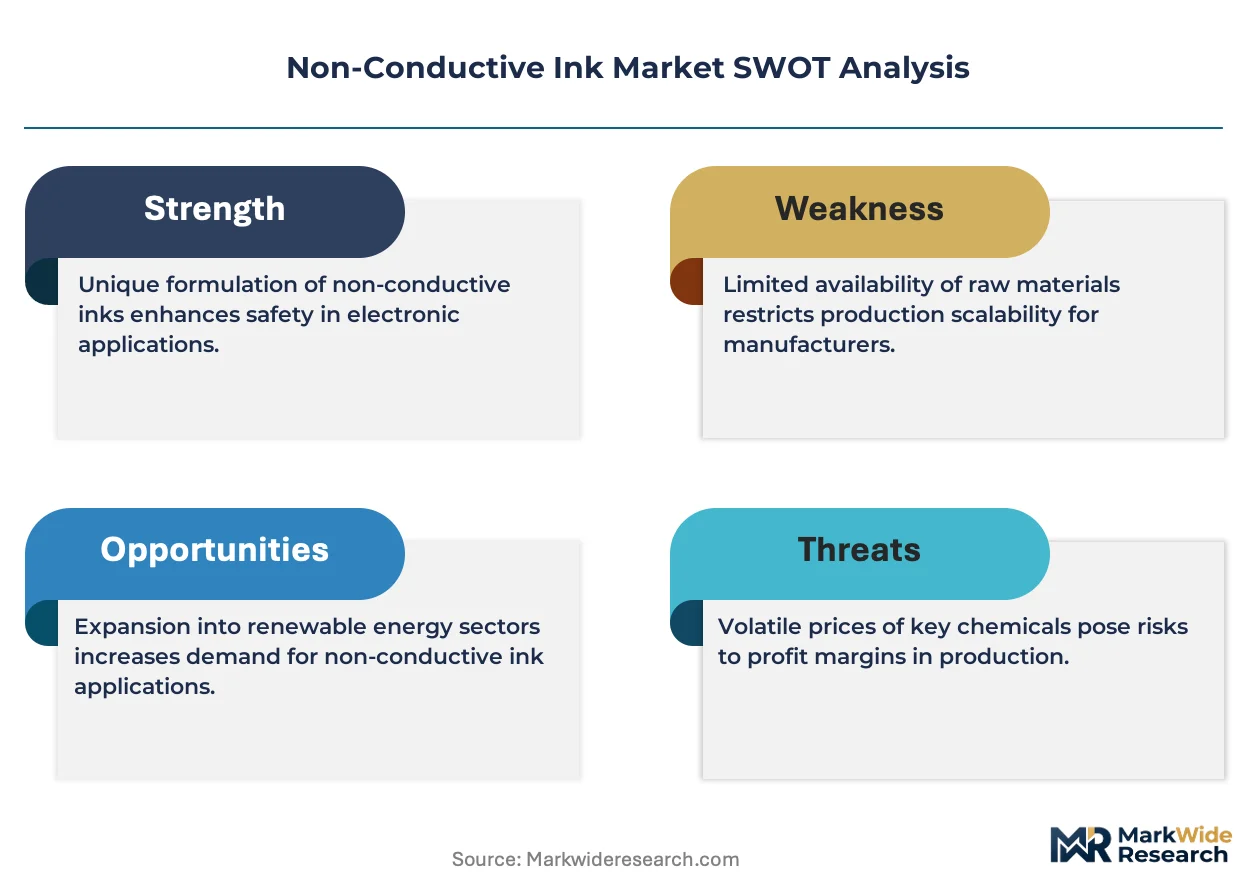
Specialty ceramic filler capacity constraints in Japanese chemical corridors prop pricing power for qualified suppliers, constraining volume expansion until tolling partnerships in India and Southeast Asia achieve certification parity.
For Market Incumbents: Deploy backward integration into nano-alumina dispersion capabilities to secure supply continuity against Osaka-Kobe concentration risk. Accelerate UL and VDE certification investments for UV-curable grades targeting automotive cell-to-pack architectures. Counter emerging water-based specialists through performance guarantee bundling that locks in decade-long OEM relationships. For New Entrants and Emerging Players: Capture qualified supplier gaps in Indian PLI scheme corridors by partnering with Gujarat and Tamil Nadu electronics manufacturing clusters for tolling arrangements. Penetrate biodegradable substrate compatibility segments where incumbent reformulation lags create specification windows. Lead with AI-assisted formulation services that compress custom dielectric development timelines for flexible electronics startups. For Investors and Strategic Acquirers: The window for entry favors ceramic filler specialists with dispersion IP and established JIS qualification track records. Long-term viability centers on supply security rather than volume scale, given raw material concentration risks. Monitor REACH authorization calendar acceleration for halogenated flame retardants as inflection signal for water-based and UV-curable substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nano-Alumina | Captures critical raw material security against Japanese supply concentration. |
| Automotive Qualification Program | Locks in decade-long offtake with German and South Korean cell manufacturers. |
| AI-Assisted Formulation Platform | Compresses R&D timelines for custom dielectric specifications in flexible electronics. |
| Indian Tolling Partnership | Accesses PLI scheme procurement pools while circumventing BIS certification delays. |
| Biodegradable Ink Development | Positions for emerging compostable electronics specifications ahead of regulatory mandates. |
Research Approach
Multi-period observation of formulation qualification timelines, regulatory authorization calendars, and automotive procurement patterns anchored the trend analysis, supplemented by interviews with technical R&D directors at specialty chemical suppliers, procurement leads at South Korean display fabs, plant managers in German automotive corridors, and distribution channel partners serving European electronics converters. Secondary validation drew from ECHA REACH registration databases, EPA Clean Air Act enforcement records, SEC 10-K filings of diversified materials conglomerates, and customs trade data tracking ceramic filler flows. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the analysis window.
Input-output matrices mapped deposition technology adoption rates, chemistry transition velocities, and end-use severity requirements to generate segment-level projections throughout the forecast period. Segmentation dimensions encompassed formulation chemistry, application substrate fragility, and regional regulatory cluster stringency. CAGRs were derived from elasticity modeling of substitution dynamics between UV-curable, water-based, and solvent-based alternatives, with nano-filler integration rates and automotive battery production forecasts serving as primary demand-side inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH authorization acceleration, ceramic filler supply disruptions, and automotive warranty claim experience that could reformulate risk-sharing arrangements. Practitioners should monitor ECHA SVHC candidate list expansion, Indian BIS certification timeline compression, and foldable display yield rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Zink Printing Market
Printing Inks
Global Conductive Inks Market
Printing Inks
UV Fluorescing Ink Market
Printing Inks
Global Flexographic Inks Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
Screen Printing Mesh Market
Printing Inks
Solder Resist for Inkjet Printer Market
Printing Inks
Global Printing Blanket Market
Printing Inks
North America Ink Market
Printing Inks
Global Gravure Printing Inks Market
Printing Inks
Global Low Migration Inks Market
Printing Inks
Security Printing Market
Printing Inks
Molecular Ink Market
Printing Inks
Global Ceramic Inks Market
Printing Inks
Ink Resins Market
Printing Inks
Printing Inks Market