
 Packaging Inks and Coatings Market | 2026-2036
Packaging Inks and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Inks and Coatings Market Outlook
CE marking under the EU Packaging and Packaging Waste Regulation is collapsing the supplier base to firms with verified migration testing and circularity documentation. Sun Chemical Corporation leverages its integrated pigment and resin operations to sustain margin control across European flexible packaging lines. Flint Group anchors gravure ink supply for high-volume carton converters in North America. DIC Corporation dominates water-based flexographic formulations for Asian beverage label printers.
Packaging inks and coatings comprise formulated liquid or solid systems containing pigments, binders, solvents or water carriers, and additives, applied via flexographic, gravure, offset, or digital processes to substrates at thicknesses typically ranging from 1 to 8 micrometers, then cured through thermal drying, oxidation, or ultraviolet polymerization to provide visual communication, barrier enhancement, and product protection. Specialty coatings command premium positioning where oxygen and moisture barriers extend protein shelf life in retort pouches. UV-curable inks are displacing solvent systems in premium label segments due to instant polymerization and elimination of volatile organic compound emissions. Water-based flexographic formulations occupy volume leadership in corrugated post-print applications where absorbency supports rapid drying without thermal energy intensity.
EMA food-contact guidelines, EPA TSCA Section 5 premanufacture notifications, and REACH SVHC candidate list expansions are forcing reformulation cycles that favor suppliers with in-house toxicology and regulatory affairs capabilities. The EU Green Deal packaging waste targets and emerging state-level extended producer responsibility laws in the US are redirecting R&D spending toward mono-material compatible coatings and deinkable chemistries. Stakeholders must monitor how chemical hazard reclassifications alter raw material access and whether bio-based binder platforms achieve performance parity with petrochemical acrylics and polyurethanes.
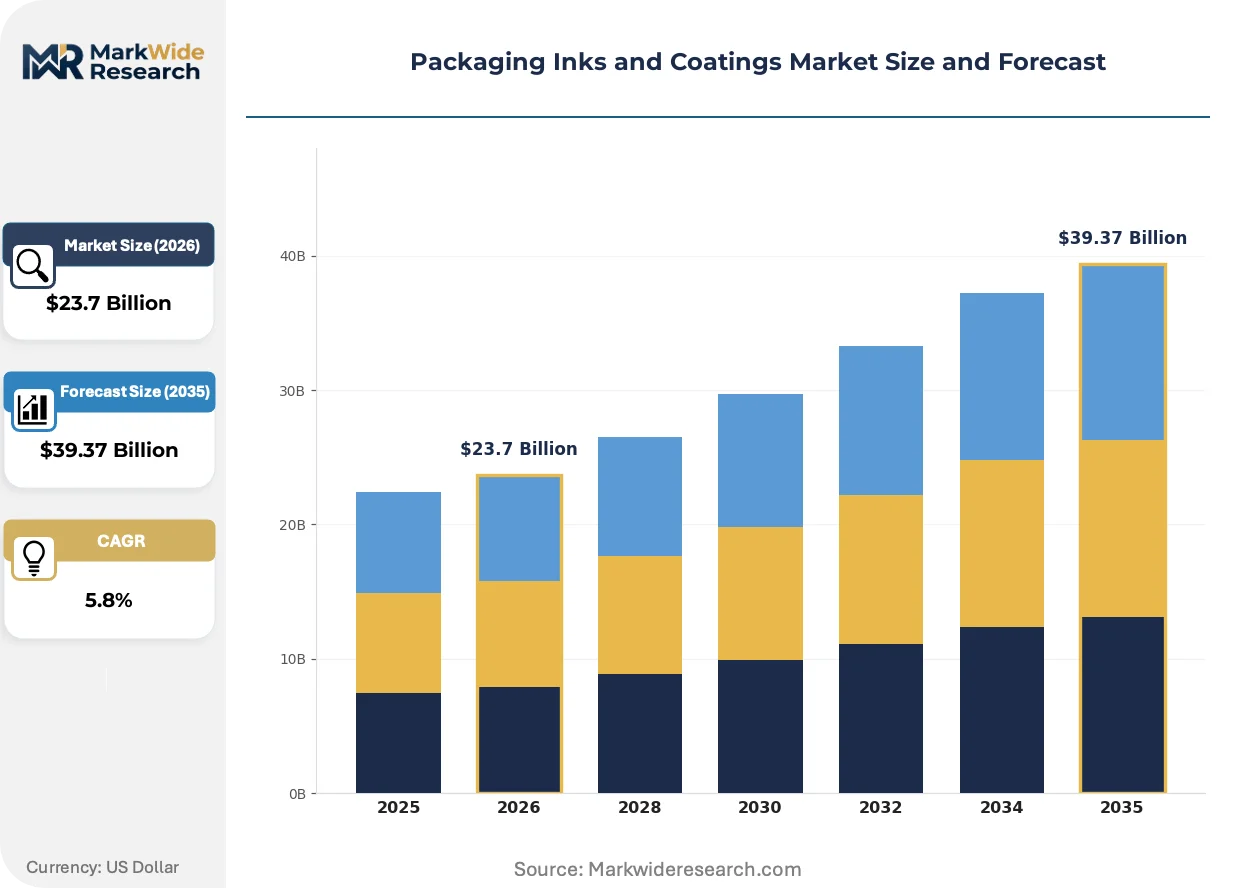
Market Dynamics
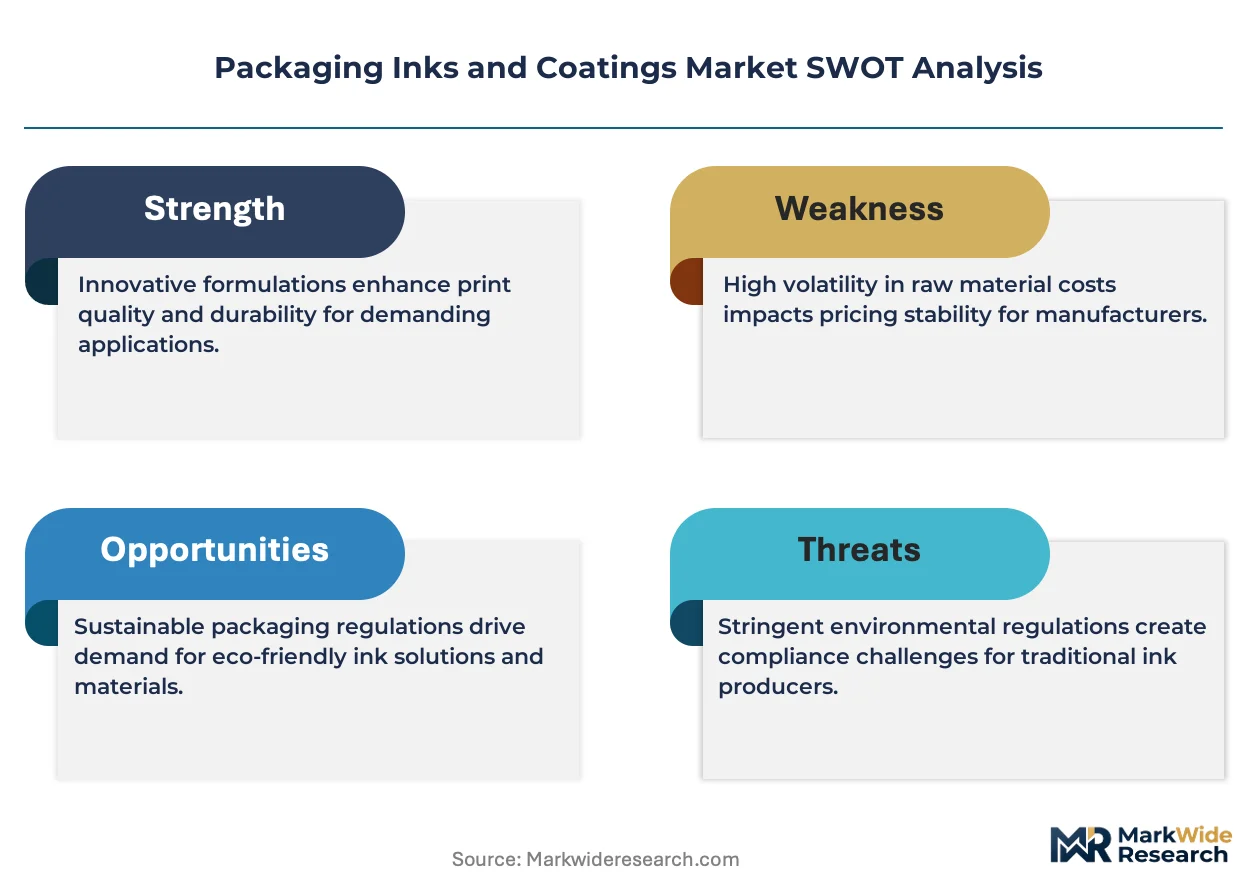
REACH SVHC candidate list expansions and EU Green Deal packaging waste targets are collapsing the supplier base to firms with verified migration testing and circularity documentation, forcing simultaneous reformulation across pigment, binder, and coating portfolios.
Growth Catalysts
- Food-contact compliance mandates:EFSA migration limits and FDA food additive regulations are accelerating replacement of photoinitiator-containing UV inks with low-migration alternatives in dairy and infant food packaging.
- Flexographic volume expansion:Corrugated post-print applications in beverage and e-commerce fulfillment are absorbing water-based flexographic formulations at rates exceeding solvent system displacement.
- Retort pouch barrier demand:Protein shelf-life extension requirements in ready-meal segments are pulling oxygen-scavenging and moisture-barrier coatings into multi-layer flexible structures.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and polyurethane binder costs fluctuate with propylene and isocyanate spot markets, compressing formulation margins for mid-tier suppliers lacking captive resin production.
- Pigment supply concentration:High-performance organic pigments for food-contact applications concentrate among three German and Japanese chemical conglomerates, creating single-source vulnerability for specialized color matching.
- Migration testing bottleneck:EFSA and FDA require 6-18 month stability documentation for new food-contact chemistries, freezing reformulation pipelines for smaller ink houses without in-house toxicology laboratories.
Strategic Opportunities
- Mono-material compatible coatings:EU Green Deal recyclability targets are creating white space for polyethylene and polypropylene-specific barrier coatings that eliminate aluminum foil lamination layers.
- Deinkable chemistry platforms:Extended producer responsibility laws in France and Italy are incentivizing caustic-washable ink systems that enable closed-loop film recycling without color contamination.
- Digital hybrid production:Short-run brand versioning for craft beverage and specialty food segments is opening installation bases for single-pass inkjet systems integrated with flexographic primer units.
Industry Challenges
- Formulation toxicology expertise:REACH and TSCA notification requirements demand regulatory affairs specialists capable of structuring substance volume tracking and exposure scenario modeling, a skill set concentrated among legacy European suppliers.
- Legacy drying infrastructure:Solvent-based gravure lines with thermal oxidation exhaust systems face stranded asset risk as converters evaluate UV LED retrofit capex against water-based system replacement.
- Color consistency across substrates:Brand owners specifying identical Pantone matching across film, paper, and cartonboard substrates require ink suppliers to maintain dispersed pigment databases with substrate-specific absorption coefficients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Inks and Coatings Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $39.37 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexographic Inks, Gravure Inks, Offset Inks, Specialty Coatings Application: Flexible Packaging, Labels, Cartons, Tags End User: Food & Beverage, Pharmaceuticals, Personal Care, Consumer Goods Technology: Water-Based Inks, Solvent-Based Inks, UV-Curable Inks, Eco-Friendly Coatings |
| Companies Covered | Sun Chemical Corporation, Flint Group, Toyo Ink Group, Siegwerk Druckfarben, DIC Corporation, ALTANA AG, Hubergroup Deutschland GmbH, Sakata INX Corporation, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Inks and Coatings Market Strategic Shifts
Energy-cured chemistries and bio-based binder platforms are restructuring competitive positioning by compressing drying energy intensity while opening compliance pathways under tightening volatile organic compound regulations.
UV LED-curable ink systems are displacing traditional mercury arc UV formulations in premium label and folding carton segments. Narrow-web converters serving wine, spirits, and cosmetics brands are retrofitting presses with 395nm LED arrays to eliminate ozone generation and reduce energy consumption. This transition is displacing photoinitiator packages optimized for broad-spectrum mercury lamps, forcing reformulation of acrylate oligomer ratios to maintain cure speed at reduced irradiance.
REACH authorization requirements for chromium VI pigments and certain phthalate plasticizers are redirecting colorant procurement toward complex inorganic pigments and non-phthalate alternatives. German packaging converters serving Central European export supply chains are demanding full material disclosure to pre-empt downstream customer audit failures. The flexographic segment is most affected, with water-based formulation houses accelerating substitution of legacy pigment dispersions to avoid supply interruption.
Brand-owner sustainability scorecards are compressing supplier qualification cycles and unbundling after-sales technical service from ink supply contracts. Major food and beverage manufacturers in the Netherlands and California are requiring life-cycle assessment documentation and carbon footprint data as mandatory bid components. This behavioral shift is most visible in corrugated post-print, where converters are consolidating supplier relationships to firms offering integrated color management and waste reduction auditing.
Packaging Inks and Coatings Market Segmentation
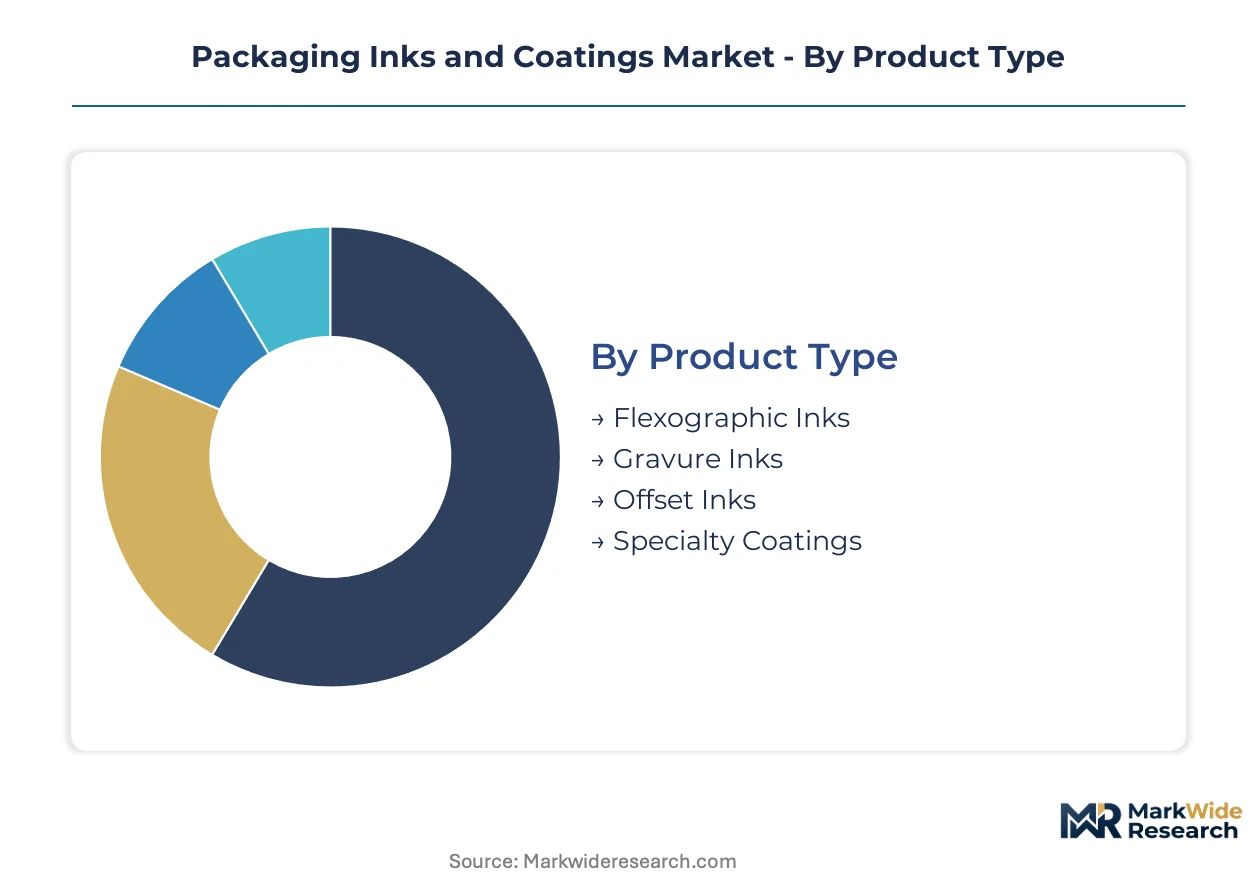
Channel-mix dynamics in packaging inks and coatings determine margin capture and regulatory compliance pathways. Product formulations flow through distinct converter networks, while application segments impose divergent migration testing and barrier performance requirements. Understanding these segment boundaries enables suppliers to align R&D spending with the highest-velocity demand corridors.
Product Type:
Flexographic and gravure formulations dominate volume channels serving corrugated post-print and flexible film converters respectively, with offset and specialty coatings occupying narrower premium pathways.
- Flexographic Inks:Water-based pigment dispersions with rapid drying profiles designed for absorbent corrugated substrates. Demand concentrates in German beverage and e-commerce fulfillment converters where EU Green Deal recyclability targets favor mono-material packaging structures. REACH-compliant binder platforms are displacing legacy acrylic systems in these high-volume lines.
- Gravure Inks:Solvent-borne or water-based formulations optimized for high-speed cylinder engraving on non-absorbent films. North American carton converters anchor volume demand for high-definition reproduction in premium consumer goods packaging. Stranded asset risk looms as converters evaluate UV LED retrofit against water-based system replacement.
- Offset Inks:Oil-based or UV-curable systems for lithographic sheet-fed and web applications on paperboard. Folding carton segments in France and Italy absorb these formulations where deinkable chemistry requirements intersect with extended producer responsibility laws.
- Specialty Coatings:Oxygen-scavenging and moisture-barrier layers for multi-layer retort pouches. Protein shelf-life extension requirements in ready-meal segments pull these formulations into flexible structures at premium pricing tiers.
By volume, flexographic inks lead. By growth pace, specialty coatings are climbing the fastest as barrier demands intensify.
Application:
Cost tier stratification separates commodity corrugated from premium label and pharmaceutical applications, with migration testing intensity escalating across the value chain.
- Flexible Packaging:Multi-substrate film and foil laminations for food, beverage, and personal care products. German converters serving Central European export supply chains demand full material disclosure to pre-empt downstream customer audit failures. EFSA migration limits are accelerating replacement of photoinitiator-containing UV systems with low-migration alternatives.
- Labels:Pressure-sensitive and shrink-sleeve applications for brand differentiation and regulatory compliance. Wine, spirits, and cosmetics brands in California and the Netherlands are retrofitting narrow-web presses with 395nm LED arrays to eliminate ozone generation. This transition forces reformulation of acrylate oligomer ratios for reduced irradiance cure profiles.
- Cartons:Folding carton and liquid packaging board applications for dairy, juice, and dry goods. Corrugated post-print in beverage segments absorbs water-based flexographic formulations where absorbency supports rapid drying without thermal energy intensity.
- Tags:Apparel and logistics identification applications with lower barrier requirements. E-commerce fulfillment growth in Asian markets is expanding demand for thermal transfer and digital inkjet tag systems.
Flexible packaging generates the largest revenue pool. Labels are gaining share fastest as brand versioning shortens print runs.
End User:
Customer type dictates regulatory scrutiny depth, with food-contact applications facing the most stringent EFSA and FDA notification requirements.
- Food & Beverage:Dairy, infant nutrition, ready-meals, and beverage packaging with direct or indirect food contact. EFSA migration limits and FDA food additive regulations freeze reformulation pipelines for suppliers lacking in-house toxicology laboratories. Major manufacturers in the Netherlands now require life-cycle assessment documentation as mandatory bid components.
- Pharmaceuticals:Blister packs, labels, and secondary packaging with serialization and tamper-evidence requirements. EMA guidelines and FDA drug master file obligations concentrate supply relationships with legacy European suppliers possessing regulatory affairs specialists.
- Personal Care:Cosmetics and toiletries packaging where shelf appeal drives premium ink selection. California state-level extended producer responsibility laws are redirecting R&D toward caustic-washable ink systems enabling closed-loop film recycling.
- Consumer Goods:Household products and electronics packaging with moderate barrier and aesthetic requirements. This segment offers the most price-sensitive demand, compressing margins for mid-tier suppliers lacking captive resin production.
Food and beverage commands the deepest supplier relationships. Pharmaceuticals show the steepest regulatory barrier to entry.
Technology:
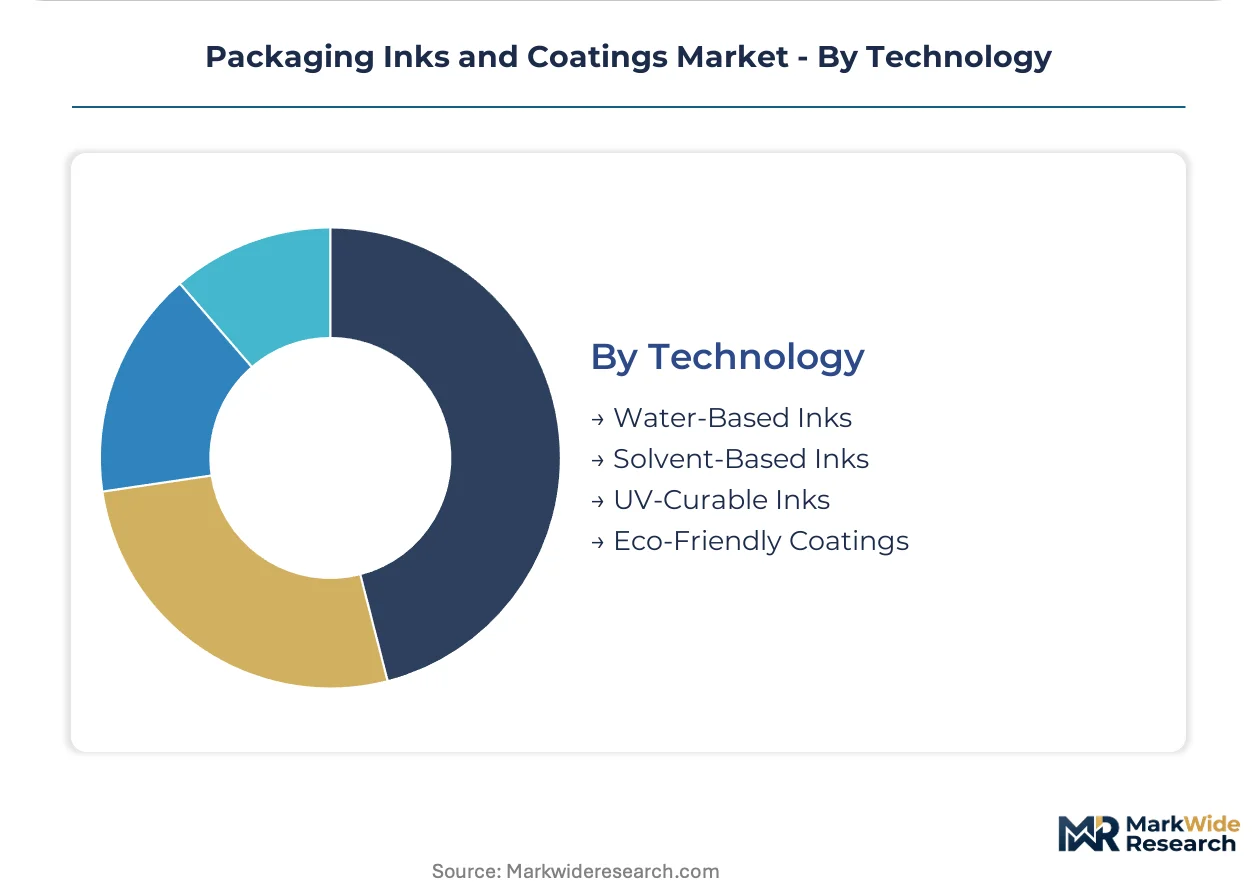
Maturity curves separate established water-based and solvent systems from emerging UV-curable and bio-based platforms, with energy intensity and VOC compliance driving substitution patterns.
- Water-Based Inks:Acrylic and polyurethane dispersions with low VOC emissions and rapid drying on absorbent substrates. Corrugated post-print applications in beverage and e-commerce fulfillment absorb these formulations at rates exceeding solvent system displacement. EU Green Deal packaging waste targets favor these systems for recyclability.
- Solvent-Based Inks:Hydrocarbon and ester-borne systems with superior adhesion and gloss on non-absorbent films. Petrochemical feedstock volatility in propylene and isocyanate spot markets compresses formulation margins for suppliers without captive resin production. Legacy gravure lines with thermal oxidation exhaust systems face stranded asset risk.
- UV-Curable Inks:Acrylate oligomer and monomer systems photopolymerized by mercury arc or LED irradiation. Premium label and folding carton segments are displacing traditional mercury arc formulations with 395nm LED arrays to reduce energy consumption and eliminate ozone generation. REACH authorization requirements for certain photoinitiators are forcing reformulation cycles.
- Eco-Friendly Coatings:Bio-based binder platforms and deinkable chemistries targeting circularity documentation requirements. Mono-material compatible barrier coatings for polyethylene and polypropylene are eliminating aluminum foil lamination layers in EU Green Deal compliance strategies.
Water-based inks hold volume leadership. UV-curable systems are expanding most quickly as converters retrofit for energy efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal packaging waste targets and REACH SVHC expansions are redirecting formulation demand toward suppliers with verified migration testing and circularity documentation. Germany, the United States, China, Japan, and India concentrate distinct technology and regulatory pressures that reshape competitive positioning across each market.
Germany
Packaging converters serving Central European export supply chains demand full material disclosure to pre-empt downstream customer audit failures. ECHA REACH authorization requirements for chromium VI pigments force accelerated substitution of legacy colorant dispersions. The Rhine-Ruhr industrial corridor anchors gravure and flexographic ink production for flexible film and carton applications.
United States
Corrugated post-print expansion in beverage and e-commerce fulfillment absorbs water-based flexographic formulations at rates exceeding solvent system displacement. EPA TSCA Section 5 premanufacture notification requirements freeze reformulation pipelines for ink houses without in-house toxicology laboratories. Wisconsin and Ohio industrial clusters concentrate narrow-web label converters retrofitting presses with UV LED arrays.
China
Domestic beverage label printers and flexible packaging converters drive volume demand for water-based flexographic and gravure formulations. SAMR food-contact material standards and GB compliance protocols tighten chemical disclosure requirements for export-oriented suppliers. The Yangtze River Delta manufacturing belt hosts integrated pigment and resin operations serving Asian packaging supply chains.
Japan
Precision coating requirements for pharmaceutical blister packs and premium cosmetics packaging sustain premium positioning for specialty ink suppliers. METI chemical substance management and PMDA drug master file obligations concentrate supply relationships with legacy domestic producers. The Kansai industrial region around Osaka maintains formulation expertise for high-barrier retort pouch applications.
India
Rapid FMCG sector expansion and organized retail growth accelerate demand for printed flexible packaging in food and personal care segments. FSSAI food-contact material regulations and BIS quality standards are tightening compliance requirements for imported and domestic ink formulations. The Maharashtra-Gujarat industrial corridor concentrates flexible packaging converter capacity serving domestic and Middle Eastern export markets.
Packaging Inks and Coatings Market Competitive Environment
Listed leaders compete with private specialists across technology platforms and regulatory compliance capabilities. The supplier base concentrates around integrated pigment and resin producers, formulation houses with captive toxicology expertise, and regional specialists serving narrow export corridors. Three archetypes dominate: diversified chemical conglomerates with backward integration into raw materials, mid-tier European specialists with legacy regulatory affairs capabilities, and Asia-Pacific volume players leveraging proximity to converter networks. Competitive moves center on M&A to acquire migration testing laboratories and strategic partnerships to secure bio-based binder supply.
Within the integrated chemical conglomerate tier, Sun Chemical Corporation and DIC Corporation exemplify players controlling captive pigment and resin operations to sustain margin stability across formulation portfolios. Among European specialists with regulatory depth, Siegwerk Druckfarben occupies a position anchored by legacy toxicology and compliance infrastructure serving food-contact applications. Flint Group represents the gravure-focused archetype supplying high-volume carton converters in North America. These three named entities illustrate how competitive positioning stratifies across integration depth, geographic footprint, and regulatory capability rather than scale alone.
| Leading Market Players |
|---|
| Sun Chemical Corporation |
| Flint Group |
| Toyo Ink Group |
| Siegwerk Druckfarben |
| DIC Corporation |
| ALTANA AG |
| Hubergroup Deutschland GmbH |
| Sakata INX Corporation |
| PPG Industries |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at integrated pigment and resin facilities in Germany and Japan establishes the floor for specialty coating formulations, compressing margin headroom for mid-tier suppliers lacking backward integration into acrylic and polyurethane binders. This scale concentration permits dominant players to absorb propylene and isocyanate spot volatility while smaller formulation houses face margin compression during feedstock spikes.
Pricing Analysis
Certification level (REACH-compliant food-contact grade versus industrial packaging tier) creates the primary spread across formulation portfolios. Three-tier pricing structure separates premium low-migration UV systems from standard water-based flexographic grades and economy solvent-based industrial lines. Pricing pressure stems from EFSA and FDA notification costs freezing reformulation pipelines, with corrugated post-print converters showing highest price sensitivity due to commodity substrate economics and pharmaceutical label printers least sensitive due to compliance-driven specification lock-in.
Supply Chain Analysis
Inventory lead times for high-performance organic pigments extend 8-12 weeks due to concentration among German and Japanese chemical conglomerates, forcing converters to maintain safety stocks for color-matching consistency. Raw material sourcing draws from Chinese titanium dioxide operations, Indian pigment intermediate manufacturers, and Middle Eastern petrochemical feedstocks for acrylic monomers. Single-source vulnerability for chromium VI pigment alternatives under REACH authorization creates supply interruption risk. Distribution runs through converter-direct technical service relationships rather than distributor intermediaries, with major ink houses embedding color management specialists at high-volume flexible packaging lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability between digital inkjet systems and legacy flexographic primer units is collapsing the traditional technology-silo boundary, creating platform-economics dynamics where formulation suppliers must bundle hardware-agnostic chemistries or risk disintermediation by integrated equipment vendors.
For Market Incumbents: Fortify regulatory affairs capabilities through captive toxicology laboratory acquisition, as EFSA and FDA notification requirements freeze out smaller competitors. Deepen backward integration into bio-based binder platforms to preempt raw material access restrictions under EU Green Deal circularity mandates. Sun Chemical Corporation's integrated pigment-resin model exemplifies the defensive posture required against specialty coating margin erosion. For New Entrants and Emerging Players: Differentiate on deinkable chemistry platforms for polyethylene and polypropylene mono-material structures, where EU Green Deal recyclability targets create unmet demand among French and Italian converters. Target the corrugated post-print segment in India and Southeast Asia, where FSSAI and emerging national standards tighten compliance requirements faster than local formulation houses can adapt. Lead with life-cycle assessment documentation and carbon footprint auditing as mandatory bid components to mirror Netherlands-based brand owner procurement practices. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists with verified migration testing infrastructure over volume players exposed to water-based flexographic commoditization. Long-term viability hinges on regulatory compliance capability depth rather than geographic footprint scale. Acquisition targets should demonstrate in-house toxicology laboratories and REACH SVHC tracking systems. The signal to watch is ECHA authorization list expansion velocity, which accelerates reformulation cycle frequency and consolidates demand toward compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Binders | Secures raw material access under tightening EU Green Deal circularity documentation requirements. |
| Migration Testing Laboratory Acquisition | Collapses EFSA and FDA notification timelines from 18 months to 6 months for food-contact formulations. |
| UV LED Retrofit Partnership Program | Captures narrow-web label converter upgrade cycles in California and Netherlands sustainability-driven markets. |
| Mono-Material Coating Platform Launch | Eliminates aluminum foil lamination layers to meet EU recyclability targets in German flexible packaging supply chains. |
| Digital Hybrid System Integration | Enables short-run brand versioning for craft beverage segments requiring rapid formulation-switching capabilities. |
Study Parameters
A standing panel of packaging converter operations directors, regulatory affairs managers at food-contact material suppliers, pigment procurement leads, and narrow-web press engineers provided ongoing calibration against market realities. Primary interview data combined with secondary validation from ECHA REACH registration databases, FDA food additive petitions, customs trade flow records for titanium dioxide and organic pigments, and SEC filings from integrated chemical conglomerates. Bottom-up volume modeling across flexographic, gravure, offset, and digital technology platforms triangulated against top-down value estimates from formulation house revenue disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology substitution patterns, end-use segment growth differentials, and regional regulatory enforcement intensity as primary segmentation dimensions. CAGRs derived from year-over-year growth rate reconciliation between historical trade data and forward-looking converter capacity expansion announcements, with specific inputs including UV LED press retrofit installation rates and EU Green Deal packaging waste target compliance timelines.
Material uncertainties — REACH SVHC list expansion velocity, petrochemical feedstock spot price volatility, and digital inkjet penetration rates in premium label segments — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology adoption S-curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Eco-Friendly Inks Market
Printing Inks
Ink Resins Market
Printing Inks
Water-Borne Inks and Paints Market
Printing Inks
Global Ceramic Inks Market
Printing Inks
Plant Oil Based Printing Inks Market
Printing Inks
Global Water-Based Inks Market
Printing Inks
Ink-Cartridge Market
Printing Inks
Global Flexographic Inks Market
Printing Inks
Waterborne Ink Market
Printing Inks
Food Marking Inks Market
Printing Inks
Flexo-Ink Market
Printing Inks
Global Digital Inks Market
Printing Inks
Global Chemical Indicator Inks Market
Printing Inks
Brazil Commercial Printing Market
Printing Inks
Inkjet Colorants Market
Printing Inks
North America Printing Inks Market