
 Global Overprint Varnish Market | 2026-2036
Global Overprint Varnish Market Size, Share, and Industry Trends Forecast 2026-2036
Global Overprint Varnish Market Intelligence
The ISO 12647 standard for print process control is unwinding the historical reliance on solvent-based formulations, pushing for greater consistency. Sun Chemical Corporation leverages its extensive global manufacturing footprint to serve multinational consumer goods clients. Siegwerk Druckfarben specializes in solutions for packaging applications, focusing on product safety and regulatory compliance. Altana differentiates through a portfolio of specialty additives that enhance varnish performance characteristics like scuff resistance.
Overprint varnish is a clear liquid coating, typically based on acrylic or polyurethane resins, applied over printed substrates. Its primary purpose is to shield ink from abrasion and environmental factors while enhancing visual appeal in commercial printing and packaging. UV Varnish formulations are gaining share rapidly due to instant curing capabilities and superior finish quality. The packaging application continues to dominate consumption, driven by demand for shelf appeal and product integrity in consumer goods.
Regulatory frameworks are a primary influence on product development and market access. Compliance with the US FDA's rules for food contact materials, Europe's REACH and FCM regulations, and China's GB standards is non-negotiable for suppliers. These rules mandate the use of low-migration chemistries and restrict volatile organic compounds. Navigating the increasingly divergent regional standards for chemical safety and recyclability remains a critical strategic challenge for all manufacturers.
Market Dynamics
The central structural force shaping the overprint varnish market is the escalating requirement for regulatory compliance in food contact materials, which now directly influences formulation chemistry and market access, particularly for packaging applications in consumer goods.
Growth Catalysts
- E-commerce Packaging Expansion:The growth of e-commerce channels necessitates robust packaging that can withstand shipping rigors, driving demand for protective, scuff-resistant varnishes that also maintain high-quality brand aesthetics.
- Food Safety Regulations:Stringent frameworks, including the US FDA's food contact material regulations and Europe's FCM directives, mandate the use of low-migration varnishes, creating a catalyst for advanced, compliant formulations.
- Curing Technology Adoption:The shift towards UV and EB curing systems in the printing industry accelerates demand for compatible varnishes, which offer faster production speeds and superior finish quality compared to conventional methods.
Market Restraints
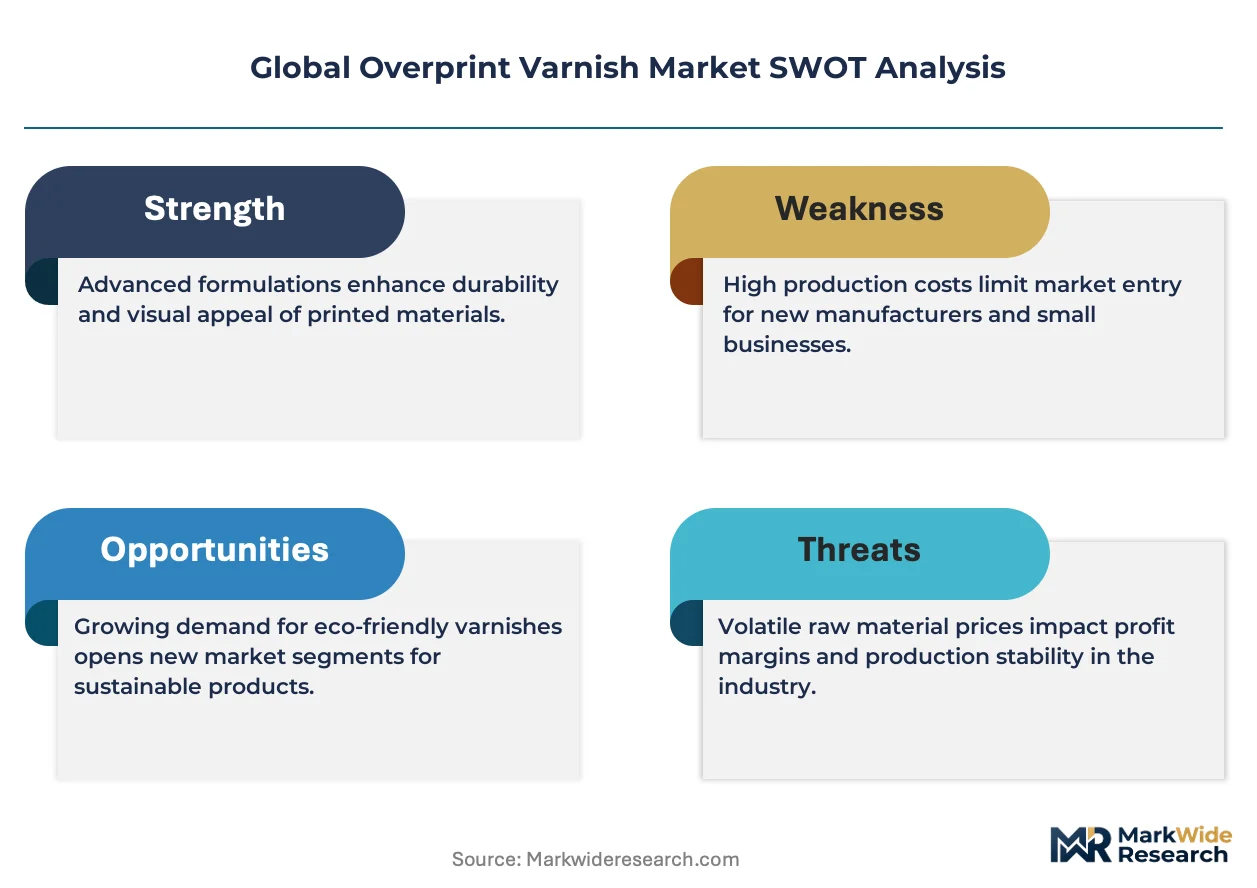
- Raw Material Price Volatility:Fluctuations in the cost of petrochemical-derived inputs, such as acrylic and polyurethane resins, create pricing instability and margin pressure for varnish manufacturers.
- Divergent Regional Standards:The lack of harmonization between major regulatory frameworks, such as Europe's REACH and China's GB standards, complicates product development and increases the cost of global market entry.
- Substitution from Film Laminates:In certain high-performance applications, plastic film lamination presents a substitution threat, offering superior durability and barrier properties that can be a challenge for liquid coatings to match.
Strategic Opportunities
- Bio-Based Formulations:Developing varnishes from renewable, bio-based feedstocks presents a significant opportunity to appeal to brand owners with strong corporate sustainability goals and to align with circular economy principles.
- Functional and Smart Coatings:There is an emerging opportunity for varnishes that incorporate specialty additives to provide functions beyond protection, such as antimicrobial properties for medical packaging or thermochromic effects for marketing.
- Expansion in Southeast Asia:As manufacturing and consumption grow in countries like Vietnam and Indonesia, their nascent packaging industries represent an underpenetrated market for higher-performance overprint varnishes.
Industry Challenges
- Compliance Certification Timelines:Securing food contact certifications from bodies like the EFSA or FDA for new varnish formulations is a time-consuming and expensive process, creating a significant barrier to innovation.
- Application Expertise Gap:A shortage of skilled press operators capable of optimizing the application of advanced UV and specialty varnishes can lead to inconsistent quality and production inefficiencies for printers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Overprint Varnish Market |
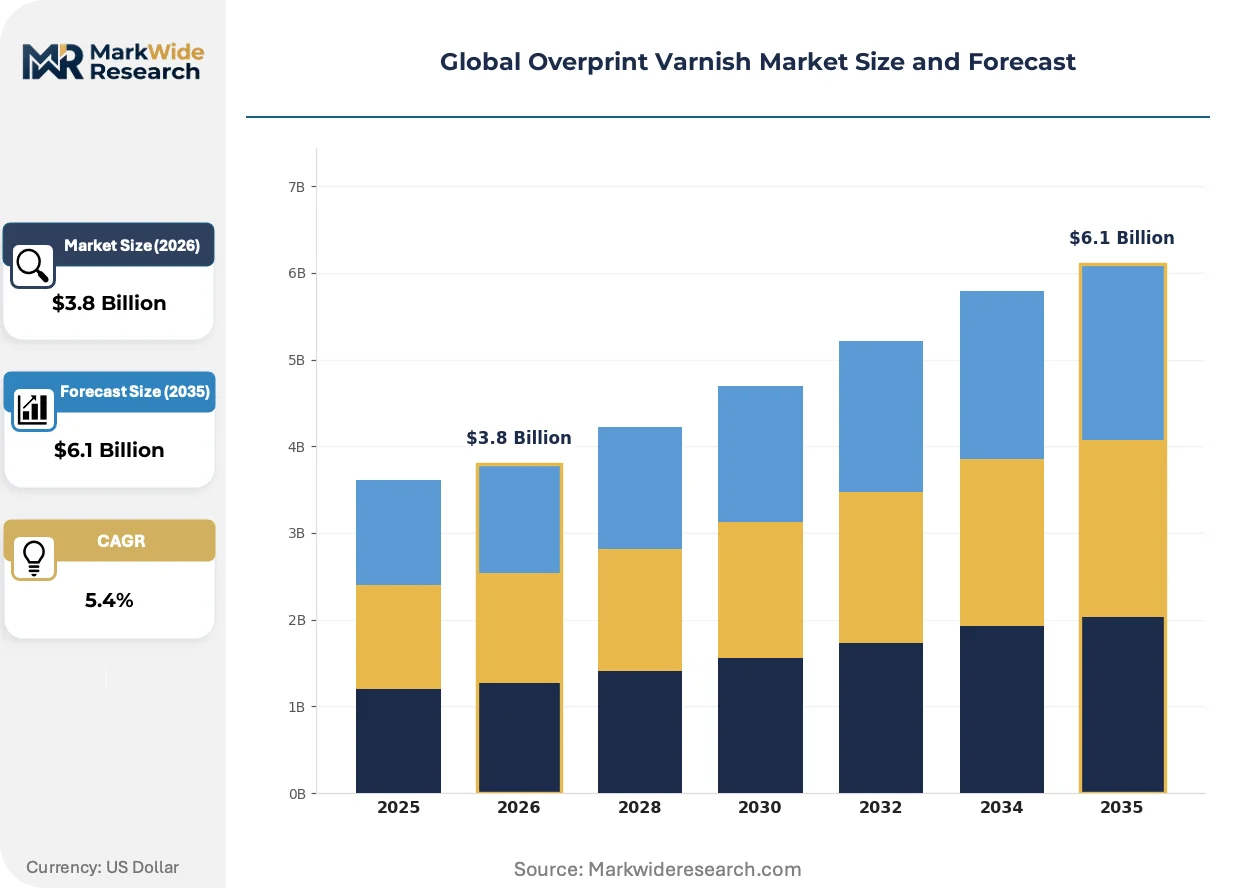
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glossy Varnish, Matte Varnish, Satin Varnish, Soft Touch Varnish, UV Varnish Application: Publishing, Packaging, Labeling, Commercial Printing, Promotional Materials End User Industry: Paperboard Manufacturers, Printing Houses, Label Printers, Promotional Product Companies Packaging Type: Rolls, Sheets, Coils, Reels |
| Companies Covered | Van Son Ink Corporation, Michelman, Zeller+Gmelin, Altana, Toyo Ink, Huber Group, CHT/BEZEMA, Sun Chemical Corporation, Siegwerk Druckfarben, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Overprint Varnish Market Strategic Shifts & Innovations
The market is actively responding to the dual pressures of sustainability mandates and the demand for enhanced functional performance in packaging. This dynamic is driving significant innovation in both material science and application technology, pushing the industry beyond traditional protective coatings.
UV-cured and Electron Beam (EB) varnishes provide instant drying, high gloss, and superior abrasion resistance. Packaging converters in the food, beverage, and pharmaceutical sectors are adopting these systems to increase production line speeds. This advanced curing technology is supplanting conventional solvent-based and water-based varnishes, particularly where lower VOC emissions and faster job turnaround are critical competitive factors.
Europe's REACH regulation, combined with specific Food Contact Material (FCM) rules, establishes rigorous controls on chemical substances used in packaging. This regulatory pressure compels varnish producers to reformulate products using low-migration chemistries and invest heavily in exhaustive safety testing. The flexible packaging segment for food is most affected, spurring innovation in barrier coatings and advanced analysis for non-intentionally added substances (NIAS).
A distinct shift in buying behavior shows brand owners prioritizing varnishes that possess formal certification for recyclability or compostability within a finished package. This disrupts procurement models based solely on cost and aesthetics, creating a preference for suppliers offering validated system solutions. This change is most visible in North America and Europe, led by consumer packaged goods companies with public sustainability targets.
Global Overprint Varnish Market Segmentation
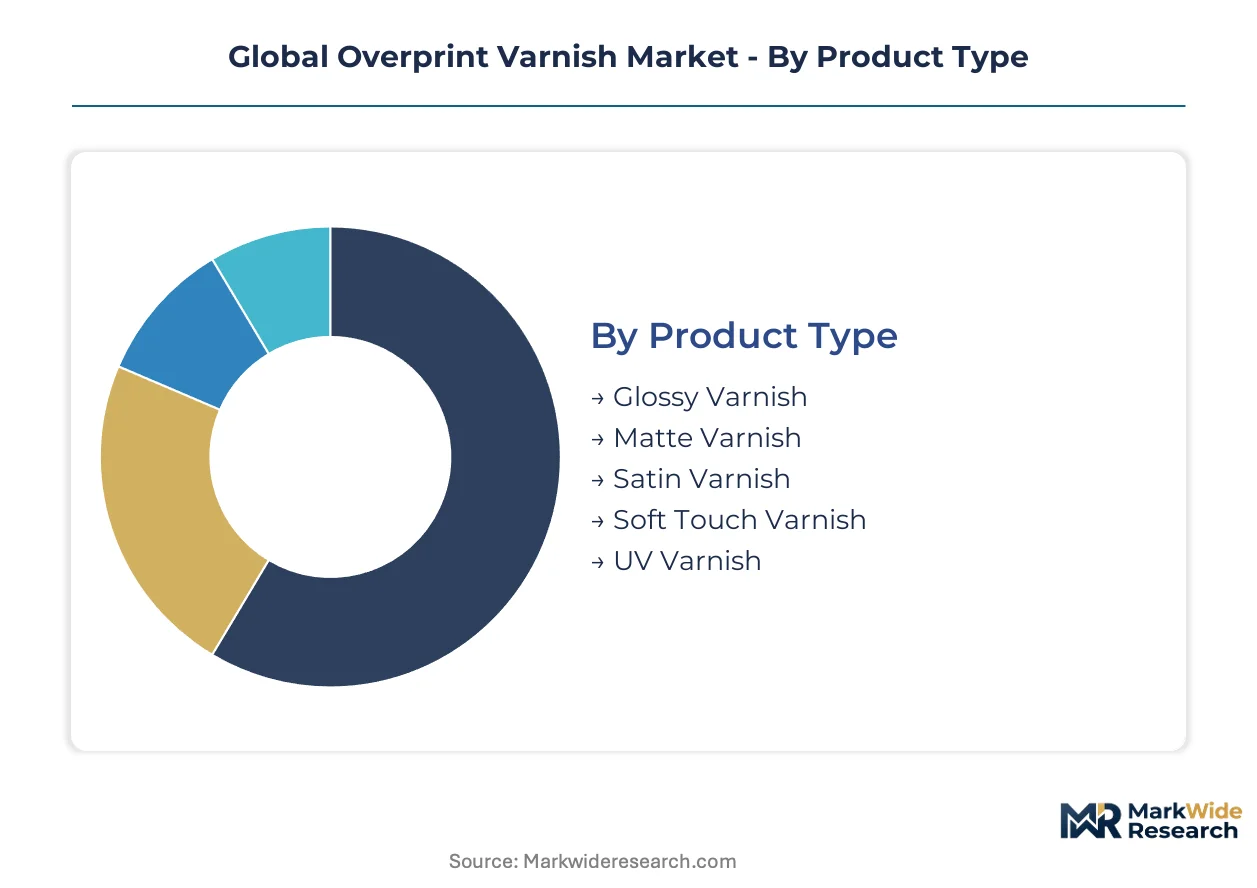
The overprint varnish market segments define distinct product characteristics, application areas, and end-user requirements. Understanding these divisions is crucial for suppliers to tailor product development, optimize distribution channels, and address specific regulatory compliance needs across diverse customer bases.
Product Type:
Margin pools in overprint varnish product types often concentrate around specialized formulations offering enhanced performance or unique aesthetic properties.
- UV Varnish:These formulations cure instantly under ultraviolet light, providing superior gloss, abrasion resistance, and fast production speeds. Demand is concentrated in high-volume packaging and label applications, driven by efficiency and finish quality.
- Soft Touch Varnish:A specialty coating that imparts a tactile, velvety feel to printed materials, enhancing brand perception and consumer experience. Its use is expanding in luxury packaging and promotional items where premium aesthetics are paramount.
- Glossy Varnish:Provides a high-sheen, reflective finish, commonly used for visual appeal and basic protection in commercial printing.
- Matte Varnish:Delivers a non-reflective, subdued finish, often preferred for sophisticated branding and to reduce glare on printed surfaces.
- Satin Varnish:Offers a semi-gloss finish, balancing the characteristics of both matte and glossy varnishes for a versatile aesthetic.
The dominant share belongs to Glossy Varnish, while UV Varnish is closing the gap fastest.
Application:
Application segments often exhibit varying cost structures, influenced by volume demands and specific performance requirements.
- Packaging:This segment involves applying varnishes to various packaging materials for protection, aesthetic enhancement, and regulatory compliance, particularly for food contact. It dominates consumption, driven by consumer goods demand for shelf appeal and product integrity.
- Labeling:Overprint varnishes protect labels from scuffing, moisture, and chemical exposure, ensuring durability and readability in diverse environments. High-speed printing lines for food and beverage labels demand fast-curing, robust formulations.
- Commercial Printing:Includes brochures, magazines, and marketing collateral, where varnishes enhance visual appeal and provide a protective layer.
- Promotional Materials:Covers items like flyers, posters, and point-of-sale displays, using varnishes for durability and visual impact.
- Publishing:Used on book covers and other print media to improve durability and aesthetic finish, though volumes are declining.
Packaging applications command the largest volume, with Labeling expanding most quickly due to e-commerce growth.
End User Industry:
End user industry segments drive demand volumes, with large-scale operations dictating specific procurement patterns.
- Printing Houses:These businesses apply overprint varnishes across a wide array of substrates and print jobs for various clients, requiring versatile product portfolios. They represent the largest customer base, servicing diverse commercial and packaging needs.
- Label Printers:Specializing in high-volume, continuous production of labels for consumer goods, these users prioritize fast-curing, durable, and compliant varnish solutions. Stringent regulations for food and beverage labels influence their material choices.
- Paperboard Manufacturers:Integrate varnishing into their production lines for cartons and other paper-based packaging, focusing on cost-effectiveness and protective properties.
- Promotional Product Companies:Utilize varnishes for enhancing the appearance and durability of branded merchandise, often requiring specialty finishes.
Printing Houses represent the largest consumer base, while Label Printers show the steepest expansion trajectory.
Packaging Type:
Customer types within packaging are often differentiated by their operational scale and material handling capabilities.
- Rolls:Overprint varnishes supplied in rolls are typically used in high-speed, web-fed printing processes common in flexible packaging and label production. This format optimizes continuous production lines for efficiency and reduced downtime.
- Sheets:Varnish supplied in sheets is primarily utilized in sheet-fed offset printing, prevalent in commercial printing and folding carton applications. This format offers flexibility for shorter runs and diverse substrate handling.
- Coils:This packaging type is less common for overprint varnishes, often associated with specific industrial coating applications.
- Reels:Similar to rolls, reels denote bulk packaging for continuous application processes, frequently used in large-scale industrial printing operations.
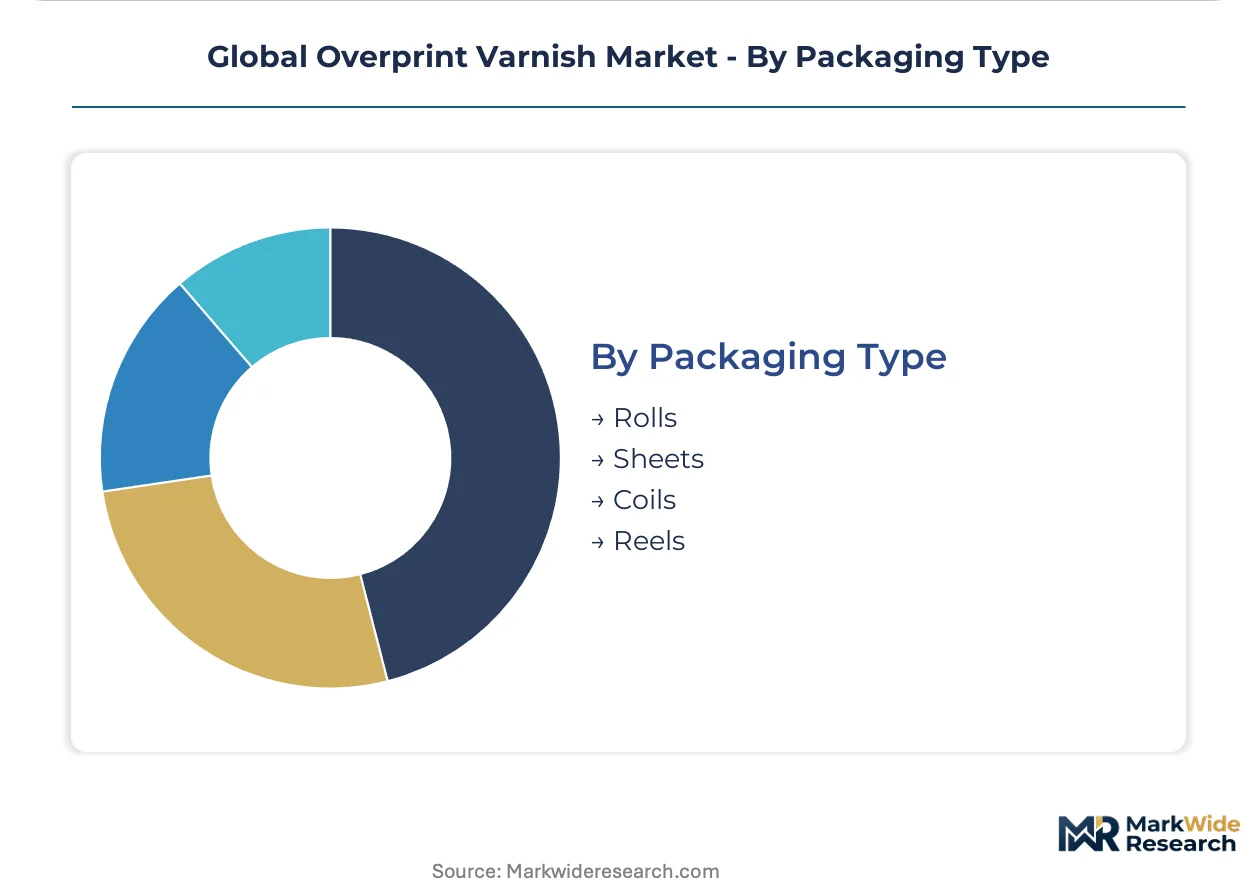
Rolls dominate the packaging type landscape for high-volume applications, with Sheets gaining share fastest in specialty print.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Policy and incentive drivers, such as stringent food contact material regulations, are fundamentally reshaping the global overprint varnish market. These frameworks compel manufacturers to prioritize low-migration chemistries and sustainable formulations. The market's evolution reflects a global push for both product safety and environmental compliance across diverse regions.
United States
United States demand for overprint varnish stems from expanding e-commerce packaging and robust food safety requirements. The US FDA's stringent rules for food contact materials dictate formulation choices for domestic suppliers. Manufacturing clusters in the Midwest continue to drive innovation in protective and aesthetic coatings for consumer goods.
Germany
German market expansion is driven by the country's advanced packaging industry and strong sustainability mandates. Europe's ECHA and REACH regulations enforce rigorous chemical substance controls for all varnish formulations. The Rhine-Ruhr region, a chemical industry hub, leads in developing compliant, high-performance solutions.
China
China's overprint varnish consumption accelerates with its vast manufacturing base and growing domestic consumer goods sector. The nation's GB standards for food contact materials directly influence product development and market access. Industrial clusters in the Pearl River Delta and Yangtze River Delta are focal points for high-volume varnish production.
India
India's market growth is supported by its rapidly expanding food and beverage packaging industry and increasing urbanization. The Bureau of Indian Standards (BIS) guides product safety and quality for packaging materials. Western India's manufacturing zones are witnessing substantial investment in modern printing and varnishing capabilities.
Japan
Japanese demand reflects a strong emphasis on high-quality printing and advanced functional packaging solutions. Japan's domestic food safety regulations and JIS standards mandate precise material specifications for varnishes. The Kanto region's sophisticated printing industry prioritizes superior finish quality and environmental compliance.
Global Overprint Varnish Market Key Industry Players
Listed leaders compete with private specialists across the full spectrum of overprint varnish formulations. The market structure includes global chemical conglomerates, specialized varnish producers, and regional players with distinct capabilities. Archetypes range from integrated material science firms to niche providers focusing on specific application technologies. Companies are pursuing strategic partnerships and portfolio diversification to enhance market reach and product offerings.
Specialists in advanced packaging solutions include Siegwerk Druckfarben, which exemplifies a strategic focus on product safety and regulatory compliance within the packaging segment. This firm's approach highlights the increasing importance of low-migration chemistries for food contact materials. Altana, a German-based company, represents innovation through its comprehensive portfolio of specialty additives that enhance varnish performance characteristics like scuff resistance and visual appeal. Sun Chemical Corporation, with its extensive global manufacturing footprint, anchors the market as a major player serving multinational consumer goods clients with a wide array of overprint varnish formulations and regional support capabilities.
| Leading Market Players |
|---|
| Van Son Ink Corporation |
| Michelman |
| Zeller+Gmelin |
| Altana |
| Toyo Ink |
| Huber Group |
| CHT/BEZEMA |
| Sun Chemical Corporation |
| Siegwerk Druckfarben |
| Others |
Cost & Logistics Intelligence
US FDA's food contact material regulations profoundly gate both overprint varnish supply qualification and price differentiation. These stringent standards compel manufacturers to invest in specific chemistries, directly influencing market access and product value across packaging applications.
Pricing Analysis
Certification level (FDA-grade, EU REACH compliance) creates the primary spread in overprint varnish pricing. The dominant pricing structure is contract-based long-term offtake for high-volume users, complemented by per-unit transactional pricing for specialty formulations. Price differentiation stems from the specific performance characteristics, such as scuff resistance or instant curing, and the volume scale of the order. Pricing softness reflects intense competition for standard glossy varnish applications, particularly in Asia. Label printers are highly price-sensitive for commodity varnishes, while luxury packaging brands prioritize performance and certification over cost.
Supply Chain Analysis
Just-in-time inventory management is common for high-volume, standard overprint varnishes, while specialty formulations often require strategic stockpiles due to complex raw material sourcing. Geographic supply concentration centers on manufacturing hubs in China, Germany, and the United States. The industry relies heavily on petrochemical-derived inputs like acrylic resins, polyurethane resins, and photoinitiators. Commodity price volatility for these chemical precursors presents a significant structural risk. Distribution runs through a network of specialized chemical distributors and direct sales channels to large printing houses and packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The overprint varnish market is experiencing high-growth disruption, driven by the rapid adoption of UV and EB curing technologies. This technological inflection point is fundamentally transforming production efficiencies and finish quality across the packaging sector.
For Market Incumbents:Compound existing regulatory compliance expertise by investing in advanced low-migration chemistries for food contact materials. Expand production capacity for UV and EB varnishes in high-demand regions like China's Pearl River Delta to counter margin pressure from conventional formulations. The threat of substitution from film laminates necessitates continuous R&D in barrier properties. Prioritize strategic partnerships with major packaging converters to secure long-term offtake agreements.
For New Entrants and Emerging Players:Anchor in specialized bio-based varnish formulations that align with circular economy principles for brand owners. Target underpenetrated markets in Southeast Asia, particularly Vietnam and Indonesia, where nascent packaging industries are growing. The most penetrable application segment is high-performance flexible packaging requiring advanced barrier properties. A go-to-market angle emphasizing validated sustainability certifications and compliant chemistries offers a distinct competitive advantage.
For Investors and Strategic Acquirers:Europe's REACH and FCM regulations reshape the acquisition landscape, favoring companies with robust portfolios of compliant, low-migration overprint varnishes. The long-term viability of this market hinges on continuous innovation in sustainable and functional coatings over the next decade. Acquisition targets should be niche specialists possessing proprietary UV/EB curing technologies or advanced bio-based formulation expertise. A critical signal to watch is the increasing adoption rate of formal recyclability or compostability certifications across major consumer brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced UV/EB Varnish R&D | Develop next-generation instant-curing formulations to meet rising demand for high-speed packaging lines. |
| Bio-Based Formulation Investment | Align with brand owners' corporate sustainability goals and circular economy principles through renewable feedstocks. |
| Regulatory Compliance Certification | Secure essential food contact material approvals, like US FDA and EU EFSA, for market access and product trust. |
| Southeast Asia Market Entry | Capitalize on the rapidly expanding packaging industries in Vietnam and Indonesia for new revenue streams. |
| Functional Coating Integration | Incorporate specialty additives for antimicrobial or thermochromic properties, enhancing product differentiation. |
Research Approach
Operator-level perspectives from R&D directors, procurement leads at packaging converters, and regulatory compliance officers anchored the qualitative base of this study. Primary interviews with these industry stakeholders were rigorously validated against secondary sources. These included customs and trade data, chemical industry association reports, and regulatory body publications from the US FDA and EU ECHA. A robust bottom-up and top-down triangulation approach was employed to ensure data accuracy and market sizing integrity.
Sensitivity analysis informed the development of the forecast framework across the analysis window, accounting for potential shifts in market dynamics. Segmentation dimensions modeled included product type, application, end-user industry, and regional regulatory clusters. Compound Annual Growth Rates were derived using historical data trends and projected market drivers. Industry-specific forecast inputs included anticipated shifts in food contact material regulations and the adoption rate of UV/EB curing technologies.
Decision-makers should treat outputs as directional under base assumptions of stable petrochemical raw material costs and consistent regulatory enforcement; material deviation would warrant model refresh. Forecasts reflect these assumptions concerning global economic stability and technological progression in varnish chemistries. Revision becomes warranted when major regulatory changes, such as new global standards for recyclability, cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
Sapphire Glass Market
Chemicals & Materials
Chlorine Market
Chemicals & Materials
Mud Sediment Tester Market
Chemicals & Materials
Basil Extracts Market
Chemicals & Materials
Pegylated Lipids Market
Chemicals & Materials
Filter Bag Market
Chemicals & Materials
Global VOC Catalysts Market
Chemicals & Materials
Global Hyaluronic Acid Based Dermal Fillers Market
Chemicals & Materials
Elastomeric Couplings Market
Chemicals & Materials
Galvanized Iron Pipes Market
Chemicals & Materials
South America Membrane Water and Wastewater (WWT) Treatment Market
Chemicals & Materials
North America Potassium Permanganate Market
Chemicals & Materials
Acrylamide Reducing Ingredients Market
Chemicals & Materials
Anti-Static Oil Market
Chemicals & Materials
Global MS Polymer Adhesives Market
Chemicals & Materials
Sodium Methyl P-Hydroxybenzoate Market