
 Ink-Cartridge Market | 2026-2036
Ink-Cartridge Market Size, Share, and Industry Trends Forecast 2026-2036
Ink-Cartridge Market Foresight
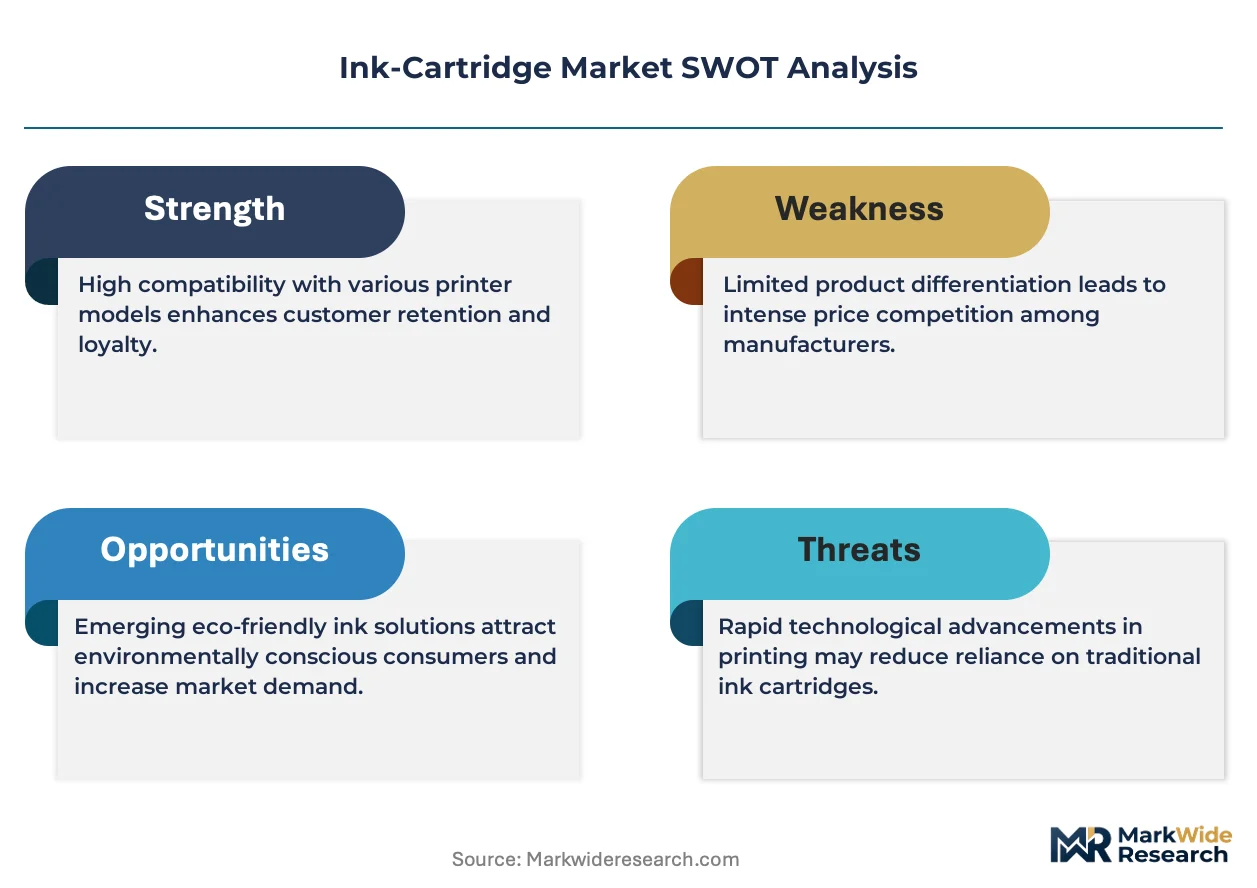
Home office printing is expanding as a durable post-pandemic end-use vertical, while large enterprise print volumes contract under digitization mandates. HP Inc. leverages its installed base of OfficeJet and ENVY systems to sustain recurring ink revenue through subscription models. Canon Inc. anchors its position in photography and graphics workflows where pigment-based formulations command loyalty. Brother Industries Ltd. competes on total cost of ownership in small office segments with high-yield cartridge architectures.
An ink-cartridge is a self-contained consumable module housing ink reservoirs, printhead interfaces, and electronic authentication chips, engineered to deliver measured droplet deposition onto substrates at resolutions typically exceeding 1200 dots per inch for document and image reproduction. The product type segment stratifies sharply: original equipment manufacturer cartridges capture the margin pool through chip-based lock-in architectures, while compatible and remanufactured alternatives erode share on price sensitivity in cost-conscious verticals. The technology dimension shows inkjet retaining volume dominance across household and educational end users, whereas laser toner cartridges concentrate in large enterprise fleets where page yield economics outweigh hardware acquisition costs.
The EPA regulates volatile organic compound emissions from ink formulations in the United States, compelling reformulation toward water-based and soy-derived carrier chemistries. REACH and RoHS frameworks in Europe restrict hazardous substances in cartridge plastics and residual ink compounds, raising compliance costs for non-compliant imports. Stakeholders must monitor evolving extended producer responsibility mandates that shift end-of-life collection burdens onto manufacturers, reshaping channel economics and recycling infrastructure investment priorities.
Market Dynamics
Hybrid work stabilization is fragmenting demand between home office replenishment cycles and enterprise fleet consolidation, forcing cartridge manufacturers to bifurcate supply chains between high-frequency consumer SKUs and yield-optimized commercial formats.
Growth Catalysts
- REACH chemical reformulation mandates:European ECHA enforcement is accelerating water-based ink adoption, creating premium positioning for compliant OEM formulations.
- Educational procurement cycles:United States K-12 and university print volumes sustain recurring demand for standard-yield cartridges during academic calendar peaks.
- Photography pigment loyalty:Graphics professionals in Japan and Germany maintain preference for archival-grade pigment systems resistant to dye-based substitution.
Market Restraints
- Input cost volatility:Specialized dye and pigment feedstock prices fluctuate with petrochemical indices, compressing margin on economy-tier compatible cartridges.
- Supply concentration risk:Microchip authentication components for OEM lock-in architectures concentrate among Taiwanese and South Korean semiconductor fabricators.
- Fundamental substitution threat:Electronic document workflows and e-signature platforms displace page volumes in legal, financial, and administrative verticals.
Strategic Opportunities
- Extended producer responsibility tailwinds:French and German EPR mandates for end-of-life cartridge collection create service-revenue streams for logistics-integrated suppliers.
- 3D printing convergence:Material jetting systems are integrating inkjet deposition heads with photopolymer and binder jetting chemistries for additive manufacturing workflows.
- Direct-to-consumer channel innovation:Subscription replenishment models bypass traditional office supply distributors, capturing lifetime value through automated chip-authenticated reorder triggers.
Industry Challenges
- Authentication chip engineering talent scarcity:Firmware engineers capable of integrating anti-cloning cryptography with printhead communication protocols command premium compensation in Taiwan and Israel.
- Multi-jurisdictional certification timelines:Simultaneous EPA VOC clearance, ECHA SVHC screening, and state-level California Proposition 65 compliance extend product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ink-Cartridge Market |
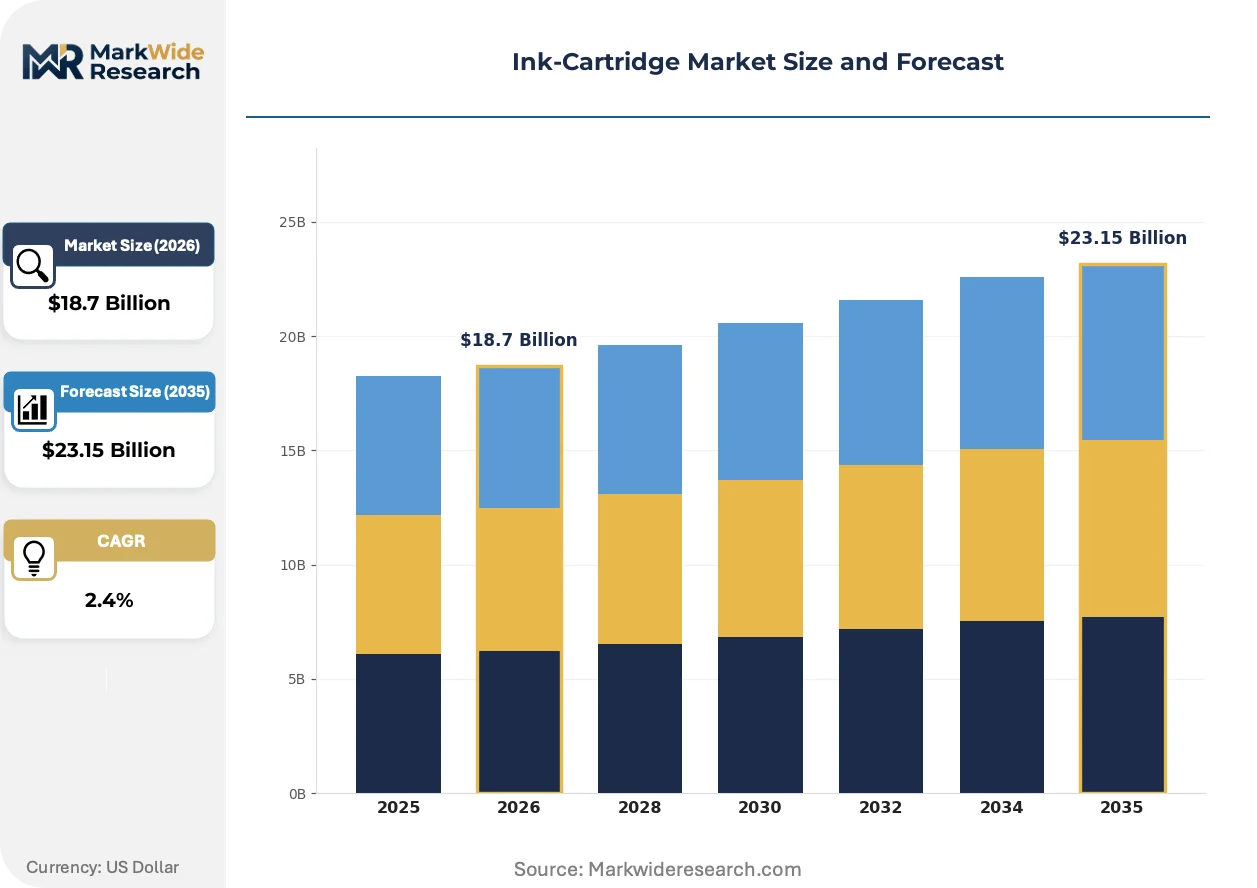
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $23.15 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Original Equipment Manufacturer, Compatible, Remanufactured, Bulk Ink End User: Households, Small Offices, Large Enterprises, Educational Institutions Technology: Inkjet, Laser, Thermal, Dye-Sublimation Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | HP Inc., Canon Inc., Seiko Epson Corporation, Brother Industries Ltd., Xerox Holdings Corporation, Lexmark International Inc., Ricoh Company Ltd., Konica Minolta Inc., Panasonic Holdings Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ink-Cartridge Market Shifts & Advancements
Active reformulation of carrier chemistries and authentication architectures is compressing the technology lifecycle, while regulatory fragmentation across North America and Europe forces parallel compliance investments.
AI-driven print optimization firmware is integrating machine learning algorithms that predict page coverage patterns and preemptively adjust droplet deposition density. Small office buyers in Germany and the United States are adopting these systems to extend cartridge yield without hardware replacement. The technology is integrating predictive analytics into subscription pricing models, enabling dynamic replenishment intervals based on actual usage rather than fixed calendar cycles.
EPA volatile organic compound regulations are tightening permissible solvent content in pigment dispersion formulations, compelling reformulation toward soy-derived and water-based carrier systems. Industrial consequence includes reduced shelf stability and accelerated printhead maintenance cycles for high-duty applications. Commercial print shops in California and Texas are responding by segregating equipment fleets between compliant document printers and exempt wide-format graphics systems.
Educational institutions are consolidating procurement through cooperative purchasing agreements that aggregate demand across district and state boundaries. Traditional distributor relationships with independent office supply dealers are yielding to direct contracts with OEM-managed e-procurement portals. This concentration is most visible in the United States, where Texas Education Agency and California Department of Education frameworks now specify chip-authenticated cartridges to prevent compatible substitution in standardized testing environments.
Ink-Cartridge Market Segmentation
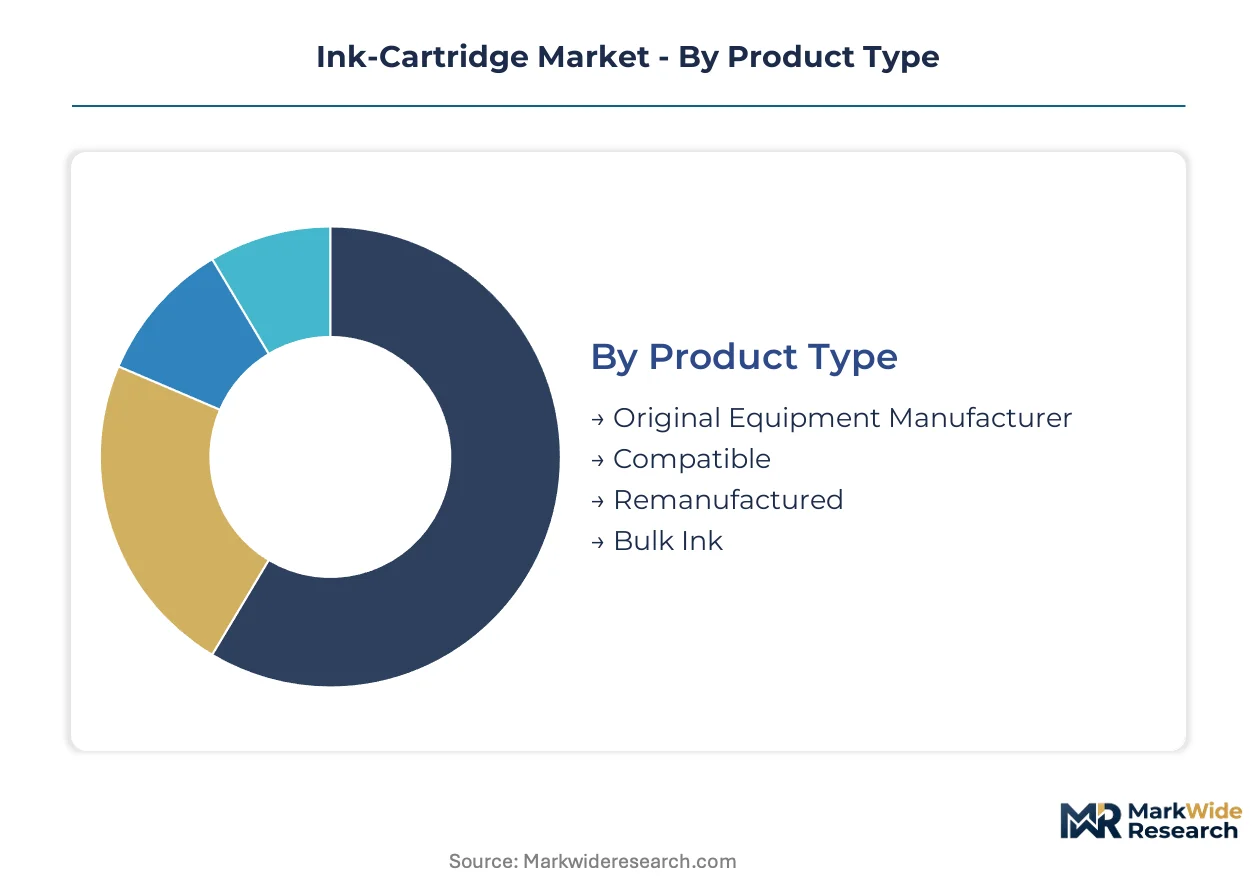
Cartridge manufacturers must architect discrete supply chains for each segment, as authentication requirements, yield specifications, and replenishment cadences diverge sharply across product types and end users. Segmentation discipline determines margin capture and compliance exposure.
Product Type:
Customization intensity varies from chip-authenticated lock-in architectures to commodity formulations with minimal firmware integration.
- Original Equipment Manufacturer:Proprietary authentication chips and printhead communication protocols create hardware-software interdependence. Demand concentrates in United States educational procurement and German graphics workflows where chip-verified output prevents compatible substitution in standardized testing and archival applications.
- Compatible:Third-party formulations reverse-engineered to bypass OEM authentication, competing on acquisition cost rather than yield optimization. Small offices in France and Italy select these alternatives for non-critical document output where print permanence requirements are minimal.
- Remanufactured:Collected OEM cores receive new ink reservoirs and replacement chips, extending material loops under extended producer responsibility mandates.
- Bulk Ink:Refill reservoirs for continuous ink supply systems, penetrating cost-sensitive high-volume households in Japan and South Korea.
Most installed capacity flows through Original Equipment Manufacturer architectures. Expansion is steepest in Remanufactured as French and German EPR collection infrastructure matures.
End User:
Volume scale and replenishment frequency create distinct margin profiles across customer types.
- Households:Fragmented demand with high SKU proliferation and low per-transaction value, served through subscription models with automated chip-authenticated reorder triggers. Hybrid work stabilization in the United States and Germany sustains replenishment cycles for home office document and photograph output.
- Small Offices:Cost-conscious buyers prioritize total cost of ownership calculations over acquisition price. Brother Industries and Canon distribution networks in Japan and the United States emphasize high-yield cartridge architectures for this segment.
- Large Enterprises:Fleet consolidation under digitization mandates contracts page volumes, shifting procurement toward managed print services with yield-optimized commercial formats.
- Educational Institutions:Cooperative purchasing agreements aggregate demand across district boundaries, with Texas and California frameworks specifying chip-authenticated cartridges for testing environments.
Revenue concentration sits with Small Offices. Educational Institutions are gaining share fastest as e-procurement portals displace independent distributors.
Technology:
Maturity curves and chemistry constraints segment investment priorities across deposition architectures.
- Inkjet:Piezoelectric and thermal droplet deposition dominate household and educational applications, with water-based and soy-derived carrier reformulations responding to EPA volatile organic compound regulations in the United States.
- Laser:Electrophotographic toner systems concentrate in enterprise fleets where page yield economics outweigh hardware costs, particularly in United States legal and financial verticals with residual paper workflows.
- Thermal:Wax-resin transfer for label and receipt printing, with specialized demand in logistics and retail point-of-sale.
- Dye-Sublimation:Solid dye diffusion for photographic output, retaining niche loyalty among Japanese and German graphics professionals for archival-grade image permanence.
Production scale favors Inkjet. Dye-Sublimation is expanding most quickly as photography pigment loyalty resists dye-based substitution.
Distribution Channel:
Channel economics reshape as direct relationships capture lifetime value previously extracted by intermediaries.
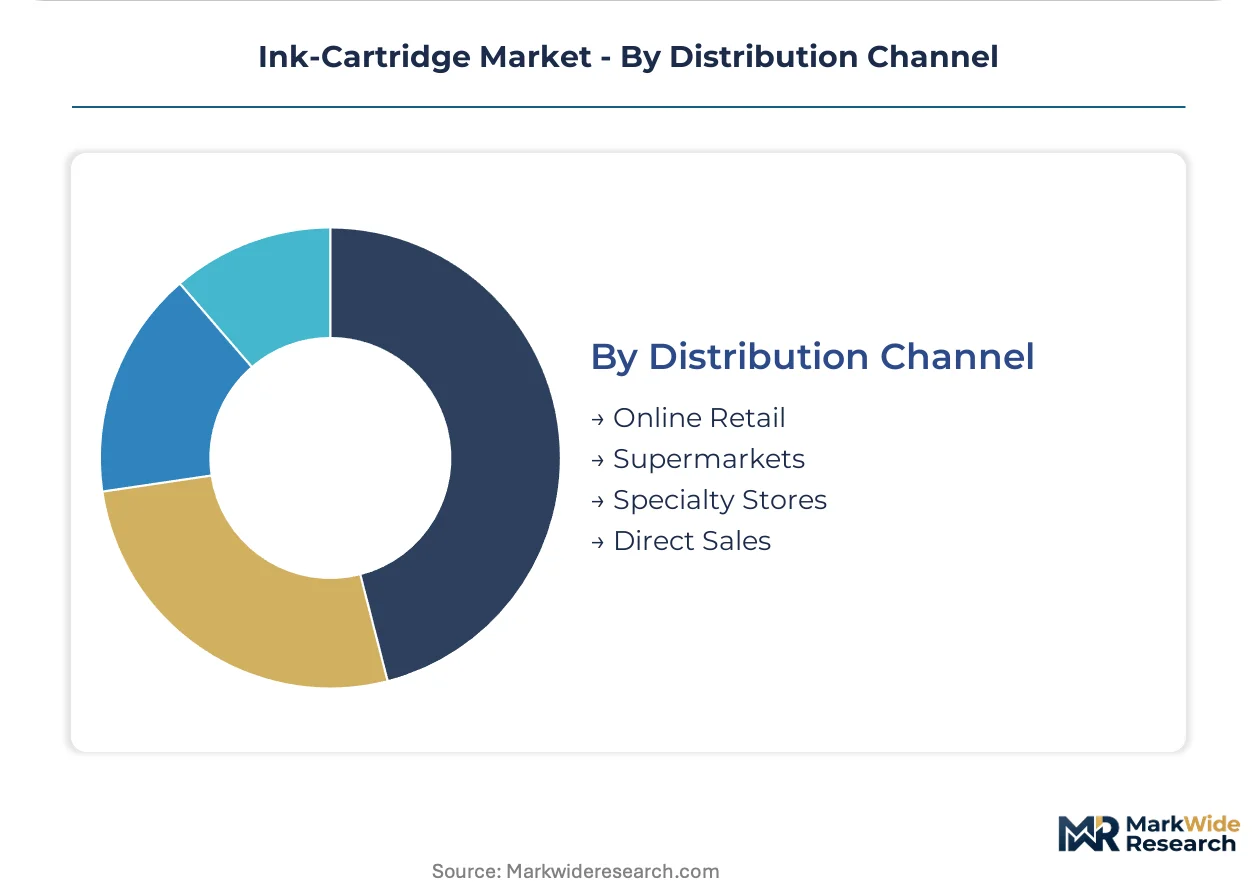
- Online Retail:Amazon and specialized office supply platforms aggregate price-transparent comparison, eroding regional distributor margins in the United States and United Kingdom.
- Supermarkets:Impulse replenishment for standard-yield consumer SKUs, with Walmart and Carrefour shelf space allocated by OEM trade spend intensity.
- Specialty Stores:Photography and graphics retailers in Japan and Germany provide technical consultation for pigment system selection.
- Direct Sales:OEM-managed e-procurement portals and subscription replenishment models bypass traditional distributors, capturing recurring revenue through automated chip-authenticated triggers.
Transaction volume flows through Online Retail. Direct Sales shows the steepest expansion trajectory as subscription models lock in lifetime value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as water-based ink reformulation costs diverge sharply between EPA jurisdictions and ECHA enforcement zones, prompting cartridge fabricators to relocate blending operations toward compliance-advantaged locations.
United States
Educational procurement through Texas Education Agency and California Department of Education frameworks sustains demand for chip-authenticated cartridges in standardized testing environments. EPA volatile organic compound regulations tighten solvent content limits, compelling reformulation investments. Dallas-Fort Worth logistics clusters concentrate distribution infrastructure for North American replenishment cycles.
Germany
Graphics professionals in Munich and Stuttgart maintain loyalty to archival-grade pigment systems for photography workflows. Extended producer responsibility mandates under German EPR frameworks shift end-of-life collection burdens onto manufacturers, raising compliance costs. The Rhine-Main manufacturing corridor hosts reformulation facilities serving EU REACH-compliant water-based ink production.
Japan
Household demand for continuous ink supply systems concentrates in Tokyo and Osaka metropolitan areas where bulk ink architectures penetrate cost-sensitive high-volume segments. METI chemical substance regulations govern residual ink compound disposal standards. Nagoya industrial clusters integrate piezoelectric printhead manufacturing with cartridge assembly operations.
France
Small offices in Paris and Lyon select compatible alternatives for non-critical document output where print permanence requirements remain minimal. EPR collection infrastructure maturity accelerates remanufactured cartridge adoption under French environmental compliance frameworks. The Lyon-Grenoble corridor specializes in logistics-integrated supplier operations for circular material loops.
South Korea
Semiconductor fabricators in Seoul and Suwon concentrate production of microchip authentication components for OEM lock-in architectures. Domestic chemical regulations align with REACH substance restrictions, reducing reformulation friction for export-oriented manufacturers. The Gyeonggi-do industrial belt supplies authentication firmware to cartridge producers across Asia-Pacific.
Ink-Cartridge Market Competitive Landscape
Subscription model expansion dominates the current landscape as cartridge manufacturers capture lifetime value through automated replenishment triggers. The vendor base stratifies across three tiers: integrated hardware-ink systems operators, third-party compatible specialists, and remanufactured material loop managers. Strategic archetypes include chip-authentication technology licensors, high-yield architecture designers, and EPR logistics integrators. Portfolio diversification toward managed print services and geographic expansion into educational procurement channels represent the dominant competitive moves.
Within the integrated systems tier, HP Inc. and Canon Inc. exemplify hardware-ink interdependence strategies, while Brother Industries Ltd. occupies a position emphasizing total cost of ownership calculations for small office segments. These three anchors represent divergent approaches to authentication architecture, yield optimization, and distribution channel control across hybrid work and enterprise fleet end uses.
| Leading Market Players |
|---|
| HP Inc. |
| Canon Inc. |
| Seiko Epson Corporation |
| Brother Industries Ltd. |
| Xerox Holdings Corporation |
| Lexmark International Inc. |
| Ricoh Company Ltd. |
| Konica Minolta Inc. |
| Panasonic Holdings Corp. |
| Others |
Supply & Pricing Matrix
Pigment and dye feedstock costs originating from petrochemical indices flow through Taiwanese semiconductor fabricators and German formulation facilities before stratifying into three distinct pricing tiers downstream. Authentication chip premiums concentrate margin at the OEM level while compatible alternatives compete on stripped-down acquisition cost for price-sensitive small offices in France and Italy.
Pricing Analysis
Distributor margins for traditional office supply channels face compression as direct-to-consumer subscription models bypass intermediary layers entirely. Three-tier pricing structure across premium, standard, and economy levels separates chip-authenticated OEM cartridges from reverse-engineered compatibles and remanufactured alternatives. Pricing pressure stems from educational procurement consolidation through cooperative purchasing agreements that aggregate demand across state boundaries. Small offices exhibit highest price sensitivity and select compatible alternatives for non-critical document output, whereas graphics professionals in Germany and Japan demonstrate lowest sensitivity due to archival-grade pigment loyalty.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and the Rhine-Main corridor coordinate hub-and-spoke patterns for North American and European replenishment cycles respectively. Manufacturing concentration spans Taiwan and South Korea for authentication microchips, Germany and Japan for pigment formulation, and China for plastic cartridge molding. Raw material dependencies center on specialized dye and pigment feedstocks, semiconductor components, and petroleum-derived carrier chemistries. Single-source vulnerability concentrates in Taiwanese and South Korean semiconductor fabricators supplying OEM lock-in architectures. Distribution runs through OEM-managed e-procurement portals, Amazon-aggregator platforms, and residual specialty photography retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH chemical reformulation mandates in Europe continuously reset formulation standards and create recurring compliance-driven demand for premium water-based ink systems.
For Market Incumbents: Hedge against fundamental substitution threats from electronic document workflows by deepening subscription model penetration with automated chip-authenticated reorder triggers. Secure backward integration into authentication firmware engineering capabilities in Taiwan and Israel where talent scarcity commands premium compensation. Defend margin position through high-yield cartridge architectures for small office segments where Brother Industries has established total cost of ownership positioning. For New Entrants and Emerging Players: Extended producer responsibility mandates in France and Germany open a window for logistics-integrated remanufactured cartridge specialists to capture service-revenue streams from end-of-life collection infrastructure. Target the compatible segment for non-critical document output in French and Italian small offices where print permanence requirements remain minimal. Pursue direct-to-consumer channel innovation with subscription replenishment models that bypass traditional office supply distributors. For Investors and Strategic Acquirers: Roll-up economics work for regional remanufacturing specialists because EPR collection infrastructure maturity in France and Germany creates fragmented acquisition targets with established reverse logistics networks. Long-term viability hinges on regulatory tailwinds persisting across the European Union with chemical reformulation mandates expanding geographically. Watch for inflection in 3D printing convergence where material jetting systems integrate inkjet deposition heads with additive manufacturing workflows.| Strategic Initiative | Industry Significance |
|---|---|
| Authentication Chip Backward Integration | In-house firmware engineering in Taiwan reduces exposure to semiconductor fabricator concentration risk. |
| Water-Based Ink Reformulation Investment | EPA VOC compliance in the United States and REACH alignment in Europe secures premium positioning. |
| Subscription Model Expansion | Automated chip-authenticated reorder triggers capture lifetime value previously extracted by distributors. |
| EPR Logistics Integration | French and German collection infrastructure creates service-revenue streams from circular material loops. |
| Direct E-Procurement Portal Development | Texas Education Agency and California Department of Education frameworks specify chip-authenticated procurement. |
Research Methodology
Coverage spans the United States, Germany, Japan, France, and South Korea, with primary inputs from each market through structured interviews with cartridge manufacturing executives, educational procurement officers, graphics workflow professionals, distribution channel partners, and regulatory compliance specialists. Secondary validation draws from EPA VOC emission filings, ECHA SVHC substance databases, SEC 10-K disclosures from listed OEMs, and customs trade data for pigment and dye feedstock flows. Bottom-up demand modeling triangulates against top-down market sizing across product type, end user, technology, and distribution channel dimensions.
Granularity-level modeling disaggregates volume and value outputs across the analysis window by original equipment manufacturer, compatible, remanufactured, and bulk ink product types intersecting with household, small office, large enterprise, and educational institution end users. CAGRs derive from trend extrapolation of historical replenishment cycle data adjusted for hybrid work stabilization effects and educational procurement calendar patterns. Industry-specific forecast inputs include petrochemical index volatility for pigment feedstock costs and EPR mandate implementation timelines across European jurisdictions.
Revisions become necessary when semiconductor supply disruptions, REACH substance restriction expansions, or accelerated enterprise digitization adoption materialize beyond baseline assumptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and substitution technology penetration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Global Conductive Inks Market
Printing Inks
Global Flexographic Inks Market
Printing Inks
Ink Resins Market
Printing Inks
Squid Ink Market
Printing Inks
Security Printing Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
Rapid Liquid Printing Market
Printing Inks
Screen Printing Inks Market
Printing Inks
Global Ceramic Inks Market
Printing Inks
Solder Resist for Inkjet Printer Market
Printing Inks
United States Printing Inks Market
Printing Inks
North America Ink Market
Printing Inks
Rotogravure Printing Inks Market
Printing Inks
Global Dye Sublimation Inks Market
Printing Inks
Functional Printing Market
Printing Inks
Global Printing Blanket Market