
 Specialty Ink Market | 2026-2036
Specialty Ink Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Ink Market Outlook
Flexible packaging printing is expanding as snack food brands and pharmaceutical blister pack converters migrate from solvent-based to UV-curable and water-based systems. Sun Chemical leverages captive resin synthesis to control raw material variability across its digital ink portfolio. Siegwerk Druckfarben AG & Co. KGaA anchors European flexographic supply through dedicated technical service hubs in Germany and Poland. Nazdar Ink Technologies specializes in narrow-web UV inkjet formulations for industrial label printers seeking short-run customization.
Specialty ink denotes engineered colorant systems formulated with specific viscosity, surface tension, and curing kinetics for targeted substrate adhesion and end-use performance. These formulations incorporate photoinitiators, oligomers, and functional pigments to achieve chemical resistance, electrical conductivity, or optical effects beyond standard graphic reproduction. Digital ink is capturing margin pools in short-run packaging and personalized textile applications where setup costs and waste reduction outweigh per-unit ink premiums. UV-curable formulations lead growth in food-contact packaging as converters replace thermal drying ovens with instant polymerization under LED arrays. Water-based gravure ink retains volume dominance in corrugated board printing despite slower drying speeds on coated stocks.
FDA migration thresholds for food-contact materials and EPA VOC emission limits constrain solvent-based formulation choices in North American packaging. ECHA REACH Annex XVII restrictions on aromatic amines and heavy metal pigments redirect European sourcing toward compliant pigment intermediates from certified suppliers. Stakeholders must monitor regulatory divergence between EPA 40 CFR printing MACT standards and EU F-Gas Regulation impacts on UV curing equipment refrigerants, as compliance cost asymmetries will reshape competitive plant location decisions.
Market Dynamics
LED-UV curing hardware is compressing thermal drying infrastructure across narrow-web label converters, forcing simultaneous ink reformulation and capital equipment replacement cycles throughout the supply base.
Growth Catalysts
- REACH Annex XVII photoinitiator restrictions:ECHA mandates on benzophenone and 4-methylbenzophenone are accelerating migration-compliant formulation development across European food-contact packaging.
- Flexible packaging converters:Snack food brands in Germany are replacing solvent-based rotogravure with UV-curable flexographic systems to eliminate thermal oven footprint and VOC permitting.
- Pharmaceutical blister packs:FDA migration thresholds for indirect food-contact materials are driving low-migration ink adoption in North American pharma packaging lines.
Market Restraints
- Photoinitiator supply concentration:German and Chinese suppliers dominate acylphosphine oxide production, creating input cost volatility during energy price spikes.
- Legacy thermal drying asset base:Corrugated board printers in the US Midwest carry fully depreciated natural gas ovens that resist LED-UV retrofit economics.
- Water-based gravure performance ceiling:Slower drying speeds on coated folding carton stocks constrain throughput versus solvent alternatives.
Strategic Opportunities
- Indian flexible packaging:FSSAI food-contact compliance deadlines are opening formulation partnerships for UV-curable systems in Mumbai and Ahmedabad converter clusters.
- Textile digital printing:Reactive dye inkjet convergence with on-demand garment production is integrating specialty ink into short-run fashion supply chains.
- EU F-Gas Regulation phase-down:Refrigerant restrictions on UV curing equipment are creating service contract opportunities for LED array retrofits.
Industry Challenges
- Formulation chemist scarcity:Photoinitiator-oligomer compatibility expertise concentrates among senior chemists at German and Japanese resin suppliers.
- Dual certification timelines:Simultaneous FDA food-contact notification and EU REACH registration extend product launch cycles for new ink systems.
- Legacy ERP integration:UV-curable ink production requires real-time viscosity monitoring that conflicts with batch-oriented MRP systems at mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Ink Market |
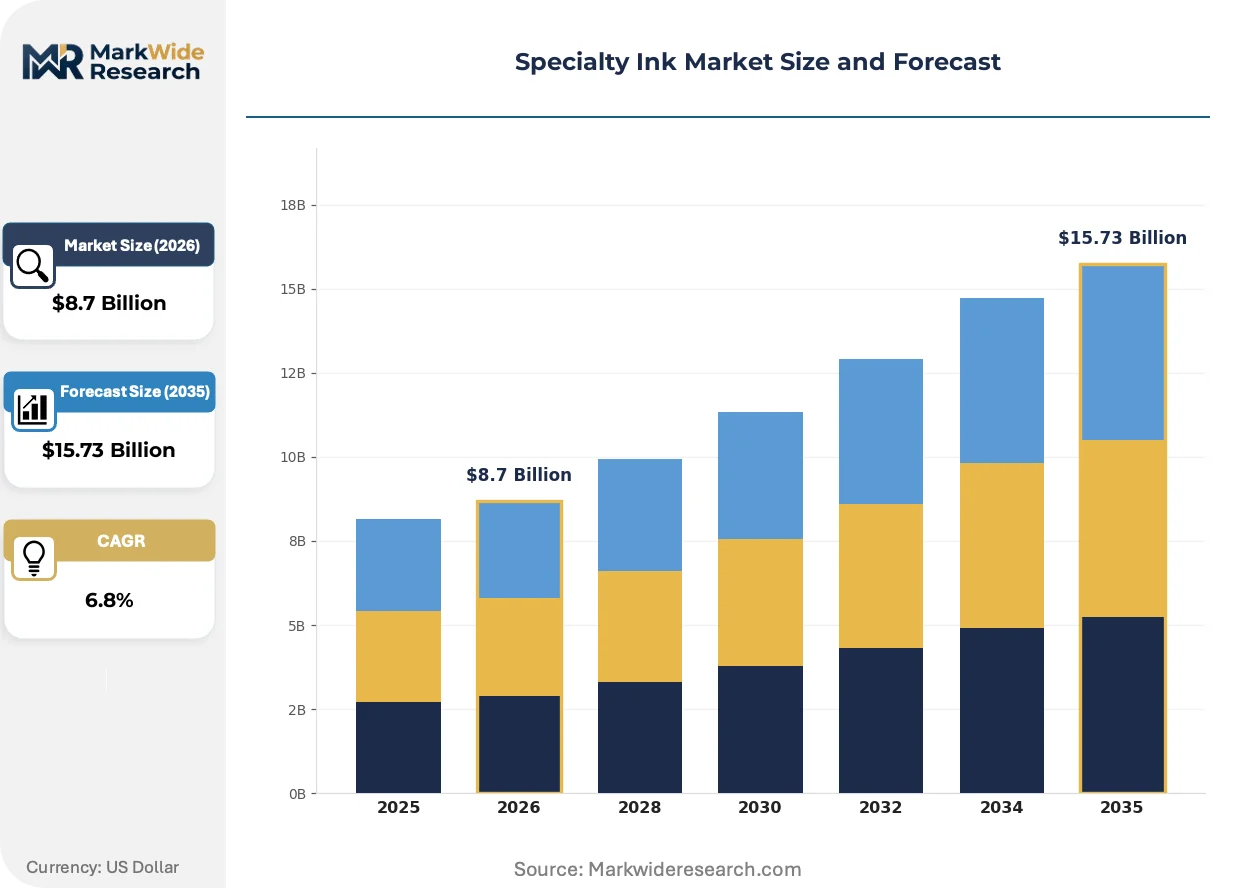
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexographic Ink, Gravure Ink, Digital Ink, Screen Ink Application: Packaging, Textile Printing, Commercial Printing, 3D Printing Formulation: Water-Based, Solvent-Based, Oil-Based, UV-Curable End User: Printing Companies, Textile Manufacturers, Packaging Firms, Creative Agencies |
| Companies Covered | INX International, Huber Group Holding SE, Sun Chemical, DuPont, Nazdar Ink Technologies, Siegwerk Druckfarben AG & Co. KGaA, Flint Group, T&K TOKA Corporation, Toyo Ink International Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Ink Market Strategic Shifts
Photoinitiator chemistry, curing hardware, and substrate pre-treatment are converging to enable single-pass digital production at speeds that challenge analog methods.
LED-UV photoinitiator systems are integrating TPO-L and BAPO variants optimized for 395nm peak wavelength arrays. Narrow-web label converters in Wisconsin and Bavaria are retrofitting presses with these arrays to eliminate mercury arc lamp warm-up delays. The technology is integrating instant polymerization into just-in-time label production, compressing job turnaround from days to hours.
ECHA REACH restrictions on aromatic amine pigment intermediates are forcing European ink manufacturers toward certified azo-free alternatives. Reformulation costs are concentrating among small- and mid-tier suppliers lacking captive pigment synthesis. Specialty ink producers serving German pharmaceutical blister pack exporters are absorbing compliance costs through dedicated technical service premiums.
Brand owners are consolidating print procurement under sustainability scorecards that weight VOC elimination and renewable content. Food and beverage packaging buyers in California and the Netherlands are unbundling ink supply from press maintenance contracts to audit environmental claims directly. This pattern is most visible in snack food flexible packaging, where EPR legislation in Germany and California mandates recycled content targets that ink suppliers must certify against.
Specialty Ink Market Segmentation
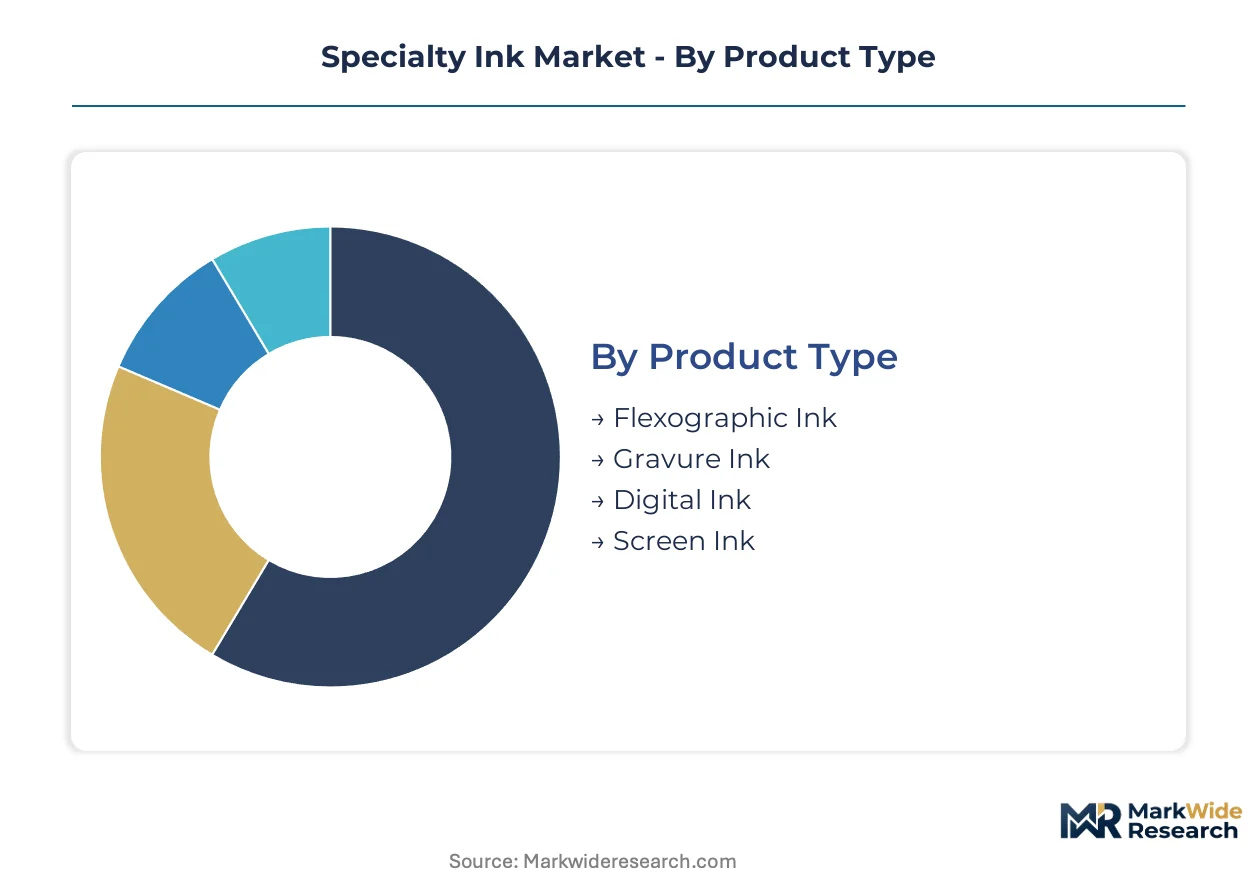
Specialty ink segmentation reveals distinct value pools where formulation chemistry, curing hardware, and substrate compatibility intersect. Each dimension carries different margin profiles and regulatory exposure that reshape supplier positioning across converter tiers.
Product Type:
Product types span standalone fluid systems and integrated press-ink combinations where converter technical service dependencies determine supplier stickiness.
- Flexographic Ink:Anilox-metered fluid systems formulated for rapid viscosity recovery between impression cycles. Demand clusters around German flexible packaging exporters serving Central European snack food brands under ECHA REACH migration compliance deadlines.
- Digital Ink:Piezoelectric and thermal inkjet formulations with precise surface tension control for single-pass deposition. Narrow-web label converters in Wisconsin and Bavaria are retrofitting presses with LED-UV arrays to compress job turnaround from days to hours.
- Gravure Ink:Low-viscosity solvent and water-based systems for engraved cylinder reproduction.
- Screen Ink:High-viscosity pastes with thixotropic behavior for stencil-based deposition.
Flexographic ink leads volumes today; digital ink is gaining share fastest.
Application:
Applications distribute across cost tiers where regulatory stringency and brand owner sustainability scorecards drive specification divergence.
- Packaging:Food-contact, pharmaceutical, and industrial containment applications requiring migration-compliant formulations. FDA notification thresholds and EU REACH Annex XVII restrictions on photoinitiators are forcing dual-certification investments from suppliers serving export markets.
- Textile Printing:Reactive dye and pigment inkjet systems for on-demand garment production. Digital convergence with short-run fashion supply chains is integrating specialty ink into Mumbai and Ahmedabad converter clusters ahead of FSSAI compliance deadlines.
- Commercial Printing:Offset and digital sheetfed applications for marketing collateral and publication.
- 3D Printing:Photopolymer resins with tunable cure depth for vat polymerization systems.
Packaging commands the largest revenue pool; textile printing shows the steepest expansion trajectory.
Formulation:
Formulations segment by curing kinetics and volatile compound exposure, with capital equipment replacement cycles locking in technology choices for decade-long horizons.
- UV-Curable:Acrylate oligomer systems with photoinitiator packages optimized for 395nm LED arrays. Snack food brands in Germany are replacing solvent-based rotogravure with UV-curable flexographic systems to eliminate thermal oven footprint and VOC permitting.
- Water-Based:Acrylic and polyurethane dispersions with co-solvent humectants for porous substrate penetration. Slower drying speeds on coated folding carton stocks constrain throughput versus solvent alternatives in corrugated board printing.
- Solvent-Based:Nitrocellulose and polyurethane systems with rapid evaporation profiles.
- Oil-Based:Vegetable oil and mineral oil vehicles for heatset web offset applications.
Water-based formulations retain volume dominance; UV-curable systems are climbing the fastest.
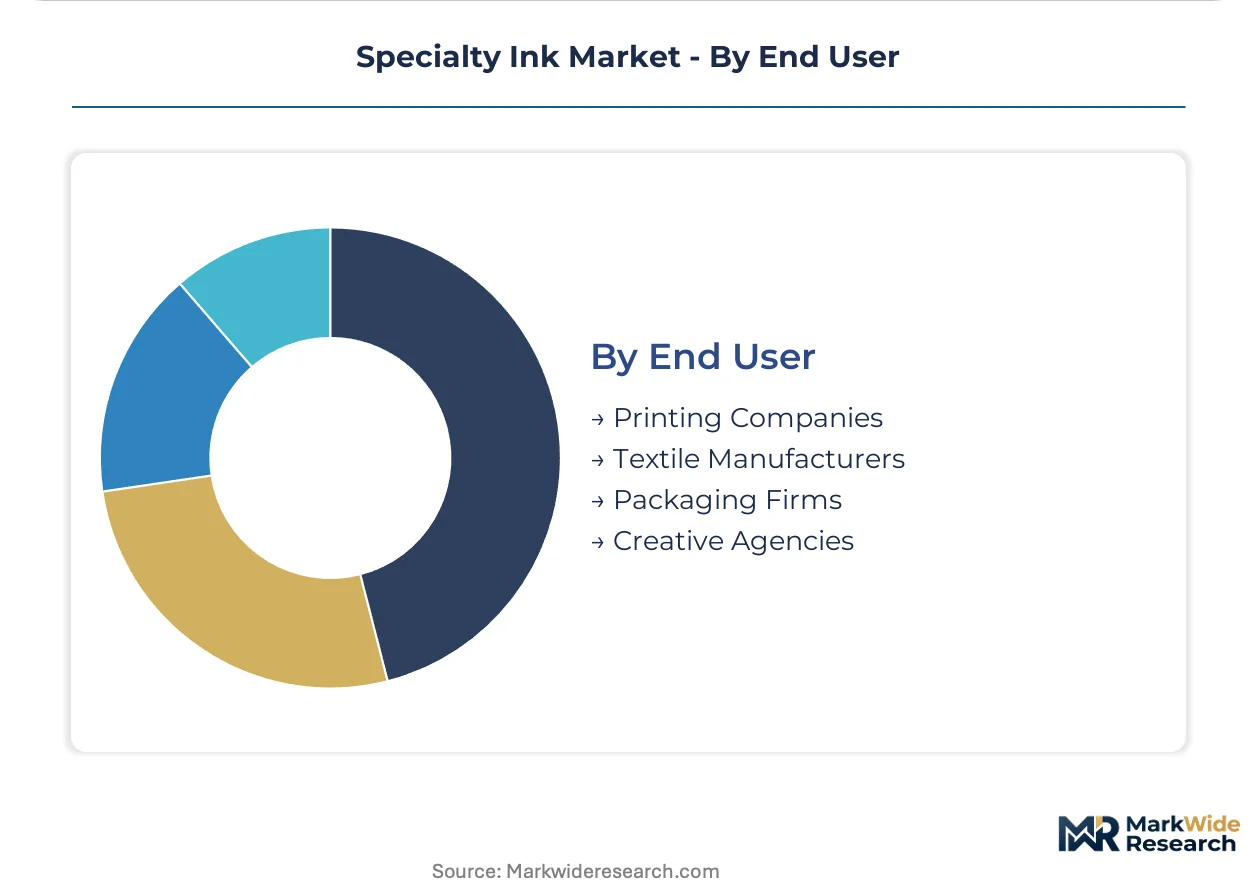
End User:
End users distribute across customer types where technical service intensity and formulation customization requirements create distinct procurement patterns.
- Packaging Firms:Flexible and rigid container converters with integrated pre-press and finishing operations. EPR legislation in Germany and California mandates recycled content targets that ink suppliers must certify against through unbundled environmental auditing.
- Printing Companies:Commercial and specialty graphic service providers with equipment-diverse floors. Legacy ERP integration conflicts with real-time viscosity monitoring requirements for UV-curable production.
- Textile Manufacturers:Fabric mills and garment producers with digital printing adoption.
- Creative Agencies:Design studios and brand consultancies with specification influence.
Packaging firms drive the largest formulation volumes; printing companies present the most fragmented procurement landscape.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heidelberg and Würzburg anchor European specialty ink demand through export-oriented flexible packaging clusters serving Central European snack food brands. Regulatory divergence between EPA and ECHA frameworks is reshaping plant location decisions across converter networks. India and Southeast Asia present expansion vectors as FSSAI compliance deadlines approach.
Germany
Flexible packaging converters in Heidelberg and Würzburg are scaling UV-curable ink purchases for high-speed label production serving export markets. ECHA REACH Annex XVII restrictions on benzophenone photoinitiators are accelerating migration-compliant reformulation investments. The Bavaria cluster concentrates technical service hubs from Siegwerk Druckfarben AG & Co. KGaA supporting pharmaceutical blister pack exporters.
United States
Narrow-web label converters in Wisconsin are retrofitting presses with LED-UV arrays to compress job turnaround timelines. FDA migration thresholds for indirect food-contact materials constrain solvent-based formulation choices in pharmaceutical packaging lines. The Midwest corrugated board segment retains natural gas thermal drying infrastructure that resists LED-UV retrofit economics.
India
FSSAI food-contact compliance deadlines are opening formulation partnerships for UV-curable systems in Mumbai and Ahmedabad converter clusters. The central food safety regulator mandates migration testing protocols that mirror EU REACH Annex XVII frameworks. Textile digital printing adoption in Tiruppur and Surat is integrating reactive dye inkjet into short-run fashion supply chains.
China
Acylphosphine oxide photoinitiator production concentrates among domestic suppliers serving flexographic ink formulators. SAMR food-contact material standards are converging with FDA notification thresholds for export-oriented packaging manufacturers. The Yangtze River Delta houses converter clusters supplying snack food brands with water-based gravure systems for corrugated board applications.
Japan
METI industrial standards for UV-curable printing equipment are driving LED array adoption among narrow-web label converters. Photoinitiator-oligomer compatibility expertise concentrates among senior chemists at domestic resin suppliers serving specialty ink formulators. The Kanto region maintains technical service density for pharmaceutical packaging applications requiring low-migration certification.
Specialty Ink Market Competitive Environment
Strategic partnerships dominate the current landscape as suppliers seek to bridge formulation chemistry and curing hardware integration. The vendor base clusters around three tiers: integrated chemical conglomerates with captive resin synthesis, mid-tier specialists with regional technical service density, and narrow-web digital inkjet formulators. Consolidation pressure concentrates among small- and mid-tier suppliers lacking certified pigment intermediates for ECHA REACH compliance. Technology licensing and geographic expansion represent the dominant competitive vectors as converters unbundle ink supply from press maintenance contracts.
Among Germany-based formulators, Siegwerk Druckfarben AG & Co. KGaA and Huber Group Holding SE exemplify the technical service-intensive archetype anchoring European flexographic supply. Sun Chemical occupies a position representing integrated chemical conglomerates with backward control over raw material variability across digital ink portfolios. These three entities illustrate how supplier positioning stratifies between resin-captive scale and regional formulation proximity to converter clusters.
| Leading Market Players |
|---|
| INX International |
| Huber Group Holding SE |
| Sun Chemical |
| DuPont |
| Nazdar Ink Technologies |
| Siegwerk Druckfarben AG & Co. KGaA |
| Flint Group |
| T&K TOKA Corporation |
| Toyo Ink International Corp. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between ECHA REACH-compliant photoinitiator systems and legacy formulations splits both pricing power and supply chain sourcing across European and export-oriented converters. Premium tiers command technical service premiums from German hub clusters, while commodity-grade water-based gravure inks compete on volume scale through depreciated thermal drying assets in the US Midwest.
Pricing Analysis
Acylphosphine oxide and oligomer input-cost pass-through dominates contract negotiations, with German and Chinese suppliers extracting pricing leverage during energy price volatility. Three-tier pricing structure across premium low-migration, standard UV-curable, and economy water-based levels differentiates by FDA notification tier and REACH Annex XVII certification completeness. Pricing pressure stems from photoinitiator supply concentration squeezing mid-tier formulators lacking captive resin synthesis. Brand owners consolidating procurement under sustainability scorecards exhibit lowest price sensitivity; corrugated board printers with fully depreciated natural gas ovens show highest sensitivity to UV-curable conversion premiums.
Supply Chain Analysis
ECHA REACH and FDA food-contact qualification gating restricts photoinitiator and pigment intermediate sourcing to certified German, Chinese, and Japanese suppliers. Raw material dependencies center on acrylphosphine oxides, acrylate oligomers, and azo-free pigment intermediates. Single-source vulnerability concentrates in German photoinitiator-oligomer compatibility expertise among senior resin supplier chemists. Distribution runs through technical service hubs anchored in Heidelberg, Würzburg, and Bavaria serving export-oriented flexible packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA REACH Annex XVII photoinitiator restrictions accelerate compliant formulation demand across European food-contact packaging.
For Market Incumbents: To counter margin compression from photoinitiator supply concentration, Siegwerk Druckfarben AG & Co. KGaA and Huber Group Holding SE should deepen backward integration into captive resin synthesis and expand technical service density in Poland and India ahead of FSSAI deadlines. Certification investment in dual FDA-EU registration streamlines product launch cycles for export markets. For New Entrants and Emerging Players: FSSAI compliance deadlines in India open a window for UV-curable formulation partnerships with Mumbai and Ahmedabad converter clusters underserved by incumbent technical service reach. Textile digital printing in Tiruppur and Surat presents the most penetrable white-space, with reactive dye inkjet convergence enabling short-run fashion supply chain integration. Go-to-market should anchor on sustainability scorecard alignment for brand owner procurement consolidation. For Investors and Strategic Acquirers: Consolidation pressure builds where small- and mid-tier suppliers lack certified azo-free pigment intermediates for ECHA REACH compliance. Long-term viability favors targets with LED-UV curing hardware integration capabilities and pharmaceutical blister pack certification density. Signal to watch is unbundling of ink supply from press maintenance contracts enabling direct environmental claim auditing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Sun Chemical's captive production controls raw material variability across digital ink portfolios. |
| LED-UV Array Retrofit Partnerships | Narrow-web label converters in Wisconsin and Bavaria compress job turnaround through hardware-ink integration. |
| Dual Certification Investment | Simultaneous FDA notification and EU REACH registration accelerates export market access for compliant formulators. |
| Technical Service Hub Expansion | Siegwerk's Poland and Germany hubs anchor European flexographic supply for pharmaceutical blister pack exporters. |
| Sustainability Scorecard Alignment | EPR legislation in Germany and California mandates recycled content certification unbundling ink from maintenance contracts. |
Study Parameters
Multiple input streams — primary interviews with ink formulation chemists, flexible packaging procurement leads, and LED-UV equipment engineers; secondary validation through ECHA REACH registration databases, FDA food-contact notification filings, and FSSAI compliance circulars — were reconciled through bottom-up converter demand modeling and top-down chemical supply analysis.
Historical volume trajectories were cross-referenced against panel input from resin suppliers and narrow-web converter associations across the projection horizon. Segmentation dimensions modeled include formulation chemistry, curing hardware compatibility, substrate adhesion requirements, end-use regulatory tier, and regional converter cluster density. CAGRs were derived from elasticity-adjusted demand curves incorporating photoinitiator substitution rates and LED-UV capital replacement cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA photoinitiator restriction acceleration or F-Gas Regulation phase-down delays affecting curing equipment refrigerants. Deviation in acylphosphine oxide supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Zink Printing Market
Printing Inks
Rotogravure Printing Inks Market
Printing Inks
Global Low Migration Inks Market
Printing Inks
Global Digital Inks Market
Printing Inks
Food Grade Inks Market
Printing Inks
Returnable Glass Bottle Ink Market
Printing Inks
Textile Printing Ink Market
Printing Inks
Global Digital Fabrication Inkjet Inks Market
Printing Inks
Global Light Changing Packaging Inks Market
Printing Inks
Eco-Friendly Inks Market
Printing Inks
Global Decorative Print Market
Printing Inks
Flexible Letterpress Printing Ink Market
Printing Inks
Solder Resist for Inkjet Printer Market
Printing Inks
Global Digital Textile Printing Inks Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
Lithographic Printing Chemicals Market