
 Eco-Friendly Inks Market | 2026-2036
Eco-Friendly Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Eco-Friendly Inks Market Analysis
Modular ink formulation kits are broadening buyer choice across the packaging value chain. Hubergroup leverages vertical integration into vegetable oil supply chains to control raw material quality. Sun Chemical anchors its position through R&D intensity in UV-curable platforms. Siegwerk competes by specializing in low-migration formulations for food-contact applications.
Eco-friendly inks are printing formulations engineered with reduced volatile organic compound content, typically incorporating vegetable oil derivatives or bio-based resin systems with VOC thresholds below five percent by weight, designed to meet industrial printing specifications while minimizing environmental and human health exposure. Aqueous and UV-curable ink types dominate current volume as mature platforms with established supply chains, while bio-based formulations represent the fastest-expanding segment as brand owners mandate renewable content thresholds. Within end-user demand, packaging absorbs the largest share of value given regulatory pressure on food-contact materials, whereas digital printing processes attract margin concentration due to shorter run lengths and customization requirements.
REACH registration requirements and the EU Green Deal framework restrict petrochemical-derived solvent content in commercial formulations, compelling reformulation investments across European supply chains. The US EPA regulates VOC emissions through federally enforceable standards that vary by printing process and facility scale, creating compliance complexity for multi-site operators. Stakeholders must monitor evolving bio-based certification standards and solvent exemption lists to align product portfolios with tightening chemical restrictions.
Market Dynamics
REACH solvent restrictions and EU Green Deal mandates are forcing reformulation across European supply chains, converting flexible packaging converters toward bio-based resin systems with sub-five-percent VOC thresholds.
Growth Catalysts
- REACH VOC Limits:ECHA registration requirements tighten petrochemical-derived solvent thresholds, compelling commercial ink producers to accelerate vegetable oil derivative adoption.
- Food-Contact Mandates:Brand owners in Germany and France now specify renewable content minimums for primary packaging materials, pulling bio-based formulation demand.
- Digital Print Short Runs:UV-curable platforms enable customization at reduced volumes, attracting margin concentration from converters serving craft beverage and specialty food segments.
Market Restraints
- Vegetable Oil Price Volatility:Linseed and soy oil feedstock costs fluctuate with agricultural commodity cycles, compressing margin predictability for mid-scale formulators.
- German Supply Concentration:Hubergroup and Siegwerk anchor regional resin and pigment networks, creating procurement dependency risk for converters outside their distribution radius.
- UV Curing Infrastructure:Legacy flexographic presses require capital-intensive LED retrofitting, slowing platform migration for smaller packaging operations.
Strategic Opportunities
- India PLI Scheme:Domestic packaging incentive programs accelerate sustainable material adoption, opening formulation partnerships with emerging flexible film producers.
- Low-Migration Food Contact:Specialized ink systems for direct-contact confectionery and dairy applications command premium positioning in underserved niche segments.
- CSRD Disclosure Requirements:EU corporate sustainability reporting mandates push brand owners to document Scope 3 chemical inputs, favoring certified bio-based suppliers.
Industry Challenges
- Formulation Chemistry Expertise:Shortage of specialists capable of balancing vegetable oil rheology with industrial drying speeds constrains R&D throughput at mid-tier producers.
- Bio-Based Certification Timelines:Third-party verification for ASTM D6866 or ISO 16620 compliance extends product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eco-Friendly Inks Market |
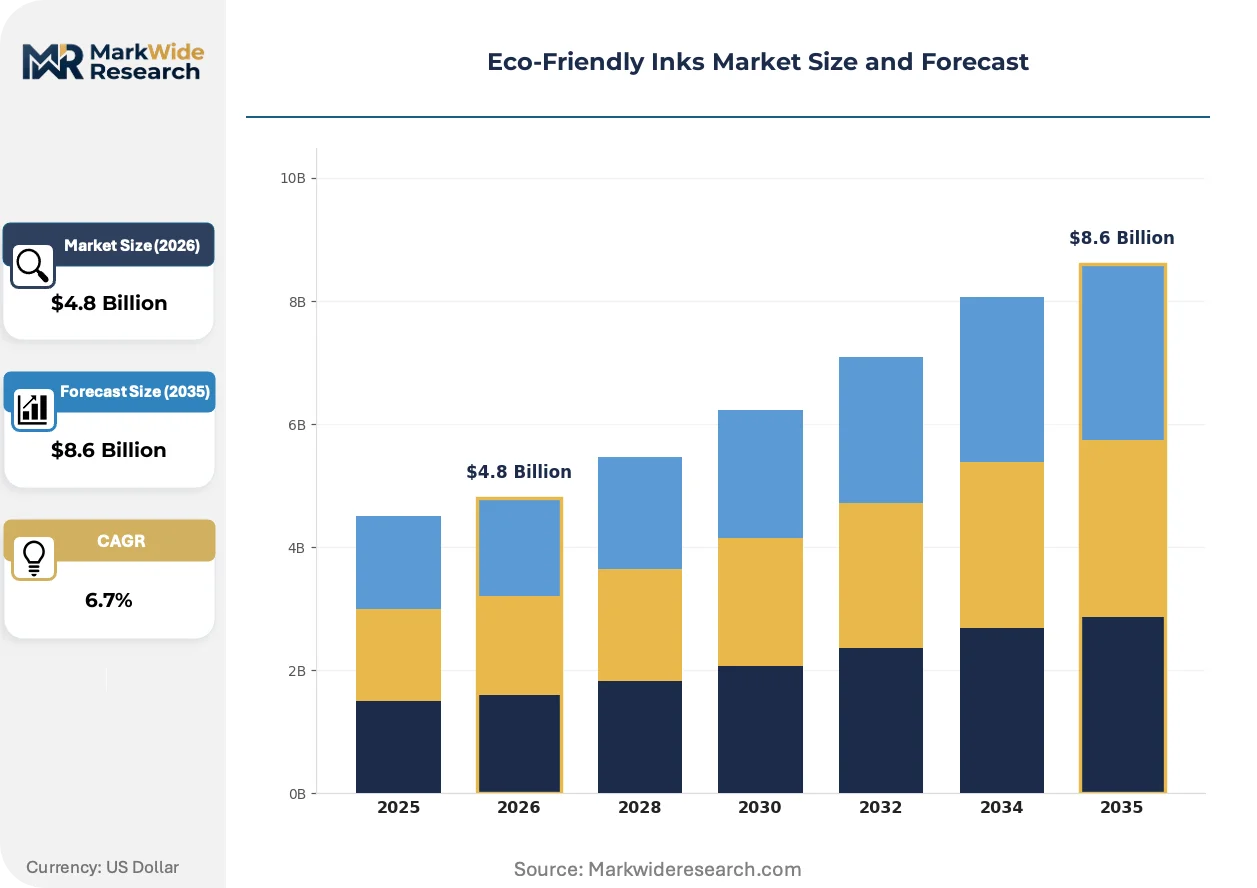
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ink Type: Aqueous, UV-Curable, Solvent-Based, Bio-Based Printing Process: Flexography, Gravure, Lithography, Digital End User: Packaging, Textile, Commercial Printing, Labeling Raw Material: Vegetable Oils, Resins, Dyes, Pigments |
| Companies Covered | Hubergroup, Omya AG, Sun Chemical, Sakata INX Corporation, Flint Group, Toyo Ink LLC, Siegwerk, DIC Corporation, INX International Ink Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eco-Friendly Inks Market Emerging Trajectories
Electrification of curing systems and polymer chemistry advances are compressing energy consumption while enabling substrate versatility previously unattainable with conventional thermal drying.
Water-based ink formulations incorporating bio-derived polyurethane dispersions are electrifying flexographic and gravure applications previously dominated by solvent systems. Folding carton converters in the Netherlands and Belgium are adopting these platforms at accelerated pace. The technology is electrifying competitive positioning by eliminating thermal oxidizer requirements and reducing facility energy intensity.
EPA National Emission Standards for Hazardous Air Pollutants impose facility-specific VOC limits on commercial printing operations, with compliance deadlines tightening for heatset web offset facilities. Multi-site operators face complexity navigating state-level implementation variations alongside federal benchmarks. Packaging segments in the US Midwest and Southeast are responding through consolidated solvent recovery investments and aqueous ink trials.
Brand procurement teams now mandate renewable content documentation upstream, displacing spot-buying relationships with multi-year formulation partnerships. Tier-one food manufacturers in Germany and France are consolidating supplier panels to three certified bio-based vendors per region. This concentration is most visible in dairy and ready-meal packaging verticals where EFSA contact material approvals serve as gating criteria.
Eco-Friendly Inks Market Segmentation
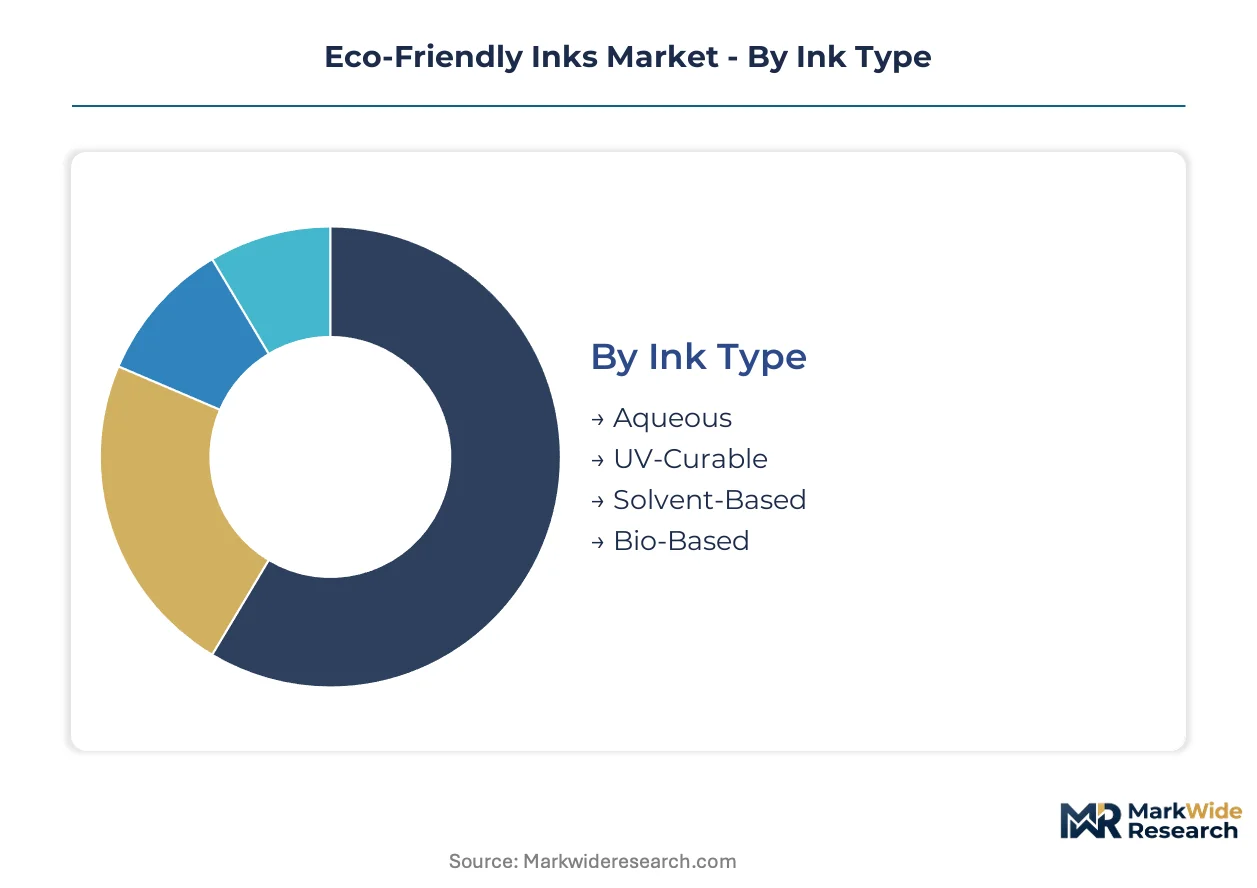
Eco-friendly ink procurement hinges on matching formulation chemistry to substrate compatibility and regulatory constraints. Buyers navigate trade-offs between drying speed, renewable content thresholds, and capital equipment requirements across four intersecting dimensions.
Ink Type:
Customization intensity varies from standardized commodity formulations to highly specified bio-based systems requiring certification documentation.
- Aqueous:Water-based systems incorporating synthetic or bio-derived polymer dispersions dominate folding carton and corrugated applications. German dairy packaging converters specify these for direct food-contact compliance under EFSA frameworks.
- UV-Curable:Photoinitiator-activated acrylate oligomers enable instant polymerization under LED or mercury arc exposure. French craft beverage brands drive specification for short-run label customization with sub-24-hour turnaround requirements.
- Solvent-Based:Low-VOC reformulations using bio-derived glycol ethers serve niche flexible film applications where water-based alternatives fail adhesion tests.
- Bio-Based:Formulations meeting ASTM D6866 or ISO 16620 certification thresholds for renewable carbon content.
Leading the category by volume: Aqueous. Growing fastest: Bio-Based.
Printing Process:
Equipment vintage and capital replacement cycles segment converter capabilities across process types.
- Flexography:Rotary relief printing with photopolymer plates dominates flexible packaging at high speeds. Dutch converters retrofit central impression presses with LED-UV curing to eliminate thermal oxidizers.
- Gravure:Intaglio engraving enables high-definition reproduction on thin films. Italian publication gravure houses face ECHA solvent restrictions compelling aqueous migration trials.
- Lithography:Planographic offset maintains cost efficiency for long-run paperboard.
- Digital:Inkjet and toner systems enable variable data and versioning without plate costs.
Highest installed base: Flexography. Steepest expansion trajectory: Digital.
End User:
Regulatory exposure and brand sustainability commitments concentrate demand heterogeneity across verticals.
- Packaging:Primary and secondary materials for food, beverage, and consumer goods absorb the largest formulation volumes. French and German retailers mandate renewable content minimums for private-label suppliers.
- Textile:Direct-to-garment and screen printing applications for fashion and technical fabrics.
- Commercial Printing:Publication, directory, and promotional materials face cost pressure from digital substitution.
- Labeling:Pressure-sensitive and shrink-sleeve formats for product identification and traceability.
Dominant value share: Packaging. Gaining share fastest: Labeling.
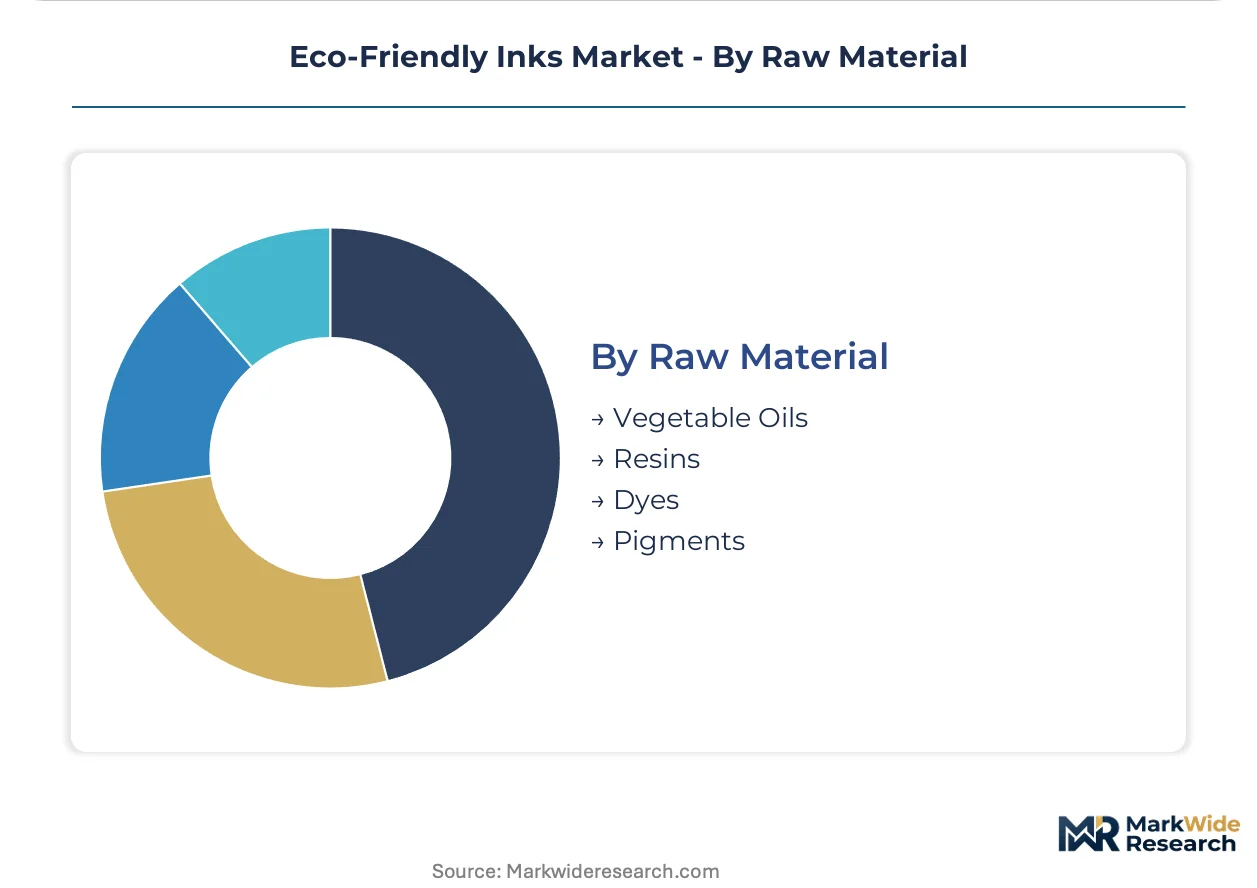
Raw Material:
Upstream supply concentration and agricultural commodity cycles dictate formulation economics.
- Vegetable Oils:Linseed, soy, and rapeseed derivatives provide renewable carrier fluids and resin building blocks. German ink producers negotiate multi-year supply contracts with agricultural cooperatives to hedge price volatility.
- Resins:Bio-based alkyds, polyurethanes, and acrylics determine film formation and adhesion properties.
- Dyes:Soluble colorants for applications requiring transparency and brilliance.
- Pigments:Insoluble particulate colorants providing opacity and lightfastness.
Most supply-constrained input: Vegetable Oils. Fastest specification change: Resins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Maharashtra and Gujarat concentrate formulation capacity serving export-oriented packaging hubs. Tax incentives under India's PLI scheme accelerate bio-based ink adoption among domestic flexible film producers.
Germany
REACH solvent restrictions drive reformulation investments across the Rhine-Ruhr industrial corridor. ECHA registration requirements tighten petrochemical-derived solvent thresholds, compelling converters toward vegetable oil derivatives. Hubergroup and Siegwerk anchor regional supply networks from their headquarters in Munich and Siegburg.
United States
EPA National Emission Standards for Hazardous Air Pollutants impose facility-specific VOC limits on commercial printing operations. Heatset web offset facilities in the Midwest face tightening compliance deadlines. Wisconsin and Ohio packaging clusters respond through consolidated solvent recovery investments and aqueous ink trials.
France
Brand procurement teams in Île-de-France mandate renewable content documentation upstream. EFSA contact material approvals serve as gating criteria for dairy and ready-meal packaging suppliers. French craft beverage brands in the Auvergne-Rhône-Alpes region drive specification for short-run label customization.
Netherlands
Folding carton converters in the Randstad region adopt water-based ink formulations at accelerated pace. Dutch central impression presses undergo LED-UV retrofitting to eliminate thermal oxidizers. The country's national environmental regulator enforces emissions standards that exceed EU minimums.
India
Domestic packaging incentive programs under the PLI scheme accelerate sustainable material adoption. Flexible film producers in Maharashtra and Gujarat expand procurement of bio-based formulations. BIS certification requirements for food-contact materials create compliance complexity for imported ink systems.
Eco-Friendly Inks Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers. The vendor base organizes around three strategic archetypes: integrated chemical conglomerates with captive resin production, mid-scale regional formulators with vertical control over vegetable oil supply chains, and specialty ink houses concentrating on low-migration food-contact applications. Dominant competitive moves include backward integration into agricultural feedstock sourcing and strategic partnerships with packaging OEMs for co-developed curing systems.
Among Germany-based chemical enterprises, Hubergroup GmbH and Siegwerk Druckfarben occupy positions exemplifying the integrated formulator archetype with upstream control over vegetable oil supply chains. Sun Chemical anchors the multinational conglomerate tier through R&D intensity in UV-curable platforms. These three companies represent distinct strategic postures: regional supply chain integration, multinational scale economies, and technology-led platform specialization.
| Leading Market Players |
|---|
| Hubergroup |
| Omya AG |
| Sun Chemical |
| Sakata INX Corporation |
| Flint Group |
| Toyo Ink LLC |
| Siegwerk |
| DIC Corporation |
| INX International Ink Co. |
| Others |
Supply Flow & Price Mechanics
Formulation chemistry specialists in the Rhine-Ruhr corridor command wage premiums that compress margin spreads between certified bio-based tiers and commodity aqueous formulations. Labor-cost differentials between German technical centers and emerging formulation hubs in Maharashtra widen pricing-tier spreads as converters weigh certification documentation against spot procurement economics.
Pricing Analysis
Lead-time-driven pricing stratification rewards converters willing to accept 8-14 month certification timelines with standard-tier positioning, while premium tiers capture urgent EFSA-compliant formulations for dairy packaging. Three-tier pricing structure across premium, standard, and economy levels separates ASTM D6866-certified bio-based systems from uncertified vegetable oil derivatives and commodity aqueous platforms. Price differentiation hinges on renewable carbon verification grade and volume scale, with mid-scale formulators facing margin compression from linseed oil commodity cycles. Brand procurement teams in France exhibit lowest price sensitivity given EFSA contact material mandates, whereas Southeast Asian flexible film producers prioritize economy-tier spot purchasing.
Supply Chain Analysis
Regional distribution centers in Munich, Siegburg, and Rotterdam orchestrate hub-and-spoke patterns serving converters across the Benelux and northern France. Supply concentration in Germany, India, and the Netherlands anchors resin and pigment networks, with Hubergroup and Siegwerk controlling captive vegetable oil sourcing from agricultural cooperatives. Raw material dependencies on linseed derivatives, bio-based alkyds, and photoinitiator chemicals expose formulators to agricultural commodity volatility and petrochemical feedstock linkage. Distribution runs through packaging OEM technical service partnerships that co-develop curing system specifications, creating single-source vulnerability for converters lacking in-house formulation expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards players securing upstream vegetable oil supply contracts as backward integration determines certification throughput and margin capture.
For Market Incumbents: Cement control over EFSA-compliant formulation pipelines by acquiring specialized low-migration R&D teams before REACH solvent restrictions tighten further. Deepen backward integration into linseed and soy oil agricultural cooperatives to hedge feedstock volatility threatening mid-tier margin structures. UV-curable platform specialists from digital printing segments represent the most credible entrant threat requiring preemptive channel lock-up through OEM co-development agreements. For New Entrants and Emerging Players: REACH registration requirements in Germany open a window for niche positioning in direct-contact confectionery ink systems underserved by incumbent capacity. Target India's PLI scheme beneficiaries in Maharashtra and Gujarat with BIS certification partnerships that bypass import complexity for food-contact materials. Lead with technical service bundling rather than price undercutting, as converter procurement panels prioritize multi-year formulation stability over spot savings. For Investors and Strategic Acquirers: The window for entry favors mid-scale regional formulators with captive vegetable oil supply chains and established EFSA approval dossiers. Mid-cap specialists with backward integration into agricultural feedstock sourcing and documented low-migration certification timelines offer the strongest long-term viability profile. Monitor BIS enforcement intensity in India as the inflection signal indicating whether domestic formulation capacity can displace European imports.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vegetable Oil Supply | Captive sourcing from German agricultural cooperatives insulates margin predictability against commodity volatility. |
| EFSA Low-Migration Certification Investment | Direct-contact dairy and ready-meal approvals unlock premium positioning in consolidating French retailer panels. |
| LED-UV Curing System Partnership | Co-development with Dutch central impression press OEMs eliminates thermal oxidizer requirements for folding carton converters. |
| India PLI Scheme Formulation Partnership | Domestic flexible film producers in Maharashtra require BIS-compliant bio-based systems for export-oriented packaging hubs. |
| ASTM D6866 Third-Party Verification Program | Documented renewable carbon content satisfies CSRD disclosure mandates from German and French brand procurement teams. |
Methodological Framework
Independent corroboration across ink formulation technical directors, flexible packaging procurement leads, and EFSA regulatory consultants underwrites the qualitative findings presented. Primary fieldwork with plant managers at German dairy packaging converters, R&D directors at UV-curable platform specialists, and distribution channel partners in the Benelux region combined with secondary validation from REACH registration databases, EFSA contact material approval dossiers, and Indian BIS certification records. Bottom-up volume estimates from formulation throughput data triangulated against top-down value projections from packaging OEM equipment deployment disclosures.
Rate-of-change decomposition across ink type, printing process, end-use vertical, and raw material feedstock anchors the analytical framework throughout the projection horizon. Segmentation dimensions modeled include formulation chemistry tier, substrate compatibility class, regulatory compliance cluster, and regional production hub concentration. CAGRs were derived from elasticity-adjusted demand curves incorporating vegetable oil commodity price scenarios and LED-UV curing adoption trajectories in flexographic applications.
The model assumes a particular technology adoption path; alternative pathways for water-based polyurethane dispersion penetration would alter the outlook if Dutch and Belgian folding carton converters accelerate migration beyond baseline assumptions. Forecasts reflect documented assumptions regarding REACH solvent restriction enforcement intensity and PLI scheme disbursement timelines in India. Periodic stress-testing of base assumptions is recommended given regulatory implementation variability and agricultural commodity cycle amplitude.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Radiation Curable Inks Market
Printing Inks
Low-Odor Inkjet Inks for On-Line Food Coding in Aseptic Filling Market
Printing Inks
Global Flexographic Inks Market
Printing Inks
Screen Printing Inks Market
Printing Inks
Global Printing Blanket Market
Printing Inks
Ink-Cartridge Market
Printing Inks
Global Gravure Printing Inks Market
Printing Inks
North America Ink Market
Printing Inks
Water-Borne Inks and Paints Market
Printing Inks
Lithography Inks Market
Printing Inks
Non-Conductive Ink Market
Printing Inks
Printing Plate Market
Printing Inks
Flexible Letterpress Printing Ink Market
Printing Inks
Global Decorative Print Market
Printing Inks
North America Printing Inks Market
Printing Inks
Solder Resist for Inkjet Printer Market