
 Brain Imaging and Neuroimaging Market | 2026-2036
Brain Imaging and Neuroimaging Market Size, Share, and Industry Trends Forecast 2026-2036
Brain Imaging and Neuroimaging Market Outlook
The gap between premium molecular imaging systems and refurbished conventional scanners is repositioning procurement strategies across hospital networks. Siemens Healthineers leverages its PET-MRI integration to dominate the high-performance tier, while GE HealthCare anchors its position through extensive service infrastructure and fleet management contracts. Koninklijke Philips N.V. differentiates via spectral CT neuroimaging workflows that reduce iodine contrast loads.
Brain imaging and neuroimaging encompasses non-invasive techniques for visualizing neural structure, function, and metabolism, with MRI systems typically operating at 1.5 to 7 Tesla field strengths and PET scanners detecting positron-emitting radiotracers at picomolar sensitivity for metabolic mapping. Functional MRI captures blood-oxygen-level-dependent signals with spatial resolution approaching one millimeter, enabling real-time mapping of cognitive task activation. Among product types, MRI maintains the largest installed base while PET scan demand accelerates fastest in amyloid-beta and tau imaging for Alzheimer's diagnostics. Research institutions represent the fastest-growing end user segment as federally funded brain mapping initiatives expand spectral analysis and magnetoencephalography adoption.
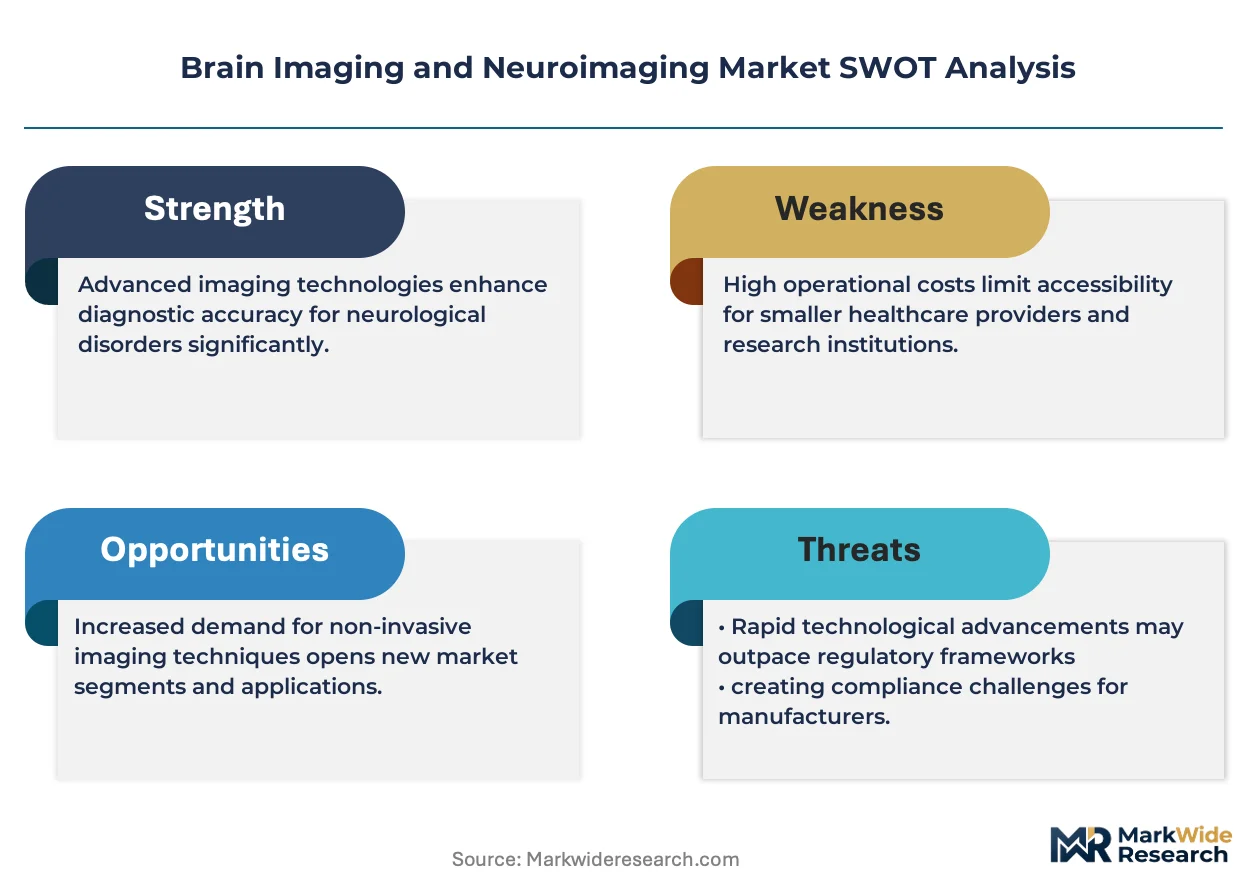
The FDA regulates neuroimaging devices under 21 CFR 892 subparts for diagnostic radiology, while the Nuclear Regulatory Commission governs radiopharmaceutical handling and cyclotron licensing for PET tracer production. In Europe, the Medical Device Regulation and CE marking requirements under notified body supervision shape market access timelines for new imaging modalities. Stakeholders must monitor reimbursement coding decisions for novel neuroimaging biomarkers, as coverage determinations will dictate capital investment cycles ahead.
Market Dynamics
Hybrid PET-MRI systems are compressing the diagnostic workflow from two separate appointments into a single session, forcing hospitals to restructure capital allocation between premium integrated platforms and conventional scanner fleets.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated clearance timelines for AI-powered neuroimaging software reduce regulatory friction for algorithm developers seeking clinical deployment.
- Amyloid-beta PET Imaging:CMS reimbursement decisions for Alzheimer's diagnostic protocols expand patient access to molecular imaging across Medicare-eligible populations.
- Magnetoencephalography:Federally funded brain mapping initiatives at research institutions drive spectral analysis instrumentation procurement beyond traditional academic budgets.
Market Restraints
- Helium Supply Concentration:Qatar and the United States control over 80% of global helium production, creating vulnerability for MRI magnet cooling systems dependent on continuous cryogen supply.
- Cyclotron Licensing Requirements:Nuclear Regulatory Commission radiopharmaceutical production permits impose multi-year barriers to PET tracer manufacturing capacity expansion.
- Superconducting Magnet Lead Times:Single-source dependency on Japanese niobium-titanium wire suppliers extends delivery schedules for high-field MRI systems to 18-24 months.
Strategic Opportunities
- Refurbished Scanner Networks:Secondary markets in India and Southeast Asia absorb decommissioned 1.5 Tesla systems from North American and European hospital upgrades.
- Spectral CT Workflows:Dual-energy imaging protocols reduce iodine contrast loads for patients with renal impairment, opening pediatric and geriatric segments previously excluded from contrast-enhanced neuroimaging.
- Tele-radiology Integration:Cloud-based image transmission enables centralized interpretation of emergency stroke protocols at rural hospitals lacking on-site neuroradiology coverage.
Industry Challenges
- Neuroradiologist Workforce Scarcity:Fellowship-trained specialists concentrate at academic medical centers, leaving community hospitals dependent on teleradiology outsourcing for complex case interpretation.
- Interoperability Friction:Legacy PACS infrastructure at mid-tier hospitals resists seamless integration with AI diagnostic overlays, delaying software deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brain Imaging and Neuroimaging Market |
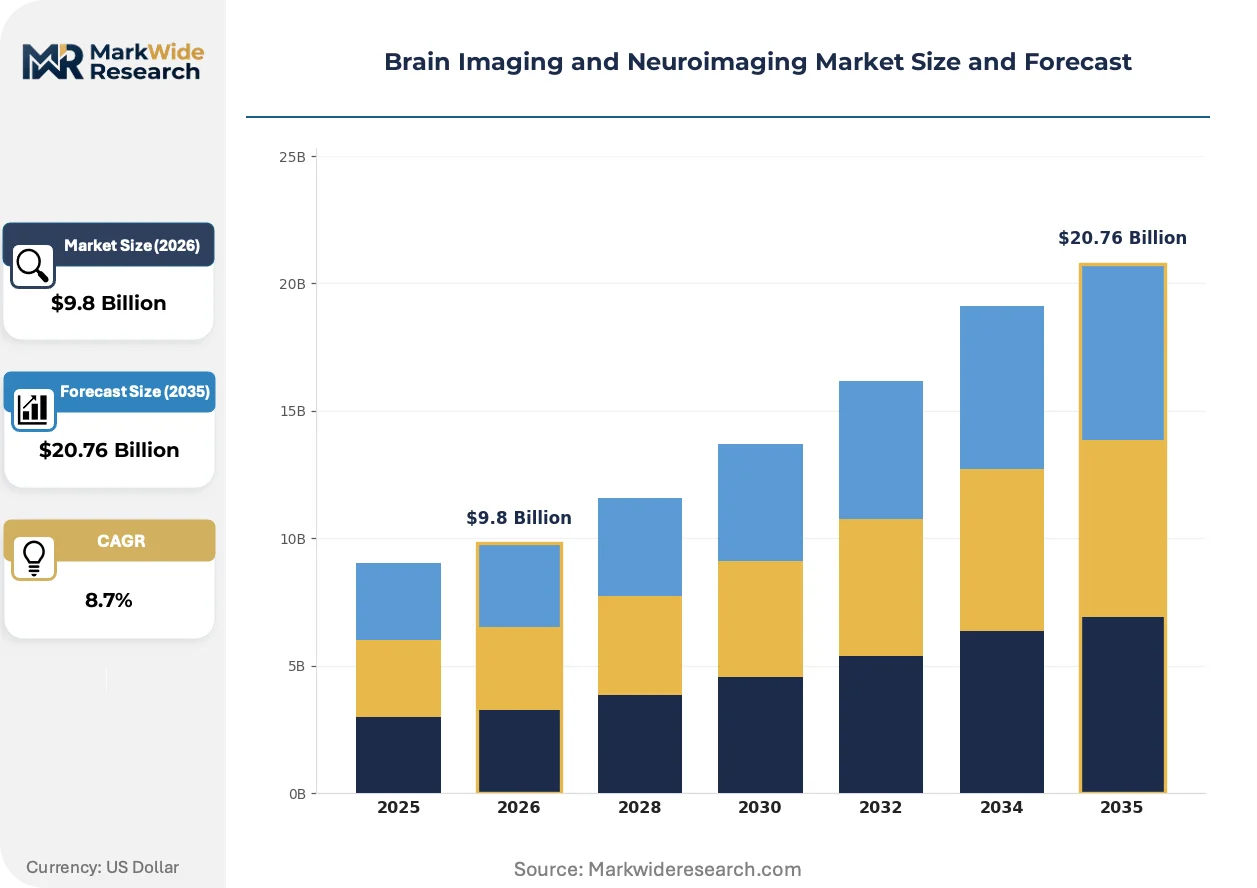
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MRI, CT Scan, PET Scan, EEG Technology: Functional MRI, Diffusion Tensor Imaging, Magnetoencephalography, Spectral Analysis Application: Neurology, Psychiatry, Research, Diagnostics End User: Hospitals, Research Institutions, Diagnostic Centers, Academic Laboratories |
| Companies Covered | Siemens Healthineers, GE HealthCare, Koninklijke Philips N.V., Canon Medical Systems Corporation, Hitachi Medical Systems, Medtronic, Fujifilm Holdings Corporation, Elekta, Neusoft Medical Systems Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brain Imaging and Neuroimaging Market Strategic Shifts
Computational imaging and radiopharmaceutical chemistry are converging to compress diagnostic timelines from days to hours, while reimbursement frameworks scramble to capture value from novel biomarker visualization.
Photon-counting CT detectors are expanding into neurovascular imaging applications by resolving iodine contrast at lower radiation doses than energy-integrating sensors. Stroke centers in Germany and the Netherlands are retrofitting angiography suites with Siemens NAEOTOM Alpha systems to capture high-resolution vessel wall imaging during acute intervention windows. This hardware transition is expanding into the premium tier of cerebrovascular assessment, compressing demand for conventional CT angiography upgrades.
The EU Medical Device Regulation's Class III requirements for software-as-a-medical-device are extending conformity assessment timelines for AI-based lesion detection algorithms. Manufacturers must now submit clinical validation data across multiple European sites to notified bodies, increasing regulatory compliance costs. French and Italian hospital procurement offices are delaying purchase decisions until CE marking under MDR is confirmed, creating a temporary demand freeze for unapproved imaging AI.
Academic medical centers are unbundling equipment purchase from service contracts, negotiating separate agreements with third-party ISOs for MRI magnet maintenance. This disintermediation of OEM service revenue is most visible in the United States, where hospital networks with captive biomedical engineering teams seek 40% cost reductions on multi-vendor fleet support. Independent service organizations are capturing maintenance contracts for GE and Philips systems previously held by manufacturer direct service divisions.
Brain Imaging and Neuroimaging Market Segmentation
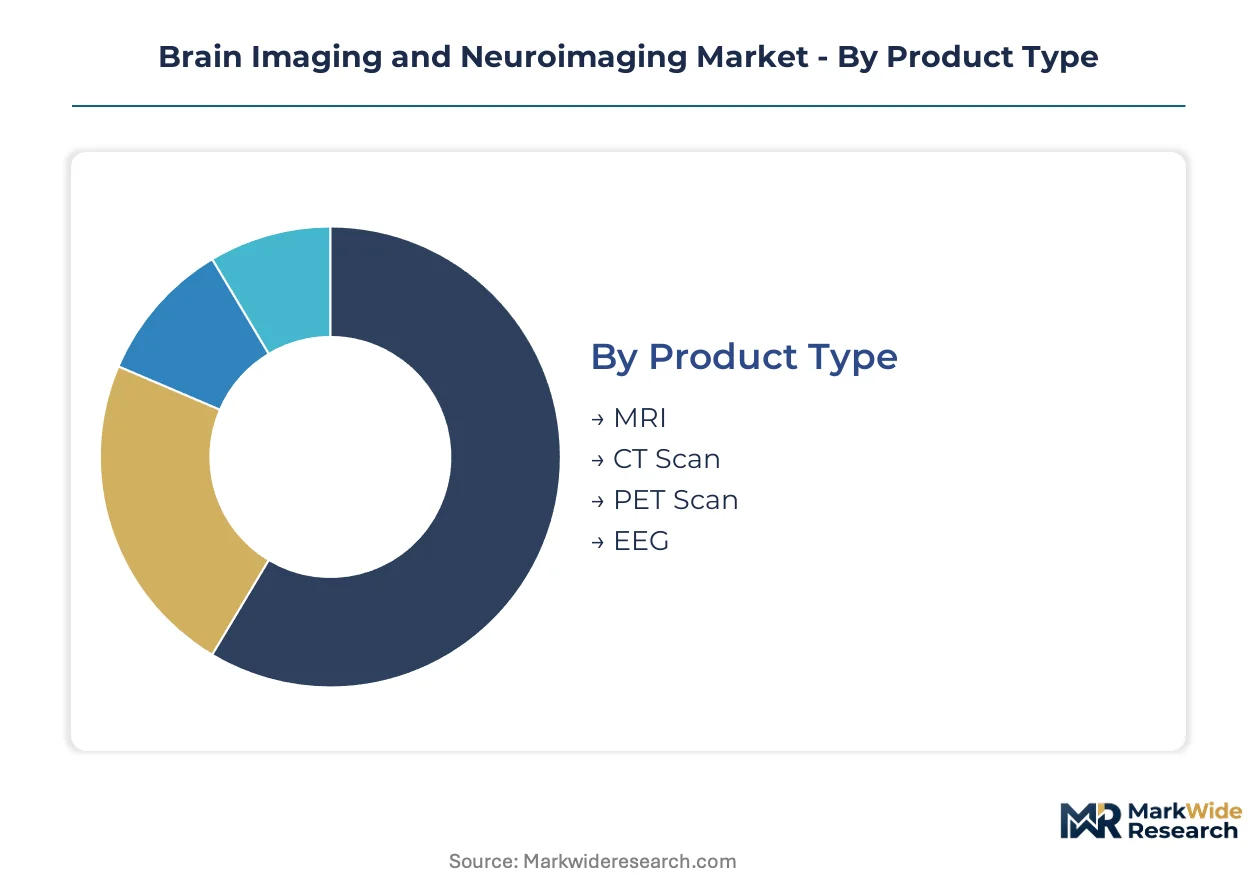
Procurement decisions across the brain imaging and neuroimaging market diverge sharply between capital-intensive hybrid platforms and discrete modality purchases. Understanding how technology selection maps to clinical workflow requirements and reimbursement pathways enables vendors to align product development with buyer budget cycles.
Product Type:
Hospital capital committees weight installed base compatibility against diagnostic throughput requirements when selecting imaging platforms.
- MRI:Systems operate at field strengths from 1.5 to 7 Tesla, with superconducting magnets requiring continuous helium cooling. United States academic medical centers drive demand for 3 Tesla platforms in stroke and dementia protocols, constrained by 18-24 month delivery schedules for niobium-titanium magnet components.
- PET Scan:Positron emission tomography detects picomolar concentrations of amyloid-beta and tau radiotracers for Alzheimer's metabolic mapping. Medicare reimbursement decisions in the United States are expanding patient access to molecular imaging across eligible populations.
- CT Scan:Computed tomography provides rapid structural assessment for emergency trauma and hemorrhage detection. Spectral CT workflows at European stroke centers are reducing iodine contrast loads for renal-impaired patients.
- EEG:Electroencephalography captures electrical activity through scalp electrodes for seizure monitoring and sleep disorder assessment. Diagnostic centers deploy portable systems for ambulatory neurological monitoring.
MRI leads on scale; PET scan leads on momentum.
Technology:
Research funding priorities and clinical validation timelines determine adoption velocity for emerging neuroimaging modalities.
- Functional MRI:Blood-oxygen-level-dependent signal detection enables real-time cognitive task activation mapping with spatial resolution approaching one millimeter. United States federally funded brain mapping initiatives are accelerating fMRI protocol standardization across research networks.
- Magnetoencephalography:SQUID-based sensors measure magnetic fields from neural electrical activity with millisecond temporal resolution. Research institutions represent the fastest-growing demand source as spectral analysis instrumentation procurement expands beyond traditional academic budgets.
- Diffusion Tensor Imaging:MRI-derived tractography visualizes white matter fiber orientation for surgical planning and traumatic injury assessment. Neurosurgical departments integrate DTI into preoperative mapping protocols.
- Spectral Analysis:Frequency-domain decomposition of electromagnetic signals supports quantitative EEG interpretation and source localization. Academic laboratories deploy hybrid MEG-EEG spectral platforms for multimodal neural dynamics research.
Functional MRI dominates clinical deployment; magnetoencephalography climbs the fastest in research procurement.
Application:
Reimbursement coding density and diagnostic specificity requirements shape technology-to-application matching.
- Neurology:Stroke protocol imaging and epilepsy surgical planning drive high-throughput scanner utilization. United States hospitals are expanding neuroimaging capacity to meet evolving thrombectomy window guidelines.
- Diagnostics:Alzheimer's biomarker visualization and dementia differential diagnosis concentrate demand for amyloid-beta PET imaging. CMS coverage determinations dictate capital investment cycles for molecular imaging suites.
- Psychiatry:Functional connectivity mapping for depression and schizophrenia treatment stratification remains predominantly research-stage. Academic medical centers pilot resting-state fMRI biomarkers for therapeutic response prediction.
- Research:Federally funded brain mapping initiatives support preclinical and clinical neuroimaging methodology development. National Institutes of Health grant portfolios are expanding spectral analysis and magnetoencephalography adoption.
Neurology leads on procedure volume; diagnostics leads on reimbursement expansion.
End User:
Technical staffing depth and capital access separate procurement patterns across institutional categories.
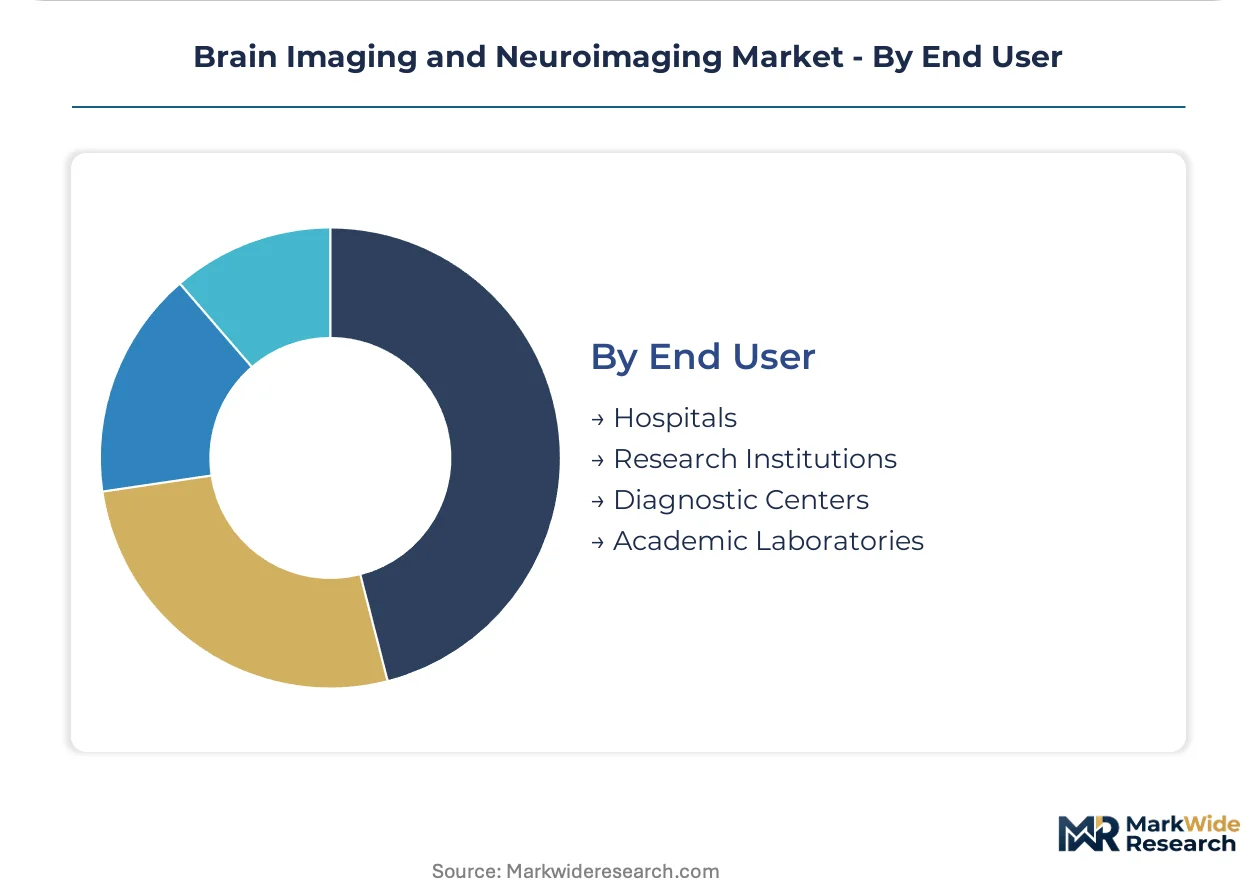
- Hospitals:Integrated health systems balance premium hybrid platform acquisition against refurbished conventional scanner fleet maintenance. Siemens Healthineers and GE HealthCare compete through service infrastructure and magnet management contracts.
- Research Institutions:National laboratory and university imaging centers prioritize spectral instrumentation and high-field MRI for federally funded neuroscience initiatives. Grant-funded procurement cycles decouple from clinical reimbursement timelines.
- Diagnostic Centers:Outpatient imaging facilities concentrate on high-volume CT and MRI protocols with rapid turnaround requirements. Teleradiology integration enables centralized interpretation for rural network affiliates.
- Academic Laboratories:Department-level neuroscience units deploy specialized EEG and optical imaging systems for cellular and circuit-level investigation. Training program accreditation requirements influence equipment selection.
Hospitals lead on installed base; research institutions lead on technology frontier adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neuroradiologist fellowship programs concentrate at United States academic medical centers, while German university hospitals anchor European PET-MRI adoption. Japanese superconducting magnet suppliers and Indian refurbished scanner networks complete the geographic talent and infrastructure map.
United States
Academic medical centers in Boston and Baltimore drive PET-MRI hybrid system procurement for Alzheimer's research protocols. The FDA's breakthrough device designation pathway accelerates AI-powered neuroimaging software clearance timelines. Stroke centers in the Southeast expand neuroimaging capacity to meet extended thrombectomy window guidelines.
Germany
University hospitals in Munich and Heidelberg prioritize photon-counting CT retrofitting for neurovascular intervention suites. The EU Medical Device Regulation's Class III software requirements extend conformity assessment timelines for AI lesion detection algorithms. Siemens Healthineers anchors high-performance imaging manufacturing in Erlangen.
Japan
Superconducting magnet wire production concentrates among niobium-titanium suppliers serving global MRI OEMs. The PMDA governs medical device approval timelines for novel neuroimaging modalities. Tokyo and Osaka academic medical centers deploy 7 Tesla research platforms for preclinical brain mapping initiatives.
India
Secondary markets absorb decommissioned 1.5 Tesla MRI systems from North American hospital upgrade cycles. The CDSCO regulates medical device imports under notified body supervision for CE-marked equipment. Diagnostic chains in Maharashtra and Karnataka expand teleradiology networks for rural stroke protocol interpretation.
United Kingdom
National Health Service trusts in London and Manchester balance premium hybrid platform acquisition against refurbished fleet maintenance. The MHRA enforces UKCA marking requirements post-Brexit for neuroimaging device market access. Oxford and Cambridge research institutions drive magnetoencephalography procurement for federally funded brain mapping consortia.
Brain Imaging and Neuroimaging Market Competitive Environment
Top-tier vendors anchor the premium hybrid platform segment, while mid-tier service organizations capture maintenance contracts from manufacturer direct divisions. The vendor base stratifies across integrated imaging conglomerates, specialized radiopharmaceutical suppliers, and third-party ISO service networks. Strategic archetypes include OEMs with captive magnet technology, disintermediated service providers, and refurbished equipment brokers. Competitive moves concentrate on M&A for AI software capabilities and geographic expansion into secondary scanner markets.
Among diversified health technology conglomerates, Siemens Healthineers, GE HealthCare, and Koninklijke Philips N.V. occupy positions exemplifying the premium-tier equipment archetype. Siemens Healthineers represents PET-MRI integration leadership, GE HealthCare anchors extensive service infrastructure and fleet management contracts, and Koninklijke Philips N.V. exemplifies spectral CT workflow differentiation. These three entities sit within the consolidated upper tier where capital intensity and regulatory compliance create structural barriers.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE HealthCare |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Hitachi Medical Systems |
| Medtronic |
| Fujifilm Holdings Corporation |
| Elekta |
| Neusoft Medical Systems Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Niobium-titanium wire from Japanese suppliers feeds into superconducting magnet production, cascading through three distinct pricing tiers for MRI systems before reaching hospital capital committees with divergent budget authority.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes procurement economics across hospital networks. Three-tier pricing structure across premium, standard, and economy levels separates PET-MRI hybrids with full OEM service contracts from refurbished 1.5 Tesla systems maintained by third-party ISOs. Price differentiation hinges on magnet field strength certification and geographic proximity to service engineering hubs. Cost compression in the refurbished tier is intensifying because academic medical centers are unbundling equipment purchase from maintenance agreements. Community hospitals exhibit highest price sensitivity due to constrained capital budgets, while research institutions prioritize performance specifications over acquisition cost.
Supply Chain Analysis
Reverse-logistics networks for decommissioned MRI systems channel retired 1.5 Tesla platforms from United States and German hospitals into refurbishment facilities serving Indian and Southeast Asian diagnostic chains. Primary manufacturing concentrates in Japan, Germany, and the United States for superconducting magnets, spectral CT detectors, and PET cyclotron components respectively. Helium cryogen supply draws from Qatar and United States production, with MRI magnet cooling systems tethered to continuous liquefied gas logistics. Single-source vulnerability in niobium-titanium wire supply creates delivery schedule risk for high-field system OEMs. Distribution runs through direct manufacturer sales teams for premium hybrid platforms and independent broker networks for secondary-market equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The brain imaging and neuroimaging market functions as a stable compounder, with aging demographics and expanding Medicare reimbursement for Alzheimer's diagnostics anchoring predictable demand expansion across the analysis window.
For Market Incumbents: Lock in service contract renewals through predictive maintenance platforms that reduce magnet downtime for hospital networks. Deepen backward integration into helium recovery and recycling infrastructure to offset supply concentration risk from Qatar and United States production. Defend against ISO disintermediation by embedding AI diagnostic overlays into captive software ecosystems that resist third-party integration. For New Entrants and Emerging Players: FDA breakthrough device designation in the United States opens a window for AI-powered lesion detection algorithms seeking accelerated clinical deployment. Target teleradiology interpretation services for rural stroke centers lacking on-site neuroradiology coverage, where reimbursement expansion for emergency protocols creates immediate addressable demand. Pursue hospital system partnerships through risk-sharing models that align software licensing fees with diagnostic accuracy outcomes rather than capital purchase structures. For Investors and Strategic Acquirers: Consolidation pressure builds where independent service organizations have captured multi-vendor maintenance contracts from OEM direct service divisions. The five-to-ten year viability thesis favors platforms with installed base density and recurring revenue attachment rather than pure equipment manufacturing. Acquisition target archetype: ISOs with captive biomedical engineering teams serving hospital networks across three or more states. Monitor CMS reimbursement coding decisions for novel neuroimaging biomarkers as the inflection signal dictating capital investment cycles ahead.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Siemens Healthineers anchors PET-MRI hybrid placement through integrated service infrastructure contracts. |
| Software Companion Development | AI-powered lesion detection algorithms require FDA breakthrough pathway validation for clinical deployment. |
| Reimbursement Strategy | CMS coverage determinations for amyloid-beta PET imaging dictate molecular imaging suite investment cycles. |
| CE Marking Pathway | EU MDR Class III requirements extend conformity assessment timelines for AI diagnostic overlays. |
| Backward Integration | Helium recovery infrastructure investment mitigates supply concentration risk from Qatar production. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. The research draws from interviews with neuroradiologists, hospital purchasing committee chairs, biomedical engineering directors, and GPO contracts managers, supplemented by FDA 510(k) filings, CMS reimbursement databases, hospital procurement records, and EU MDR notified body documentation. Bottom-up installed base estimates triangulate against top-down capital expenditure surveys across academic medical center networks.
Granularity-level modeling disaggregates revenue across product type, technology modality, clinical application, and end-user institution category throughout the forecast period. The analytical framework incorporates field strength tier, radiotracer chemistry class, and service contract attachment rate as neuroimaging-specific segmentation dimensions. CAGRs derive from logistic diffusion curves fitted to historical replacement cycles and projected reimbursement expansion timelines. Forecast inputs include NIH grant portfolio allocations for brain mapping initiatives and cyclotron licensing capacity under NRC jurisdiction.
Forecast precision tightens around the base case; tail outcomes carry wider variance under helium supply disruption or extended MDR conformity assessment delays. Practitioners should monitor FDA breakthrough device designation awards and CMS national coverage determinations for early signals of diagnostic protocol expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Chemical Imaging Systems Market
Imaging
Camera Accessories Market
Imaging
Embedded Smart Cameras Market
Imaging
CMOS X-Ray Detectors Market
Imaging
North America Digital Camera Market
Imaging
Fiducial Markers Market
Imaging
Global Optical Preclinical Imaging Market
Imaging
Europe Thermal Imaging Systems Market
Imaging
Photoconductor Drums Market
Imaging
Hybrid Imaging Market
Imaging
Global Cell Imagers Market
Imaging
X-Ray Photoelectron Spectroscopy Market
Imaging
Camera Lens Market
Imaging
Live Cell Imaging Market
Imaging
Wearable IP Camera Market
Imaging
Asia-Pacific Image Recognition Market