
 Embedded Smart Cameras Market | 2026-2036
Embedded Smart Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Smart Cameras Market Foresight
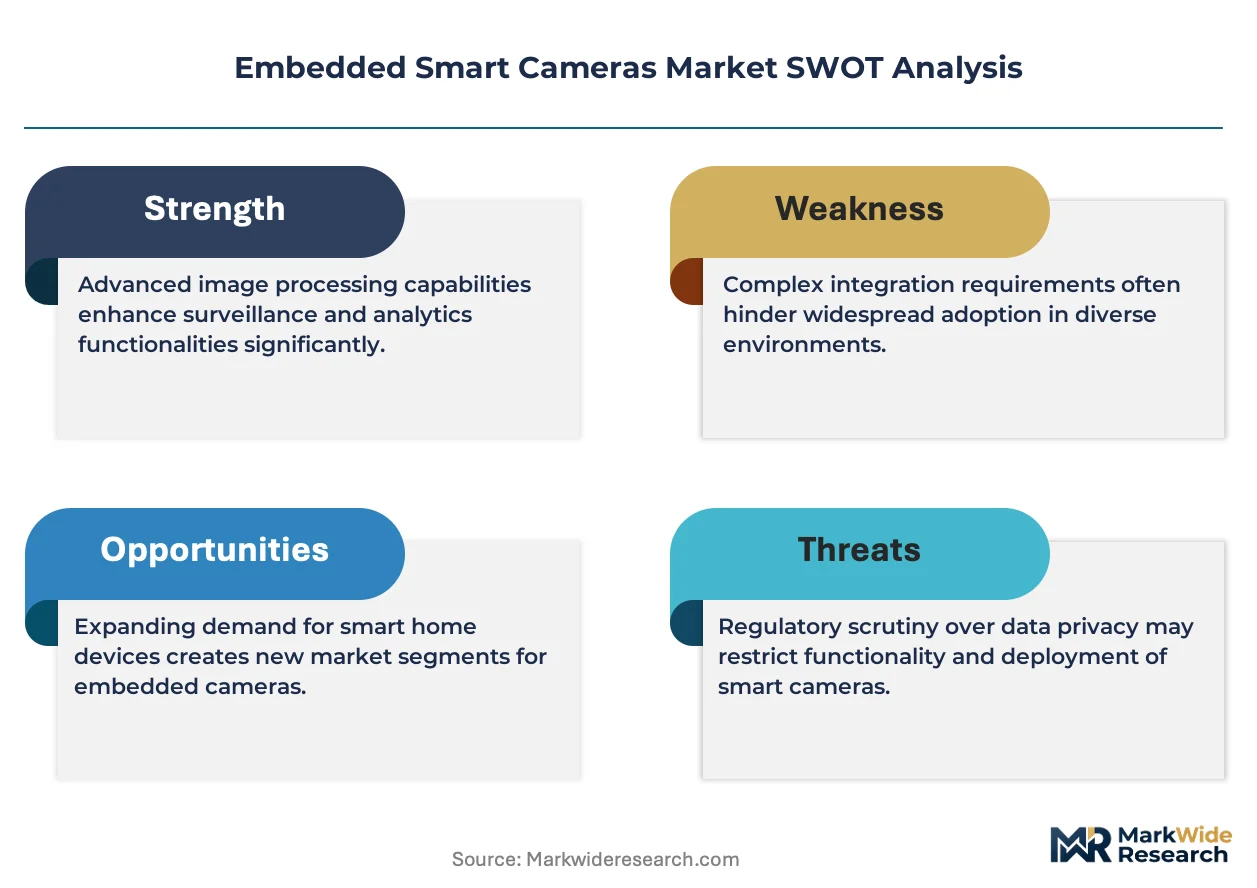
Asset-light manufacturing partnerships and contract-assembly financing is reconfiguring competitive entry barriers for mid-tier sensor vendors. Sony Corporation leverages captive CMOS foundry capacity to anchor premium image sensor supply. Basler AG specializes in industrial-grade camera modules with GigE Vision compliance. Cognex Corporation controls machine-vision software stacks that bind hardware procurement decisions.
Embedded smart cameras integrate image sensors, dedicated processors, and firmware into sealed units performing localized visual analysis without host-dependency. These devices typically operate on MIPI CSI-2 interfaces with power budgets under 5W for continuous edge deployment. Fixed cameras dominate security surveillance installations where infrastructure replacement cycles extend operational tenure. Edge computing technology captures margin pools through software-defined feature licensing. Ultra-HD cameras serve precision inspection in semiconductor and pharmaceutical packaging lines.
FCC Part 15 emissions rules constrain RF-integrated camera modules in US deployments, while EU AI Act risk classifications govern biometric inference in public spaces. Japan's METI safety standards shape automotive camera reliability specifications for Tier-1 suppliers. Stakeholders must track evolving conformity requirements across FDA, EMA, and NHTSA jurisdictions as embedded vision penetrates healthcare diagnostics and advanced driver assistance simultaneously.
Market Dynamics
Edge-native inference architectures are compressing latency tolerances below 10 milliseconds, forcing hardware vendors to relocate processing from cloud relays onto die-integrated neural accelerators. This shift rewrites procurement criteria across automotive, industrial automation, and surveillance verticals.
Growth Catalysts
- EU AI Act biometric governance:Risk-classification mandates for public-space inference are accelerating certified hardware refresh cycles among municipal surveillance operators.
- Automotive cabin monitoring:Euro NCAP 2026 protocols for driver distraction detection are embedding dual-camera arrays into mainstream vehicle platforms.
- On-device learning:Federated training on edge silicon is reducing bandwidth costs for distributed quality-inspection networks.
Market Restraints
- CMOS sensor concentration:Japanese and Korean foundry dominance exposes module assemblers to wafer allocation volatility during automotive demand surges.
- FCC Part 15 emissions testing:RF-integrated modules face 6-9 month certification timelines that gate US market entry for new product families.
- Silicon photonics substitution:Emerging LiDAR-on-chip architectures threaten stereo-camera redundancy in mid-range autonomous navigation stacks.
Strategic Opportunities
- India industrial corridors:PLI scheme incentives for electronics manufacturing are attracting camera module assembly investments near Chennai and Pune clusters.
- Healthcare point-of-care diagnostics:FDA breakthrough device pathways for AI-enabled retinal imaging are opening clinical-grade embedded vision applications.
- 5G-RedCap convergence:Reduced-capability cellular modems paired with edge cameras are enabling battery-operated surveillance without Wi-Fi infrastructure.
Industry Challenges
- Embedded vision engineering talent:Shortage of firmware developers fluent in OpenVX and TensorRT Lite optimization is extending product development cycles.
- Multi-jurisdiction certification stacking:Simultaneous FDA, EMA, and NHTSA submissions for diagnostic-ADAS hybrid devices consume 18-24 month compliance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Smart Cameras Market |
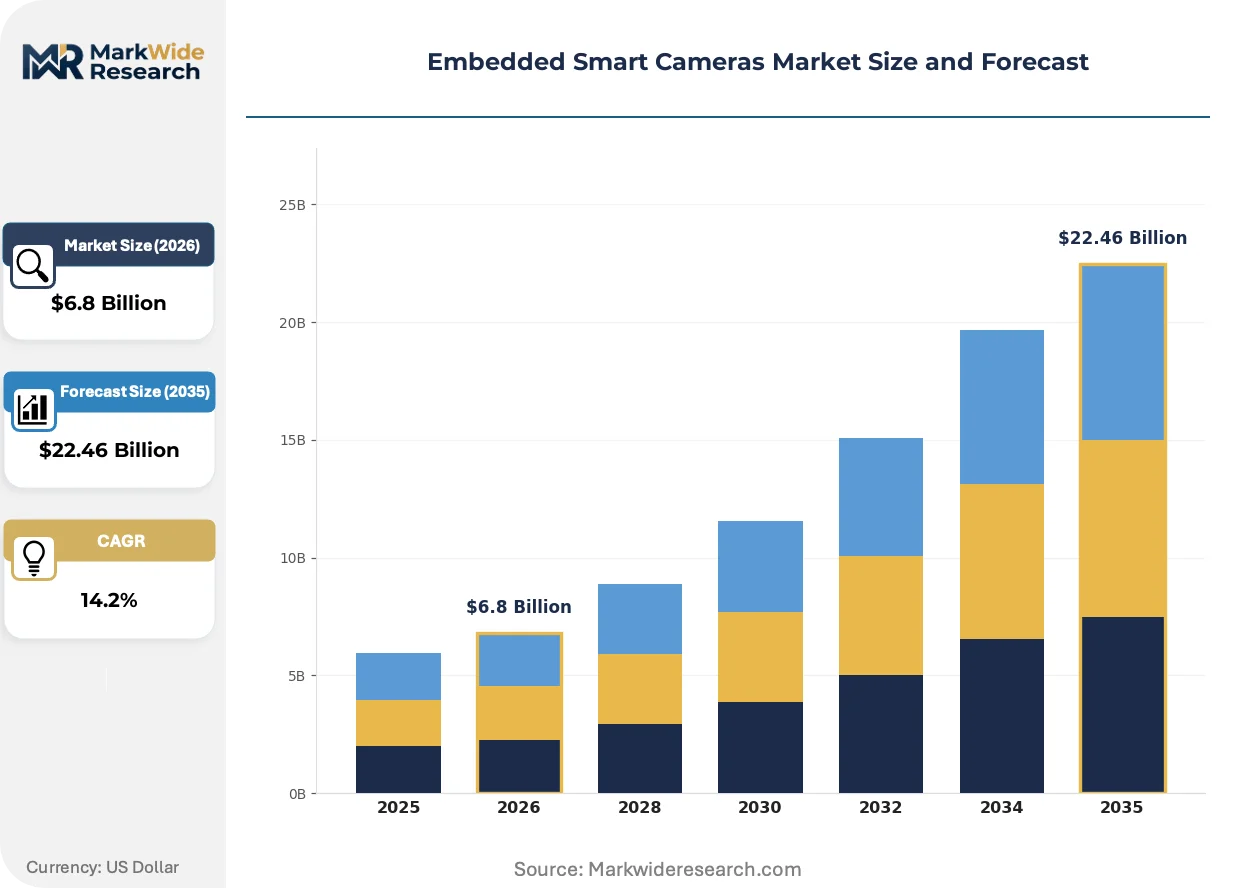
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Cameras, Pan-Tilt-Zoom Cameras, Ultra-HD Cameras, Infrared Cameras Technology: Computer Vision, Edge Computing, AI Processing, Image Sensor Technology Application: Security Surveillance, Automotive Assistance, Industrial Automation, Smart Retail End User: Healthcare Facilities, Retail Outlets, Manufacturing Units, Transportation Hubs |
| Companies Covered | Sony Corporation, SICK AG, Cognex Corporation, Microscan Systems, Teli Corporation, Basler AG, Teledyne DALSA Inc, Allied Vision Technologies, Keyence Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Smart Cameras Market Shifts & Advancements
Neural accelerator integration is migrating from discrete co-processors onto image sensor die stacks, collapsing power budgets and board footprints simultaneously. This convergence is redefining competitive differentiation around thermal efficiency and inference throughput rather than raw pixel resolution.
Event-based vision sensors is rendering obsolete frame-based architectures in high-speed industrial inspection. Semiconductor packaging lines in Germany and Japan are adopting Prophesee and Sony IMX-based event cameras for sub-millisecond defect detection. The technology is compressing data transmission volumes by orders of magnitude, reducing edge server provisioning requirements.
Japan's METI safety standards for automotive camera reliability are tightening temperature-cycling and vibration specifications beyond ISO 26262 baselines. Tier-1 suppliers are redesigning lens actuator mechanisms to withstand 85°C continuous operation. German OEMs are qualifying these enhanced modules for electric vehicle platforms where thermal management complexity exceeds internal combustion architectures.
Buyers in precision agriculture are unbundling hardware acquisition from analytics subscriptions, shifting toward sensor-as-a-service contracts with per-acre pricing. John Deere and CNH Industrial dealers in the US Midwest are piloting revenue-sharing models where camera hardware is deployed at zero upfront cost. This restructures vendor cash flow profiles and accelerates replacement cycles beyond traditional depreciation schedules.
Embedded Smart Cameras Market Segmentation
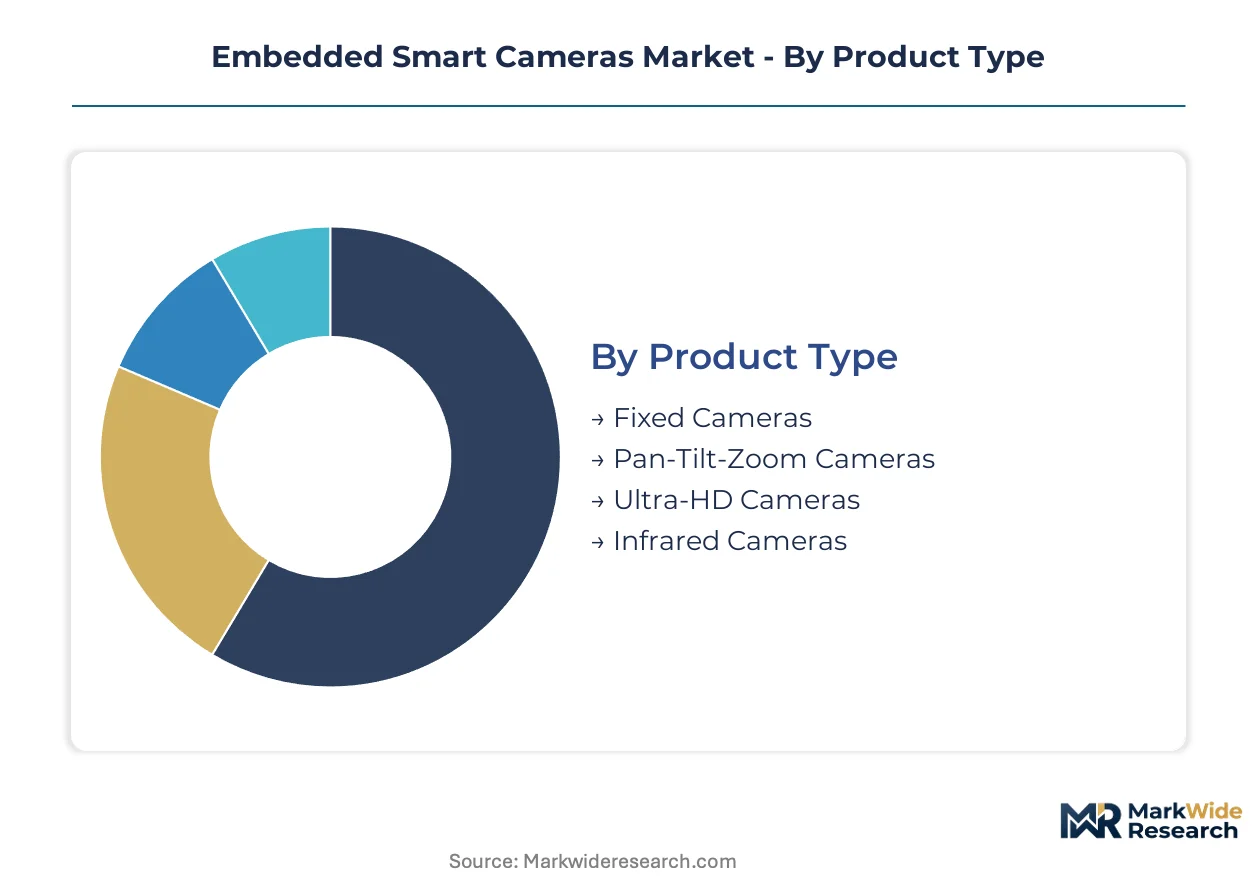
Embedded smart cameras fragment across four intersecting dimensions that reshape procurement criteria. Product type determines physical form factor and environmental sealing. Technology stack selection locks buyers into specific inference latency and power consumption profiles.
Product Type:
Mature fixed-camera architectures dominate legacy security infrastructure, while emerging PTZ and Ultra-HD variants capture specification upgrades in precision applications.
- Fixed Cameras:Sealed units with static lens assemblies and MIPI CSI-2 interfaces operate under 5W continuous draw. Municipal surveillance operators in Germany and Japan specify these for decade-long replacement cycles in transit corridors.
- Ultra-HD Cameras:4K and 8K resolution sensors with high-speed SerDes links enable semiconductor wafer inspection. Pharmaceutical packaging lines in the United States demand these for micron-level defect detection under FDA quality guidelines.
- Pan-Tilt-Zoom Cameras:Motorized lens actuators with optical zoom ratios exceeding 30x serve perimeter monitoring at transportation hubs.
- Infrared Cameras:Thermal imaging cores with vanadium oxide microbolometers penetrate darkness for night-vision security.
Fixed cameras retain volume leadership; Ultra-HD variants hold the steepest expansion curve.
Technology:
Cost tier separation runs from commodity image pipelines to premium neural accelerator integration, with edge-native architectures commanding software licensing premiums.
- Edge Computing:On-device inference below 10 milliseconds latency eliminates cloud relay dependencies. Automotive Tier-1 suppliers in Japan qualify these modules under METI thermal cycling standards for cabin monitoring systems.
- AI Processing:Dedicated neural accelerators on sensor die stacks collapse board footprints. Industrial automation buyers in Germany prioritize these for federated learning on distributed quality-inspection networks.
- Computer Vision:OpenVX and TensorRT Lite firmware stacks perform object detection and tracking.
- Image Sensor Technology:Backside-illuminated CMOS architectures with global shutter capability freeze high-speed motion.
Image sensor technology anchors baseline procurement; AI processing layers capture the fastest margin expansion.
Application:
Customer type differentiation separates capital-intensive industrial buyers from subscription-oriented service operators, with automotive OEMs driving the most stringent reliability specifications.
- Automotive Assistance:Dual-camera arrays for driver monitoring and autonomous navigation integrate into vehicle platforms. Euro NCAP 2026 protocols mandate these for distraction detection, accelerating OEM refresh cycles.
- Industrial Automation:GigE Vision-compliant modules perform real-time defect detection on German and Japanese semiconductor packaging lines. Event-based vision sensors from Prophesee and Sony are displacing frame-based architectures here.
- Security Surveillance:Fixed and PTZ deployments serve municipal and commercial infrastructure.
- Smart Retail:Shelf-mounted units with anonymized analytics track shopper behavior patterns.
Security surveillance retains installed base dominance; automotive assistance climbs the fastest as regulatory mandates tighten.
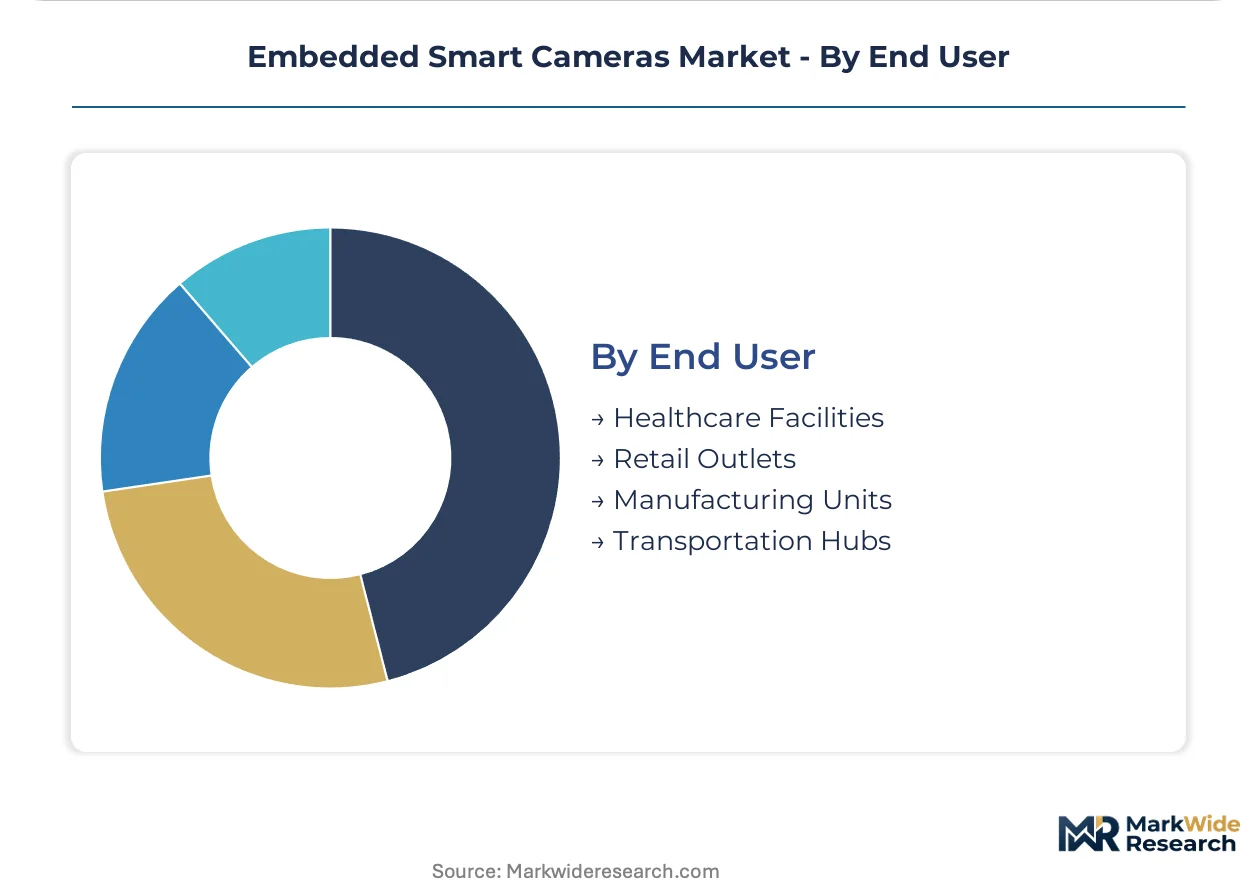
End User:
Geography concentrates demand in automotive clusters and industrial corridors, with healthcare emerging as a regulated premium segment.
- Manufacturing Units:Precision inspection networks in Germany and Japan consume Ultra-HD and event-camera modules. These buyers unbundle hardware from analytics, shifting toward sensor-as-a-service contracts with per-line pricing.
- Healthcare Facilities:FDA breakthrough device pathways for AI-enabled retinal imaging open clinical-grade applications. Point-of-care diagnostics in the United States demand embedded vision with HIPAA-compliant edge processing.
- Transportation Hubs:Airports and rail terminals deploy PTZ and fixed arrays for perimeter control.
- Retail Outlets:Smart checkout and inventory tracking systems integrate compact embedded cameras.
Manufacturing units command current volume; healthcare facilities trace the steepest adoption trajectory as regulatory pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in embedded smart cameras tilt toward surplus economies with captive sensor foundries and precision optics clusters. Import dependency concentrates in regions assembling finished modules without wafer-level fabrication.
United States
FDA breakthrough device pathways for AI-enabled diagnostics and NHTSA autonomous vehicle mandates drive dual-demand streams. FCC Part 15 emissions testing creates six-to-nine month certification gates for RF-integrated modules. The Greater Boston corridor hosts machine-vision software development for semiconductor inspection applications.
Germany
Euro NCAP 2026 cabin-monitoring protocols and EU AI Act biometric governance accelerate hardware refresh cycles. REACH compliance shapes material selection for automotive camera housings. The Stuttgart industrial cluster anchors precision inspection networks serving Bosch and Continental supply chains.
Japan
METI safety standards for automotive camera reliability exceed ISO 26262 baselines with tightened temperature-cycling specifications. PMDA pathways govern clinical-grade embedded vision for point-of-care diagnostics. The Nagoya automotive corridor qualifies enhanced modules for electric vehicle thermal management.
China
MIIT industrial internet initiatives and GB standards for machine vision expand domestic module procurement. Dual carbon goals pressure foundry energy intensity for CMOS sensor production. The Yangtze River Delta concentrates contract assembly investments near Shanghai and Suzhou electronics corridors.
India
PLI scheme incentives for electronics manufacturing attract camera module assembly near Chennai and Pune industrial corridors. BIS certification requirements govern import substitution for security surveillance deployments. The Tamil Nadu electronics manufacturing cluster hosts Foxconn and Dixon Technologies assembly partnerships.
Embedded Smart Cameras Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling critical supply chokepoints. Market structure concentrates around three strategic layers: captive foundry operators, industrial-grade module fabricators, and machine-vision software stacks. Competitive moves center on foundry capacity allocation during automotive demand surges and firmware stack licensing to bind hardware procurement decisions.
Among Japanese and Korean foundry-dependent players, Sony Corporation exemplifies captive CMOS supply control, while Basler AG and Cognex Corporation occupy positions spanning industrial-grade hardware and software-defined feature licensing respectively. These three anchors represent divergent strategic archetypes: upstream sensor dominance, mid-tier module specialization, and downstream software capture.
| Leading Market Players |
|---|
| Sony Corporation |
| SICK AG |
| Cognex Corporation |
| Microscan Systems |
| Teli Corporation |
| Basler AG |
| Teledyne DALSA Inc |
| Allied Vision Technologies |
| Keyence Corporation |
| Others |
Supply & Pricing Matrix
Single-source CMOS sensor dependency on Japanese and Korean foundries compresses pricing tier spreads while forcing module assemblers into long-term offtake commitments. This concentration simultaneously inflates premium-tier margins for captive-foundry players and erodes bargaining power at the mid-market tier.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on METI automotive certification grade and volume scale, with certified modules commanding substantial premiums over commercial-grade alternatives. Cost compression in the economy tier is intensifying because contract manufacturers in India are absorbing margin erosion to secure PLI-linked assembly volumes. Security surveillance operators exhibit highest price sensitivity, while automotive Tier-1 suppliers prioritize thermal reliability over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for RF-integrated modules. Geographic supply concentrates in Japan, South Korea, and Taiwan for CMOS sensors, with Germany and China anchoring precision optics and final assembly. Raw material dependencies include silicon wafers, rare-earth lens coatings, and high-speed SerDes interconnects. Single-source vulnerability in automotive-grade image sensors threatens allocation volatility during demand surges. Distribution runs through Tier-1 automotive suppliers and industrial automation integrators with embedded software licensing bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as edge-native inference architectures splinter procurement criteria across latency, thermal, and software-stack dimensions, creating specialist niches beneath platform integrators.
For Market Incumbents: Build firmware stack lock-in as the primary moat. Cognex-style machine-vision software licensing binds hardware procurement decisions and raises switching costs. Defend against neural-accelerator-on-sensor substitution by accelerating OpenVX and TensorRT Lite optimization talent acquisition. Expand captive CMOS foundry allocation to automotive cabin-monitoring demand surges. For New Entrants and Emerging Players: India's PLI-subsidized assembly corridors offer the most penetrable geographic entry point. Target healthcare point-of-care diagnostics where FDA breakthrough device pathways lower certification barriers versus automotive reliability mandates. Pursue sensor-as-a-service contracts with per-acre pricing in precision agriculture to bypass upfront hardware cost competition with established industrial vendors. For Investors and Strategic Acquirers: EU AI Act biometric risk-classification mandates reshape the acquisition landscape toward certified-hardware specialists. Long-term viability favors vertically integrated module fabricators with captive neural accelerator IP, not pure-play software licensors. Watch for automotive OEM qualification decisions on electric vehicle thermal management specifications as the inflection signal for module reliability tier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Neural Accelerator Die Integration | Sony and Prophesee are collapsing board footprints by stacking inference silicon directly on image sensors. |
| Event-Based Vision Sensor Deployment | German semiconductor packaging lines are adopting sub-millisecond defect detection architectures. |
| Sensor-as-a-Service Contract Structuring | John Deere dealers pilot zero-upfront hardware models with per-acre analytics pricing. |
| METI Automotive Certification Investment | Tier-1 suppliers redesign lens actuators for 85°C continuous operation on electric vehicles. |
| 5G-RedCap Modem Pairing | Battery-operated surveillance deployments bypass Wi-Fi infrastructure dependency. |
Research Methodology
Initial hypotheses were tested against primary input from embedded vision firmware developers, automotive Tier-1 procurement officers, industrial automation integrators, and machine-vision software architects, then refined through secondary validation. Primary interviews combined with trade data from MIIT industrial internet disclosures, METI safety standard filings, FDA breakthrough device designations, and EU AI Act implementation guidance. Bottom-up module shipment aggregation and top-down semiconductor foundry capacity allocation were triangulated to anchor volume estimates.
Demand-supply balance modeling across the analysis window integrated four segmentation dimensions: product type architecture, technology stack tier, application vertical, and end-user geography. CAGRs were derived from elasticity-calibrated adoption curves for edge-native inference and regulatory-mandated automotive refresh cycles. Industry-specific forecast inputs included Euro NCAP protocol compliance timelines and federated learning deployment rates in distributed quality-inspection networks.
The forecast holds incumbent behavior within observed patterns; aggressive foundry capacity expansion by captive operators or accelerated LiDAR-on-chip substitution would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Machine Vision Camera Market
Imaging
X-Ray Microscopes Market
Imaging
Multimodal Imaging Market
Imaging
High-Speed Camera Market
Imaging
Global Flow Imaging Microscopy/Dynamic Image Analysis Market
Imaging
Micro Computed Tomography Market
Imaging
X-Ray Photoelectron Spectroscopy Market
Imaging
APAC Thermal Imaging Systems Market
Imaging
Global Digital Binoculars Market
Imaging
Chemiluminescence Imaging Market
Imaging
Global Whole Slide Imaging Market
Imaging
Instaprint Camera Market
Imaging
Event Camera Market
Imaging
Global Broadcast Cameras Market
Imaging
Cooled IR Camera Market
Imaging
Compact Camera Module Market