
 ATV-UTV Tire Market | 2026-2036
ATV-UTV Tire Market Size, Share, and Industry Trends Forecast 2026-2036
ATV-UTV Tire Market Analysis
DOT certification for highway-speed rated ATV-UTV tires is bifurcating the competitive landscape into road-legal and off-road-only suppliers. Bridgestone Corporation leverages its passenger tire R&D infrastructure to fast-track DOT-compliant crossover designs. Maxxis International dominates the pure off-road segment through deep channel relationships with original equipment manufacturers in powersports.
ATV-UTV tires are pneumatic rubber structures engineered with reinforced sidewalls, multi-ply carcass construction, and tread compounds optimized for variable terrain traction at inflation pressures typically ranging from 5 to 15 psi; they transmit engine torque to unpaved surfaces while absorbing impact loads from rocks, roots, and ruts. The all-terrain product category sustains the largest volume share due to its versatility across recreational and utility applications, while the mud segment commands premium pricing through specialized lug geometry and self-cleaning tread patterns. Agricultural application demand is accelerating as farmers replace dedicated tractors with UTV platforms for spraying and light hauling tasks.
EPA small off-road engine standards and NHTSA equipment safety regulations constrain compound formulation and labeling requirements for tires sold in the United States, while ISO 9001 quality management certification governs export eligibility for Asian manufacturers. The Department of Transportation's evolving stance on side-by-side vehicle registration classes will determine whether road-legal tire demand expands beyond current niche status. Stakeholders must monitor state-level trail access legislation and its direct impact on replacement cycle frequency and product mix.
Market Dynamics
DOT certification requirements for highway-speed rated ATV-UTV tires are bifurcating supplier capabilities and forcing compound reformulation investments across the value chain. This regulatory pressure is concentrating R&D spending among manufacturers with existing passenger tire infrastructure.
Growth Catalysts
- EPA small off-road engine standards:Rolling efficiency mandates are accelerating demand for low-hysteresis tread compounds that reduce fuel consumption and emissions in utility applications.
- Off-road recreation park expansion:Fleet operators across the United States and Canada are scaling UTV purchases for guided adventure tourism experiences.
- Agricultural mechanization:Farmers are substituting dedicated tractors with UTV platforms for spraying and light hauling tasks.
Market Restraints
- Natural rubber price volatility:Compound input costs fluctuate with Southeast Asian supply disruptions and weather patterns affecting plantation yields.
- DOT certification timeline:Highway-speed testing protocols create 18-24 month product development cycles that freeze capital in R&D.
- Trail access restrictions:State-level land-use legislation in the American Northeast and Pacific Northwest limits recreational replacement demand.
Strategic Opportunities
- Electric UTV platforms:Torque characteristics of battery-powered side-by-sides favor specialized low-rolling-resistance tire designs without existing incumbent lock-in.
- Rocky Mountain trail networks:Colorado, Utah, and Wyoming permit structures support higher replacement cycle frequency than coastal states.
- ISO 9001 certification pathways:Asian manufacturers can unlock North American distribution by upgrading quality management systems to meet export eligibility requirements.
Industry Challenges
- Compound formulation expertise:Tire engineers with deep knowledge of silica-silane coupling agents for off-road durability remain scarce relative to passenger tire specialization.
- Dual-certification complexity:Simultaneous DOT and NHTSA compliance for road-legal products requires parallel testing tracks that strain mid-capacity manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ATV-UTV Tire Market |
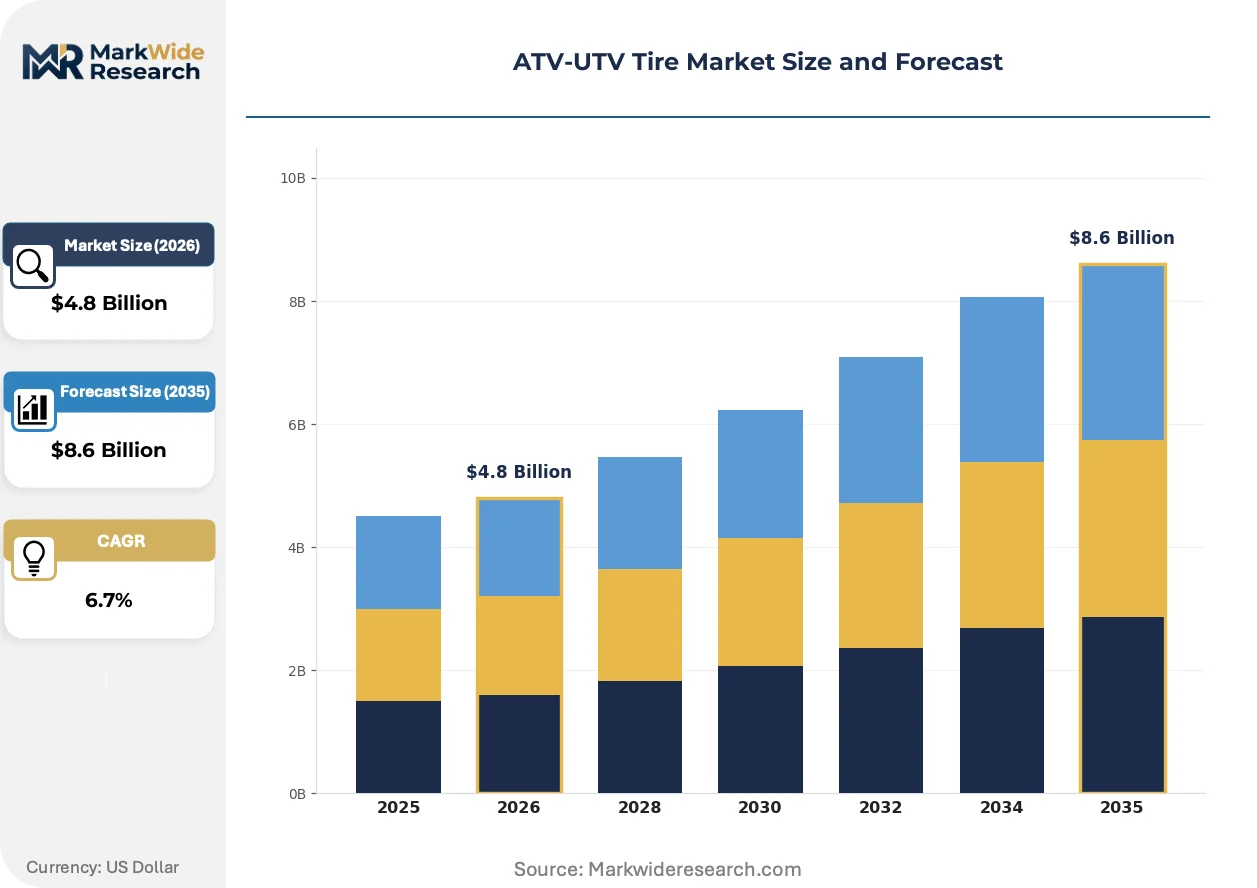
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Terrain, Mud, Sand, Sport Size: Small, Medium, Large, Extra Large Application: Recreational, Agricultural, Industrial, Racing End User: Private Owners, Rental Companies, Farmers, Commercial Users |
| Companies Covered | Bridgestone Corporation, Michelin Group, The Goodyear Tire & Rubber Company, Maxxis International, Kenda Rubber Industrial, Carlisle Companies, Titan International, Toyo Tire Corporation, Cheng Shin Rubber Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ATV-UTV Tire Market Emerging Trajectories
Tire architecture is fragmenting around terrain-specific performance requirements while regulatory pressure accelerates material science investment. Three converging developments are reshaping competitive positioning.
Aramid fiber reinforcement is decomposing the traditional nylon-ply carcass hierarchy in high-load UTV applications. Side-by-side manufacturers spec these materials for rock-crawling and desert racing segments where puncture resistance commands premium positioning. The shift is compressing margin structures for suppliers without upstream fiber partnerships.
NHTSA equipment safety regulations are tightening labeling and performance disclosure requirements for tires sold in the United States. Manufacturers must now document speed rating, load index, and construction type with standardized sidewall markings. The mud-terrain segment faces the steepest compliance burden due to its specialized lug geometry and non-uniform wear patterns.
Ranchers and farm operators are consolidating purchases through agricultural equipment dealers rather than independent tire distributors. This channel migration bundles UTV tires with sprayer and hauler attachments in single procurement events. The American Midwest exhibits the clearest concentration of this behavior.
ATV-UTV Tire Market Segmentation
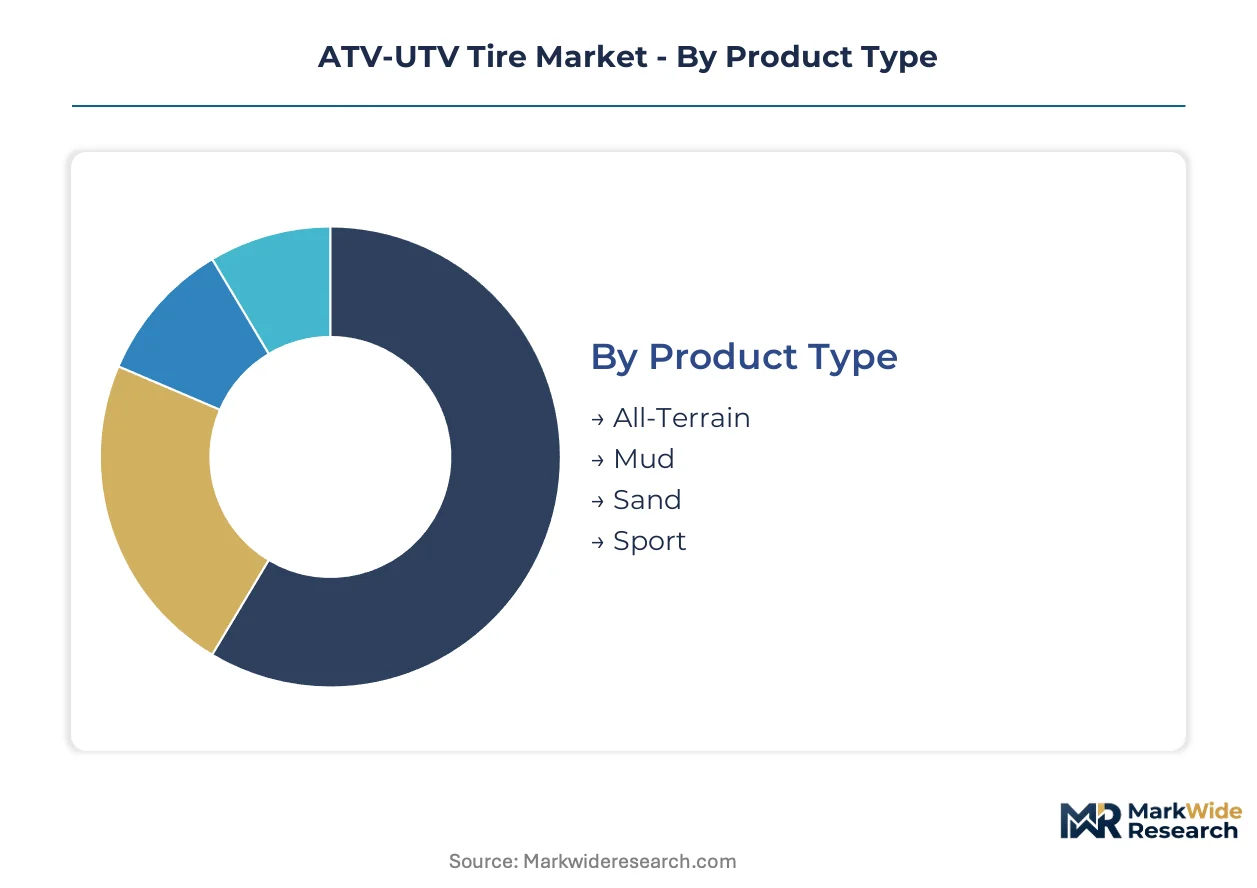
ATV-UTV tire purchasing patterns fragment sharply across terrain demands and duty cycles. Channel strategy must align with how each segment flows through powersports dealers, agricultural equipment distributors, or direct-to-fleet procurement.
Product Type:
All-terrain and mud tires move through distinct channel ecosystems, with powersports OEMs dominating volume for the former and specialty retailers capturing premium positioning for the latter.
- All-Terrain:Multi-lug tread patterns with siped blocks balance hardpack grip and loose-surface traction. Demand concentrates in the American Southwest where trail networks span rock, sand, and graded surfaces within single rides. Ranchers and recreational users favor this category for its replacement predictability across variable terrain.
- Mud:Deep, self-cleaning lugs with reinforced shoulders prevent packing in saturated clay. The American Southeast and Pacific Northwest replacement cycles run shortest here due to year-round wet conditions and aggressive tread wear. Premium positioning reflects compound durability requirements and specialized mold costs.
- Sand:Paddle or scoop tread configurations with minimal ground pressure maximize flotation on dunes. Coastal recreation parks in California and the Gulf States drive fleet procurement for this segment.
- Sport:Low-profile sidewalls and high-speed ratings support racing applications and aggressive trail riding. Closed-course competition circuits and desert racing series in Nevada and Arizona sustain niche volume.
All-Terrain dominates installed base. Mud is where expansion concentrates.
Size:
Cost tier alignment separates the size categories, with larger diameters commanding disproportionate margin through specialized compound requirements and lower manufacturing scale.
- Small:Traditional ATV fitments under 25 inches serve legacy machine parks and youth segment entry points. Southeast Asian manufacturing concentration keeps pricing accessible for price-sensitive replacement demand.
- Medium:25- to 27-inch diameters represent the crossover point where UTV platforms displace pure ATV volume. This tier captures the highest absolute unit movement through agricultural dealer networks bundling tires with sprayer attachments.
- Large:28- to 30-inch specifications accommodate lifted UTV platforms and rock-crawling builds. Rocky Mountain states exhibit steepest adoption curves as trail difficulty ratings increase and machine modification rates climb.
- Extra Large:31-inch-plus diameters require specialized load ratings and reinforced bead construction. Custom builders and high-end rental fleets in Moab and Glamis represent primary demand concentration.
Medium size brackets anchor current volume. Large diameters are climbing the fastest as machine displacement trends upward.
Application:
Customer type fragmentation determines procurement cadence, with agricultural and industrial users running predictable replacement schedules against recreational and racing demand spikes.
- Recreational:Seasonal replacement patterns track trail access permit seasons and weather windows. Private land access in Texas and Montana supports longer wear cycles than public trail systems in the Northeast.
- Agricultural:Sprayer and light hauler duty cycles drive systematic replacement through equipment dealer service departments. Midwest row-crop operations exhibit highest UTV substitution rates for dedicated tractor tasks.
- Industrial:Mining, construction, and utility maintenance applications demand puncture-resistant carcass construction. Fleet procurement through national rental chains concentrates volume in standardized sizes.
- Racing:Closed-course and desert competition runs tires to cord exposure within single events. Professional series and amateur sanctioning bodies in the Southwest sustain specialized distribution through race-day service vendors.
Recreational users represent the broadest installed base. Agricultural application is gaining share fastest as mechanization patterns shift.
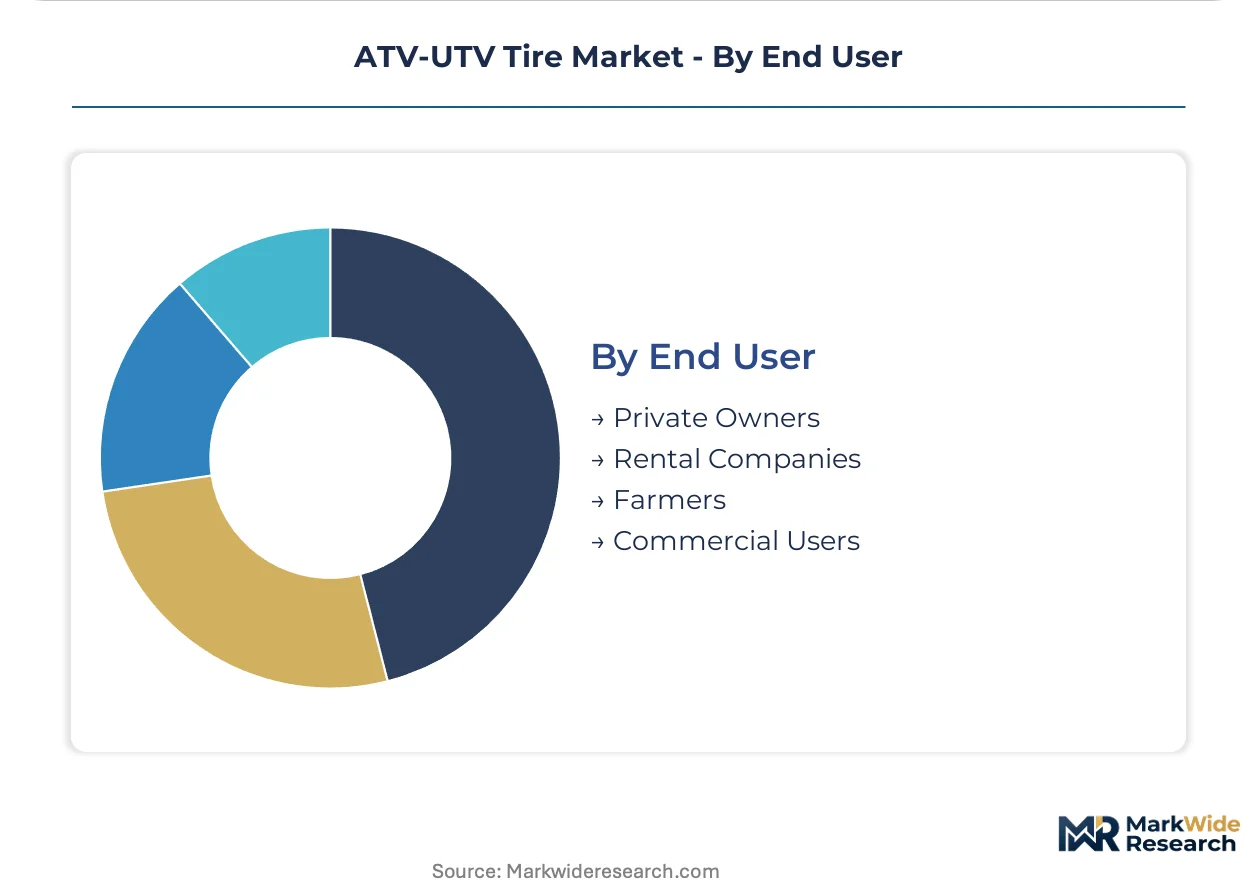
End User:
Procurement scale separates the end-user categories, with rental companies and commercial fleets negotiating volume pricing against individual owner premium sensitivity.
- Private Owners:Individual purchasing decisions prioritize upfront cost over total cost of ownership. Online retailers and local powersports dealers split this fragmented demand base.
- Rental Companies:Guided adventure tourism operators in Colorado and Utah run standardized fleets with predictable seasonal replacement. National park concession contracts drive specification uniformity.
- Farmers:Equipment dealer bundling consolidates tire procurement with attachment and service purchases. Crop insurance and depreciation schedules influence timing more than spot pricing.
- Commercial Users:Mining, pipeline maintenance, and utility inspection fleets negotiate multi-year supply agreements. Specifications prioritize downtime avoidance over initial acquisition cost.
Private owners dominate unit count. Rental companies are expanding most quickly as adventure tourism infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors North American tire import volume through dedicated breakbulk terminals handling containerized rubber compound shipments from Southeast Asian plantation networks.
United States
EPA small off-road engine standards drive rolling efficiency investments across utility fleets while NHTSA equipment safety regulations tighten labeling requirements for highway-speed rated products. The Department of Transportation's evolving side-by-side registration stance shapes road-legal tire demand. Colorado, Utah, and Wyoming trail networks concentrate replacement cycle frequency above national averages.
Canada
Health Canada and PMRA coordinate equipment safety standards with cross-border NHTSA alignment while provincial trail access programs in British Columbia and Alberta expand recreation infrastructure. The country's national environmental regulator maintains parallel emissions protocols for small off-road engines. Guided adventure tourism operators in Whistler and Banff scale fleet procurement through seasonal concession contracts.
Germany
KBA vehicle classification standards influence EU-wide side-by-side equipment regulations while REACH chemical compliance governs compound formulation for export manufacturers. The country's automotive testing infrastructure supports DOT certification parallel tracks for highway-speed rated products. Stuttgart and Munich industrial clusters host tire R&D facilities serving premium UTV OEM relationships.
Japan
METI industrial standards coordinate with ISO 9001 quality management certification pathways for Asian manufacturers seeking North American distribution eligibility. JIS standards govern domestic off-road equipment specifications. Tokyo and Nagoya metropolitan areas concentrate powersports OEM headquarters driving original equipment tire specifications.
Australia
TGA equipment safety frameworks align with international standards while the country's mining sector drives industrial UTV fleet procurement through national rental chains. State-level trail access legislation in Queensland and Western Australia supports recreational replacement demand. Perth and Brisbane serve as distribution hubs for Asia-Pacific supply chain integration.
ATV-UTV Tire Market Vendor Landscape
Listed leaders compete with private specialists across certification capability and channel access dimensions. The market structures around three tiers: integrated rubber conglomerates with passenger tire R&D infrastructure, pure-play powersports specialists with deep OEM relationships, and regional fabricators serving price-sensitive replacement demand. Two dominant competitive moves concentrate competitive energy: DOT certification investments that freeze capital in 18-24 month development cycles, and agricultural dealer channel bundling that consolidates procurement with equipment attachments.
Within the integrated conglomerate tier, Bridgestone Corporation and Michelin Group exemplify archetypes leveraging existing highway-speed tire testing infrastructure to fast-track crossover designs. Maxxis International occupies a position representing pure-play specialists dominating off-road-only segments through powersports OEM channel density. These three anchors illustrate how certification capability and channel specialization split competitive positioning between road-legal and off-road market vectors.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Michelin Group |
| The Goodyear Tire & Rubber Company |
| Maxxis International |
| Kenda Rubber Industrial |
| Carlisle Companies |
| Titan International |
| Toyo Tire Corporation |
| Cheng Shin Rubber Industries |
| Others |
Supply Flow & Price Mechanics
Aramid fiber substitution for traditional nylon-ply carcasses is redrawing supply geography toward Southeast Asian fiber producers while compressing margin structures for tire manufacturers lacking upstream partnerships. This material transition concentrates pricing power among suppliers with captive aramid sourcing, forcing mid-tier competitors toward commodity positioning in standard nylon-reinforced segments.
Pricing Analysis
Volume-discount tiering structures separate national fleet operators negotiating multi-year supply agreements from individual owners purchasing single sets through retail channels. Price differentiation rests on DOT certification status and agricultural dealer bundling arrangements, with road-legal products commanding substantial premiums over off-road-only alternatives. Cost compression in the economy tier is intensifying because Southeast Asian imports flood replacement channels with undifferentiated all-terrain specifications. Private owners exhibit highest price sensitivity, while commercial mining and utility fleets prioritize downtime avoidance over acquisition cost.
Supply Chain Analysis
Inventory strategy preferences bifurcate between just-in-time procurement favored by powersports OEMs and strategic stockpiling practiced by agricultural equipment dealers facing seasonal demand spikes. Geographic supply concentration centers on Thailand, Indonesia, and Vietnam for natural rubber cultivation, with China and Taiwan dominating synthetic polymer and aramid fiber production. Raw material dependencies include natural rubber latex, silica-silane coupling agents, and steel bead wire. Single-source vulnerability in aramid fiber supply creates exposure for manufacturers pursuing puncture-resistant product lines. Distribution runs through agricultural equipment dealers, powersports OEM service networks, and direct-to-fleet procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric UTV platform proliferation constitutes a high-growth disruption reshaping tire demand, with EPA emissions standards accelerating fleet electrification timelines and creating openings for specialized low-rolling-resistance designs.
For Market Incumbents: Secure DOT certification pipelines for highway-speed rated products before regulatory clarity solidifies side-by-side registration classes. Deepen backward integration into aramid fiber supply to defend margin position against nylon-ply commoditization. Agricultural dealer channel control represents the priority lever for utility segment retention. For New Entrants and Emerging Players: Aftermarket service bundling for rental fleet operators represents an underexploited service-layer gap where incumbents under-serve with transactional product sales. Electric UTV tire specifications offer the most penetrable white space, lacking incumbent lock-in and demanding novel compound formulations. Target Rocky Mountain state rental operators with direct technical sales teams offering predictive replacement scheduling. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap manufacturers possessing ISO 9001 certification and established Southeast Asian manufacturing footprints but lacking North American distribution scale. Long-term viability favors suppliers bridging agricultural and recreational segments through versatile all-terrain platforms. Watch EPA enforcement intensity on small off-road engine standards as the inflection signal determining electric platform adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| DOT Certification Investment | Highway-speed testing infrastructure unlocks road-legal premium tier access for crossover tire designs. |
| Aramid Fiber Backward Integration | Upstream control over puncture-resistant reinforcement materials compresses competitor margin structures in rock-crawling segments. |
| Agricultural Dealer Channel Partnership | Equipment bundling consolidates UTV tire procurement with sprayer and hauler attachment sales. |
| Electric UTV Tire Platform Development | Low-rolling-resistance compounds tailored to battery-powered torque characteristics capture emerging fleet demand. |
| Rocky Mountain Distribution Expansion | Colorado and Utah trail network density supports highest replacement cycle frequency in North America. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, tire manufacturer SEC filings, and EPA regulatory dockets. Primary interviews engaged tire R&D directors, agricultural equipment dealer procurement managers, powersports OEM platform engineers, and fleet maintenance supervisors at national rental chains. Secondary validation drew from NHTSA equipment safety filings, ISO certification registries, and state-level trail access legislation databases. Bottom-up unit demand modeling triangulates against top-down value estimates across product type, size, application, and end-user segmentation dimensions.
Segmentation dimensions modeled encompass terrain-specific product categories, diameter-based size tiers, duty-cycle application segments, and procurement-scale end-user archetypes across the projection horizon. CAGRs derive from regression analysis of historical replacement patterns against machine park growth and regulatory inflection timing. Industry-specific forecast inputs include UTV platform electrification penetration curves and agricultural mechanization substitution rates for dedicated tractor tasks.
Forecasts assume regulatory continuity in EPA small off-road engine standards and NHTSA equipment safety frameworks; material policy shifts would require re-modeling of rolling efficiency investment returns and certification timeline economics. Revision becomes warranted when electric UTV fleet penetration crosses thresholds that invalidate existing compound performance assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Electric Golf Cart Market
Recreational Vehicles
Recreational Vehicle Parks and Campgrounds Market
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
Global Houseboats Market
Recreational Vehicles
Luxury Yacht Market
Recreational Vehicles
Superyacht Market
Recreational Vehicles
Asia-Pacific Motor Home Market
Recreational Vehicles
United States Luxury Yacht Market
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
Kayak Seats Market
Recreational Vehicles
Middle East and Africa Personal Watercraft Market
Recreational Vehicles
North America Youth ATV and UTV Market
Recreational Vehicles
Motorhome Market
Recreational Vehicles
Golf Cart Market
Recreational Vehicles
Specialty Vehicle Market
Recreational Vehicles
Recreational Boats Market