
 Infantry Fighting Vehicle (IFV) Market | 2026-2036
Infantry Fighting Vehicle (IFV) Market Size, Share, and Industry Trends Forecast 2026-2036
Infantry Fighting Vehicle (IFV) Market Foresight
Market Context
Poland is rewriting armored vehicle procurement timelines across NATO's eastern flank. Rheinmetall leverages KNDS partnership structures to anchor manufacturing capacity in central Europe. BAE Systems sustains long-term supply relationships through CV90 platform variants spanning multiple national programs. General Dynamics Land Systems dominates the Stryker family production footprint across U.S. Army modernization cycles.
Technical Definition and Segment Structure
An infantry fighting vehicle is an armored combat platform designed to transport infantry squads under protection while delivering direct fire support through integrated weapon systems, typically mounting autocannons of 20-40mm caliber alongside anti-tank guided missiles. Tracked configurations retain structural preference for frontline mechanized units requiring cross-country mobility and heavy armor integration, while wheeled variants capture growing interest for rapid deployment and lower operational burden in stabilization missions. Cannon armament segments concentrate margin pools where turret integration complexity creates vendor lock-in, whereas electronic warfare technology layers represent the fastest-expanding capability insertion point as spectrum dominance becomes mission-critical.
Regulatory Framework and Outlook
U.S. Army Futures Command, Germany's BAAINBw procurement office, and NATO's Standardization Office collectively shape interoperability mandates, weight classification protocols, and cybersecurity certification requirements that determine market access eligibility. REACH chemical restrictions and EU Green Deal carbon accounting rules increasingly influence armor material selection and powertrain development pathways across European supply chains. Stakeholders must monitor how bilateral security agreements redirect national procurement sovereignty toward collaborative framework contracts.
Market Dynamics
Active protection systems and hybrid-electric drivelines are compressing legacy platform replacement cycles across NATO mechanized formations. Defense ministries now mandate integrated electronic warfare suites and reduced thermal signatures as baseline requirements, forcing fundamental redesigns of turret architectures and powertrain layouts.
Growth Catalysts
- Collective defense procurement frameworks:NATO's Standardization Office is accelerating interoperability mandates that enable cross-border maintenance networks and shared ammunition pools. Member states are consolidating orders to secure volume pricing on turret systems.
- Hybrid-electric propulsion mandates:The EU Green Deal's carbon accounting rules for defense procurement are redirecting R&D budgets toward battery-diesel architectures. This creates new supplier entry points in power electronics and thermal management.
- Eastern flank territorial defense requirements:Poland's accelerated tracked vehicle programs are establishing regional manufacturing hubs that serve adjacent Baltic and Nordic markets through offset agreements.
Market Restraints
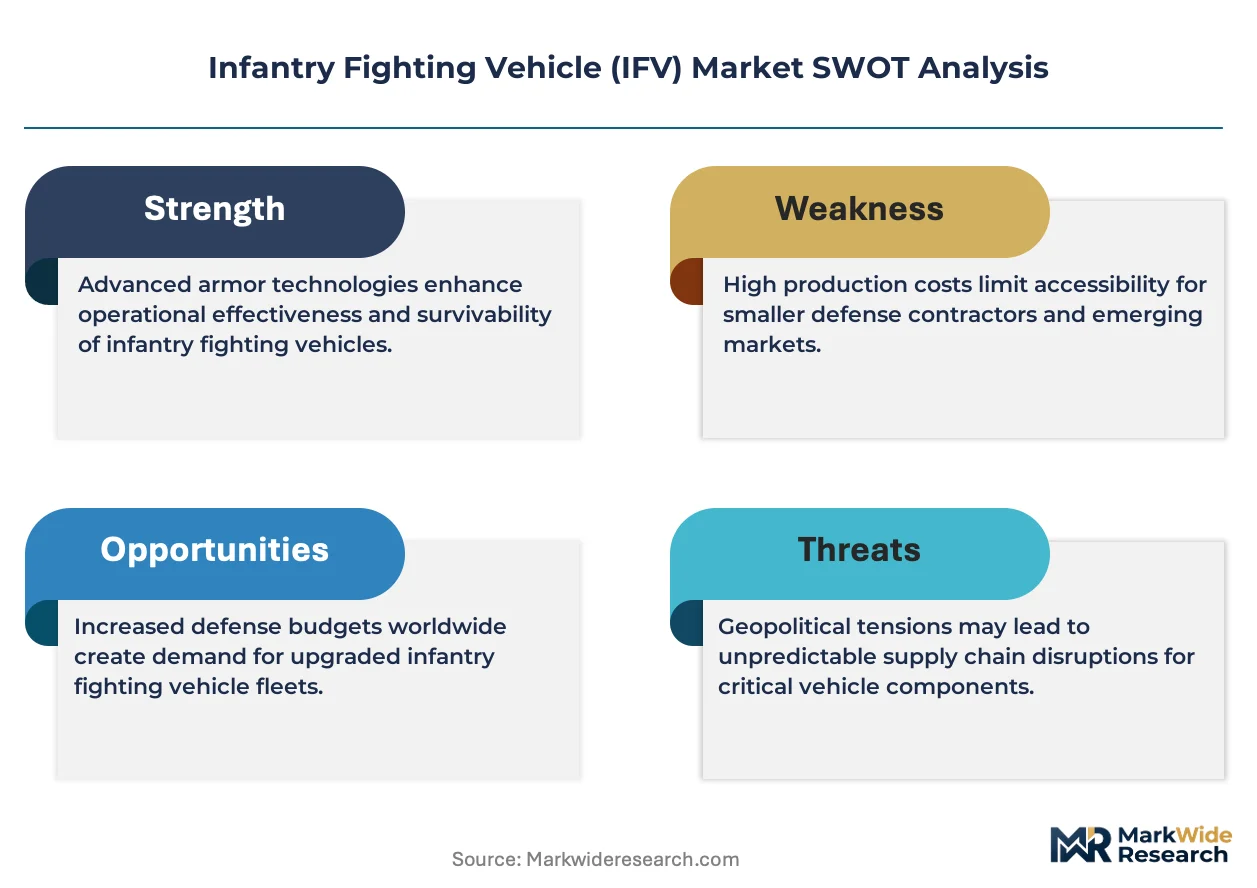
- Titanium and composite armor input volatility:Specialized armor-grade alloys face supply concentration among a limited set of metallurgical processors. Price swings in rare earth elements for ceramic composite matrices directly impact platform unit economics.
- Single-source turret integration risk:Autocannon and missile launcher integration complexity has consolidated around a handful of European and Israeli systems houses. Buyer dependency on proprietary fire-control software creates long-term vendor lock-in.
- REACH chemical restrictions on coatings:ECHA's substance authorization requirements are eliminating legacy hexavalent chromium surface treatments. Qualification timelines for replacement corrosion protection extend platform development cycles.
Strategic Opportunities
- Unmanned turret retrofits for legacy fleets:Remote weapon station architectures enable crew compartment reconfiguration without full hull replacement. Germany's BAAINBw is evaluating upgrade pathways for existing vehicle pools.
- Artificial intelligence-enabled target recognition:Machine vision algorithms for automatic threat classification are converging with millimeter-wave radar. This dual-sensor fusion creates aftermarket value capture in software-defined capability layers.
- Indo-Pacific amphibious platform demand:Coastal defense forces in the region are expressing interest in wheeled amphibious variants derived from established IFV architectures. Export licensing frameworks favor platforms with proven NATO interoperability.
Industry Challenges
- Embedded software security certification:NATO's cybersecurity certification requirements for military platforms demand formal verification of millions of lines of code. Qualified engineering capacity for high-assurance software development remains scarce.
- Active protection system integration complexity:Radar and effector placement on existing hull designs requires extensive electromagnetic interference testing. Retrofit programs face extended qualification timelines that compress operational availability windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infantry Fighting Vehicle (IFV) Market |
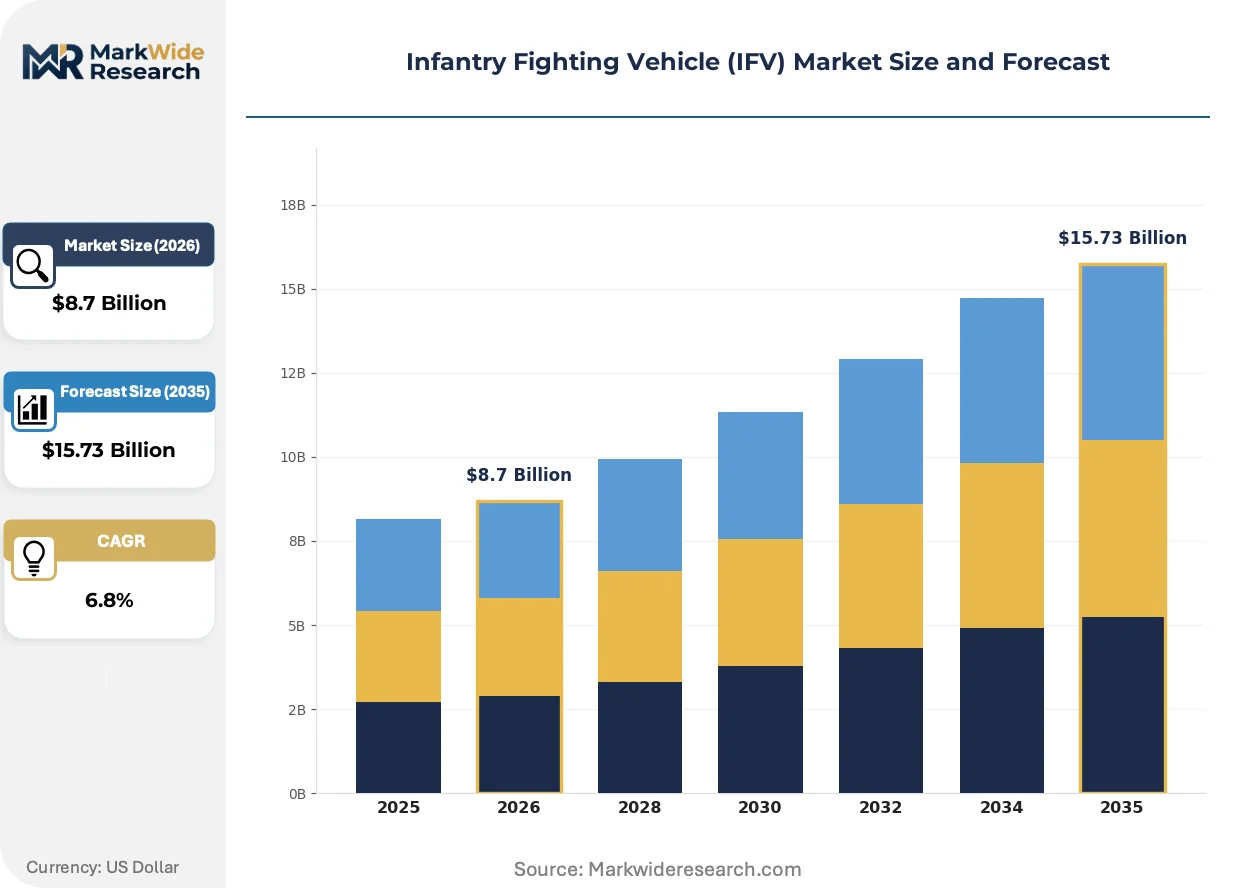
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Tracked, Wheeled, Amphibious, Light Armament: Cannon, Machine Gun, Missile, Grenade Launcher End User: Military, Defense Contractors, Government Agencies, NGOs Technology: Electronic Warfare, Networking, Surveillance, Armor |
| Companies Covered | Textron Inc, FNSS Savunma Sistemleri, General Dynamics Land Systems, Hanwha Corporation, Oshkosh Corporation, BAE Systems, Nexter Group, Patria Group, Rheinmetall, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infantry Fighting Vehicle (IFV) Market Shifts & Advancements
Powertrain architectures and crew protection systems are undergoing simultaneous transformation. Platform designers must reconcile competing demands for silent watch capability, reduced logistics burden, and survivability against top-attack munitions.
Hybrid-electric driveline technology is hybridizing combat vehicle mobility concepts. The series-hybrid architecture enables silent movement for tactical approaches and reduces acoustic signature during stationary operations. U.S. Army Futures Command is prototyping these configurations for next-generation demonstrators. This propulsion shift is hybridizing supplier ecosystems, drawing automotive battery specialists into defense supply chains alongside traditional transmission manufacturers.
REACH chemical restrictions are eliminating legacy surface treatment processes across European armor fabrication. ECHA's authorization requirements for hexavalent chromium and cadmium-based coatings are forcing qualification of alternative corrosion protection systems. Platform integrators in Germany and Poland are responding by vertically integrating surface engineering capabilities to control qualification timelines and protect proprietary process knowledge.
Defense ministries are consolidating platform orders through multi-year framework contracts that bundle development, production, and through-life support. Traditional sequential procurement—separate development, production, and sustainment phases—is yielding to single-source responsibility models. Poland's armored vehicle programs exemplify this concentration, with national industrial participation requirements embedded in decade-long supply agreements.
Infantry Fighting Vehicle (IFV) Market Segmentation
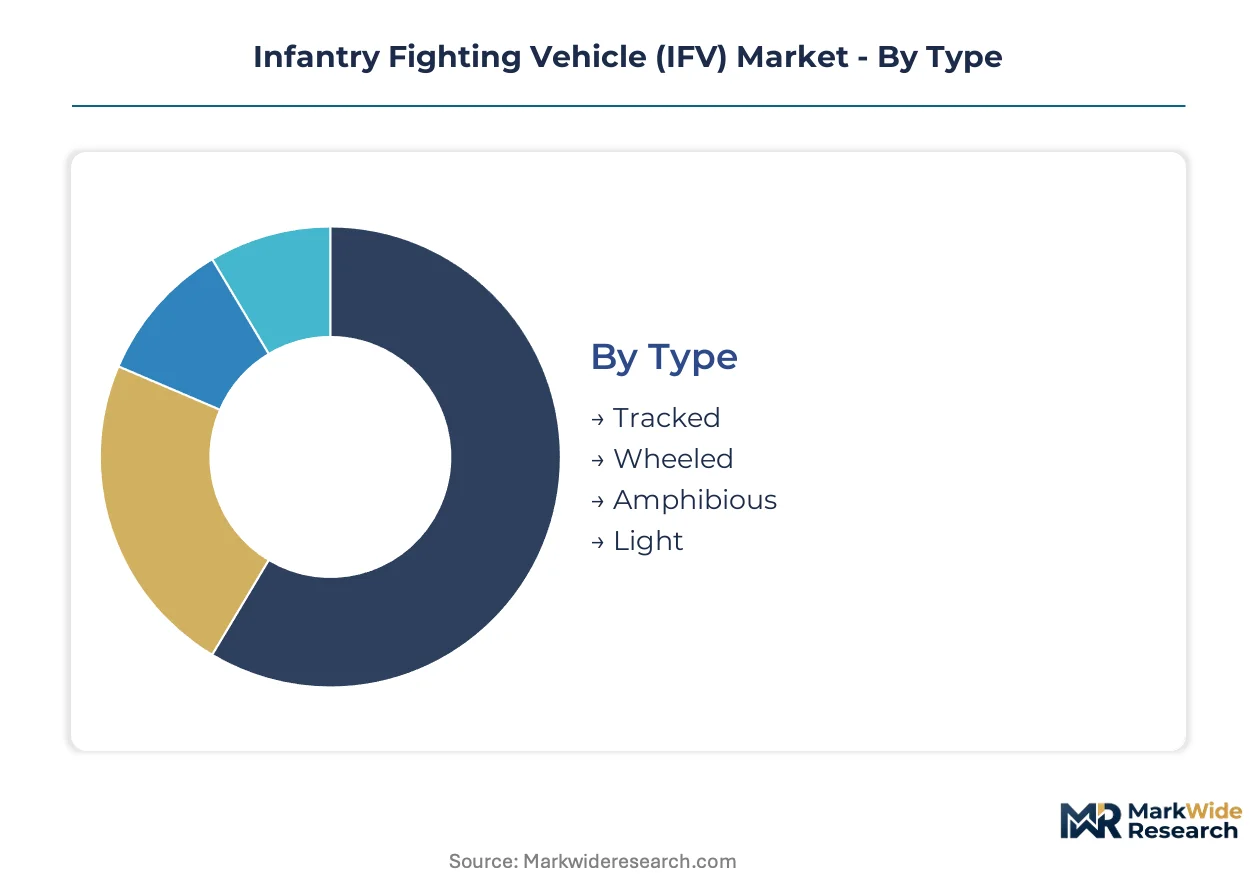
IFV procurement cycles vary dramatically across platform types and capability layers. Defense ministries prioritize segments offering the fastest operational payoff against near-peer threats while managing decades-long fleet modernization timelines.
Type:
Tracked configurations turn over slowest due to hull longevity and upgrade pathways, while wheeled variants cycle faster as mission profiles shift toward rapid reaction forces.
- Tracked:Steel or aluminum hulls with continuous track propulsion deliver superior cross-country mobility and armor integration for frontline mechanized units. Poland and Germany are compressing procurement timelines for these platforms under collective defense commitments.
- Wheeled:6x6 or 8x8 architectures reduce operational burden and enable rapid deployment by road or air transport. Baltic and Nordic forces favor these for territorial defense scenarios requiring quick repositioning.
- Amphibious:Sealed hulls with waterjet or propeller propulsion support riverine and coastal operations.
- Light:Reduced-weight platforms prioritize air transportability and strategic mobility over protection.
Tracked platforms dominate installed base across NATO mechanized brigades. Wheeled variants are where expansion concentrates for rapid response formations.
Armament:
Cost tiers separate cannon-integrated turrets from lighter weapon stations, with integration complexity driving margin concentration at the high end.
- Cannon:25-40mm autocannons with stabilized fire-control systems provide direct fire support against armored vehicles and fortifications. Turret integration complexity creates vendor lock-in around European and Israeli systems houses.
- Machine Gun:7.62mm or 12.7mm remote weapon stations offer cost-effective suppression capability for secondary missions and peacekeeping operations.
- Missile:Anti-tank guided missiles extend engagement range against heavy armor.
- Grenade Launcher:Automatic grenade systems deliver area suppression for urban and close terrain.
Cannon armament claims the largest share of turret procurement budgets. Missile integration is gaining share fastest as top-attack threats proliferate.
End User:
Volume concentrates with military services, while procurement sovereignty varies sharply between direct government acquisition and contractor-mediated programs.
- Military:Army and marine corps mechanized infantry units drive platform requirements through formal capability development processes. U.S. Army Futures Command and Germany's BAAINBw shape specifications through structured modernization cycles.
- Defense Contractors:Prime integrators manage multi-year framework contracts bundling development, production, and through-life support.
- Government Agencies:Border security and internal security forces acquire lighter variants for territorial control.
- NGOs:Humanitarian and observer missions lease or contract protected mobility.
Military end users control platform specification and funding flows. Defense contractors are capturing expanding scope through single-source responsibility models.
Technology:
Maturity gaps separate proven armor packages from emerging electronic warfare layers requiring rapid capability insertion.
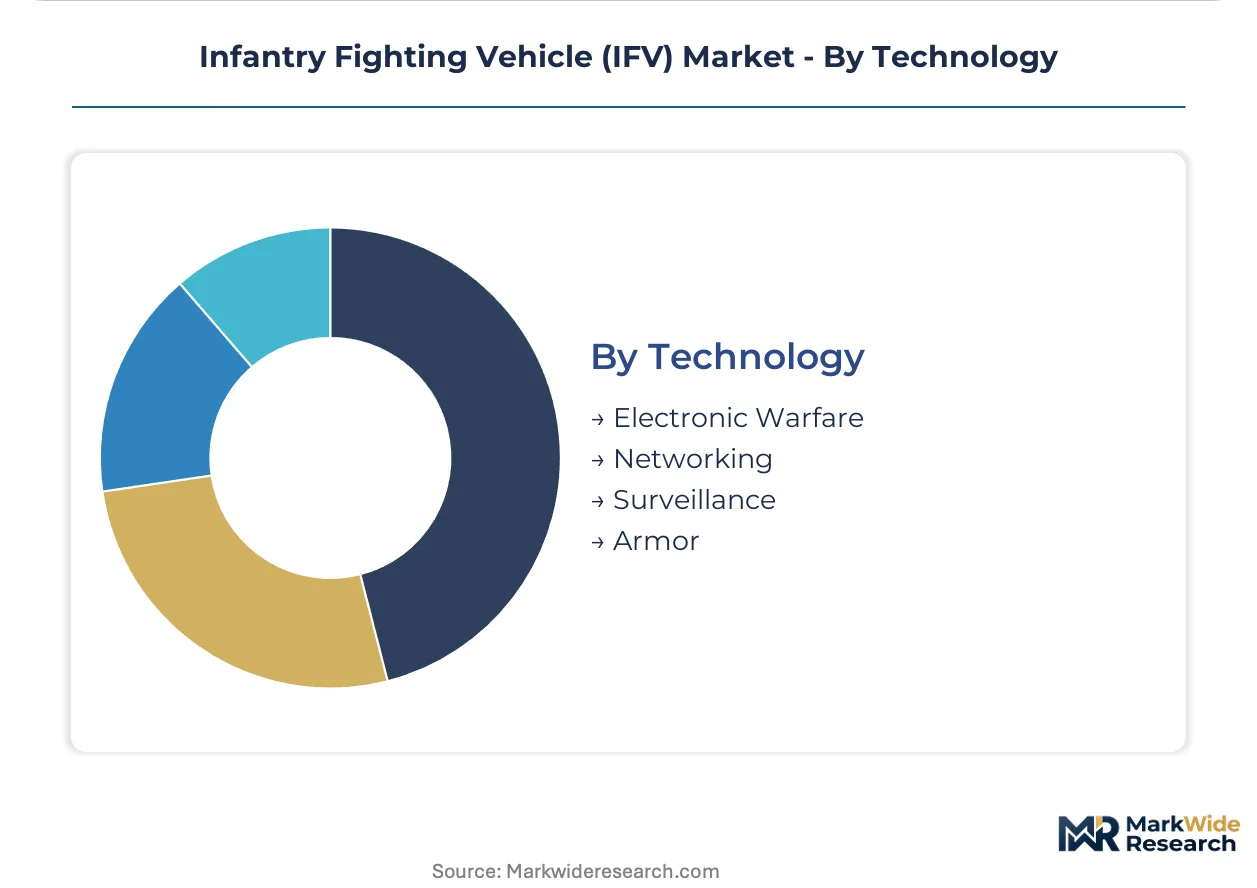
- Electronic Warfare:Spectrum dominance systems including jamming, direction-finding, and signal intelligence suites are becoming mission-critical baseline requirements. NATO's Standardization Office is accelerating interoperability mandates for cross-border maintenance networks.
- Networking:Vehicle and dismounted soldier datalinks enable coordinated maneuver and shared situational awareness.
- Surveillance:Electro-optical and infrared sensors support target acquisition in degraded visibility.
- Armor:Passive and reactive protection systems including composite arrays and active protection radars.
Armor technology dominates platform weight and cost structure. Electronic warfare represents the steepest expansion trajectory as spectrum operations become decisive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
U.S. Army Futures Command anchors procurement volume through structured modernization cycles. Collective defense commitments across NATO's eastern flank are compressing replacement timelines for mechanized formations.
United States
Army Futures Command drives tracked vehicle requirements through next-generation combat vehicle programs. Pentagon acquisition regulations mandate modular open systems architectures for interoperability. Michigan-based manufacturing clusters around Detroit sustain General Dynamics Land Systems production footprints for Stryker family variants.
Germany
BAAINBw procurement office consolidates framework contracts bundling development and through-life support. EU Green Deal carbon accounting rules redirect powertrain R&D toward hybrid-electric architectures. Bavarian industrial concentrations around Munich and Augsburg anchor Rheinmetall's manufacturing partnerships with KNDS structures.
Poland
Accelerated territorial defense programs establish regional manufacturing hubs serving adjacent Baltic markets. NATO Standardization Office interoperability mandates enable cross-border maintenance networks. Southwestern industrial zones around Wrocław and Poznań concentrate armored vehicle assembly under offset agreements with European primes.
United Kingdom
Army modernization reviews prioritize electronic warfare integration and active protection systems. Ministry of Defence procurement regulations emphasize single-source responsibility models for multi-decade support. BAE Systems maintains long-term supply relationships through CV90 platform variants spanning Nordic and Baltic export programs.
South Korea
Hanwha Corporation leverages domestic mechanized modernization to establish export positioning in Indo-Pacific amphibious segments. Defense Acquisition Program Administration regulations favor platforms with proven NATO interoperability for licensing frameworks. Southeastern industrial complexes around Changwon concentrate tracked vehicle production capacity for regional export growth.
Infantry Fighting Vehicle (IFV) Market Competitive Landscape
Capability concentration sits with systems integration specialists; scale advantage sits with established land systems primes. The vendor base separates into turret integration houses, hull fabricators, and powertrain specialists. Two archetypes dominate: European-Israeli systems houses controlling fire-control software layers, and North American primes managing multi-year framework contracts. Competitive moves concentrate on strategic partnerships for regional manufacturing access and captive supply of armor-grade materials.
Among U.S.-based land systems primes, General Dynamics Land Systems and Oshkosh Corporation exemplify scale-driven framework contract positioning. Rheinmetall and BAE Systems represent European integration specialists leveraging partnership structures for eastern flank manufacturing access. Textron Inc occupies a position bridging commercial automotive supply chains with defense powertrain requirements.
| Leading Market Players |
|---|
| Textron Inc |
| FNSS Savunma Sistemleri |
| General Dynamics Land Systems |
| Hanwha Corporation |
| Oshkosh Corporation |
| BAE Systems |
| Nexter Group |
| Patria Group |
| Rheinmetall |
| Others |
Supply & Pricing Matrix
Armor-grade titanium and composite ceramic suppliers in Germany, Japan, and the United States capture disproportionate margin pools downstream where platform integrators face vendor lock-in around turret fire-control software. This upstream concentration transfers pricing power to metallurgical processors and systems houses while compressing margins for hull fabricators competing on volume.
Pricing Analysis
Price spreads between NATO-interoperable platforms and non-aligned variants run wide, reflecting certification complexity and after-sales bundling. Three-tier pricing structure across expeditionary-grade, standard mechanized, and economy light variants segments buyers by mission profile and armor integration level. Cost compression in economy tiers intensifies as Eastern European ministries consolidate orders for volume leverage. Government defense agencies show highest price sensitivity due to budget cycle constraints, while rapid reaction forces prioritize deployment speed over unit cost.
Supply Chain Analysis
International Traffic in Arms Regulations and EU dual-use export controls restrict flows of active protection radar and fire-control software across supplier networks. Manufacturing concentrates in Germany, Poland, and the United States for final assembly, while South Korea and Japan supply armor-grade steel and electro-optical sensors. Supply chains draw from rare earth processors in China for ceramic composite matrices, creating single-source vulnerability in thermal protection layers. Distribution runs through prime integrators managing multi-year framework contracts with direct defense ministry relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as NATO members consolidate procurement through collective defense frameworks, shifting leverage from fragmented national programs toward centralized volume negotiations.
For Market Incumbents: Harden software-defined capability layers through captive development of AI-enabled target recognition algorithms to offset commoditization pressure in hull fabrication. Lock in turret integration expertise via exclusive partnerships with Israeli and European systems houses before emerging entrants qualify alternative fire-control architectures. Prioritize backward integration into armor-grade material processing to escape titanium and composite input volatility. For New Entrants and Emerging Players: Indo-Pacific amphibious platform demand offers the most penetrable white-space, where coastal defense forces seek wheeled variants with proven NATO interoperability for export licensing advantages. Target software-defined electronic warfare suites as the fastest-expanding capability insertion point, leveraging commercial automotive battery expertise for hybrid-electric driveline subsystems. Pursue offset agreements with Polish manufacturing hubs to anchor regional production access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed turret integration specialists holding proprietary fire-control software and long-term NATO maintenance contracts. Five-to-ten year viability hinges on successful navigation of cybersecurity certification requirements and active protection system integration complexity. Watch for inflection signals in EU Green Deal procurement rule implementation accelerating hybrid-electric R&D budget redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Driveline Development | Battery-diesel architectures open supplier entry points for automotive power electronics specialists entering defense. |
| Unmanned Turret Retrofit Programs | Germany's BAAINBw evaluations create aftermarket revenue streams without full hull replacement cycles. |
| Active Protection System Integration | Radar and effector placement demands electromagnetic interference testing capacity scarce among mid-tier integrators. |
| Regional Manufacturing Hub Establishment | Polish offset agreements concentrate assembly capacity serving adjacent Baltic and Nordic markets. |
| Electronic Warfare Suite Certification | NATO Standardization Office interoperability mandates enable cross-border maintenance network revenue capture. |
Research Methodology
A spread of perspectives from program managers at defense ministries, procurement officers at prime integrators, turret systems engineers, and armor materials specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through NATO Standardization Office technical documentation, national defense procurement regulations, EU defense industrial strategy filings, and customs trade data on armor-grade material flows. Bottom-up platform unit economics and top-down defense budget allocation triangulation anchored volume estimates.
Demand-supply balance dynamics across the projection horizon shaped the analytical framework, with segmentation modeled by mobility architecture, armament tier, end-user sovereignty level, and technology maturity. CAGRs derived from replacement cycle compression rates and capability insertion timelines. Forecast inputs incorporated hybrid-electric propulsion mandate implementation schedules and REACH chemical restriction phase-out calendars affecting surface treatment processes.
Macroeconomic conditions sit as an overlay; deviation in defense budget growth trajectories or rare earth element price volatility would shift the trajectory. Material shifts in collective defense procurement framework adoption or bilateral security agreement restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Taiwan Defense Market
Military Vehicles
Southeast Asia Defense Market
Military Vehicles
Military Land Vehicles Market
Military Vehicles
Global Military Vehicle Electrification Market
Military Vehicles
Riot Control Vehicle Market
Military Vehicles
Indonesia Defense Market
Military Vehicles
Military Ground Vehicle Actuators Market
Military Vehicles
Military Unmanned Ground Vehicle Market
Military Vehicles
India Combat Vehicle Systems Market
Military Vehicles
Japan Defense Market
Military Vehicles
Iran Defense Market
Military Vehicles
Eastern Europe Defense Market
Military Vehicles
Russia Defense Market
Military Vehicles
Military Vehicle & Aircraft Protection Systems Market
Military Vehicles
Combat Support Vehicle Market
Military Vehicles
Robotic Combat Vehicle (RCV) Market