
 Indonesia Defense Market | 2026-2036
Indonesia Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Defense Market Foresight
Indonesia's Ministry of Defense local content mandates is consolidating domestic industrial capacity across strategic platforms. PT PAL Indonesia anchors naval construction with frigate and submarine programs leveraging Dutch and South Korean technology partnerships. PT Pindad dominates land systems manufacturing, sustaining armored vehicle and small arms production for the Indonesian Army. PT Dirgantara Indonesia navigates aerospace maintenance and component assembly, positioning itself within regional supply chains despite capacity constraints.
Indonesia defense encompasses military equipment, platforms, and systems designed for national security operations across maritime, aerial, and terrestrial domains, typically manufactured to MIL-STD-810 environmental resilience specifications and STANAG interoperability protocols. Aircraft procurement absorbs substantial budget allocation as the Indonesian Air Force pursues fighter fleet recapitalization and maritime patrol capabilities. Naval Vessels represent the fastest-growing product category, reflecting archipelagic geography and exclusive economic zone patrol requirements. Cybersecurity technology attracts emergent investment, though domestic capability maturity lags behind platform-centric segments.
BIS certification requirements and Ministry of Defense procurement regulations shape supplier qualification pathways, while PT Len Industri competes in electronics and radar integration under national industrial policy frameworks. The country's defense procurement regulator enforces offset obligations and technology transfer conditions on foreign prime contractors. Stakeholders must monitor implementation consistency across procurement cycles and assess partnership durability against shifting geopolitical alignment priorities.
Market Dynamics
Indonesia's defense industrial base consolidation is accelerating under Ministry of Defense local content mandates, forcing foreign primes to transfer submarine, radar, and armored vehicle technology to state-owned enterprises while archipelagic patrol requirements reshape naval procurement priorities.
Growth Catalysts
- Ministry of Defense Local Content Mandates:Procurement regulations now require minimum 35% domestic value addition for major platforms, compelling technology transfer partnerships that elevate PT PAL and PT Dirgantara Indonesia into tier-one supplier roles.
- Exclusive Economic Zone Patrol Requirements:Indonesia's 5.8 million square kilometer maritime jurisdiction drives sustained demand for offshore patrol vessels, maritime patrol aircraft, and coastal surveillance radars across the Navy and Maritime Security Agency.
- Submarine Force Expansion:The Indonesian Navy's submarine fleet modernization program anchors long-term procurement, with South Korean technology partnerships enabling local assembly capabilities at the Surabaya shipyard cluster.
Market Restraints
- Defense Budget Cyclicality:Parliamentary appropriations fluctuate with commodity export revenues and fiscal consolidation pressures, creating procurement delays and payment timeline uncertainty for foreign contractors.
- Technology Transfer Asymmetry:Foreign primes retain control over critical subsystems—combat management systems, propulsion controls, and encrypted communications—limiting genuine industrial autonomy for domestic integrators.
- Skilled Workforce Scarcity:Naval architecture, systems engineering, and advanced electronics fabrication expertise concentrates in Java, constraining capacity expansion to Batam and Eastern Indonesia shipbuilding zones.
Strategic Opportunities
- Eastern Indonesia Maritime Infrastructure:Sorong, Biak, and Saumlaki port facilities remain underdeveloped for naval logistics, creating openings for integrated base construction and maintenance capability deployment.
- Cyber Defense Capability Gaps:Military network protection and critical infrastructure cybersecurity remain nascent, presenting entry points for specialized firms addressing command system vulnerabilities and data protection mandates.
- Regional Maintenance Hub Positioning:Batam's proximity to Singapore and exemption from certain trade restrictions positions PT Dirgantara Indonesia to capture Southeast Asian aerospace MRO contracts beyond domestic military demand.
Industry Challenges
- Multi-Platform Systems Integration Complexity:The Indonesian Armed Forces operate equipment from NATO, Russian, Chinese, and South Korean origins, forcing costly customization of command-and-control architectures and logistics chains.
- Offset Obligation Fulfillment:Foreign contractors struggle to identify viable Indonesian partners capable of absorbing mandated counter-trade and technology transfer commitments across electronics, materials, and precision manufacturing.
- Inter-Service Coordination Friction:Army, Navy, and Air Force procurement cycles operate on independent timelines with competing industrial priorities, fragmenting demand signals and diluting negotiating leverage with international suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Defense Market |
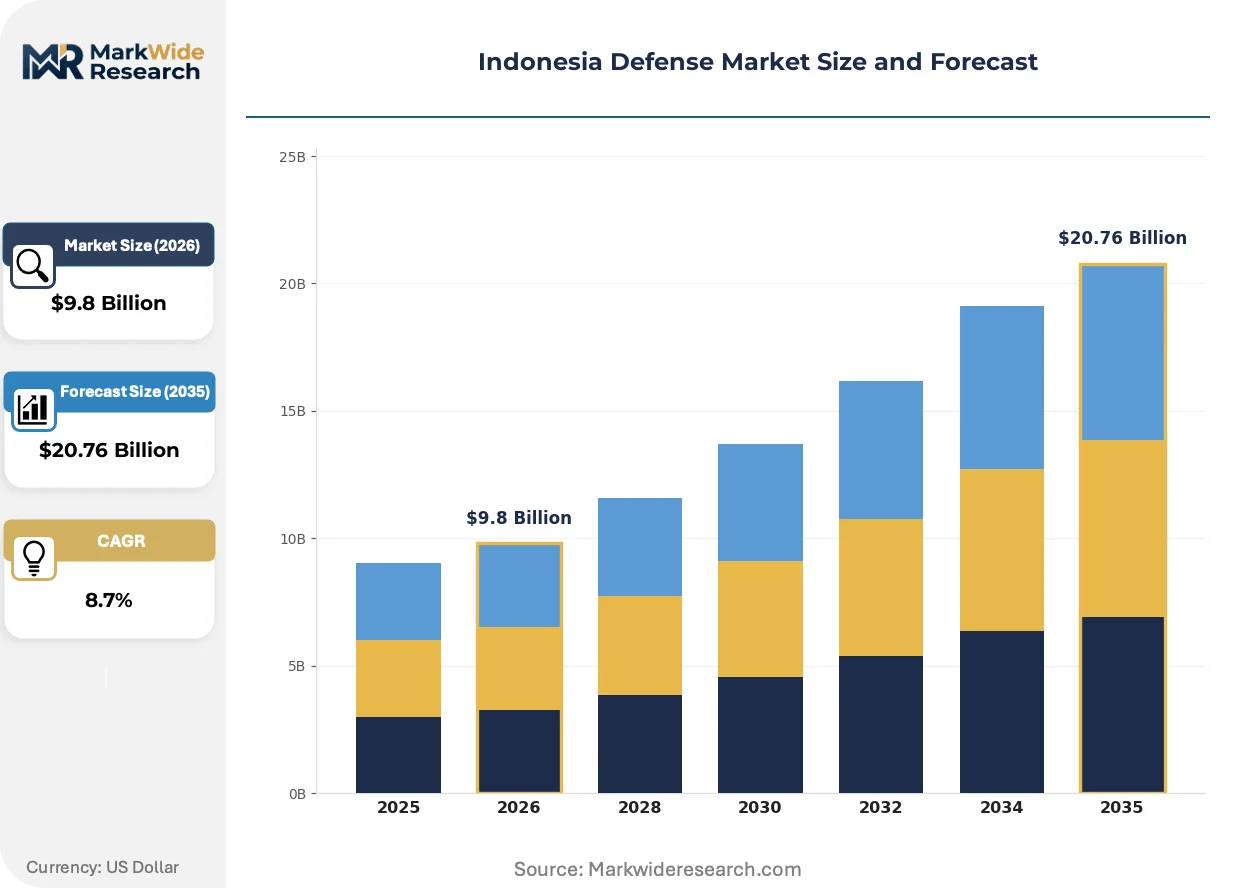
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aircraft, Naval Vessels, Land Systems, Munitions Technology: Cybersecurity, Surveillance Systems, Communication Equipment, Radar End User: Armed Forces, Government Agencies, Private Security, Defense Contractors Deployment: Domestic, International, Joint Ventures, Partnerships |
| Companies Covered | Airbus SE, Leonardo SpA, PT PAL Indonesia, Daewoo Shipbuilding & Marine Engineering Co. Ltd, Kongsberg Gruppen ASA, PT Pindad, BAE Systems PLC, PT Len Industri, PT Dirgantara Indonesia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Defense Market Shifts & Advancements
Unmanned systems and digital network architectures are displacing crewed patrol platforms and standalone sensor arrays across Indonesia's maritime domain awareness strategy, compressing procurement evaluation cycles for legacy equipment categories.
Artificial intelligence-enabled maritime surveillance is integrating optical, radar, and electronic intelligence feeds into unified threat detection platforms. The Indonesian Navy and Maritime Security Agency are piloting these systems for Malacca Strait monitoring. This convergence is integrating previously siloed sensor procurement budgets into single-vessel, multi-mission platform competitions.
BIS certification requirements and Ministry of Defense procurement regulations are tightening component traceability and cybersecurity resilience standards for imported electronics. Foreign suppliers must now document supply chain provenance and demonstrate anti-tamper protections for navigation and communications systems. Naval combat management systems and military-grade radar processors face the most stringent compliance timelines.
Fleet recapitalization priorities are rotating procurement emphasis from quantity-driven vessel acquisitions toward capability-per-platform metrics. The Indonesian Navy now evaluates hulls based on integrated sensor suites and interoperability with regional partners rather than hull count alone. This recalibration is most visible in frigate and corvette competitions where combat system architecture outweighs displacement specifications.
Indonesia Defense Market Segmentation
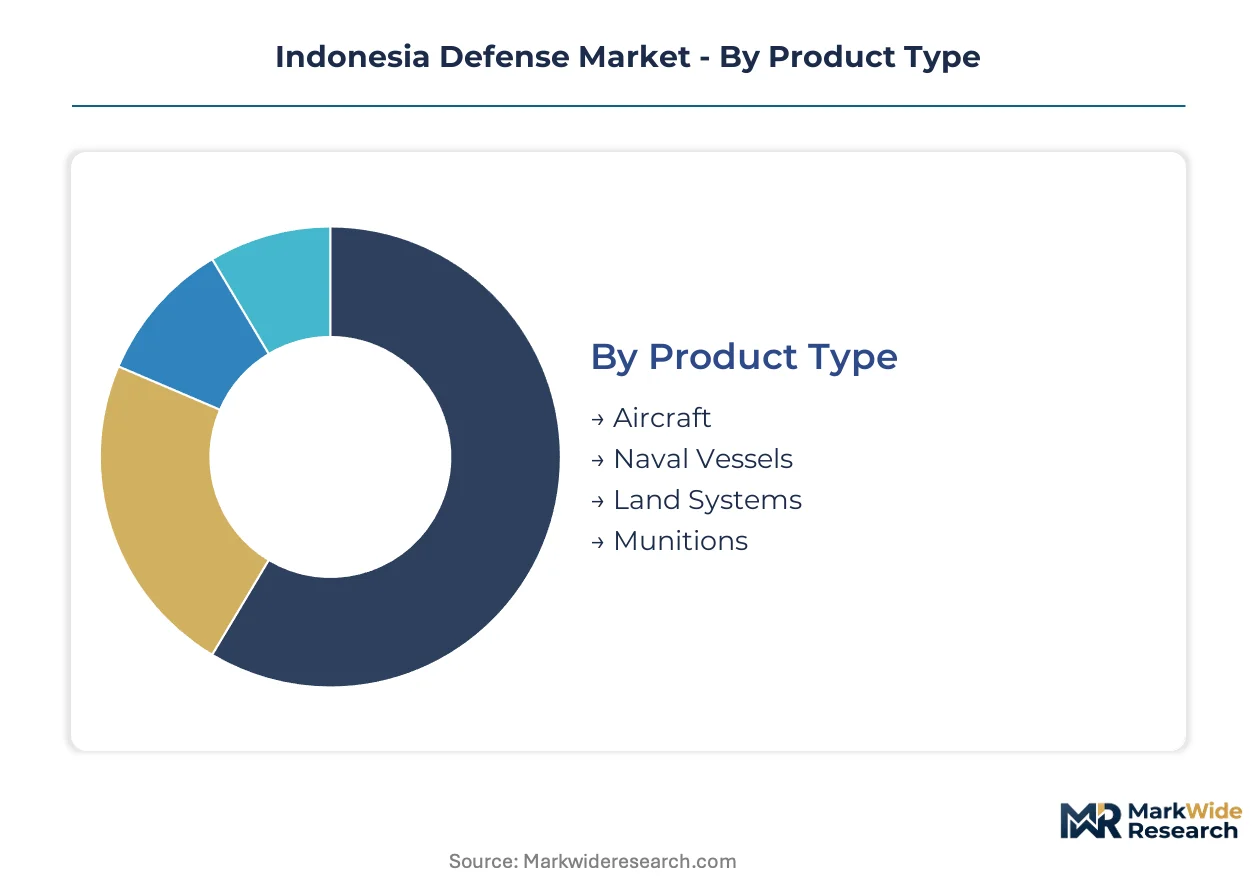
Segmentation of the Indonesia defense market reveals procurement concentration patterns that align with archipelagic geography and Ministry of Defense industrial policy priorities. Understanding these divisions exposes where technology transfer mandates reshape supplier positioning and where budget allocation friction occurs between services.
Product Type:
Domestic shipbuilding capacity concentrates procurement decisions in Java-based facilities, while aerospace and land systems follow divergent qualification pathways.
- Naval Vessels:Frigates, corvettes, and offshore patrol vessels incorporate combat management systems from South Korean and Dutch partnerships. PT PAL Indonesia's Surabaya shipyard cluster absorbs the largest procurement volumes as the Indonesian Navy expands exclusive economic zone patrol capabilities.
- Aircraft:Fighter fleet recapitalization and maritime patrol platforms consume substantial budget share. The Indonesian Air Force prioritizes multi-role capabilities compatible with regional interoperability protocols, concentrating demand in Java-based maintenance infrastructure.
- Land Systems:PT Pindad manufactures armored vehicles and small arms under technology transfer arrangements with European and South Korean primes.
- Munitions:Domestic production capabilities remain limited for precision-guided systems, driving import dependency for advanced ordnance categories.
Today's leader: Naval Vessels. Tomorrow's challenger: Aircraft.
Technology:
Procurement evaluation cycles compress as digital architectures displace standalone sensor investments across maritime domain awareness programs.
- Surveillance Systems:Optical, radar, and electronic intelligence feeds converge into unified threat detection platforms for Malacca Strait monitoring. The Maritime Security Agency pilots artificial intelligence-enabled integration, collapsing previously siloed procurement budgets.
- Communication Equipment:Encrypted military networks require BIS certification and documented supply chain provenance. Foreign suppliers face tightening cybersecurity resilience standards for navigation and command systems.
- Radar:PT Len Industri competes in military-grade radar processor integration under national industrial policy frameworks.
- Cybersecurity:Military network protection and critical infrastructure defense remain nascent, with domestic capability maturity lagging platform-centric segments.
Surveillance Systems gain share fastest; Cybersecurity climbs from smallest base.
End User:
Budget authority fragmentation across institutional boundaries creates competing demand signals and dilutes negotiating leverage with international suppliers.
- Armed Forces:The Indonesian Army, Navy, and Air Force operate independent procurement cycles with competing industrial priorities. Inter-service coordination friction fragments demand signals, particularly where multi-platform systems integration complexity arises from mixed NATO, Russian, Chinese, and South Korean equipment origins.
- Government Agencies:The Maritime Security Agency and intelligence services drive parallel procurement for coastal surveillance and counter-terrorism capabilities.
- Private Security:Critical infrastructure protection contracts expand following regulatory mandates for energy and transportation asset security.
- Defense Contractors:Offset obligation fulfillment requirements channel technology transfer through state-owned enterprise partnerships.
Armed Forces dominate current procurement; Government Agencies expand fastest on maritime security investments.
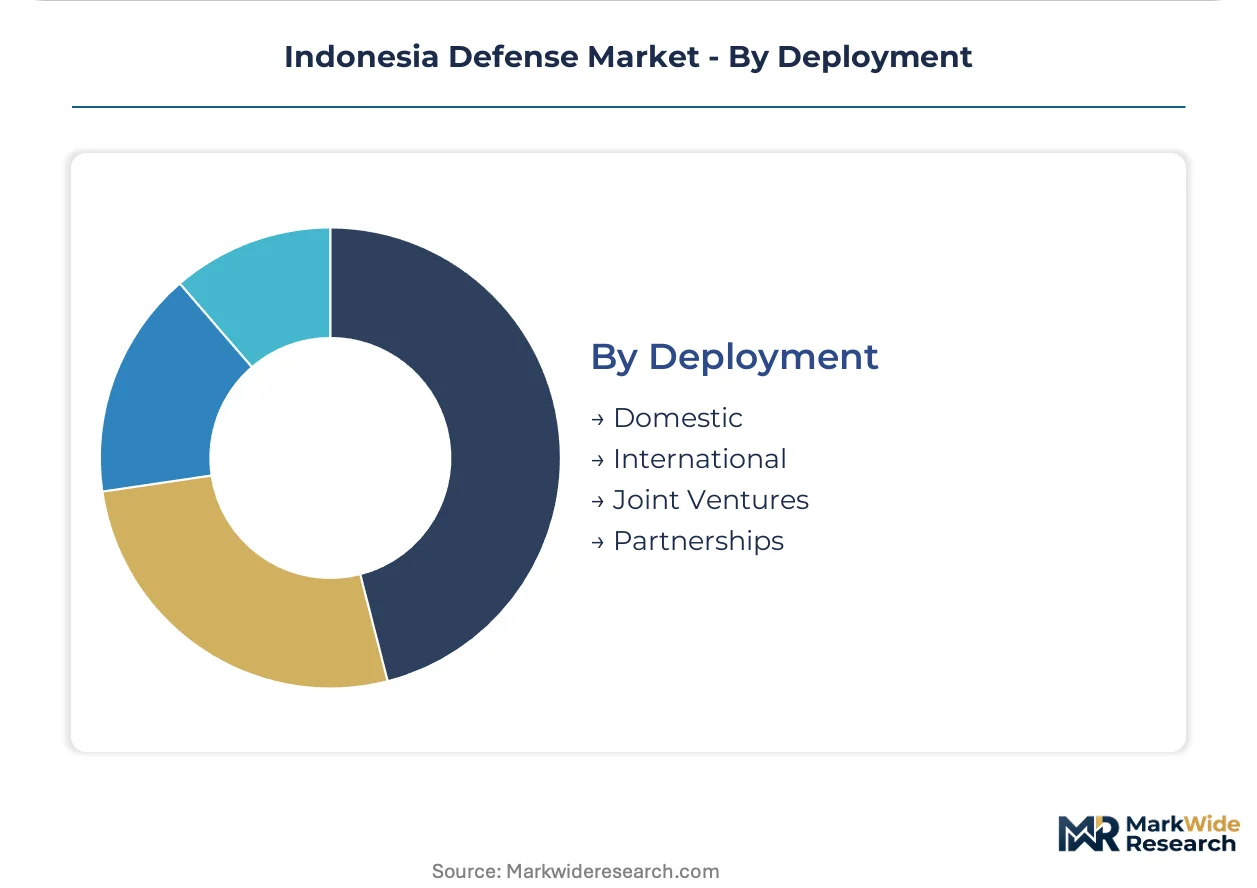
Deployment:
Local content mandates restructure contractual arrangements, forcing foreign primes into capability-transfer relationships with designated domestic integrators.
- Joint Ventures:Minimum 35% domestic value addition requirements compel submarine, radar, and armored vehicle technology partnerships. PT PAL and PT Dirgantara Indonesia assume tier-one supplier roles through these structures.
- Domestic:Sole-source procurement applies where indigenous capabilities meet operational requirements, particularly for small arms and basic naval auxiliaries.
- Partnerships:Technology transfer conditions apply to major platform acquisitions, with durability contingent on shifting geopolitical alignment priorities.
- International:Direct import remains necessary for advanced combat aircraft and precision munitions where domestic integration capabilities are absent.
Joint Ventures command procurement reform momentum; International procurement persists where capability gaps remain unbridgeable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's defense industrialization traces its modern foundations to the 1970s state-led manufacturing mandates that established PT Pindad and PT PAL as strategic national champions. Archipelagic geography and exclusive economic zone imperatives have since concentrated procurement authority in Java-based production clusters while eastern maritime infrastructure remains underdeveloped.
Java
Java absorbs the dominant share of defense manufacturing capacity, with Surabaya's shipyard cluster hosting submarine and frigate assembly under South Korean technology partnerships. The Ministry of Defense enforces 35% minimum domestic value addition requirements that elevate PT PAL Indonesia into tier-one supplier status for naval platforms. Bandung anchors aerospace maintenance and component fabrication, positioning PT Dirgantara Indonesia within regional supply chains despite persistent capacity constraints.
Batam
Batam's free trade zone status and proximity to Singapore create distinctive aerospace maintenance opportunities exempt from certain import restrictions. The Maritime Security Agency channels coastal surveillance radar procurement through facilities here, leveraging the island's logistics connectivity for regional MRO contract capture. PT Dirgantara Indonesia maintains overhaul capabilities that extend beyond domestic military demand into Southeast Asian commercial aviation networks.
Sulawesi
Sulawesi's Makassar Strait location positions the island as a forward logistics node for eastern maritime patrol operations. The Indonesian Navy has expanded port infrastructure at Makassar to support offshore patrol vessel deployments into the Flores and Banda Seas. Local content mandates face implementation challenges here due to skilled workforce scarcity and limited precision manufacturing ecosystems.
Papua
Papua's border proximity to Pacific maritime routes drives surveillance infrastructure investment under the Maritime Security Agency's domain awareness programs. Sorong port facilities remain underdeveloped for naval logistics, creating openings for integrated base construction and maintenance capability deployment. The Ministry of Defense prioritizes coastal radar networks here to monitor transit corridors near Australian and Papua New Guinea waters.
Sumatra
Sumatra's Malacca Strait frontage concentrates maritime security procurement for chokepoint monitoring and counter-piracy capabilities. The Indonesian Navy maintains forward operating facilities at Belawan and Lampung to project presence into one of the world's busiest shipping lanes. PT Len Industri competes in radar integration for these installations under national industrial policy frameworks that favor domestic electronics assembly.
Indonesia Defense Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Indonesia's defense procurement ecosystem, where state-owned enterprises absorb technology transfer obligations while foreign primes retain control over critical subsystems. The market structure fragments across three tiers: domestic integrators fulfilling local content mandates, regional specialists from South Korea and Europe anchoring platform partnerships, and global primes supplying advanced combat systems where indigenous capabilities remain absent. Strategic archetypes include state-owned platform integrators, foreign technology licensors, and electronics subsystem specialists. Competitive dynamics center on joint venture formation for submarine and radar programs, alongside capacity expansion at Surabaya and Batam facilities to meet exclusive economic zone patrol requirements.
Within the state-owned integrator tier, PT PAL Indonesia, PT Pindad, and PT Dirgantara Indonesia occupy foundational positions mandated by Ministry of Defense industrial policy. PT PAL Indonesia exemplifies the naval platform archetype through frigate and submarine assembly leveraging Dutch and South Korean partnerships. PT Pindad represents land systems manufacturing dominance in armored vehicles and small arms. PT Dirgantara Indonesia anchors aerospace maintenance positioning despite capacity constraints that limit full system integration. Foreign primes including Airbus SE, Leonardo SpA, and BAE Systems PLC operate through technology transfer arrangements rather than direct market presence, reflecting procurement regulations that compel domestic partnership structures.
| Leading Market Players |
|---|
| Airbus SE |
| Leonardo SpA |
| PT PAL Indonesia |
| Daewoo Shipbuilding & Marine Engineering Co. Ltd |
| Kongsberg Gruppen ASA |
| PT Pindad |
| BAE Systems PLC |
| PT Len Industri |
| PT Dirgantara Indonesia |
| Others |
Supply & Pricing Matrix
MIL-STD-810 environmental resilience certification gates qualified supply access and premium-tier pricing for defense electronics and platform subsystems in Indonesia. Foreign primes absorbing technology transfer obligations under Ministry of Defense mandates face cost compression in standard-tier naval vessels while integrated combat management systems sustain pricing premiums.
Pricing Analysis
Project-based contracting with milestone-linked payments dominates major platform acquisitions, separating turnkey system integrators from component suppliers. Price differentiation hinges on BIS certification grade and combat system interoperability tier, with STANAG-compliant architectures commanding substantial premiums over baseline configurations. Pricing pressure stems from parliamentary appropriation cyclicality tied to commodity export revenues, compressing margins for foreign contractors in frigate and submarine competitions. State-owned enterprises exhibit lowest price sensitivity due to sole-source procurement authority, while private sector maintenance providers face acute cost scrutiny.
Supply Chain Analysis
Domestic content mandates requiring 35% minimum value addition are reshaping sourcing patterns, forcing foreign primes into joint venture structures with PT PAL Indonesia and PT Dirgantara Indonesia. Critical subsystems draw from South Korea, the Netherlands, and France for combat management systems, propulsion controls, and encrypted communications. Supply chain risk concentrates in single-source dependencies for military-grade radar processors and precision navigation equipment. Distribution runs through Java-based shipbuilding clusters and Batam aerospace maintenance facilities, with eastern Indonesian port infrastructure remaining underdeveloped for naval logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's defense market represents a late-cycle quality story as procurement evaluation cycles rotate from quantity-driven vessel counts toward capability-per-platform metrics. Demand is shifting toward integrated sensor suites and artificial intelligence-enabled maritime surveillance systems that command premium specifications.
For Market Incumbents: Lock in technology transfer partnerships with PT PAL Indonesia and PT Len Industri before local content mandates tighten further. Secure submarine and frigate combat system architecture positions against emerging South Korean prime competition. Prioritize certification investment in BIS-compliant radar and navigation electronics to defend tier-one supplier status. For New Entrants and Emerging Players: The mid-tier pricing gap between premium NATO-origin platforms and economy-tier Russian/Chinese alternatives creates entry space for specialized cybersecurity and unmanned maritime system providers. Target coastal surveillance radar integration for Maritime Security Agency deployments in Papua and Sulawesi. Pursue offset obligation fulfillment partnerships as the primary go-to-market pathway. For Investors and Strategic Acquirers: Roll-up economics work for electronics subsystem specialists because fragmented domestic capability across radar, communications, and combat management creates consolidation value. Five-to-ten year viability hinges on partnership durability with state-owned platform integrators. Watch for Indonesian Navy fleet recapitalization program acceleration as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Transfer Partnership | Ministry of Defense local content mandates compel foreign primes into joint ventures with PT PAL Indonesia for submarine assembly. |
| Combat System Integration | Artificial intelligence-enabled maritime surveillance converges optical, radar, and electronic intelligence procurement budgets. |
| Regional MRO Expansion | PT Dirgantara Indonesia leverages Batam's free trade zone status to capture Southeast Asian aerospace maintenance contracts. |
| Cybersecurity Capability Buildout | Military network protection gaps present entry points for specialized firms addressing command system vulnerabilities. |
| Eastern Infrastructure Development | Sorong and Biak port facility investments support Indonesian Navy exclusive economic zone patrol requirements. |
Research Methodology
Direct dialogue with Ministry of Defense procurement officials, PT PAL Indonesia engineering directors, foreign prime contractor country managers, and Maritime Security Agency operational planners grounded this analysis. Secondary validation drew from parliamentary defense appropriation records, BIS certification databases, Indonesian Navy fleet modernization announcements, and South Korean shipbuilder technology partnership disclosures. Bottom-up procurement pipeline assessment triangulated against top-down defense budget allocation analysis.
Segmented projections across naval vessels, aircraft, land systems, and munitions categories integrated technology transfer implementation timelines and local content mandate compliance trajectories. Modeled dimensions spanned platform type, combat system architecture tier, end-user service branch, and deployment structure. CAGRs derived from parliamentary appropriation trend analysis, commodity export revenue correlation, and fleet recapitalization program acceleration indicators. Indonesian Navy submarine force expansion targets and Maritime Security Agency coastal radar network deployment schedules informed platform-specific demand curves.
The model assumes a particular technology adoption path for artificial intelligence-enabled maritime surveillance; alternative pathways for unmanned surface vessel integration would alter the outlook. Forecasts reflect assumptions regarding Ministry of Defense procurement reform consistency, technology transfer partnership durability, and parliamentary budget execution rates. Geopolitical alignment shifts or commodity export revenue volatility could revise projections substantially. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Military Unmanned Ground Vehicle Market
Military Vehicles
Military Tank Container Market
Military Vehicles
India Combat Vehicle Systems Market
Military Vehicles
Colombia Defense Market
Military Vehicles
Global Offshore Patrol Vessel (OPV) Market
Military Vehicles
Japan Defense Market
Military Vehicles
Eastern Europe Defense Market
Military Vehicles
Military Vehicle & Aircraft Protection Systems Market
Military Vehicles
Iran Defense Market
Military Vehicles
Military Ground Vehicle Actuators Market
Military Vehicles
Main Battle Tank Market
Military Vehicles
Destroyers Market
Military Vehicles
Taiwan Defense Market
Military Vehicles
Global Military Vehicle Electrification Market
Military Vehicles
Combat Support Vehicle Market
Military Vehicles
Military Trucks Market