
 Eastern Europe Defense Market | 2026-2036
Eastern Europe Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Eastern Europe Defense Market Foresight
EU Green Deal defense procurement amendments is realigning the cost-of-entry calculus for contractors seeking Eastern European contracts. Rheinmetall AG leverages its armored vehicle engineering to anchor production partnerships in Poland and Romania. PGZ sustains state-backed manufacturing scale across land systems and ammunition verticals. RTX Corporation competes through integrated air defense and missile system portfolios tailored to NATO member requirements.
Eastern Europe defense encompasses military equipment, platforms, and services designed for territorial protection, deterrence, and alliance interoperability, spanning armored vehicles with composite armor ratings above STANAG 4569 Level 4, naval frigates with integrated combat management systems, and layered air defense architectures. The primary purpose centers on equipping national militaries and alliance structures against conventional and hybrid threats. Land Systems occupies the largest revenue pool given tracked vehicle modernization cycles across Poland and Czechia, while Cybersecurity Solutions represents the fastest-expanding segment as government agencies harden critical infrastructure against state-sponsored intrusion campaigns. Drone Technology within the technology dimension concentrates margin capture among firms mastering autonomous swarm coordination and electronic warfare resistance.
Poland's Ministry of National Defence procurement directives, NATO STANAG standardization mandates, and the EU European Defence Fund eligibility rules collectively shape product certification pathways and cross-border joint venture requirements for market access. The country's national pharmaceutical regulator does not apply here; defense-specific oversight falls under military procurement authorities and alliance technical bodies. Stakeholders must monitor how EU defence industrial strategy revisions alter local content thresholds and technology transfer obligations for non-EU suppliers.
Market Dynamics
NATO STANAG standardization mandates are compressing procurement cycles across Poland, Romania, and the Baltic states. Defense ministries now require certified interoperability before contract award, forcing suppliers to restructure engineering workflows around alliance technical specifications rather than national requirements.
Growth Catalysts
- EU European Defence Fund eligibility rules:Joint procurement frameworks reduce per-unit costs for member states pooling air defense acquisitions. Polish and Romanian ministries leverage this mechanism for drone swarm system contracts.
- Poland's Vistula River industrial corridor:Concentrated manufacturing infrastructure enables rapid scaling of armored vehicle production. State-backed foundries and composite armor facilities cluster within 150 kilometers of Warsaw.
- Hybrid threat doctrine adoption:Military planners prioritize layered defense architectures combining kinetic and electronic warfare capabilities. This drives demand for integrated command systems across land and air domains.
Market Restraints
- Specialized steel alloy supply concentration:High-hardness armor plate production concentrates in German and Swedish mills. Eastern European vehicle assemblers face extended lead times and price volatility for STANAG 4569 Level 4+ certified materials.
- EU Green Deal defense procurement amendments:New carbon accounting requirements add compliance overhead for non-EU suppliers bidding on Polish tenders. The cost-of-entry calculus shifts against North American and Asian contractors lacking EU manufacturing footprints.
- Legacy Soviet platform maintenance burden:Romanian and Bulgarian forces operate aging T-72 variants and MiG-29 fleets. Sustained operational expenditure drains modernization budgets that could redirect toward NATO-standard equipment.
Strategic Opportunities
- Czechia's underdeveloped cyber defense procurement:Government agencies lack mature acquisition frameworks for critical infrastructure protection. Contractors with NATO-certified security clearances can anchor long-term service relationships before formal tender processes mature.
- AI-enabled predictive maintenance convergence:Machine learning diagnostics layered onto existing armored vehicle fleets reduce through-life costs. Polish land forces command structures actively pilot these systems for Leopard 2PL modernization programs.
- Baltic states' joint ammunition stockpiling initiative:Estonia, Latvia, and Lithuania pool procurement for artillery shell reserves. Suppliers establishing regional storage and rapid distribution hubs gain preferential contracting status.
Industry Challenges
- STANAG 4569 Level 4+ ballistic certification timelines:Testing protocols at NATO-certified facilities require 18-24 months for new composite armor configurations. Product development cycles misalign with urgent procurement deadlines set by defense ministries.
- Electronic warfare systems integration complexity:Drone platforms must harmonize with existing air defense networks. Software architecture mismatches between national command systems create deployment friction.
- Specialized welding technician scarcity:Armored vehicle hull fabrication requires certified personnel for ballistic-grade joint construction. Training pipelines across Poland and Romania lag production ramp schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eastern Europe Defense Market |
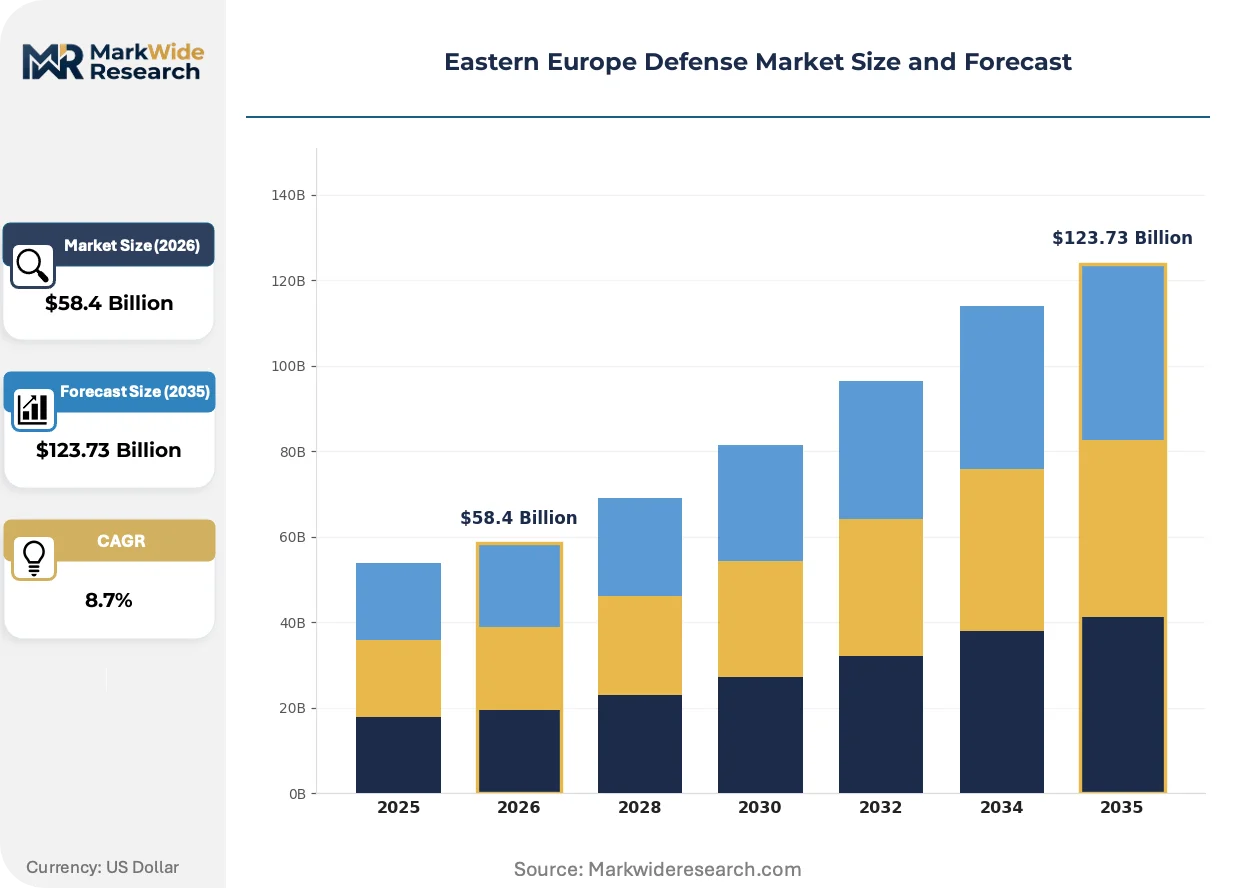
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $123.73 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Land Systems, Naval Systems, Air Defense Systems, Cybersecurity Solutions End User: Military Forces, Government Agencies, Defense Contractors, Private Security Firms Technology: Drone Technology, Communication Systems, Armor Technologies, Simulation Software Application: Border Security, Combat Operations, Intelligence Gathering, Logistics Management |
| Companies Covered | Rostec, Rheinmetall AG, United Shipbuilding Corporation, BAE Systems plc, THALES, MESKO, PGZ, JSC Ukrainian Defense Industry, RTX Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eastern Europe Defense Market Shifts & Advancements
Autonomous systems architecture is displacing manned platforms across reconnaissance and strike missions. Defense ministries rewrite operational doctrines around human-machine teaming, compressing development timelines for AI-enabled coordination software.
Drone swarm coordination technology is expanding into layered air defense architectures. Polish and Romanian military procurement offices now require autonomous deconfliction and electronic warfare resistance as baseline specifications for unmanned aerial system tenders. This capability compression is forcing traditional aerospace contractors to acquire or partner with specialized autonomy software houses rather than develop internally.
EU Green Deal defense procurement amendments are mandating lifecycle carbon accounting for equipment contracts. The industrial consequence requires suppliers to document embodied emissions from steel smelting through final assembly. Polish Ministry of National Defence tenders now weight environmental criteria at 15 percent of technical evaluation scores, disadvantaging contractors without EU-based supply chains.
Buyer concentration around NATO joint procurement frameworks is consolidating vendor relationships. Defense ministries pool requirements through the NATO Support and Procurement Agency, replacing bilateral negotiations with multilateral competitive processes. This channel shift is most visible in Baltic states artillery and air defense acquisitions, where national procurement offices cede specification authority to alliance technical bodies.
Eastern Europe Defense Market Segmentation
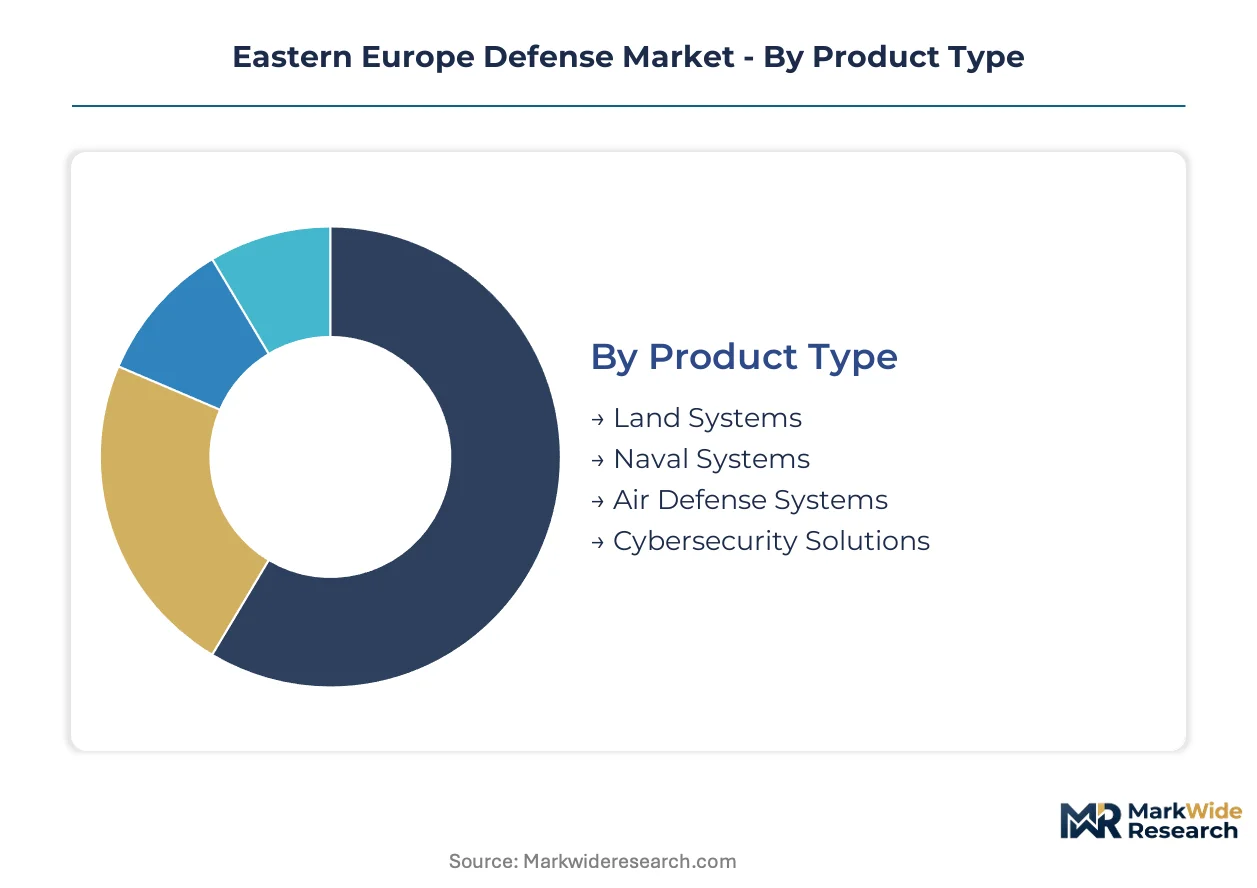
Defense procurement across Eastern Europe demands granular segmentation to align NATO interoperability mandates with national modernization priorities. Product specifications, end-user requirements, and technology maturity vary sharply between Polish land force upgrades and Baltic cyber defense initiatives.
Product Type:
Armor ratings and platform integration complexity define procurement evaluation criteria across Polish, Romanian, and Czech defense ministries.
- Land Systems:Tracked vehicles with STANAG 4569 Level 4+ composite armor configurations dominate procurement volumes. Poland's Ministry of National Defence channels modernization budgets through the Vistula River industrial corridor for rapid production scaling.
- Air Defense Systems:Layered architectures combining kinetic interceptors with electronic warfare resistance are displacing legacy Soviet-era platforms. Romanian procurement offices prioritize NATO-certified interoperability before contract award.
- Naval Systems:Frigates with integrated combat management systems serve Black Sea deterrence requirements.
- Cybersecurity Solutions:Critical infrastructure protection contracts are climbing the fastest as government agencies harden against state-sponsored intrusion campaigns.
Mature deployment sits with Land Systems. Newer deployment is concentrated in Cybersecurity Solutions.
End User:
Budget authority and certification requirements create distinct procurement channels across institutional buyers.
- Military Forces:National armies in Poland, Romania, and the Baltic states hold primary contracting authority for platform acquisitions. STANAG standardization mandates compress their procurement cycles and reshape vendor qualification pathways.
- Government Agencies:Ministries of interior and critical infrastructure operators drive cyber defense spending. Czechia's underdeveloped acquisition frameworks create first-mover advantages for NATO-cleared contractors.
- Defense Contractors:Tier-one system integrators subcontract component manufacturing to Polish and Romanian state-backed facilities.
- Private Security Firms:Peripheral demand concentrates on communications equipment and surveillance technologies for border zone operations.
Volume concentration rests with Military Forces. Margin expansion is shifting toward Government Agencies.
Technology:
Autonomy software and electronic warfare resistance separate competitive tiers in unmanned system tenders.
- Drone Technology:Autonomous swarm coordination with deconfliction algorithms is now mandatory in Polish and Romanian UAS specifications. Traditional aerospace contractors must partner with specialized autonomy houses to meet baseline requirements.
- Armor Technologies:High-hardness steel alloys and composite configurations face 18-24 month NATO certification timelines at specialized testing facilities.
- Communication Systems:Secure networks must harmonize with existing national command architectures.
- Simulation Software:Human-machine teaming doctrine is compressing development timelines for AI-enabled training platforms.
Procurement maturity favors Armor Technologies. Capability gaps are widest in Drone Technology.
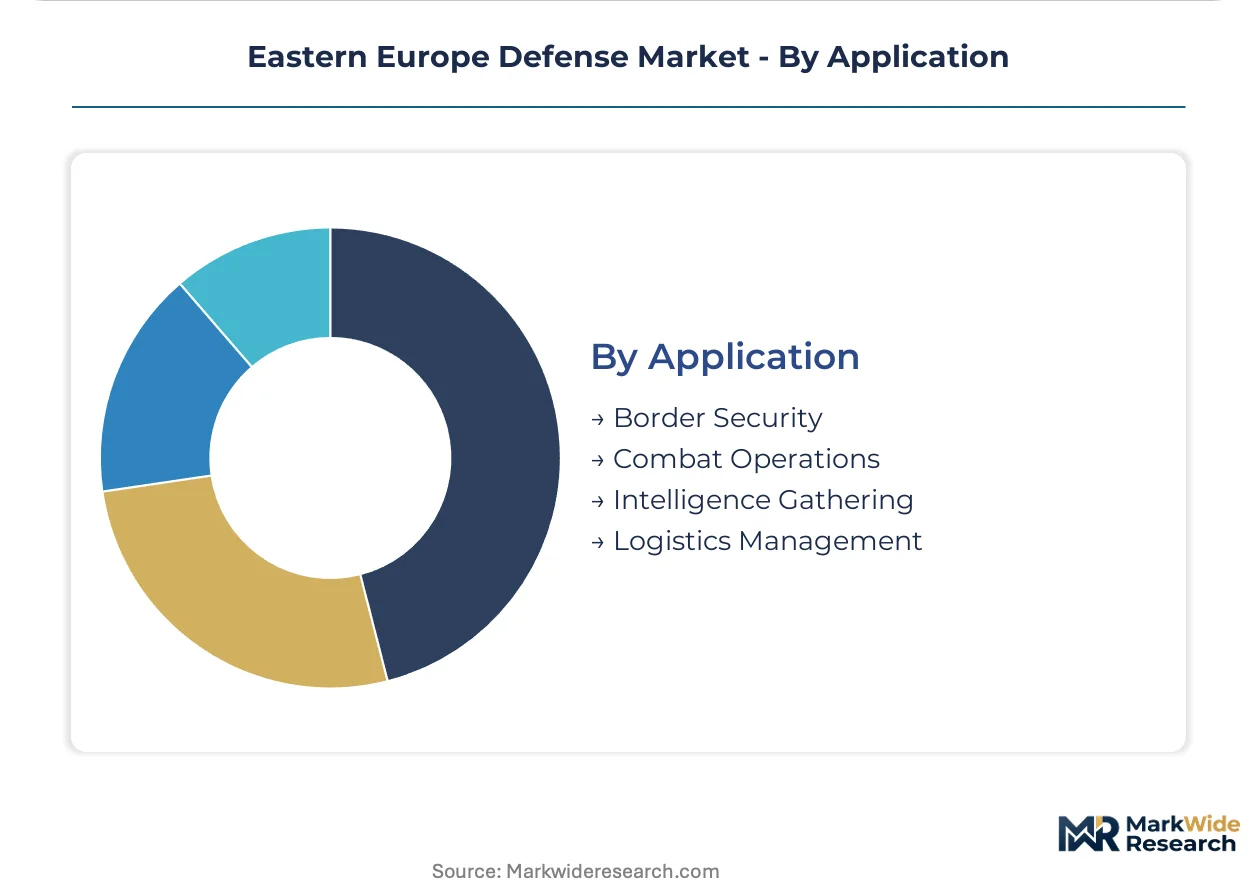
Application:
Operational doctrine revisions are reweighting investment across mission profiles.
- Combat Operations:Manned-unmanned teaming architectures are displacing legacy platform concepts. Polish land forces pilot AI-enabled predictive maintenance for Leopard 2PL fleets to reduce through-life costs.
- Border Security:Baltic states pool artillery and surveillance procurement through NATO joint frameworks, ceding national specification authority to alliance technical bodies.
- Intelligence Gathering:Sensor fusion requirements drive integration contracts across air and space domains.
- Logistics Management:Ammunition stockpiling initiatives in Estonia, Latvia, and Lithuania favor suppliers establishing regional distribution hubs.
Established investment patterns center on Combat Operations. Fastest budget reallocation is occurring in Border Security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's Special Economic Zone for National Defense in Radom anchors regional production concentration, channeling state incentives toward armored vehicle and ammunition manufacturing clusters along the Vistula River corridor.
Poland
Poland's Ministry of National Defence channels procurement through the Vistula River industrial corridor for rapid scaling of tracked vehicle production. EU European Defence Fund eligibility rules enable joint framework contracts that reduce per-unit costs for air defense acquisitions. State-backed foundries and composite armor facilities cluster within 150 kilometers of Warsaw, supporting Leopard 2PL modernization programs.
Romania
Romanian forces operate aging T-72 variants that drain budgets from NATO-standard equipment procurement. The country's defense ministry prioritizes certified interoperability before contract award under NATO STANAG standardization mandates. Black Sea deterrence requirements drive demand for frigates with integrated combat management systems at Constanța shipyard facilities.
Czechia
Czechia's government agencies lack mature acquisition frameworks for critical infrastructure protection against state-sponsored intrusion campaigns. NATO-certified security clearances create first-mover advantages for contractors establishing service relationships before formal tender processes mature. Land systems modernization concentrates in Moravian industrial zones with legacy heavy machinery expertise.
Estonia
Estonia pools artillery shell procurement with Latvia and Lithuania through joint ammunition stockpiling initiatives. Baltic defense planners cede specification authority to NATO Support and Procurement Agency for border security acquisitions. Regional storage and rapid distribution hubs in Tallinn gain preferential contracting status under alliance frameworks.
Ukraine
Ukraine's defense industrial base operates under wartime mobilization with state-directed production of drone systems and armored platforms. JSC Ukrainian Defense Industry consolidates fragmented Soviet-era facilities under centralized control. Lviv and Dnipro manufacturing clusters prioritize electronic warfare-resistant unmanned systems for frontline deployment.
Eastern Europe Defense Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Eastern Europe defense procurement channels. The vendor structure organizes into three tiers: state-backed national champions with captive domestic markets, diversified European industrial groups leveraging NATO certification pathways, and specialized autonomy software houses capturing drone technology margins. Consolidation pressures intensify as defense ministries require STANAG interoperability before contract award. Joint venture formation and technology licensing agreements represent dominant competitive moves for market access.
Within the state-backed tier, PGZ anchors Polish manufacturing scale across land systems and ammunition verticals. Rheinmetall AG exemplifies diversified European industrial positioning through armored vehicle engineering partnerships in Poland and Romania. RTX Corporation occupies the integrated systems tier, competing through air defense and missile portfolios tailored to NATO member requirements.
| Leading Market Players |
|---|
| Rostec |
| Rheinmetall AG |
| United Shipbuilding Corporation |
| BAE Systems plc |
| THALES |
| MESKO |
| PGZ |
| JSC Ukrainian Defense Industry |
| RTX Corporation |
| Others |
Supply & Pricing Matrix
High-hardness armor plate spot prices at German and Swedish mills cascade through three distinct procurement tiers, compressing margins for Eastern European vehicle assemblers while rewarding contractors with captive steel supply or long-term offtake agreements.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with 18-24 month STANAG 4569 Level 4+ certification timelines commanding 15-25 percent price escalations over standard-grade alternatives. Three-tier pricing structure across NATO-certified, national-standard, and legacy Soviet-compatible equipment segments reflects certification burden and interoperability guarantees. Cost compression in the legacy tier is intensifying because Romanian and Bulgarian forces divert maintenance budgets toward urgent platform replacement. Government procurement offices exhibit highest price sensitivity, while private security contractors purchasing communications equipment demonstrate willingness to absorb premiums for rapid fielding.
Supply Chain Analysis
Single-source vulnerability sits with Swedish SSAB and German ThyssenKrupp for ballistic-grade steel alloys certified to STANAG 4569 Level 4+. Raw material dependencies center on nickel-chromium-molybdenum alloys, ceramic composite precursors, and rare earth elements for electronic warfare systems. Tariff exposure runs through EU carbon border adjustment mechanisms targeting non-EU smelters. Distribution runs through NATO Support and Procurement Agency consolidated frameworks, replacing bilateral national contracts with multilateral competitive processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over specialized welding technician pipelines and captive armor-grade steel supply determines contract win rates against competitors dependent on spot-market inputs.
For Market Incumbents: Deploy backward integration into Polish and Romanian foundry infrastructure to secure STANAG 4569 Level 4+ material supply. Rheinmetall AG and PGZ anchor production partnerships that lock out competitors facing 18-24 month certification delays. Capacity addition in the Vistula River industrial corridor creates geographic moats against Asian contractors lacking EU manufacturing footprints. Certification investment in NATO interoperability standards compresses rival qualification timelines. For New Entrants and Emerging Players: Launch via Czechia's underdeveloped cyber defense procurement channels before formal tender frameworks mature. NATO-cleared security clearances create first-mover advantages in critical infrastructure protection contracts. Baltic states' joint ammunition stockpiling initiatives represent the most penetrable segment for regional storage and rapid distribution hub establishment. Direct engagement with Estonian, Latvian, and Lithuanian defense procurement offices bypasses incumbent relationship lock-in. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized autonomy software houses with drone swarm coordination capabilities in Poland and Romania. Long-term viability hinges on AI-enabled predictive maintenance convergence with existing armored vehicle fleets. The signal to watch is Polish Ministry of National Defence tender weighting for environmental criteria, which advantages EU-based supply chains and disadvantages North American competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | Polish PGZ partnerships with Rheinmetall AG accelerate Leopard 2PL production scaling. |
| Technology Licensing Agreement | RTX Corporation air defense portfolios transfer NATO interoperability protocols to Romanian forces. |
| Backward Integration | Captive control over high-hardness steel supply eliminates German and Swedish mill dependency. |
| Regional Distribution Hub | Tallinn-based ammunition storage facilities gain preferential status under Baltic joint procurement. |
| Certification Investment | STANAG 4569 Level 4+ testing at NATO facilities compresses rival product development cycles. |
Research Methodology
Defense industry databases, NATO procurement registries, and EU European Defence Fund disbursement records formed the secondary backbone for this analysis. Primary interviews with Polish Ministry of National Defence procurement officers, Romanian military attachés, Baltic defense ministry planners, NATO Support and Procurement Agency contracting specialists, and PGZ manufacturing executives validated quantitative estimates. Bottom-up and top-down triangulation reconciled platform-level production data with national defense budget appropriations.
Bottom-up modeling aggregated tracked vehicle unit forecasts, air defense system procurement pipelines, and cyber defense contract awards across Poland, Romania, Czechia, and the Baltic states. Segmentation dimensions included product type, end-user institution, technology maturity, and application mission profile. CAGRs were derived from defense ministry modernization program timelines and NATO interoperability mandate compliance deadlines. Industry-specific inputs incorporated STANAG certification backlog durations and EU Green Deal carbon accounting implementation schedules.
Defense budget reallocation, STANAG standardization mandate delays, and EU Green Deal procurement amendment revisions are the dominant revision risks to these projections. Forecasts reflect documented assumptions regarding NATO joint framework adoption rates and national platform replacement urgency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Taiwan Defense Market
Military Vehicles
Global Offshore Patrol Vessel (OPV) Market
Military Vehicles
Military Ground Robots Market
Military Vehicles
Military Unmanned Ground Vehicle Market
Military Vehicles
Military Land Vehicles Market
Military Vehicles
Main Battle Tank Market
Military Vehicles
Destroyers Market
Military Vehicles
India Combat Vehicle Systems Market
Military Vehicles
Combat Support Vehicle Market
Military Vehicles
Russia Defense Market
Military Vehicles
Military Amphibious Vehicle Market
Military Vehicles
Military Vehicle & Aircraft Protection Systems Market
Military Vehicles
Middle East Military Vehicles Market
Military Vehicles
Riot Control Vehicle Market
Military Vehicles
Amphibious Land Craft Market
Military Vehicles
Iran Defense Market