
 Taiwan Defense Market | 2026-2036
Taiwan Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Defense Market Insights
The gap between indigenous development programs and imported systems is repositioning procurement budgets toward dual-source strategies. National Chung-Shan Institute of Science and Technology leverages domestic missile expertise to anchor Taiwan's asymmetric deterrent posture. Aerospace Industrial Development Corporation sustains airframe manufacturing capacity despite technology transfer constraints. CSBC Corporation Taiwan dominates naval construction with submarine and surface combatant programs.
Taiwan defense encompasses military preparedness spanning weapons platforms, command infrastructure, and operational support services designed to deter aggression and maintain territorial integrity. The ecosystem integrates precision-guided munitions with layered surveillance architectures, requiring semiconductor-grade components and hardened communications protocols. Missiles and drones within Defense Technology command disproportionate investment given their centrality to anti-access strategies, while naval vessels under Equipment Type absorb sustained capital allocation for submarine and frigate modernization. Maintenance and training within Service Type represent expanding margin pools as platform complexity rises and operational tempo intensifies.
Taiwan's Ministry of National Defense procurement operates under Legislative Yuan oversight with mandatory indigenous content thresholds shaping vendor eligibility. The National Chung-Shan Institute of Science and Technology functions as both prime contractor and technology gatekeeper, blurring lines between regulator and supplier in ways that constrain foreign direct participation. Stakeholders must track how cross-strait tension fluctuations alter US Foreign Military Sale pacing and whether Taipei relaxes technology transfer restrictions to accelerate capability fielding.
Market Dynamics
Cross-strait military tension is compressing procurement cycles and forcing Taiwan's Ministry of National Defense toward accelerated asymmetric capability fielding, with indigenous missile production absorbing disproportionate budget allocation.
Growth Catalysts
- Indigenous Production Mandates:Legislative Yuan content thresholds compel domestic manufacturing of critical subsystems, expanding National Chung-Shan Institute of Science and Technology contract flows.
- US Foreign Military Sale Pipeline:Congressional notification acceleration for Harpoon coastal defense and Patriot missile refreshers sustains platform modernization momentum.
- Drone Swarm Proliferation:Aerospace Industrial Development Corporation ramped rotary-wing unmanned output to saturate littoral zones with low-cost attritable assets.
Market Restraints
- Semiconductor Component Bottlenecks:TSMC advanced node allocation constraints throttle guidance system production for precision munitions.
- Submarine Construction Delays:CSBC Corporation Taiwan faces welding technician shortages and foreign propulsion technology transfer blocks.
- Maintenance Infrastructure Gaps:Aging F-16 and Mirage fleets outstrip Air Force Logistics Command depot capacity, degrading mission-capable rates.
Strategic Opportunities
- Penghu Archipelago Layered Defense:Island garrison modernization opens demand for short-range air defense and coastal surveillance integration.
- AI-Enabled Targeting Fusion:Machine vision convergence with synthetic aperture radar is compressing kill-chain latency for maritime strike.
- Dual-Use Civil-Military Drone Channels:Commercial unmanned aerial system manufacturers pivot into defense supply chains under relaxed technology transfer protocols.
Industry Challenges
- Systems Integration Complexity:Legacy command-and-control architectures resist interoperability with new indigenous platforms, forcing expensive middleware development.
- Cleared Workforce Scarcity:Security clearance processing bottlenecks constrain engineering talent pipelines at classified facilities in Taichung and Kaohsiung.
- Test Range Limitations:Restricted airspace and maritime exercise zones compress validation cycles for beyond-visual-range missile systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Defense Market |
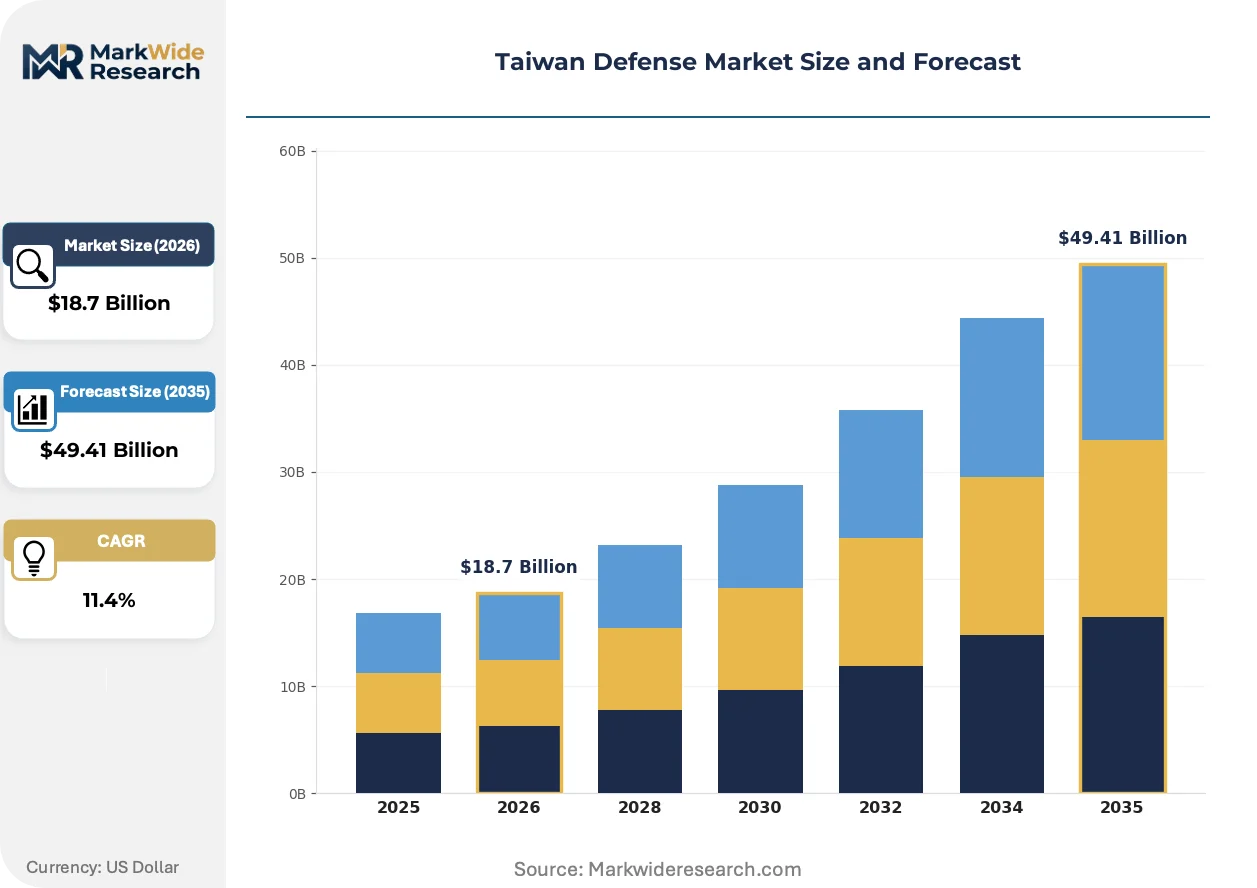
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Defense Technology: Missiles, Drones, Surveillance Systems, Cybersecurity Solutions Equipment Type: Aircraft, Naval Vessels, Ground Vehicles, Artillery End User: Military, Government Agencies, Defense Contractors, Research Institutions Service Type: Maintenance, Training, Logistics, Consulting |
| Companies Covered | National Chung-Shan Institute of Science and Technology, Aerospace Industrial Development Corporation, CSBC Corporation Taiwan, Lockheed Martin Corporation, RTX Corporation, General Dynamics Corporation, Northrop Grumman Corporation, The Boeing Company, Thunder Tiger Technology Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Defense Market Trends and Innovations
Autonomous systems and hardened communications are displacing crewed platforms in procurement priority, while semiconductor supply security reshapes subsystem sourcing strategies across all major programs.
Hypersonic interceptor development is electrifying air defense architecture planning, with National Chung-Shan Institute of Science and Technology prioritizing boost-phase engagement capabilities. The Air Force is adopting these systems faster than surface fleet modernization timelines permit. This acceleration is compressing traditional layered defense procurement into integrated multi-domain programs.
Taiwan's Ministry of National Defense revised indigenous content regulations now mandate 55% domestic value for critical munitions, tightening vendor eligibility and redirecting foreign partnership terms. Industrial consequence includes forced technology localization for guidance electronics and propulsion subsystems. Missile and drone segments absorb the most compliance cost, with primes restructuring subcontractor tiers to maintain program access.
Consolidated platform contracting is displacing discrete system purchases, with the Navy bundling ship construction with decade-long integrated logistics support. CSBC Corporation Taiwan and domestic maintenance providers capture elongated revenue streams through availability-based service structures. This shift concentrates most visibly in the submarine program, where construction and through-life support are now indivisible contract elements.
Taiwan Defense Market Segmentation
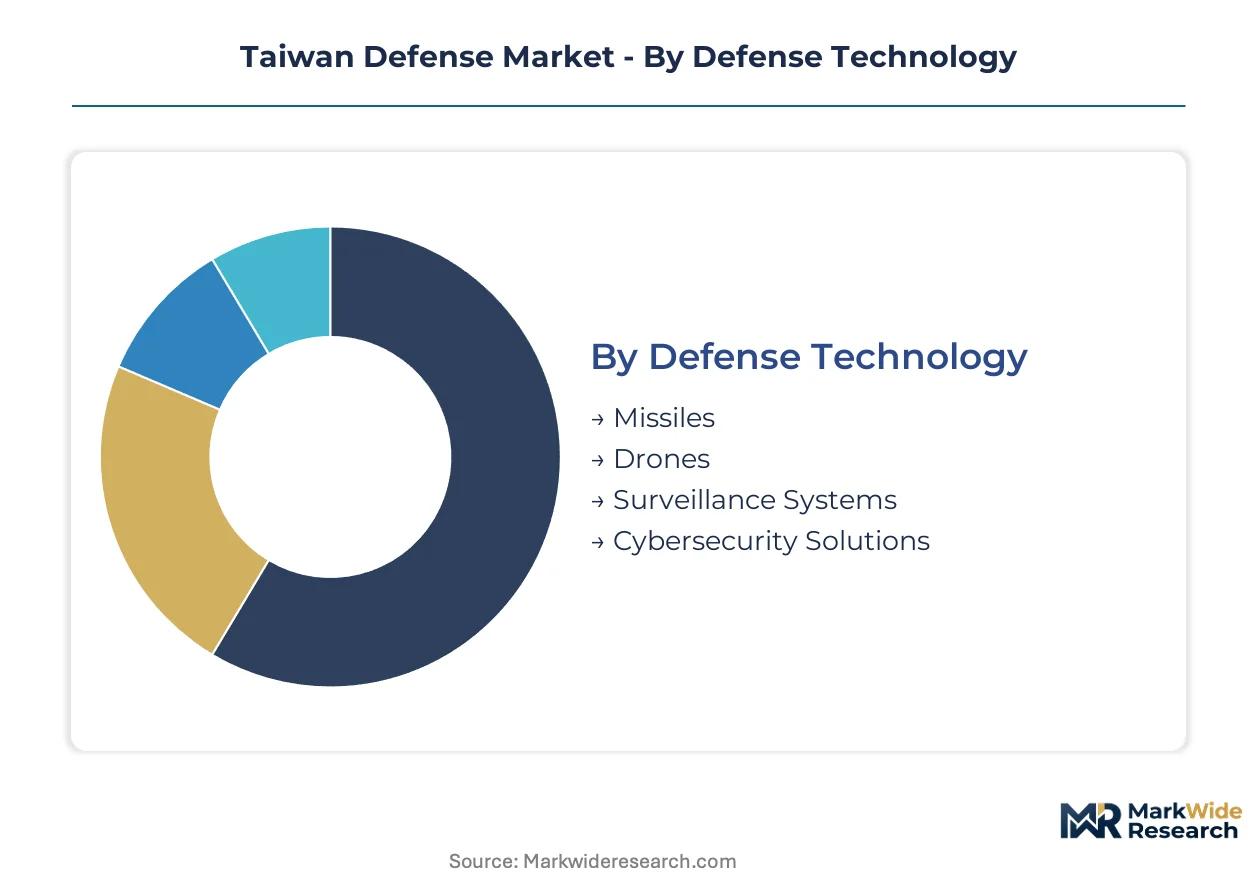
Taiwan's defense procurement channels resources through four distinct segmentation lenses that reflect asymmetric warfare priorities. Each category reveals how budget allocation shifts between indigenous production mandates and imported platform integration. Understanding these segment boundaries clarifies where National Chung-Shan Institute of Science and Technology authority intersects with foreign supplier access.
Defense Technology:
Standardization dominates missile and drone platforms where NCSIST controls design specifications, while surveillance and cybersecurity segments permit greater vendor customization flexibility.
- Missiles:Precision-guided munitions encompass anti-ship, air defense, and cruise missile variants with domestic propulsion systems. Demand concentrates in coastal defense batteries along the Taiwan Strait, driven by Legislative Yuan mandates for 55% indigenous content in critical munitions procurement.
- Drones:Rotary-wing and fixed-wing unmanned systems span reconnaissance, loitering munition, and electronic warfare configurations. Aerospace Industrial Development Corporation manufacturing lines in Taichung absorb expanding budgets as the Air Force prioritizes attritable swarm tactics for littoral saturation.
- Surveillance Systems:Synthetic aperture radar and electro-optical/infrared sensor suites integrate with command networks.
- Cybersecurity Solutions:Military-grade encryption and intrusion detection systems protect classified communications infrastructure.
Most installed capacity flows through Missiles. Expansion is steepest in Drones.
Equipment Type:
Volume concentration tilts toward naval construction where CSBC Corporation Taiwan maintains production dominance, while aircraft procurement follows Foreign Military Sale pacing with elongated delivery timelines.
- Naval Vessels:Submarine construction and surface combatant programs absorb the largest capital allocation within indigenous shipbuilding. Kaohsiung shipyards face welding technician shortages even as the Navy bundles decade-long integrated logistics support with new hull orders.
- Aircraft:Fighter modernization centers on F-16V upgrade programs and indigenous trainer development. Air Force Logistics Command depot capacity constraints in Taoyuan degrade mission-capable rates for aging Mirage and F-16 fleets.
- Ground Vehicles:Armored personnel carriers and tactical transport platforms support island defense mobilization.
- Artillery:Long-range rocket and conventional tube artillery systems provide area denial coverage.
Naval Vessels command the heaviest capital deployment. Aircraft procurement timelines stretch the longest.
End User:
Customer concentration clusters at the military apex with trickle-down effects to contractor tiers, while research institutions operate at smaller scale with higher specification variance.
- Military:Army, Navy, and Air Force commands drive platform requirements through Ministry of National Defense budget cycles. Cross-strait tension fluctuations compress procurement cycles and accelerate asymmetric capability fielding across all service branches.
- Defense Contractors:Prime and subcontractor networks execute NCSIST-directed manufacturing with mandated domestic content thresholds. CSBC Corporation Taiwan and Aerospace Industrial Development Corporation anchor this tier with classified facility operations in Taichung and Kaohsiung.
- Government Agencies:Coast Guard Administration and national security organs acquire dual-use surveillance assets.
- Research Institutions:Academic and state laboratory partners support technology validation and workforce development.
Military budgets dominate procurement volume. Defense Contractors capture the widest subcontractor spread.
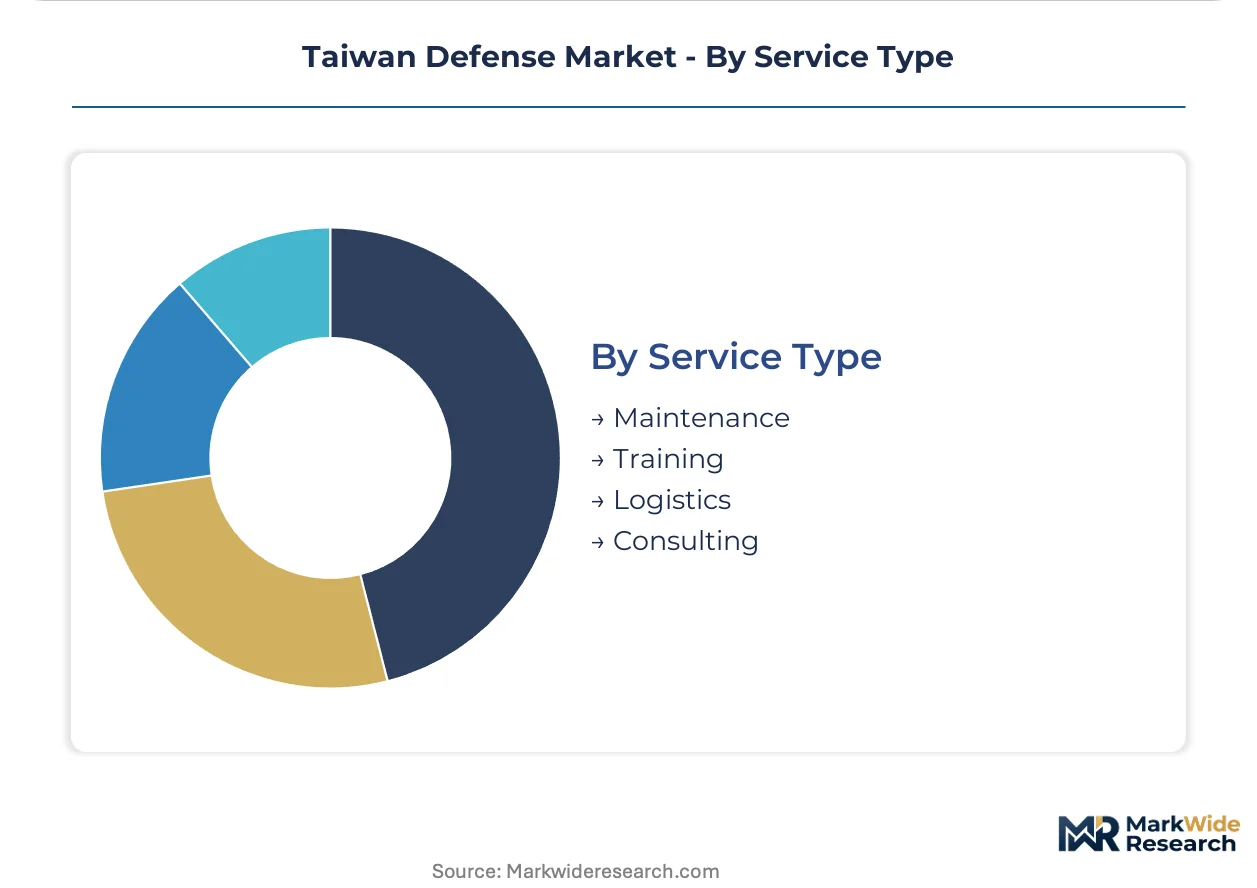
Service Type:
Margin structures diverge sharply between maintenance contracts with predictable revenue streams and training services with higher variability but lower capital intensity.
- Maintenance:Platform availability-based service structures now bundle with original construction contracts, particularly for submarine programs. Aging fleet complexity drives expanding margin pools as Air Force Logistics Command depot capacity strains against F-16 and Mirage sustainment demands.
- Training:Flight simulator networks and tactical exercise programs scale with operational tempo intensification. Security clearance processing bottlenecks constrain engineering talent pipelines at classified facilities.
- Logistics:Supply chain management and spare parts distribution support forward-deployed units.
- Consulting:Systems integration advisory addresses legacy command-and-control architecture interoperability gaps.
Maintenance contracts lock in the longest revenue visibility. Training scales fastest with platform fielding acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's defense industrial workforce clusters around Taichung and Kaohsiung, where classified facilities concentrate missile, drone, and naval construction expertise. These talent pools anchor indigenous production mandates under Legislative Yuan oversight.
United States
The US Foreign Military Sale pipeline sustains Taiwan's platform modernization through Congressional notifications for coastal defense and missile refreshers. The Department of Defense coordinates these transfers under the Taiwan Relations Act framework. Defense contractors in Texas and Arizona maintain production lines for fighter upgrades and precision munitions bound for Taipei.
Japan
Tokyo's defense export guidelines are gradually relaxing to permit component sales for Taiwan's submarine and maritime patrol programs. METI oversees dual-use technology classifications affecting semiconductor-grade guidance system exports. Industrial partnerships in the Kansai region are exploring sonar and propulsion subsystem collaboration with Kaohsiung shipyards.
South Korea
Seoul's defense procurement agency faces political pressure to expand submarine battery and ship component sales to Taiwan. The MFDS regulates military-grade lithium-ion cell exports under tightened end-use monitoring. Busan-Ulsan shipbuilding clusters are positioning for maintenance support contracts on Taiwan's indigenous submarine fleet.
Australia
Canberra's AUKUS alignment is redirecting some defense industrial attention toward Taiwan-compatible undersea warfare technologies. The Department of Defence manages technology release protocols affecting sonar and combat system integration. Queensland-based firms are exploring training and logistics support arrangements for Taiwan's expanding submarine force.
United Kingdom
London's submarine propulsion expertise remains central to Taiwan's indigenous boat program despite formal technology transfer blocks. The Ministry of Defence controls export licensing for nuclear-related maritime technologies with conventional applications. Scottish shipyard engineering talent is consulting on welding and pressure hull fabrication challenges at CSBC Corporation Taiwan facilities.
Taiwan Defense Market Competitive Landscape
Capital-heavy state-owned producers compete with asset-light foreign prime contractors for platform integration roles, creating a bifurcated procurement structure. National Chung-Shan Institute of Science and Technology dominates missile and drone segments through indigenous content mandates, while US aerospace and defense majors capture high-value Foreign Military Sale contracts. Strategic archetypes separate into state-directed primes, foreign system integrators, and specialized subsystem vendors. Competitive positioning hinges on technology transfer negotiations and long-term integrated logistics support bundling rather than pure manufacturing scale.
Within the state-directed tier, National Chung-Shan Institute of Science and Technology exemplifies the technology gatekeeper archetype, controlling design specifications and vendor eligibility. CSBC Corporation Taiwan anchors naval construction with submarine and surface combatant programs absorbing sustained capital allocation. Among foreign contractors, Lockheed Martin Corporation and RTX Corporation occupy positions as primary Foreign Military Sale channel partners, their access contingent on Congressional notification pacing and cross-strait tension calibration.
| Leading Market Players |
|---|
| National Chung-Shan Institute of Science and Technology |
| Aerospace Industrial Development Corporation |
| CSBC Corporation Taiwan |
| Lockheed Martin Corporation |
| RTX Corporation |
| General Dynamics Corporation |
| Northrop Grumman Corporation |
| The Boeing Company |
| Thunder Tiger Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Semiconductor-grade guidance electronics anchor cost structures from TSMC advanced node allocation through precision munitions pricing tiers, with Legislative Yuan indigenous content mandates compressing margins on foreign-sourced subsystems while elevating domestically manufactured alternatives.
Pricing Analysis
Bundled availability-based service contracts now dominate submarine and naval construction, displacing discrete platform purchases with decade-long integrated logistics support commitments. Three-tier pricing structure across premium, standard, and economy levels separates Foreign Military Sale channels with Congressional notification pacing from accelerated indigenous production with relaxed technology transfer terms. Cost compression in missile guidance systems intensifies because TSMC capacity constraints throttle high-end component supply. Defense Contractors exhibit highest price sensitivity due to mandated domestic content thresholds, while Military end-users absorb premium pricing for asymmetric capability urgency.
Supply Chain Analysis
Legislative Yuan 55% domestic value mandates for critical munitions are reshaping sourcing from foreign prime dependency toward National Chung-Shan Institute of Science and Technology-controlled vendor tiers. Supply concentration centers on Taiwan for semiconductor-grade components, the United States for Foreign Military Sale platforms, and Japan for submarine propulsion subsystem consultation. Raw material dependencies span advanced lithography nodes, military-grade lithium-ion cells, and pressure hull steel alloys. Single-source vulnerability runs through TSMC advanced node allocation for precision guidance electronics. Distribution runs through Ministry of National Defense procurement cycles with Legislative Yuan oversight and mandatory indigenous content verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan Defense Market reads as a late-cycle quality story where procurement acceleration toward asymmetric platforms favors suppliers with cleared facility access and domestic manufacturing certification.
For Market Incumbents: Deepen backward integration into semiconductor-grade guidance electronics to offset TSMC allocation constraints threatening precision munitions output. Expand classified facility capacity in Taichung and Kaohsiung to capture maintenance contract bundling with original construction. Legislative Yuan content threshold tightening presents the primary regulatory threat requiring certification investment leverage. For New Entrants and Emerging Players: Launch via dual-use civil-military drone channel partnerships with relaxed technology transfer protocols opening access to Aerospace Industrial Development Corporation supplier tiers. Penetrable white space concentrates in Penghu Archipelago layered defense integration and AI-enabled targeting fusion for maritime strike compression. Coast Guard Administration dual-use surveillance procurement offers lowest barrier to initial contract capture. For Investors and Strategic Acquirers: Consolidation pressure builds where cleared workforce scarcity constrains engineering talent pipelines at classified facilities. Long-term viability favors asset-light subsystem vendors with semiconductor supply security and domestic content compliance capability. Acquisition target archetype: specialized guidance electronics manufacturers with existing National Chung-Shan Institute of Science and Technology certification. Signal to watch: Legislative Yuan relaxation of technology transfer restrictions accelerating foreign partnership terms.| Strategic Initiative | Industry Significance |
|---|---|
| Indigenous Content Compliance Investment | Legislative Yuan 55% thresholds mandate vendor restructuring to maintain program access. |
| Classified Facility Capacity Expansion | Taichung and Kaohsiung cleared workforce pipelines constrain missile and drone output scaling. |
| Integrated Logistics Support Bundling | CSBC Corporation Taiwan captures elongated revenue streams through availability-based submarine contracts. |
| Dual-Use Drone Channel Pivot | Commercial unmanned aerial system manufacturers enter defense supply chains under relaxed protocols. |
| Semiconductor Supply Security Partnership | TSMC advanced node allocation agreements anchor precision munitions production continuity. |
Research Methodology
Direct dialogue with Ministry of National Defense procurement officers, National Chung-Shan Institute of Science and Technology program managers, CSBC Corporation Taiwan engineering leads, and Foreign Military Sale channel representatives grounded qualitative assessment. Secondary validation drew from Legislative Yuan defense budget disclosures, US Congressional notification records, US Department of Defense security cooperation reports, and Taiwan Ministry of National Defense capability development white papers. Bottom-up platform-level procurement tracking triangulated against top-down budget allocation analysis.
Bottom-up modeling segmented procurement flows across Defense Technology, Equipment Type, End User, and Service Type dimensions, with additional granularity on indigenous versus imported sourcing splits. CAGRs derived from historical budget execution patterns and announced program acceleration timelines across the projection horizon. Forecast inputs incorporated cross-strait tension calibration effects on Foreign Military Sale pacing and Legislative Yuan indigenous content threshold enforcement intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cross-strait escalation scenarios or US Congressional notification delays. Assumptions reflect current Legislative Yuan mandate enforcement and TSMC capacity allocation prioritization for defense applications. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Robotic Combat Vehicle (RCV) Market
Military Vehicles
Middle East Military Vehicles Market
Military Vehicles
Eastern Europe Defense Market
Military Vehicles
Main Battle Tank Market
Military Vehicles
Colombia Defense Market
Military Vehicles
Military Ground Robots Market
Military Vehicles
India Combat Vehicle Systems Market
Military Vehicles
Global Military Vehicle Electrification Market
Military Vehicles
Indonesia Defense Market
Military Vehicles
Iran Defense Market
Military Vehicles
Infantry Fighting Vehicle (IFV) Market
Military Vehicles
Global Offshore Patrol Vessel (OPV) Market
Military Vehicles
Military Ground Vehicle Actuators Market
Military Vehicles
Southeast Asia Defense Market
Military Vehicles
Military Land Vehicles Market
Military Vehicles
Military Amphibious Vehicle Market