
 Southeast Asia Defense Market | 2026-2036
Southeast Asia Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Defense Market Analytics
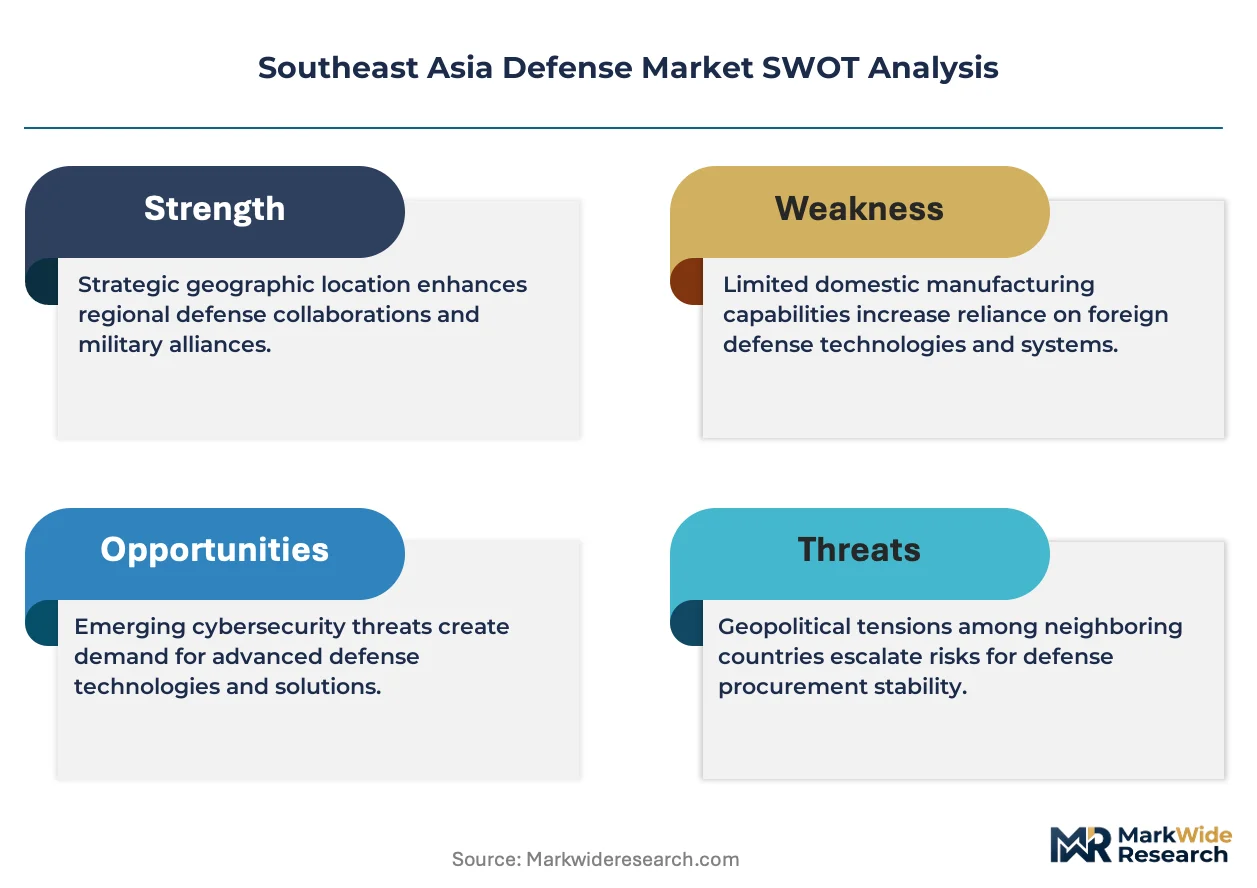
Naval modernization is pivoting Southeast Asian defense procurement toward submarine and frigate acquisitions. Lockheed Martin Corporation leverages integrated combat systems to anchor naval upgrade programs across multiple regional fleets. Thales Group sustains electronic warfare and sonar technology leadership that differentiates its offerings in undersea domain awareness. Singapore Technologies Engineering Ltd dominates regional maintenance, repair, and overhaul infrastructure through its captive shipyard network.
Southeast Asia defense encompasses military capability procurement spanning platforms, systems, and services designed for territorial defense, maritime security, and asymmetric deterrence, typically requiring interoperability with ASEAN partners and allied forces using NATO-standard or hybrid communication protocols. Aircraft procurement concentrates margin pools in multirole fighter programs where lifecycle support exceeds platform acquisition costs, while C4ISR systems represent the fastest-expanding technology segment as networked command requirements displace siloed national systems. Ground Vehicles remain the most mature product category with replacement cycles elongated by fiscal constraints across smaller ASEAN militaries.
Indonesia's defense procurement reforms and Vietnam's military modernization directives shape contracting transparency and offset requirements for foreign suppliers entering these markets. The country's national pharmaceutical regulator equivalent in defense—defense ministry acquisition boards—imposes local content thresholds that redirect supply chain configuration toward joint ventures with domestic partners. Stakeholders must monitor how Philippines naval base upgrades and Malaysia's littoral combat ship program revisions redistribute platform demand across the archipelagic theater.
Market Dynamics
Naval modernization across Southeast Asian fleets is compressing procurement cycles for undersea and surface combatants, while Indonesia's defense procurement reforms impose local content thresholds that restructure foreign supplier entry strategies.
Growth Catalysts
- Maritime Territorial Tensions:Persistent disputes in the South China Sea accelerate submarine and frigate acquisitions by Vietnam and the Philippines.
- ASEAN Interoperability Mandates:Standardized communication protocols for combined exercises drive C4ISR system upgrades across member states.
- Electronic Warfare Modernization:Sonar and signals intelligence investments expand as regional navies prioritize undersea domain awareness.
Market Restraints
- Domestic Content Requirements:Indonesia's defense ministry acquisition boards mandate joint ventures that fragment supplier economics.
- Extended Platform Lifecycles:Fiscal constraints across smaller ASEAN militaries elongate replacement cycles for armored vehicles and rotary-wing assets.
- Technology Transfer Limitations:Advanced combat system exporters restrict core subsystem access, limiting indigenous capability development.
Strategic Opportunities
- Philippines Naval Base Upgrades:Subic Bay and Oyster Bay infrastructure investments create maintenance and logistics service demand.
- Malaysia Littoral Combat Ship Revisions:Program restructuring opens platform slots for alternative hull designs and combat system integrators.
- Unmanned Maritime Systems:Surface and underwater drone procurement represents underpenetrated demand across coastal surveillance missions.
Industry Challenges
- Skilled Workforce Scarcity:Naval architecture and systems integration expertise concentrates in Singapore, creating recruitment bottlenecks for emerging programs.
- Legacy System Integration:NATO-standard C4ISR architectures must interface with hybrid national networks, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Defense Market |
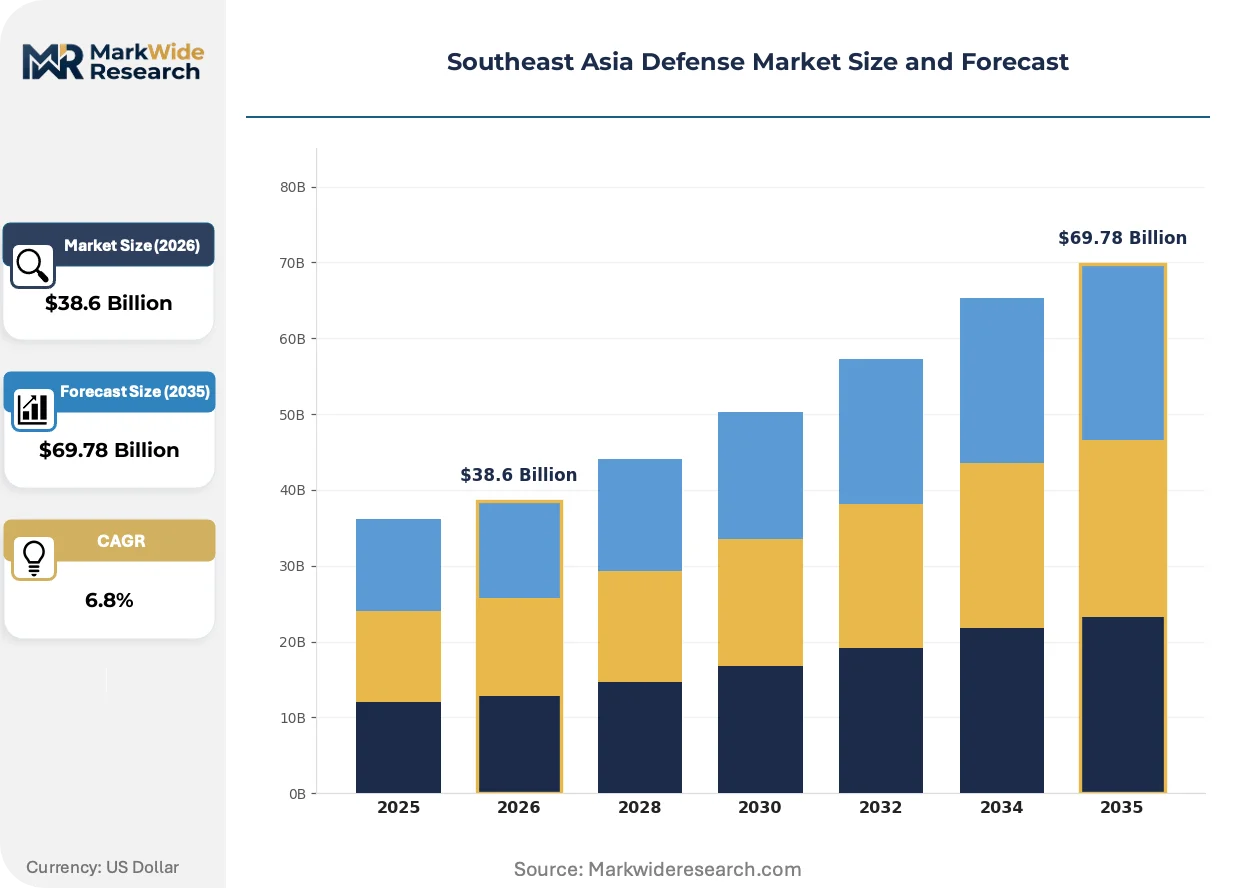
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aircraft, Naval Vessels, Missiles, Ground Vehicles Technology: C4ISR, Cybersecurity, Robotics, Drones End User: Military, Government, Private Contractors, Security Forces Service Type: Maintenance, Training, Logistics, Consulting |
| Companies Covered | The Boeing Company, Thales Group, Lockheed Martin Corporation, Rostec, Elbit Systems Ltd, Singapore Technologies Engineering Ltd, Leonardo S.p.A., Saab AB, Airbus SE, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Defense Market Evolving Landscape
Integrated combat systems and networked command architectures are displacing platform-centric procurement models across Southeast Asian defense ministries. Three developments are compressing technology adoption timelines and reshaping supplier relationships.
Hybrid electric propulsion for submarines and surface combatants is electrifying naval architecture requirements. Thai and Indonesian navies are specifying integrated power systems for new frigate classes. This technology is electrifying traditional mechanical-drive supply chains and compressing engine room footprints.
Indonesia's defense procurement transparency framework is mandating open-bidding disclosures for contracts exceeding defined thresholds. Foreign suppliers must now document offset commitments and technology transfer provisions in public filings. Malaysian and Vietnamese defense ministries are observing these disclosure standards for potential adoption.
Lifecycle service contracts are unbundling from platform purchases as Southeast Asian navies seek predictable sustainment costs. Singapore's shipyard infrastructure anchors regional maintenance capacity, while Philippine and Indonesian operators negotiate performance-based logistics arrangements. This model concentrates margin capture in established MRO networks.
Southeast Asia Defense Market Segmentation
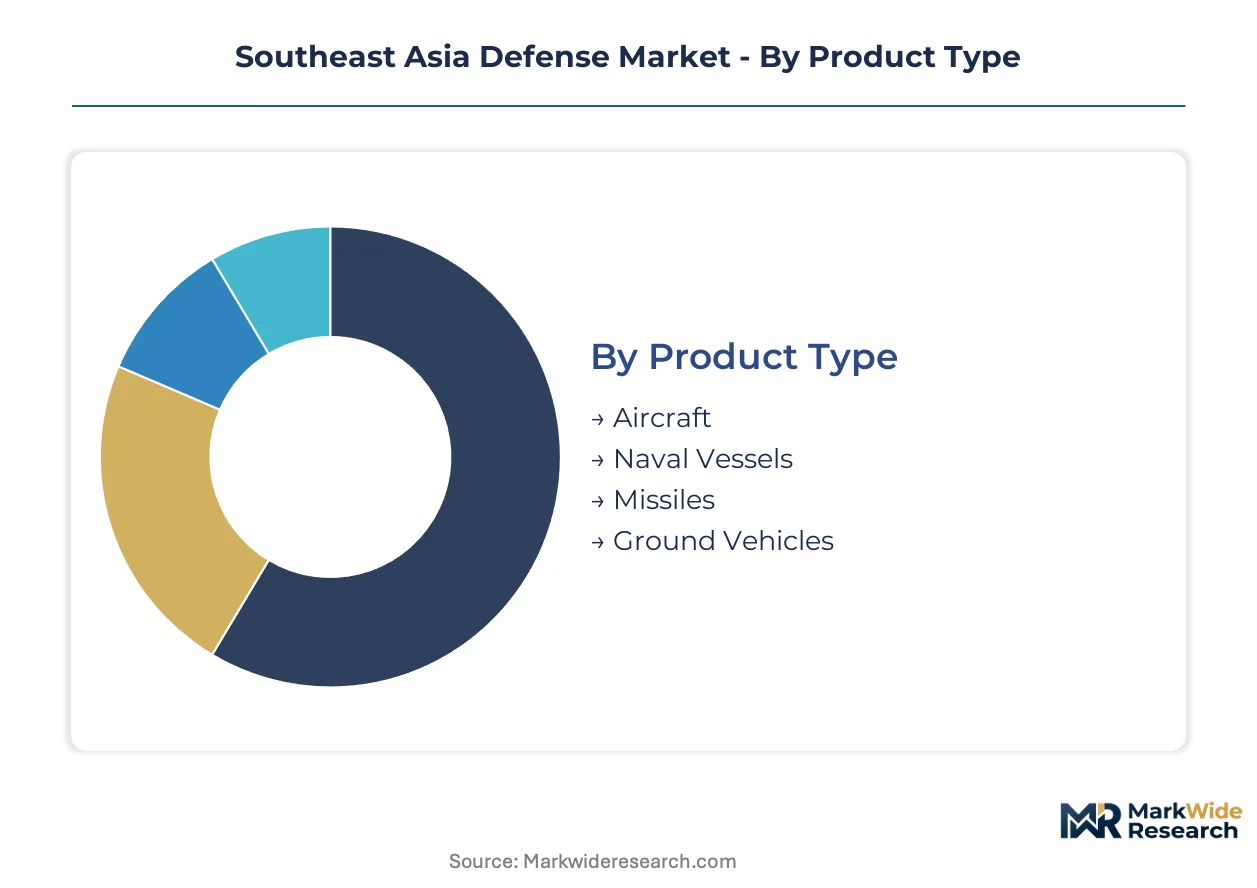
Defense procurement across Southeast Asia fragments along capability tiers and operational domains, with platform acquisition cycles diverging sharply from technology refresh timelines. Understanding these splits reveals where budget authority concentrates and which supplier relationships prove sticky over multi-decade programs.
Product Type:
Upgrade cycles vary dramatically across platform categories, with maritime assets commanding accelerated replacement schedules while land systems face extended service lives.
- Naval Vessels:Frigates and submarines integrate hybrid electric propulsion and integrated combat systems. Vietnam and Indonesia compress procurement timelines for undersea domain awareness capabilities as South China Sea patrol demands intensify.
- Aircraft:Multirole fighter programs absorb lifecycle support budgets exceeding platform acquisition costs. Singapore and Thailand prioritize NATO-interoperable avionics for coalition exercise requirements.
- Missiles:Coastal defense and anti-ship systems concentrate procurement authority in Vietnam and Philippines maritime commands.
- Ground Vehicles:Armored personnel carriers and main battle tanks face elongated replacement cycles across smaller ASEAN militaries constrained by fiscal limitations.
Naval Vessels sits at the top of the volume ranking, with Aircraft climbing the fastest as airframe obsolescence drives multirole replacement programs.
Technology:
Capability gaps between legacy national networks and coalition-interoperable standards create tiered investment patterns across defense ministries.
- C4ISR:Networked command architectures displace siloed national systems as ASEAN interoperability mandates standardize communication protocols. Malaysia and Indonesia prioritize battlefield management systems linking maritime and air domains.
- Cybersecurity:Military-grade network defense contracts expand as critical infrastructure protection requirements harden. Singapore's digital defense doctrine shapes regional procurement specifications.
- Drones:Unmanned maritime surveillance platforms represent underpenetrated demand across coastal patrol missions in Philippines and Indonesia.
- Robotics:Explosive ordnance disposal and logistics automation systems gain traction in urban warfare training environments.
C4ISR captures the dominant share of technology budgets, while Cybersecurity expands most quickly as attack surface concerns mount across connected weapons systems.
End User:
Contracting authority and offset negotiation leverage diverge substantially across institutional customer types.
- Military:Defense ministry acquisition boards in Indonesia and Vietnam impose local content thresholds and technology transfer requirements that restructure foreign supplier economics.
- Government:Coast guard and maritime law enforcement agencies in Philippines and Malaysia pursue dual-use platforms with surveillance and interdiction capabilities.
- Security Forces:Paramilitary units concentrate demand for tactical communications and mobility platforms in internal security theaters.
- Private Contractors:Logistics and training service providers capture performance-based sustainment contracts as navies unbundle lifecycle services from platform purchases.
Military commands dominate committed procurement volumes, with Government agencies gaining share fastest as maritime constabulary functions expand.
Service Type:
Sustainment economics increasingly separate from platform acquisition, with long-term service contracts commanding separate budget lines and vendor selection criteria.
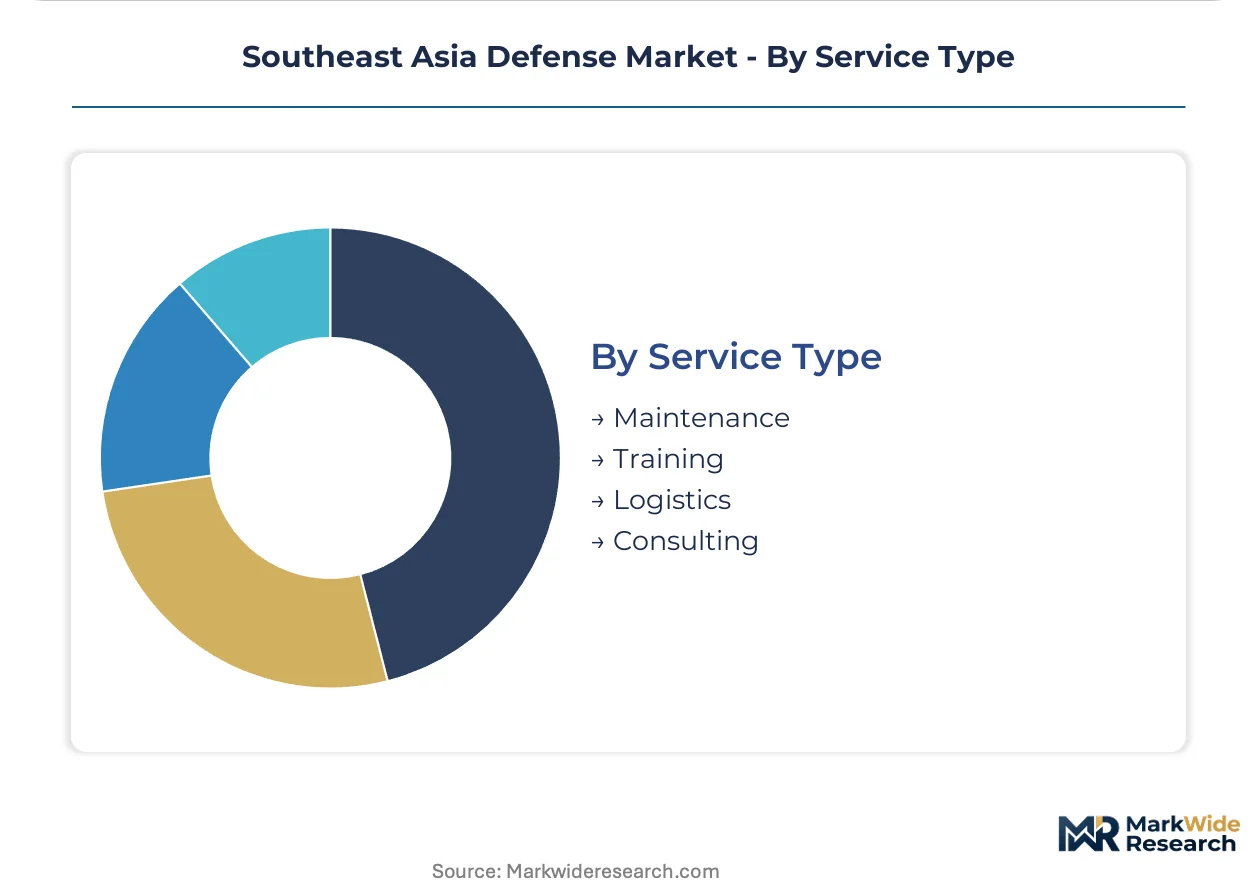
- Maintenance:Performance-based logistics arrangements concentrate margin capture in Singapore's established shipyard infrastructure and emerging Indonesian facilities.
- Training:Simulator-based instruction and live-fire exercise support expand as crew qualification requirements outpace indigenous capacity.
- Logistics:Spare parts inventory management and forward positioning agreements reduce operational readiness gaps across dispersed archipelagic deployments.
- Consulting:Defense procurement reform advisory and offset compliance documentation support foreign suppliers navigating Indonesia's transparency framework.
Maintenance commands the largest service expenditure, with Training showing the steepest expansion trajectory as platform complexity outstrips indigenous technical education pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement across Southeast Asia fragments along regulatory-arbitrage lines, with Indonesia's transparency mandates and Vietnam's modernization directives creating divergent cost-of-compliance environments that reshape supplier entry strategies and joint venture requirements.
Indonesia
Naval modernization and submarine acquisitions drive procurement volume as the defense ministry acquisition boards enforce local content thresholds above defined contract values. The country's defense procurement transparency framework mandates open-bidding disclosures and documented offset commitments. Jakarta anchors regional shipbuilding capacity through state-owned yards negotiating technology transfer provisions with foreign combat system integrators.
Vietnam
Maritime surveillance capabilities and coastal defense systems concentrate budget authority as South China Sea patrol demands intensify. Military modernization directives from Hanoi reshape contracting terms and indigenous capability development timelines. The Cam Ranh naval complex and Haiphong shipbuilding zone host submarine maintenance infrastructure and frigate construction programs.
Singapore
Multirole fighter programs and NATO-interoperable C4ISR systems absorb disproportionate technology budgets relative to fleet size. The country's defense procurement specifications emphasize coalition exercise compatibility and networked command architectures. Changi naval base and Tuas shipyard infrastructure anchor regional maintenance, repair, and overhaul capacity serving neighboring fleets.
Philippines
Naval base upgrades at Subic Bay and Oyster Bay create maintenance and logistics service demand alongside frigate acquisition programs. Coast guard and maritime law enforcement agencies pursue dual-use platforms with surveillance and interdiction capabilities. The Cavite naval shipyard and Subic freeport zone concentrate infrastructure investment and foreign contractor presence.
Malaysia
Littoral combat ship program revisions open platform slots for alternative hull designs and combat system integrators after restructuring delays. The country's defense ministry acquisition boards balance fiscal constraints with fleet modernization requirements. The Boustead Naval Shipyard in Lumut and Kota Kinabalu naval base anchor west and east coast maritime deployment infrastructure.
Southeast Asia Defense Market Competitive Landscape
Strategic partnerships and joint venture formations dominate the current landscape as foreign suppliers navigate domestic content requirements. The vendor base concentrates around integrated combat system providers, electronic warfare specialists, and established maintenance networks. Three archetypes define competitive positioning: Western prime contractors anchoring platform sales, European subsystem specialists capturing sensor and electronics margins, and Singapore-based engineering groups controlling regional sustainment infrastructure. Technology licensing agreements and local production partnerships represent the dominant competitive moves, followed by performance-based logistics contract unbundling from platform purchases.
Among Western prime contractors, Lockheed Martin Corporation and Thales Group exemplify contrasting approaches to regional market penetration. Lockheed Martin occupies a position as an integrated combat system anchor for naval upgrade programs, while Thales represents the electronic warfare and sonar technology specialist archetype. Singapore Technologies Engineering Ltd anchors the regional maintenance infrastructure tier through its captive shipyard network. These three companies illustrate how competitive positioning separates platform-centric suppliers from subsystem specialists and sustainment operators across Southeast Asian procurement cycles.
| Leading Market Players |
|---|
| The Boeing Company |
| Thales Group |
| Lockheed Martin Corporation |
| Rostec |
| Elbit Systems Ltd |
| Singapore Technologies Engineering Ltd |
| Leonardo S.p.A. |
| Saab AB |
| Airbus SE |
| Others |
Value Network & Pricing Analysis
Sovereign-backed defense ministries across Southeast Asia function as price-setters through offset mandates and local content thresholds that reshape supplier economics. Indonesia's defense procurement transparency framework compresses margin capture for foreign integrators while concentrating pricing power in state-owned shipyards and joint-venture entities.
Pricing Analysis
Distributor margins for combat system integrators compress under Indonesia's open-bidding disclosure requirements that document offset commitments in public filings. Three-tier pricing structure across NATO-interoperable, hybrid-national, and legacy-refit configurations separates Singapore's premium C4ISR specifications from Vietnam's coastal defense priorities and Philippine dual-use platform demand. Cost compression in frigate propulsion systems intensifies as Thai and Indonesian navies specify integrated power architectures that displace mechanical-drive suppliers. Government maritime agencies exhibit highest price sensitivity due to constabulary budget constraints, while military commands absorb premium pricing for submarine undersea domain awareness capabilities.
Supply Chain Analysis
Regional distribution centers for naval combat systems concentrate in Singapore's Tuas shipyard cluster and Jakarta's state-owned yard network, with hub-and-spoke patterns radiating to Subic Bay and Cam Ranh maintenance facilities. Manufacturing gravity rests on South Korean hull fabrication, French sensor integration, and German propulsion engineering for submarine programs. Supply chains draw from gallium nitride semiconductors for radar systems, high-tensile steel for pressure hulls, and lithium-ion battery cells for hybrid electric architectures. Single-source vulnerability concentrates in Singapore's skilled naval architecture workforce, creating recruitment bottlenecks for emerging Indonesian and Philippine programs. Distribution runs through defense ministry acquisition boards that mandate joint-venture structures for contracts exceeding local content thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Southeast Asia defense procurement functions as a stable compounder where maritime territorial tensions sustain replacement cycles for undersea and surface combatants regardless of fiscal headwinds elsewhere.
For Market Incumbents: Anticipate margin compression from Indonesia's transparency framework by deepening joint-venture equity stakes in Jakarta's state-owned yards before disclosure mandates harden. Lockheed Martin and Thales Group should anchor integrated combat system offerings through technology licensing agreements that satisfy local content thresholds while restricting core subsystem access. Electronic warfare specialists must defend sensor margins against emerging Korean and Chinese entrants by certifying NATO-interoperable architectures for Singapore and Thailand coalition exercise requirements. For New Entrants and Emerging Players: Unmanned maritime surveillance platforms offer the most penetrable white-space target as Philippine and Indonesian coast guard agencies pursue coastal patrol capabilities with limited crew requirements. Vietnamese submarine maintenance infrastructure at Cam Ranh presents second-mover opportunity for European propulsion specialists excluded from initial platform sales. New entrants should pursue performance-based logistics contracts unbundled from frigate acquisitions, leveraging Singapore's established MRO network for regional credibility. For Investors and Strategic Acquirers: Sovereign wealth funds from Gulf states are the most active acquirer in this space, targeting Southeast Asian shipyard joint ventures that anchor regional maintenance capacity. Five-to-ten year viability hinges on sustained South China Sea patrol demands and ASEAN interoperability mandate expansion. Acquisition target archetype: mid-tier combat system integrators with Indonesian offset compliance documentation and Vietnamese submarine program relationships. Watch for Malaysia's littoral combat ship program restructuring as inflection indicator for alternative hull design demand.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | Indonesian local content thresholds mandate equity partnerships with PT PAL and state-owned yards. |
| Technology Licensing Agreement | Thales Group's sonar exports to Vietnam require documented transfer limitations preserving core subsystem control. |
| Performance-Based Logistics Contract | Singapore Technologies Engineering captures sustainment margins unbundled from Philippine frigate platform sales. |
| Combat System Integration | Lockheed Martin anchors naval upgrade programs through NATO-standard C4ISR architectures for Thailand. |
| Skilled Workforce Development | Indonesian defense ministry acquisition boards require foreign suppliers to fund naval architecture training pipelines. |
Research Methodology
Direct dialogue with defense ministry procurement officers, shipyard operations directors, combat system integration engineers, and offset compliance advisors grounded this analysis in contracting practice. Secondary validation drew from ASEAN defense white papers, Indonesian defense procurement transparency filings, Vietnamese military modernization directives, and customs records for naval platform imports. Bottom-up platform delivery schedules triangulated against top-down defense budget appropriations across Indonesia, Vietnam, Singapore, Philippines, and Malaysia.
Bottom-up modeling tracked frigate and submarine procurement timelines, C4ISR upgrade cycles, and lifecycle service contract unbundling patterns across the analysis window. Segmentation dimensions spanned platform type, technology tier, end-user institution, and service category. CAGRs derived from defense ministry budget trajectory analysis and platform replacement cycle compression observed in South China Sea patrol demand response. Forecast inputs included hybrid electric propulsion adoption curves and ASEAN interoperability mandate implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to territorial tension de-escalation, procurement reform reversals in Jakarta, and technology transfer restriction tightening by Western exporters. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Global Military Vehicle Electrification Market
Military Vehicles
Eastern Europe Defense Market
Military Vehicles
Military Tank Container Market
Military Vehicles
Colombia Defense Market
Military Vehicles
Amphibious Land Craft Market
Military Vehicles
Taiwan Defense Market
Military Vehicles
Military Amphibious Vehicle Market
Military Vehicles
Iran Defense Market
Military Vehicles
Middle East Military Vehicles Market
Military Vehicles
Riot Control Vehicle Market
Military Vehicles
Infantry Fighting Vehicle (IFV) Market
Military Vehicles
Combat Support Vehicle Market
Military Vehicles
Military Vehicle & Aircraft Protection Systems Market
Military Vehicles
Robotic Combat Vehicle (RCV) Market
Military Vehicles
Destroyers Market
Military Vehicles
Military Ground Robots Market