
 Japan Defense Market | 2026-2036
Japan Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Defense Market Foresight
Software-defined mission systems is realigning procurement patterns across Japan's defense industrial base. Mitsubishi Heavy Industries Ltd. leverages integrated naval and aerospace production lines to anchor government contracts. Kawasaki Heavy Industries Ltd. specializes in submarine and rotary-wing platforms, sustaining long-term maritime programs. IHI Corporation dominates propulsion and engine systems, extending its position through precision manufacturing scale.
Japan defense encompasses sovereign military capability spanning kinetic platforms, electronic warfare architectures, and dual-use aerospace systems engineered to JIS standards and METI technical benchmarks. The sector secures territorial integrity while advancing indigenous sensor and propulsion technologies. Naval Vessels and Aircraft command the largest procurement allocations under current defense buildup plans. Cybersecurity Solutions within the Technology dimension shows the steepest capability investment curve as digital resilience integrates into platform design. Military Forces remain the dominant end-user channel, though Defense Contractors absorb expanding offset and co-development responsibilities.
METI, Japan's Ministry of Defense acquisition framework, and JIS standards collectively govern industrial participation, export controls, and technology transfer protocols. These frameworks mandate domestic content thresholds and restrict foreign supply chain exposure for critical subsystems. Stakeholders must track constitutional reinterpretation dynamics and collective security alignment decisions that will determine procurement pacing and industrial policy latitude.
Market Dynamics
Constitutional reinterpretation and collective security alignment are restructuring Japan's defense procurement velocity, compressing platform acquisition timelines while expanding industrial policy latitude for indigenous system development.
Growth Catalysts
- Maritime platform modernization:Japan's Maritime Self-Defense Force vessel replacement programs drive sustained shipyard output across the Kanto industrial cluster.
- METI defense production guidelines:Domestic content thresholds and technology transfer protocols channel investment toward precision manufacturing capabilities.
- Electronic warfare architectures:Sensor fusion requirements for territorial defense missions accelerate subsystem integration contracts.
Market Restraints
- Specialized alloy supply concentration:High-grade naval steel and titanium sourcing remains captive to limited East Asian smelter capacity.
- JIS certification timelines:Extended qualification periods for dual-use aerospace components delay platform integration schedules.
- Propulsion system technical limitations:Indigenous marine gas turbine development lags established Western designs in thermal efficiency benchmarks.
Strategic Opportunities
- Kyushu aerospace corridor expansion:Underutilized manufacturing zones near Fukuoka offer assembly capacity for unmanned systems production.
- Cyber-physical platform convergence:Integration of software-defined mission systems with legacy naval hulls creates upgrade contract white space.
- Co-development partnership frameworks:Australia's AUKUS-aligned procurement opens offset opportunities for Japanese submarine component suppliers.
Industry Challenges
- Systems engineering talent scarcity:Software-defined mission architecture expertise outpaces domestic university pipeline output.
- Legacy platform integration complexity:Retrofitting digital backbone infrastructure into 1980s-era destroyer hulls demands bespoke interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Defense Market |
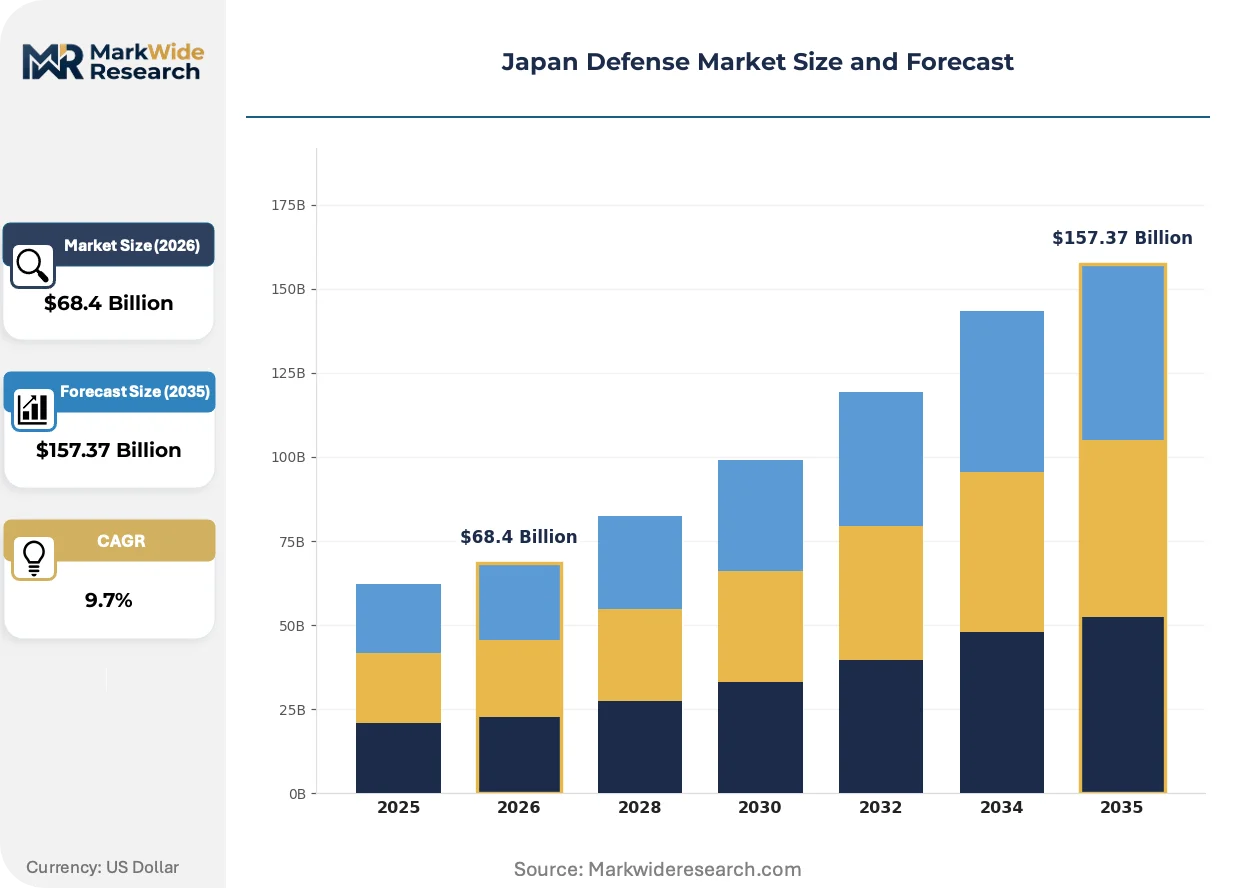
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $157.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Land Systems, Naval Vessels, Aircraft, Missiles Technology: Cybersecurity Solutions, Surveillance Systems, Communication Networks, Radar Systems End User: Military Forces, Defense Contractors, Government Agencies, Research Institutions Service Type: Logistics Support, Maintenance Services, Training Programs, Consulting Services |
| Companies Covered | ShinMaywa Industries Ltd., Namura Shipbuilding Co. Ltd, Mitsubishi Heavy Industries Ltd., Subaru Corporation, JAMCO Corp, Kawasaki Heavy Industries Ltd., IHI Corporation, Hitachi Ltd., Mitsui E&S Holdings Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Defense Market Shifts & Advancements
Software-defined architectures are displacing hardware-centric mission systems across Japan's naval and aerospace platforms, compressing upgrade cycles while expanding contractor responsibility for through-life capability management.
Artificial intelligence-enabled threat detection is automating sensor correlation workflows aboard Japan's next-generation destroyer fleet. The Maritime Self-Defense Force is fielding these systems at accelerated commissioning intervals. This capability compression is automating operator decision loops while reducing crew complement requirements for distributed maritime operations.
METI's revised defense production base guidelines now mandate domestic content thresholds for critical subsystems while restricting foreign supply chain exposure. Industrial participants must reconfigure procurement networks to satisfy localization requirements. Naval propulsion and electronic warfare segments face the steepest compliance reconfiguration demands.
Defense contractors are absorbing expanding offset responsibilities through co-development arrangements with government acquisition channels. Traditional equipment vendor relationships are yielding to multi-decade capability partnership structures. This channel evolution is most visible in submarine and rotary-wing platform programs where Kawasaki Heavy Industries maintains long-term maritime system commitments.
Japan Defense Market Segmentation
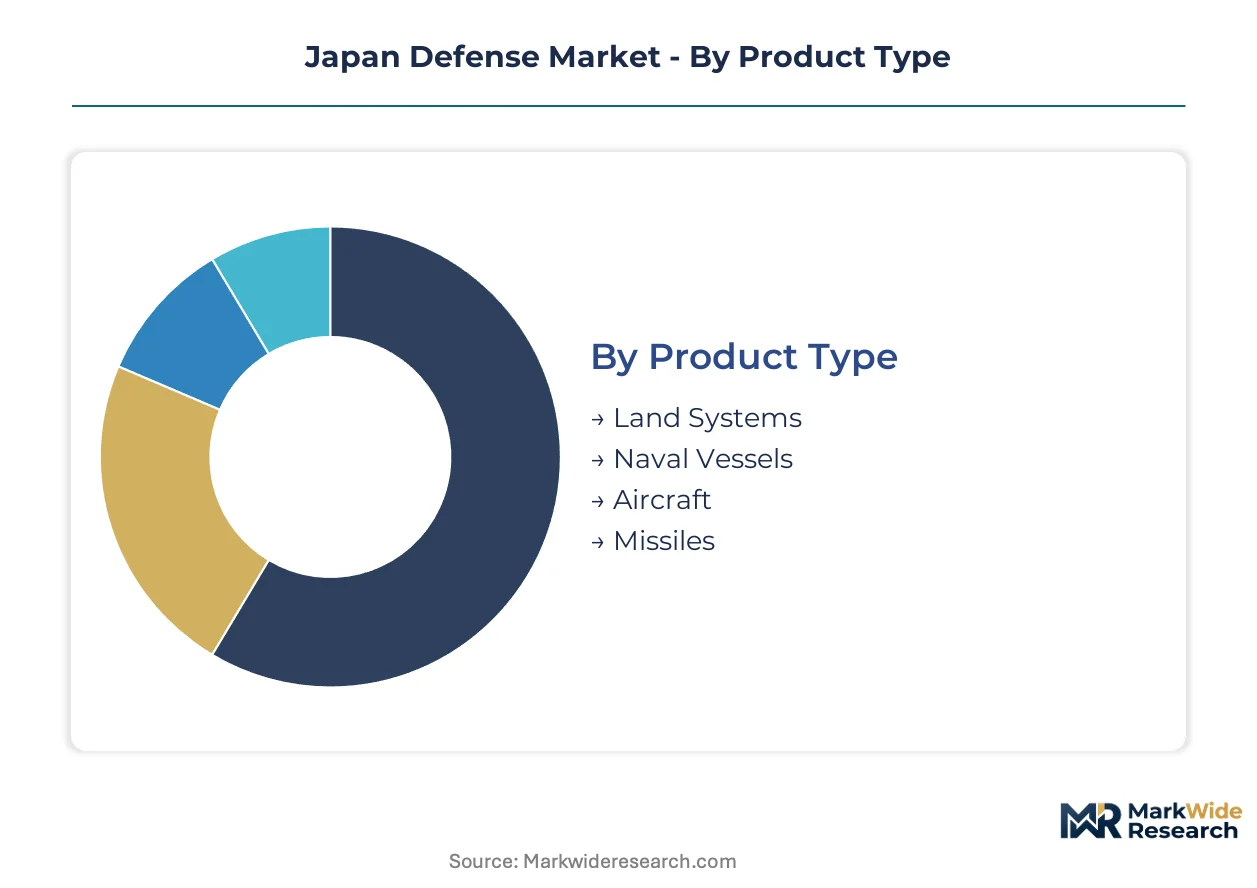
Segmentation reveals how procurement concentration and capability specialization distribute across Japan's defense industrial base. Distinct technology maturity curves and end-user requirements create divergent investment profiles across each dimension.
Product Type:
Platform manufacturing concentrates in the Kanto and Nagoya industrial corridors, with hull and airframe assembly driving the largest capital allocations.
- Naval Vessels:Surface combatants and submarine hulls integrate indigenous steel processing with precision propulsion engineering. Maritime Self-Defense Force destroyer replacement programs concentrate demand at Yokosuka and Kure shipyards, sustaining multi-year production backlogs.
- Aircraft:Fixed-wing and rotary platforms span fighter airframes, maritime patrol aircraft, and transport systems. Final assembly at Komaki and Gifu facilities absorbs precision avionics from the Nagoya aerospace cluster, with F-X fighter development accelerating domestic content thresholds.
- Land Systems:Armored vehicles and artillery platforms serve ground self-defense formations with lower procurement velocity.
- Missiles:Stand-off and interceptor systems integrate solid-rocket motor production with terminal guidance subsystems.
Naval Vessels absorb the bulk of installed capacity; Aircraft is expanding most quickly.
Technology:
Capability investment curves diverge sharply between hardware-dominant sensor systems and software-intensive mission architectures.
- Cybersecurity Solutions:Network defense, cryptographic infrastructure, and platform-hardened computing layers protect distributed maritime operations. Defense Ministry acquisition channels prioritize zero-trust architectures for next-generation destroyer fleets, compressing procurement timelines for indigenous security stacks.
- Surveillance Systems:Electro-optical and signals intelligence payloads integrate multi-spectral sensing for territorial monitoring. Coastal defense installations and airborne patrol platforms concentrate demand at Fujisawa and Iruma technology centers.
- Radar Systems:Active electronically scanned arrays and multi-function apertures support air and missile defense missions.
- Communication Networks:Tactical data links and satellite relay infrastructure enable joint force coordination.
Cybersecurity Solutions commands the steepest capability investment trajectory; Surveillance Systems maintains the largest installed base.
End User:
Channel structure determines contract duration, offset requirements, and technology transfer exposure.
- Military Forces:Japan's three self-defense branches—Maritime, Air, and Ground—issue platform-centric procurement with through-life support mandates. Maritime Self-Defense Force vessel programs sustain the longest contract horizons, absorbing integrated logistics packages from prime contractors.
- Defense Contractors:Tier-one system integrators and component suppliers absorb expanding co-development responsibilities. Kawasaki Heavy Industries and Mitsubishi Heavy Industries anchor submarine and rotary-wing offset arrangements, extending industrial participation beyond equipment delivery.
- Government Agencies:Cabinet-level coordination bodies manage strategic capability roadmaps and export control compliance.
- Research Institutions:National laboratories and university-affiliated centers prototype next-generation propulsion and sensor technologies.
Military Forces channels dominate procurement volume; Defense Contractors absorb expanding program management scope.
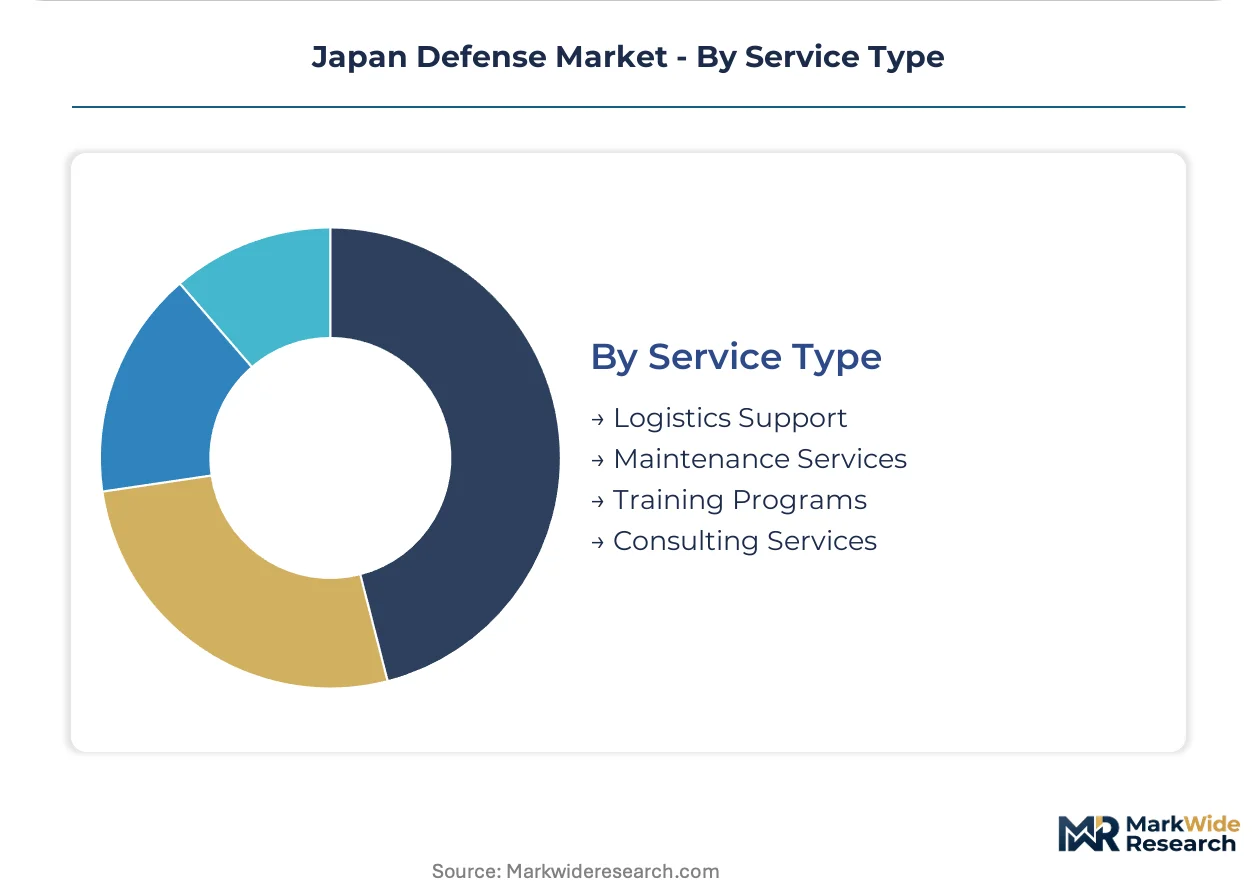
Service Type:
Post-delivery revenue streams increasingly determine contractor profitability as platform margins compress.
- Maintenance Services:Depot-level overhaul, component repair, and predictive diagnostics sustain operational availability across aging destroyer hulls and fighter airframes. Yokosuka Naval Base and Gifu Air Base facilities anchor regional maintenance networks with contractor-embedded technical teams.
- Logistics Support:Spare parts provisioning, supply chain management, and forward stocking position combat-ready assets. Maritime patrol squadrons and submarine flotillas demand specialized alloy and precision component inventories with extended procurement lead times.
- Training Programs:Simulator-based instruction and live-fire exercises develop operator proficiency for software-defined mission systems.
- Consulting Services:Systems engineering and program management advisory supports defense acquisition reform initiatives.
Maintenance Services captures the largest recurring revenue share; Logistics Support faces the most acute supply chain reconfiguration pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's defense production concentrates in coastal industrial corridors while consumption distributes across three self-defense branches. Domestic shipyards and aerospace facilities absorb the bulk of procurement expenditure. Sub-regional specialization creates distinct capability clusters.
Kanto/Tokyo
Yokosuka Naval Base drives destroyer maintenance demand while sustaining multi-year vessel overhaul contracts. METI's defense production guidelines channel precision manufacturing investment toward Kawasaki and Yokohama facilities. The Tokyo metropolitan corridor anchors aerospace electronics integration for next-generation fighter programs.
Kansai/Osaka
Kobe and Osaka harbor districts concentrate submarine component fabrication and marine propulsion engineering. JIS certification requirements for dual-use steel products extend qualification timelines at local forges. The Kansai industrial belt sustains long-term maritime platform supply relationships with defense acquisition channels.
Chubu/Nagoya
Komaki Air Base and surrounding aerospace facilities absorb fixed-wing final assembly operations. Precision avionics suppliers cluster around Nagoya's manufacturing corridor to satisfy domestic content thresholds. The Chubu region's machine tool base supports turbine blade machining for indigenous propulsion programs.
Kyushu
Fukuoka manufacturing zones offer underutilized capacity for unmanned systems assembly expansion. METI's industrial policy identifies Kyushu as a target location for defense production base diversification. Local shipyards at Nagasaki maintain historical naval construction expertise for surface combatant hull fabrication.
Hokkaido
Northern territorial defense missions drive coastal surveillance system deployment across Hokkaido's maritime approaches. Cold-weather testing facilities at Chitose support aerospace platform validation for extreme climate operations. The sub-region's strategic position sustains radar and signals intelligence infrastructure investment.
Japan Defense Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Japan's defense industrial base. Prime contractors operating integrated shipyards and airframe facilities dominate platform procurement. Three archetypes prevail: vertically integrated system integrators, specialized subsystem suppliers, and dual-use technology providers. Consolidation pressures favor long-term co-development partnerships over transactional equipment sales. Geographic clustering around Kanto and Kansai corridors reinforces incumbent positioning.
Within the integrated system integrator tier, Mitsubishi Heavy Industries Ltd. and Kawasaki Heavy Industries Ltd. occupy anchor positions spanning naval and aerospace domains. IHI Corporation exemplifies the specialized propulsion archetype through marine gas turbine and engine system concentration. These three entities represent the core industrial structure through which METI channels defense production investment and technology transfer protocols.
| Leading Market Players |
|---|
| ShinMaywa Industries Ltd. |
| Namura Shipbuilding Co. Ltd |
| Mitsubishi Heavy Industries Ltd. |
| Subaru Corporation |
| JAMCO Corp |
| Kawasaki Heavy Industries Ltd. |
| IHI Corporation |
| Hitachi Ltd. |
| Mitsui E&S Holdings Co Ltd |
| Others |
Supply & Pricing Matrix
Software-defined mission system integration is compressing platform upgrade cycles while concentrating procurement leverage among prime contractors capable of delivering through-life capability management. This production-method transition simultaneously elevates engineering cost structures and reinforces supplier consolidation across Japan's Kanto and Kansai industrial corridors.
Pricing Analysis
Margin tightening in naval platform tiers reflects METI-mandated domestic content thresholds that elevate precision manufacturing input costs. Contract-based long-term offtake structures dominate, with price differentiation resting on JIS certification grade and volume scale for dual-use aerospace components. Pricing pressure stems from indigenous propulsion development lagging Western thermal efficiency benchmarks. Maritime Self-Defense Force procurement channels exhibit lowest price sensitivity; tier-two component suppliers face acute cost-down demands.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Chinese smelter capacity for high-grade naval steel and titanium alloys. Japan's defense industrial base draws from domestic precision manufacturing clusters, Australian rare earth processing, and Taiwanese semiconductor fabrication for mission-critical electronics. Tariff exposure on specialty alloy imports presents structural risk. Distribution runs through prime contractor-anchored supply networks with embedded technical teams at Yokosuka and Gifu facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
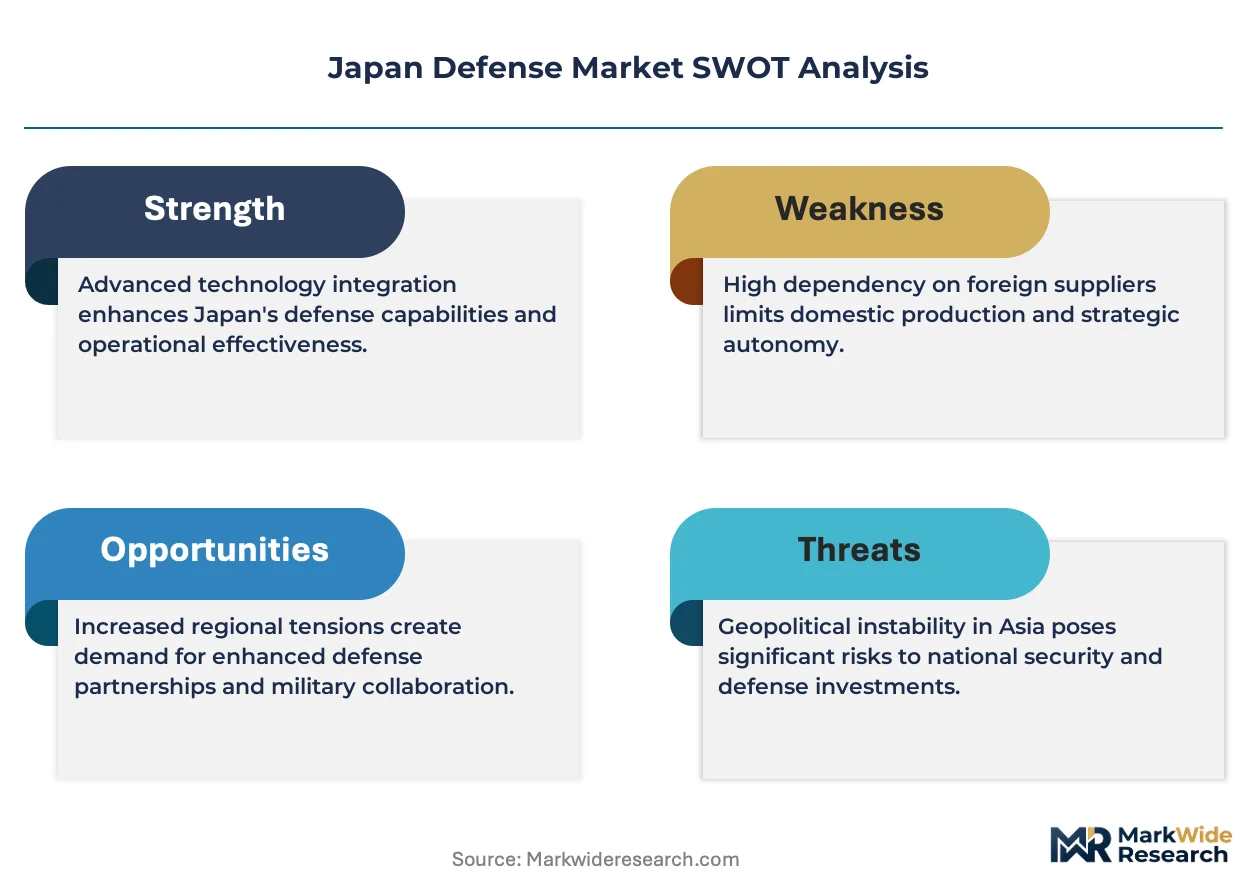
Japan's defense market operates as a supply-constrained environment where JIS certification bottlenecks prop pricing power for qualified precision manufacturers. Capacity scarcity in systems engineering talent further tightens contractor selection criteria.
For Market Incumbents: Extend co-development partnership structures to absorb expanding offset responsibilities from government acquisition channels. Deepen backward integration into marine gas turbine component production to mitigate indigenous thermal efficiency gaps. Secure long-term maritime platform commitments through integrated logistics packages that embed technical teams at Self-Defense Force facilities. For New Entrants and Emerging Players: Artificial intelligence-enabled threat detection architectures offer technology-first wedge opportunities into software-defined mission system upgrades. Kyushu's underutilized manufacturing zones present the most penetrable geography for unmanned systems assembly. Pursue subcontractor qualification under METI defense production guidelines as the primary go-to-market pathway. For Investors and Strategic Acquirers: Re-rating potential sits with specialized propulsion subsystem suppliers given accelerating destroyer replacement programs. Five-to-ten year viability favors entities with JIS-certified precision manufacturing capabilities and established Self-Defense Force maintenance relationships. Watch constitutional reinterpretation dynamics as the signal for procurement pacing inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Development Partnership Structuring | Multi-decade capability commitments with Maritime Self-Defense Force replace transactional equipment sales. |
| JIS Certification Investment | Qualification for dual-use aerospace components unlocks F-X fighter and next-generation destroyer integration contracts. |
| Kyushu Manufacturing Footprint Expansion | Underutilized Fukuoka capacity supports METI's defense production base diversification objectives. |
| Software-Defined Mission System Integration | Compression of upgrade cycles expands contractor responsibility for through-life capability management. |
| Indigenous Propulsion Development | Marine gas turbine advancement reduces dependency on Western thermal efficiency benchmarks. |
Research Methodology
Multi-period observation of defense procurement velocity, JIS certification timelines, and prime contractor backlog composition anchored the trend analysis, supplemented by interviews with Maritime Self-Defense Force acquisition officers, METI industrial policy directors, shipyard program managers, and precision manufacturing executives. Secondary validation drew from Japan Ministry of Defense budget submissions, METI defense production base guideline revisions, JIS standard documentation, and customs data on specialty alloy imports. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume estimates.
Input-output matrices modeled demand across platform type, technology maturity tier, end-user channel structure, and regional industrial cluster concentration. CAGRs were derived from regression analysis of historical procurement patterns against constitutional reinterpretation scenarios and collective security alignment trajectories. Forecast inputs incorporated destroyer replacement program schedules and F-X fighter development milestones without specifying calendar years.
Several conditions sit outside the modeled scope, including specific constitutional amendment outcomes, bilateral technology transfer agreements, and commodity price volatility in titanium and rare earth markets. Deviation in METI defense production guideline enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Eastern Europe Defense Market
Military Vehicles
Middle East Military Vehicles Market
Military Vehicles
Military Trucks Market
Military Vehicles
Military Unmanned Ground Vehicle Market
Military Vehicles
Colombia Defense Market
Military Vehicles
Amphibious Land Craft Market
Military Vehicles
Southeast Asia Defense Market
Military Vehicles
Military Vehicle & Aircraft Protection Systems Market
Military Vehicles
Global Military Vehicle Electrification Market
Military Vehicles
Destroyers Market
Military Vehicles
Combat Support Vehicle Market
Military Vehicles
Military Tank Container Market
Military Vehicles
Military Ground Robots Market
Military Vehicles
Robotic Combat Vehicle (RCV) Market
Military Vehicles
Indonesia Defense Market
Military Vehicles
Military Ground Vehicle Actuators Market