
 Combat Support Vehicle Market | 2026-2036
Combat Support Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Combat Support Vehicle Market Outlook
The capability gap between full-system integrators and component suppliers is collapsing as modular open architecture standards proliferate across defense procurement. BAE Systems leverages its British manufacturing footprint and active protection systems expertise to anchor European NATO contracts. Rheinmetall AG sustains its position through in-house production of tracked chassis and turret systems, competing aggressively for German Army modernization programs. General Dynamics Corporation dominates North American ground combat platforms with its extensive service network and established US Army relationships.
A combat support vehicle constitutes a purpose-built military platform engineered for battlefield logistics, command coordination, casualty evacuation, or equipment recovery, typically featuring ballistic protection levels from STANAG 4569 Level 2 to Level 4 and gross vehicle weights spanning 10 to 40 tonnes depending on mission profile. These platforms integrate C4ISR suites, auxiliary power units, and modular payload interfaces to sustain combined-arms operations under contested conditions. Armored Personnel Carrier and Recovery Vehicle categories command the largest current procurement volumes, reflecting persistent demand for force protection and sustainment in high-intensity conflict scenarios. Diesel propulsion retains overwhelming installed base share, though Hybrid technology attracts disproportionate R&D allocation as militaries confront operational signature reduction and fuel logistics burdens.
The US Army's Climate Strategy, NATO STANAG standardization processes, and the EU Green Deal's defense sector applicability collectively reshape powertrain certification and emissions benchmarking for military vehicles. Germany's KBA and the US EPA coordinate divergent testing protocols that complicate transatlantic platform commonality. Buyers must weigh interoperability mandates against sovereign industrial requirements as procurement cycles lengthen and technical specifications harden around electrification pathways.
Market Dynamics
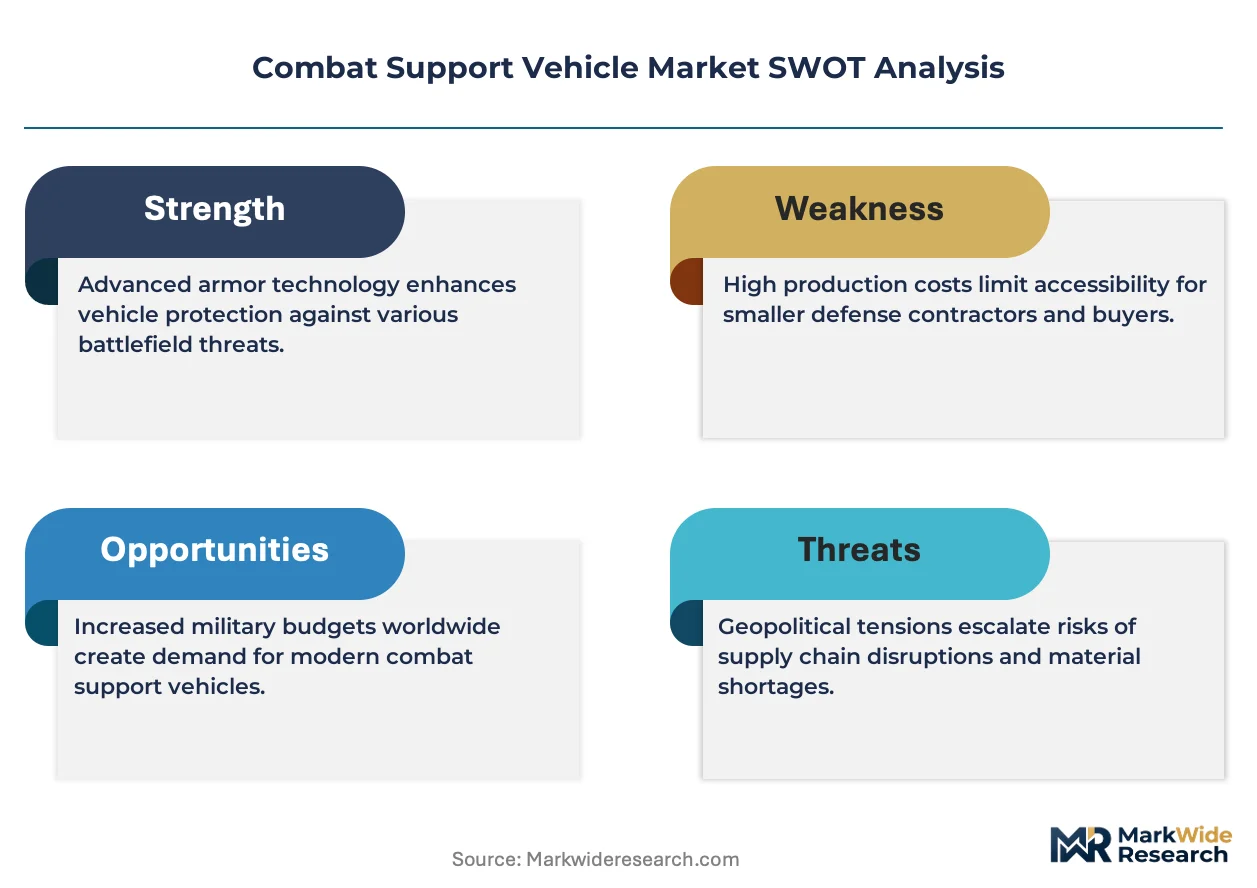
Hybrid-electric propulsion mandates under the US Army Climate Strategy and NATO STANAG standardization are compressing traditional diesel-centric supply chains while forcing integrators to rebuild powertrain competencies around battery thermal management and silent-watch capabilities.
Growth Catalysts
- NATO STANAG 4569 Level 4 Protection Mandates:Alliance members in Eastern Europe are retrofitting existing fleets with enhanced ballistic packages, creating sustained demand for armored recovery variants.
- South Korean K2 Tank Program:Seoul's indigenous armor modernization is spawning parallel combat support vehicle procurement for bridge-layers and armored engineering platforms.
- Hybrid-Electric Powertrain Development:Silent mobility requirements for forward command posts are accelerating R&D allocation toward battery-diesel series hybrid architectures.
Market Restraints
- Armor Steel Input Volatility:High-hardness rolled homogeneous armor plate from Ukrainian and Russian mills faces supply disruption, forcing European integrators toward Swedish and Japanese specialty steel sources.
- Transatlantic Certification Divergence:Germany's KBA and the US EPA maintain incompatible emissions testing protocols for military diesel engines, fragmenting platform commonality.
- Unmanned Ground Vehicle Substitution:Autonomous logistics platforms for ammunition resupply are displacing manned cargo variants in experimental brigade combat team formations.
Strategic Opportunities
- Polish Armored Vehicle Modernization:Warsaw's $20 billion technical modernization program includes dedicated procurement lines for command post vehicles and armored ambulances.
- EU Green Deal Defense Applicability:Brussels is developing military vehicle emissions benchmarking that will favor early hybrid-electric certifiers in continental tender processes.
- Australian Land 400 Phase 3:Canberra's combat reconnaissance vehicle competition includes mandatory combat support variants for regional expeditionary operations.
Industry Challenges
- Powertrain Thermal Management Expertise Gap:Battery cooling system integration for desert and arctic operating envelopes requires skill sets concentrated in automotive racing and aerospace sectors.
- Legacy C4ISR Integration Complexity:NATO's Federated Mission Networking standards demand backward compatibility with 1990s-era command systems still fielded by member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combat Support Vehicle Market |
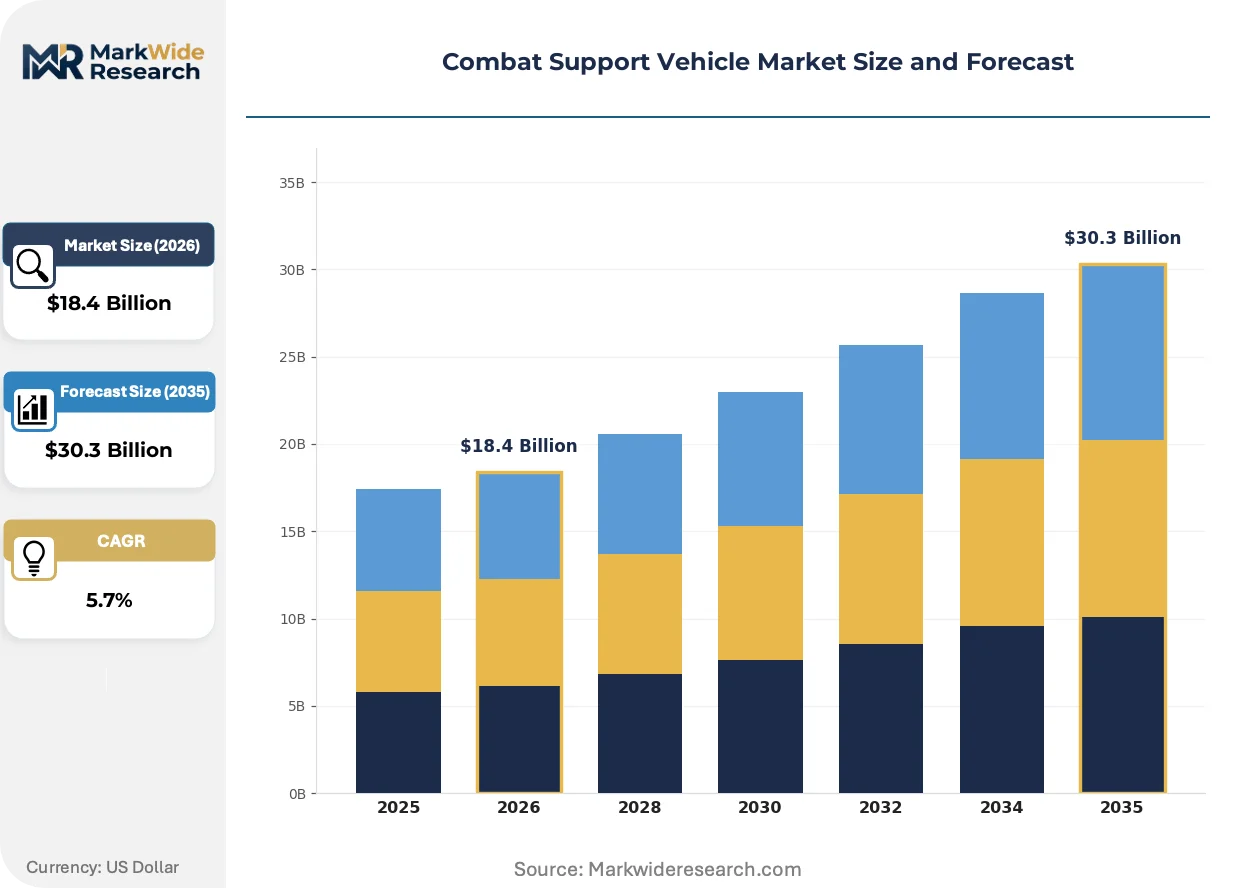
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $30.3 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Armored Personnel Carrier, Tactical Vehicle, Command Vehicle, Recovery Vehicle Technology: Hybrid, Electric, Diesel, Fuel Cell End User: Military, Defense Contractors, Government Agencies, Security Forces Capacity: Small, Medium, Large, Heavy |
| Companies Covered | BAE Systems, General Dynamics Corporation, Rheinmetall AG, Oshkosh Corporation, Textron Inc., Leonardo S.p.A., Hanwha Defense, Krauss-Maffei Wegmann, Elbit Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combat Support Vehicle Market Strategic Shifts
Active protection systems and modular mission equipment packages are converging to redefine platform lifecycle economics, compressing the traditional 30-year service intervals that once dominated ground vehicle procurement.
Silicon carbide ceramic armor inserts are fragmenting the monolithic steel protection paradigm that defined Cold War-era vehicle design. NATO members are retrofitting legacy hulls with tile-based appliqué systems rather than procuring clean-sheet replacements. This approach is fragmenting revenue concentration away from full-system integrators toward specialized armor subsystem suppliers.
The US EPA and Germany's KBA are negotiating mutual recognition agreements for military diesel engine emissions certification, though divergence in test cycles persists. European manufacturers face dual compliance burdens when bidding on Pentagon contracts. Armored recovery vehicles with auxiliary power generation capabilities are most affected, as their stationary engine operating profiles trigger divergent regulatory thresholds.
Service-life extension programs are displacing new-build procurement across NATO-aligned forces. Denmark and Norway are pursuing 15-year hull refurbishment contracts rather than replacement purchases. This pattern is most visible in command post vehicle categories, where electronics modernization delivers greater capability uplift than chassis replacement.
Combat Support Vehicle Market Segmentation
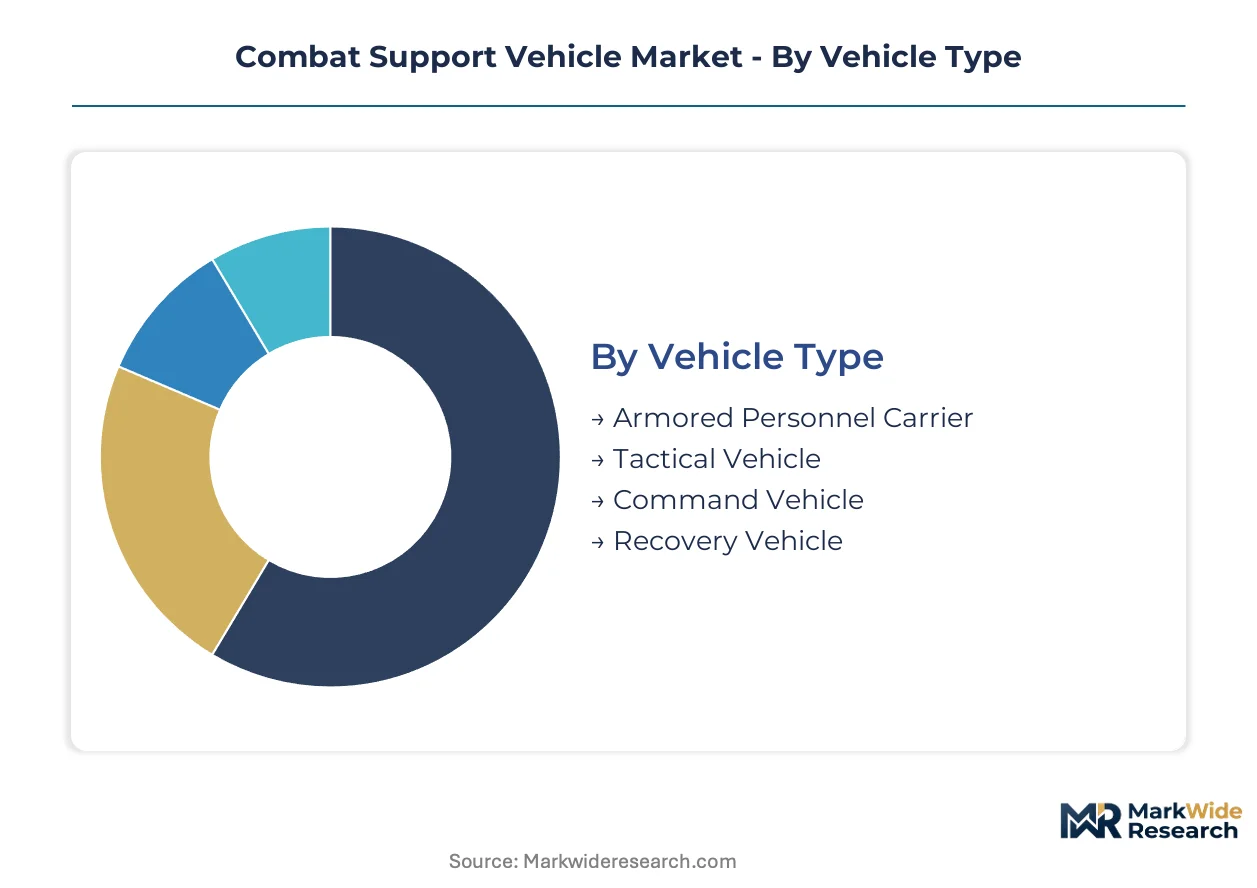
Combat support vehicle procurement diverges sharply across national defense priorities, with vehicle type and technology choices reflecting distinct operational doctrines. Segment boundaries are blurring as modular architectures allow single platforms to serve multiple mission profiles, complicating traditional procurement categorization.
Vehicle Type:
Armored Personnel Carrier and Recovery Vehicle variants dominate domestic procurement in NATO-aligned forces, while Command Vehicle exports concentrate in Middle Eastern and Asia-Pacific militaries seeking C4ISR integration.
- Armored Personnel Carrier:These platforms integrate STANAG 4569 Level 2-4 ballistic protection with modular seating for 8-12 dismounted troops. Demand concentrates in Eastern European NATO members retrofitting Soviet-era fleets with enhanced mine blast protection following regional security realignment.
- Recovery Vehicle:Purpose-built hulls with 30-40 tonne winch capacity and auxiliary power generation for forward repair operations. Germany and South Korea anchor procurement through indigenous armor modernization programs requiring dedicated technical support variants.
- Tactical Vehicle:Light mobility platforms under 10 tonnes GVW for special operations and reconnaissance support.
- Command Vehicle:Integrated C4ISR suites with electromagnetic interference shielding for battalion-level coordination.
Armored Personnel Carrier holds the largest share; momentum sits with Recovery Vehicle as fleet sustainment requirements intensify.
Technology:
Cost tier stratification separates mature diesel platforms from emerging hybrid architectures, with fuel cell systems occupying experimental niches in arctic warfare applications.
- Diesel:Compression-ignition engines with 300-600 kW output ratings dominate installed base economics. The US EPA and Germany's KBA maintain incompatible emissions certification protocols, fragmenting transatlantic platform commonality for armored recovery variants with extended stationary operating profiles.
- Hybrid:Series battery-diesel architectures enabling silent-watch capability for forward command posts. The US Army Climate Strategy mandates hybrid-electric propulsion for new programs, compressing traditional supply chains around battery thermal management competencies.
- Electric:Pure battery platforms limited to rear-area logistics by energy density constraints and battlefield charging infrastructure gaps.
- Fuel Cell:Hydrogen proton-exchange membrane systems under evaluation for extreme cold-weather operations where battery performance degrades.
Diesel retains dominant installed share; hybrid architectures are climbing the fastest as operational signature reduction becomes a procurement priority.
End User:
Customer type determines specification rigidity, with military end users demanding STANAG compliance while security forces accept commercial-off-the-shelf armor packages.
- Military:National armed forces requiring full-spectrum protection, interoperability certification, and 25-30 year service life projections. Procurement concentrates in the United States, Germany, and South Korea as these nations modernize legacy mechanized formations.
- Defense Contractors:Private military companies and logistics providers operating in contested environments under government contract.
- Government Agencies:Border patrol, disaster response, and critical infrastructure protection units with modified threat profiles.
- Security Forces:Paramilitary and law enforcement units prioritizing urban mobility over cross-country performance.
Military end users command the largest procurement volumes; defense contractors are expanding fastest as outsourced sustainment roles proliferate.
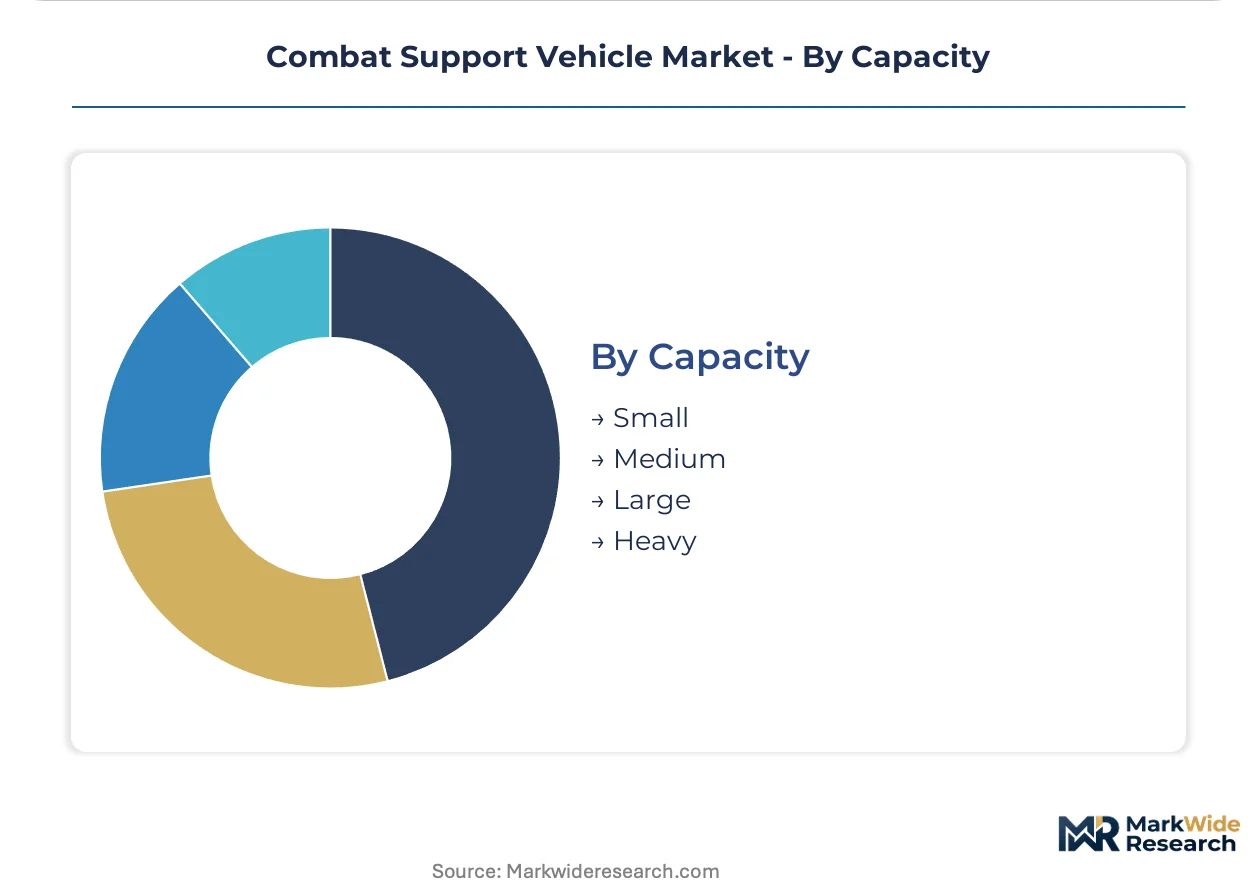
Capacity:
Volume distribution skews toward medium and heavy platforms as mechanized brigade structures persist, though light variants gain traction in expeditionary rapid-response formations.
- Heavy:Platforms exceeding 30 tonnes GVW with Level 4 protection and heavy equipment transporter compatibility. Poland's technical modernization program and Australia's Land 400 Phase 3 competition anchor demand for this category.
- Medium:15-30 tonne vehicles balancing protection with strategic deployability via C-130 transport.
- Small:Under 10 tonnes platforms for special operations and airborne insertion.
- Large:30-40 tonne bridging vehicles and armored engineering platforms with specialized superstructures.
Heavy capacity holds the largest share; small platforms are gaining share fastest as special operations procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from German and South Korean manufacturing clusters dominate transatlantic and Asia-Pacific procurement channels, while the United States remains a net importer of armored recovery hulls despite indigenous final assembly capacity.
United States
The US Army's Climate Strategy mandates hybrid-electric propulsion for new combat support vehicle programs, compressing traditional diesel supply chains. The EPA coordinates emissions certification with Germany's KBA through ongoing mutual recognition negotiations. Detroit Arsenal in Michigan anchors domestic production of armored recovery variants with auxiliary power generation capabilities.
Germany
German Army modernization programs under the K2 tank initiative spawn parallel procurement for bridge-layers and armored engineering platforms. The KBA maintains divergent testing protocols from US EPA standards, fragmenting transatlantic platform commonality. Rheinmetall's Kassel facility and Krauss-Maffei Wegmann's Munich operations concentrate tracked chassis production for NATO export contracts.
South Korea
Seoul's indigenous K2 tank program drives demand for dedicated combat support variants including armored ambulances and command post vehicles. The Defense Acquisition Program Administration prioritizes local content thresholds above 60 percent for hull fabrication. Hanwha Defense's Changwon complex and Hyundai Rotem's Ulsan facility anchor heavy platform manufacturing for regional export.
Poland
Warsaw's technical modernization program allocates dedicated procurement lines for command post vehicles and armored ambulances under its armored forces expansion. The Polish Armaments Group coordinates offset requirements favoring domestic integration of foreign subsystems. Bumar-Łabędy in Gliwice and Rosomak S.A. in Siemianowice Śląskie concentrate hull refurbishment and new-build assembly.
Australia
Canberra's Land 400 Phase 3 competition mandates combat support variants for regional expeditionary operations alongside primary combat reconnaissance platforms. The Department of Defence's LAND 8116 program specifies STANAG 4569 Level 4 protection for armored recovery vehicles. Thales Australia's Bendigo facility and Rheinmetall's Military Vehicle Centre of Excellence in Ipswich, Queensland anchor tracked platform integration.
Combat Support Vehicle Market Competitive Environment
Concentration sits with full-system integrators possessing captive chassis production and established government relationships. The vendor base compresses around three strategic tiers: legacy defense conglomerates with multi-domain portfolios, regional specialists anchored to single-national procurement programs, and subsystem suppliers capturing modular architecture shifts. Competitive moves center on backward integration into powertrain components and strategic partnerships for battery thermal management expertise.
Within the legacy integrator tier, BAE Systems, General Dynamics Corporation, and Rheinmetall AG exemplify divergent geographic anchoring strategies. BAE Systems occupies a position tied to British manufacturing footprints and European NATO relationships. General Dynamics Corporation exemplifies North American ground platform dominance through extensive service networks. Rheinmetall AG represents German-centered production integration with aggressive positioning for Bundeswehr modernization awards.
| Leading Market Players |
|---|
| BAE Systems |
| General Dynamics Corporation |
| Rheinmetall AG |
| Oshkosh Corporation |
| Textron Inc. |
| Leonardo S.p.A. |
| Hanwha Defense |
| Krauss-Maffei Wegmann |
| Elbit Systems Ltd. |
| Others |
Value Chain & Pricing Dynamics
Twenty-four-month lead times for high-hardness rolled homogeneous armor plate from Swedish and Japanese specialty mills concentrate pricing power with integrators holding captive steel inventories. This supply concentration shapes procurement economics as buyers face take-or-pay commitments for STANAG 4569 Level 4 ballistic packages while spot-market alternatives remain unavailable.
Pricing Analysis
The customization-premium spread between configured-to-order armored recovery vehicles and standard tactical platforms runs wide as modular C4ISR integration commands substantial engineering overhead. Contract-based long-term offtake agreements dominate procurement, with price differentiation anchored in certification level and after-sales service bundling rather than base chassis economics. Cost compression in mid-tier diesel platforms intensifies as hybrid-electric mandates from the US Army Climate Strategy force dual powertrain development. Defense contractors exhibit highest price sensitivity due to fixed-margin government contracts, while national military end users prioritize capability over unit cost.
Supply Chain Analysis
Inventory positions for silicon carbide ceramic armor inserts have tightened to ninety-day coverage as NATO retrofit programs surge demand beyond Korean and German ceramic foundry capacity. Geographic supply concentration centers on Germany for tracked chassis fabrication, South Korea for heavy platform final assembly, and Sweden for specialty armor steel. The supply chain draws from Ukrainian mill disruption legacy, Japanese high-grade steel, and Chinese rare-earth processing for electromagnetic shielding components. Single-source vulnerability in battery thermal management subsystems from automotive racing suppliers poses structural risk. Distribution runs through government procurement offices with multi-year tender cycles and offset requirement negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid-electric propulsion mandates under the US Army Climate Strategy constitute a technological inflection disrupting traditional diesel-centric supplier relationships and compressing established competitive positions.
For Market Incumbents: Secure captive supply of battery thermal management components through backward integration into automotive racing sector partnerships. Lock in multi-year offtake agreements with Swedish and Japanese specialty steel producers before capacity constraints harden. The threat of autonomous ground vehicle substitution for logistics roles demands accelerated investment in manned-unmanned teaming interfaces to preserve platform relevance. For New Entrants and Emerging Players: Lead with modular open-architecture C4ISR subsystems that retrofit legacy NATO hulls rather than competing for full-system integrator contracts. Poland's technical modernization program and Australia's Land 400 Phase 3 competition represent the most penetrable procurement channels for non-incumbent bidders. A direct engagement model with national armaments agencies bypassing established prime contractor relationships offers viable go-to-market positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from automotive Tier 1 suppliers possessing battery cooling expertise but lacking defense sector relationships. Long-term viability in this market hinges on hybrid-electric certification timing rather than legacy diesel platform maintenance. Watch for EPA-KBA mutual recognition agreement finalization as the signal indicating transatlantic platform commonality opportunities and consolidated procurement volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Powertrain Certification | Early EPA-KBA dual compliance positions integrators for NATO-wide procurement consolidation. |
| Specialty Steel Long-Term Supply Agreement | Captive access to Swedish and Japanese high-hardness plate insulates against input volatility. |
| Battery Thermal Management Partnership | Automotive racing sector alliances address powertrain expertise gaps in desert and arctic envelopes. |
| Modular C4ISR Platform Development | Open-architecture systems capture service-life extension program spending across NATO refurbishment cycles. |
| Regional Manufacturing Footprint Expansion | Polish and Australian facility investments satisfy offset requirements in high-growth procurement markets. |
Study Parameters
Initial hypotheses were tested against primary input from program managers at national defense acquisition agencies, platform engineers at full-system integrators, procurement officers at NATO allied commands, and aftermarket service directors at regional refurbishment facilities and refined through secondary validation against SEC 10-K filings from publicly traded defense conglomerates, customs and trade data for armored vehicle component flows, national defense budget appropriations documentation, and STANAG standardization committee records. Bottom-up build-ups of national procurement pipelines were triangulated against top-down market sizing from defense expenditure databases.
Variance decomposition across vehicle type, propulsion technology, end-user category, and regional procurement cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate aggregation weighted by procurement volume trajectories. Forecast inputs incorporated NATO fleet modernization timelines, US Army Climate Strategy implementation pacing, and EU Green Deal defense applicability development.
Forecasts assume regulatory continuity in US EPA and Germany KBA emissions certification regimes; material policy shifts would require re-modeling of hybrid-electric platform adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Military Ground Vehicle Actuators Market
Military Vehicles
Military Amphibious Vehicle Market
Military Vehicles
India Combat Vehicle Systems Market
Military Vehicles
Robotic Combat Vehicle (RCV) Market
Military Vehicles
Global Military Vehicle Electrification Market
Military Vehicles
Global Offshore Patrol Vessel (OPV) Market
Military Vehicles
Iran Defense Market
Military Vehicles
Russia Defense Market
Military Vehicles
Main Battle Tank Market
Military Vehicles
Military Land Vehicles Market
Military Vehicles
Riot Control Vehicle Market
Military Vehicles
Military Tank Container Market
Military Vehicles
Southeast Asia Defense Market
Military Vehicles
Destroyers Market
Military Vehicles
Amphibious Land Craft Market
Military Vehicles
Indonesia Defense Market