
 Russia Defense Market | 2026-2036
Russia Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Defense Market Analytics
A widening capability gap between state-backed conglomerates and specialized manufacturers is rotating capital allocation across the Russia Defense Market. Rostec leverages its sprawling industrial holdings to dominate vertically integrated production of armored vehicles and aircraft subsystems. Tactical Missiles Corporation anchors Russia's precision-strike industrial base through sustained R&D investment in cruise and ballistic missile technologies. Kalashnikov Concern JSC differentiates via specialization in small arms and unmanned combat platforms, occupying a niche that larger entities navigate less aggressively.
Russia Defense encompasses the research, development, production, and sustainment of military equipment spanning kinetic weapons, aerospace platforms, naval architecture, and electronic warfare systems, with specifications typically requiring hardened electronics rated for extreme temperature ranges and electromagnetic pulse resilience. The sector serves state security objectives through force projection, territorial defense, and strategic deterrence. Aircraft and missile product categories command the dominant share of procurement budgets, reflecting structural prioritization of long-range strike and air dominance capabilities. Cybersecurity technology within the broader technology dimension represents the fastest-expanding segment, as digital infrastructure protection attracts disproportionate investment relative to legacy electronic systems.
Russia's defense industrial complex operates under oversight from the Ministry of Defence, the Federal Service for Technical and Export Control, and state military standards (GOST-R/GOST-OV) that prescribe technical parameters for equipment acceptance. These frameworks shape demand by mandating domestic content thresholds and certifying only locally produced components for critical weapons platforms. The Federal Antimonopoly Service additionally regulates consolidation patterns among prime contractors. Stakeholders must monitor how export control tightening and technology sovereignty mandates reshape supplier qualification criteria and program participation rights.
Market Dynamics
Import substitution mandates under Russia's Federal Service for Technical and Export Control are forcing defense contractors to replace Western-sourced components with domestic alternatives, compressing supplier qualification timelines and elevating GOST-R certification requirements across all procurement tiers.
Growth Catalysts
- State Armament Program mandates:The Russian Ministry of Defence maintains multi-year procurement commitments for precision-strike systems, creating predictable demand visibility for missile subsystem manufacturers.
- Electronic warfare modernization:Hardened electronics rated for electromagnetic pulse resilience attract disproportionate R&D allocation, as battlefield survivability specifications tighten across airborne platforms.
- Siberian industrial cluster expansion:Relocated production facilities in Novosibirsk and Tomsk regions reduce supply chain exposure to Western sanctions while tapping established aerospace engineering labor pools.
Market Restraints
- Semiconductor input scarcity:Advanced node chips remain unavailable through formal import channels, forcing redesigns around legacy 90nm+ fabrication processes with performance trade-offs.
- Dual-use technology export controls:Wassenaar Arrangement restrictions block acquisition of precision machining equipment, limiting tolerance capabilities in turbine blade and guidance component production.
- Technical limitation in composite materials:Carbon fiber prepregs with aerospace-grade thermal stability lack qualified domestic substitutes, constraining airframe weight reduction programs.
Strategic Opportunities
- Unmanned combat aerial vehicle expansion:Kalashnikov Concern and specialized entrants are scaling production of strike-capable drones, opening subsystem sourcing requirements for propulsion and guidance modules.
- Cybersecurity technology convergence:Military-grade encryption and intrusion detection systems for critical infrastructure protection represent underdeveloped white space with civilian-military dual applicability.
- Arctic logistics infrastructure:Northern Sea Route militarization programs generate demand for ice-rated naval architecture and polar-hardened communications equipment from specialized yards.
Industry Challenges
- Systems engineering talent compression:Soviet-era aerospace and missile design expertise is aging out without equivalent pipeline depth in integrated avionics and software-defined systems.
- GOST-OV certification timeline elongation:Expanded testing protocols for electromagnetic compatibility and environmental hardening extend platform acceptance schedules by 18-24 months.
- Legacy platform integration friction:New digital subsystems must interface with analog-era Soviet airframes and armored vehicles through costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Defense Market |
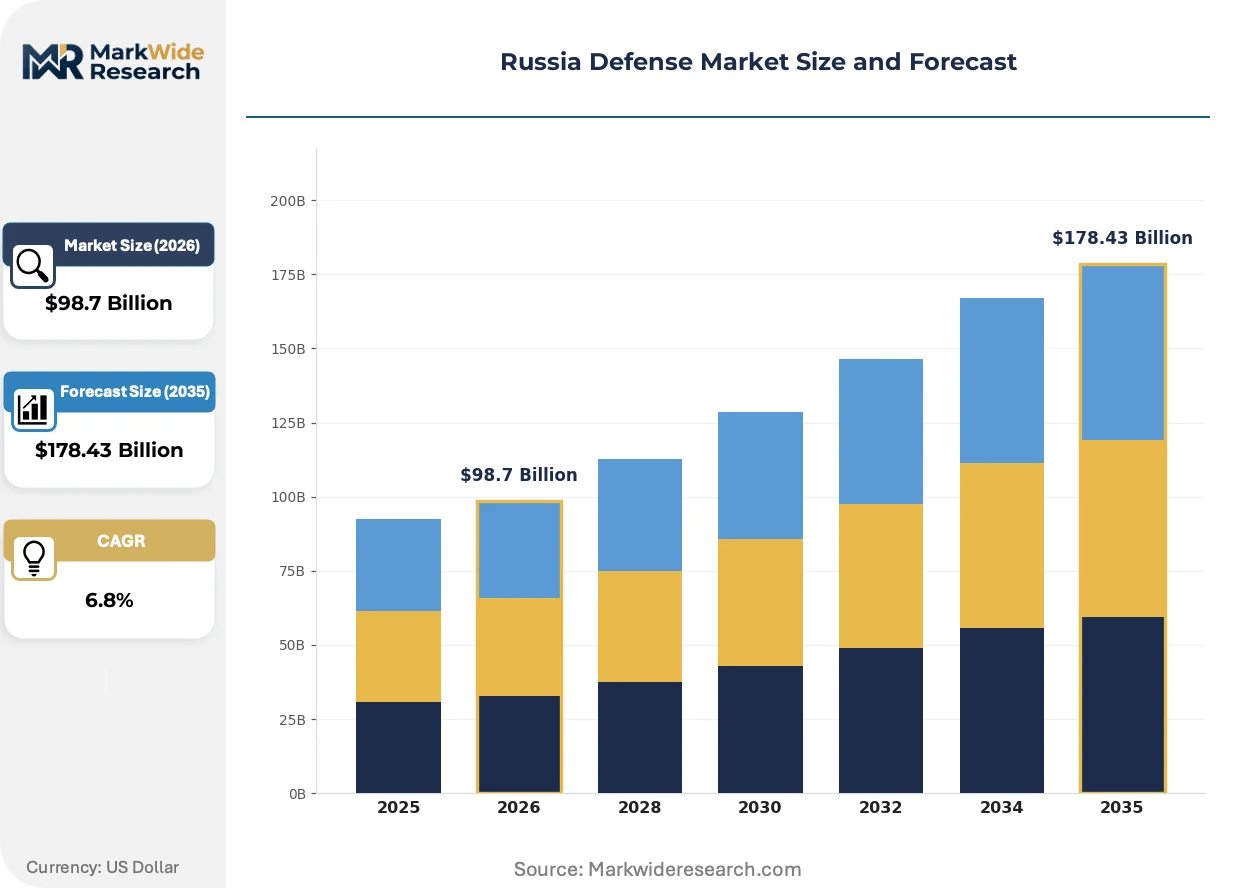
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aircraft, Missiles, Naval Vessels, Armored Vehicles Technology: Telecommunications, Cybersecurity, Surveillance Systems, Weapon Systems End User: Military, Government, Defense Contractors, Research Institutions Application: Combat Operations, Intelligence Gathering, Training, Logistics |
| Companies Covered | Almaz-Antey Air and Space Defence Corporation, United Aircraft Corporation, United Shipbuilding Corporation, Kalashnikov Concern JSC, Russian Helicopters JSC, Tactical Missiles Corporation, Uralvagonzavod, Rostec, United Engine Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Defense Market Evolving Landscape
Digital infrastructure protection is commanding R&D priority over legacy electronic warfare systems, while manufacturing processes adapt to sanctions-constrained supply environments through materials substitution and process requalification.
Hypersonic glide vehicle technology is bifurcating Russia's missile industrial base between established cruise missile architectures and scramjet-powered maneuvering reentry vehicles. Tactical Missiles Corporation and specialized design bureaus are diverging engineering teams to pursue both trajectories simultaneously. This technological split is compressing supplier consolidation as component requirements diverge sharply between thermal protection systems and traditional turbine propulsion.
Russia's Federal Antimonopoly Service has intensified scrutiny of defense contractor consolidation patterns, requiring pre-approval for vertical acquisitions exceeding threshold asset values. This regulatory friction is slowing Rostec's integration of specialized subsystem suppliers while creating compliance overhead for mid-tier manufacturers seeking scale. The aircraft segment faces the most pronounced approval delays as the service examines market concentration in avionics and propulsion categories.
Defense procurement is fragmenting across multiple state entities beyond the Ministry of Defence, with Roscosmos, Rosatom, and the National Guard establishing independent technical specifications and supplier qualification pathways. This buyer proliferation is fragmenting volume concentration and forcing manufacturers to maintain parallel certification tracks. The shift is most visible in secure communications equipment, where domestic security services specify distinct encryption standards from military procurement frameworks.
Russia Defense Market Segmentation
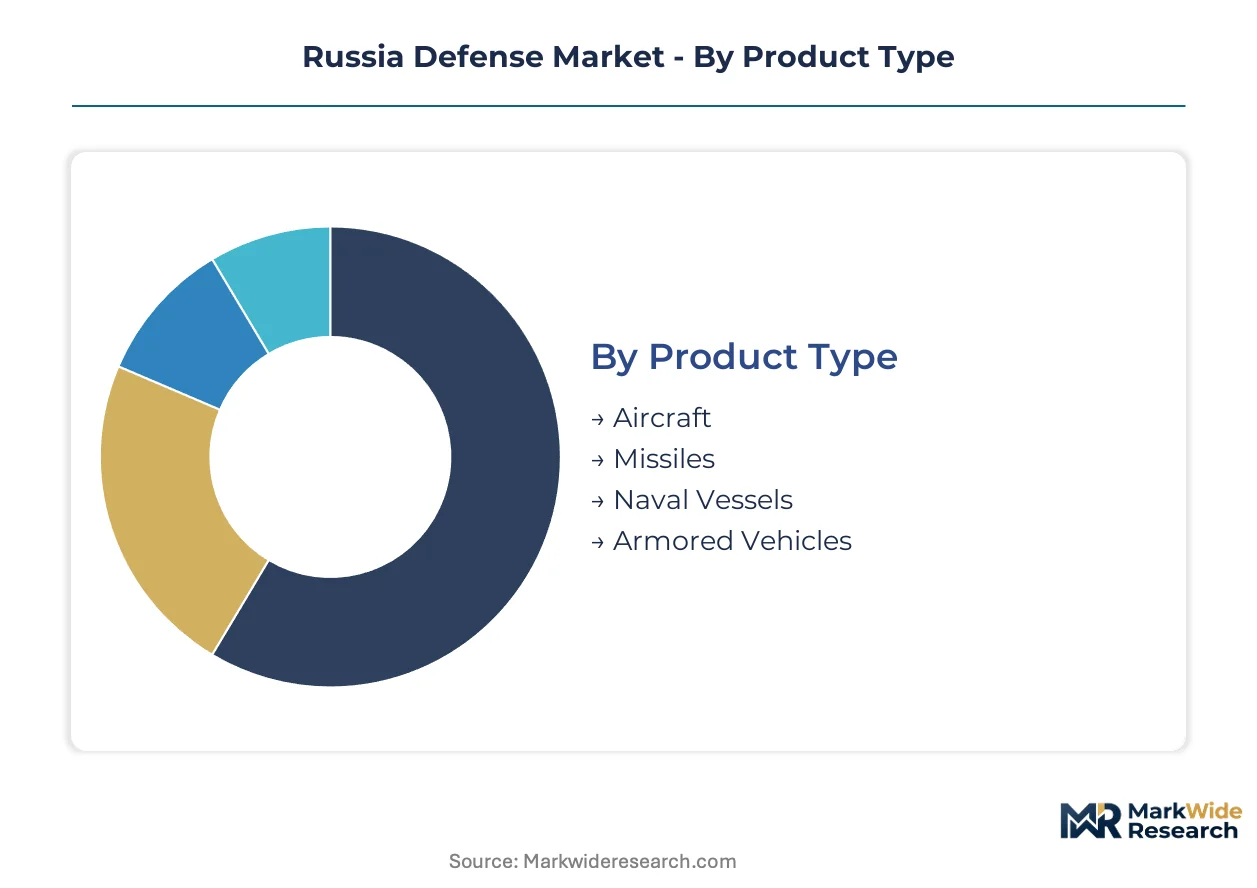
Defense procurement in Russia fragments across four distinct classification axes, each revealing divergent margin structures and qualification barriers. Understanding where capital concentrates within these categories illuminates supplier positioning requirements and technology investment priorities.
Product Type:
Margin pools concentrate in platforms requiring sustained R&D amortization and long-tail sustainment contracts.
- Aircraft:Fixed-wing and rotary platforms demand hardened avionics rated for electromagnetic pulse resilience. Procurement from the Russian Ministry of Defence prioritizes air superiority configurations, though semiconductor input scarcity forces redesigns around legacy fabrication nodes.
- Missiles:Cruise and ballistic architectures anchor precision-strike modernization programs. Tactical Missiles Corporation dominates vertically integrated production, capturing disproportionate allocation through scramjet and hypersonic glide vehicle development.
- Naval Vessels:Surface combatants and submarines require ice-rated hull architectures for Arctic logistics infrastructure.
- Armored Vehicles:Rostec controls subsystem integration for main battle tanks and infantry fighting vehicles.
The dominant share belongs to Aircraft, while Missiles is closing the gap fastest.
Technology:
Application intensity varies sharply between legacy electronic systems and digitally-native architectures.
- Weapon Systems:Kinetic effectors and directed-energy prototypes absorb capital through materials science investment in thermal protection and propulsion.
- Cybersecurity:Military-grade encryption and intrusion detection for critical infrastructure protection attracts disproportionate spend relative to legacy electronic warfare. Roscosmos and the National Guard specify distinct encryption standards from military frameworks.
- Surveillance Systems:Signals intelligence and electro-optical platforms serve intelligence gathering applications.
- Telecommunications:Polar-hardened communications equipment supports Northern Sea Route militarization.
Weapon Systems retains procurement priority, though Cybersecurity exhibits the steepest expansion trajectory.
End User:
Buyer fragmentation across state entities reshapes supplier qualification pathways and certification overhead.
- Military:The Russian Ministry of Defence maintains multi-year procurement commitments through State Armament Program mandates.
- Government:Civil security agencies specify distinct technical parameters from defense frameworks.
- Defense Contractors:Prime manufacturers source subsystems under GOST-R domestic content thresholds.
- Research Institutions:Design bureaus prototype hypersonic and unmanned platforms ahead of production transfer.
Military commands the dominant share, while Research Institutions is gaining share fastest through technology maturation pipelines.
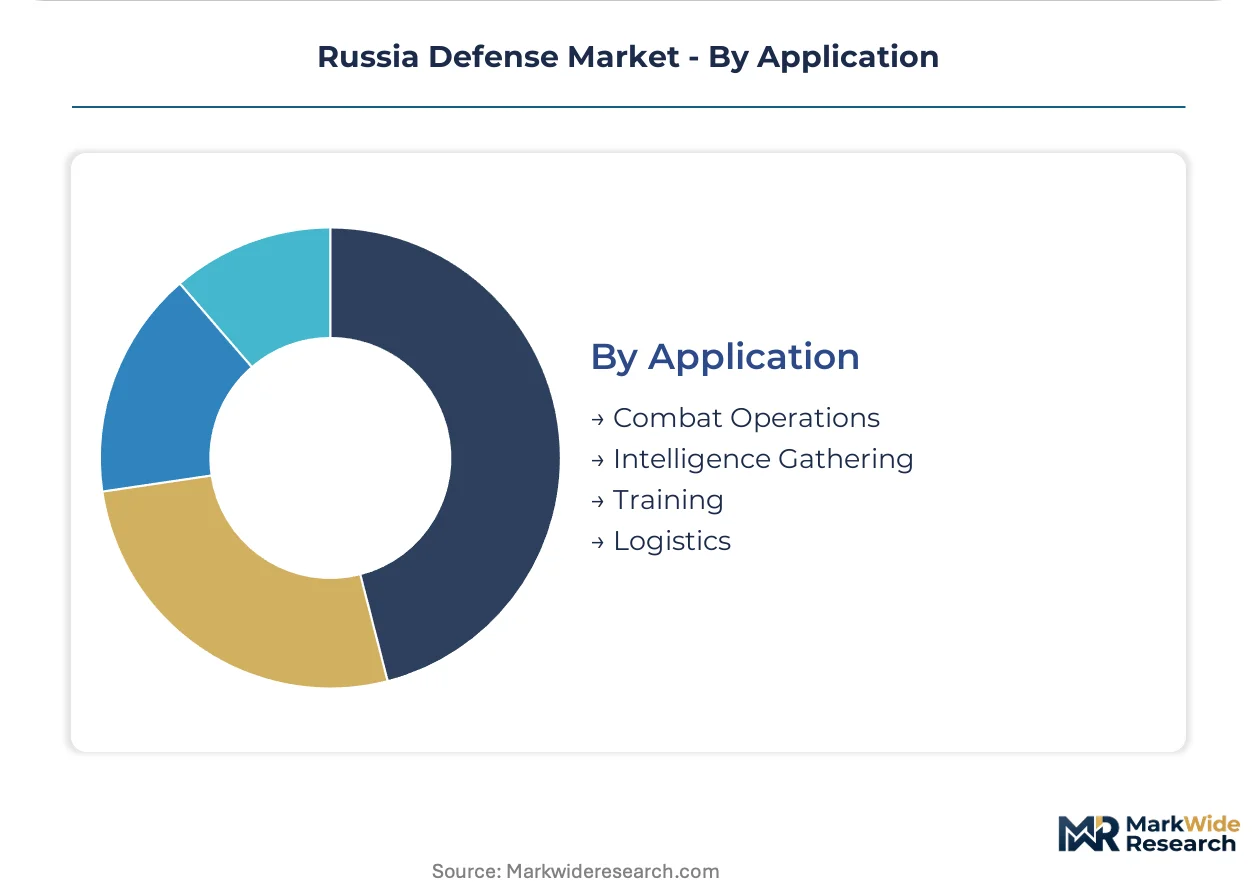
Application:
Operational tempo and platform utilization rates determine lifecycle revenue capture for sustainment providers.
- Combat Operations:Force projection requirements drive aircraft and missile procurement prioritization.
- Intelligence Gathering:Surveillance and signals platforms serve territorial defense and strategic deterrence objectives.
- Training:Simulator systems and live-fire ranges absorb capital through synthetic environment development.
- Logistics:Arctic infrastructure and Siberian industrial cluster expansion generate demand for polar-rated equipment.
Combat Operations holds the dominant share, while Logistics is expanding most quickly through geographic repositioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement elasticity varies sharply across Russian sub-regions, with Siberian industrial clusters showing lowest price sensitivity due to strategic relocation mandates, while legacy Volga-Ural facilities face acute cost pressure from component scarcity and certification delays.
Central Federal District
The Moscow Oblast concentration drives highest-value procurement through Ministry of Defence headquarters proximity and Roscosmos independent specifications. The Federal Service for Technical and Export Control enforces GOST-OV certification timelines that extend platform acceptance by 18-24 months. Khrunichev State Research and Production Space Center anchors aerospace design bureau clustering in the capital region.
Volga Federal District
Tatarstan and Samara Oblast sustain missile production through Tactical Missiles Corporation vertical holdings and TsSKB-Progress design heritage. State Armament Program multi-year commitments provide demand visibility for precision-strike subsystem manufacturers. Kazan and Samara cities concentrate scramjet propulsion research and hypersonic glide vehicle thermal protection development.
Siberian Federal District
Novosibirsk and Tomsk regions absorb relocated production facilities to reduce Western sanctions exposure, tapping established aerospace engineering labor pools from Soviet-era aircraft design bureaus. The Federal Antimonopoly Service intensifies scrutiny of defense contractor consolidation patterns affecting regional acquisition thresholds. Chkalov Aviation Plant and Tomsk-based electronics manufacturers expand polar-hardened communications equipment output.
Southern Federal District
Rostov Oblast and Krasnodar Krai concentrate armored vehicle subsystem integration under Rostec industrial holdings, with Uralvagonzavod affiliate facilities serving ground force modernization. Domestic content thresholds under import substitution policies redirect supply chains toward qualified local producers. Taganrog and Rostov-on-Don anchor unmanned combat aerial vehicle scaling for strike-capable drone production.
Northwestern Federal District
St. Petersburg and Severodvinsk sustain naval architecture through United Shipbuilding Corporation ice-rated hull construction for Arctic logistics infrastructure. The Northern Sea Route militarization programs generate demand for specialized yards capable of polar-rated vessel production. Admiralty Shipyards and Sevmash concentrate submarine and surface combatant output with distinct technical specifications from military procurement frameworks.
Russia Defense Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Russia Defense Market, with state-backed conglomerates dominating capital-intensive platform integration while specialized manufacturers capture niche subsystem margins. The structure consolidates around vertically integrated holdings with sprawling industrial assets, creating tiered access to Ministry of Defence procurement channels. Three archetypes define competitive positioning: diversified state corporations controlling multiple product categories, focused missile and aerospace specialists with captive R&D pipelines, and agile unmanned systems entrants scaling through modular subsystem sourcing. Dominant competitive moves include geographic relocation to Siberian industrial clusters and parallel certification track maintenance for fragmented state buyer proliferation.
Within the state corporation tier, Rostec exemplifies diversified holding architecture spanning armored vehicles, aircraft subsystems, and electronic warfare components. Tactical Missiles Corporation and United Aircraft Corporation occupy positions as specialized platform integrators with established Ministry of Defence supply relationships. Kalashnikov Concern JSC represents the agile specialist archetype, differentiating through small arms heritage and unmanned combat platform scaling.
| Leading Market Players |
|---|
| Almaz-Antey Air and Space Defence Corporation |
| United Aircraft Corporation |
| United Shipbuilding Corporation |
| Kalashnikov Concern JSC |
| Russian Helicopters JSC |
| Tactical Missiles Corporation |
| Uralvagonzavod |
| Rostec |
| United Engine Corporation |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four month GOST-OV certification timelines compress supplier cash conversion cycles and amplify pricing power for qualified domestic producers holding Ministry of Defence contracts. This lead-time rigidity forces tier-two manufacturers to absorb inventory carrying costs while prime contractors capture margin through after-sales bundling.
Pricing Analysis
After-sales service contracts and multi-year sustainment agreements drive lifetime value capture for platform integrators. The dominant pricing structure rests on long-term contract-based offtake with volume-scale differentiation separating strategic procurement from spot acquisitions. Pricing pressure stems from semiconductor input scarcity forcing redesigns around legacy fabrication nodes with performance trade-offs. State Armament Program participants exhibit lowest price sensitivity due to mandated procurement commitments, while research institutions face acute cost compression from parallel certification track requirements.
Supply Chain Analysis
China and South Korea anchor legacy semiconductor wafer supply for 90nm+ fabrication processes that Russian defense contractors now redesign around. The supply chain draws from domestic Tomsk and Novosibirsk electronics clusters for polar-hardened communications equipment while turbine blade machining remains tethered to German and Japanese precision equipment now blocked under Wassenaar Arrangement restrictions. Single-source vulnerability concentrates in carbon fiber prepreg inputs lacking qualified domestic substitutes. Distribution runs through vertically integrated Rostec holdings and Tactical Missiles Corporation captive production networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia Defense Market expansion sits in early-cycle acceleration as Arctic logistics infrastructure militarization and hypersonic platform maturation drive penetration into unmanned systems and cybersecurity subsystems.
For Market Incumbents: Shield program participation rights through accelerated GOST-R certification investment for electromagnetic pulse-hardened avionics. Deepen backward integration into Novosibirsk semiconductor packaging to reduce Wassenaar Arrangement exposure. Consolidate specialized subsystem suppliers ahead of Federal Antimonopoly Service threshold reviews. For New Entrants and Emerging Players: GOST-OV fast-track pathways for unmanned combat aerial vehicle subsystems open accessible entry points. Polar-hardened communications equipment for Northern Sea Route programs represents the most penetrable white space. Pursue modular propulsion sourcing relationships with Kalashnikov Concern strike-drone scaling programs. For Investors and Strategic Acquirers: Long-term, this sits as a state-mandated import substitution play because Federal Service for Technical and Export Control domestic content thresholds permanently reorient supply chains toward qualified local producers. Acquisition targets cluster around mid-tier electromagnetic compatibility testing laboratories and Siberian-based electronics packaging facilities. Watch Federal Antimonopoly Service pre-approval velocity for vertical integration attempts as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Siberian Production Relocation | Novosibirsk and Tomsk facilities reduce Western sanctions exposure while tapping Soviet-era aerospace engineering labor pools. |
| Hypersonic Glide Vehicle R&D Scale-Up | Tactical Missiles Corporation scramjet development captures disproportionate State Armament Program allocation. |
| Unmanned Combat Aerial Vehicle Production Scaling | Kalashnikov Concern strike-drone programs generate subsystem sourcing demand for propulsion modules. |
| Domestic Semiconductor Packaging Investment | Legacy 90nm+ fabrication redesigns require qualified local back-end processing under import substitution mandates. |
| Arctic Logistics Infrastructure Expansion | Northern Sea Route militarization programs demand ice-rated naval architecture from United Shipbuilding Corporation yards. |
Research Methodology
Initial hypotheses were tested against primary input from Ministry of Defence procurement officers, design bureau chief engineers, Federal Service for Technical and Export Control certification specialists, and Rostec subsidiary program managers and refined through secondary validation. Defense industrial base assessments drew from GOST-R technical documentation, customs substitution tracking data, State Armament Program budget disclosures, and Federal Antimonopoly Service consolidation filings. Bottom-up platform production estimates triangulated against top-down procurement budget allocations.
Variance decomposition across product type, technology intensity, end-user entity, and regional production cluster dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segmented volume build-ups incorporating platform lifecycle sustainment revenue recognition patterns. Forecast inputs included semiconductor node availability constraints and GOST-OV certification timeline elasticity assumptions.
Underlying assumptions cover sustained Federal Service for Technical and Export Control enforcement intensity and State Armament Program multi-year commitment continuity, with deviation risk concentrated in Wassenaar Arrangement expansion and dual-use technology control tightening. Recalibration cycles align with material shifts in domestic semiconductor qualification progress and Arctic infrastructure appropriation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Japan Defense Market
Military Vehicles
Amphibious Land Craft Market
Military Vehicles
Military Tank Container Market
Military Vehicles
Eastern Europe Defense Market
Military Vehicles
Middle East Military Vehicles Market
Military Vehicles
Main Battle Tank Market
Military Vehicles
Global Military Vehicle Electrification Market
Military Vehicles
Global Offshore Patrol Vessel (OPV) Market
Military Vehicles
India Combat Vehicle Systems Market
Military Vehicles
Indonesia Defense Market
Military Vehicles
Riot Control Vehicle Market
Military Vehicles
Infantry Fighting Vehicle (IFV) Market
Military Vehicles
Taiwan Defense Market
Military Vehicles
Combat Support Vehicle Market
Military Vehicles
Military Ground Vehicle Actuators Market
Military Vehicles
Southeast Asia Defense Market