
 Military Vehicle & Aircraft Protection Systems Market | 2026-2036
Military Vehicle & Aircraft Protection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Military Vehicle & Aircraft Protection Systems Market Insights
Israeli armor producers is broadening composite manufacturing capacity to meet surging export orders for vehicle protection kits. Plasan leverages its expertise in lightweight vehicle armor to dominate NATO light tactical vehicle programs. Rheinmetall AG sustains engineering leadership through integrated active protection system development across European land platforms. General Dynamics anchors North American supply chains with captive production of ballistic-grade aluminum and ceramic matrix composites for ground combat vehicles.
Military vehicle and aircraft protection systems encompass engineered materials and active mechanisms designed to defeat kinetic threats, directed energy, and electromagnetic attack through layered defense architectures typically rated to STANAG 4569 or MIL-STD-810 ballistic and blast specifications; their primary purpose is preserving crew and platform survivability across contested operational environments. Armor plating and active protection systems together command the largest share of procurement budgets as legacy vehicle fleets undergo systematic retrofit cycles, while electronic countermeasures represent the fastest-expanding technology category as peer adversaries field precision-guided munitions with multi-spectral seekers. Reactive armor and radar jamming technologies concentrate margin pools where specialized foundries and gallium nitride semiconductor fabs face capacity constraints.
The US Department of Defense mandates MIL-STD-810 and STANAG 4569 compliance through NHTSA-aligned survivability protocols, while the EU Green Deal and REACH regulations restrict hexavalent chromium in surface treatments, compelling coating reformulation across European supply chains. NATO's standardization office enforces interoperability requirements that shape cross-border procurement patterns and vendor qualification timelines. Stakeholders must monitor how emerging directed-energy threats reshape material specifications and whether domestic rare earth processing capacity constrains next-generation armor ceramic production.
Market Dynamics
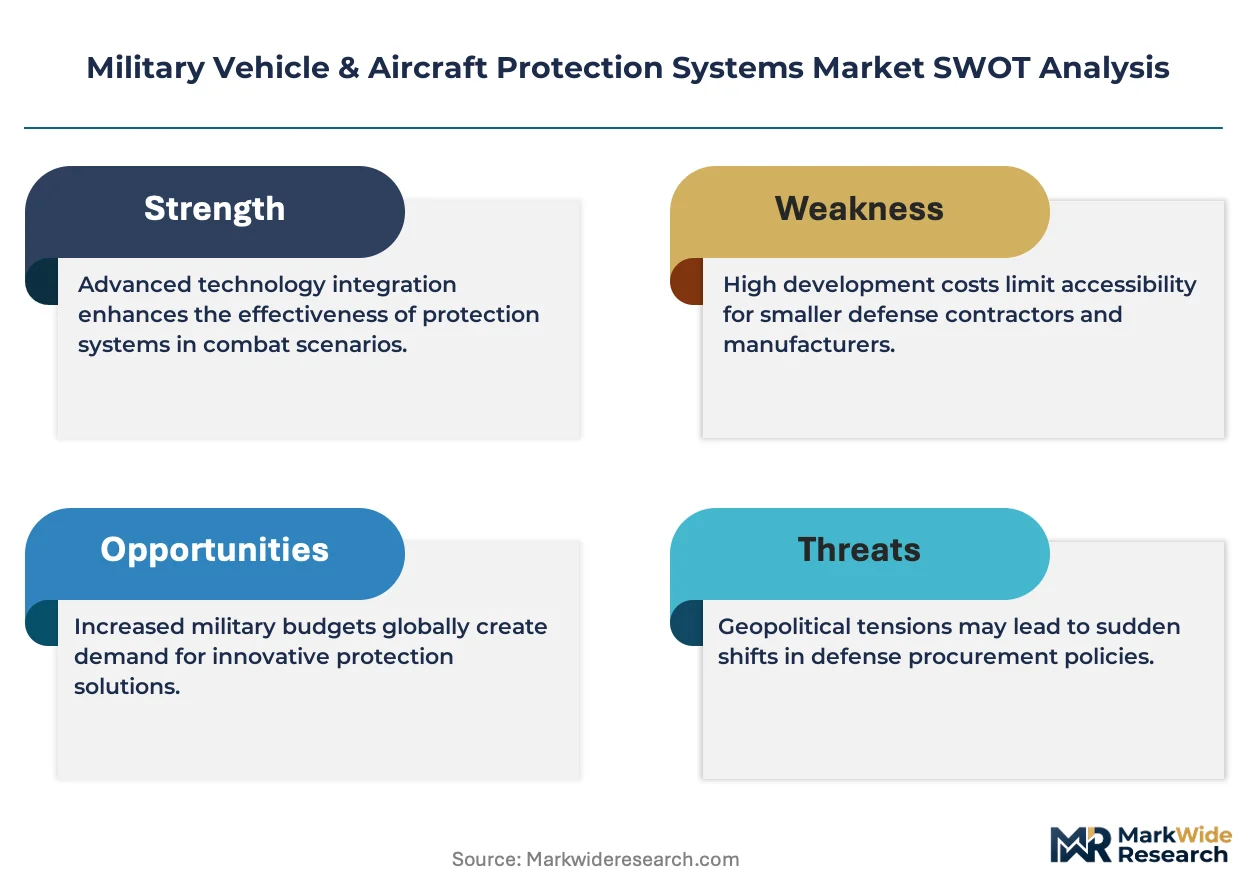
The transition from passive to active protection architectures is compressing procurement cycles across NATO armored vehicle programs, forcing material suppliers to requalify composite-ceramic arrays under accelerated STANAG 4569 timelines.
Growth Catalysts
- STANAG 4569 ballistic certification mandates:European defense ministries are retrofitting legacy fleets with composite-ceramic arrays, creating sustained demand for advanced armor foundries.
- Directed-energy weapon proliferation:Peer adversary fielding of high-energy lasers is accelerating investment in electromagnetic shielding and thermal management materials for vehicle hulls.
- Army modernization programs:United States crew survivability priorities in next-generation combat vehicles are channeling procurement budgets toward integrated protection suites.
Market Restraints
- Rare earth oxide supply concentration:China controls 60-90% of global processing capacity for yttrium and cerium used in next-generation armor ceramics, creating input vulnerability.
- REACH hexavalent chromium restrictions:EU surface treatment regulations are forcing coating reformulation across European supply chains, extending qualification timelines.
- Gallium nitride fab capacity scarcity:Specialized semiconductor foundries face bottlenecks in producing radar jamming components for electronic countermeasure systems.
Strategic Opportunities
- Light tactical vehicle retrofit demand:NATO member states are upgrading unprotected transport fleets with bolt-on armor kits, opening aftermarket channels for composite manufacturers.
- Dual-use electromagnetic protection:Convergence of military hardening and commercial aerospace shielding standards is expanding addressable markets for specialized coating suppliers.
- Domestic rare earth processing incentives:United States Defense Production Act funding is reshoring critical mineral supply chains for armor ceramic precursors.
Industry Challenges
- STANAG 4569 recertification timelines:Material suppliers face 18-24 month validation cycles for new composite formulations, compressing R&D-to-revenue windows.
- Active-passive system integration complexity:Sensor fusion between radar warning receivers and hard-kill interceptors requires cross-vendor software harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Vehicle & Aircraft Protection Systems Market |
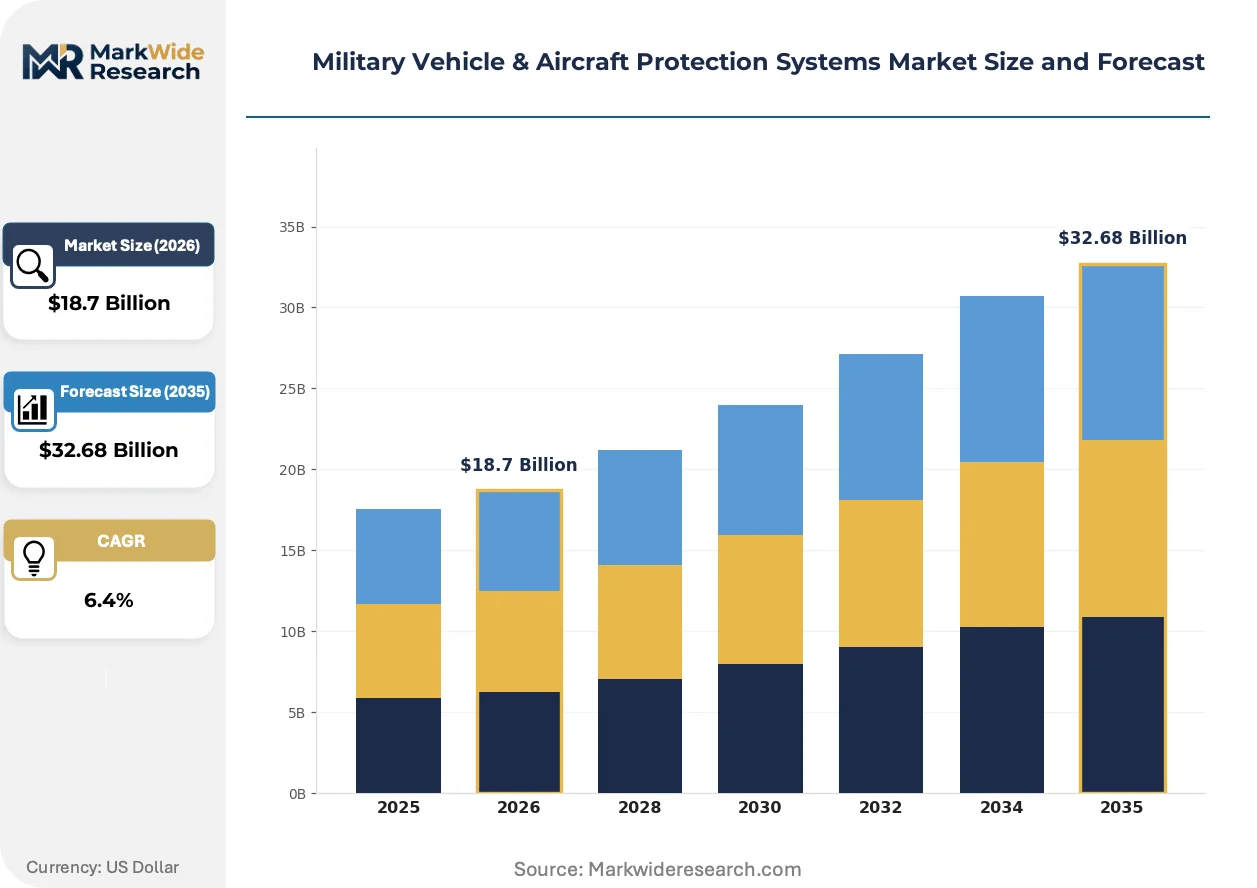
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Armor Plating, Active Protection Systems, Electronic Countermeasures, Blast Mitigation Materials, Fire Suppression Systems Technology: Reactive Armor, Stealth Coating, Radar Jamming, Infrared Countermeasures, Acoustic Sensors Application: Armored Vehicles, Fixed-Wing Aircraft, Rotary-Wing Aircraft, Unmanned Aerial Vehicles, Support Vehicles End User: Defence Forces, Paramilitary Units, Homeland Security, Peacekeeping Agencies, Tactical Response Teams |
| Companies Covered | Plasan, RUAG AG, General Dynamics, Amsafe Birdport, QinetiQ North America, Tencate Advanced Armor, MDT Armour, Rheinmetall AG, Ensign-Bickford, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Vehicle & Aircraft Protection Systems Market Trends and Innovations
Protection system architectures are bifurcating between weight-optimized passive materials and software-defined active interceptors, with procurement patterns favoring modular upgrade paths over monolithic platform redesigns.
Ceramic matrix composites are expanding into main battle hull applications as manufacturers demonstrate multi-hit survivability against tungsten penetrators. United States Army Ground Vehicle Systems Center is fast-tracking qualification of silicon carbide tiles for Bradley replacement programs. This material transition is expanding into supplier consolidation pressure as foundries require capital-intensive hot isostatic pressing equipment.
REACH regulations restricting hexavalent chromium in surface treatments are compelling European armor producers to adopt trivalent alternatives and plasma electrolytic oxidation coatings. ECHA enforcement timelines are compressing supplier transition windows to 24 months. German and French vehicle integrators are most affected, with coating reformulation costs flowing through to NATO procurement contracts.
Platform-as-a-service contracting is displacing traditional hardware purchase models for electronic warfare suites. United States Special Operations Command is piloting subscription-based access to threat library updates and countermeasure algorithms. This model is most visible in airborne self-protection systems, where software refresh cycles now outpace hardware replacement timelines.
Military Vehicle & Aircraft Protection Systems Market Segmentation
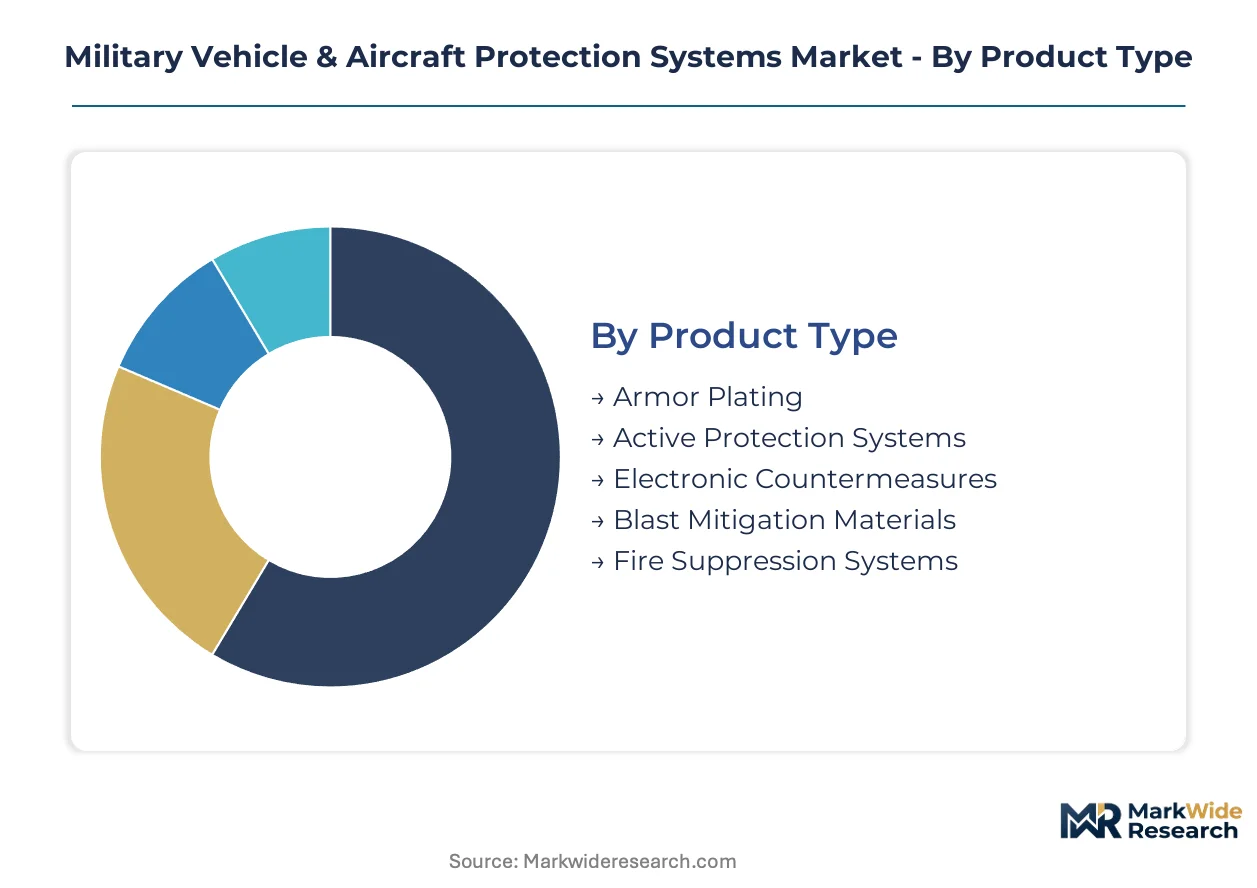
Military vehicle and aircraft protection systems fragment across multiple technical dimensions that reflect divergent procurement priorities among NATO defense ministries and allied forces. Upgrade cycles for legacy armored fleets create asynchronous demand patterns across product categories, while platform-specific survivability requirements drive technology selection. Understanding these segmentation boundaries clarifies where supplier capabilities align with buyer procurement roadmaps.
Product Type:
Retrofit-driven procurement across NATO armored vehicle fleets is compressing replacement timelines for legacy passive systems while accelerating active protection adoption.
- Armor Plating:Composite-ceramic arrays and ballistic-grade aluminum formulations rated to STANAG 4569 specifications dominate hull and turret applications. United States Army Ground Vehicle Systems Center procurement for Bradley replacement programs concentrates demand for silicon carbide tiles, though rare earth oxide supply constraints from Chinese processing dominance create input bottlenecks for next-generation formulations.
- Active Protection Systems:Hard-kill interceptors and soft-kill jammers integrated through sensor fusion architectures defeat kinetic threats before platform contact. Israeli and German engineering leadership in radar warning receiver integration is channeling NATO procurement toward European and Middle Eastern supply sources, with software-defined upgrade paths displacing hardware refresh cycles.
- Electronic Countermeasures:Gallium nitride semiconductor-based jamming suites address precision-guided munitions with multi-spectral seekers.
- Blast Mitigation Materials:Under-hull and seating-mounted composites absorb improvised explosive device energy.
- Fire Suppression Systems:Halon-alternative agents and condensed aerosol technologies protect crew compartments and engine bays.
Volume placements concentrate in Armor Plating; the faster expansion belongs to Active Protection Systems.
Technology:
Cost-tier stratification separates mature passive technologies from emerging active and signature-management systems requiring specialized manufacturing infrastructure.
- Reactive Armor:Explosive-filled tiles detonate outward to disrupt shaped charge jets and kinetic penetrators, with specialized foundry capacity constraints limiting supplier entry. German and Israeli arsenals maintain the deepest operational experience, driving standardization across NATO procurement specifications for main battle tank upgrades.
- Stealth Coating:Radar-absorbent materials and infrared-suppressive surface treatments reduce platform detectability across multiple spectrums. United States Air Force Next Generation Air Dominance program requirements are pulling coating formulation toward broader bandwidth absorption, though REACH hexavalent chromium restrictions force European suppliers into accelerated trivalent alternative qualification.
- Radar Jamming:Gallium nitride amplifier-based systems generate coherent interference against threat radars.
- Infrared Countermeasures:Directional jamming and decoy dispensing defeat heat-seeking missiles.
- Acoustic Sensors:Gunfire and blast detection arrays provide threat localization for crew warning.
Procurement volumes favor Reactive Armor; Stealth Coating is climbing the fastest as directed-energy threats proliferate.
Application:
Platform-specific survivability requirements create distinct material specifications, with crewed systems demanding higher protection levels than unmanned alternatives.
- Armored Vehicles:Main battle tanks, infantry fighting vehicles, and light tactical platforms integrate layered passive-active protection architectures. United States Army modernization programs for next-generation combat vehicles are the dominant demand source, with bolt-on armor kit retrofits for unprotected transport fleets opening aftermarket channels.
- Fixed-Wing Aircraft:Fast jets and transport aircraft require lightweight electromagnetic shielding and self-protection suites. NATO airborne early warning and electronic attack platforms drive integrated countermeasure procurement, with platform-as-a-service contracting models displacing traditional hardware purchases for threat library updates.
- Rotary-Wing Aircraft:Helicopters combine infrared suppression, radar warning, and ballistic protection for low-altitude survivability.
- Unmanned Aerial Vehicles:Remotely piloted systems prioritize electronic protection over crew survivability, reducing armor mass requirements.
- Support Vehicles:Logistics and command platforms receive lower-tier protection upgrades compared to frontline combat systems.
Contract awards cluster in Armored Vehicles; Unmanned Aerial Vehicles are gaining share fastest as autonomous platform procurement accelerates.
End User:
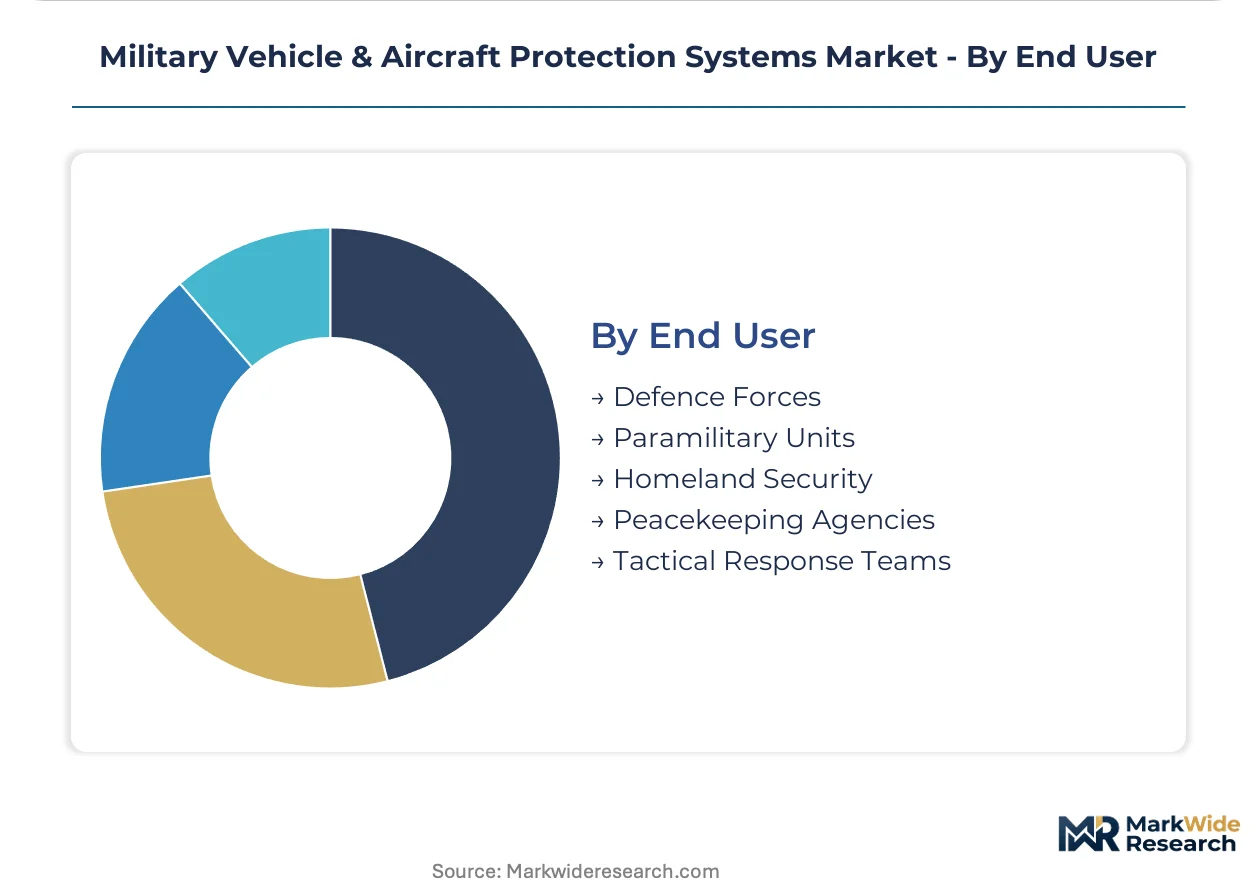
Customer-type segmentation reveals divergent procurement authority structures, with national defense ministries controlling capital expenditure while tactical units influence operational requirements.
- Defence Forces:National armies, navies, and air forces execute platform-level protection system procurement through defense ministry acquisition channels. United States Department of Defense MIL-STD-810 and STANAG 4569 compliance mandates shape supplier qualification requirements across NATO-aligned industrial bases.
- Paramilitary Units:Gendarmerie, coast guard, and border security forces acquire lighter protection suites for constabulary operations. European Union member state interior ministry budgets fund these acquisitions, with lighter threat profiles permitting cost-optimized material selections compared to military-grade specifications.
- Homeland Security:Domestic counterterrorism and critical infrastructure protection agencies deploy vehicle hardening against asymmetric threats.
- Peacekeeping Agencies:United Nations and regional stabilization missions lease protected mobility platforms from contributing nations.
- Tactical Response Teams:Special weapons and assault units require rapid-deployment protection for urban operations.
Budget authority concentrates in Defence Forces; Paramilitary Units show the steepest expansion trajectory as internal security priorities reshape procurement allocations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth oxide processing capacity in China anchors upstream material flows for armor ceramics, while NATO defense procurement concentrates demand generation across three allied industrial bases.
United States
Army modernization programs for next-generation combat vehicles drive composite-ceramic procurement through Ground Vehicle Systems Center channels. MIL-STD-810 and STANAG 4569 compliance mandates shape supplier qualification requirements. Michigan and Ohio manufacturing clusters host captive production of ballistic-grade aluminum and ceramic matrix composites for ground combat vehicle hulls.
Germany
Rheinmetall AG sustains engineering leadership through integrated active protection system development across European land platforms. REACH hexavalent chromium restrictions force coating reformulation across supplier networks, extending qualification timelines. Baden-Württemberg and Bavaria industrial corridors concentrate foundry capacity for reactive armor tile production.
Israel
Export orders for vehicle protection kits accelerate composite manufacturing capacity expansion at armor producers. Hard-kill interceptor and soft-kill jammer integration expertise channels NATO procurement toward Middle Eastern supply sources. Haifa and Beersheba defense technology clusters specialize in sensor fusion architectures for active protection systems.
United Kingdom
QinetiQ North America leverages transatlantic engineering presence to access United States defense procurement channels. ECHA enforcement timelines for surface treatment regulations compress supplier transition windows for British vehicle integrators. Midlands and South West England manufacturing regions concentrate blast mitigation material production for under-hull applications.
Military Vehicle & Aircraft Protection Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electronic warfare software-defined upgrade paths. The vendor base stratifies across three capability tiers: integrated platform suppliers, specialized armor foundries, and semiconductor component providers. Strategic archetypes include captive raw material producers, software-centric countermeasure developers, and dual-use electromagnetic protection specialists. Dominant competitive moves encompass strategic partnerships for sensor fusion integration and capacity expansion in gallium nitride semiconductor fabrication.
Among Israeli and European armor specialists, Plasan exemplifies lightweight vehicle armor production for NATO light tactical vehicle programs. Rheinmetall AG occupies a position within the integrated active protection system tier, anchoring European land platform engineering leadership. General Dynamics represents North American supply chain consolidation through captive production of ballistic-grade materials for ground combat vehicles.
| Leading Market Players |
|---|
| Plasan |
| RUAG AG |
| General Dynamics |
| Amsafe Birdport |
| QinetiQ North America |
| Tencate Advanced Armor |
| MDT Armour |
| Rheinmetall AG |
| Ensign-Bickford |
| Others |
Pricing and Supply Chain Analysis
Hot isostatic pressing equipment requirements for silicon carbide tile production are simultaneously concentrating foundry economics among capital-rich suppliers and compressing procurement timelines for STANAG 4569 recertification. This capital intensity reshapes cost structures across composite-ceramic armor supply chains while pricing power accrues to integrated producers with captive rare earth oxide processing.
Pricing Analysis
Platform-as-a-service contracting for electronic warfare suites bundles threat library subscriptions with hardware access, unbundling traditional capital expenditure into recurring operational budgets. Three-tier pricing structure across premium, standard, and economy levels separates integrated active protection systems from bolt-on armor kits and basic electronic countermeasures. Cost compression in standard-tier reactive armor reflects gallium nitride fab capacity scarcity. Paramilitary units exhibit highest price sensitivity due to interior ministry budget constraints, while United States Army modernization programs demonstrate lowest sensitivity for crew survivability investments.
Supply Chain Analysis
Reverse-logistics flows for refurbished active protection system interceptors and remanufactured radar warning receivers create secondary supply channels that compete with original equipment procurement. Production concentrates in the United States, Germany, and Israel, with Chinese rare earth oxide processing anchoring upstream ceramic precursor supply. Armor ceramic production draws from yttrium, cerium, and silicon carbide feedstocks. Single-source vulnerability in Chinese rare earth processing creates structural exposure. Distribution runs through defense ministry acquisition channels and NATO standardization office qualification pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active protection systems are displacing passive armor architectures as the dominant procurement priority, creating a technology-transition phase where software-defined interceptors replace monolithic hull materials.
For Market Incumbents: Anticipate margin compression in reactive armor foundries as ceramic matrix composites penetrate main battle tank applications. Defend position through backward integration into rare earth oxide processing and capacity expansion in gallium nitride semiconductor fabrication. Certification investment in STANAG 4569 Level 6 formulations represents the priority lever for platform integrator relationships. For New Entrants and Emerging Players: NATO light tactical vehicle retrofit demand offers the most penetrable white-space target, with unprotected transport fleet upgrades creating aftermarket channels outside prime contractor capture. Paramilitary units in European Union member states present secondary entry points with lighter threat profiles permitting cost-optimized material selections. Go-to-market execution should emphasize bolt-on armor kit modularity and accelerated qualification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in defense prime contractor acquisition of electronic warfare software specialists and active protection system integrators. Long-term viability hinges on positioning within Army modernization program supply chains rather than legacy platform retrofit cycles. Monitor United States Defense Production Act funding disbursements for domestic rare earth processing as the inflection signal for supply chain reshoring momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Active Protection System Integration | Sensor fusion expertise channels NATO procurement toward Israeli and German engineering sources. |
| Ceramic Matrix Composite Capacity Expansion | Hot isostatic pressing investments qualify silicon carbide tiles for Bradley replacement programs. |
| Rare Earth Processing Reshoring | Defense Production Act funding reduces Chinese supply concentration for armor ceramic precursors. |
| Platform-as-a-Service Contracting | Subscription models displace hardware purchases for United States Special Operations Command electronic warfare. |
| REACH-Compliant Coating Reformulation | Trivalent chromium alternatives extend qualification timelines for European vehicle integrators. |
Research Methodology
Document review covered defense ministry procurement databases, NATO standardization office specifications, and ECHA regulatory filings, complemented by interviews with program managers at Ground Vehicle Systems Center, procurement leads at European armor foundries, active protection system engineering directors, and threat library software developers. Secondary validation drew from MIL-STD-810 technical documentation, STANAG 4569 ballistic test protocols, and United States Department of Defense budget justification materials. Bottom-up and top-down triangulation reconciled platform-level procurement forecasts with material input demand models.
Segmentation outputs across the analysis window reflect product type, technology tier, platform application, and end-user authority structures, with CAGRs derived from defense ministry capital expenditure trajectories and retrofit cycle timing. Modeling incorporated Army modernization program roadmap disclosures, gallium nitride semiconductor fab capacity constraints, and rare earth oxide supply elasticity assumptions.
Revisions become necessary when directed-energy weapon fielding accelerates material specification changes, Chinese export controls on rare earth processing tighten, or REACH enforcement timelines compress coating reformulation windows. Practitioners should monitor Pentagon rapid prototyping program awards and NATO standardization office qualification backlog indicators for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Indonesia Defense Market
Military Vehicles
Military Ground Robots Market
Military Vehicles
Amphibious Land Craft Market
Military Vehicles
Japan Defense Market
Military Vehicles
Middle East Military Vehicles Market
Military Vehicles
Taiwan Defense Market
Military Vehicles
Combat Support Vehicle Market
Military Vehicles
Eastern Europe Defense Market
Military Vehicles
India Combat Vehicle Systems Market
Military Vehicles
Russia Defense Market
Military Vehicles
Military Unmanned Ground Vehicle Market
Military Vehicles
Riot Control Vehicle Market
Military Vehicles
Military Tank Container Market
Military Vehicles
Military Trucks Market
Military Vehicles
Military Ground Vehicle Actuators Market
Military Vehicles
Military Land Vehicles Market