
 Parabolic Antenna Market | 2026-2036
Parabolic Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Parabolic Antenna Market Insights
The parabolic antenna supply base is consolidating around a sharp split between precision-molded composite reflectors for defense and satellite operators versus stamped-aluminum dishes for consumer broadband. L3Harris Technologies Inc. anchors the premium tier through captive manufacturing of Ka-band terminals for military satellite programs. Guangdong Shenglu Telecommunication Tech. Co., Ltd. competes aggressively on cost for C-band broadcast downlinks across emerging markets. Cobham Limited differentiates through environmental qualification protocols that satisfy NATO and ITU-R standards for maritime and aerospace terminals.
A parabolic antenna is a directional microwave antenna that uses a curved paraboloid reflector surface, typically formed from aluminum alloys or carbon-fiber-reinforced composites with surface accuracy tolerances below one-tenth of the operating wavelength, to focus incoming or outgoing electromagnetic radiation onto a single feed horn at the focal point. These devices serve as the primary signal collection and transmission interface for satellite ground stations, deep-space communications networks, and meteorological radar installations worldwide. Offset configurations now lead in commercial satellite communications because their asymmetric feed placement eliminates aperture blockage and improves sidelobe performance for densely packed orbital slots. Ku-band and Ka-band frequency segments represent the fastest-expanding revenue pools as high-throughput satellites and non-geostationary constellations demand smaller beamwidths and higher gain-to-noise ratios. Prime-focus architectures remain entrenched in radio astronomy and deep-space research organizations where maximum aperture efficiency at L-band and S-band frequencies outweighs installation footprint constraints.
The FCC enforces Part 25 licensing for earth station transmitters while the ITU coordinates orbital slot and frequency assignments through Radio Regulations that directly shape antenna certification requirements for cross-border operations. ETSI in Europe and GB standards in China impose additional pattern envelopes and cross-polarization discrimination thresholds that manufacturers must satisfy for market access. Stakeholders must monitor spectrum reallocation proceedings and emerging quantum encryption payloads that could redefine feed assembly complexity and reflector precision specifications.
Market Dynamics
Spectrum coordination pressures from the FCC and ITU are forcing antenna manufacturers to retool feed assemblies for tighter Ka-band beamwidth compliance while low Earth orbit constellation operators multiply ground station purchase orders.
Growth Catalysts
- LEO Constellation Deployment:Satellite operators expanding ground station networks require thousands of compact high-gain terminals. This demand concentrates in India where ISRO's commercial arm and private space startups are building domestic manufacturing capacity.
- Ka-band Spectrum Allocation:The FCC's Part 25 licensing reforms and ITU Radio Regulations updates enable higher-frequency terminals with smaller apertures. Military and maritime end-users are accelerating procurement of these compact systems.
- Carbon-Fiber Reflector Adoption:Precision-molded composite manufacturing is displacing stamped aluminum for applications requiring surface accuracy below one-tenth wavelength. Defense contractors and deep-space research organizations drive this materials transition.
Market Restraints
- Aluminum Price Volatility:Stamped-aluminum dish producers face margin compression from raw material cost swings. Emerging market broadcast downlink suppliers compete primarily on price and lack pricing power to pass through input spikes.
- Precision Manufacturing Concentration:Molded composite reflector production clusters among defense-tier suppliers with captive autoclave capacity. New entrants face capital barriers and qualification timelines stretching multiple years.
- Phased Array Substitution:Electronically steered flat-panel antennas threaten parabolic designs for mobile platforms. Maritime and aerospace integrators are evaluating these alternatives for vessels and aircraft where mechanical steering adds failure modes.
Strategic Opportunities
- Indian Domestic Production:The country's national space regulator and ISRO commercial policies incentivize local antenna manufacturing. Foreign suppliers can partner with emerging domestic fabricators to meet constellation operator procurement mandates.
- Quantum Encryption Payload Integration:Feed assembly complexity will expand to accommodate quantum key distribution hardware. Early alignment with satellite payload developers positions antenna suppliers for premium specification tiers.
- Environmental Qualification Services:NATO and ITU-R maritime certification protocols create recurring revenue streams. Cobham Limited's qualification methodology can be productized as a service for smaller manufacturers lacking in-house test infrastructure.
Industry Challenges
- Electromagnetic Simulation Talent Scarcity:Reflector design requires specialized expertise in physical optics and method-of-moments modeling. Defense contractors and prime satellite manufacturers are competing for the limited pool of antenna engineers trained in these methods.
- Cross-Border Certification Complexity:ETSI pattern envelopes, GB standards in China, and FCC Part 25 requirements create overlapping compliance obligations. Manufacturers serving multiple geographies must maintain parallel qualification test matrices.
- Legacy Ku-band Inventory Stranding:High-throughput satellite migration to Ka-band leaves existing ground station installations with depreciating asset values. Service providers face upgrade capex cycles before original equipment reaches end-of-design-life.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parabolic Antenna Market |
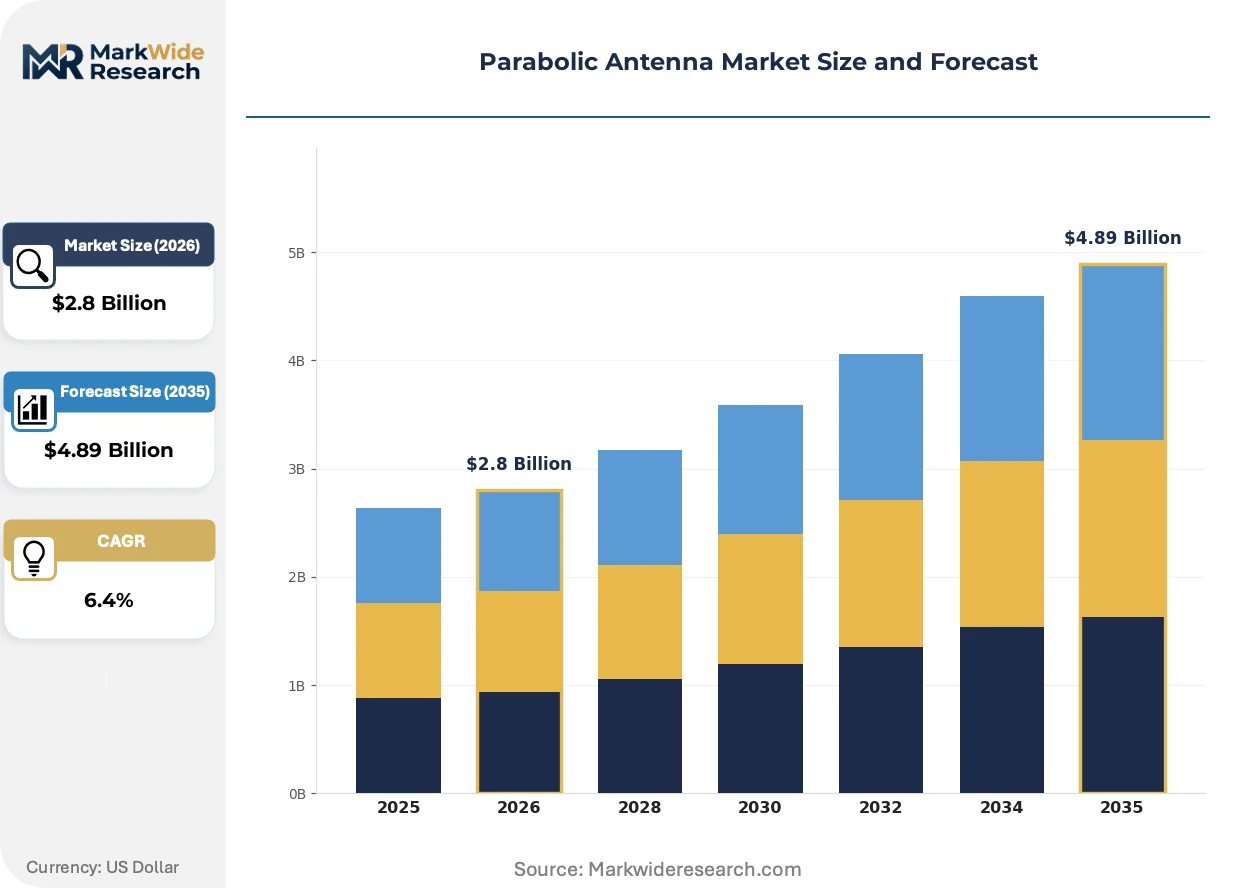
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Offset, Prime Focus, Cassegrain, Dual Reflector Frequency Band: L-Band, S-Band, C-Band, Ku-Band, Ka-Band Application: Broadcasting, Satellite Communications, Radar Systems, Space Communications End User: Telecommunication Providers, Defense Sector, Satellite Operators, Research Organizations |
| Companies Covered | TESSCO Technologies, Inc., Helander, Miwave Techno Ventures, Guangdong Shenglu Telecommunication Tech. Co., Ltd., Kenbotong Technology Co., Ltd., Antenna Research Associates, Inc., RadioWaves, Inc., Cobham Limited, L3Harris Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parabolic Antenna Market Trends and Innovations
Antenna architecture is bifurcating between precision composite systems for spectrum-constrained orbital slots and cost-optimized stamped metal for volume consumer broadband. Three developments are compressing design cycles and reshaping procurement patterns.
Carbon-fiber-reinforced composite reflector manufacturing is converging with automated fiber placement robotics to achieve surface tolerances previously requiring hand layup. L3Harris Technologies and defense-tier suppliers are adopting these production methods for Ka-band military terminals. The structural consequence is collapsing lead times for precision-molded reflectors while raising capital barriers for competitors lacking robotic fabrication.
The ITU's tightening Radio Regulations on Ka-band coordination are compressing sidelobe envelope requirements for cross-border operations. Manufacturers must redesign feed horn geometries and implement advanced shaping techniques to maintain market access. European satellite operators and ground station deployers are most affected, with ETSI pattern specifications now exceeding baseline ITU-R thresholds in several member states.
Constellation operators are unbundling antenna procurement from satellite service contracts, reversing historical bundled pricing models. Ground station as a service providers and independent network operators now source terminals through competitive tender rather than sole-source satellite operator channels. This behavioral shift concentrates in India and emerging Asian markets where private space startups are building independent ground infrastructure.
Parabolic Antenna Market Segmentation
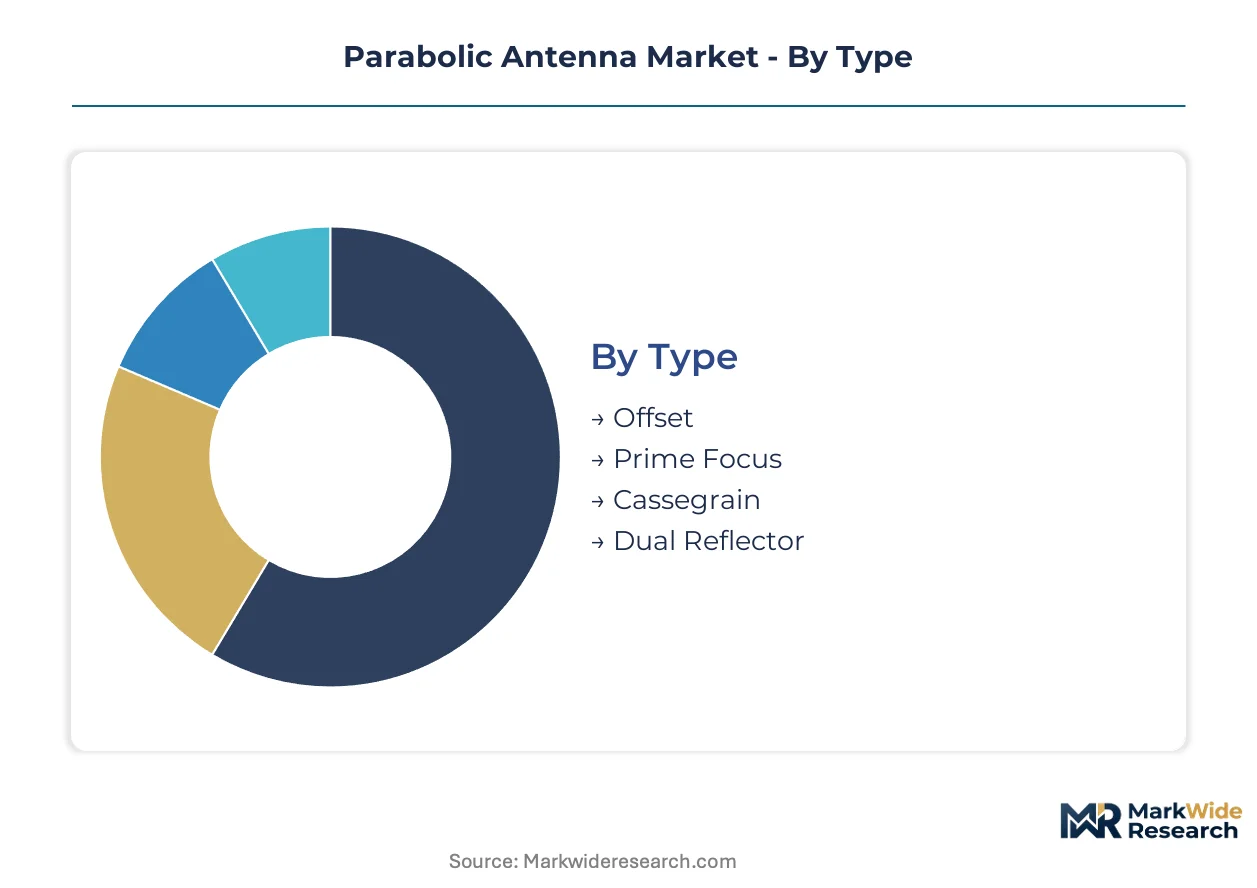
Parabolic antenna procurement patterns diverge sharply across architectural configurations and frequency specifications. Capital deployment intensity varies by surface precision requirements and spectrum licensing complexity, creating distinct investment profiles for each segment category.
Type:
Composite reflector molding and precision surface finishing drive capital intensity most acutely in asymmetric feed architectures.
- Offset:Asymmetric paraboloid geometry positions the feed horn outside the primary reflector aperture, eliminating blockage losses critical for densely packed orbital slots. Demand concentrates among commercial satellite operators deploying ground stations for high-throughput satellites, compelled by ITU sidelobe envelope tightening for Ka-band coordination.
- Prime Focus:Central feed placement at the paraboloid vertex maximizes aperture efficiency for single-frequency reception. Research organizations and deep-space networks in the United States and Europe anchor procurement, prioritizing L-band and S-band sensitivity over installation footprint constraints.
- Cassegrain:Secondary hyperbolic subreflector folds the optical path, enabling compact mechanical packaging for large apertures. Defense satellite programs specify these geometries for transportable military terminals.
- Dual Reflector:Gregorian and Cassegrain variants with shaped subreflectors achieve tailored illumination patterns for multi-band operation. Emerging satellite operators in India evaluate these configurations for ground station flexibility.
Most installed capacity flows through Offset. Expansion is steepest in Cassegrain.
Frequency Band:
Spectrum licensing costs and feed assembly complexity stratify capital requirements across microwave segments.
- L-Band:Lower frequencies penetrate atmospheric moisture with minimal attenuation, supporting maritime and aeronautical safety services. European ground station operators maintain legacy infrastructure for GPS augmentation networks.
- S-Band:Allocations balance propagation resilience with moderate antenna gain requirements. Weather radar installations and some space communications applications specify these frequencies.
- C-Band:Traditional broadcast downlink spectrum with established global coordination frameworks. Emerging market telecommunication providers in India and Southeast Asia continue deploying stamped-aluminum dishes for television distribution.
- Ku-Band:Direct-to-home satellite television and enterprise broadband terminals dominate volume procurement. Service providers face asset stranding risk as high-throughput satellites migrate spectrum.
- Ka-Band:Millimeter-wave frequencies enable compact apertures with high gain-to-noise ratios for non-geostationary constellations. FCC Part 25 licensing reforms and ITU Radio Regulations updates accelerate military and maritime procurement of these terminals.
Procurement volume concentrates in Ku-Band. Ka-Band is climbing the fastest.
Application:
Environmental qualification protocols and operational availability requirements determine upfront engineering investment.
- Broadcasting:C-band and Ku-band downlink reception for television distribution networks. Cost-optimized stamped-aluminum dishes serve emerging market cable headends.
- Satellite Communications:Two-way voice, data, and broadband services across fixed and mobile platforms. Ground station as a service providers in India unbundle terminal procurement from satellite operator contracts.
- Radar Systems:Weather monitoring, air traffic control, and surveillance applications requiring coherent pulse transmission. Precision surface tolerances and polarization purity specifications elevate capital requirements.
- Space Communications:Deep-space research and interplanetary probe support demanding maximum aperture efficiency. NASA and ESA facilities in the United States and Europe anchor demand for prime-focus architectures.
Deployment scale favors Satellite Communications. Technical complexity peaks in Space Communications.
End User:
Procurement authority centralization and qualification timeline tolerance shape supplier engagement economics.
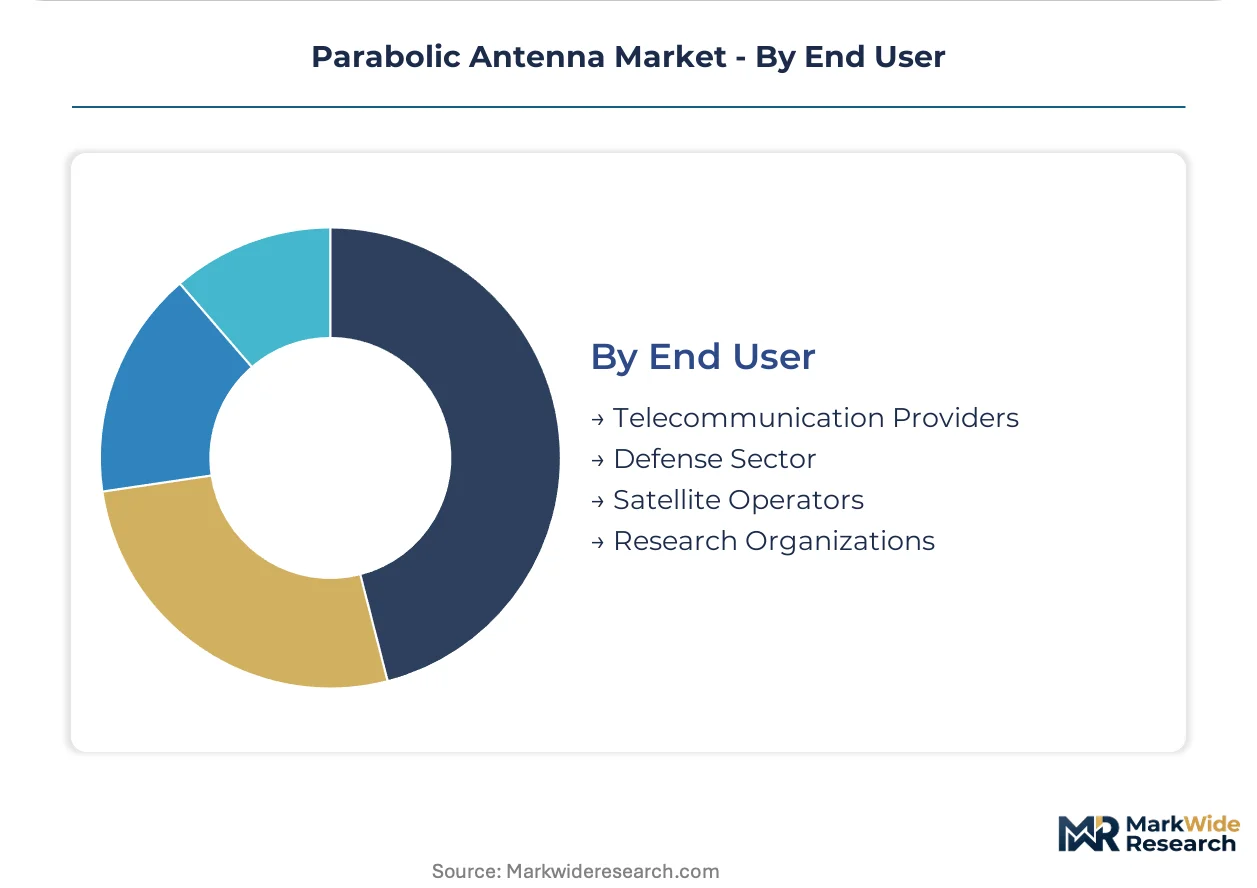
- Telecommunication Providers:Commercial ground station operators and broadband service retailers sourcing terminals through competitive tender. Indian private space startups build independent procurement channels.
- Defense Sector:Military satellite programs with captive supply chains and multi-year qualification horizons. L3Harris Technologies and defense-tier suppliers serve this tier through Ka-band terminal manufacturing.
- Satellite Operators:Constellation owners historically bundled antenna procurement with service contracts. Behavioral shift toward unbundled sourcing concentrates in emerging Asian markets.
- Research Organizations:Radio astronomy observatories and deep-space networks prioritizing aperture efficiency over cost. European and North American facilities specify prime-focus L-band and S-band systems.
Contract value concentrates with Defense Sector. Procurement velocity is gaining share fastest among Satellite Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antenna engineering talent clusters in defense hubs and satellite manufacturing corridors across five countries, concentrating procurement authority and qualification expertise in specific metropolitan zones.
United States
Military satellite programs and NASA deep-space networks drive precision reflector demand in California and Colorado. The FCC enforces Part 25 licensing for earth station transmitters with stringent Ka-band coordination rules. Huntsville, Alabama hosts concentrated defense contractor activity for transportable military terminals.
China
Domestic broadcast infrastructure and emerging constellation ground stations absorb stamped-aluminum and composite reflector output. GB standards impose pattern envelope and cross-polarization discrimination thresholds for market access. Guangdong province anchors manufacturing capacity for C-band broadcast downlinks serving Southeast Asian export markets.
India
ISRO's commercial arm and private space startups are expanding ground station networks for low Earth orbit constellations. The national space regulator incentivizes local antenna fabrication through procurement mandates for domestic operators. Bengaluru and Hyderabad clusters are building composite reflector autoclave capacity to meet qualification timelines.
Germany
European space research organizations and maritime integrators specify NATO-qualified terminals for aerospace applications. ETSI pattern specifications exceed baseline ITU-R thresholds in several member states, tightening sidelobe compliance. Bavaria hosts precision manufacturing for radio astronomy installations requiring prime-focus L-band sensitivity.
United Kingdom
Maritime satellite operators and defense satellite programs procure environmental-qualified terminals for naval platforms. ITU Radio Regulations coordination shapes antenna certification for cross-border North Sea operations. Cobham Limited's qualification methodology in Dorset anchors NATO and ITU-R maritime certification protocols.
Parabolic Antenna Market Competitive Landscape
Top-tier vendors anchor defense and satellite operator supply chains with captive manufacturing, while cost-optimized fabricators serve broadcast downlink volume. The supply base splits between precision-molded composite specialists and stamped-metal producers. Three archetypes dominate: defense-tier integrators with autoclave capacity, emerging-market cost competitors, and environmental qualification specialists. Consolidation pressure is accelerating through strategic partnerships and capacity expansion in Indian domestic production zones.
Among defense-tier suppliers, L3Harris Technologies Inc. occupies a position exemplifying captive Ka-band terminal manufacturing for military satellite programs. Guangdong Shenglu Telecommunication Tech. Co., Ltd. represents the cost-competitive archetype for C-band broadcast downlinks across emerging markets. Cobham Limited anchors the environmental qualification specialist tier, with its NATO and ITU-R maritime protocols serving as a reference methodology for certification-heavy segments.
| Leading Market Players |
|---|
| TESSCO Technologies, Inc. |
| Helander |
| Miwave Techno Ventures |
| Guangdong Shenglu Telecommunication Tech. Co., Ltd. |
| Kenbotong Technology Co., Ltd. |
| Antenna Research Associates, Inc. |
| RadioWaves, Inc. |
| Cobham Limited |
| L3Harris Technologies Inc. |
| Others |
Pricing and Supply Chain Analysis
Defense-tier integrators with captive autoclave capacity and sovereign-backed Indian producers anchor supply discipline, translating concentrated manufacturing control into pricing power across precision-molded composite tiers while cost-optimized stamped-aluminum segments compete on thin margins.
Pricing Analysis
The bundled-versus-unbundled service split now defines transaction structures. Subscription-based terminal leasing dominates constellation operator procurement, while project-based pricing persists for defense satellite programs. Price differentiation hinges on ITU-R certification grade and Ka-band sidelobe compliance thresholds. Cost compression in stamped-aluminum broadcast tiers intensifies because aluminum price volatility erodes fabricator margins. Emerging market telecommunication providers exhibit highest price sensitivity; military satellite programs demonstrate lowest sensitivity due to multi-year qualification lock-in.
Supply Chain Analysis
India's domestic-content procurement mandates for ISRO commercial operators are reshaping sourcing patterns, compelling foreign suppliers to partner with Bengaluru and Hyderabad fabricators. Precision-molded composite reflector production draws from the United States, Germany, and China; stamped-aluminum dish manufacturing centers on China and India. Raw material dependencies span carbon fiber prepreg, aerospace-grade aluminum sheet, and low-noise amplifier assemblies. Single-source vulnerability concentrates in robotic fiber placement equipment. Distribution runs through satellite operator procurement channels, ground station as a service providers, and independent network operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The parabolic antenna market functions as a stable compounder, with LEO constellation ground station deployment providing steady terminal demand across the analysis window.
For Market Incumbents: Hedge against phased array substitution by accelerating environmental qualification service productization for smaller manufacturers lacking NATO and ITU-R test infrastructure. Deepen backward integration into carbon fiber prepreg supply to defend margin position against raw material cost spikes. Lock in multi-year procurement contracts with Indian constellation operators before domestic autoclave capacity matures. For New Entrants and Emerging Players: The price-point gap between premium Ka-band military terminals and economy C-band broadcast dishes offers white-space targeting. Focus initial penetration on Indian domestic production partnerships serving private space startup ground station networks. Pursue dual-reflector configurations for emerging satellite operators seeking multi-band operational flexibility without premium-tier qualification timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among stamped-aluminum fabricators facing margin compression, though structural headwinds limit long-term viability. Target environmental qualification specialists with captive NATO and ITU-R certification protocols for acquisition; these assets compound recurring revenue streams. Watch for inflection when Indian domestic autoclave capacity achieves defense-tier surface tolerance specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Fiber Autoclave Capacity Expansion | Captive composite reflector production shortens Ka-band terminal lead times for military satellite programs. |
| Indian Domestic Production Partnership | Foreign suppliers align with ISRO procurement mandates to access constellation operator ground station contracts. |
| Environmental Qualification Service Launch | Cobham Limited's NATO and ITU-R methodology productizes recurring revenue from smaller manufacturers. |
| Quantum Encryption Feed Assembly Development | Early alignment with satellite payload developers positions suppliers for premium specification tiers. |
| Phased Array Technology Monitoring | Maritime and aerospace integrators evaluate electronically steered alternatives for mobile platform applications. |
Research Methodology
Direct dialogue with satellite operator procurement directors, defense contractor antenna engineers, ground station as a service providers, and ISRO commercial arm executives grounded qualitative assessment. Secondary validation drew from FCC Part 25 licensing databases, ITU Radio Regulations filings, ETSI pattern specification documents, and customs records of carbon fiber prepreg imports. Bottom-up terminal deployment estimates triangulated against top-down constellation operator capex disclosures.
Bottom-up modeling aggregated segment-level unit economics across offset, prime-focus, Cassegrain, and dual-reflector architectures by frequency band and end-user category. The analytical lens weighted Ka-band military procurement velocity, Indian domestic production incentive structures, and carbon-fiber reflector adoption curves. CAGRs derived from regression of historical terminal shipment patterns against constellation deployment schedules. Industry-specific inputs included ITU coordination timeline assumptions and defense qualification backlog durations.
The model assumes a particular technology adoption path; alternative pathways for electronically steered flat-panel antennas would alter the outlook for mechanical parabolic designs. Forecasts reflect assumptions regarding FCC spectrum reallocation proceedings and Indian domestic-content enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Global Virtualized Evolved Packet Core (VEPC) Market
Telecom Hardware
Very Small Aperture Terminal (VSAT) Market
Telecom Hardware
Industrial Transceivers Market
Telecom Hardware
Broadcast Antenna Market
Telecom Hardware
Telecom Equipment Market
Telecom Hardware
Europe Set-Top Box Market
Telecom Hardware
Digital TV Soc Market
Telecom Hardware
Land Mobile Radio System Market
Telecom Hardware
Repeaters Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
Global LTE Modems Market
Telecom Hardware
Africa Small Cell Market
Telecom Hardware
LPWAN Market
Telecom Hardware
Subscriber Identity Module (SIM) Market
Telecom Hardware
Global Volte Market
Telecom Hardware
Satellite Communication Terminal Market