
 Africa Small Cell Market | 2026-2036
Africa Small Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Small Cell Market Outlook
Mobile network equipment procurement is tilting toward open RAN-compatible small cell architectures across African markets. Huawei Technologies Co. Ltd. leverages its established base station supply relationships to sustain project pipelines in North and West Africa. Ericsson anchors premium 5G NR small cell deployments through operator partnerships in South Africa and Nigeria. Nokia Corporation competes on energy-efficient metrocell designs suited to markets with unreliable grid power.
Africa small cells are low-power radio access nodes operating between 100 milliwatts and 5 watts, designed to extend cellular coverage and capacity in targeted zones through licensed spectrum bands. These devices primarily serve to offload traffic from congested macro towers in dense urban environments and extend broadband reach into underserved suburban and rural clusters. Picocell and microcell segments dominate current volume as telecom operators prioritize mid-range coverage solutions for enterprise campuses and public venues. Femtocell demand is accelerating among residential users in South African and Nigerian metros where fiber backhaul availability supports consumer-grade deployments. Hybrid solutions combining 4G LTE with Wi-Fi are capturing margin pools in enterprise and public venue applications where seamless indoor mobility commands pricing premiums.
National regulators including Nigeria's NCC, South Africa's ICASA, and Kenya's CA shape deployment timelines through spectrum auction rules and infrastructure sharing mandates. Equipment standards from the African Telecommunications Union and ITU-R frameworks influence product certification requirements for cross-border supply. Stakeholders must monitor spectrum harmonization progress and power infrastructure reliability as determinants of deployment economics and vendor selection criteria.
Market Dynamics
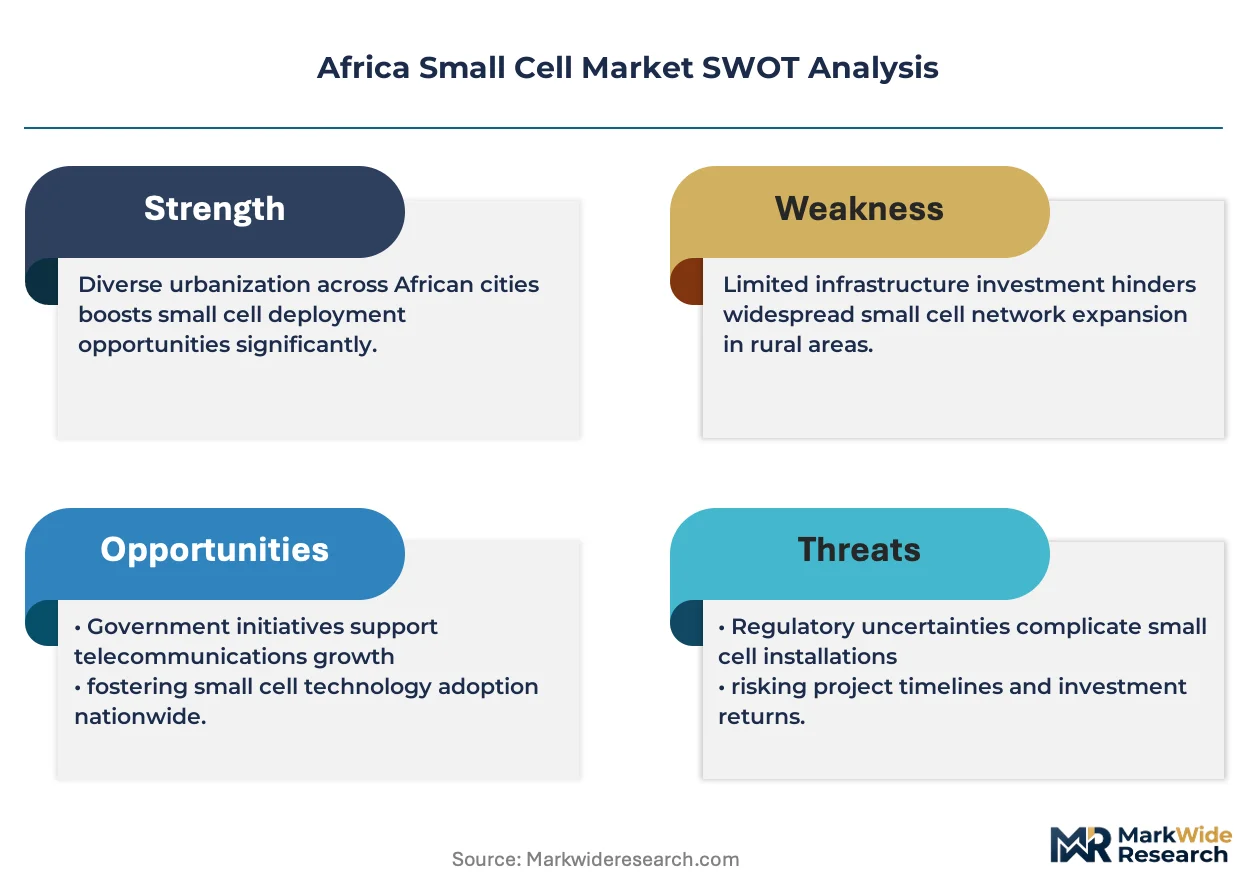
Spectrum liberalization policies across Nigeria, South Africa, and Kenya are compressing deployment timelines and forcing equipment vendors to reconfigure supply chains for rapid site activation.
Growth Catalysts
- National Broadband Plans:Nigeria's National Broadband Plan and South Africa's SA Connect program mandate universal coverage targets that accelerate small cell procurement for last-mile densification.
- Urban Traffic Offloading:Lagos, Johannesburg, and Cape Town macro towers face congestion thresholds that trigger automatic femtocell and picocell deployment clauses in operator infrastructure contracts.
- Open RAN Architectures:Disaggregated baseband and radio unit specifications from the O-RAN Alliance reduce vendor lock-in and expand eligible supplier pools for tier-two African operators.
Market Restraints
- Diesel Generator Dependency:Unreliable grid infrastructure in Nigerian and Kenyan deployment zones forces 40-60% higher opex for backup power systems, eroding small cell ROI calculations.
- Import Tariff Cascades:Non-Common External Tariff discrepancies between ECOWAS members and SADC states fragment equipment sourcing strategies and inflate landed costs for multi-country operators.
- Licensed Spectrum Scarcity:Sub-1 GHz band fragmentation between 700 MHz and 800 MHz assignments across Kenya, Nigeria, and South Africa complicates multi-band small cell hardware certification.
Strategic Opportunities
- Rural Cluster Extension:Kenyan agricultural cooperatives and Nigerian rural banking agents present untapped demand for solar-powered microcell deployments with satellite backhaul.
- Enterprise Neutral Host Models:Shopping mall operators and mining compounds in South Africa are procuring multi-operator small cells as infrastructure-as-a-service, bypassing traditional carrier-led deployment.
- 4G-5G Convergence:Dual-mode small cell platforms supporting NSA 5G NR and LTE-Advanced allow operators to defer full 5G core investments while capturing premium enterprise subscriptions.
Industry Challenges
- RF Engineering Talent Scarcity:Link budget optimization and interference management for dense urban HetNets require skills concentrated in Johannesburg, Lagos, and Nairobi consulting pools.
- Multi-Vendor Integration Complexity:Open RAN deployments force operators to assume system integration risks previously borne by single-vendor turnkey contracts, stretching internal engineering capacity.
- Equipment Certification Backlogs:Type approval queues at Nigeria's NCC and South Africa's ICASA extend product launch windows by 4-8 months versus European reference timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Small Cell Market |
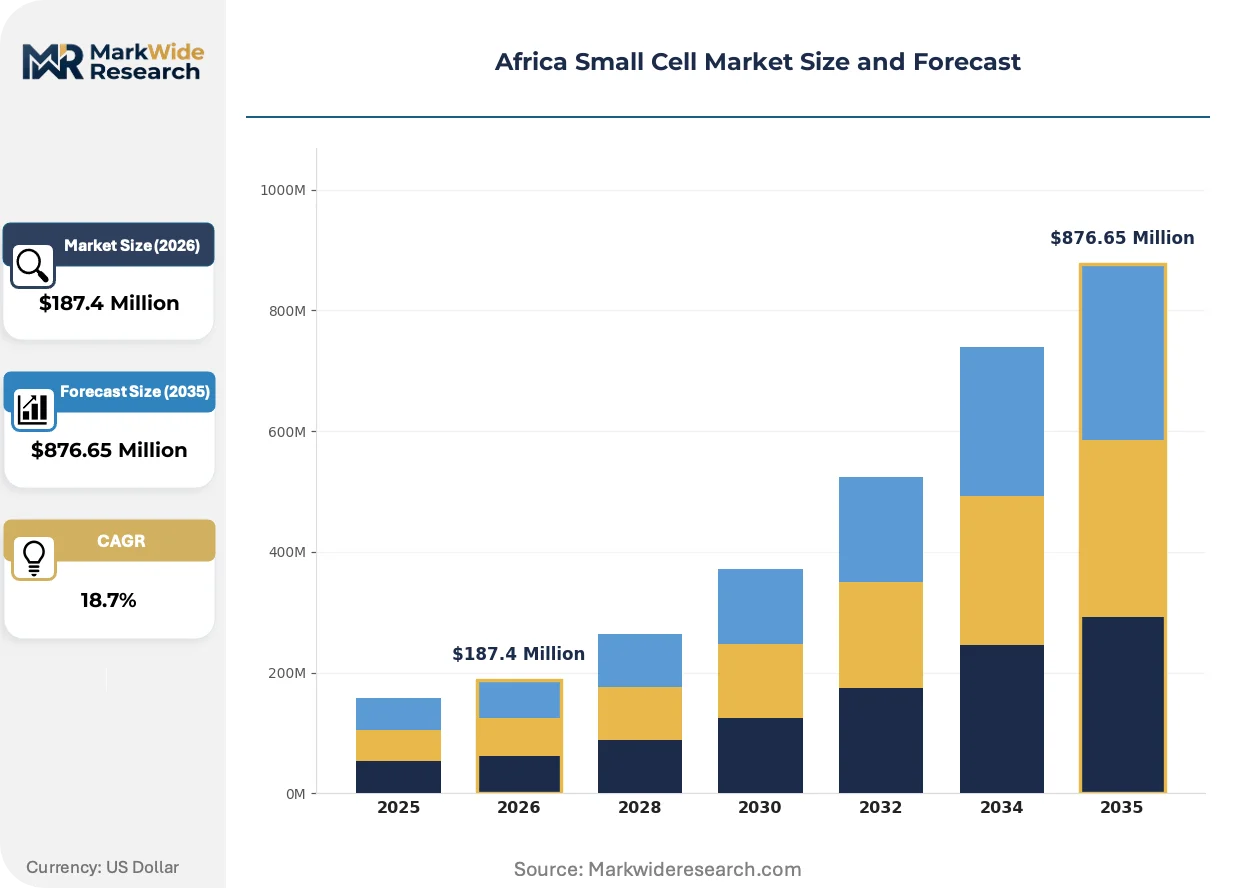
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Femtocell, Picocell, Microcell, Metrocells End User: Telecom Operators, Enterprises, Public Venues, Residential Users Technology: 4G LTE, 5G NR, Wi-Fi, Hybrid Solutions Deployment Model: Indoor, Outdoor, Urban, Suburban |
| Companies Covered | Huawei Technologies Co. Ltd., Ericsson, Nokia Corporation, Samsung Electronics Co. Ltd., ZTE Corporation, Airspan Networks Inc., Parallel Wireless Inc., Qualcomm Technologies, Inc., CommScope Holding Company, Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Small Cell Market Strategic Shifts
Deployment architectures are pivoting from carrier-controlled macro densification toward neutral host and enterprise-led models, compressing traditional infrastructure procurement cycles.
vRAN software stacks are hybridizing with legacy distributed unit hardware across African operator labs. MTN Nigeria and Vodacom South Africa are trialing containerized baseband functions on commercial off-the-shelf servers. This convergence is collapsing the historical separation between radio hardware and cloud infrastructure procurement, forcing vendors to retrain sales teams on software subscription economics.
ICASA's 2023 spectrum trading framework permits secondary market leasing of 2.6 GHz and 3.5 GHz assignments between mobile operators and private network deployers. Industrial mining licenses in South Africa's platinum belt now include conditional spectrum provisions that mandate small cell infrastructure sharing. Enterprise verticals with captive spectrum are engaging directly with original equipment manufacturers, bypassing traditional mobile network operator intermediation.
Network-as-a-service contracting is displacing capital purchase models for campus and venue deployments. South African universities and Nigerian hospital groups are procuring connectivity outcomes—defined coverage SLAs and per-user throughput guarantees—rather than hardware ownership. This transfer of operational risk to vendors is visible most acutely in enterprise segments where internal IT teams lack RF deployment expertise.
Africa Small Cell Market Segmentation
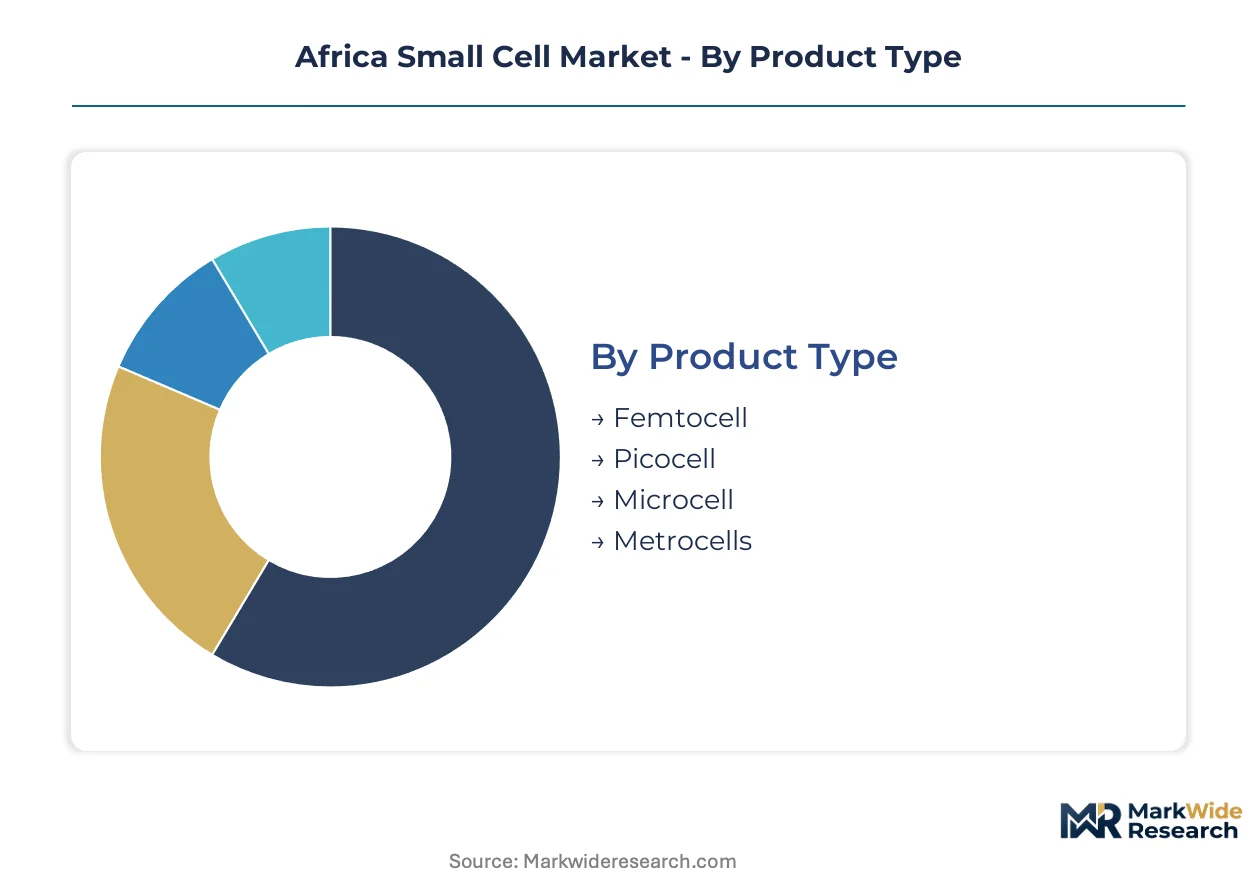
Small cell procurement patterns diverge sharply across product architectures and deployment contexts, with each segment demanding distinct installation protocols, backhaul configurations, and ongoing technical support. Equipment vendors structure service contracts and spare parts logistics around these segmentation boundaries, recognizing that femtocell residential deployments require minimal field intervention while outdoor metrocell installations demand continuous maintenance presence.
Product Type:
After-sales service intensity varies dramatically across power classes, with outdoor-rated metrocells requiring quarterly preventive maintenance cycles versus plug-and-play femtocell replacements handled through courier logistics.
- Femtocell:Low-power residential units operating below 100 milliwatts, typically consumer-provisioned through operator retail channels. Demand concentrates in South African metros and Nigerian urban corridors where fiber-to-the-home penetration supports self-installation models, though inconsistent power quality drives elevated return rates.
- Picocell:Mid-range indoor solutions spanning 100 milliwatts to 250 milliwatts, designed for enterprise campuses and retail venues. Procurement clusters in Johannesburg and Lagos banking districts where building owners mandate multi-operator neutrality clauses in lease agreements.
- Microcell:Street-level outdoor units addressing coverage gaps in suburban transport corridors and peri-urban commercial zones.
- Metrocells:High-capacity outdoor nodes serving dense urban hotspots and stadium venues with carrier-grade reliability requirements.
By volume, Picocell leads current procurement cycles. By growth pace, Femtocell is expanding most quickly among residential subscribers.
End User:
Customer procurement sophistication spans from standardized enterprise RFP processes to informal residential purchasing, with public venues occupying a hybrid middle ground requiring customized SLA negotiations.
- Telecom Operators:Carrier-led deployment remains the dominant procurement channel, with MTN Nigeria and Vodacom South Africa driving volume through framework agreements that bundle small cells with macro network expansion contracts. These operators prioritize multi-vendor interoperability to preserve negotiating leverage across refresh cycles.
- Enterprises:Mining compounds, agricultural cooperatives, and logistics hubs are procuring private cellular networks directly, bypassing traditional carrier intermediation. South African platinum belt operations leverage ICASA's industrial spectrum provisions to justify captive infrastructure investments.
- Public Venues:Shopping mall operators and transport terminals in Nairobi and Cape Town are adopting neutral-host models where a single infrastructure owner serves multiple roaming operators.
- Residential Users:Consumer-grade femtocell uptake accelerates in fiber-enabled neighborhoods where macro tower congestion degrades indoor coverage quality.
Telecom Operators command the largest share of current shipments. Enterprises are gaining share fastest as vertical-specific spectrum allocations proliferate.
Technology:
Radio access technology selection determines hardware refresh timelines, with hybrid architectures allowing phased migration paths that defer full core network replacement costs.
- 4G LTE:Mature ecosystem with established certification pathways at Nigeria's NCC and South Africa's ICASA, dominating current volume in markets where 5G spectrum allocation remains pending.
- 5G NR:Next-generation deployments concentrated in South African urban cores where 3.5 GHz spectrum availability supports non-standalone architectures, though equipment costs and power consumption constrain rural viability.
- Wi-Fi:Unlicensed spectrum offload for enterprise campuses and hospitality venues seeking to reduce cellular backhaul expenditure.
- Hybrid Solutions:Converged 4G-Wi-Fi platforms capturing premium pricing in stadium and convention center applications where seamless session continuity commands operator attention.
4G LTE maintains volume leadership across the forecast window. 5G NR is climbing the fastest as spectrum auctions in Kenya and Nigeria accelerate carrier deployment roadmaps.
Deployment Model:
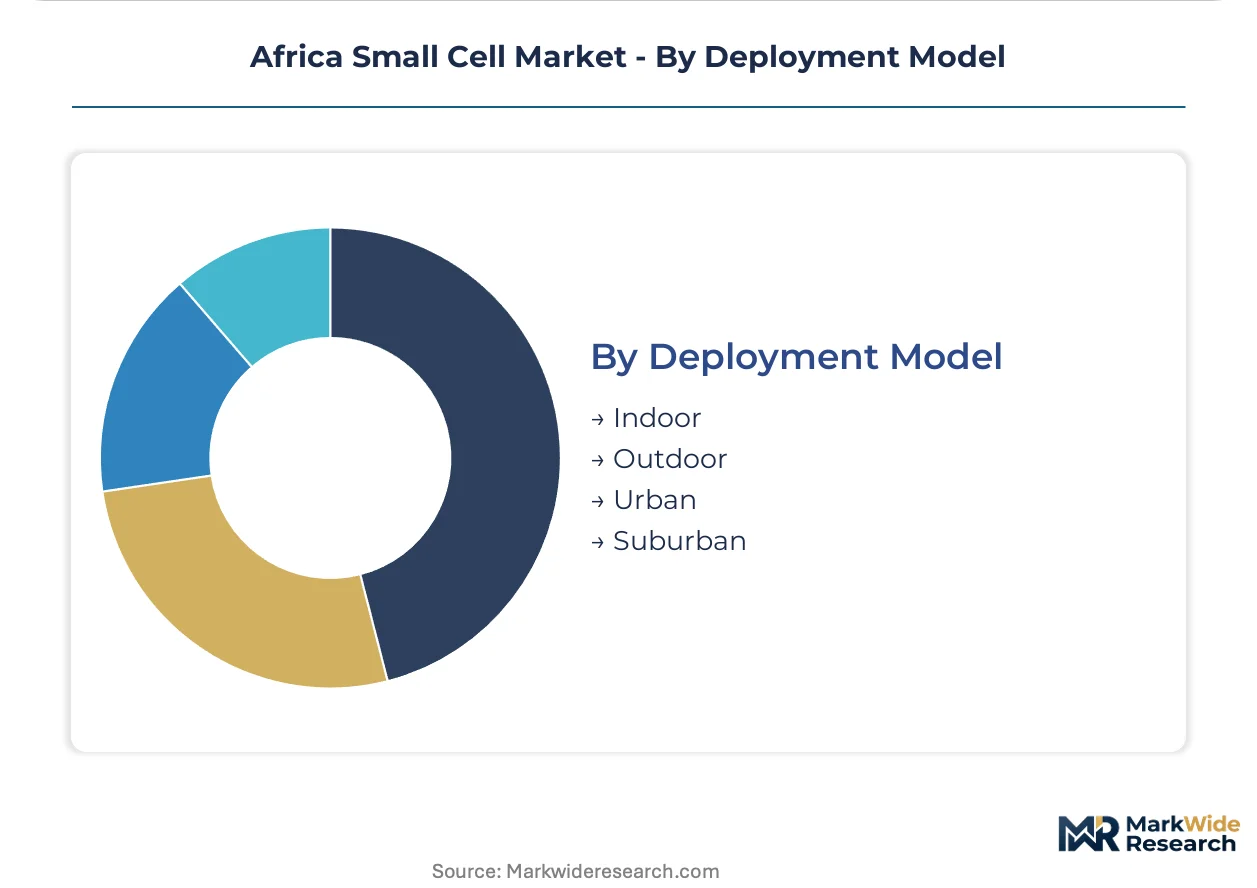
Physical installation environment dictates enclosure specifications, backhaul media selection, and power redundancy requirements, with outdoor urban deployments commanding 3-4x the hardware cost of indoor suburban equivalents.
- Indoor:Climate-controlled environments enabling fanless designs and passive cooling, prevalent in enterprise headquarters and retail banking branches across Lagos and Nairobi.
- Outdoor:Hardened enclosures with IP67 ratings and integrated surge protection, mandatory for street furniture mounting in South African metros exposed to seasonal electrical storms.
- Urban:Hyperdense deployment zones where interference coordination and handover optimization dominate network engineering priorities, particularly in Johannesburg's Sandton district and Cape Town's CBD.
- Suburban:Lower-density coverage extension targeting residential clusters and light industrial parks, often served through solar-powered microcells with satellite backhaul in Kenyan agricultural regions.
Urban deployments lead by installed base volume. Suburban applications are gaining share fastest as national broadband plans mandate universal coverage targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South African operators extract pricing premiums for 5G-ready small cells that Nigerian carriers cannot match due to currency volatility and import cost structures. Kenya commands intermediate valuations reflecting its more stable regulatory environment. These asymmetries shape vendor prioritization across the continent.
Nigeria
Lagos banking corridors and Abuja government districts drive picocell procurement for enterprise campus densification. The Nigerian Communications Commission's infrastructure sharing mandates accelerate multi-operator neutral host deployments. MTN Nigeria and Airtel Nigeria compete for street-level microcell sites in Lagos Island and Victoria Island commercial zones.
South Africa
Johannesburg's Sandton financial district and Cape Town's CBD anchor premium 5G NR small cell rollouts with carrier-grade reliability requirements. ICASA's 2023 spectrum trading framework permits secondary market leasing that enables private mining networks. Vodacom and MTN South Africa deploy outdoor metrocells at scale across Gauteng province transport corridors.
Kenya
Nairobi's Westlands business district and Mombasa port logistics hubs concentrate indoor picocell demand for enterprise connectivity. The Communications Authority's national broadband targets compress deployment timelines for rural cluster extension. Safaricom trials solar-powered microcells with satellite backhaul in Rift Valley agricultural cooperatives.
Egypt
Cairo's New Administrative Capital and Alexandria industrial zones drive government-led smart city small cell procurement. The National Telecommunications Regulatory Authority's 5G spectrum roadmap shapes vendor certification priorities. Telecom Egypt accelerates outdoor densification along Nile Delta transport corridors connecting major urban centers.
Morocco
Casablanca financial district and Rabat government complexes anchor enterprise femtocell and picocell deployments. The National Telecommunications Regulatory Agency harmonizes equipment standards with European CE marking frameworks. Inwi and Orange Morocco compete for neutral host contracts in Marrakech hospitality and conference venues.
Africa Small Cell Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying radio units and baseband silicon. The vendor base stratifies between turnkey infrastructure providers and disaggregated Open RAN suppliers. Three archetypes dominate: established telecom equipment conglomerates with African field operations, emerging software-centric challengers leveraging cloud-native architectures, and specialized RF component vendors supplying across ecosystem tiers. Competitive intensity centers on spectrum certification speed and multi-operator interoperability guarantees rather than pure hardware cost.
Among the established infrastructure tier, Huawei Technologies Co. Ltd., Ericsson, and Nokia Corporation exemplify contrasting geographic anchoring strategies. Huawei leverages its West and North African installed base to sustain project pipelines through existing supply relationships. Ericsson occupies the premium 5G deployment segment through operator partnerships in South African and Nigerian metros. Nokia competes on energy-efficient designs suited to markets with unreliable grid power, reflecting divergent responses to African infrastructure constraints.
| Leading Market Players |
|---|
| Huawei Technologies Co. Ltd. |
| Ericsson |
| Nokia Corporation |
| Samsung Electronics Co. Ltd. |
| ZTE Corporation |
| Airspan Networks Inc. |
| Parallel Wireless Inc. |
| Qualcomm Technologies, Inc. |
| CommScope Holding Company, Inc. |
| Others |
Value Chain & Pricing Dynamics
Import tariff cascades across ECOWAS and SADC boundaries determine both equipment tier spreads and supply chain configuration for African small cell procurement. Non-Common External Tariff discrepancies fragment sourcing strategies and inflate landed costs, compressing margins on standard-grade units while widening premiums for certified multi-band hardware.
Pricing Analysis
Configured-to-order pricing for multi-operator neutral host deployments commands 40-60% premiums over standard single-carrier units. Project-based contracting dominates carrier-led procurement, with price differentiation driven by certification tier (NCC/ICASA type approval status) and after-sales service bundling. Cost compression in entry-level femtocell tiers intensifies as Chinese vendors compete on volume, though enterprise buyers show lowest price sensitivity for 5G-ready metrocells with carrier-grade SLAs.
Supply Chain Analysis
Export-control restrictions on 5G NR baseband silicon limit component flows from US and allied jurisdictions to certain African markets. Manufacturing concentrates in China, South Korea, and Finland for finished small cell units, while RF front-end modules draw from Taiwanese and Japanese foundries. Single-source vulnerability in mmWave filter supply creates chokepoint exposure. Distribution runs through operator framework agreements and systems integrators rather than open channel resale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-one African operators consolidating procurement through multi-year framework agreements, fragmenting vendor access for smaller carriers and enterprise deployers.
For Market Incumbents: Build certification moats through accelerated NCC and ICASA type approval pipelines to lock out emerging Open RAN challengers. Prioritize backward integration into power-efficient enclosure manufacturing to offset diesel generator dependency costs eroding project ROI in Nigerian deployment zones.
For New Entrants and Emerging Players: Kenyan agricultural cooperatives and Nigerian rural banking networks present the most penetrable white-space for solar-powered microcell deployments with satellite backhaul. Target enterprise neutral host contracts in South African mining compounds where ICASA's industrial spectrum provisions bypass traditional carrier intermediation. Lead with network-as-a-service subscription models to transfer operational risk from IT-constrained buyers.
For Investors and Strategic Acquirers: ICASA's 2023 spectrum trading framework reshapes the acquisition landscape toward private network infrastructure-as-a-service platforms. Long-term viability rests on software-centric vendors with containerized vRAN stacks capable of displacing legacy distributed unit hardware. Monitor Kenya's Communications Authority spectrum harmonization progress as the signal for East African deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Certification Investment | NCC and ICASA type approval acceleration locks out single-v turnkey competitors in Nigerian carrier procurement. |
| Solar-Backhaul Microcell Deployment | Safaricom's Rift Valley trials validate satellite-backhaul economics for Kenyan agricultural cooperative extension. |
| Neutral Host Infrastructure-as-a-Service | South African university SLA contracting transfers RF operational risk from IT-constrained campus buyers. |
| Dual-Mode 4G-5G Platform Convergence | NSA architecture support defers full 5G core investment while capturing premium enterprise subscriptions. |
| Power Enclosure Backward Integration | In-house production of IP67-rated enclosures mitigates diesel generator dependency eroding Nigerian project returns. |
Study Parameters
Operator-level perspectives from MTN Nigeria, Vodacom South Africa, and Safaricom procurement executives anchored the qualitative base for this study. Primary interviews with NCC and ICASA regulatory affairs leads, neutral host infrastructure deployers, and Open RAN systems integrators combined with secondary validation from African Telecommunications Union spectrum frameworks, ITU-R equipment standards, and operator capex disclosure filings. Bottom-up deployment volume estimates triangulated against top-down national broadband plan targets.
Scenario-bracketing around spectrum auction timing and power infrastructure reliability shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product power class, deployment environment, radio access technology generation, and end-user procurement sophistication. CAGRs derived from deployment pipeline visibility and infrastructure sharing mandate compliance trajectories. Key inputs encompassed spectrum harmonization progress and satellite backhaul cost curves for rural cluster extension.
Practitioners should monitor NCC infrastructure sharing rule enforcement and ICASA secondary spectrum market liquidity for early signals of procurement model displacement. Forecasts reflect assumptions on national broadband plan funding continuity and import tariff regime stability. Material shifts in ECOWAS-SADC tariff harmonization or 5G spectrum auction delays would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Global Ultra Portable Internet Device Market
Telecom Hardware
Subscriber Identity Module (SIM) Market
Telecom Hardware
Voice Communication Equipment Market
Telecom Hardware
SATCOM Transceivers Market
Telecom Hardware
Digital TV Soc Market
Telecom Hardware
LPWAN Market
Telecom Hardware
Asia Pacific Enterprise Routers Market
Telecom Hardware
5G BTS Antenna Market
Telecom Hardware
4G Equipment Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
Parabolic Antenna Market
Telecom Hardware
Broadcast Antenna Market
Telecom Hardware
Low Power Wide Area Network (LPWAN) Market
Telecom Hardware
Point-To-Point Microwave Antenna Market
Telecom Hardware
Room Cell Module Market
Telecom Hardware
Global LTE Modems Market