
 5G Radio Unit Market | 2026-2036
5G Radio Unit Market Size, Share, and Industry Trends Forecast 2026-2036
5G Radio Unit Market Outlook
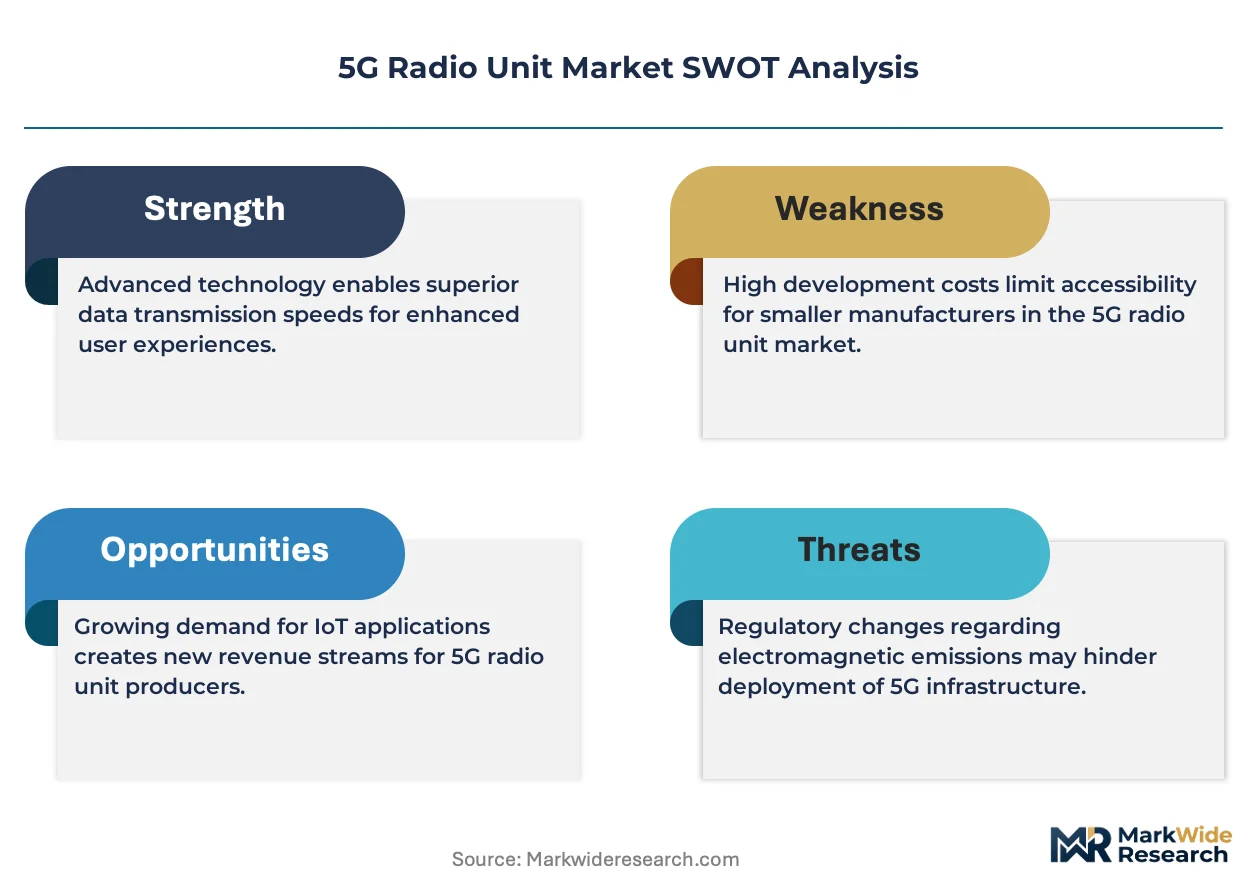
Enterprise buyers are rotating into the 5G Radio Unit Market as private network deployments displace traditional telecom-operator-centric procurement patterns. Ericsson leverages its massive MIMO portfolio to sustain leadership in macro-cell infrastructure across European Union member states. Samsung anchors its position through vertical integration into semiconductor fabrication for mmWave modules. Qualcomm Technologies differentiates via chipset-level dominance in sub-6 GHz and mmWave radio architectures.
A 5G radio unit is a base station transceiver subsystem that converts digital baseband signals to radio frequency transmissions, typically operating across sub-6 GHz and millimeter-wave spectra with carrier aggregation supporting bandwidths exceeding 400 MHz, and its primary purpose is enabling high-capacity, low-latency wireless connectivity for cellular networks and industrial automation systems. Massive MIMO configurations command the largest share of deployed capital as telecom operators prioritize spectral efficiency in dense urban environments. Small cells represent the fastest-expanding product category as enterprises deploy dedicated coverage solutions for factories, warehouses, and campuses. Cloud-based deployment models are capturing margin pools through software-defined radio architectures that reduce hardware refresh cycles.
The Federal Communications Commission governs spectrum allocation and equipment authorization in the United States, while the European Telecommunications Standards Institute coordinates harmonized frequency bands and Open RAN interface specifications across European Union markets, and China's Ministry of Industry and Information Technology mandates domestic encryption standards and vendor certification protocols that shape market access conditions. Stakeholders must monitor regulatory divergence between spectrum harmonization frameworks and national security-driven vendor restrictions when structuring supply chain and partnership strategies.
Market Dynamics
Open RAN interoperability mandates are forcing vendor consolidation and procurement recalibration across telecom infrastructure buyers. The transition from proprietary hardware stacks to disaggregated software-defined architectures is redistributing margin pools from traditional equipment suppliers to semiconductor and software specialists.
Growth Catalysts
- Enterprise Private Networks:Smart manufacturing facilities in Germany and South Korea are deploying dedicated radio units for deterministic latency control over industrial automation systems.
- Spectrum Auction Frameworks:The Federal Communications Commission's mid-band allocation programs are accelerating capital deployment by mobile network operators seeking capacity expansion.
- Open RAN Mandates:The European Union's interoperability specifications are compelling incumbent vendors to open interfaces and certify multi-supplier configurations.
Market Restraints
- Semiconductor Supply Concentration:Advanced node fabrication for mmWave beamforming chips depends on Taiwan-based foundry capacity with limited geographic diversification.
- Energy Cost Volatility:Massive MIMO arrays require sustained power inputs, exposing operators to electricity price swings in European markets.
- Legacy Integration Friction:Existing 4G macro-cell infrastructure constrains site upgrade timelines and physical space for additional antenna modules.
Strategic Opportunities
- India Infrastructure Buildout:National 5G deployment programs are creating procurement windows for radio unit suppliers qualifying under domestic production-linked incentive schemes.
- Neutral Host Models:Shared infrastructure deployments in dense urban corridors enable third-party ownership of radio assets serving multiple operators.
- AI-Driven Beam Management:Machine learning integration with massive MIMO systems is opening software licensing revenue streams alongside hardware sales.
Industry Challenges
- RF Engineering Talent Scarcity:mmWave system design and antenna calibration expertise remains concentrated among a narrow specialist workforce.
- Multi-Vendor Integration Complexity:Open RAN configurations demand interoperability testing across radio unit, distributed unit, and centralized unit suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Radio Unit Market |
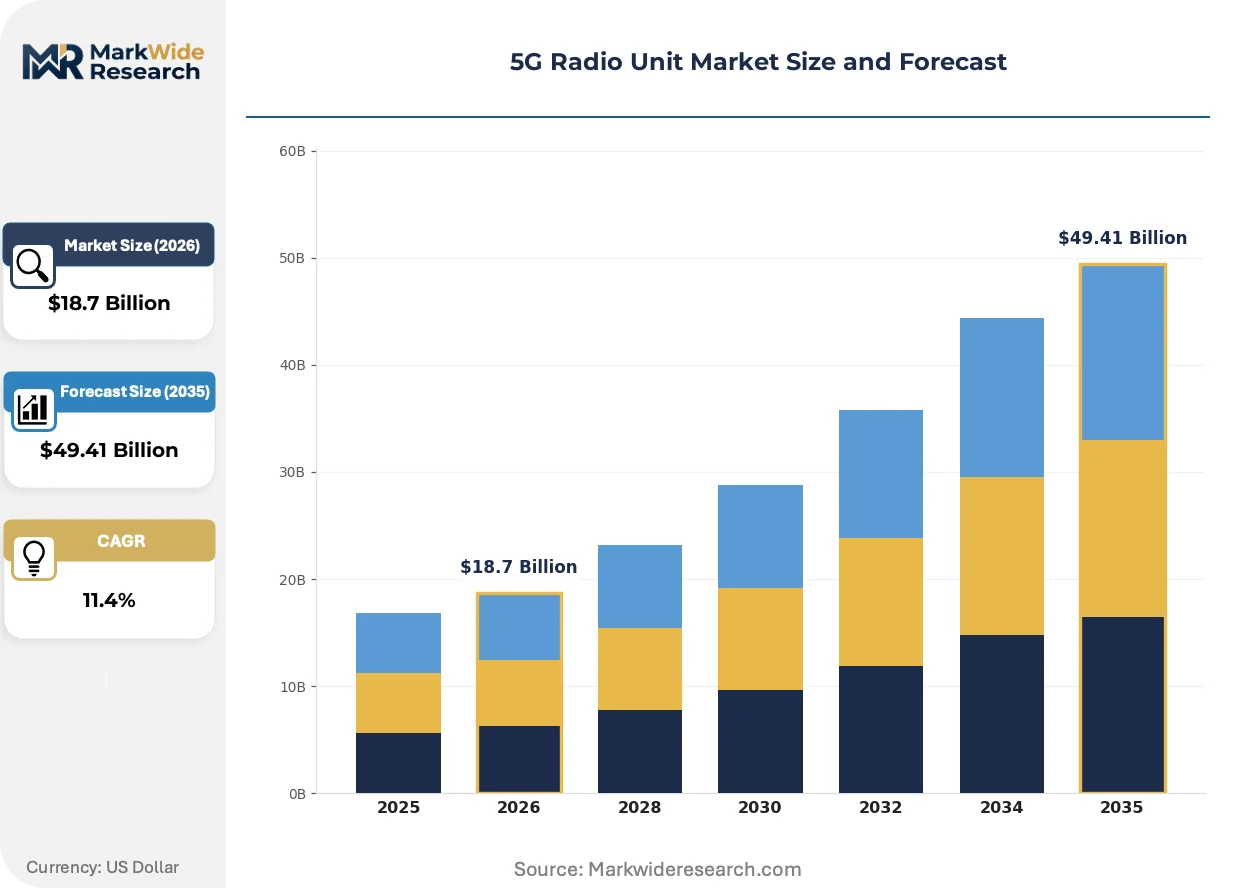
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Massive MIMO, Small Cells, Distributed Antenna Systems, Beamforming End User: Telecom Operators, Enterprises, Government, OEMs Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing Technology: Sub-6 GHz, mmWave, Network Slicing, Virtualization |
| Companies Covered | Ericsson, Nokia, Huawei, Samsung, Qualcomm Technologies, Fujitsu, NEC Corporation, ZTE, onsemi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Radio Unit Market Strategic Shifts
Software-defined radio architectures are compressing hardware refresh cycles and redistributing value toward cloud-native orchestration layers. Three concurrent developments are restructuring competitive positioning and procurement patterns.
Open RAN reference designs are fragmenting the traditional baseband processing market. These disaggregated architectures separate radio unit hardware from baseband software, enabling enterprise buyers to mix semiconductor suppliers. Telecom operators in Germany and South Korea are piloting multi-vendor configurations that bypass single-source lock-in.
The European Telecommunications Standards Institute's Open Fronthaul interface specifications are mandating interoperability testing for radio unit certification. This regulatory pressure is compressing proprietary feature differentiation among incumbent vendors. Equipment suppliers serving European Union member states must now document compliance with standardized control and user plane separation protocols.
Enterprise buyers are consolidating procurement authority from distributed IT departments to centralized digital transformation offices. This organizational shift is displacing traditional telecom-operator-mediated purchasing for private 5G deployments. Manufacturing conglomerates in India and Germany are establishing direct vendor relationships for campus-wide radio unit installations.
5G Radio Unit Market Segmentation
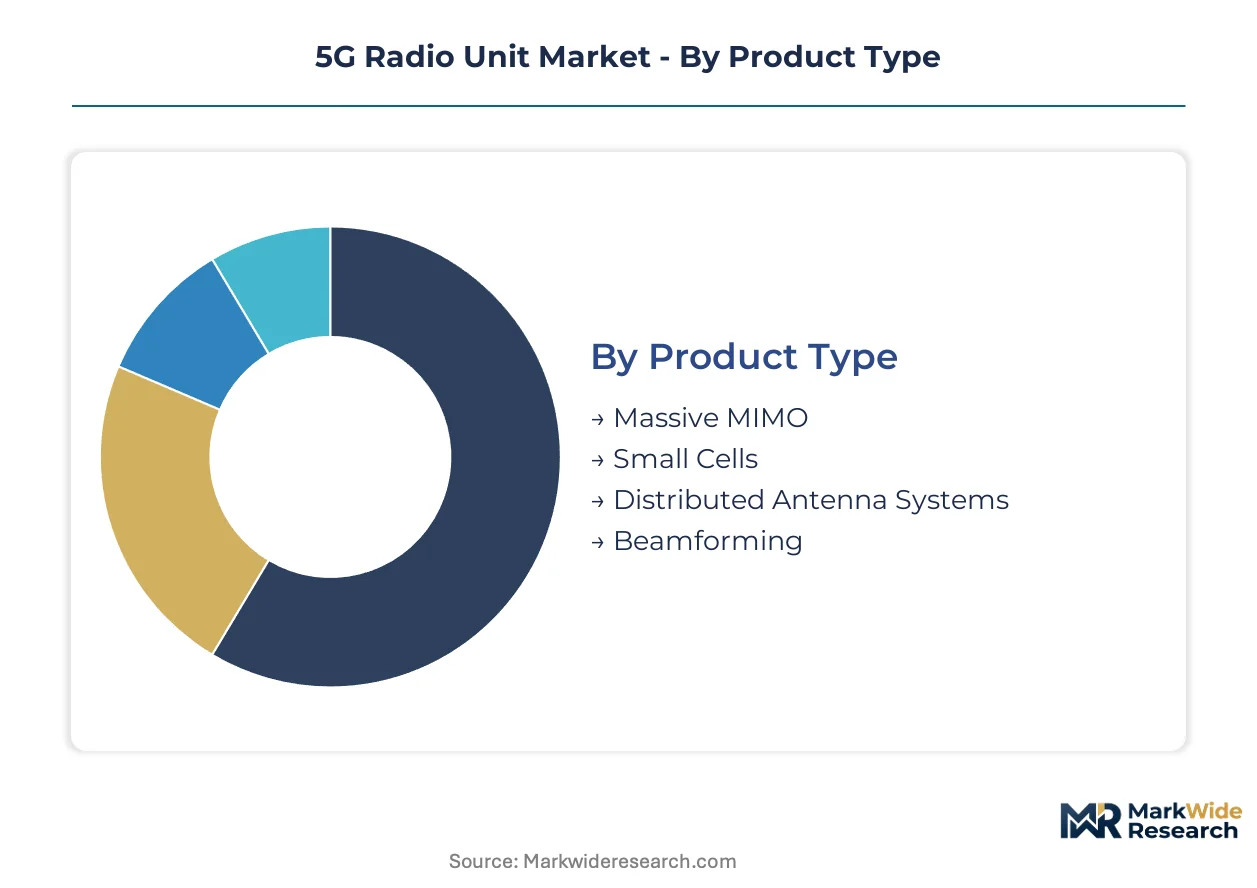
Segmentation in the 5G Radio Unit Market reveals how procurement authority, deployment architecture, and spectrum strategy redistribute value across hardware, software, and service layers. Understanding these divisions exposes where vendor margin pools concentrate and where new entrants can bypass incumbent lock-in.
Product Type:
Margin pools in this category concentrate in beamforming silicon and massive MIMO antenna arrays where semiconductor content drives hardware premiums.
- Massive MIMO:These antenna systems deploy 64 or more radiating elements with active beam steering to maximize spectral efficiency in dense urban corridors. Telecom operators in Germany and South Korea are prioritizing these configurations for stadium and central business district coverage where subscriber density justifies capital intensity.
- Small Cells:Low-power radio units operating below 10 watts deliver targeted coverage for indoor environments and outdoor hotspots. Manufacturing conglomerates in India are deploying these for deterministic latency control across factory floors, bypassing traditional operator-mediated procurement.
- Distributed Antenna Systems:Network of spatially separated antenna nodes connected to a common source via transport media.
- Beamforming:Signal processing technique directing radio energy toward specific receivers rather than broadcasting uniformly.
The dominant share belongs to Massive MIMO, while Small Cells is closing the gap fastest.
End User:
Procurement patterns in this dimension track the shift from centralized carrier capital planning to decentralized enterprise IT budgets.
- Telecom Operators:Traditional mobile network operators deploying macro-cell infrastructure for wide-area coverage. These buyers concentrate procurement in Germany, South Korea, and India as national 5G programs advance.
- Enterprises:Manufacturing, logistics, and energy firms acquiring dedicated radio units for private network autonomy. Smart manufacturing facilities are accelerating procurement as deterministic latency requirements displace Wi-Fi for industrial automation.
- Government:Public sector agencies deploying secure communications infrastructure for emergency services and defense applications.
- OEMs:Original equipment manufacturers integrating radio units into vehicles, machinery, and IoT endpoints.
Telecom Operators still command procurement volume, though Enterprises are expanding most quickly as private network deployments multiply.
Deployment Model:
Cost tier differentiation in this category separates capital-intensive hardware ownership from recurring software subscription models.
- On-Premises:Buyer-owned infrastructure with dedicated physical radio units at each site. Enterprises in Germany favor this model for data sovereignty compliance and deterministic performance guarantees.
- Cloud-Based:Centralized baseband processing with remote radio heads, compressing hardware refresh cycles through software-defined architectures. This model is redistributing margin pools from equipment suppliers to orchestration platform vendors.
- Hybrid:Combination of local radio units with cloud-managed orchestration layers.
- Edge Computing:Distributed processing architecture placing compute and radio resources at network periphery.
On-Premises retains the installed base, yet Cloud-Based is gaining share fastest as Open RAN architectures mature.
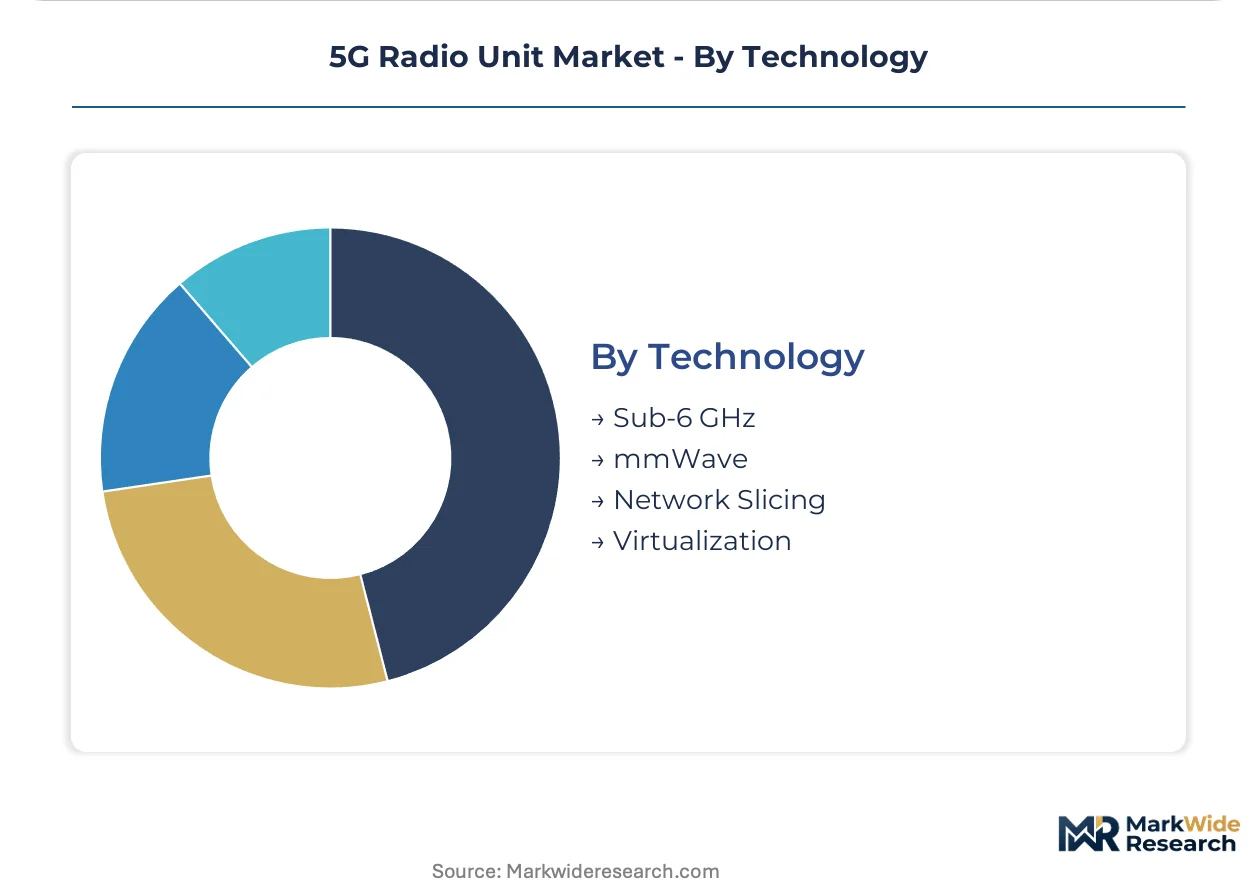
Technology:
Supply concentration in this category sits with sub-6 GHz chipset suppliers serving volume markets, while mmWave module production depends on limited foundry capacity.
- Sub-6 GHz:Radio units operating below 6 GHz delivering balanced coverage and capacity for broad deployment. This spectrum band dominates procurement in India where propagation characteristics suit rural coverage expansion.
- mmWave:Millimeter-wave systems operating above 24 GHz with extreme bandwidth for dense urban capacity. Samsung anchors its position through captive semiconductor fabrication for these modules.
- Network Slicing:Virtual network architecture enabling isolated logical networks atop shared physical infrastructure.
- Virtualization:Software-defined radio implementation decoupling hardware from baseband processing functions.
Sub-6 GHz holds the dominant position, while mmWave is climbing the fastest as urban density drives capacity requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced node fabrication for beamforming silicon concentrates in Taiwan and South Korea, while radio unit assembly clusters in Germany, China, and the United States. National 5G infrastructure programs and spectrum auction frameworks are redistributing procurement authority across these manufacturing hubs.
United States
Mid-band spectrum allocations and private network deployments for defense and manufacturing drive procurement. The Federal Communications Commission's auction frameworks accelerate capital deployment by mobile operators seeking capacity expansion. Deployment clusters concentrate in Texas and California where hyperscale data centers anchor edge computing integration with radio infrastructure.
Germany
Industrial automation demand from automotive and machinery sectors propels private 5G network investments. The European Telecommunications Standards Institute's Open RAN specifications mandate interoperability testing for radio unit certification. Manufacturing conglomerates in Bavaria and Baden-Württemberg establish direct vendor relationships for campus-wide installations.
China
Domestic encryption standards and vendor certification protocols shape market access conditions under MIIT oversight. The Ministry of Industry and Information Technology mandates domestic security requirements that influence procurement specifications. Deployment concentrates in the Yangtze River Delta and Pearl River Delta where smart manufacturing facilities drive dense radio unit installation.
South Korea
Deterministic latency requirements for semiconductor and electronics manufacturing accelerate dedicated radio unit procurement. The national regulator coordinates harmonized frequency bands for industrial 5G deployment. Seoul Capital Area and Busan-Ulsan regions host the densest concentration of private network pilots for factory automation.
India
National 5G deployment programs create procurement windows under production-linked incentive schemes administered by TRAI and related agencies. The Department of Telecommunications oversees spectrum allocation for rural coverage expansion. Maharashtra and Karnataka emerge as primary deployment clusters where telecom operators prioritize sub-6 GHz propagation for broad geographic reach.
5G Radio Unit Market Competitive Environment
Concentration sits with integrated equipment suppliers possessing captive semiconductor fabrication and massive MIMO antenna expertise. The vendor base stratifies across three tiers: full-stack infrastructure providers, semiconductor specialists supplying beamforming silicon, and emerging Open RAN disaggregators attacking interface standardization. Strategic moves center on backward integration into mmWave module production and partnership formations to certify multi-vendor configurations.
Within the full-stack infrastructure tier, Ericsson and Nokia exemplify European-anchored equipment suppliers with established carrier relationships, while Samsung occupies a position bridging semiconductor fabrication and integrated radio unit supply. These three represent divergent geographic bases—Swedish, Finnish, and South Korean respectively—reflecting how national industrial policy shaped competitive positioning in 5G infrastructure.
| Leading Market Players |
|---|
| Ericsson |
| Nokia |
| Huawei |
| Samsung |
| Qualcomm Technologies |
| Fujitsu |
| NEC Corporation |
| ZTE |
| onsemi |
| Others |
Value Chain & Pricing Dynamics
Foundry-scale economies in advanced node semiconductor fabrication concentrate beamforming silicon production among Taiwan-based and South Korean suppliers, compressing cost floors for massive MIMO arrays while elevating price premiums for mmWave modules where capacity utilization runs tightest.
Pricing Analysis
Volume-discount tiering structures separate enterprise private network procurement from telecom operator bulk purchasing, with three-tier pricing stratification across premium certified, standard interoperable, and economy single-source configurations. Price differentiation centers on Open RAN certification level and captive semiconductor fabrication depth. Cost compression in sub-6 GHz chipsets intensifies as Qualcomm and MediaTek expand foundry allocations. Enterprise buyers in Germany exhibit the highest price sensitivity due to capital budget constraints, while defense sector procurement shows the least sensitivity given security-driven specification rigidity.
Supply Chain Analysis
Inbound logistics costs through the Shanghai-Singapore and Busan-Long Beach trade lanes fluctuate with container availability, compressing margin buffers for radio unit assembly operations in Germany and the United States. Beamforming silicon draws from Taiwan and South Korea, while antenna substrate materials rest on Japanese and Chinese ceramic suppliers. Single-source vulnerability concentrates in 7nm and below foundry capacity for mmWave beamforming chips. Distribution runs through carrier-direct procurement for macro-cell infrastructure and systems integrator channels for enterprise private deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor fragmentation in the 5G Radio Unit Market creates white-space opportunities as enterprise procurement authority displaces traditional operator-mediated purchasing patterns.
For Market Incumbents: Compound carrier relationship depth through backward integration into mmWave module production and accelerated Open RAN certification timelines. Samsung's captive semiconductor fabrication anchors its defensive position against emerging disaggregators. Prioritize interoperability testing investments to maintain qualification under European Telecommunications Standards Institute mandates. For New Entrants and Emerging Players: Lead with software-defined radio orchestration platforms targeting cloud-based deployment models where margin pools are redistributing fastest. The India production-linked incentive scheme offers the most penetrable geography for radio unit assembly qualification. Pursue direct vendor relationships with manufacturing conglomerates in Baden-Württemberg bypassing traditional systems integrator channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors semiconductor specialists with beamforming silicon expertise over hardware-assembly operations facing commoditization pressure. Long-term viability concentrates in vendors controlling sub-6 GHz and mmWave chipset architectures. Monitor Open RAN interoperability certification velocity as the inflection indicator for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Certification Investment | European Telecommunications Standards Institute compliance unlocks procurement eligibility across German and South Korean operator tenders. |
| Backward Integration into mmWave Fabrication | Samsung's captive semiconductor production insulates margin structures against Taiwan foundry capacity constraints. |
| Enterprise Direct Sales Channel Buildout | Manufacturing conglomerates in Bavaria now procure campus-wide installations bypassing telecom operator intermediation. |
| AI-Driven Beam Management Software Licensing | Machine learning integration with massive MIMO systems generates recurring revenue alongside hardware refresh cycles. |
| India Production-Linked Incentive Qualification | Domestic assembly certification under TRAI-administered schemes secures preferential access to national 5G deployment programs. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with radio unit procurement directors, semiconductor supply chain managers, Open RAN integration specialists, and telecom infrastructure planners; and secondary validation through Federal Communications Commission spectrum auction records, European Telecommunications Standards Institute certification databases, MIIT vendor approval registries, and foundry capacity utilization disclosures. Bottom-up unit shipment estimates triangulated against top-down capital expenditure projections across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product architecture, deployment model, spectrum technology, and end-user procurement authority. CAGRs derived from slope-intercept fitting of historical capital deployment patterns against announced infrastructure program timelines. Industry-specific forecast inputs incorporated Open RAN interoperability certification velocity and production-linked incentive scheme uptake rates.
Forecasts assume regulatory continuity in FCC spectrum allocation frameworks and European Union Open RAN mandates; material policy shifts would require re-modeling. Semiconductor supply concentration risk and enterprise procurement cyclicality represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Commercial Antennas Market
Telecom Hardware
Digital Smart Set-Top Box (STB) Market
Telecom Hardware
Synchronous Optical Network (SONET) Market
Telecom Hardware
Broadcast Antenna Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
Europe Zero-Touch Provisioning Market
Telecom Hardware
Room Cell Module Market
Telecom Hardware
Point-To-Point Microwave Antenna Market
Telecom Hardware
Asia Pacific Enterprise Routers Market
Telecom Hardware
Global Time Sensitive Networking Market
Telecom Hardware
Global Microwave Transmission Equipment Market
Telecom Hardware
Laser Communications Terminals (Lcts) Market
Telecom Hardware
Satellite Communication Terminal Market
Telecom Hardware
Telecom Electronic Manufacturing Services (EMS) Market
Telecom Hardware
LTE IoT Devices Market
Telecom Hardware
Telecom Equipment Market