
 Digital TV Soc Market | 2026-2036
Digital TV Soc Market Size, Share, and Industry Trends Forecast 2026-2036
Digital TV Soc Market Analysis
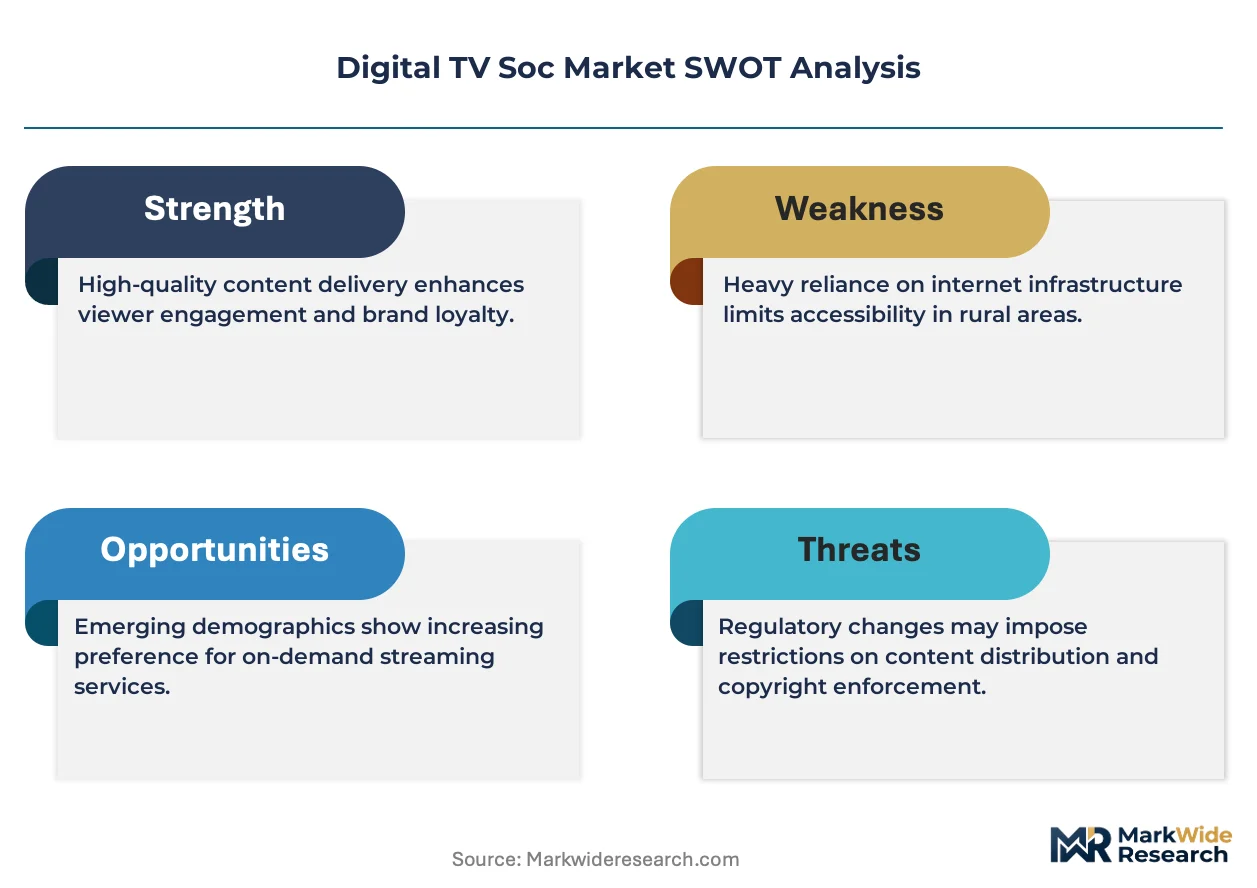
Taiwan is tilting toward advanced packaging capacity for TV SoC fabrication. MediaTek leverages its integrated design-to-test workflow to sustain leadership in cost-optimized solutions. Broadcom anchors premium-tier supply through vertical control over DOCSIS and Wi-Fi silicon blocks.
A Digital TV SoC is a single-chip system integrating CPU, GPU, demodulator, decoder, and connectivity modules on one die, typically manufactured at 12nm to 7nm process nodes to balance thermal budgets with 4K/8K video processing throughput. Its primary commercial purpose is to reduce bill-of-materials count while enabling smart TV platforms, streaming sticks, and set-top boxes to render HDR content and run concurrent applications. Integrated TV platforms dominate unit volume as OEMs consolidate tuner, scaler, and operating system functions onto one substrate, while streaming devices capture faster growth as cord-cutting households replace legacy cable hardware. OLED technology commands premium positioning in high-end panels, though LED-backlit LCD retains margin density through scale economies in emerging markets.
The FCC mandates ATSC 3.0 tuner compatibility for US-bound devices, reshaping demodulator requirements and RF front-end integration. REACH and RoHS frameworks in Europe restrict hazardous substances in semiconductor packaging, pushing foundries toward lead-free bumping and halogen-free substrates. China's GB standards and MIIT certification rules govern terrestrial broadcast decoding and cybersecurity features for domestic retail channels. Stakeholders must weigh regional tuner fragmentation against the cost of maintaining multiple silicon SKUs as broadcast protocols diverge.
Market Dynamics
Broadcast protocol fragmentation is forcing semiconductor vendors to maintain multiple demodulator IP blocks while foundry costs for advanced nodes compress margin structures at the premium tier.
Growth Catalysts
- ATSC 3.0 mandate:The FCC's tuner compatibility requirement for US-bound devices is pulling demand for next-generation RF front-end integration and software-defined demodulation.
- Smart home convergence:Residential households are consolidating entertainment, security, and climate control onto unified platforms, expanding addressable silicon content per installation.
- China production scaling:Domestic OEMs in Shenzhen and Hefei are vertically integrating tuner, scaler, and OS functions onto single substrates, reducing import dependency for broadcast decoding components.
Market Restraints
- Advanced node cost escalation:Migration from 12nm to 7nm process technology at TSMC and Samsung Foundry is inflating mask set expenses and minimum order quantities for mid-tier TV platforms.
- Regional tuner fragmentation:Divergent terrestrial broadcast standards across DVB-T2, ISDB-T, and DTMB geographies necessitate multiple silicon SKUs, inflating inventory carrying costs.
- Raw material concentration:High-purity silicon wafer supply concentrates in Japanese and German chemical processing clusters, exposing fabs to input cost volatility.
Strategic Opportunities
- India retail penetration:The country's PLI scheme for electronics manufacturing is attracting set-top box and smart TV assembly, creating captive demand for cost-optimized SoC platforms.
- EU Ecodesign tailwind:Tightening standby power limits and material efficiency mandates are accelerating replacement cycles for energy-intensive legacy television hardware.
- Edge AI convergence:Integration of neural processing units with video decoding pipelines is enabling on-device content recommendation and voice assistant processing without cloud dependency.
Industry Challenges
- RF analog design scarcity:Foundries report acute shortages of engineers proficient in mixed-signal layout for tuner-demodulator integration at sub-10nm geometries.
- Multi-protocol certification timelines:Simultaneous validation against FCC Part 15, CE marking EMC, and MIIT radio transmission rules extends product qualification by 6-9 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital TV Soc Market |
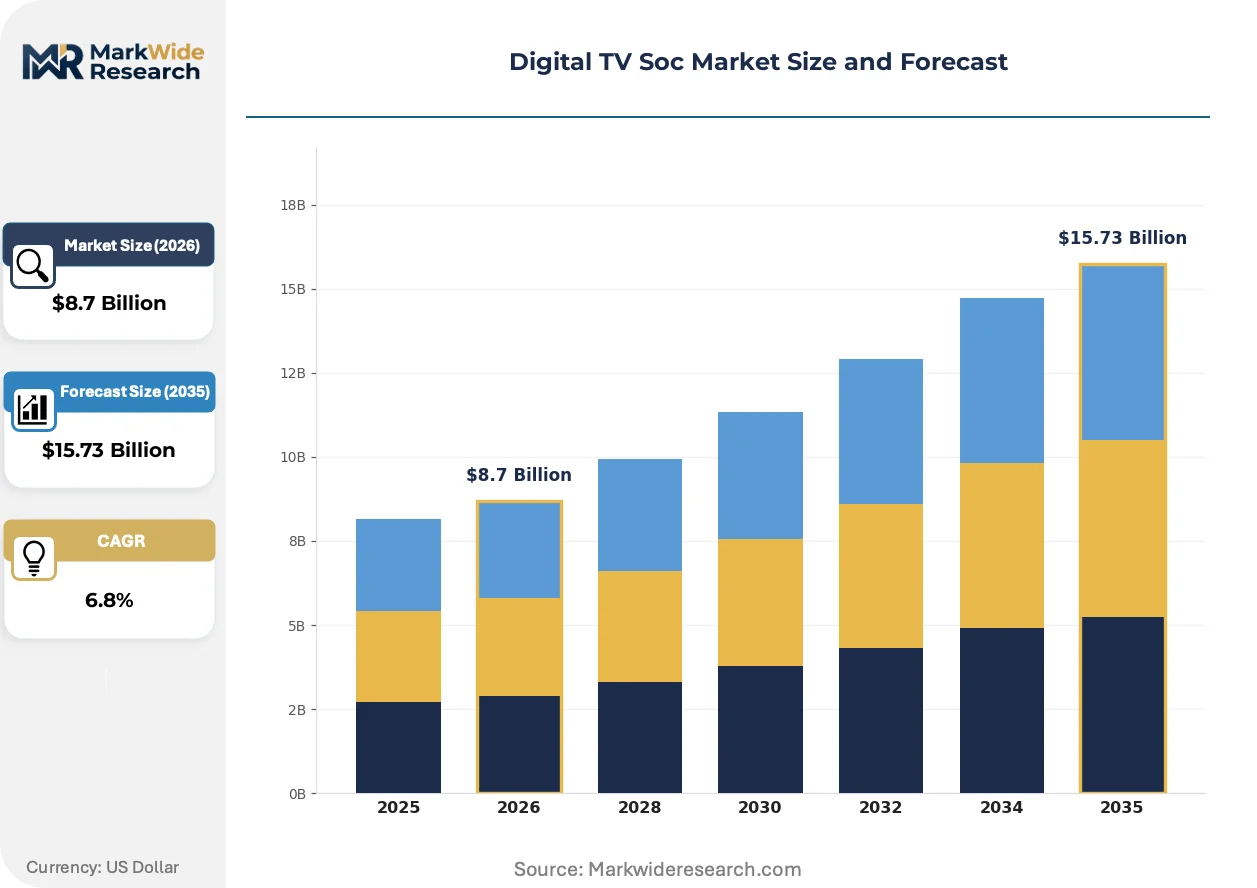
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Set-Top Box, Streaming Device, Integrated TV, Media Player Technology: OLED, QLED, LED, LCD Application: Home Entertainment, Smart Home Integration, Gaming, Online Streaming End User: Households, Commercial Establishments, Educational Institutions, Hospitality |
| Companies Covered | MediaTek Inc., Broadcom Inc., Samsung Electronics Co., Ltd., Qualcomm Technologies Inc., STMicroelectronics N.V., Novatek Microelectronics Corp., Realtek Semiconductor Corp., NXP Semiconductors N.V., Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital TV Soc Market Emerging Trajectories
Virtualization of broadcast reception functions is compressing hardware boundaries while regulatory energy mandates and shifting retail channel structures reshape how silicon reaches end-device manufacturers.
Software-defined radio architectures are virtualizing tuner and demodulator functions that previously required discrete RF components. Tier-one TV OEMs in Korea and Japan are adopting these platforms for 2024-2025 product cycles. This shift is virtualizing the traditional boundary between broadcast hardware and streaming application layers, collapsing BOM line items into programmable logic.
REACH and RoHS frameworks in Europe are restricting hazardous substances in semiconductor packaging, pushing foundries toward lead-free bumping and halogen-free substrate materials. The industrial consequence is elevated qualification costs for legacy product lines and accelerated end-of-life declarations for non-compliant components. Premium-tier panel manufacturers in Germany and the Netherlands are responding by mandating full material disclosure from SoC suppliers.
Cord-cutting households are displacing traditional operator-sourced set-top boxes with retail-purchased streaming sticks and smart TVs, fragmenting procurement authority from broadcast operators to consumer electronics retailers. This channel disintermediation is compressing volume commitments and elevating demand volatility for silicon vendors. The shift is most visible in North American and Western European markets where streaming penetration exceeds broadcast subscription rates.
Digital TV Soc Market Segmentation
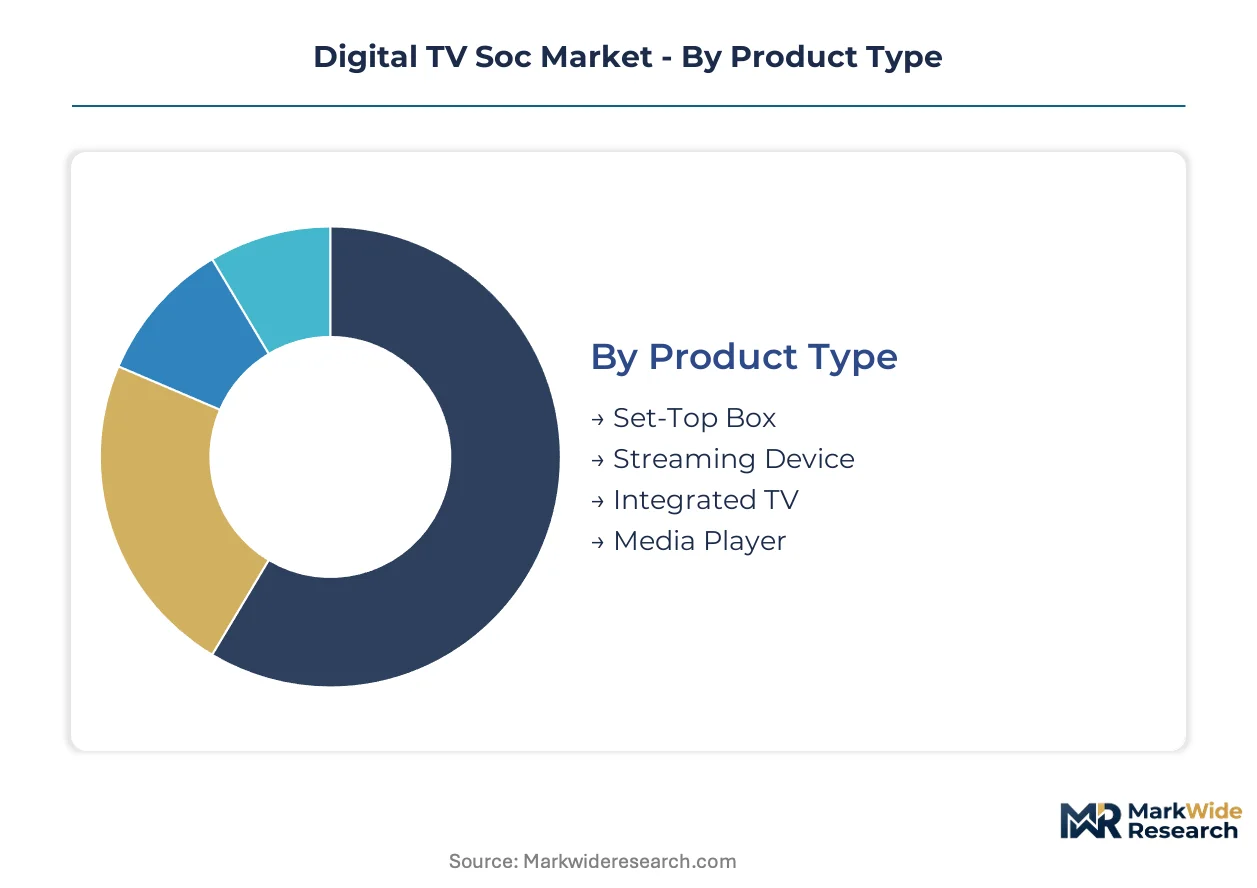
Segmentation in the Digital TV SoC market exposes divergent silicon requirements across device form factors and display technologies. Each category carries distinct thermal constraints, certification burdens, and replacement cycle dynamics that reshape vendor priorities.
Product Type:
After-sales service intensity varies sharply across these categories, with operator-deployed hardware demanding multi-year field support while retail devices shift liability to end users.
- Set-Top Box:A dedicated receiver unit connecting broadcast or IP-delivered content to display panels, typically housing tuner-demodulator pairs and conditional access modules. Demand concentrates in India and Latin America where cable and satellite operators subsidize hardware to secure subscription revenue, though cord-cutting pressures compress upgrade cycles in mature markets.
- Streaming Device:Compact HDMI dongles or pucks running lean operating systems optimized for over-the-top content delivery. Shenzhen-based OEMs are scaling production of cost-optimized SoCs for this segment, capitalizing on retail channel expansion through Amazon and Walmart distribution networks.
- Integrated TV:Single-substrate platforms consolidating scaler, tuner, and smart OS functions directly into panel electronics. Korean and Japanese panel manufacturers source these chips for premium-tier product lines with 4K and 8K resolution support.
- Media Player:Standalone boxes prioritizing local file playback and home network streaming over broadcast reception. Niche positioning in professional AV installations and enthusiast markets limits volume scale.
Integrated TV holds the largest share; momentum sits with streaming devices.
Technology:
Cost tier stratification determines SoC thermal design power budgets and process node selection, with premium display technologies justifying advanced silicon investments.
- OLED:Self-emissive pixel arrays delivering infinite contrast ratios and sub-millisecond response times. LG Display and Samsung Display fabs in Korea anchor procurement for high-end television lines, where image processing algorithms demand substantial GPU compute.
- QLED:Quantum dot-enhanced LED backlights extending color gamut coverage. Chinese panel manufacturers in Hefei and Shenzhen are expanding capacity for this mid-premium tier, creating captive demand for cost-optimized yet feature-rich SoC platforms.
- LED:Direct-lit and edge-lit configurations dominating emerging market volume. Indian and Indonesian OEMs prioritize this technology for price-sensitive retail segments.
- LCD:Legacy liquid crystal architectures retaining share in commercial signage and hospitality applications where brightness and durability outweigh contrast performance.
OLED commands premium positioning; QLED is climbing the fastest.
Application:
Customer type heterogeneity splits procurement authority between retail consumers, systems integrators, and facility managers with divergent specification priorities.
- Home Entertainment:The core consumption environment for broadcast and streaming content. Residential households in China and the United States drive volume, with smart home convergence expanding silicon content per installation through voice assistant and sensor integration.
- Smart Home Integration:Television as central control hub for climate, security, and lighting systems. European markets under EU Ecodesign mandates show particular appetite for energy-efficient platforms that reduce standby power consumption.
- Gaming:Low-latency display requirements and variable refresh rate support. Console manufacturers and PC peripheral vendors specify enhanced HDMI 2.1 feature sets.
- Online Streaming:Pure over-the-top consumption without broadcast tuner requirements. This segment expands most quickly in North American and Western European markets where subscription video services displace traditional cable.
Home Entertainment holds the largest share; momentum sits with online streaming.
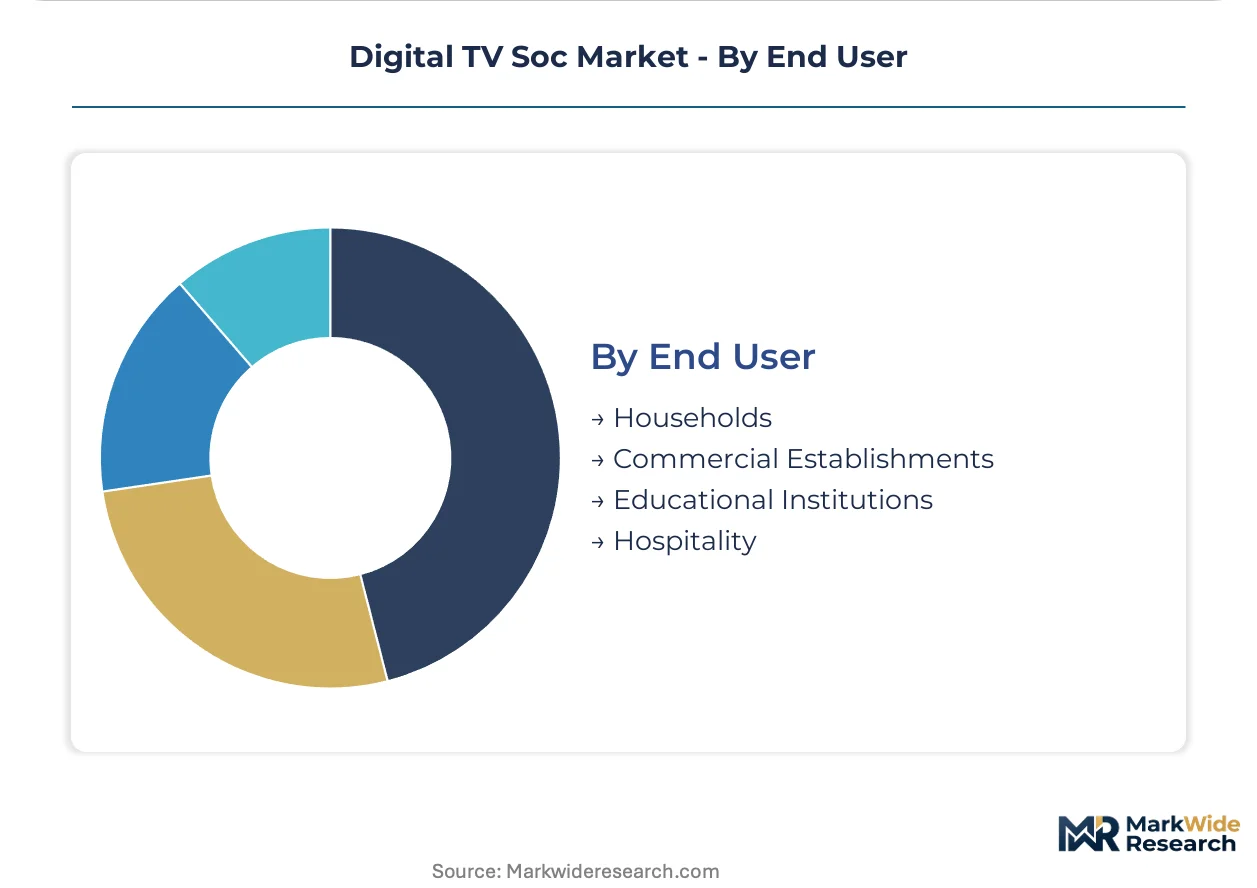
End User:
Volume concentration versus margin capture trade-offs differentiate procurement patterns across these customer categories.
- Households:Individual consumers purchasing through retail channels or receiving operator-subsidized equipment. China's domestic market scale dominates global unit volume for this segment.
- Commercial Establishments:Corporate lobbies, retail environments, and healthcare facilities requiring durable signage solutions. Extended warranty and remote management capabilities drive SoC selection.
- Educational Institutions:K-12 and university deployments emphasizing interactive whiteboard integration and content casting. Government procurement frameworks in India and Brazil shape vendor access.
- Hospitality:Hotel and cruise line installations demanding lockdown configurations and centralized content management. Customized firmware requirements extend qualification timelines.
Households hold the largest share; commercial establishments show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shenzhen anchors Asia-Pacific semiconductor logistics, handling over 25 million TEUs annually and connecting Yangtze River Delta fabrication clusters to global TV OEM assembly lines.
United States
ATSC 3.0 tuner mandates from the FCC are pulling demand for next-generation RF front-end integration across smart TV and set-top box categories. The FCC's Part 15 EMC rules and Part 74 broadcast equipment certifications extend product qualification timelines by 6-9 months. Austin and Dallas-Fort Worth semiconductor design clusters are expanding engineering headcount for software-defined demodulation architectures.
China
Domestic OEMs in Shenzhen and Hefei are vertically integrating tuner, scaler, and OS functions onto single substrates, reducing import dependency for broadcast decoding components. MIIT certification rules and GB standards govern terrestrial broadcast decoding and cybersecurity features for domestic retail channels. The Yangtze River Delta fabrication corridor is scaling 12nm to 7nm capacity for integrated TV platforms.
Germany
EU Ecodesign Regulation tightening standby power limits is accelerating replacement cycles for energy-intensive legacy television hardware. REACH and RoHS frameworks restrict hazardous substances in semiconductor packaging, pushing foundries toward lead-free bumping. Dresden's semiconductor cluster is expanding advanced packaging capacity for TV SoC fabrication serving premium-tier panel manufacturers.
India
The PLI scheme for electronics manufacturing is attracting set-top box and smart TV assembly, creating captive demand for cost-optimized SoC platforms. TRAI broadcast distribution regulations and BIS certification requirements shape hardware specifications for operator-deployed equipment. Noida and Sriperumbudur industrial corridors are consolidating EMS capacity for domestic and export-bound TV production.
South Korea
OLED panel manufacturers in Gyeonggi Province are sourcing premium-tier SoCs with 4K and 8K resolution support and HDR processing capabilities. METI-aligned energy efficiency standards and KC certification rules govern domestic retail hardware specifications. Suwon and Hwaseong semiconductor design centers are integrating neural processing units with video decoding pipelines for on-device AI features.
Digital TV Soc Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying discrete tuner-demodulator IP and RF front-end modules. The vendor base stratifies across three tiers: fabless design houses with integrated design-to-test workflows, IDMs with captive fabrication and advanced packaging capabilities, and specialist demodulator IP licensors. Dominant competitive moves include strategic partnerships between SoC vendors and panel manufacturers for reference design co-development, plus geographic expansion into India and Vietnam to capture PLI-driven assembly demand.
Within the fabless design tier, MediaTek Inc. and Realtek Semiconductor Corp. represent cost-optimized platform specialists serving high-volume integrated TV and streaming device segments. Broadcom Inc. occupies a position upstream in premium-tier supply through control over DOCSIS and Wi-Fi silicon blocks. These three entities exemplify the competitive archetypes defining procurement authority across operator, retail, and panel-direct channels.
| Leading Market Players |
|---|
| MediaTek Inc. |
| Broadcom Inc. |
| Samsung Electronics Co., Ltd. |
| Qualcomm Technologies Inc. |
| STMicroelectronics N.V. |
| Novatek Microelectronics Corp. |
| Realtek Semiconductor Corp. |
| NXP Semiconductors N.V. |
| Renesas Electronics Corporation |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta fabrication clusters anchor global TV SoC wafer supply, with TSMC and Samsung Foundry capacity allocation decisions directly determining margin capture for fabless design houses serving cost-optimized streaming device tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations. Premium-tier integrated TV platforms command substantial markups based on 8K HDR certification and advanced node allocation, while economy streaming sticks face acute price compression from Shenzhen-based OEMs. Cost compression in mid-tier set-top boxes is intensifying because domestic Chinese vendors are scaling captive tuner-demodulator production. Operator-deployed hardware exhibits lowest price sensitivity due to multi-year service bundling; retail streaming devices show highest sensitivity with direct consumer price comparison.
Supply Chain Analysis
High-purity silicon wafer feedstock draws from Japanese and German chemical processing clusters, with photoresist and specialty gas inputs resting on concentrated supply from Belgium and the United States. Taiwan, South Korea, and China dominate frontend fabrication capacity for 12nm to 7nm process nodes. Single-source vulnerability concentrates in EUV lithography equipment where ASML holds effective monopoly. Distribution runs through Shenzhen and Hong Kong logistics hubs connecting Yangtze River Delta foundries to global TV OEM assembly lines in Vietnam and Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ATSC 3.0 mandate represents a high-growth disruption, pulling demand for software-defined demodulation architectures while compressing margins for legacy tuner IP holders unable to pivot.
For Market Incumbents: Build switching-cost moats through reference design co-development with Korean and Japanese panel manufacturers. Defensive consolidation centers on acquiring discrete demodulator IP specialists to fill RF analog capability gaps. Threat from cord-cutting acceleration demands channel control expansion into retail streaming stick distribution. R&D priority lever sits with neural processing unit integration for on-device AI features. For New Entrants and Emerging Players: Build out white-space presence in India's PLI-driven set-top box assembly corridor and Vietnam's emerging smart TV export manufacturing. Most penetrable segment is cost-optimized streaming devices where Shenzhen OEMs lack integrated OS-tuner-scaler platforms. Go-to-market angle emphasizes MIIT certification pre-qualification for China domestic channel access. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fabless design houses with software-defined radio architectures and advanced packaging partnerships. Long-term viability over the next decade hinges on RF analog design talent scarcity resolution. Acquisition target archetype: demodulator IP licensors with FCC Part 15 and CE marking validation completed. Signal to watch is ATSC 3.0 penetration rate in North American retail channels as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Reference Design Co-Development | Locks panel manufacturers into multi-year SoC procurement commitments with MediaTek and Realtek. |
| Software-Defined Radio Architecture | Virtualizes tuner functions at Broadcom, collapsing BOM line items for tier-one Korean OEMs. |
| India PLI Scheme Manufacturing Entry | Captures set-top box assembly demand from TRAI-regulated operator deployments in Noida corridor. |
| Advanced Packaging Capacity Expansion | Dresden and Taiwan clusters enable 7nm TV SoC thermal management for 8K HDR processing. |
| Neural Processing Unit Integration | Suwon design centers embed on-device content recommendation without cloud dependency for Samsung. |
Methodological Framework
Initial hypotheses were tested against primary input from semiconductor design executives, foundry account managers, TV OEM procurement directors, and broadcast equipment regulatory specialists and refined through secondary validation. Primary fieldwork combined structured interviews with fabless design house engineering leads and panel manufacturer supply chain managers. Secondary sources encompassed FCC equipment authorization databases, MIIT certification filings, EU Ecodesign directive implementation reports, and SEC 10-K disclosures from publicly traded semiconductor vendors. Bottom-up wafer demand modeling triangulated against top-down consumer electronics shipment forecasts.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include device form factor, display technology tier, application environment, and end-user procurement authority. CAGRs were derived from shipment volume trajectories and silicon content per unit assumptions. Industry-specific forecast inputs incorporated ATSC 3.0 mandate compliance timelines and EU Ecodesign standby power limit phase-ins.
Stress conditions across foundry capacity allocation, raw material input cost volatility, and regional tuner standard fragmentation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding broadcast protocol adoption curves and smart home convergence penetration. Cross-checking against hyperscaler set-top box deployment disclosures and panel manufacturer capex guidance is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
Voice Communication Equipment Market
Telecom Hardware
Industrial Transceivers Market
Telecom Hardware
Point-To-Point Antenna Market
Telecom Hardware
Infiniband Market
Telecom Hardware
Satellite Communication Terminal Market
Telecom Hardware
Global Virtualized Evolved Packet Core (VEPC) Market
Telecom Hardware
Broadcast Antenna Market
Telecom Hardware
Global LTE Modems Market
Telecom Hardware
Commercial Antennas Market
Telecom Hardware
OTN Hardware Market
Telecom Hardware
Room Cell Module Market
Telecom Hardware
Africa Small Cell Market
Telecom Hardware
SATCOM Transceivers Market
Telecom Hardware
Base Station Market
Telecom Hardware
Subscriber Identity Module (SIM) Market