
 Global Virtualized Evolved Packet Core (VEPC) Market | 2026-2036
Global Virtualized Evolved Packet Core (VEPC) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtualized Evolved Packet Core (VEPC) Market Foresight
Cloud-native VEPC specifications are reorganizing procurement criteria for tier-one mobile operators. Samsung Electronics leverages its end-to-end 5G portfolio to anchor large-scale deployments across Asian markets. Ericsson competes through R&D intensity in automated orchestration and slice lifecycle management. Nokia Corporation differentiates via geographic dominance in European telecommunications infrastructure.
Virtualized Evolved Packet Core refers to a software-based implementation of the 3GPP-defined mobile core network architecture, decoupling control and user plane functions from proprietary hardware through network function virtualization and containerized microservices operating on commercial-off-the-shelf servers. Its primary industrial purpose is enabling elastic scaling, rapid service deployment, and multi-tenant network slicing for 5G and advanced LTE networks. Deployment models show hybrid cloud configurations capturing margin pools from operators balancing latency requirements against capital efficiency. Solution type segmentation reveals network slice management as the fastest-expanding category driven by enterprise verticals requiring isolated quality-of-service guarantees.
FCC spectrum policies in the United States, ETSI NFV standards across Europe, and MIIT 5G licensing frameworks in China collectively shape vendor qualification requirements and interoperability testing protocols. The EU AI Act introduces emerging compliance dimensions for automated network optimization algorithms embedded within VEPC orchestration layers. Stakeholders must monitor how open RAN interface specifications from the O-RAN Alliance reshape supplier ecosystems and procurement strategies for cloud-native core infrastructure.
Market Dynamics
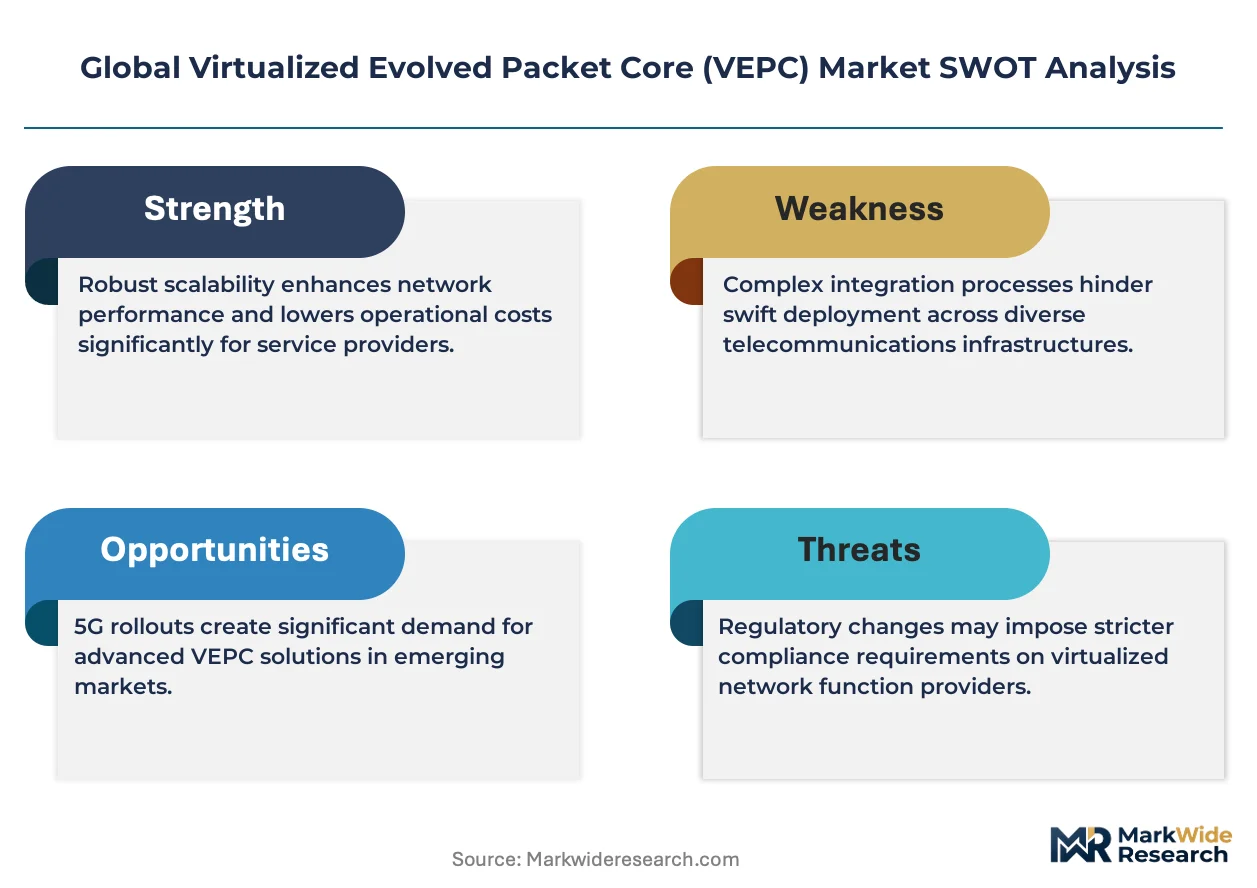
Cloud-native VEPC architectures are decomposing the mobile core into containerized microservices, forcing operators to restructure procurement around ETSI NFV compliance and automated orchestration capabilities rather than legacy hardware specifications.
Growth Catalysts
- 5G Standalone Core Mandates:South Korea's Ministry of Science and ICT spectrum allocation terms require operators to deploy cloud-native cores for mid-band 5G services, accelerating VEPC procurement cycles.
- ETSI NFV Release 4 Standards:The updated network function virtualization framework introduces automated lifecycle management specifications that reduce integration testing timelines for multi-vendor deployments.
- Enterprise Network Slicing:Manufacturing verticals in Germany demand isolated quality-of-service guarantees for industrial IoT, creating dedicated VEPC procurement streams separate from consumer mobile cores.
Market Restraints
- Specialized Engineering Talent Scarcity:Kubernetes orchestration expertise for telco-grade workloads concentrates in Silicon Valley, Stockholm, and Seoul, inflating implementation costs for operators outside these clusters.
- Legacy Hardware Stranding Risk:Proprietary packet core appliances from incumbent suppliers retain residual value on operator balance sheets, creating accounting friction for accelerated replacement timelines.
- Interoperability Certification Burden:GSMA's 5G security specifications and 3GPP release compliance testing add eighteen-to-twenty-four month qualification periods for new vendor entrants.
Strategic Opportunities
- India Telecom Infrastructure:Reliance Jio and Bharti Airtel's 5G core modernization programs under TRAI's national broadband targets create greenfield deployment opportunities without legacy migration constraints.
- Open RAN Interface Convergence:O-RAN Alliance specifications for open fronthaul and midhaul interfaces enable disaggregated VEPC procurement from specialized software vendors rather than integrated system suppliers.
- Edge Computing Co-location:Multi-access edge computing deployments in Germany's Industrie 4.0 zones require distributed user plane functions, creating new VEPC architectural variants optimized for factory-floor latency requirements.
Industry Challenges
- Cloud-Native Skill Migration:Mobile operators must retrain existing network engineering teams in container orchestration and CI/CD pipelines, competing for talent against hyperscale cloud providers.
- Hybrid Integration Complexity:Operators maintaining parallel 4G EPC and 5G VEPC instances face state synchronization challenges during inter-system handovers that degrade service continuity metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtualized Evolved Packet Core (VEPC) Market |
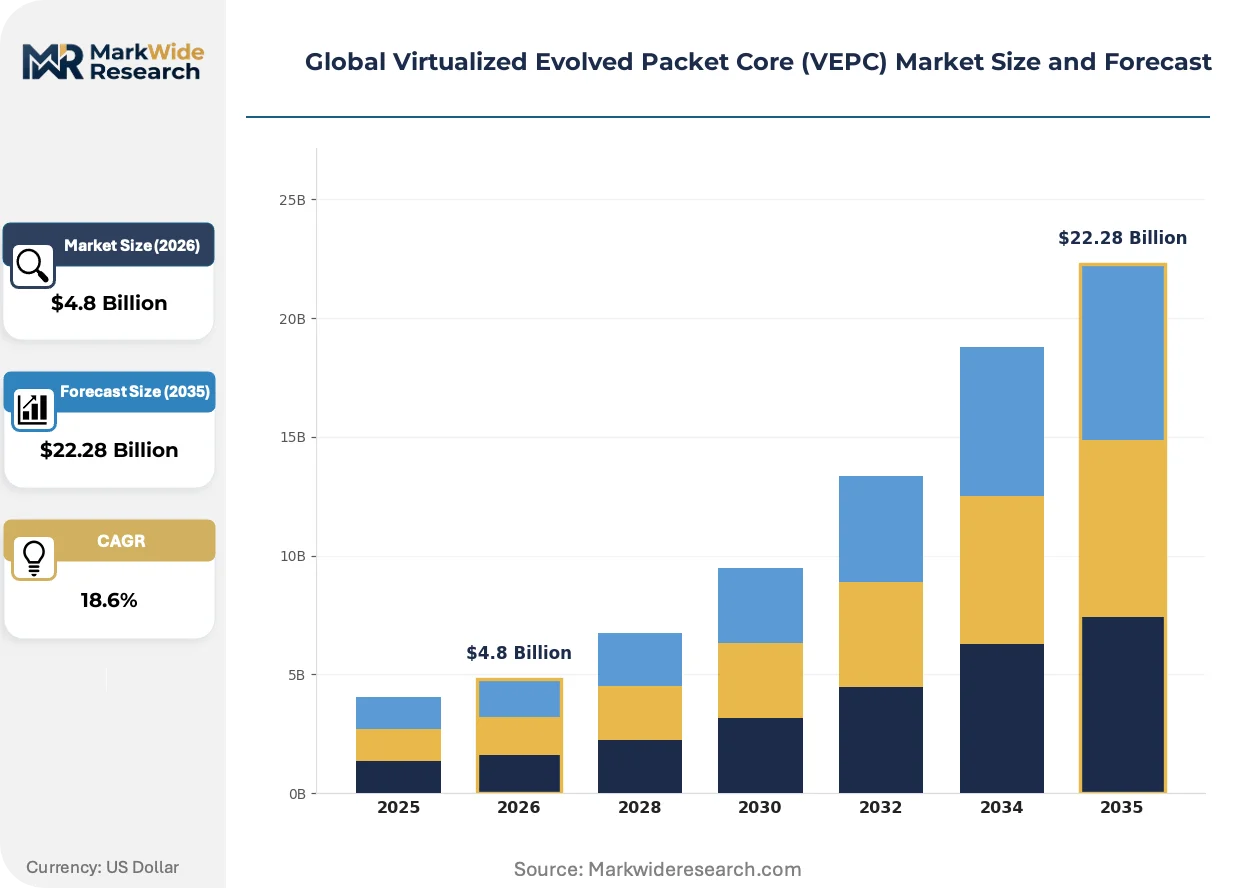
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud, Edge Computing Solution Type: Core Network Function Virtualization, Network Slice Management, Session Management, Policy Control, Subscriber Data Management Use Case: Mobile Broadband, Fixed Wireless Access, Internet of Things, Voice over LTE, Mission-Critical Communications End User: Mobile Network Operators, Infrastructure Providers, System Integrators, Service Providers, Virtual Network Operators |
| Companies Covered | Cisco Systems, Samsung Electronics, Ericsson, Mavenir, NEC Corporation, Huawei Technologies, ZTE Corporation, Affirmed Networks, Nokia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtualized Evolved Packet Core (VEPC) Market Shifts & Advancements
Service-based architectures are reorganizing how mobile operators procure, deploy, and scale core network functions. Three distinct shifts are compressing traditional vendor relationships and procurement cycles.
Containerized VEPC implementations are decomposing monolithic packet core functions into discrete microservices. Tier-one operators in the United States are migrating control plane functions to Kubernetes clusters ahead of user plane transitions. This decomposition enables independent scaling of authentication, session management, and charging functions based on real-time traffic patterns rather than peak-capacity hardware provisioning.
The EU AI Act introduces algorithmic transparency requirements for automated network optimization systems embedded within VEPC orchestration layers. European operators must now document decision logic for load-balancing and fault-recovery automation. German and French regulators are requiring model cards and bias assessments for machine learning components managing network slice allocation.
Enterprise procurement teams are consolidating mobile core decisions with private network infrastructure purchases. Manufacturing and logistics verticals in South Korea are issuing combined RFPs for 5G radio access, edge computing, and VEPC functions from single accountability sources. This bundling compresses vendor evaluation cycles and shifts technical risk allocation toward system integrators.
Global Virtualized Evolved Packet Core (VEPC) Market Segmentation
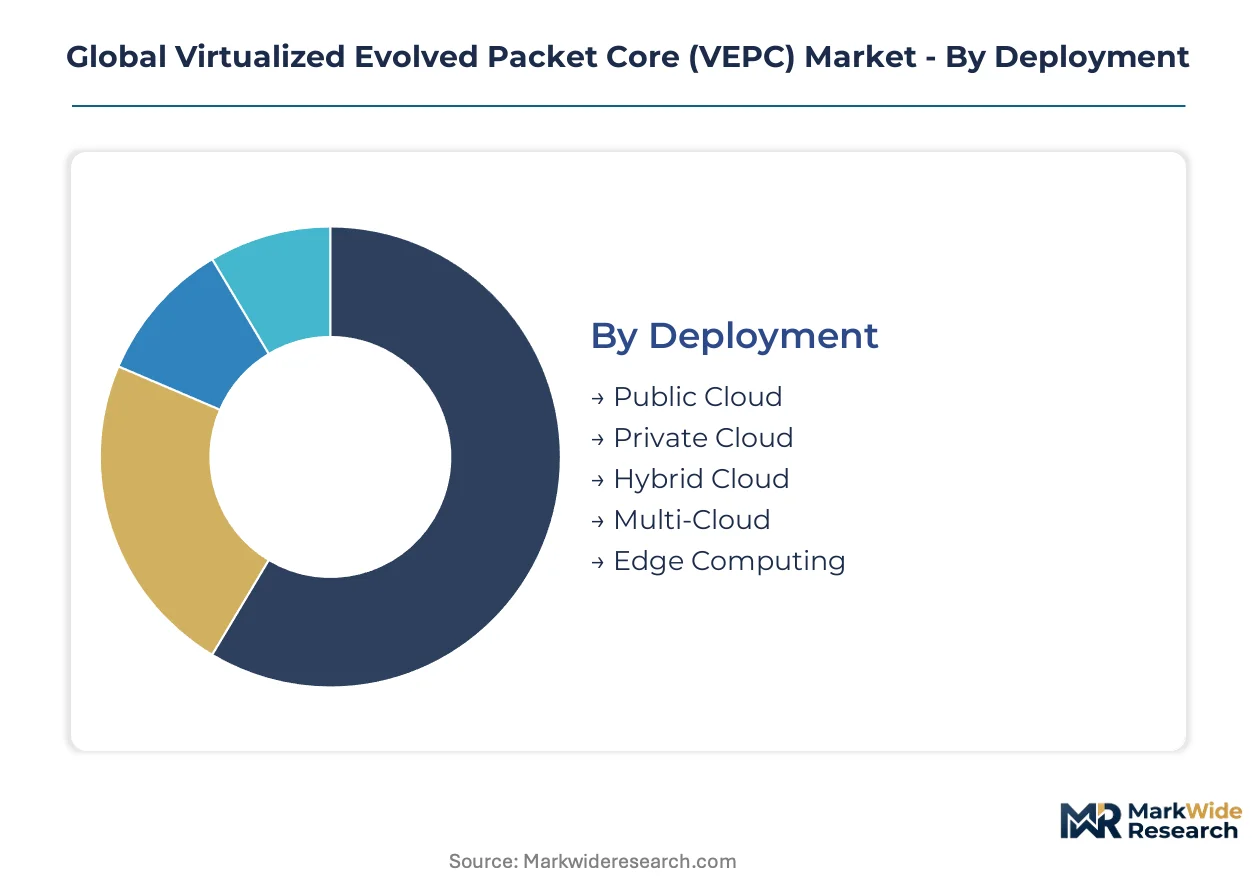
VEPC procurement patterns diverge sharply across deployment topologies and solution architectures. Operators in South Korea and Germany prioritize slice management capabilities for industrial verticals, while US carriers emphasize hybrid cloud configurations balancing latency against capital efficiency. Understanding these segment boundaries clarifies where vendor consolidation concentrates versus where specialized entrants retain opportunity.
Deployment:
Geographic concentration varies by cloud topology. Edge computing deployments cluster around manufacturing zones in Germany and spectrum-dense urban corridors in South Korea, while multi-cloud strategies dominate US operator procurement.
- Public Cloud:Third-party infrastructure hosts control plane functions on hyperscale platforms. South Korean operators under MSIT spectrum mandates deploy here for rapid 5G SA core scaling with minimal capital commitment.
- Private Cloud:Dedicated infrastructure on operator premises delivers regulatory data sovereignty and sub-10ms latency guarantees. German Industrie 4.0 zones demand this topology for factory-floor user plane anchoring.
- Hybrid Cloud:Split architectures place control functions in central data centers while distributing user plane processing. US tier-one operators favor this for balancing elastic scaling against hardware asset utilization.
- Multi-Cloud:Workload portability across competing hyperscale providers prevents vendor lock-in. Procurement concentrates among North American operators negotiating rate arbitrage across AWS, Azure, and Google Cloud.
- Edge Computing:Distributed micro-data centers collocate VEPC functions with radio access infrastructure. South Korean smart factory deployments and German automotive testbeds drive specialized variants optimized for sub-5ms latency.
Hybrid cloud commands the established base. The steepest expansion runs through edge computing.
Solution Type:
Functional decomposition intensity separates cost tiers. Network slice management commands premium pricing for guaranteed isolation, while subscriber data management operates as a commoditized foundation layer.
- Core Network Function Virtualization:Base virtualization layer decouples packet gateway, mobility management, and serving gateway from proprietary hardware. South Korea's three mobile operators completed nationwide deployments, shifting procurement focus to lifecycle automation.
- Network Slice Management:Orchestration layer provisions isolated virtual networks with distinct quality-of-service profiles. Manufacturing verticals in Germany demand this for separating industrial IoT traffic from consumer mobile data on shared infrastructure.
- Session Management:State maintenance for subscriber connectivity handles authentication, bearer establishment, and handover coordination. Mature functionality with limited differentiation across ETSI NFV-compliant vendors.
- Policy Control:Real-time traffic shaping and charging rule enforcement. Integration with BSS/OSS layers determines procurement decisions among European operators modernizing revenue assurance systems.
- Subscriber Data Management:Unified repositories for authentication credentials, service profiles, and location information. Migration from legacy HSS systems creates replacement demand without architectural transformation.
Core network function virtualization anchors current revenue pools. Network slice management gains share fastest through enterprise vertical penetration.
Use Case:
Application maturity drives volume concentration. Mobile broadband saturates developed markets while fixed wireless access and mission-critical communications expand the addressable base.
- Mobile Broadband:Consumer data and video delivery over 4G and 5G networks. South Korea's 5G subscriber density exceeds 50 percent penetration, compressing incremental VEPC investment to capacity augmentation.
- Fixed Wireless Access:Residential and enterprise broadband substitution using 5G radio instead of fiber or cable. US operators deploy this aggressively in rural markets under FCC rural digital opportunity fund requirements.
- Internet of Things:Massive machine-type communications and ultra-reliable low-latency connectivity. German automotive and logistics sectors specify this for fleet management and predictive maintenance applications.
- Voice over LTE:Circuit-switched voice replacement using IMS-anchored packet transport. Declining segment as operators complete 3G sunsetting and VoLTE becomes table stakes.
- Mission-Critical Communications:Public safety and emergency services requiring guaranteed availability and priority preemption. South Korea's national public safety LTE network drives specialized hardening requirements.
Mobile broadband absorbs the majority of current deployment volume. Fixed wireless access shows the steepest trajectory as fiber-alternative economics improve.
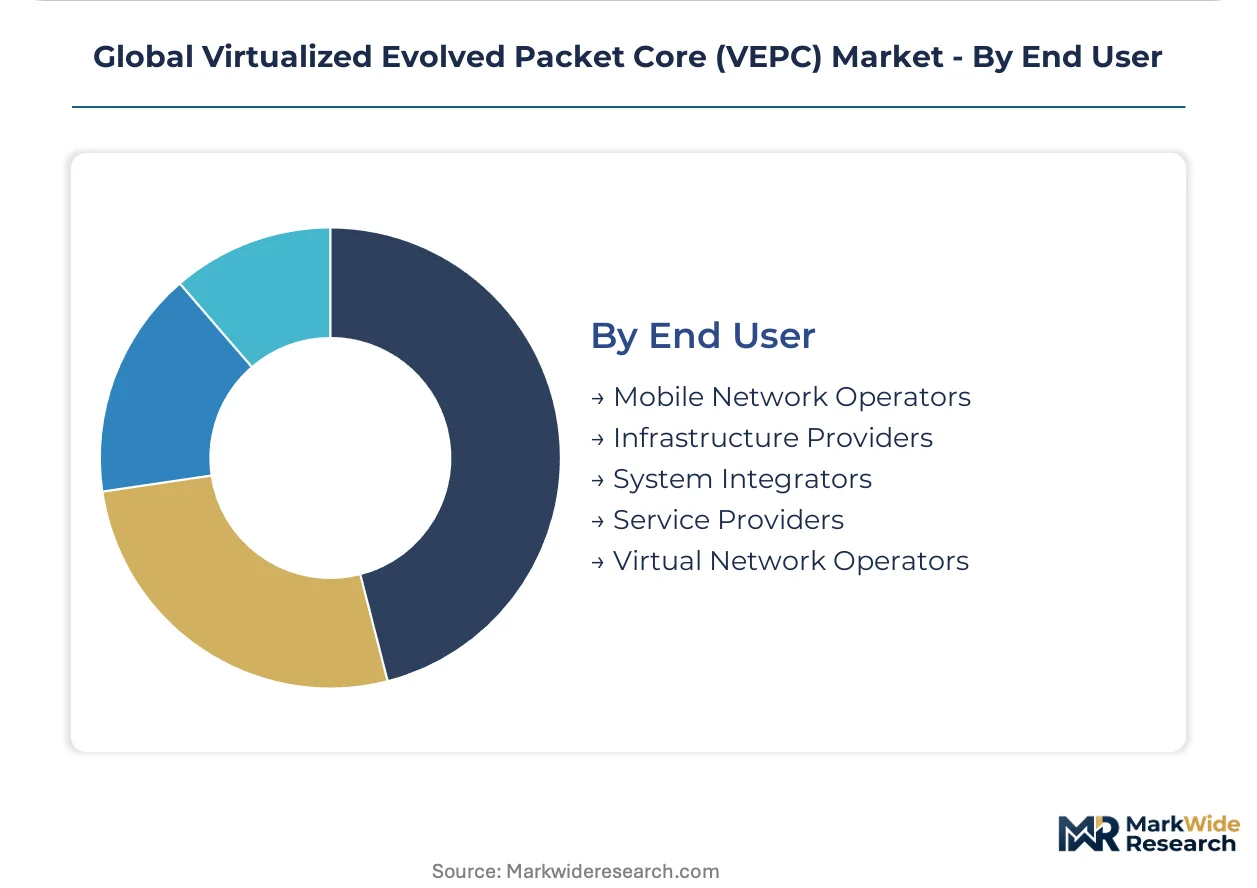
End User:
Customer type determines integration complexity and contract structure. Mobile network operators demand full stack accountability while virtual network operators seek disaggregated procurement.
- Mobile Network Operators:Tier-one and tier-two carriers owning spectrum licenses and subscriber relationships. South Korea's SK Telecom, KT, and LG Uplus anchor regional procurement volumes through consolidated national deployments.
- Infrastructure Providers:Tower companies and data center operators hosting neutral-host VEPC infrastructure. German market sees Deutsche Funkturm and Vantage Towers expanding into edge compute hosting.
- System Integrators:Professional services firms assembling multi-vendor solutions for operator clients. Accenture and Deloitte compete for 5G core transformation contracts with managed service overlays.
- Service Providers:Enterprise-facing entities delivering private 5G and network slicing as-a-service. Manufacturing verticals in Germany procure through this channel for single-accountability industrial network deployments.
- Virtual Network Operators:Resellers without physical infrastructure leasing capacity from host networks. Limited VEPC procurement direct to vendors; typically consume slices provisioned by host MNOs.
Mobile network operators dominate current spending. Service providers expand most quickly as enterprise private network adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor engineering resources cluster in Stockholm, Seoul, and Silicon Valley, creating implementation bottlenecks for operators outside these metropolitan technology corridors. This geographic concentration shapes procurement timelines and support availability across national deployment programs.
United States
Verizon and AT&T drive hybrid cloud VEPC procurement under FCC spectrum auction conditions requiring rapid 5G standalone core deployment. The FCC's 3.5 GHz CBRS framework enables private network variants that industrial enterprises deploy alongside carrier infrastructure. Seattle and Austin host Kubernetes orchestration talent pools that operators tap for cloud-native migration programs.
Germany
Deutsche Telekom and Vodafone anchor European VEPC volumes through Industrie 4.0 network slicing mandates. The EU AI Act imposes algorithmic documentation requirements on automated orchestration systems managing factory-floor latency guarantees. Bavaria's automotive testbeds around Munich and Ingolstadt demand sub-5ms user plane configurations for connected vehicle validation.
South Korea
SK Telecom, KT, and LG Uplus completed nationwide cloud-native core deployments under MSIT spectrum licensing terms requiring 5G SA architecture. The Korea Communications Commission enforces interoperability testing that compresses multi-vendor integration cycles. Seoul Capital Area concentration enables rapid field engineering response for enterprise slice provisioning.
China
China Mobile, China Telecom, and China Unicom pursue massive-scale VEPC deployment under MIIT 5G licensing frameworks emphasizing domestic vendor qualification. GB standards for network function virtualization shape procurement specifications that favor indigenous suppliers. Beijing and Shanghai host concentrated R&D facilities developing automated lifecycle management for containerized core functions.
India
Reliance Jio and Bharti Airtel execute greenfield 5G core modernization under TRAI national broadband targets without legacy hardware migration constraints. The Department of Telecommunications mandates security clearance protocols that extend vendor qualification timelines. Mumbai and Bangalore clusters attract container orchestration specialists from hyperscale cloud providers for telco workload transitions.
Global Virtualized Evolved Packet Core (VEPC) Market Competitive Landscape
Concentration sits with integrated telecom infrastructure suppliers holding end-to-end 5G portfolios spanning radio access through core network layers. The vendor landscape organizes around three strategic archetypes: diversified technology conglomerates with semiconductor-to-services integration, pure-play network equipment specialists, and cloud-native software vendors challenging hardware-centric incumbents. Dominant competitive moves include R&D intensity in automated orchestration and strategic partnerships with hyperscale cloud providers for hybrid deployment topologies.
Within the diversified technology tier, Samsung Electronics and Huawei Technologies exemplify integrated suppliers leveraging captive semiconductor capabilities and radio access expertise to anchor comprehensive 5G core proposals. Ericsson and Nokia Corporation occupy positions as European-headquartered network specialists with geographic dominance in their respective home markets and established operator relationships across legacy infrastructure generations. Mavenir represents the cloud-native software archetype, challenging hardware-anchored competitors through containerized microservices architectures and open interface advocacy.
| Leading Market Players |
|---|
| Cisco Systems |
| Samsung Electronics |
| Ericsson |
| Mavenir |
| NEC Corporation |
| Huawei Technologies |
| ZTE Corporation |
| Affirmed Networks |
| Nokia Corporation |
| Others |
Supply & Pricing Matrix
Containerized microservices architectures are displacing proprietary hardware appliances across mobile core procurement, simultaneously shifting supply geography toward hyperscale cloud regions and compressing pricing premiums previously commanded by integrated system vendors. This substitution dynamic restructures cost allocation between software licensing and infrastructure-as-a-service consumption.
Pricing Analysis
ETSI NFV Release 4 standards dictate the pricing tier structure across VEPC procurement, separating certified multi-vendor orchestration platforms from single-source integrated stacks. Three-tier pricing stratifies across premium certified orchestration, standard compliant virtualization, and economy containerized alternatives. Cost compression in the standard tier is intensifying because Korean and German operators are consolidating vendor panels under interoperability mandates. Virtual network operators exhibit the highest price sensitivity due to thin wholesale margins, while industrial enterprises in German automotive zones prioritize latency guarantees over unit economics.
Supply Chain Analysis
Kubernetes orchestration expertise concentration in Silicon Valley, Stockholm, and Seoul creates a talent chokepoint that underwrites implementation timeline risk and inflates professional services premiums. Software development draws from Indian engineering centers, Taiwanese semiconductor fabrication for underlying servers, and German precision manufacturing for edge computing enclosures. Single-source vulnerability concentrates in container orchestration platforms where Red Hat OpenShift and VMware Tanzu dominate telco-grade deployments. Distribution runs through direct enterprise sales for tier-one operators and systems integrator channels for mid-market mobile network operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VEPC market sits at a cyclical recovery phase driven by 5G standalone core replacement cycles, with capital deployment accelerating as spectrum auction obligations mature across South Korea, Germany, and the United States.
For Market Incumbents: Fortify automated orchestration capabilities through R&D investment in slice lifecycle management, as Mavenir and other cloud-native specialists threaten margin pools in multi-vendor deployments. Deepen backward integration into container platforms through strategic partnerships with Red Hat or VMware to secure supply chain positioning for Kubernetes-dependent implementations. Prioritize certification investment under GSMA security specifications to extend qualification barriers against emerging entrants. For New Entrants and Emerging Players: Lead with edge-optimized user plane functions targeting German Industrie 4.0 zones where sub-5ms latency requirements outstrip incumbent architectural flexibility. Private 5G deployments for manufacturing verticals represent the most penetrable segment, with single-accountability procurement models compressing vendor evaluation cycles. Pursue a channel partnership strategy with systems integrators like Accenture or Deloitte to bypass direct operator sales barriers. For Investors and Strategic Acquirers: The market sits at an infrastructure replacement phase that favors cloud-native software vendors over hardware-anchored incumbents. Long-term viability hinges on container orchestration expertise and open interface compliance rather than legacy radio access integration. Target acquisition profiles should emphasize firms with Kubernetes-native architectures and ETSI NFV certification completion. Watch O-RAN Alliance specification adoption rates as the inflection indicator for disaggregated procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Integration | Containerized microservices enable elastic scaling for Korean 5G SA core deployments. |
| Network Slice Management Specialization | Isolated quality-of-service guarantees unlock German industrial IoT procurement streams. |
| Strategic Partnership with Hyperscalers | AWS and Azure co-location addresses US operator hybrid cloud latency requirements. |
| Acquisition of Orchestration Specialist | Kubernetes expertise scarcity in Stockholm and Seoul inflates organic build timelines. |
| ETSI NFV Release 4 Certification | Automated lifecycle management specifications reduce Korean operator integration testing. |
Research Methodology
The analysis maps deployment topology segments, solution type categories, and end-user archetypes, each validated through chief technology officers at mobile network operators, procurement directors at industrial enterprises, and network architects at systems integrators. Primary fieldwork combined structured interviews with secondary validation against ETSI NFV specification documents, 3GPP release compliance filings, and GSMA security certification registries. Bottom-up deployment volume estimates triangulated against top-down operator capex disclosures across the analysis window.
Consistency checks validated volume and value outputs against hyperscaler infrastructure revenue segments and telecom equipment vendor reporting. The forecast framework modeled deployment models, solution types, use cases, and end-user segments across the projection horizon, with CAGRs derived from operator procurement cycle analysis and spectrum auction obligation timelines. Industry-specific inputs included 5G standalone core migration schedules and enterprise network slicing adoption curves.
Underlying assumptions cover ETSI NFV standardization timelines and operator cloud-native skill acquisition rates, with deviation risk concentrated in regulatory interoperability testing extensions. Forecasts reflect these documented conditions, with revision becoming warranted when O-RAN Alliance specification adoption crosses commercial deployment thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Global Microwave Transmission Equipment Market
Telecom Hardware
Point-To-Point Antenna Market
Telecom Hardware
Repeaters Market
Telecom Hardware
Asia Pacific Enterprise Routers Market
Telecom Hardware
4G Equipment Market
Telecom Hardware
5G Temperature-Compensated Crystal Oscillator (TCXO) Market
Telecom Hardware
Synchronous Optical Network (SONET) Market
Telecom Hardware
Europe Zero-Touch Provisioning Market
Telecom Hardware
Microwave Antenna Market
Telecom Hardware
Set-Top Box Market
Telecom Hardware
Digital Smart Set-Top Box (STB) Market
Telecom Hardware
Subscriber Identity Module (SIM) Market
Telecom Hardware
SATCOM Transceivers Market
Telecom Hardware
Telecom Equipment Market
Telecom Hardware
Satellite Communication Terminal Market
Telecom Hardware
Digital TV Soc Market