
 Repeaters Market | 2026-2036
Repeaters Market Size, Share, and Industry Trends Forecast 2026-2036
Repeaters Market Analysis
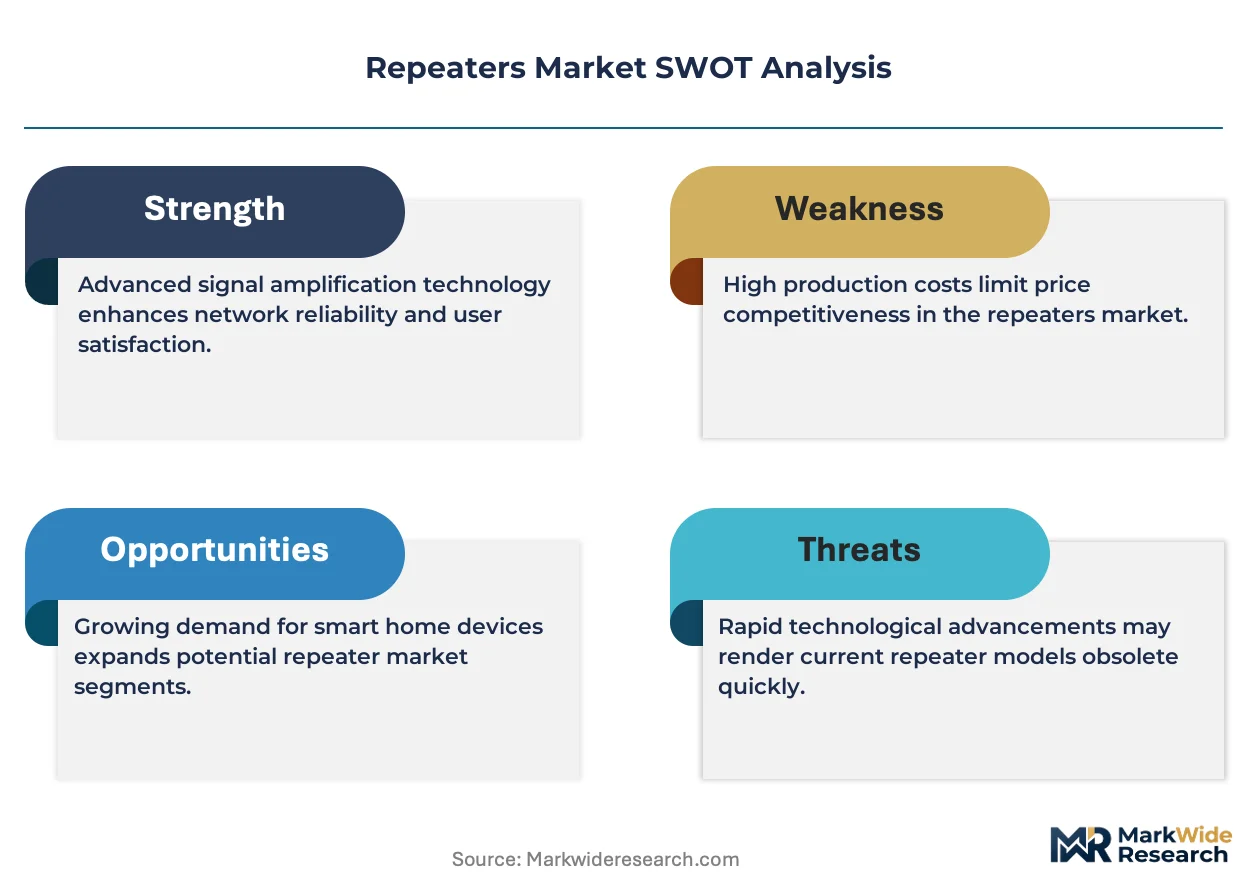
A wide capability gap in semiconductor sourcing and RF front-end design is bifurcating competitive tiers across the repeaters landscape. CommScope leverages captive antenna and cable portfolios to bundle full-path solutions for carrier customers. Huawei Technologies anchors its position through in-house baseband and power amplifier fabrication, insulating margins from component volatility. Motorola Solutions differentiates via public-safety certification depth, controlling access to mission-critical频段 segments that generalist vendors cannot serve.
Repeaters are signal regeneration devices that amplify, reshape, and retransmit attenuated communications signals across copper, coaxial, fiber, or wireless media, typically operating at specified gain levels and noise figures to preserve data integrity over extended distances. Their primary purpose spans extending cellular coverage into dead zones, boosting Wi-Fi reach across commercial facilities, and regenerating optical pulses in long-haul fiber networks where dispersion degrades signal quality. Wireless repeaters capture the largest revenue pool as outdoor macro densification and indoor distributed antenna system retrofits accelerate, while fiber optic repeaters are registering the fastest expansion driven by submarine cable upgrades and metro fiber ring extensions. Smart repeaters incorporating real-time interference cancellation and self-optimizing network algorithms command premium positioning as mobile operators prioritize automated spectrum management over static analog units.
FCC Part 20 and Part 27 rules in the United States mandate specific out-of-band emission limits and hearing aid compatibility for consumer signal boosters, directly shaping product architecture and testing costs for vendors seeking commercial distribution. CE marking under the EU Radio Equipment Directive and ETSI EN 301 489 standards enforce electromagnetic compatibility and spectrum efficiency thresholds that filter non-compliant imports from European telecommunications procurement channels. Stakeholders must monitor evolving 6 GHz unlicensed band allocations and national spectrum reframing decisions, as these regulatory shifts will determine which repeater architectures retain relevance and which require fundamental redesign.
Market Dynamics
5G network densification is fragmenting demand between macro outdoor amplification and indoor distributed antenna systems, forcing vendors to dual-track development roadmaps and certification pipelines without guaranteed carrier volume commitments.
Growth Catalysts
- Submarine cable modernization:Transoceanic fiber upgrades require optical repeaters with dispersion compensation. Cable consortiums in the Atlantic corridor are accelerating procurement timelines.
- FCC Part 20 hearing aid compatibility mandates:Consumer signal booster certification now requires specific emission controls. This filters marginal vendors from US commercial distribution channels.
- Smart repeater algorithms:Real-time interference cancellation and self-optimizing network management are commanding premium positioning. Mobile operators prioritize automated spectrum management over static analog units.
Market Restraints
- RF front-end component volatility:Gallium nitride and silicon germanium supply concentrates in East Asian foundries. Price swings compress margin predictability for mid-tier repeater manufacturers.
- CE marking electromagnetic compatibility testing:ETSI EN 301 489 certification costs and timeline uncertainty deter smaller vendors from European market entry.
- Wi-Fi 6E and 7 unlicensed substitution:Enterprise buyers in commercial facilities are bypassing cellular repeaters for native Wi-Fi coverage where latency tolerance permits.
Strategic Opportunities
- German in-building wireless mandates:Federal building codes now require cellular coverage in new commercial construction above specified floor areas. This creates captive demand for indoor repeater systems.
- 6 GHz unlicensed band allocation:National spectrum reframing decisions in multiple jurisdictions will determine which repeater architectures retain relevance and which require fundamental redesign.
- Public safety mission-critical频段 segments:First responder network authorities are specifying hardened repeaters with encryption and priority access protocols. Generalist vendors cannot serve this certification depth.
Industry Challenges
- RF systems engineering talent scarcity:Specialized expertise in microwave circuit design and antenna integration concentrates at a handful of university programs and incumbent employers.
- Legacy DAS integration complexity:Retrofitting smart repeaters into existing distributed antenna systems requires protocol bridging and power budget recalculation that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Repeaters Market |
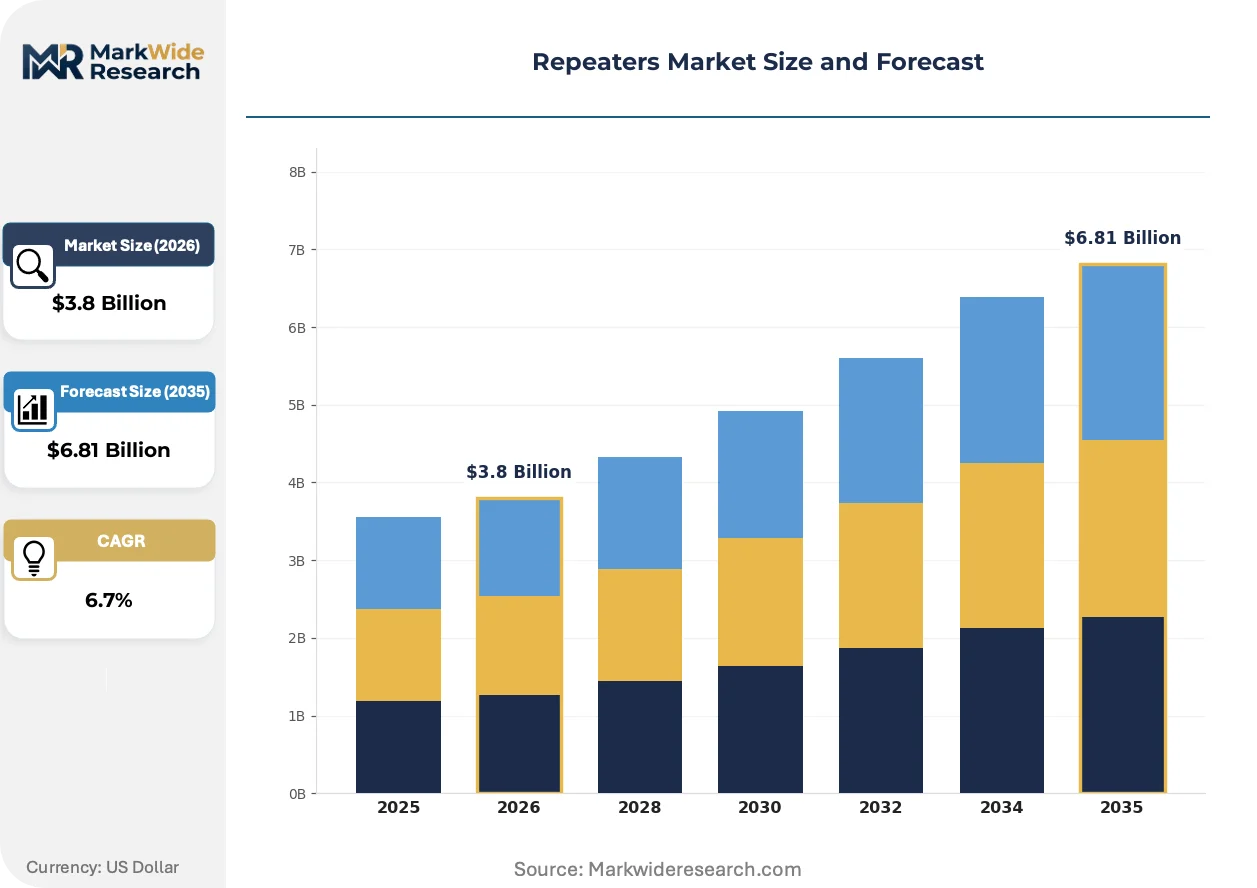
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Repeaters, Wireless Repeaters, Fiber Optic Repeaters, Digital Repeaters End User: Telecommunications, Broadcasting, Networking, Home Automation Technology: Analog, Digital, Hybrid, Smart Repeaters Deployment: Indoor, Outdoor, In-Building, Small Cell |
| Companies Covered | CommScope, Motorola Solutions, Huawei Technologies, Nextivity, Cisco Systems, ZTE Corporation, Stelladoradus, Huaptec, JDTECK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Repeaters Market Emerging Trajectories
Digital signal processing architectures are displacing analog amplification cores across repeater categories, enabling software-defined gain control and remote management that static hardware cannot match.
GaN-on-SiC power amplifiers are bifurcating the RF front-end landscape between high-efficiency military-aerospace suppliers and cost-optimized commercial vendors. 5G macro densification programs in South Korea and the United States are adopting GaN-based remote radio heads for their thermal and efficiency advantages. This technology compression is marginalizing silicon LDMOS incumbents in frequency bands above 3.5 GHz.
ETSI EN 303 645 cybersecurity standards for radio equipment are mandating firmware integrity verification and secure boot protocols for repeaters sold into European Union member states. Manufacturers must redesign supply chains to exclude components from non-trusted sources. Public safety and critical infrastructure segments face the steepest compliance ramps.
Carrier procurement teams are unbundling hardware acquisition from deployment services, reversing the bundled turnkey contracts that dominated 4G-era repeater rollouts. System integrators and specialized in-building wireless contractors are capturing the installation and commissioning revenue that equipment vendors previously retained. This channel restructuring is most pronounced in United States commercial real estate and German industrial facility markets.
Repeaters Market Segmentation
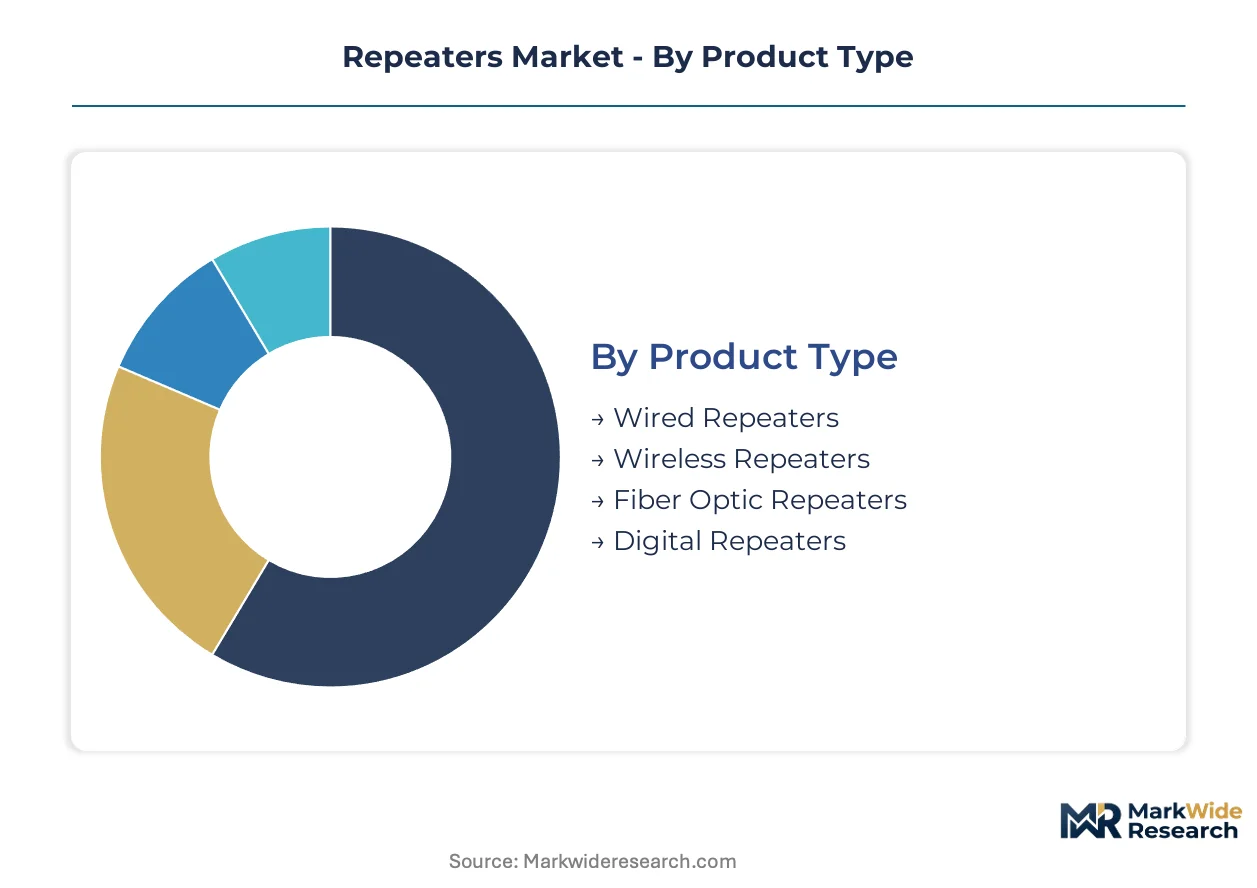
Repeater architectures diverge sharply across installation environments, frequency bands, and signal processing methodologies. Regulatory mandates from FCC Part 20 and ETSI EN 301 489 impose certification boundaries that reshape which segments capture carrier procurement volumes versus commercial retail channels.
Product Type:
FCC Part 20 hearing aid compatibility requirements and CE marking electromagnetic compatibility thresholds bifurcate the product landscape between consumer-distributed signal boosters and carrier-grade infrastructure equipment.
- Wireless Repeaters:Radio frequency amplification systems operating across licensed cellular bands with specified gain limits and automatic gain control. Outdoor macro densification and indoor distributed antenna system retrofits in the United States and South Korea concentrate procurement volumes as 5G mid-band buildouts accelerate.
- Fiber Optic Repeaters:Optical signal regeneration devices employing erbium-doped fiber amplifiers and dispersion compensation modules. Submarine cable consortiums in the Atlantic corridor and metro fiber ring extensions in Germany are expanding deployment timelines for transoceanic and urban backbone applications.
- Wired Repeaters:Electrical signal amplification across copper or coaxial transmission lines for legacy infrastructure support.
- Digital Repeaters:Software-defined signal processing units with protocol translation capabilities for heterogeneous network integration.
Established volume favors wireless repeaters; emerging adoption favors fiber optic repeaters.
End User:
Customer procurement authority determines certification depth, with telecommunications carriers mandating type acceptance testing that commercial facilities rarely require.
- Telecommunications:Carrier network infrastructure spanning macro cell densification, rural coverage extension, and capacity augmentation. United States and South Korean operators prioritize automated spectrum management capabilities as 5G standalone core deployments mature.
- Networking:Enterprise data center interconnects and campus backbone extension requiring low-latency signal integrity. German industrial facilities and US commercial real estate markets are unbundling hardware acquisition from deployment services, shifting procurement toward specialized system integrators.
- Broadcasting:Terrestrial television and radio transmission chain amplification for regional coverage footprint maintenance.
- Home Automation:Consumer-grade signal boosters for residential cellular and Wi-Fi coverage extension subject to FCC Part 20 emission controls.
Telecommunications commands the steepest certification investment; networking offers the most fragmented channel structure.
Technology:
Signal processing architecture determines remote management capability and interference resilience, with analog units facing displacement as operators prioritize automated optimization.
- Smart Repeaters:Self-optimizing network algorithms with real-time interference cancellation and spectrum sensing capabilities. Mobile operators in the United States and Germany are commanding premium positioning for automated spectrum management over static configurations.
- Digital Repeaters:Software-defined gain control with remote monitoring and firmware-upgradable modulation support. South Korean 5G densification programs are adopting digital architectures for their protocol flexibility and operational expenditure advantages.
- Analog Repeaters:Fixed-gain amplification with hardware-limited adjustment range for cost-sensitive legacy deployments.
- Hybrid Repeaters:Mixed-signal architectures combining analog front-ends with digital control loops for transitional network upgrades.
Smart repeaters are climbing the fastest; analog repeaters face replacement pressure.
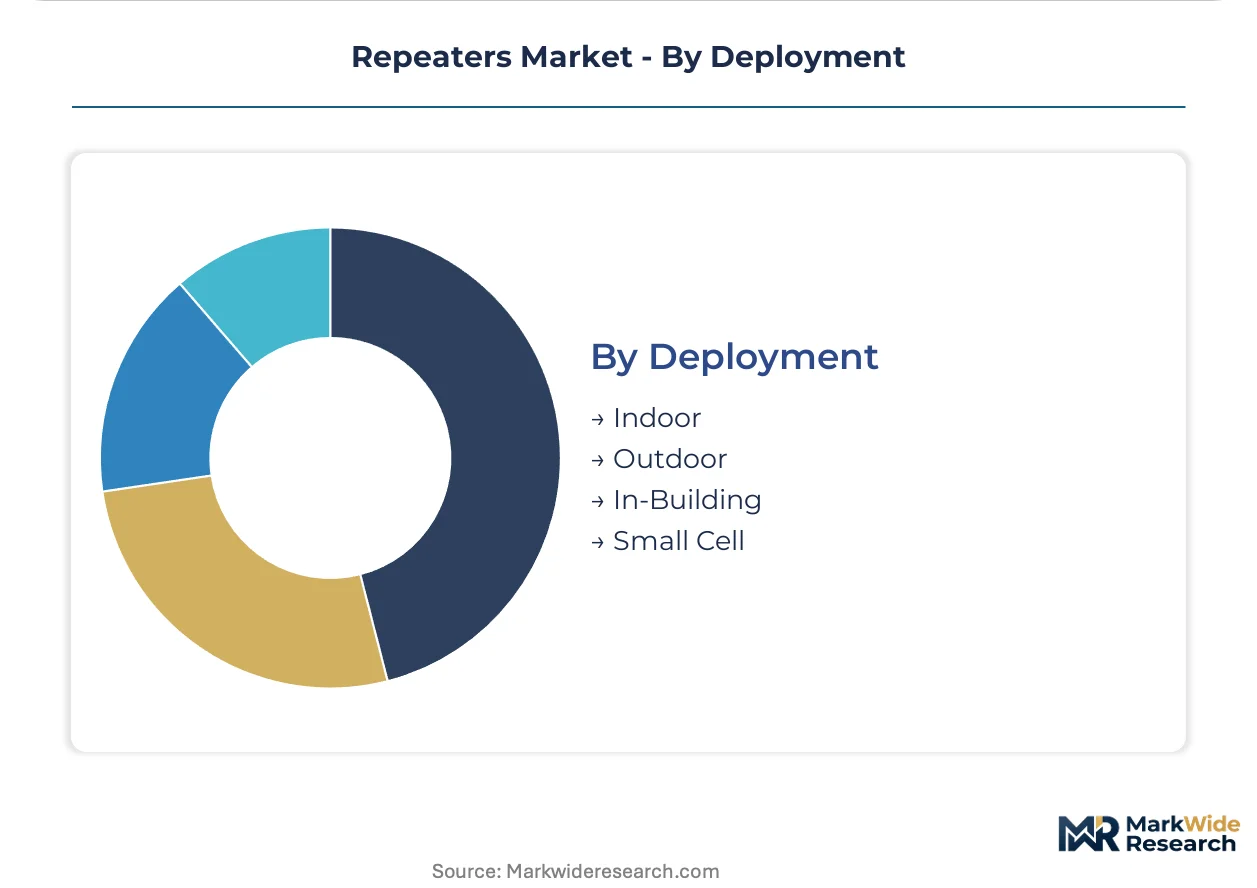
Deployment:
Installation environment dictates thermal design, enclosure hardening, and power supply architecture, with indoor mandates creating captive demand in specific jurisdictions.
- In-Building:Distributed antenna system nodes and small cell backhaul amplification for commercial and industrial facilities. German federal building codes now require cellular coverage in new construction above specified floor areas, generating regulatory-locked procurement volumes.
- Outdoor:Macro cell edge extension and rural coverage infill with weather-hardened enclosures and extended temperature specifications. United States carrier densification programs concentrate demand in suburban fringe zones where fiber backhaul remains uneconomical.
- Indoor:Residential and small office signal boosters subject to FCC Part 20 consumer certification requirements.
- Small Cell:Low-power radio heads with integrated repeater functions for hyperlocal capacity augmentation.
In-building systems benefit from regulatory mandate tailwinds; outdoor deployments track carrier capital cycle timing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecommunications carriers in South Korea accept premium pricing for GaN-based amplification systems, while enterprise buyers in Germany demand cost-optimized indoor solutions under federal coverage mandates. This elasticity split shapes procurement patterns across major deployment zones.
United States
Carrier densification programs in suburban fringe zones drive outdoor macro repeater procurement where fiber backhaul remains uneconomical. FCC Part 20 hearing aid compatibility mandates filter marginal vendors from commercial distribution channels. The Dallas-Fort Worth metroplex anchors RF systems engineering talent clusters for microwave circuit design.
Germany
Federal building codes now require cellular coverage in new commercial construction above specified floor areas, generating regulatory-locked demand for indoor distributed antenna systems. CE marking under ETSI EN 301 489 enforces electromagnetic compatibility thresholds that reshape procurement channels. The Rhine-Ruhr industrial corridor concentrates metro fiber ring extension projects for optical signal regeneration.
South Korea
5G standalone core deployments mature with automated spectrum management capabilities prioritized by mobile operators. National spectrum reframing decisions determine which repeater architectures retain relevance for mid-band buildouts. Seoul Capital Area vendors supply GaN-on-SiC power amplifiers for remote radio head densification programs.
China
Submarine cable consortiums in the Pacific corridor accelerate optical repeater procurement with dispersion compensation requirements. MIIT spectrum allocation frameworks shape architectural decisions for unlicensed band equipment. The Yangtze River Delta hosts manufacturing clusters for silicon germanium RF front-end components.
United Kingdom
Enterprise data center interconnects drive low-latency signal integrity requirements across campus backbone extensions. ETSI EN 303 645 cybersecurity standards mandate firmware integrity verification for radio equipment sold into EU member states. London's financial district concentrates demand for hardened public safety repeaters with encryption protocols.
Repeaters Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the repeaters landscape, with GaN-on-SiC power amplifier specialists commanding premium positioning while silicon LDMOS incumbents compete on unit economics. The vendor base stratifies between integrated infrastructure conglomerates, RF component pure-plays, and public safety certification specialists. Three archetypes dominate: captive semiconductor fabricators insulating margins from component volatility, antenna-cable bundlers controlling full-path solutions, and mission-critical频段 vendors with regulatory access moats. M&A activity concentrates on RF front-end capability acquisition, while strategic partnerships unbundle hardware from deployment services.
Among integrated infrastructure conglomerates, Huawei Technologies and ZTE Corporation exemplify the captive fabrication archetype through in-house baseband and power amplifier production. CommScope occupies a position within the bundling tier, leveraging antenna and cable portfolios for carrier-facing full-path solutions. Motorola Solutions anchors the mission-critical specialization segment, where public safety certification depth controls access to first responder network specifications that generalist vendors cannot serve.
| Leading Market Players |
|---|
| CommScope |
| Motorola Solutions |
| Huawei Technologies |
| Nextivity |
| Cisco Systems |
| ZTE Corporation |
| Stelladoradus |
| Huaptec |
| JDTECK |
| Others |
Supply Flow & Price Mechanics
GaN-on-SiC foundry scale in South Korea and the United States determines cost floors for high-efficiency power amplifiers, compressing margin structures for vendors without captive wafer supply or long-term offtake agreements with East Asian substrate producers.
Pricing Analysis
After-sales service contracts and firmware maintenance subscriptions drive lifetime value differentiation between carrier-grade and consumer-tier repeater vendors. Three-tier pricing structure across premium, standard, and economy levels separates mission-critical public safety certification from commercial indoor coverage and residential signal boosters. Cost compression in mid-tier digital repeaters is intensifying because silicon LDMOS incumbents face displacement above 3.5 GHz. Enterprise networking buyers in German industrial facilities exhibit the highest price sensitivity, while telecommunications carriers in South Korea accept premium positioning for automated spectrum management capabilities.
Supply Chain Analysis
China and Taiwan anchor substrate and RF front-end component fabrication for repeater power amplifiers and baseband processors. Erbium-doped fiber amplifiers for submarine cable applications draw from Japanese and German specialty glass manufacturers. Single-source vulnerability concentrates in GaN wafer supply from East Asian foundries. Distribution runs through carrier procurement teams unbundling hardware from deployment services, shifting fulfillment toward specialized system integrators in United States commercial real estate and German industrial facility markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized microwave circuit design expertise concentrates at a handful of university programs and incumbent employers, constraining vendor expansion and acquisition timelines for RF systems engineering talent.
For Market Incumbents: Compound certification depth in public safety mission-critical频段 segments to erect regulatory access moats against generalist competitors. Deepen backward integration into GaN-on-SiC power amplifier fabrication to insulate margins from East Asian foundry price volatility. Extend capacity addition in South Korea and the United States to capture 5G macro densification procurement volumes before silicon LDMOS incumbents complete architectural transitions.
For New Entrants and Emerging Players: Differentiate on smart repeater algorithms with real-time interference cancellation capabilities that command premium positioning from mobile operators prioritizing automated spectrum management. Target German in-building wireless mandates as the most penetrable geography, where federal building codes generate regulatory-locked procurement volumes for indoor distributed antenna systems. Pursue channel partnerships with specialized system integrators capturing installation and commissioning revenue unbundled from carrier hardware procurement.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among smart repeater vendors with firmware-upgradable software-defined architectures and long-term service contracts. Over the projection horizon, acquisition targets should demonstrate RF front-end capability depth or public safety certification portfolios that generalist vendors cannot replicate. Monitor 6 GHz unlicensed band allocation decisions across multiple jurisdictions as the signal indicating which repeater architectures require fundamental redesign versus retain relevance.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Power Amplifier Integration | Seoul Capital Area vendors supply high-efficiency amplification for 5G remote radio head densification programs. |
| Smart Reater Algorithm Development | Real-time interference cancellation capabilities command premium positioning from United States mobile operators. |
| Public Safety Certification Investment | FCC Part 20 and first responder network specifications filter generalist vendors from mission-critical频段 segments. |
| Backward Integration into RF Front-End | In-house baseband and power amplifier fabrication insulates margins from East Asian foundry price volatility. |
| System Integrator Channel Partnership | German industrial facilities and United States commercial real estate markets unbundle hardware from deployment services. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across telecommunications carrier procurement teams, RF systems engineering directors, distributed antenna system integrators, and semiconductor fabrication specialists. Primary interview insights were validated against FCC Part 20 rulemakings, ETSI EN 301 489 certification databases, submarine cable consortium procurement disclosures, and carrier capital expenditure filings. Bottom-up unit economics and top-down market sizing were triangulated to anchor volume and value estimates.
Across the analysis window, forecasts model product type segmentation across wireless, fiber optic, wired, and digital repeater architectures alongside technology tiers spanning smart, digital, analog, and hybrid signal processing methodologies. CAGRs were derived from carrier capital cycle timing, regulatory mandate implementation schedules, and substrate supply expansion trajectories. Inputs include GaN-on-SiC power amplifier adoption curves, 5G standalone core deployment maturity, and in-building wireless mandate compliance timelines.
Material uncertainties — spectrum reframing decisions, foundry capacity allocation shifts, and cybersecurity standard evolution — sit outside the modeled envelope. Forecasts reflect assumptions about carrier procurement unbundling trends and RF component supply concentration that could revise with trade policy adjustments or alternative substrate technology maturation. Recalibration cycles align with material shifts in national 6 GHz allocations and submarine cable modernization procurement waves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Subscriber Identity Module (SIM) Market
Telecom Hardware
Global Ultra Portable Internet Device Market
Telecom Hardware
Global Volte Market
Telecom Hardware
Africa Small Cell Market
Telecom Hardware
OTN Hardware Market
Telecom Hardware
5G Radio Unit Market
Telecom Hardware
LPWAN Market
Telecom Hardware
Global LTE Modems Market
Telecom Hardware
Europe Set-Top Box Market
Telecom Hardware
Digital Smart Set-Top Box (STB) Market
Telecom Hardware
Asia Pacific Enterprise Routers Market
Telecom Hardware
Base Station Antenna Market
Telecom Hardware
Point-To-Point Microwave Antenna Market
Telecom Hardware
Communication Base Station Equipment Pcb Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
Europe Zero-Touch Provisioning Market