
 Smart Card Tapes Market | 2026-2036
Smart Card Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Card Tapes Market Insights
Polyester is decoupling from legacy PVC substrates in high-security card applications, narrowing the raw-material cost gap and enabling thinner lamination stacks. Linxens leverages its integrated module-tape production across European and Asian plants to control substrate specifications for banking clients. Thales anchors its supply relationships through proprietary antenna-tape bonding processes that reduce delamination risk in dual-interface cards.
Smart card tapes are precision dielectric films, typically 50–150 micrometers thick, that laminate between embedded microprocessor modules and card bodies to ensure electrical insulation, mechanical adhesion, and thermal stability during personalization cycles. The product-type dimension shows PET gaining share in contactless applications where dimensional stability under heat and pressure outperforms standard polyester; among technology segments, EMV migration in developing markets sustains magnetic-stripe overlay demand even as NFC contactless volumes accelerate in transit and mobile-wallet schemes.
EMA medical-device traceability standards and EU REACH substance restrictions shape tape formulation requirements, particularly phthalate plasticizer bans that force reformulation of flexible PVC layers. The US FDA's indirect food-contact migration limits influence tape selection for prepaid benefit cards distributed through nutrition assistance programs. Stakeholders must monitor evolving halogen-free certification thresholds and substrate-recyclability mandates as environmental compliance becomes a gatekeeper for supplier qualification in European and North American procurement frameworks.
Market Dynamics
EMV migration in developing economies and REACH-mandated substrate reformulation are restructuring procurement priorities across card material supply chains, compressing legacy PVC conversion timelines while elevating halogen-free specification requirements.
Growth Catalysts
- EMV Compliance Mandates:Banking regulators in India and Brazil enforce chip-card deadlines that sustain tape laminator demand for dual-interface modules. Domestic converters in these markets expand capacity to serve government ID and financial card programs.
- Halogen-Free Reformulation:ECHA REACH substance restrictions and EU RoHS amendments accelerate substrate transitions away from brominated flame retardants. European module laminators now specify PET alternatives to maintain CE marking eligibility.
- Contactless Transit Expansion:NFC-enabled transport schemes in South Korea and the United Kingdom replace magnetic-stripe ticketing. Tape specifications for antenna bonding in these dual-interface cards require enhanced thermal cycling performance.
Market Restraints
- Petrochemical Input Volatility:PTA and MEG feedstock prices for polyester film production fluctuate with crude oil derivatives. Asian tape converters face margin compression when resin contracts reset quarterly.
- Concentrated Adhesive Supply:Solvent-free acrylic formulations for high-tack lamination depend on specialized German and Japanese chemical suppliers. Disruptions to these concentrated sources delay tape qualification cycles.
- PVC Substitution Technical Limits:Legacy personalization equipment in Latin American card bureaus cannot process thinner PET stacks without retrofitting. Technical inertia slows substrate transition in cost-sensitive procurement environments.
Strategic Opportunities
- Biometric Card Integration:Fingerprint-sensor modules in payment cards from Saudi Arabia and the United Arab Emirates create demand for multi-layer tape stacks. These constructions require precise dielectric matching between sensor pads and card bodies.
- Recyclable Substrate Certification:EU Green Deal circular-economy mandates position mono-material PET constructions for preferential procurement. Early adopters in French and Dutch banking consortia pilot closed-loop card recycling programs.
- Central Bank Digital Currency Interfaces:Hardware-wallet functionality in physical cards for China's e-CNY pilot requires enhanced electromagnetic shielding. Tape suppliers with controlled-impedance formulations capture specification roles in these programs.
Industry Challenges
- Specialized Lamination Engineering Talent:Thin-film adhesive chemistry expertise concentrates among aging technical workforces in Germany and Japan. Knowledge transfer gaps threaten formulation continuity as retirement cycles accelerate.
- Multi-Jurisdiction Certification Complexity:Simultaneous FDA indirect food-contact, EMA medical-device traceability, and BIS smart card standards force parallel qualification tracks. Timeline misalignment between regulators delays product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Card Tapes Market |
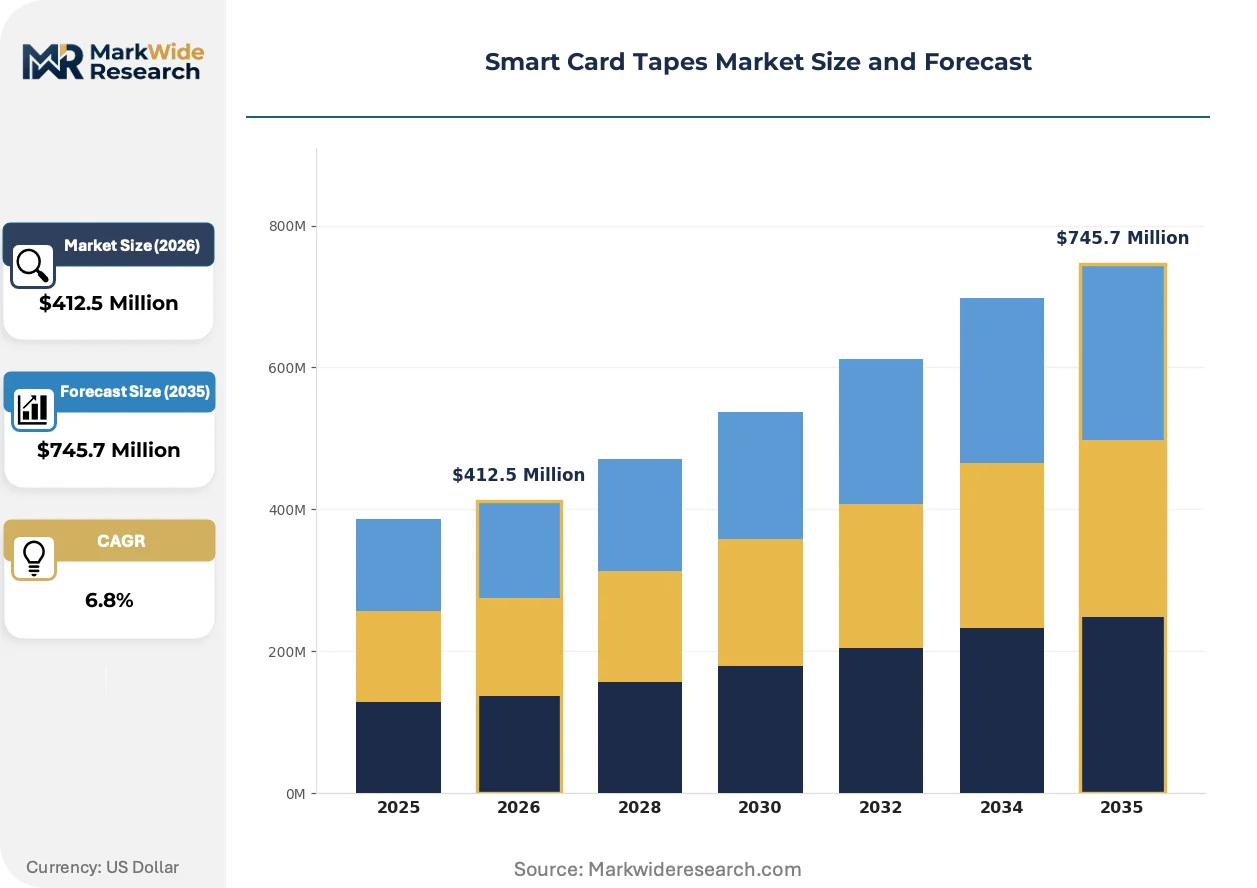
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, PVC, PET, Polypropylene Application: Identification Cards, Payment Cards, Access Control, Loyalty Cards End User: Retail, Banking, Healthcare, Education Technology: Contactless, Magnetic Stripe, EMV, NFC |
| Companies Covered | Linxens, HENGHUI Technology, LG Innotek, Thales, IDEMIA, Giesecke & Devrient, NXP Semiconductors, Infineon Technologies, HID Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Card Tapes Market Trends and Innovations
Laser personalization systems and halogen-free substrate specifications are converging to redefine tape performance thresholds, while procurement centralization among banking consortia compresses supplier qualification windows.
Laser-engraved personalization technology is automating the replacement of mechanical embossing in high-volume card bureaus. European financial institutions adopt these systems to eliminate mechanical stress on embedded modules during data writing. The shift is automating demand for thermally stable tape constructions that withstand localized heating without delamination or dimensional distortion.
EU REACH Annex XVII phthalate restrictions and RoHS recast directives now explicitly cover smart card materials as electrical and electronic equipment. Tape formulators reformulate plasticized PVC layers to comply with DEHP and BBP bans while maintaining flexibility for antenna embedding. German automotive payment card programs, governed by KBA transport standards, now specify full material disclosure to preempt future substance restrictions.
Banking consortium procurement in the Netherlands and Belgium consolidates tape sourcing through nominated supplier frameworks. Single-source agreements with module laminators replace fragmented spot purchasing, compressing price negotiation cycles and elevating technical service requirements. This concentration is most visible in Benelux markets where domestic card personalization bureaus have merged into shared-service operations.
Smart Card Tapes Market Segmentation
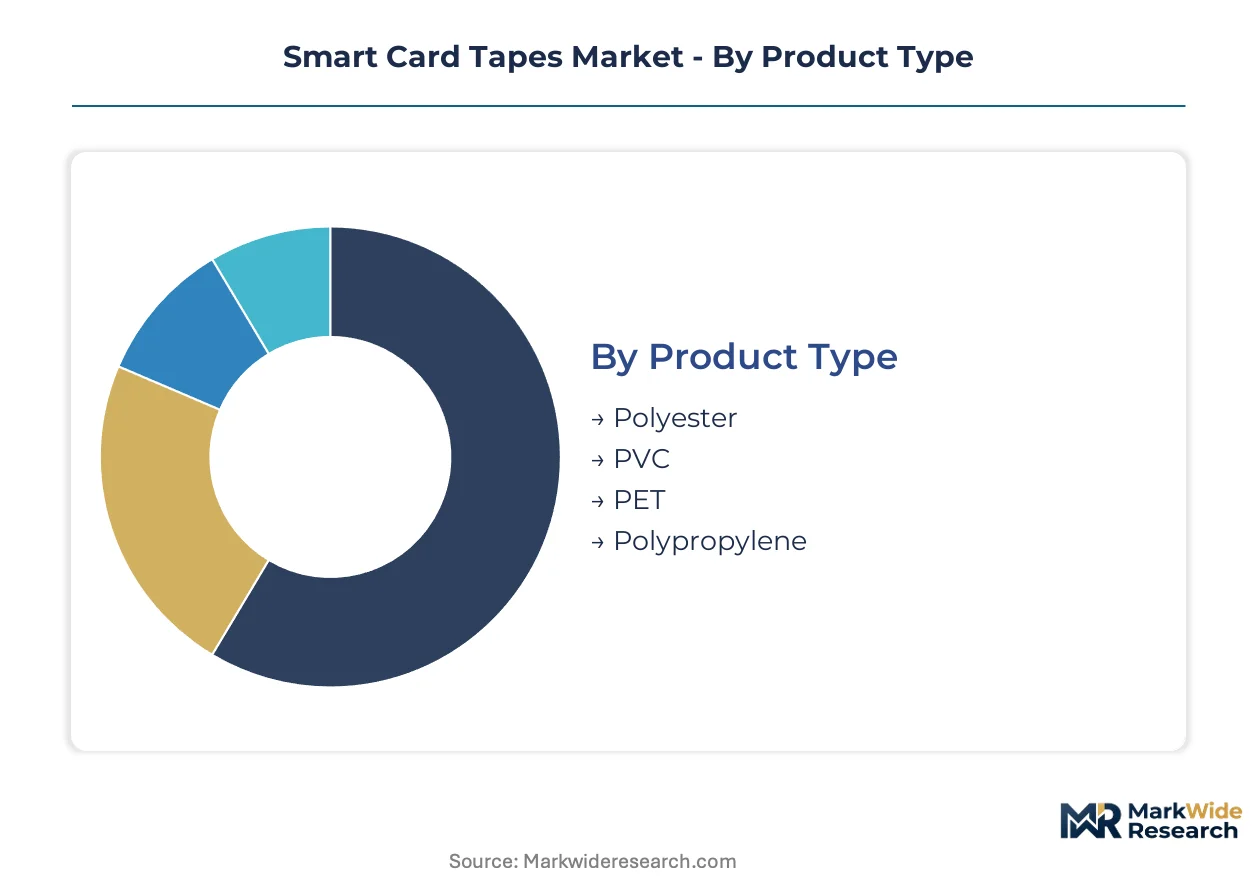
Smart card tape procurement varies sharply by substrate chemistry, card function, and compliance regime. Each segmentation dimension carries distinct specification requirements that reshape supplier qualification criteria and manufacturing priorities across module laminators.
Product Type:
Upgrade cycles from legacy PVC to halogen-free alternatives are compressing reformulation timelines and elevating PET specification requirements in European banking procurement.
- Polyester:Biaxially oriented film with dimensional stability under thermal cycling serves dual-interface cards where laser personalization generates localized heat. Banking consortia in the Netherlands and Belgium specify this substrate for closed-loop recycling compatibility.
- PVC:Plasticized homopolymer with established embossing compatibility retains volume in Latin American card bureaus with legacy personalization infrastructure. REACH Annex XVII phthalate restrictions are forcing progressive phase-out in European government ID programs.
- PET:Amorphous glycol-modified variant offers enhanced clarity and barrier properties for optical security features. Demand concentrates in Asian transit card applications requiring antenna-embedding precision.
- Polypropylene:Lower-density olefin film provides cost reduction in high-volume prepaid benefit card programs. US FDA indirect food-contact migration limits constrain formulation flexibility for nutrition assistance distribution.
Polyester sits at the top of the volume ranking, with PET climbing the fastest.
Application:
Card function determines lamination stack complexity, with payment and identification segments driving divergent specification paths for dielectric matching and durability testing.
- Identification Cards:Multi-layer constructions incorporating holographic overlays and biometric sensor interfaces require precise dielectric constant control. Government programs in Saudi Arabia and the United Arab Emirates specify these for national identity and resident permit schemes.
- Payment Cards:EMV module lamination with dual-interface antenna bonding demands thermal cycling resistance across personalization temperature ranges. Indian and Brazilian banking regulators enforce chip-card deadlines that sustain tape laminator capacity expansion.
- Access Control:Proximity card formats prioritize flexibility for curved badge geometries. Corporate campus deployments in South Korea specify these for employee and visitor management systems.
- Loyalty Cards:Single-layer constructions with magnetic stripe overlays dominate cost-sensitive retail programs. Magnetic-stripe overlay demand persists even as NFC contactless volumes accelerate in transit and mobile-wallet schemes.
Payment Cards command the largest specification volume, with Identification Cards expanding most quickly.
End User:
Customer-type concentration shapes technical service requirements, with banking and healthcare procurement centralizing through nominated supplier frameworks that compress price negotiation cycles.
- Retail:High-volume loyalty and gift card programs prioritize unit cost minimization through simplified lamination stacks. Prepaid benefit card distribution through US nutrition assistance programs requires FDA-compliant substrate selection.
- Banking:EMV compliance mandates and biometric card pilots drive multi-layer tape stack demand with enhanced electromagnetic shielding. Central bank digital currency hardware-wallet functionality in China's e-CNY pilot requires controlled-impedance formulations.
- Healthcare:EMA medical-device traceability standards and patient data security requirements shape tape formulation for smart health cards. EU MDR compliance adds material disclosure obligations for card body substrates.
- Education:Campus access and payment integration schemes specify durability for high-frequency daily use. Student ID programs in the United Kingdom combine transit functionality with library and facility access.
Banking leads procurement value, with Healthcare gaining specification share fastest.
Technology:
Interface architecture determines antenna-embedding requirements and thermal performance thresholds, with contactless migration restructuring tape qualification priorities across card bureaus.
- Contactless:NFC-enabled modules require antenna-tape bonding with precise impedance matching and delamination resistance. Transit schemes in South Korea and the United Kingdom replace magnetic-stripe ticketing with these formats.
- Magnetic Stripe:Legacy overlay tapes with ferric oxide compatibility persist in developing market banking migration timelines. Technical inertia in Latin American personalization equipment sustains residual demand.
- EMV:Chip-module lamination specifications standardize across dual-interface and contact-only variants. RBI and BIS standards in India enforce compliance deadlines that drive domestic converter capacity expansion.
- NFC:Near-field communication antenna embedding demands enhanced thermal cycling performance for mobile-wallet integration. Mobile payment schemes in China and South Korea accelerate specification adoption.
Contactless dominates technology-specific procurement, with NFC showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dongguan and Shenzhen anchor tape converter capacity serving module laminators across Asia-Pacific financial card programs. Government ID procurement in China, EMV migration timelines in India and Brazil, and REACH-mandated substrate transitions in Germany are restructuring regional supply priorities.
China
Domestic tape converters in Guangdong Province supply module laminators for government ID and financial card programs. MIIT standards for smart card interoperability guide substrate specification requirements. The Pearl River Delta cluster concentrates PET film extrusion and adhesive coating capacity for e-CNY hardware-wallet pilots.
Germany
KBA transport standards and ECHA REACH Annex XVII restrictions drive halogen-free PET adoption in automotive payment card programs. EMA medical-device traceability requirements shape tape formulation for health card applications. The Rhine-Ruhr industrial corridor hosts specialized adhesive chemistry operations serving European banking consortia.
India
RBI chip-card deadlines sustain tape laminator demand for dual-interface EMV modules. BIS smart card standards enforce compliance timelines that accelerate domestic converter capacity expansion. Mumbai-Pune manufacturing belts concentrate module assembly operations serving financial inclusion programs.
United States
FDA indirect food-contact migration limits influence tape selection for prepaid benefit cards through nutrition assistance distribution. EMV compliance mandates in community banking sustain magnetic-stripe overlay demand alongside contactless migration. The Southeast industrial corridor hosts card personalization bureaus consolidating procurement through shared-service frameworks.
Brazil
ANVISA traceability requirements and Banco Central EMV deadlines compress legacy PVC conversion timelines. Technical inertia in Latin American personalization equipment sustains residual demand for thicker substrate stacks. São Paulo state concentrates card bureau operations serving regional banking migration programs.
Smart Card Tapes Market Competitive Landscape
Global majors compete with regional champions across substrate specification and module-tape integration capabilities. The vendor base stratifies between integrated module producers controlling upstream tape supply and independent film converters serving spot procurement markets. Three archetypes dominate: European banking specialists with captive adhesive chemistry, Asian volume producers leveraging polyester film integration, and module-anchored players specifying proprietary lamination stacks. Competitive positioning hinges on halogen-free certification speed and qualification cycle compression through nominated supplier frameworks.
Within the integrated-module tier, Linxens exemplifies European-Asian production coordination for banking substrate control, while Thales occupies a position anchored by antenna-tape bonding specialization. Among Asian volume producers, HENGHUI Technology represents the Dongguan-based converter archetype serving domestic government ID programs. These three sit within a competitive matrix where REACH compliance velocity and laser-personalization thermal stability separate premium-tier qualification from commodity spot supply.
| Leading Market Players |
|---|
| Linxens |
| HENGHUI Technology |
| LG Innotek |
| Thales |
| IDEMIA |
| Giesecke & Devrient |
| NXP Semiconductors |
| Infineon Technologies |
| HID Global |
| Others |
Pricing and Supply Chain Analysis
Laser-personalization thermal stability requirements and halogen-free substrate transitions are compressing qualification timelines while concentrating pricing power among REACH-certified European suppliers and integrated Asian film converters.
Pricing Analysis
PTA and MEG feedstock pass-through from polyester film extrusion dominates tape converter cost structures, with quarterly resin contract resets transmitting crude oil derivative volatility directly into module laminator procurement. Pricing stratifies across REACH-certified premium tiers, laser-thermal-stable mid-tiers, and legacy PVC economy tiers, with certification grade and volume scale as primary differentiation drivers. Price erosion runs through Latin American legacy PVC segments as technical inertia in personalization equipment sustains spot-market purchasing. Retail loyalty card programs exhibit highest price sensitivity; banking consortium procurement in Benelux markets demonstrates lowest sensitivity due to nominated supplier framework lock-in.
Supply Chain Analysis
REACH and FDA certification gating restricts qualified adhesive chemistry supply to German and Japanese specialty chemical operations, creating single-source vulnerability for solvent-free acrylic formulations. Tape production concentrates in China, Germany, and India, with biaxially oriented polyester film, halogen-free flame retardants, and precision-coated adhesive layers as critical input dependencies. Tariff exposure on Chinese PET film exports to European module laminators threatens margin structures. Distribution runs through nominated supplier frameworks in banking consortia and spot procurement networks in retail loyalty programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart card tape procurement operates as a geographic-arbitrage play between REACH-mandated European premium specifications and cost-optimized Asian volume production, with regulatory compliance velocity determining supplier viability across jurisdictions.
For Market Incumbents: Anchor qualification-cycle compression through captive adhesive chemistry operations in the Rhine-Ruhr corridor, defending against Asian converter encroachment by accelerating halogen-free certification timelines beyond regulatory minimums. Deepen backward integration into biaxially oriented polyester film extrusion to secure thermal-stability specifications for laser-personalization banking contracts. For New Entrants and Emerging Players: Biometric card multi-layer dielectric matching offers technology-first wedge positioning, with Saudi Arabian and UAE national ID programs as the most penetrable white-space target due to fingerprint-sensor module procurement expansion. Pursue hardware-wallet electromagnetic shielding specifications for central bank digital currency pilots as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among independent film converters without module-anchored supply relationships, with long-term viability hinging on REACH compliance velocity across the analysis window. Target European adhesive chemistry specialists with aging technical workforces facing knowledge-transfer gaps. Monitor ECHA substance restriction expansion timelines as the critical inflection signal for substrate reformulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Halogen-Free Substrate Certification | REACH Annex XVII compliance secures CE marking eligibility for European banking procurement. |
| Laser-Personalization Thermal Stability Investment | Localized heat resistance specifications capture high-volume card bureau automation demand. |
| Biometric Card Multi-Layer Stack Development | Dielectric matching for fingerprint sensors penetrates Saudi and UAE government ID programs. |
| Backward Integration into PET Film Extrusion | In-house biaxially oriented film production controls dimensional stability for dual-interface cards. |
| Closed-Loop Recycling Program Partnership | Mono-material PET constructions align with EU Green Deal circular-economy mandates. |
Research Methodology
Direct dialogue with module laminator procurement directors, adhesive chemistry formulators, card personalization bureau operations managers, and banking consortium technical specification committees grounded qualitative findings, combined with secondary validation from ECHA REACH substance restriction databases, BIS smart card standard filings, RBI circulars on EMV migration timelines, and customs trade data on polyester film imports. Bottom-up and top-down triangulation reconciled converter capacity estimates with end-use demand segmentation.
Bottom-up modeling of tape laminator capacity expansion across Pearl River Delta, Rhine-Ruhr, and Mumbai-Pune manufacturing belts anchored volume projections, while top-down banking card issuance forecasts and transit scheme NFC rollout schedules validated demand trajectories across the projection horizon. Segmentation dimensions included substrate chemistry, card function, end-user procurement centralization, and interface technology architecture. CAGRs derived from fitted growth curves incorporating EMV compliance deadline enforcement and regulatory reformulation mandate acceleration.
The model holds under stable REACH substance restriction timelines and crude oil derivative feedstock pricing; deviation in ECHA Annex XVII expansion scope or PTA/MEG supply disruption would shift converter margin structures and procurement qualification priorities. A model refresh is warranted upon material change in halogen-free certification threshold adoption or central bank digital currency hardware-wallet specification finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Tape and Label Adhesives Market
Tapes
Nano Tapes Market
Tapes
India Reflective Tapes Market
Tapes
Pipe Marking Tape Market
Tapes
Labels, Tapes and Films Market
Tapes
Tear Tape Dispenser Market
Tapes
Foil Tapes Market
Tapes
Thread Seal Tape Market
Tapes
Flatback Tapes Market
Tapes
Invisible Tapes Market
Tapes
Paper Gummed Tape Market
Tapes
ESD Tapes and Labels Market
Tapes
Wing Walk Tapes Market
Tapes
Thermal Release Tapes Market
Tapes
Self-Fusing Silicone Tapes Market
Tapes
United States End-Of-Line Packaging Tape Market