
 Coalescing Filter Market | 2026-2036
Coalescing Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Coalescing Filter Market Analysis
The coalescing filter market is recalibrating around a widening split between specification-grade aerospace and pharmaceutical tiers and commodity compressed-air units serving light manufacturing. MANN + HUMMEL leverages its automotive filtration heritage to dominate OEM channel access for precision-engineered coalescers. Pall Corporation anchors the bioprocessing segment with membrane-integrated coalescing systems that command premium positioning. Donaldson Company competes aggressively in industrial air compressor aftermarket channels with broad distribution coverage.
A coalescing filter removes liquid aerosols and fine mists from gas streams by forcing flow through fibrous media where droplets collide, accumulate, and drain by gravity, typically achieving removal efficiencies of 99.97% for particles down to 0.3 microns. Microfilter and membrane filter product types capture the highest margin pools in sterile process applications where validation documentation drives switching costs. Fuel filtration and process filtration applications lead volume demand from oil and gas infrastructure and chemical processing plants respectively, while liquid filtration segments in water treatment are expanding fastest as utilities upgrade to meet tighter discharge standards.
EPA regulations under the Clean Air Act and OSHA compressed air purity requirements shape product specifications for industrial users across the United States, while ISO 8573 international standards define oil aerosol content limits that manufacturers must certify against for global equipment sales. The EU F-Gas Regulation and REACH chemical restrictions additionally constrain filter media material choices for European market access. Stakeholders must monitor evolving refrigerant handling rules and biopharma single-use system trends that could redirect coalescer demand toward disposable cartridge formats or extended-life washable designs.
Market Dynamics
Specification-grade coalescing filters for sterile pharmaceutical processes are diverging from commodity compressed-air units as ISO 8573 purity classes tighten and bioprocessing validation requirements harden. This bifurcation is compressing margin pools at the mid-tier while concentrating value capture at certified extremes.
Growth Catalysts
- EPA Clean Air Act enforcement:Industrial facilities in the United States face escalating penalties for oil aerosol emissions, forcing upgrades to high-efficiency coalescer systems that achieve 99.97% removal at 0.3 microns.
- Bioprocessing expansion:Single-use bioreactor adoption in mammalian cell culture is extending filter replacement cycles and demanding membrane-integrated coalescing validation documentation.
- German automotive cluster procurement:Stuttgart and Wolfsburg manufacturing hubs specify OEM-grade coalescers for compressed air systems in paint shops and assembly lines, creating specification-grade pull-through.
Market Restraints
- Specialized media supply concentration:Borosilicate glass microfiber production for high-efficiency coalescers concentrates among limited European suppliers, exposing buyers to input volatility.
- REACH chemical restrictions:ECHA constraints on fluoropolymer coatings limit hydrophobic treatment options for filter media, forcing reformulation costs onto manufacturers.
- Membrane filtration substitution:Hollow-fiber membrane contactors for liquid-gas separation capture select applications previously served by depth-style coalescers.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO regulatory alignment with PIC/S standards is driving sterile process infrastructure investment where validated coalescing systems remain underdeployed.
- Hydrogen economy fuel cell protection:Proton exchange membrane fuel cell anode humidification requires ultra-clean gas streams, opening coalescer applications in electrolyzer and fueling station builds.
- Extended-life washable designs:Stainless steel mesh coalescing elements with automated cleaning protocols address sustainability mandates in EU water treatment utilities.
Industry Challenges
- ISO 8573-1:2010 Class 0 certification timelines:Third-party verification of oil aerosol content below detection limits extends product launch cycles by 8-14 months for new coalescer designs.
- Legacy compressor system integration:Retrofitting high-efficiency coalescers into existing compressed air networks requires pressure-drop recalculation and receiver tank reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coalescing Filter Market |
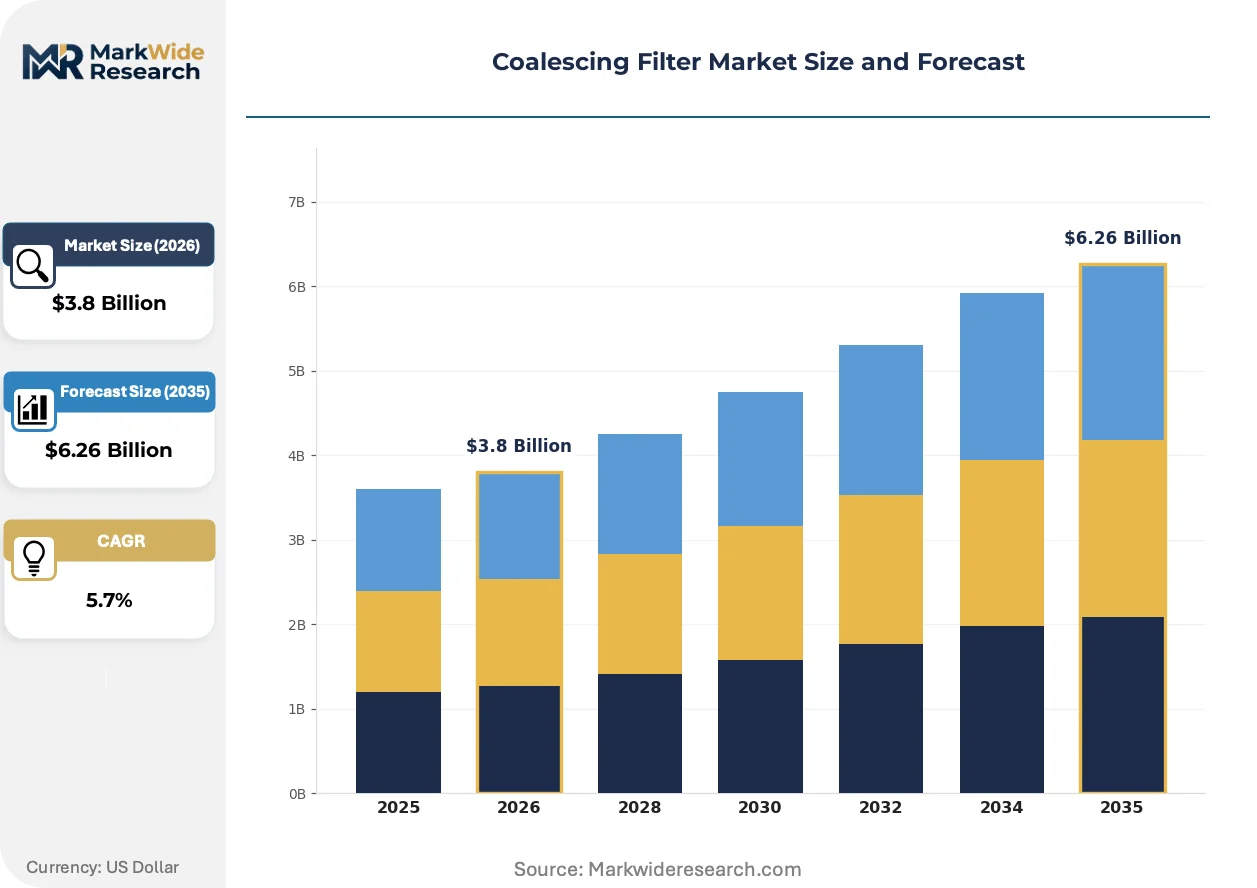
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfilter, Separator, Coalescer, Membrane Filter End Use Industry: Oil & Gas, Chemicals, Water Treatment, HVAC Application: Fuel Filtration, Liquid Filtration, Air Filtration, Process Filtration Technology: Vapor Separation, Pressure Filtration, Gravity Separation, Chemical Treatment |
| Companies Covered | MANN + HUMMEL, Filson Filter, Pall Corporation, Sogefi Group, Graver Technologies, Parker Hannifin, Eaton Corporation, Bosch Rexroth, Donaldson Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coalescing Filter Market Emerging Trajectories
Active materials science and regulatory precision are compressing the gap between aerospace-grade and industrial coalescing performance. Filter architectures are converging around modular cartridge platforms that accommodate rapid media swaps without housing replacement.
Electrospun nanofiber surface layers are decentralizing the traditional depth-loading coalescer construction by enabling surface-capture mechanisms that release captured droplets at lower pressure differentials. Pharmaceutical sterile process engineers in Basel and Boston facilities are specifying these composite media for protein-based biologic manufacturing. The technology is decentralizing procurement authority from central engineering teams to site-level quality units that validate media lots independently.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant handling infrastructure upgrades across industrial cold chain facilities. Coalescing filters for compressor crankcase ventilation and refrigerant recovery systems now require compatibility with low-GWP hydrofluoroolefins and natural refrigerants. German chemical processing clusters in Ludwigshafen and Leverkusen are piloting ammonia-compatible coalescer materials ahead of 2027 compliance deadlines.
Compressed air service contracts are unbundling filter replacement from compressor maintenance agreements, creating direct procurement relationships between end-users and filter specialists. Automotive tier-1 suppliers in Detroit and Stuttgart are negotiating multi-year coalescer supply agreements separate from OEM compressor service packages. This shift is most visible in high-volume paint shop operations where filter consumption predictability supports inventory consignment models.
Coalescing Filter Market Segmentation
Coalescing filter procurement splits sharply between standalone replacement cartridges and integrated OEM systems. Understanding where each segment sits in this integration hierarchy shapes margin capture and channel strategy for suppliers.
Product Type:
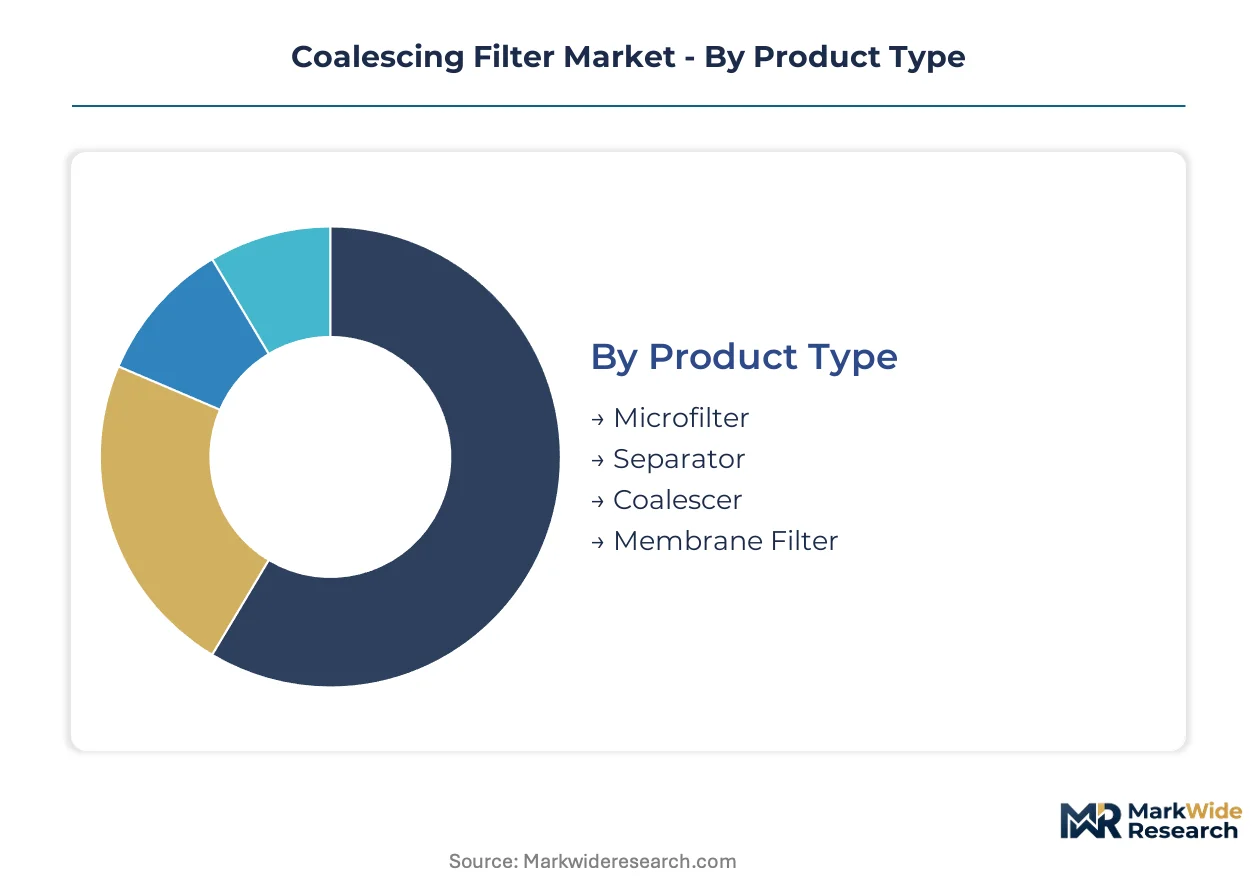
Microfilter and membrane units dominate embedded bioprocessing skids, while separator and coalescer cartridges flow through aftermarket distribution for field replacement.
- Microfilter:Borosilicate glass microfiber media achieves 99.97% efficiency at 0.3 microns for sterile pharmaceutical processes. Demand concentrates in Basel and Boston biologics facilities where FDA and EMA validation documentation locks in multi-year supply agreements.
- Membrane Filter:Polymeric membrane layers integrate with coalescing stages in single-use bioreactor trains. German chemical clusters in Ludwigshafen specify these for ammonia-compatible refrigerant systems ahead of EU F-Gas Regulation deadlines.
- Separator:Centrifugal or impingement designs handle bulk liquid removal upstream of fine coalescers.
- Coalescer:Depth-loading fibrous media captures sub-micron aerosols in compressed air and fuel gas treatment.
Coalescer cartridges lead volumes today; membrane filters are gaining share fastest.
End Use Industry:
Capital intensity and regulatory exposure vary dramatically across these verticals, with oil and gas infrastructure demanding field-serviceable durability while water treatment utilities prioritize lifecycle cost.
- Oil & Gas:Offshore platforms and midstream compressor stations specify stainless steel housings with automated drain systems for hydrocarbon condensate removal. EPA Clean Air Act enforcement on volatile organic compound emissions drives upgrade cycles in Gulf Coast refining corridors.
- Chemicals:Process plants handling aggressive solvents require fluoropolymer-coated media compatible with REACH chemical restrictions. Stuttgart automotive paint shops specify OEM-grade units for compressed air purity under ISO 8573 Class 0.
- Water Treatment:Municipal utilities deploy extended-life washable designs to meet EU discharge standards.
- HVAC:Commercial building systems prioritize low pressure-drop configurations for energy compliance.
Oil and gas anchors revenue today; water treatment is climbing the fastest.
Application:
Fluid phase and contamination type dictate media selection, with liquid-liquid separation commanding premium pricing over gas-phase applications.
- Fuel Filtration:Aviation and marine diesel systems require coalescers that handle surfactant-laden fuels without disarming. Demand clusters in Rotterdam bunkering hubs and Singapore refueling terminals where ISO 4406 cleanliness codes mandate continuous filtration.
- Process Filtration:Chemical reactor feed streams and solvent recovery loops integrate coalescers with distillation columns. Indian pharmaceutical manufacturing under CDSCO alignment with PIC/S standards is expanding validated system deployment.
- Liquid Filtration:Water-oil separation in industrial wastewater precedes membrane bioreactor stages.
- Air Filtration:Compressed air systems for pneumatic controls and instrumentation require oil aerosol removal to 0.01 mg/m³.
Process filtration leads volumes today; fuel filtration is expanding most quickly.
Technology:
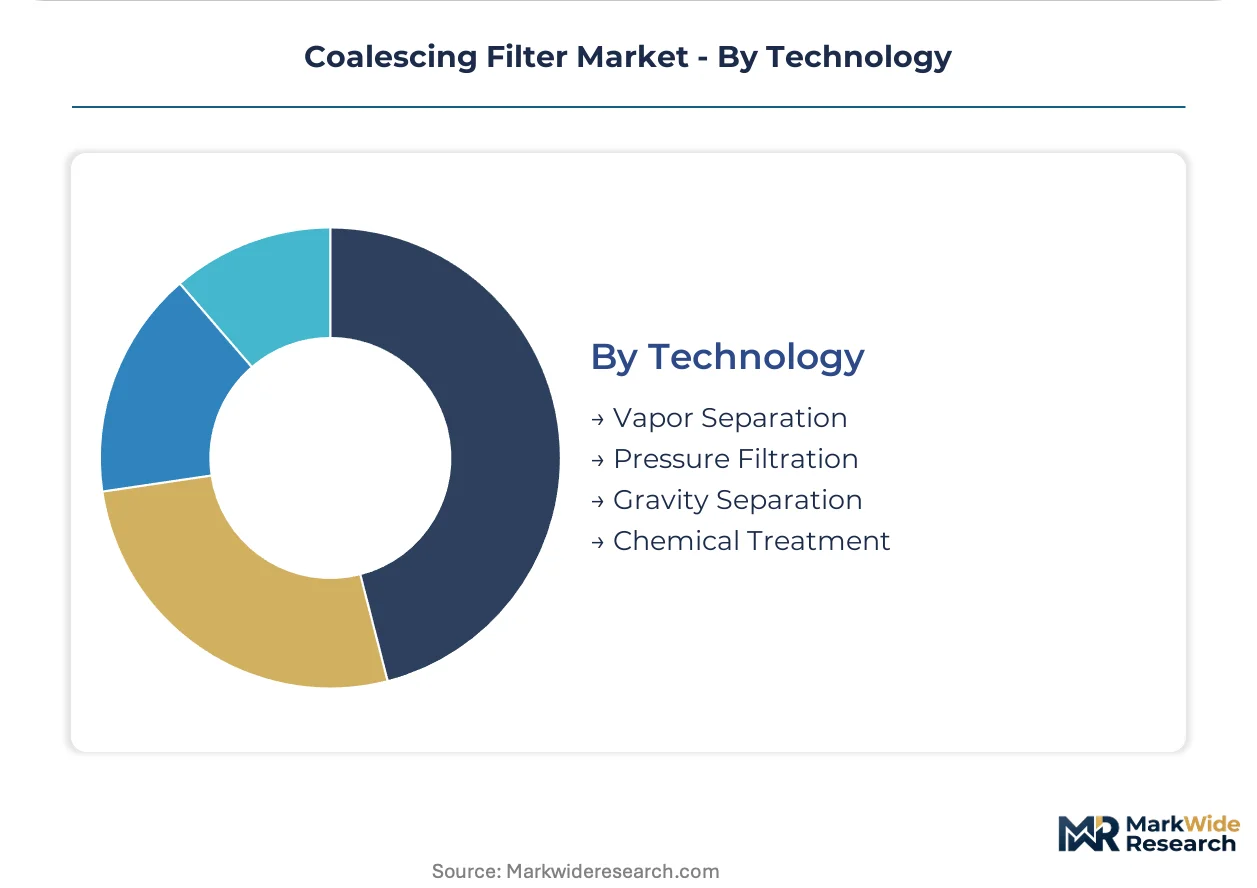
Energy input requirements separate passive gravity systems from active pressure-driven alternatives, with hybrid configurations emerging for difficult emulsions.
- Vapor Separation:Membrane contactors and condensation surfaces extract hydrocarbons from natural gas streams. Hydrogen economy infrastructure in electrolyzer and fueling station builds requires ultra-clean gas protection for proton exchange membrane fuel cells.
- Pressure Filtration:Forced flow through depth media achieves sub-micron capture in high-velocity compressed air networks. German automotive assembly lines in Wolfsburg specify these for paint shop robotics where moisture or oil contamination destroys finish quality.
- Gravity Separation:Settling tanks and impingement stages remove bulk liquids before fine polishing.
- Chemical Treatment:Demulsifier injection assists coalescence in heavy crude processing.
Pressure filtration leads volumes today; vapor separation shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive and chemical clusters drive specification-grade procurement intensity unmatched elsewhere, while the United States channels enforcement-heavy EPA mandates into upgrade cycles across Gulf Coast refining corridors. This divergence creates distinct procurement patterns: precision-engineered OEM integration versus regulatory-forced replacement demand.
United States
EPA Clean Air Act enforcement escalates penalties for oil aerosol emissions from industrial facilities. OSHA compressed air purity requirements shape specifications for manufacturing plants across the Midwest and Southeast. Houston and Corpus Christi refining clusters drive demand for stainless steel coalescer systems with automated drain capabilities.
Germany
EU F-Gas Regulation deadlines accelerate refrigerant handling infrastructure upgrades across industrial cold chain facilities. REACH chemical restrictions constrain fluoropolymer coating options for filter media formulations. Stuttgart and Wolfsburg automotive manufacturing hubs specify OEM-grade coalescers for compressed air systems in paint shop operations.
India
CDSCO regulatory alignment with PIC/S standards expands sterile process infrastructure investment in pharmaceutical manufacturing. The country's national pharmaceutical regulator tightens validation documentation requirements for bioprocessing equipment. Maharashtra and Gujarat pharmaceutical clusters in Mumbai and Ahmedabad deploy membrane-integrated coalescing systems for single-use bioreactor trains.
China
GB standards for compressed air purity tighten specifications for oil aerosol removal in manufacturing equipment. The Ministry of Ecology and Environment enforces discharge standards that upgrade wastewater treatment infrastructure. Yangtze River Delta chemical processing hubs in Shanghai and Ningbo pilot ammonia-compatible coalescer materials for refrigerant system conversions.
Japan
METI industrial efficiency programs promote energy-optimized compressed air systems with reduced pressure-drop configurations. JIS standards define performance benchmarks for filtration equipment in precision manufacturing. Kanto region automotive and electronics clusters in Tokyo and Yokohama specify validated coalescers for cleanroom pneumatic controls.
Coalescing Filter Market Vendor Landscape
Top-tier vendors anchor specification-grade pharmaceutical and aerospace tiers, while mid-scale fabricators compete on replacement cartridge volumes and distribution reach. The market structure concentrates premium positioning among membrane-integrated system specialists and OEM-channel filtration heritage players, with commodity compressed-air segments fragmenting across regional aftermarket distributors. Two strategic archetypes dominate: precision-engineered bioprocessing validators and broad-coverage industrial aftermarket suppliers. Competitive moves center on unbundling filter replacement from compressor service contracts and expanding multi-year direct supply agreements with high-volume end-users.
Among Germany-based filtration specialists, MANN + HUMMEL GmbH occupies a position exemplifying automotive heritage leveraged into OEM coalescer channels. Pall Corporation represents the membrane-integrated bioprocessing tier where validation documentation creates switching cost barriers. Donaldson Company anchors the industrial aftermarket archetype with distribution coverage across compressed-air replacement cycles. These three entities illustrate how geographic origin and corporate structure align with distinct competitive positioning in a market splitting between certified precision and volume accessibility.
| Leading Market Players |
|---|
| MANN + HUMMEL |
| Filson Filter |
| Pall Corporation |
| Sogefi Group |
| Graver Technologies |
| Parker Hannifin |
| Eaton Corporation |
| Bosch Rexroth |
| Donaldson Company |
| Others |
Supply Flow & Price Mechanics
Specification-grade bioprocessing coalescers and commodity compressed-air units diverge sharply in both cost structures and sourcing configurations, with ISO 8573 Class 0 certification creating a pricing ladder that concentrates margin capture among validated suppliers while compressing mid-tier positions. This bifurcation channels procurement authority toward site-level quality units in Basel and Boston, decentralizing traditional central engineering purchasing and fragmenting supply relationships across multiple validation-dependent tiers.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for standard-grade coalescer cartridges while premium membrane-integrated systems maintain pricing power through FDA and EMA validation documentation. Three-tier pricing structure across premium, standard, and economy levels separates bioprocessing validators from industrial aftermarket suppliers, with price differentiation driven by certification grade and geographic delivery cost. Cost compression in commodity compressed-air tiers is intensifying because unbundled service contracts expose filter specialists to direct volume negotiations. Water treatment utilities in the EU exhibit highest price sensitivity due to lifecycle cost mandates, while pharmaceutical sterile process engineers show least sensitivity given validation lock-in.
Supply Chain Analysis
Refurbishment flows for stainless steel coalescer housings are emerging as a reverse-logistics revenue stream for German and Japanese aftermarket specialists, extending asset life in automotive paint shop applications. Geographic supply concentration centers on Germany for precision-engineered OEM systems, the United States for aerospace-grade membrane integration, and China for standard cartridge volumes. Raw material dependencies rest on borosilicate glass microfiber from European suppliers, fluoropolymer coatings constrained by REACH restrictions, and polymeric membrane substrates. Single-source vulnerability in specialized media production exposes buyers to input volatility. Distribution runs through compressor OEM service networks for integrated systems and direct procurement relationships for high-volume replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coalescing filter market reads as a late-cycle quality story where bioprocessing validation requirements and EPA enforcement are redirecting procurement toward specification-grade tiers with documented performance guarantees.
For Market Incumbents: Lock in multi-year validation documentation contracts with Basel and Boston biologics facilities before membrane filtration substitution accelerates. Prioritize backward integration into borosilicate glass microfiber production to secure input supply against European supplier concentration. Channel control through unbundled filter replacement agreements with Stuttgart automotive paint shops reinforces OEM-grade positioning against compressor service package competitors. For New Entrants and Emerging Players: EU F-Gas Regulation phase-down schedules in Germany open a window for ammonia-compatible coalescer materials ahead of 2027 compliance deadlines. Target CDSCO-aligned pharmaceutical manufacturing in Maharashtra and Gujarat where validated coalescing systems remain underdeployed relative to PIC/S infrastructure investment. A direct site-level quality unit go-to-market angle bypasses entrenched central engineering procurement relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with membrane-integrated bioprocessing specialists possessing FDA master file documentation and locked-in multi-year supply agreements. Long-term viability over the next decade favors validators over commodity cartridge fabricators given regulatory tightening trajectories. Watch hydrogen economy electrolyzer build rates as an inflection indicator for ultra-clean gas protection demand.| Strategic Initiative | Industry Significance |
|---|---|
| Validation Documentation Investment | FDA and EMA master file submissions lock in multi-year pharmaceutical supply agreements against switching. |
| Backward Integration into Media Production | In-house borosilicate glass microfiber capacity secures supply against European supplier concentration. |
| Direct Procurement Relationship Development | Unbundled filter replacement contracts with automotive paint shops bypass compressor OEM service networks. |
| Ammonia-Compatible Material Development | German chemical clusters pilot refrigerant system conversions ahead of EU F-Gas Regulation deadlines. |
| Extended-Life Washable Design Engineering | Stainless steel mesh elements with automated cleaning protocols address EU water treatment sustainability mandates. |
Methodological Framework
Direct dialogue with plant engineers, aftermarket service heads, OEM procurement teams, and bioprocessing quality directors grounded the qualitative assessment, cross-referenced against customs and trade data, SEC 10-K filings, EPA enforcement records, and ISO certification databases. Bottom-up and top-down triangulation reconciled field-level procurement patterns with macro-level regulatory enforcement trends across the analysis window.
Segment-level outputs across product type, end-use industry, application, technology, and regional production cluster fed into the analytical framework. CAGRs were derived from modeled replacement cycle frequencies, regulatory compliance upgrade timelines, and infrastructure investment trajectories. Hydrogen economy build rates and bioprocessing single-use adoption curves served as industry-specific demand inputs.
Revisions become necessary when EPA enforcement intensity shifts, REACH chemical restrictions expand, or membrane filtration substitution accelerates beyond current trajectory assumptions. Practitioners should monitor CDSCO regulatory alignment progress, EU F-Gas Regulation compliance deadlines, and hydrogen fueling station deployment rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Egg and Egg Products Market
Others
Evidence Management Market
Others
Storm Surge Barriers Market
Others
US Mobile MRI Services Market
Others
Vortexers Market
Others
Griffin Beaker Market
Others
Egg Market
Others
Hypersensitivity Market
Others
Snus Market
Others
Fresh Durian Market
Others
Fibert Market
Others
France Location-Based Services Market
Others
Global Essential Oils and Plant Extracts for Livestock Market
Others
Global Aircraft Sensors Market
Others
Wearable Translator Market
Others
Calendered Polyvinyl Chloride Flexible Films Market