
 France Location-Based Services Market | 2026-2036
France Location-Based Services Market Size, Share, and Industry Trends Forecast 2026-2036
France Location-Based Services Market Insights
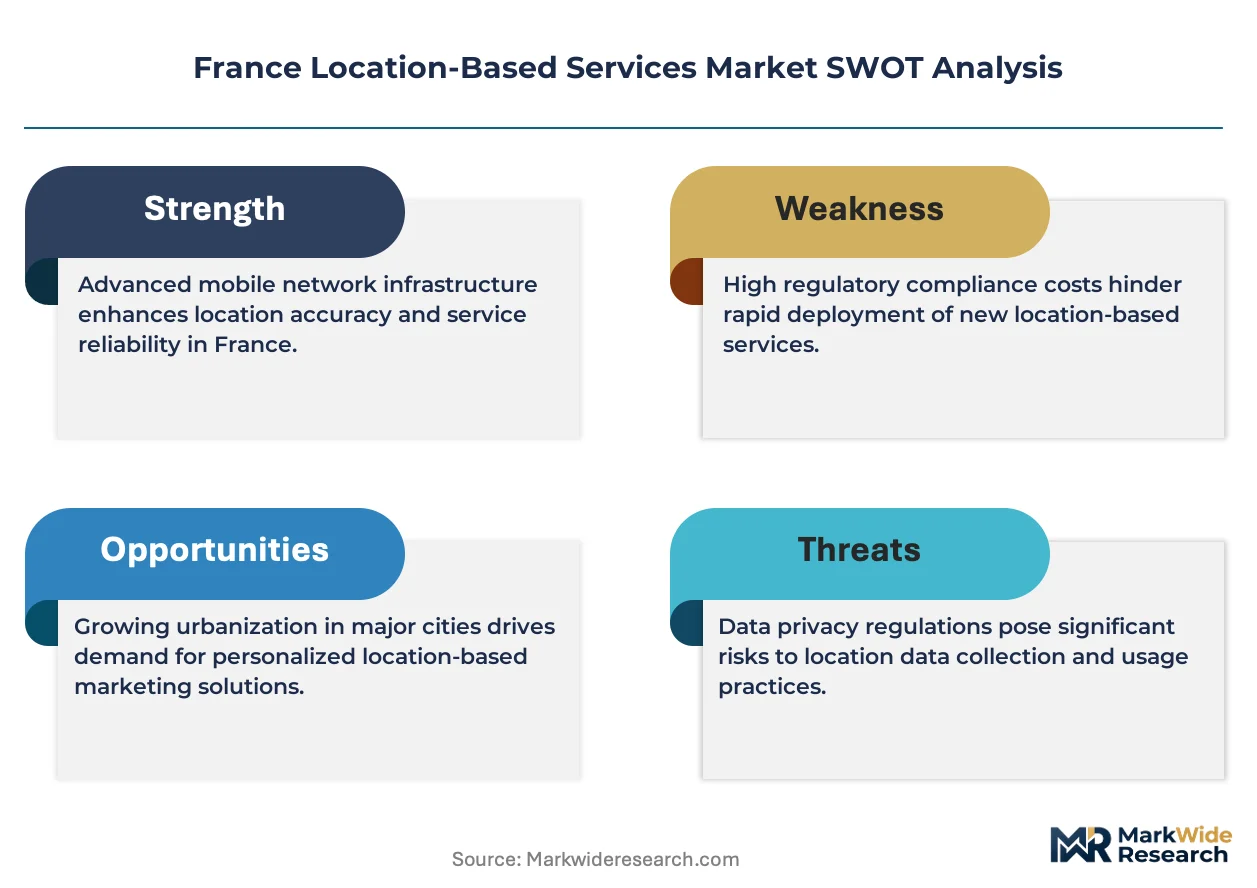
Buyer concentration across French retail chains and transport operators is realigning procurement priorities toward integrated location platforms. HERE Technologies leverages its mapping heritage to anchor enterprise contracts with national logistics providers. TomTom International BV competes through specialized fleet management APIs optimized for European road networks. GEOCONCEPT SAS differentiates by embedding geographic intelligence directly into public-sector emergency response systems.
Location-Based Services encompass hardware, software, and data layers that determine precise geographic coordinates through satellite triangulation, signal fingerprinting, or proximity sensing for real-time spatial decision-making. GPS and Wi-Fi Positioning dominate outdoor and indoor deployments respectively, with Bluetooth Beacons gaining traction in French hypermarkets for sub-meter accuracy. Navigation applications occupy the largest revenue pool among application segments, while Transportation and Retail segments capture accelerating enterprise budgets as route optimization and proximity marketing mature.
CNIL enforces GDPR-aligned geolocation consent rules that shape how French providers collect, store, and monetize positional data, while the EU AI Act imposes algorithmic transparency requirements on automated location-based decision systems. BSI and ISO standards for location data interoperability influence procurement specifications among government buyers. Stakeholders must monitor evolving CNIL guidance on biometric-location fusion and anticipate how EU-wide digital identity frameworks will reshape authentication requirements for consumer-facing services.
Market Dynamics
French retailers and logistics operators are consolidating procurement around unified location platforms that fuse indoor positioning, fleet telematics, and predictive analytics into single vendor relationships.
Growth Catalysts
- EU AI Act compliance mandates:Automated location-based decision systems in French transport and retail must meet algorithmic transparency requirements, forcing upgrades to auditable positioning infrastructure and creating replacement demand.
- Île-de-France smart city densification:Paris municipal investments in multi-modal transit hubs and last-mile logistics corridors concentrate demand for real-time passenger and cargo tracking.
- Bluetooth beacon deployments:French hypermarkets are installing sub-meter accuracy proximity systems for personalized in-aisle engagement, expanding hardware refresh cycles.
Market Restraints
- CNIL consent enforcement:GDPR-aligned geolocation data processing rules impose granular opt-in requirements that increase customer acquisition friction and limit historical data monetization.
- Wi-Fi infrastructure fragmentation:Indoor positioning accuracy depends on signal fingerprinting databases that remain incomplete in secondary French urban centers outside Lyon and Marseille.
- Galileo receiver cost premiums:Dual-frequency GNSS chipsets required for urban canyon accuracy carry 15-25% hardware cost penalties versus single-band GPS alternatives.
Strategic Opportunities
- Auvergne-Rhône-Alpes manufacturing corridors:Industrial asset tracking penetration remains below 20% in Grenoble and Saint-Étienne production zones, creating greenfield deployment potential.
- Emergency response system integration:GEOCONCEPT's public-sector anchor contracts demonstrate viable pathways for embedding location intelligence into national civil security frameworks.
- 5G positioning convergence:Network-based timing and ranging protocols are unifying cellular and satellite positioning layers for seamless indoor-outdoor handoff.
Industry Challenges
- Geospatial data science talent scarcity:French universities produce insufficient candidates fluent in both positioning algorithms and CNIL privacy engineering requirements.
- Legacy fleet management migration:National logistics providers maintain decade-old telematics contracts that resist API-based platform consolidation without operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Location-Based Services Market |
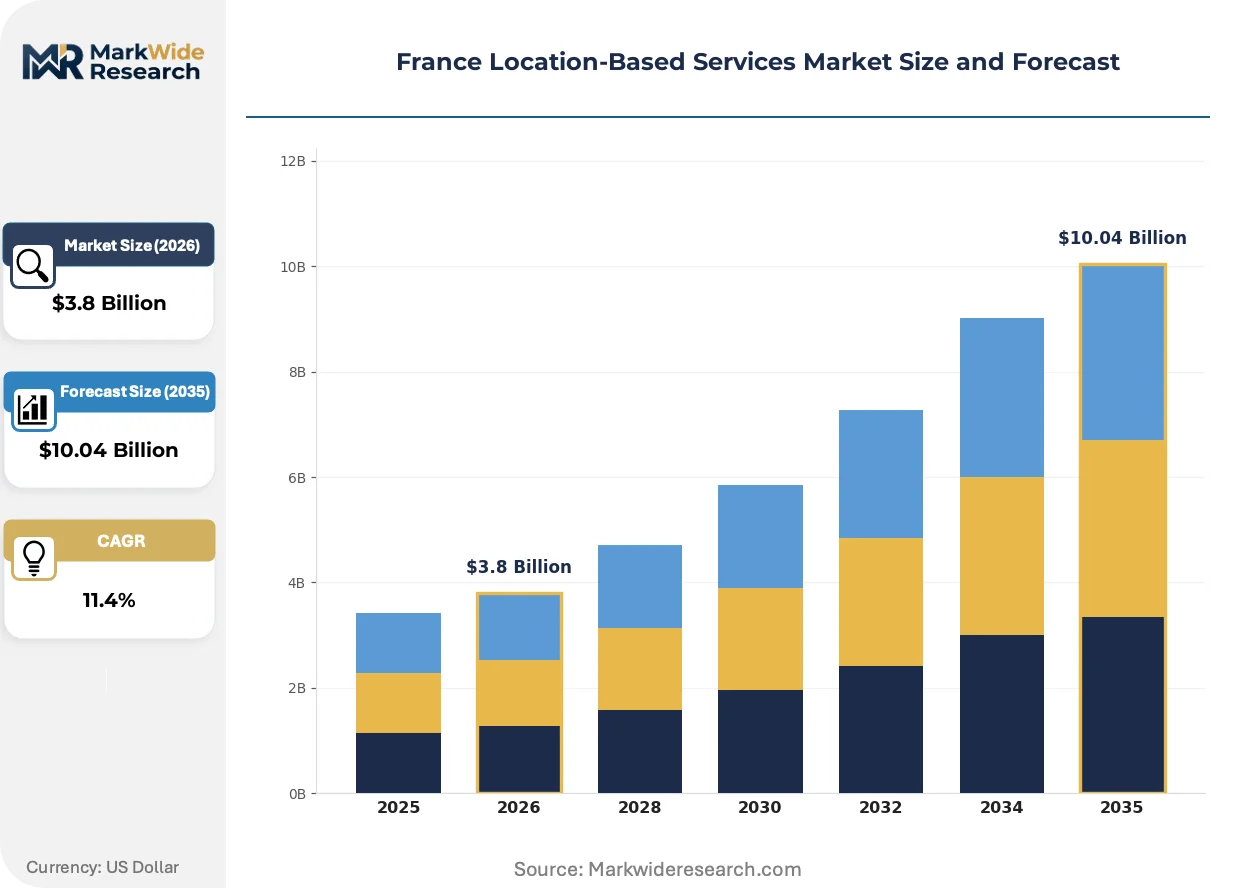
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Navigation, Retail, Emergency Services, Transportation Technology: GPS, Wi-Fi Positioning, Bluetooth Beacons, RFID End User: Consumers, Enterprises, Government, Healthcare Providers Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Integration |
| Companies Covered | HERE Technologies, TomTom International BV, GEOCONCEPT SAS, Zebra Technologies France SAS, Ubisense SAS, Google, Apple, Foursquare, Mapbox, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Location-Based Services Market Trends and Innovations
Edge computing architectures and privacy-preserving positioning techniques are compressing latency and consent burdens simultaneously, altering how French enterprises architect location stacks.
Ultra-wideband (UWB) chipsets are unifying high-precision indoor positioning with secure device-to-device ranging for contactless access and asset tracking. French automotive suppliers are embedding UWB anchors in vehicle interiors for smartphone-as-key functionality. This convergence is collapsing the historical separation between consumer electronics and enterprise asset management hardware procurement.
France's CNIL is tightening biometric-location fusion guidance that restricts how facial recognition coordinates combine with GPS traces in public spaces. Retail analytics vendors must now maintain separate data streams for identity verification and spatial tracking. Mall operators in Paris and Lyon are responding by segmenting camera networks from beacon infrastructures to preserve compliance flexibility.
Consolidated platform procurement is displacing point-solution buying as French retail chains and transport operators demand unified indoor-outdoor-fleet visibility. HERE Technologies and TomTom International BV are anchoring multi-year enterprise contracts that bundle mapping, routing, and positioning APIs. This bundling is squeezing specialized indoor positioning vendors into subsystem supplier roles.
France Location-Based Services Market Segmentation
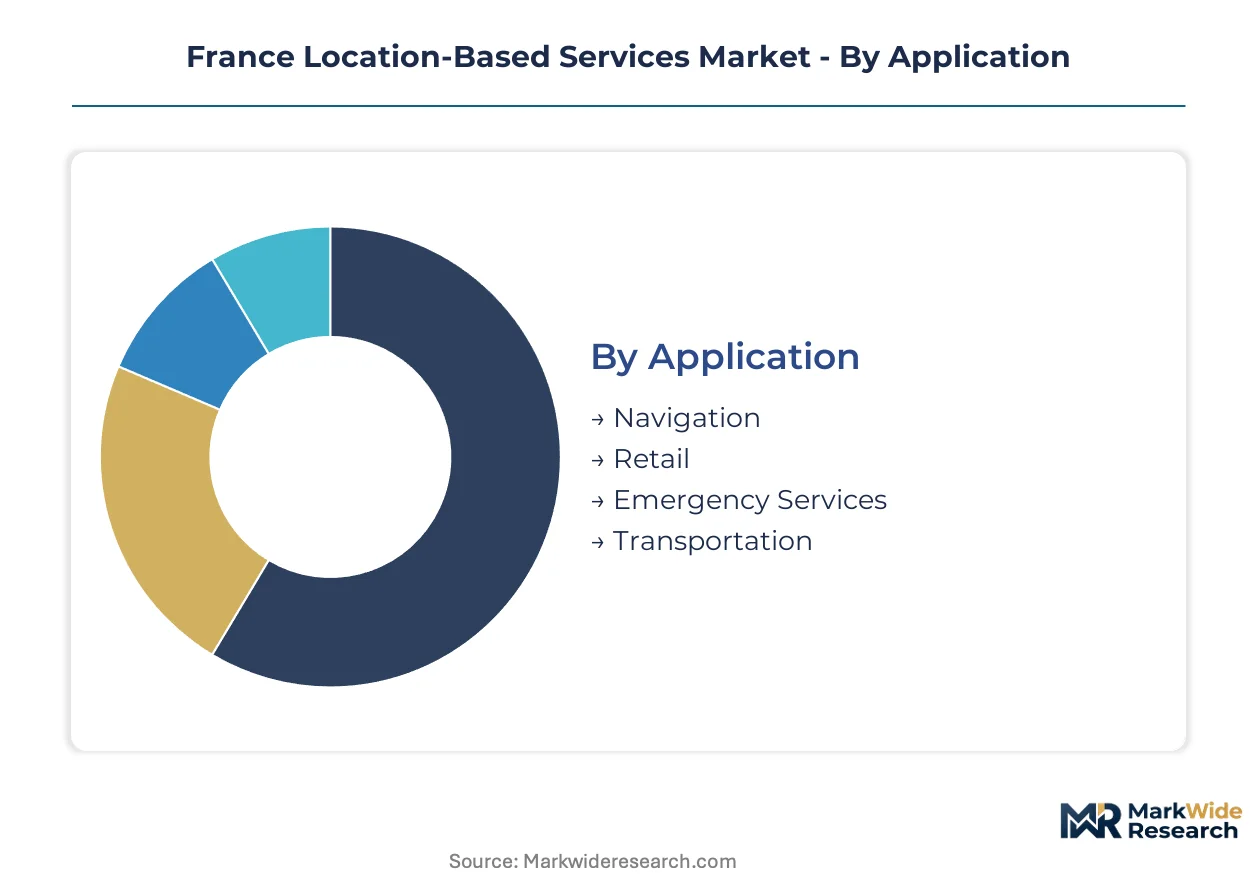
Segmentation in France's Location-Based Services market reflects how CNIL consent frameworks, EU AI Act algorithmic transparency mandates, and deployment complexity vary across use cases. Procurement patterns diverge sharply between consumer-facing applications requiring granular opt-in infrastructure and enterprise systems governed by BSI interoperability standards.
Application:
CNIL's GDPR-aligned geolocation rules impose distinct consent burdens: navigation apps face lighter transparency requirements than retail proximity systems processing biometric-location fusion.
- Navigation:Satellite triangulation and real-time routing algorithms dominate this segment. Paris and Île-de-France transport authorities concentrate procurement for multi-modal transit hubs, driven by municipal smart city densification and last-mile logistics corridor investments.
- Retail:Bluetooth beacon deployments enable sub-meter accuracy for in-aisle personalized engagement. French hypermarkets in Lyon and Marseille lead hardware refresh cycles, constrained by CNIL's tightening guidance on facial recognition coordinate fusion with GPS traces.
- Emergency Services:GEOCONCEPT anchors public-sector contracts embedding geographic intelligence into national civil security frameworks. BSI standards for location data interoperability shape government buyer specifications.
- Transportation:Fleet telematics and route optimization systems serve national logistics providers. EU AI Act compliance mandates force upgrades to auditable positioning infrastructure for automated location-based decision systems.
Leading the category by volume: Navigation. Growing fastest: Retail.
Technology:
Hardware cost tiers separate urban-canyon precision requirements from baseline outdoor accuracy, with dual-frequency GNSS chipsets carrying 15-25% premiums over single-band alternatives.
- GPS:Satellite triangulation remains the backbone of outdoor positioning. Single-band receivers dominate cost-sensitive consumer applications, while dual-frequency chipsets penetrate Île-de-France logistics corridors requiring urban canyon accuracy.
- Wi-Fi Positioning:Signal fingerprinting databases enable indoor navigation where satellite signals degrade. Deployment concentrates in Paris, Lyon, and Marseille, with incomplete coverage in secondary urban centers limiting accuracy.
- Bluetooth Beacons:Sub-meter proximity systems anchor French hypermarket personalization strategies.
- RFID:Passive and active radio-frequency tags support industrial asset tracking in Auvergne-Rhône-Alpes manufacturing zones.
Widest deployment: GPS. Steepest expansion trajectory: Bluetooth Beacons.
End User:
Privacy engineering requirements and procurement scale separate consumer applications from enterprise and government buyers with dedicated compliance teams.
- Consumers:Smartphone-native navigation and retail apps dominate this segment. Granular opt-in requirements under CNIL enforcement increase customer acquisition friction and limit historical data monetization opportunities.
- Enterprises:Unified indoor-outdoor-fleet visibility platforms consolidate procurement among French retail chains and transport operators. HERE Technologies and TomTom anchor multi-year contracts bundling mapping, routing, and positioning APIs.
- Government:Emergency response and smart city infrastructure deployments follow BSI and ISO standards for location data interoperability.
- Healthcare Providers:Patient tracking and asset location systems operate under strict GDPR health data overlays.
Revenue concentration: Enterprises. Gaining share fastest: Government.
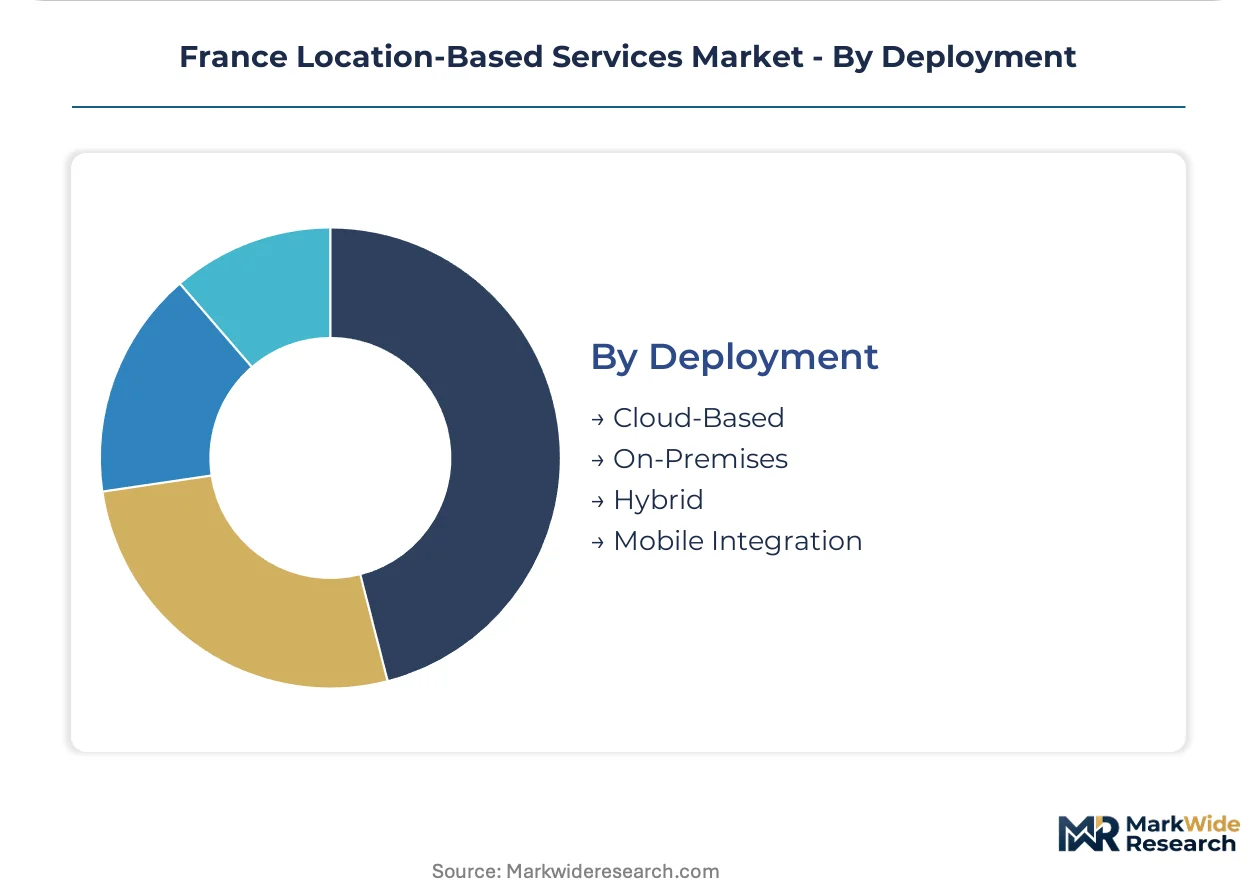
Deployment:
Latency requirements and data sovereignty concerns drive architecture choices between edge processing and centralized cloud analytics.
- Cloud-Based:Centralized positioning analytics and predictive routing engines serve distributed retail chains. French buyers prioritize EU-hosted infrastructure to satisfy GDPR data residency requirements.
- On-Premises:Sensitive government and healthcare deployments maintain full data control within institutional boundaries. CNIL guidance on biometric-location fusion particularly favors air-gapped architectures for public-sector camera networks.
- Hybrid:Edge-compute nodes handle real-time positioning while cloud layers manage historical analytics and model training.
- Mobile Integration:Smartphone-as-key functionality and contactless access systems leverage UWB chipsets embedded by French automotive suppliers.
Dominant architecture: Cloud-Based. Expanding most quickly: Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for location-based services concentrates in Île-de-France and its surrounding logistics corridors, with procurement decisions radiating outward to secondary urban centers and industrial zones across metropolitan France.
Île-de-France
Paris municipal authorities anchor national demand through smart city investments in multi-modal transit hubs and last-mile logistics corridors. CNIL's GDPR-aligned geolocation consent frameworks shape how providers collect positional data across the capital's dense retail and transport networks. La Défense and Roissy-Charles de Gaulle logistics clusters drive real-time passenger and cargo tracking procurement.
Auvergne-Rhône-Alpes
Grenoble and Saint-Étienne manufacturing zones generate emerging demand for industrial asset tracking systems with penetration rates below one-fifth of facility capacity. EU AI Act algorithmic transparency requirements are forcing upgrades to auditable positioning infrastructure in automated production environments. Lyon hypermarkets lead Bluetooth beacon deployments for sub-meter in-aisle personalization.
Provence-Alpes-Côte d'Azur
Marseille port authorities and tourism operators are consolidating procurement around unified indoor-outdoor-fleet visibility platforms. Wi-Fi positioning signal fingerprinting databases remain incomplete relative to Paris, constraining indoor navigation accuracy. Sophia Antipolis technology cluster hosts positioning algorithm development for automotive and aerospace applications.
Hauts-de-France
Calais-Dunkirk logistics corridors concentrate cross-channel freight tracking demand from British and Benelux supply chain operators. BSI standards for location data interoperability influence government buyer specifications for port and highway infrastructure. Lille metropolitan area is expanding predictive routing engines for last-mile delivery consolidation.
Nouvelle-Aquitaine
Bordeaux wine logistics and aerospace supply chains in Toulouse generate specialized fleet telematics demand. Galileo dual-frequency GNSS chipset adoption carries 15-25% hardware cost premiums that slow deployment in cost-sensitive agricultural asset tracking. Biarritz and Bayonne tourism operators are piloting proximity marketing for seasonal visitor engagement.
France Location-Based Services Market Competitive Landscape
Dutch and American producers anchor one tier of the market; French specialists hold public-sector and industrial niches. The vendor structure fragments across mapping heritage providers, fleet management API specialists, and geographic intelligence embedders. Three archetypes dominate: platform bundlers anchoring multi-year enterprise contracts, subsystem suppliers serving indoor positioning niches, and public-sector integrators embedding location intelligence into emergency frameworks. Competitive moves concentrate on API-based platform consolidation and 5G positioning convergence partnerships.
Within the platform bundler tier, HERE Technologies and TomTom International BV exemplify mapping-heritage providers anchoring enterprise relationships with national logistics operators. GEOCONCEPT SAS occupies a position as the public-sector archetype, embedding geographic intelligence into civil security frameworks. These three companies represent distinct strategic postures: unified indoor-outdoor-fleet visibility, specialized European road network optimization, and regulatory-compliant emergency response integration.
| Leading Market Players |
|---|
| HERE Technologies |
| TomTom International BV |
| GEOCONCEPT SAS |
| Zebra Technologies France SAS |
| Ubisense SAS |
| Apple |
| Foursquare |
| Mapbox |
| Others |
Pricing and Supply Chain Analysis
UWB chipset convergence with Bluetooth beacon hardware is compressing unit economics while concentrating procurement leverage among platform bundlers anchoring multi-year enterprise contracts. Dual-frequency GNSS receiver premiums of 15-25% over single-band alternatives are reshaping cost allocation between precision-grade logistics deployments and baseline consumer navigation tiers.
Pricing Analysis
Volume concentration in Île-de-France logistics corridors splits margin capture between SaaS-tiered platform subscriptions and per-unit transactional hardware sales. Three-tier pricing structure across premium dual-frequency GNSS, standard single-band GPS, and economy Wi-Fi positioning tiers differentiates by urban canyon accuracy requirements and CNIL compliance certification. Pricing pressure stems from Galileo chipset cost premiums slowing replacement cycles in secondary French urban centers. National retail chains exhibit lowest price sensitivity due to unified platform procurement mandates, while municipal transport authorities face acute budget constraints.
Supply Chain Analysis
Reverse logistics flows for UWB anchor refurbishment and Bluetooth beacon battery replacement are emerging as cost centers in French hypermarket deployments. Semiconductor fabrication concentrates in Taiwan, South Korea, and the Netherlands for positioning chipsets, while antenna and sensor assembly clusters in Germany and China feed European distribution. Dual-frequency GNSS silicon and UWB transceiver modules constitute critical input dependencies. Single-source vulnerability in EU-sourced Galileo receiver supply creates tariff-exposed chokepoints. Distribution runs through authorized distributor networks serving systems integrators and direct enterprise platform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geospatial data science talent scarcity propping platform development costs sustains incumbent pricing power despite hardware commoditization pressures in standard-tier positioning equipment.
For Market Incumbents: Lock in multi-year API contracts with national logistics providers before 5G positioning convergence commoditizes network-based ranging layers. Deepen backward integration into UWB chipset supply through captive sourcing agreements with Dutch semiconductor fabricators. Defend against TomTom's European road network specialization by anchoring indoor-outdoor handoff patents. For New Entrants and Emerging Players: Capture greenfield industrial asset tracking deployments in Auvergne-Rhône-Alpes manufacturing zones where penetration remains below one-fifth of facility capacity. Target Grenoble production environments with RFID-to-UWB upgrade pathways and CNIL-compliant edge-compute architectures. Lead with predictive maintenance integration rather than pure positioning accuracy. For Investors and Strategic Acquirers: Exit pathways concentrate in platform bundler acquisitions by automotive OEMs seeking smartphone-as-key functionality. Five-to-ten year viability hinges on EU AI Act compliance infrastructure becoming non-negotiable procurement specification. Target acquisition archetype: indoor positioning specialists with existing GEOCONCEPT-style public-sector anchor contracts. Watch CNIL biometric-location fusion enforcement intensity as inflection signal for privacy-preserving positioning premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| 5G Positioning Convergence Partnership | Unifies cellular and satellite layers for seamless indoor-outdoor handoff in Île-de-France logistics corridors. |
| CNIL Compliance Certification Investment | Enables biometric-location fusion deployments in Paris retail analytics without regulatory penalty exposure. |
| UWB Anchor Manufacturing Scale-Up | Captures smartphone-as-key demand from French automotive suppliers embedding interior ranging infrastructure. |
| Auvergne-Rhône-Alpes Geographic Expansion | Penetrates sub-20% industrial asset tracking coverage in Grenoble and Saint-Étienne production zones. |
| Emergency Response System Integration | Replicates GEOCONCEPT's civil security embedding model for national-scale public-sector platform anchoring. |
Research Methodology
Independent corroboration across positioning technology vendors, CNIL regulatory affairs specialists, and French retail chain procurement directors underwrites the qualitative findings. Primary interviews with fleet telematics managers, smart city infrastructure planners, and UWB chipset distributors combined with secondary validation from EU AI Act implementation guidance, CNIL geolocation consent enforcement records, and BSI location data interoperability specifications. Bottom-up deployment counts across Île-de-France transit hubs and top-down platform revenue triangulation anchored the market sizing.
Rate-of-change decomposition across application segments, technology tiers, and deployment architectures structured the analytical framework over the projection horizon. Segmentation dimensions modeled include navigation versus retail versus emergency services applications, GPS versus Wi-Fi versus Bluetooth versus UWB technology layers, and cloud versus on-premises versus hybrid deployment modes. CAGRs derived from hardware refresh cycle analysis and platform subscription renewal rates. Industry-specific inputs incorporated Galileo receiver adoption curves and CNIL enforcement intensity indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act algorithmic transparency implementation timelines and CNIL biometric-location fusion guidance evolution. Forecasts reflect documented assumptions regarding 5G positioning protocol standardization and UWB cost compression trajectories. Material deviation in CNIL enforcement intensity or Galileo chipset supply continuity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Vegan Confectionery Market
Others
Smart Home Gateways Market
Others
Thiamethoxam Market
Others
Global Tobacco Market
Others
India Smart Home Market
Others
Bio-Based Leather Market
Others
Italy Automotive Adaptive Lighting System Market
Others
APAC Smart Home Market
Others
China Smart Home Market
Others
High-Performance Films Market
Others
Industrial Gauges Market
Others
Boston Round Bottle Market
Others
Latin America 3D Printing Construction Market
Others
Europe Digital Experience Platform Market
Others
Global Snow Sports Apparel Market
Others
Powder Coating Equipment Market