
 North America Smart Homes Market | 2026-2036
North America Smart Homes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart Homes Market Foresight
The North America smart homes market is rebalancing between premium whole-home ecosystems and commodity point solutions. Amazon.com Inc. leverages its Alexa voice platform and Ring security portfolio to anchor recurring service revenue. Google LLC competes through Nest hardware and deep Android integration across thermostat and camera lines. Apple Inc. differentiates via privacy-centric HomeKit architecture and seamless iOS device pairing.
A smart home integrates connected devices, sensors, and control systems that automate lighting, climate, security, and appliance functions through centralized or distributed network architectures, typically operating over Wi-Fi, Zigbee, Z-Wave, or Bluetooth protocols with cloud or edge processing for real-time responsiveness. Smart Security commands the largest installed base among product types, though Energy Management applications within HVAC Control and Smart Lighting segments attract the fastest retrofit spending as utility rate structures penalize peak consumption. Wi-Fi remains the dominant connectivity layer for consumer self-installation, while Z-Wave and Zigbee sustain professional integrator channels where reliability and mesh redundancy justify premium hardware margins.
The FCC governs wireless spectrum allocation for IoT device communication, while the EPA's ENERGY STAR specifications shape smart appliance efficiency benchmarks and the CSA Group's UL certification mandates electrical safety standards for connected home equipment. Stakeholders must monitor how NIST cybersecurity frameworks and evolving state-level data privacy statutes in California and New York reshape liability exposure for device manufacturers and platform operators.
Market Dynamics
The Matter protocol is consolidating device interoperability standards across the North America smart homes market, forcing platform operators to abandon proprietary walled gardens in favor of unified certification frameworks that reduce consumer switching costs.
Growth Catalysts
- Utility Rebate Programs:Texas, Florida, and California metropolitan corridors offer the most generous incentives for energy management system installations, accelerating HVAC control and smart lighting adoption among cost-conscious homeowners.
- FCC Broadband Infrastructure Investments:Federal Communications Commission funding for rural and underserved area connectivity expansion is extending addressable market reach beyond traditional urban fiber footprints.
- New Construction Pre-Installation:National homebuilders are embedding smart devices during construction phases, converting retrofit-dependent demand into built-in infrastructure across greenfield residential developments.
Market Restraints
- Silicon Supply Concentration:Semiconductor fabrication for Zigbee and Z-Wave chipsets concentrates in East Asian foundries, exposing North American hardware manufacturers to geopolitical supply disruption risks.
- Cybersecurity Liability Exposure:Evolving NIST cybersecurity frameworks and state-level data privacy statutes in California and New York are expanding manufacturer liability for breach incidents without standardized insurance coverage models.
- Wi-Fi Spectrum Congestion:Dense urban deployments in Texas and California corridors experience interference saturation, degrading real-time responsiveness for latency-sensitive security and climate applications.
Strategic Opportunities
- Aging-in-Place Applications:Florida's demographic concentration of retirees creates underserved demand for health-monitoring integrations within existing smart home architectures, combining fall detection with automated environmental controls.
- Edge Processing Convergence:On-device AI inference paired with local mesh networking is reducing cloud dependency for privacy-sensitive consumers, opening premium positioning for hardware with dedicated neural processing units.
- Professional Integrator Channel Expansion:Z-Wave and Zigbee reliability advantages justify premium margins in custom installation markets where electricians and AV specialists capture recurring service relationships.
Industry Challenges
- Certification Timeline Compression:CSA Group UL certification mandates for electrical safety require extended testing cycles that delay product launches, particularly for manufacturers integrating multiple wireless protocols.
- Interoperability Testing Complexity:Matter protocol compliance demands cross-platform validation against Amazon Alexa, Google Nest, and Apple HomeKit implementations, multiplying pre-release engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart Homes Market |
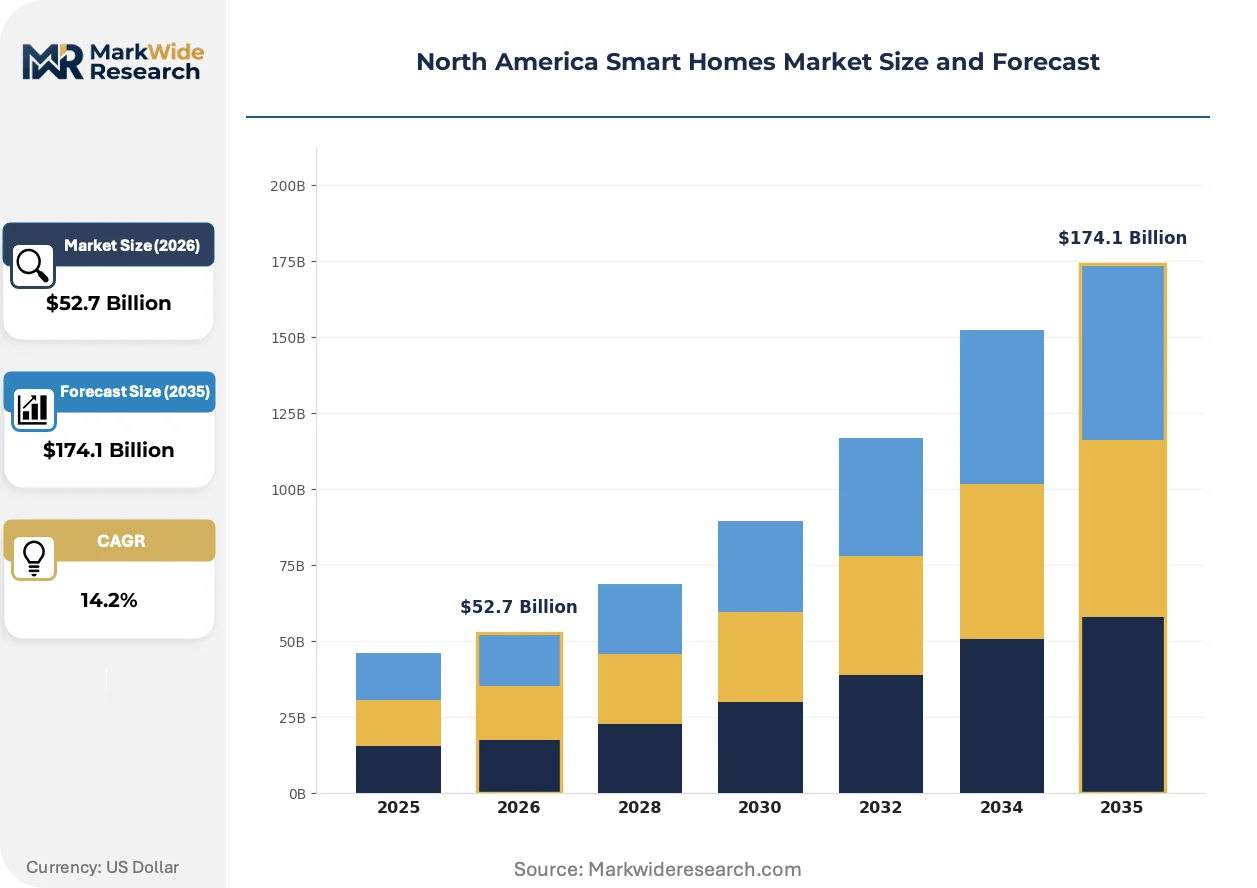
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $174.1 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Security, Smart Lighting, HVAC Control, Smart Appliances Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth End User: Homeowners, Renters, Property Managers, Builders Application: Residential Automation, Energy Management, Home Security, Health Monitoring |
| Companies Covered | Amazon.com Inc., Google LLC, Apple Inc., Samsung Electronics Co. Ltd., Honeywell International Inc., LG Electronics Inc., Schneider Electric SE, Johnson Controls International PLC, ASSA ABLOY, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart Homes Market Shifts & Advancements
Matter-certified hardware is eliminating fragmentation between competing smart home platforms, while edge AI and utility-integrated demand response systems are redefining value capture beyond device sales.
Thread mesh networking combined with Matter-over-Thread certification is electrifying whole-home automation reliability. Custom integrators in California and Texas corridors are specifying Thread border routers as standard infrastructure. This convergence is compressing commissioning timeframes and reducing truck-roll service calls for connectivity troubleshooting.
The EPA's ENERGY STAR specifications for smart appliances are tightening efficiency benchmarks annually. Manufacturers must redesign power management circuits to maintain certification eligibility. HVAC control and water heater segments face the steepest redesign cycles as ENERGY STAR Version 7.0 requirements phase in.
Homeowners are unbundling professional monitoring contracts from hardware purchases, favoring self-managed alert systems with optional on-demand dispatch. This pattern disrupts traditional security dealer recurring revenue models. The shift is most visible in Florida and Arizona retirement communities where tech-comfortable retirees reject long-term service commitments.
North America Smart Homes Market Segmentation
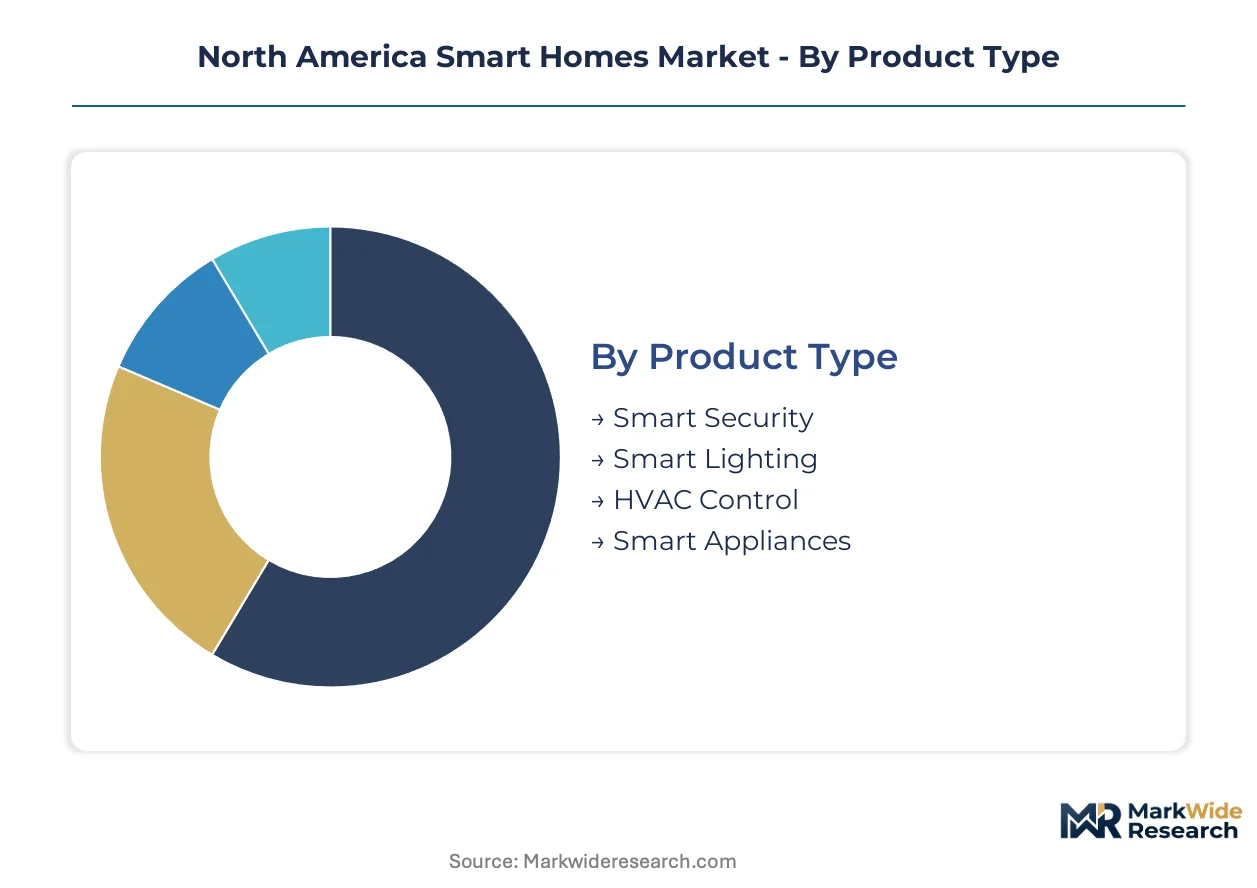
Smart home purchasing decisions fragment across technical sophistication, installation channel, and ownership tenure. Buyers self-select into segments based on DIY capability, rental restrictions, and builder relationships that pre-determine ecosystem choices.
Product Type:
Buyers differentiate primarily by upfront hardware cost versus recurring service attachment.
- Smart Security:Cameras, sensors, and monitoring systems with cloud storage subscriptions anchor the largest installed base. Demand concentrates in Florida and Texas metropolitan corridors where retirees and suburban homeowners prioritize property protection with professional monitoring fallback.
- HVAC Control:Smart thermostats and climate zoning systems with utility-integrated demand response. California and Texas utility rebate programs accelerate retrofit adoption among cost-conscious households facing peak-rate penalties.
- Smart Lighting:Connected bulbs, switches, and fixture-integrated controls with circadian programming. Builders in greenfield developments specify these as standard infrastructure.
- Smart Appliances:Refrigerators, washers, and ovens with remote diagnostics and energy optimization. ENERGY STAR Version 7.0 compliance requirements are forcing redesign cycles for manufacturers.
Smart Security leads volumes today; HVAC Control is gaining share fastest.
Technology:
Connectivity choice tracks buyer tolerance for configuration complexity against reliability requirements.
- Wi-Fi:Ubiquitous protocol for consumer self-installation leveraging existing home networks. Dense urban deployments in California and Texas corridors experience spectrum congestion degrading real-time responsiveness.
- Z-Wave:Sub-GHz mesh protocol with proven reliability in professional integrator channels. Custom installers capture premium margins where electricians and AV specialists demand truck-roll reduction.
- Zigbee:IEEE 802.15.4-based mesh with broad device ecosystem. Silicon supply concentration in East Asian foundries exposes North American hardware manufacturers to geopolitical disruption.
- Bluetooth:Low-energy pairing for proximity-based device commissioning and audio streaming. Matter-over-Thread convergence is compressing its standalone role in whole-home architectures.
Wi-Fi dominates installation counts; Z-Wave commands the highest hardware margins.
End User:
Ownership duration and modification permissions shape ecosystem lock-in versus flexibility priorities.
- Homeowners:Permanent residents investing in whole-home infrastructure with multi-year payback horizons. Texas and Florida markets show strongest concentration of premium system adoption.
- Renters:Tenants requiring portable, non-destructive installations with lease-transferable devices. Demand favors battery-powered cameras and plug-in lighting over hardwired infrastructure.
- Property Managers:Multi-unit operators standardizing across portfolios for centralized monitoring and maintenance efficiency. California rent-control jurisdictions drive automation for operational cost reduction.
- Builders:National homebuilders embedding devices during construction to differentiate new developments. Pre-installation converts retrofit-dependent demand into built-in infrastructure.
Homeowners account for the largest revenue pool; Builders show the steepest expansion trajectory.
Application:
Use-case priority determines whether buyers lead with convenience, cost reduction, or safety.
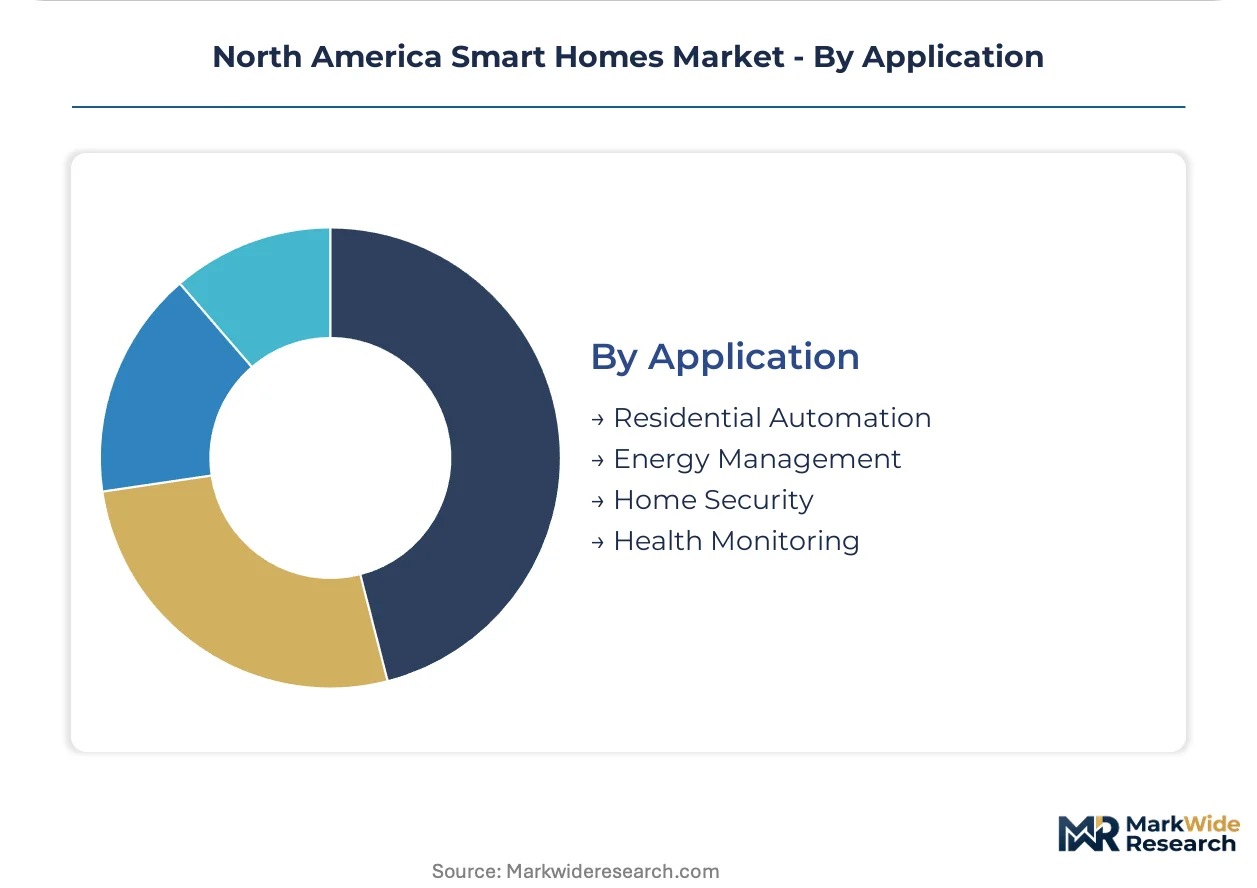
- Residential Automation:Whole-home orchestration of lighting, climate, and entertainment through centralized or distributed control. Voice platform integration with Alexa, Google Nest, or Apple HomeKit drives ecosystem selection.
- Energy Management:Utility-integrated demand response and consumption optimization. EPA ENERGY STAR specifications tighten efficiency benchmarks annually, forcing power management circuit redesigns.
- Home Security:Perimeter monitoring, intrusion detection, and emergency dispatch integration. Self-managed alert systems with on-demand dispatch are displacing traditional dealer recurring revenue models.
- Health Monitoring:Fall detection, medication reminders, and environmental controls for aging-in-place. Florida's retiree concentration creates underserved demand combining biometric sensors with automated climate.
Residential Automation captures the most device connections; Health Monitoring is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep pools of IoT engineering talent concentrate in Austin, Seattle, and Toronto, anchoring platform development and hardware design capabilities across the continent.
United States
Texas and California metropolitan corridors drive retrofit demand through utility rebate programs for energy management systems. The FCC's broadband infrastructure investments extend connectivity into rural markets previously beyond fiber footprints. Dallas-Fort Worth and Silicon Valley host the densest concentrations of smart home R&D facilities and venture-backed device startups.
Canada
Toronto and Vancouver anchor North American expansion for several platform operators seeking English-French bilingual deployment capabilities. Health Canada regulates radio frequency emissions for IoT devices under standards harmonized with FCC frameworks. Quebec's provincial energy utility operates demand response pilots accelerating smart thermostat adoption in Montreal and Quebec City corridors.
Mexico
Guadalajara and Mexico City manufacturing clusters produce connected home hardware for re-export to US markets under nearshoring arrangements. The country's federal telecommunications regulator manages spectrum allocation for Zigbee and Z-Wave protocols in industrial corridors. Monterrey's electronics assembly sector is capturing contract manufacturing previously concentrated in East Asian facilities.
North America Smart Homes Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the North America smart homes market. Platform operators with cloud infrastructure investments battle hardware specialists dependent on third-party foundry capacity. Three archetypes dominate: voice-first ecosystem orchestrators, component-integrated appliance manufacturers, and professional-channel security specialists. Competitive intensity centers on Matter protocol certification speed and utility partnership exclusivity rather than raw hardware specifications.
Among voice-first ecosystem architects, Amazon.com Inc. and Google LLC exemplify the platform-anchored archetype where recurring service revenue supersedes device margin capture. Apple Inc. occupies a differentiated position emphasizing privacy-centric architecture and seamless iOS integration. Samsung Electronics Co. Ltd. represents the vertically integrated electronics conglomerate model, spanning semiconductor fabrication through finished appliance distribution.
| Leading Market Players |
|---|
| Amazon.com Inc. |
| Google LLC |
| Apple Inc. |
| Samsung Electronics Co. Ltd. |
| Honeywell International Inc. |
| LG Electronics Inc. |
| Schneider Electric SE |
| Johnson Controls International PLC |
| ASSA ABLOY |
| Others |
Supply & Pricing Matrix
Captive semiconductor fabrication in South Korean and Taiwanese foundries anchors hardware cost structures while simultaneously constraining margin flexibility for North American device assemblers facing geopolitical tariff exposure. This upstream concentration forces pricing power asymmetries that favor component suppliers over finished-goods manufacturers.
Pricing Analysis
The bundled-vs-unbundled service split separates professional integrator channels from direct-to-consumer retail. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Cost compression in the economy tier intensifies because Matter protocol compliance demands cross-platform validation overhead. Property managers exhibit the highest price sensitivity due to portfolio-standardization mandates, while custom integrators in Texas and California corridors accept premium hardware margins for Z-Wave reliability advantages.
Supply Chain Analysis
Workforce availability constraints in Guadalajara and Monterrey electronics assembly clusters are accelerating nearshoring contract migration from East Asian facilities. Silicon wafer supply draws from Taiwanese and South Korean foundries, while Zigbee and Z-Wave chipset production rests on Malaysian packaging operations. Single-source vulnerability in sub-GHz radio module sourcing creates disruption exposure. Distribution runs through big-box retail for consumer self-installation and electrical distributor networks for professional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Texas and California utility rebate differentials create a geographic-arbitrage play for energy management system deployment, with regulatory generosity in these states compressing payback periods versus jurisdictions lacking comparable incentive structures.
For Market Incumbents: Deepen Matter certification speed advantages to outpace compliance timelines that delay competitor launches. Lock in exclusive utility partnership arrangements in Florida and Texas corridors before rebate program caps trigger. Channel control through certified integrator networks defends against direct-to-consumer entrants undercutting hardware margins.
For New Entrants and Emerging Players: Launch via property manager direct sales targeting California rent-control jurisdictions where operational cost reduction mandates automate adoption. Aging-in-place health monitoring in Florida retirement communities represents the most penetrable white-space segment. Matter-over-Thread hardware positioning bypasses incumbent ecosystem lock-in.
For Investors and Strategic Acquirers: Roll-up economics work for professional integrator roll-ups because fragmented electrician and AV specialist networks lack national scale. The five-to-ten-year viability window favors platform operators with recurring service revenue attachment over pure hardware vendors. Monitor CSA Group UL certification backlog as inflection indicator for product launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Cross-platform validation against Amazon Alexa, Google Nest, and Apple HomeKit implementations reduces consumer switching costs. |
| Utility Partnership Exclusivity | Rebate program anchoring in Texas, Florida, and California metropolitan corridors locks in demand response integration. |
| Professional Integrator Acquisition | Certified electrician and AV specialist networks capture recurring service relationships with premium hardware margins. |
| Edge AI Hardware Development | On-device neural processing units reduce cloud dependency for privacy-sensitive consumers in health monitoring segments. |
| Nearshoring Manufacturing Footprint | Guadalajara and Monterrey assembly clusters mitigate East Asian foundry concentration risks for North American markets. |
Research Methodology
Bottom-up builder and homeowner demand modeling reconciled against top-down semiconductor supply tracking forms the analytical core. Primary interviews with smart home platform engineers, electrical contractor purchasing managers, utility demand response officers, and retail category buyers combined with secondary validation from FCC spectrum allocation filings, EPA ENERGY STAR certification databases, CSA Group UL safety records, and utility rebate program disclosures. Triangulation across these sources anchors volume estimates.
Input-output matrices map connectivity protocol adoption rates against installation channel preferences across the projection horizon. Segmentation dimensions include product type, technology layer, end-user archetype, and application use-case. CAGRs derive from fitted growth curves incorporating broadband infrastructure investment trajectories and new construction pre-installation penetration. Matter protocol certification timelines and ENERGY STAR Version 7.0 compliance cycles constitute industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical disruption of East Asian semiconductor supply, state-level data privacy statute evolution beyond California and New York frameworks, and Wi-Fi spectrum congestion thresholds in dense urban deployments. Forecasts reflect documented assumptions about rebate program continuity and interoperability standard consolidation. Material deviation in FCC infrastructure funding allocation or Matter protocol adoption velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Smartphone Gimbal Market
Others
Smart Plug Market
Others
Global Optical Coordinate Measuring Machine Market
Others
Ammeters Market
Others
Cat Dry Food Market
Others
Fluorite Market
Others
Cat Food Market
Others
North America Video Conferencing Hardware Market
Others
Griffin Beaker Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market
Others
Europe Virtual Reality Gaming Market
Others
Global Magnetic Flow Meters Market
Others
Coconut Activated Carbon Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
United States Smart Homes Market
Others
Global Essential Oils and Plant Extracts for Livestock Market